
 Cinema Point of Sale (POS) Solutions Market | 2026-2036
Cinema Point of Sale (POS) Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Cinema Point of Sale (POS) Solutions Market Outlook
A shift from fragmented single-vendor installations toward unified multi-source ecosystems is repositioning how exhibitors architect their technology stacks. Vista Cinema dominates North American large-format deployments through its end-to-end software suite. BQT Solutions anchors Asia-Pacific markets with hardware specialization in ruggedized kiosk terminals. PAR Technology extends its restaurant-hospitality DNA into cinema concession integration, competing on cross-vertical platform consistency.
Cinema Point of Sale (POS) Solutions encompass integrated hardware-software systems processing ticket sales, concession transactions, and membership programs through terminals, servers, and cloud-connected peripherals operating at sub-second response thresholds for high-throughput lobby environments. Cloud-Based technology leads new deployments as exhibitors shed on-premises server maintenance burdens, while Self-Service Kiosks represent the fastest-growing hardware category driven by labor cost containment and throughput optimization. Software segments capture disproportionate margin pools through recurring subscription models, whereas Integration services face commoditization from standardized API protocols.
PCI-DSS governs payment card data security across all deployments, compelling vendors to certify encryption architectures and tokenization pathways. The EU AI Act and GDPR constrain automated customer profiling and biometric payment verification in European cinema deployments, while India's RBI guidelines on digital payment interoperability shape kiosk terminal specifications for domestic exhibitors. Stakeholders must weigh cloud dependency against data sovereignty requirements as regulatory fragmentation intensifies across operating geographies.
Market Dynamics
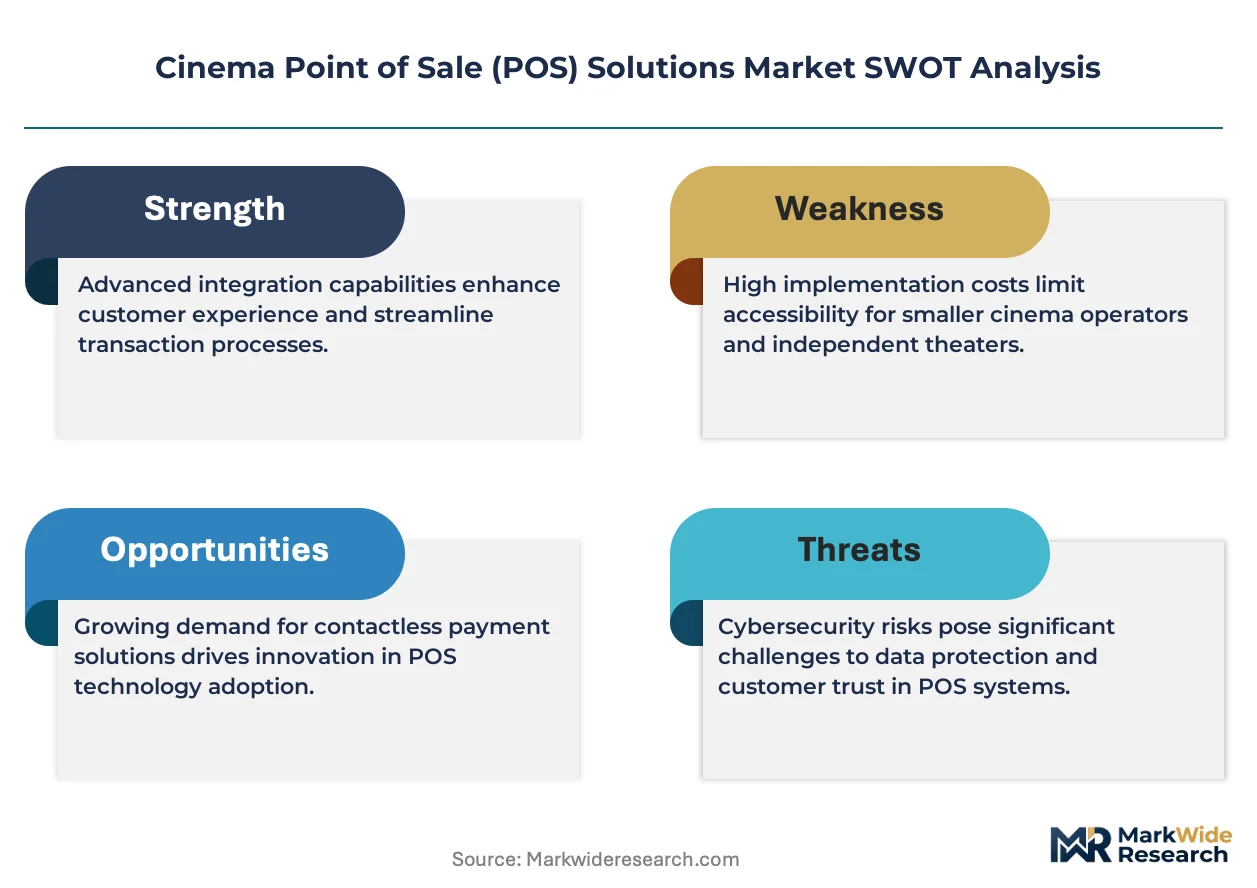
Cloud migration is compressing deployment cycles for exhibitors while PCI-DSS certification requirements are forcing hardware refresh decisions across fragmented legacy estates. The tension between data sovereignty mandates and SaaS convenience is restructuring vendor procurement priorities.
Growth Catalysts
- India's cinema infrastructure expansion:Multiplex construction in tier-2 and tier-3 cities is generating concentrated demand for integrated ticketing-concession platforms. RBI digital payment interoperability guidelines are accelerating terminal upgrade cycles.
- Self-Service Kiosk proliferation:Labor cost containment pressures across Southeast Asian exhibition chains are driving deployment of ruggedized lobby terminals. Throughput optimization in high-traffic multiplexes favors automated transaction flows.
- PCI-DSS 4.0 compliance mandates:Enhanced encryption and tokenization requirements are compelling hardware replacement across North American and European installed bases. Certification deadlines are synchronizing procurement waves.
Market Restraints
- Semiconductor supply concentration:Kiosk terminal production depends on concentrated Asian foundry capacity for payment processors and touch controllers. Geopolitical friction creates delivery uncertainty for hardware vendors.
- Cloud dependency risks:Exhibitors in markets with unreliable connectivity face operational vulnerability from SaaS-first architectures. Hybrid deployment costs erode the total-cost-of-ownership advantage.
- GDPR biometric restrictions:EU AI Act constraints on automated facial recognition limit deployment of frictionless payment verification in European cinema lobbies. Compliance complexity adds implementation overhead.
Strategic Opportunities
- Middle East luxury cinema buildout:Saudi Arabia's entertainment sector liberalization is creating demand for premium lobby experiences with integrated F&B and retail POS. MOHAP and SFDA food safety regulations favor certified platform providers.
- API standardization convergence:Open banking protocols and cinema industry data standards are enabling modular best-of-breed architectures. Exhibitors can mix ticketing, payment, and loyalty components without vendor lock-in.
- Edge computing deployment:Local transaction processing at kiosk level reduces cloud bandwidth costs and enables offline operation. This architecture addresses connectivity constraints in emerging market multiplexes.
Industry Challenges
- Legacy system integration complexity:Decades-old TMS (Theatre Management System) installations require custom middleware for cloud POS connectivity. Project timelines extend due to scarce specialized integration talent.
- Certification timeline compression:PCI-DSS 4.0 migration deadlines overlap with EMV contactless mandates in multiple jurisdictions. Vendors face resource strain from concurrent compliance programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cinema Point of Sale (POS) Solutions Market |
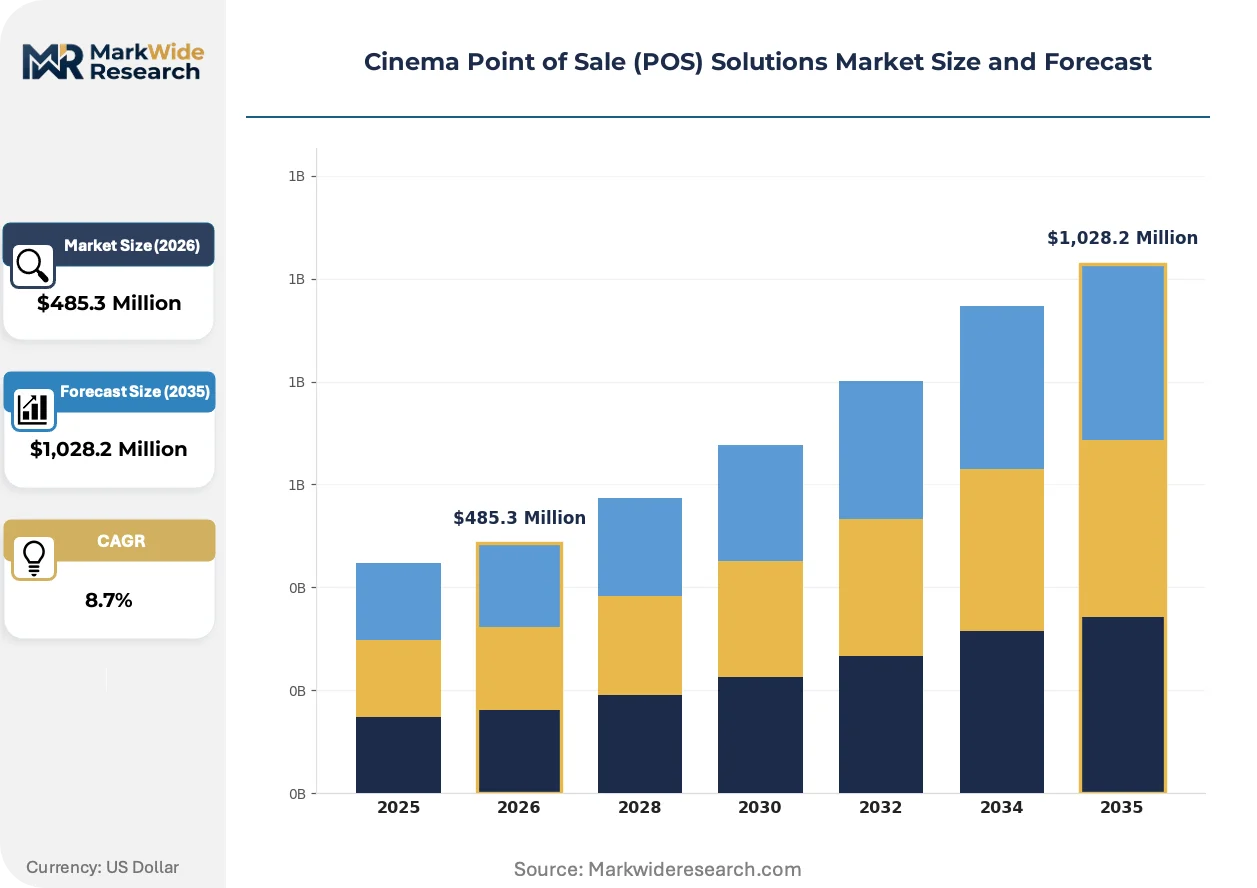
| Market Size in 2026 | $485.3 Million |
| Market Size in 2035 | $1,028.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hardware, Software, Services, Integration Customer Type: Cinemas, Theaters, Restaurant Chains, Event Venues Technology: Cloud-Based, On-Premises, Mobile, Self-Service Kiosks Service Type: Installation, Support, Maintenance, Customization |
| Companies Covered | BQT Solutions, RTS, Vista Cinema, USL Cinema, Embassy Cinema Software, PAR Technology, Omniterm, EliteTeQ POS, Veezi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cinema Point of Sale (POS) Solutions Market Strategic Shifts
Unified platform architectures are displacing fragmented point solutions as exhibitors prioritize operational visibility across ticketing, concession, and membership functions. The convergence of payment technology and cinema management software is compressing vendor consolidation timelines.
Mobile wallet integration is unifying payment acceptance across NFC, QR, and tokenized card formats within single terminal deployments. Mid-market multiplex chains in India and Southeast Asia are adopting these platforms at accelerated rates. This convergence is unifying transaction data streams that previously required separate reconciliation processes, enabling real-time inventory and revenue analytics.
EU AI Act algorithmic transparency requirements are constraining automated upsell and dynamic pricing engines in European cinema deployments. Exhibitors must document decision logic for concession recommendations and membership tier assignments. Premium cinema operators in Germany and France are responding by simplifying recommendation engines and adding explicit consent flows.
Subscription membership models are altering transaction frequency patterns and POS system load profiles. AMC Stubs-style programs in North America and comparable offerings in South Korea are replacing single-ticket purchases with recurring credential-verification flows. This shift is most visible in Seoul and Los Angeles metropolitan clusters where membership penetration exceeds forty percent of admissions.
Cinema Point of Sale (POS) Solutions Market Segmentation
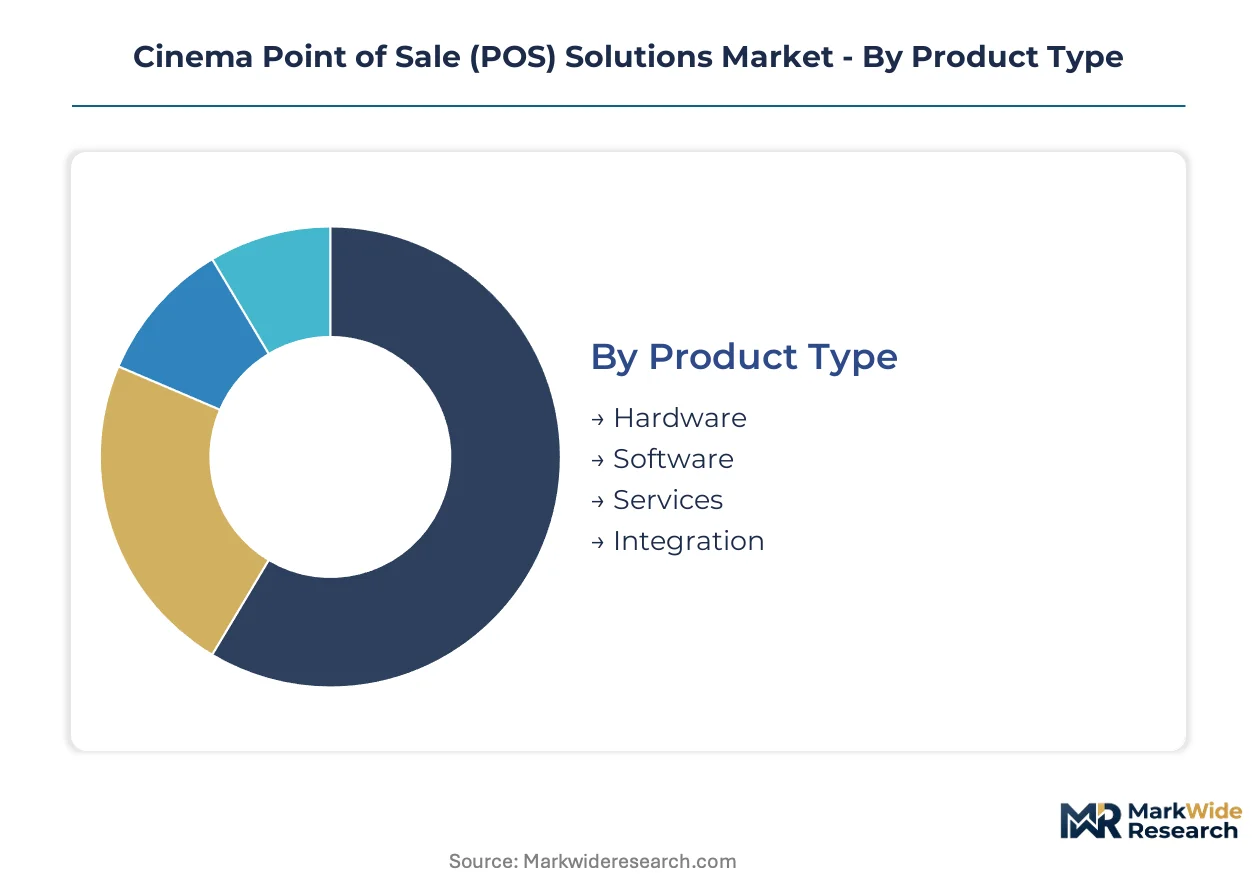
Segmentation reveals how procurement priorities diverge across deployment scales and regulatory environments. Exhibitors balance upfront capital constraints against recurring operational burdens when selecting platform architectures.
Product Type:
Volume deployments favor hardware-heavy configurations while premium operators invest disproportionately in software layers.
- Hardware:Ruggedized terminals, payment processors, and touch controllers form the physical transaction layer. Demand concentrates in India where RBI-mandated terminal upgrades drive replacement cycles across tier-2 and tier-3 multiplex construction.
- Software:Subscription-based ticketing engines, concession management modules, and membership platforms capture recurring revenue streams. Large-format exhibitors in Los Angeles and Seoul prioritize unified suites over fragmented point solutions.
- Services:Training and operational consulting support deployment scale-up.
- Integration:Middleware connecting legacy TMS installations to cloud architectures faces margin compression from standardized API protocols.
Today's leader: Software. Tomorrow's challenger: Integration.
Customer Type:
Application context determines throughput requirements and compliance exposure.
- Cinemas:Multiplex operators process high-velocity lobby transactions requiring sub-second response thresholds. Southeast Asian chains accelerate kiosk deployment for labor cost containment.
- Theaters:Single-screen and boutique venues favor compact, all-in-one terminal configurations with simplified maintenance profiles.
- Restaurant Chains:Cross-vertical operators like PAR Technology extend hospitality-honed F&B integration into cinema concession environments.
- Event Venues:Temporary and seasonal installations demand rapid-deployment hardware with minimal infrastructure dependency.
Core demand anchors in Cinemas. Adjacent growth surfaces in Event Venues.
Technology:
Margin pools concentrate at the infrastructure-liberation frontier.
- Cloud-Based:SaaS architectures eliminate on-premises server maintenance while enabling real-time analytics across distributed circuits. GDPR data sovereignty constraints create hybrid deployment friction in European markets.
- On-Premises:Legacy server installations persist where connectivity reliability remains problematic. Total cost-of-ownership disadvantages accelerate replacement timelines.
- Mobile:Smartphone-based ticket validation and payment acceptance reduce terminal density requirements. QR and NFC convergence unifies acceptance formats.
- Self-Service Kiosks:Automated lobby terminals optimize throughput in high-traffic multiplexes. Labor arbitrage drives Southeast Asian deployment acceleration.
Expansion concentrates in Cloud-Based. Steepest trajectory belongs to Self-Service Kiosks.
Service Type:
Revenue predictability varies sharply across engagement duration.
- Installation:Project-based deployment services face pricing pressure from standardized hardware configurations.
- Support:24/7 operational assistance commands premium pricing for mission-critical cinema environments.
- Maintenance:Preventive service contracts stabilize vendor cash flows while reducing exhibitor downtime exposure.
- Customization:Tailored middleware development for legacy TMS integration captures project-based margins from scarce specialized talent.
Recurring revenue concentrates in Support. Project upside resides in Customization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's multiplex construction boom in tier-2 and tier-3 cities anchors regional demand concentration for integrated ticketing-concession platforms. RBI digital payment interoperability guidelines accelerate terminal upgrade cycles across domestic exhibition circuits. Southeast Asian operators deploy ruggedized kiosks for labor cost containment.
United States
AMC Stubs-style subscription programs exceed forty percent membership penetration in Los Angeles metropolitan clusters, altering POS load profiles toward recurring credential verification. PCI-DSS 4.0 compliance deadlines synchronize hardware replacement waves across legacy installed bases. Vista Cinema dominates large-format deployments through end-to-end software suites in California and New York exhibition circuits.
India
Multiplex construction in Pune, Hyderabad, and Kochi generates concentrated demand for unified ticketing-concession platforms. RBI guidelines on digital payment interoperability mandate terminal specifications for domestic exhibitors. PVR-Inox and Cinepolis circuits drive kiosk deployment acceleration in Maharashtra and Telangana state clusters.
Germany
Premium cinema operators in Berlin and Munich simplify recommendation engines under EU AI Act algorithmic transparency requirements. GDPR biometric restrictions limit frictionless payment verification deployment in lobby environments. Compliance complexity adds implementation overhead for concession upsell automation.
Saudi Arabia
Entertainment sector liberalization creates demand for premium lobby experiences with integrated F&B and retail POS in Riyadh and Jeddah. MOHAP and SFDA food safety regulations favor certified platform providers. VOX Cinemas and AMC circuits anchor luxury cinema buildout in Eastern Province developments.
South Korea
Seoul metropolitan membership penetration exceeds forty percent of admissions, shifting transaction patterns toward subscription credential verification. MFDS food safety standards constrain concession integration architectures. CGV and Lotte Cinema circuits optimize kiosk throughput in Busan-Ulsan multiplex clusters.
Cinema Point of Sale (POS) Solutions Market Competitive Environment
Global majors compete with regional champions across hardware specialization and software integration depth. The vendor base stratifies between end-to-end suite providers, hardware-centric fabricators, and cross-vertical hospitality entrants. Three archetypes dominate: unified platform architects, ruggedized terminal specialists, and restaurant-hospitality extenders. Consolidation pressure intensifies through API standardization and cloud migration procurement preferences.
Within the unified platform tier, Vista Cinema and Veezi exemplify end-to-end software suite positioning. BQT Solutions anchors Asia-Pacific markets with hardware specialization archetypes. PAR Technology occupies the cross-vertical extension position, competing on hospitality-honed F&B integration consistency. These three representations illustrate how geographic origin and vertical DNA shape competitive differentiation without vendor lock-in.
| Leading Market Players |
|---|
| BQT Solutions |
| RTS |
| Vista Cinema |
| USL Cinema |
| Embassy Cinema Software |
| PAR Technology |
| Omniterm |
| EliteTeQ POS |
| Veezi |
| Others |
Value Chain & Pricing Dynamics
Multiplex operators in India's tier-2 and tier-3 construction boom concentrate procurement power, anchoring subscription-based SaaS pricing as the dominant model across hardware-software bundles. This buyer concentration shifts pricing leverage toward volume-scale exhibitors while fragmenting price realization for smaller single-screen venues.
Pricing Analysis
Payment processor and touch controller cost pass-through from concentrated Asian foundries compresses hardware margins for kiosk terminal vendors. Three-tier pricing structure across premium, standard, and economy levels separates PCI-DSS 4.0 certified configurations from legacy encryption tiers. Cost compression in standard-tier hardware intensifies because semiconductor supply concentration limits vendor negotiation leverage. Single-screen and boutique theaters exhibit highest price sensitivity, while large-format exhibitors in Los Angeles and Seoul absorb premium pricing for unified suite deployments.
Supply Chain Analysis
PCI-DSS certification and RBI terminal specification compliance gate entry for payment hardware suppliers, favoring established vendors with certification infrastructure. Manufacturing concentrates in China, Taiwan, and South Korea for payment processors, touch controllers, and ruggedized enclosure fabrication. Kiosk terminal production draws from concentrated Asian foundry capacity for specialized semiconductors. Single-source vulnerability in payment processor supply creates delivery uncertainty during geopolitical friction periods. Distribution runs through direct vendor-exhibitor contracts with regional integration partners handling legacy TMS middleware deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Exhibitors arbitrage labor cost differentials between Southeast Asian kiosk deployment and North American subscription model adoption, capturing operational savings from automated transaction flows against higher SaaS recurring burdens.
For Market Incumbents: Anticipate margin compression from API standardization enabling modular best-of-breed architectures that break end-to-end suite lock-in. Defend position through backward integration into edge computing hardware for offline-capable kiosk deployments. Certification investment in PCI-DSS 4.0 and EMV contactless standards preserves incumbent status against emerging cloud-native entrants. For New Entrants and Emerging Players: Regional integration partners in India and Saudi Arabia represent the most accessible channel for white-space penetration. Target tier-2 multiplex construction in Maharashtra and Telangana state clusters where legacy TMS integration complexity slows incumbent response times. Pursue kiosk-terminal-as-a-service models with embedded payment processing to bypass capital-constrained exhibitor procurement cycles. For Investors and Strategic Acquirers: Cross-vertical hospitality technology consolidators are the most active acquirer in this space, seeking F&B integration capabilities from cinema-specialist vendors. Long-term viability hinges on cloud migration completion and self-service kiosk saturation across emerging market multiplex buildouts. Acquisition target archetype: mid-scale software vendors with RBI-certified terminal specifications and established India circuit relationships. Watch kiosk deployment velocity in Saudi Arabia's Eastern Province developments as inflection indicator for Middle East luxury cinema POS demand.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unified ticketing-concession suites displace fragmented point solutions in Los Angeles large-format circuits. |
| Geographic Expansion | Saudi Arabia entertainment liberalization creates premium lobby POS demand in Riyadh and Jeddah developments. |
| Acquisition of Specialist Firm | Middleware vendors with legacy TMS connectivity expertise command scarcity premiums from cloud migration timelines. |
| Product Launch | Edge-enabled kiosk terminals with offline transaction processing address connectivity constraints in Indian tier-3 cities. |
| Strategic Partnership | Open banking protocol alignment enables modular API architectures reducing exhibitor vendor lock-in exposure. |
Study Parameters
Bottom-up cinema operator deployment modeling reconciled against top-down hardware shipment tracking forms the analytical core of this study. Primary interviews with multiplex operations directors, POS procurement managers, cinema technology integrators, and RBI compliance officers combined with secondary validation from SEC filings, customs import records, and PCI-DSS certification databases. Triangulation across exhibitor capex disclosures and vendor revenue segmentations ensures cross-source consistency.
Input-output matrix framing maps kiosk terminal shipments against multiplex construction permits and SaaS subscription bookings across the projection horizon. Segmentation dimensions modeled include deployment architecture, circuit scale tier, integration complexity level, and regional regulatory cluster. CAGRs derive from deployment cycle timing, replacement wave synchronization, and digital payment penetration trajectories. Forecast inputs incorporate RBI interoperability mandate compliance deadlines and PCI-DSS 4.0 certification timeline compression effects.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to semiconductor supply disruption and geopolitical friction in Asian foundry regions. Forecasts reflect documented assumptions regarding cloud migration velocity and self-service kiosk adoption curves. A model refresh is warranted upon material change in RBI digital payment specification updates or PCI-DSS compliance deadline adjustments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Global Mobile Content Management Market
Digital Solutions
Digital Twin Market
Digital Solutions
Epedigree Software Market
Digital Solutions
Returnless Refund Fraud Detection Market
Digital Solutions
Global IC Card/Smart Card Market
Digital Solutions
North America Smart Card Market
Digital Solutions
Australia Digital Marketing Software Market
Digital Solutions
North America Everything As a Service (Xaas) Market
Digital Solutions
Container Management Software Market
Digital Solutions
Product As a Service Market
Digital Solutions
Digital Workplace Technologies Market
Digital Solutions
Global Network Engineering Service Market
Digital Solutions
Procure-To-Pay Solutions Market
Digital Solutions
Lecture Capture Solutions Market
Digital Solutions
Global Ad Tech Software Market
Digital Solutions
Singapore System Integration Market