
 Digital Project Delivery Solutions Market | 2026-2036
Digital Project Delivery Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Project Delivery Solutions Market Outlook
Cloud-to-edge orchestration is fragmenting legacy monolithic project management architectures into modular, API-first platforms. Autodesk leverages deep BIM interoperability to anchor design-to-construction workflows across major infrastructure programs. Oracle Corporation competes through database-centric integration of financial and scheduling systems within unified cloud environments. Procore Technologies specializes in field-centric mobile collaboration, extending its position through subcontractor network density rather than top-down enterprise sales.
Digital project delivery solutions encompass software platforms that coordinate design, construction, and operational data through federated model servers, 4D/5D simulation engines, and real-time IoT telemetry ingestion from job sites. Their primary commercial purpose is to compress project timelines and reduce rework by maintaining a single source of truth across geographically dispersed teams. Building Information Modeling occupies the largest value pool due to regulatory mandates for digital handover in public infrastructure, while Artificial Intelligence within the Technology segment represents the fastest-expanding margin layer as predictive risk analytics displace manual schedule buffering. Cloud-Based Management solutions sustain premium pricing through multi-tenant architectures that eliminate on-premise server maintenance for mid-tier contractors.
The EU Cyber Resilience Act and ISO 19650 series are elevating software security and information management standards, forcing vendors to embed compliance tooling directly into platform offerings. The US National Institute of Standards and Technology framework and OSHA digitization directives are accelerating federal construction project requirements for traceable digital documentation. Stakeholders must evaluate vendor roadmaps for native AI governance features before regulatory deadlines harden procurement criteria.
Market Dynamics
Cloud-to-edge orchestration is fragmenting legacy monolithic project management architectures into modular, API-first platforms that compress coordination timelines across dispersed construction teams.
Growth Catalysts
- ISO 19650 mandates:Digital handover requirements for public infrastructure in the United Kingdom, Singapore, and Australia are forcing asset owners to procure federated model servers before project commencement.
- Real-time IoT telemetry:Field sensor networks capturing concrete curing data and equipment utilization metrics are reducing rework cycles by maintaining continuous as-built documentation.
- Subcontractor network density:Mobile-first collaboration platforms are concentrating adoption among mid-tier mechanical and electrical trades that coordinate through shared schedule feeds rather than document exchanges.
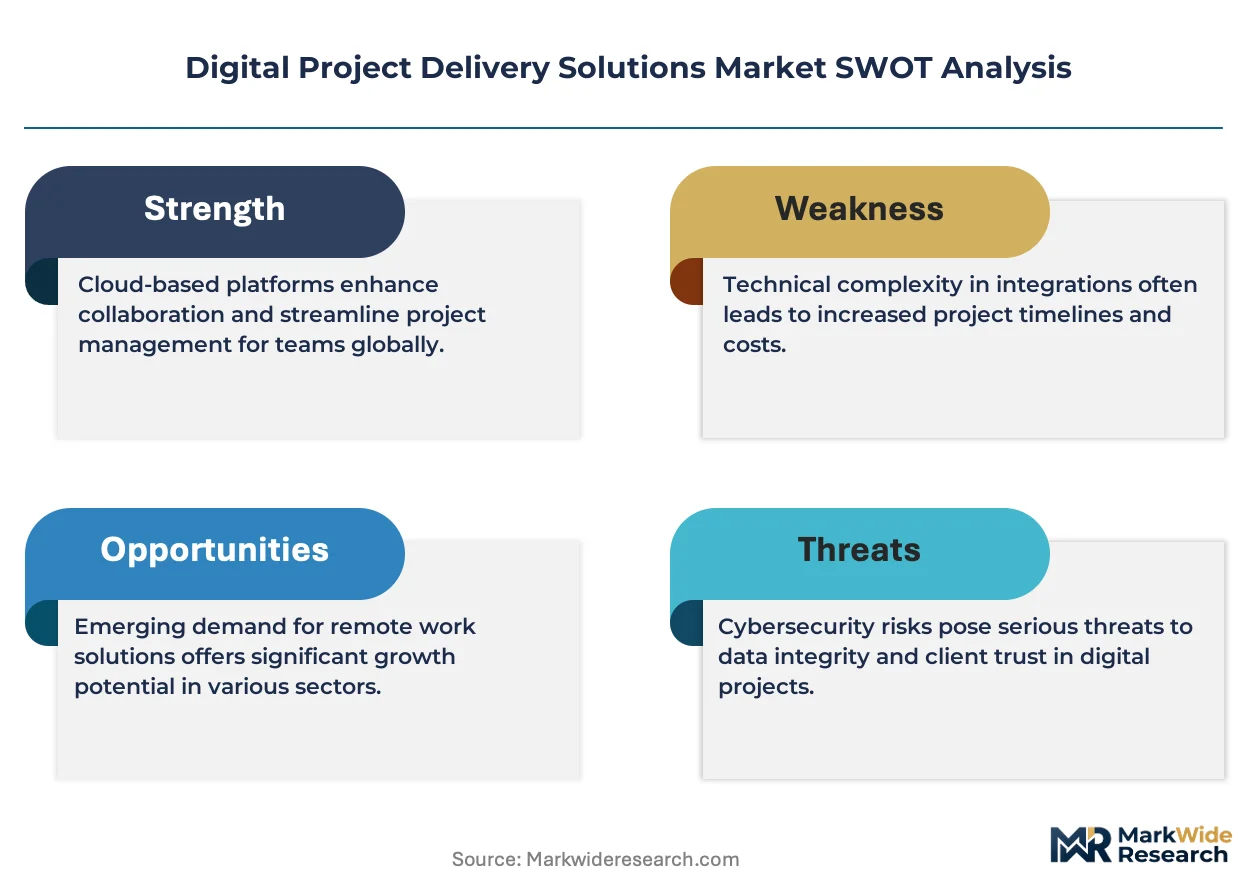
Market Restraints
- Legacy system integration costs:On-premise ERP installations from the 2010s require expensive middleware to connect with cloud-native platforms, delaying procurement decisions at established contractors.
- Cybersecurity compliance burden:The EU Cyber Resilience Act mandates embedded security tooling that extends vendor development cycles and elevates platform pricing beyond mid-market budgets.
- Data sovereignty fragmentation:Divergent national cloud storage requirements across Germany, France, and China are forcing vendors to maintain region-specific instances that dilute multi-tenant economies.
Strategic Opportunities
- AI governance tooling:Native algorithmic audit features that satisfy emerging NIST AI Risk Management Framework requirements will harden into procurement criteria for federal construction programs.
- 4D/5D simulation convergence:Integration of schedule-linked cost modeling with generative design engines opens new workflows for design-build contractors pursuing fixed-price delivery.
- India infrastructure digitization:The country's National Infrastructure Pipeline and Smart Cities Mission are creating first-mover advantages for platforms that localize BIM compliance to Indian Standard codes.
Industry Challenges
- VDC technician scarcity:Virtual design and construction specialists capable of federating discipline models command salary premiums that strain regional contractor margins.
- API standardization delays:Proprietary data exchange formats between competing platforms force project teams to maintain redundant model servers that fragment the single source of truth.
- OSHA digitization compliance:Traceable safety documentation requirements demand reconfiguration of field data capture workflows without established vendor certification pathways.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Project Delivery Solutions Market |
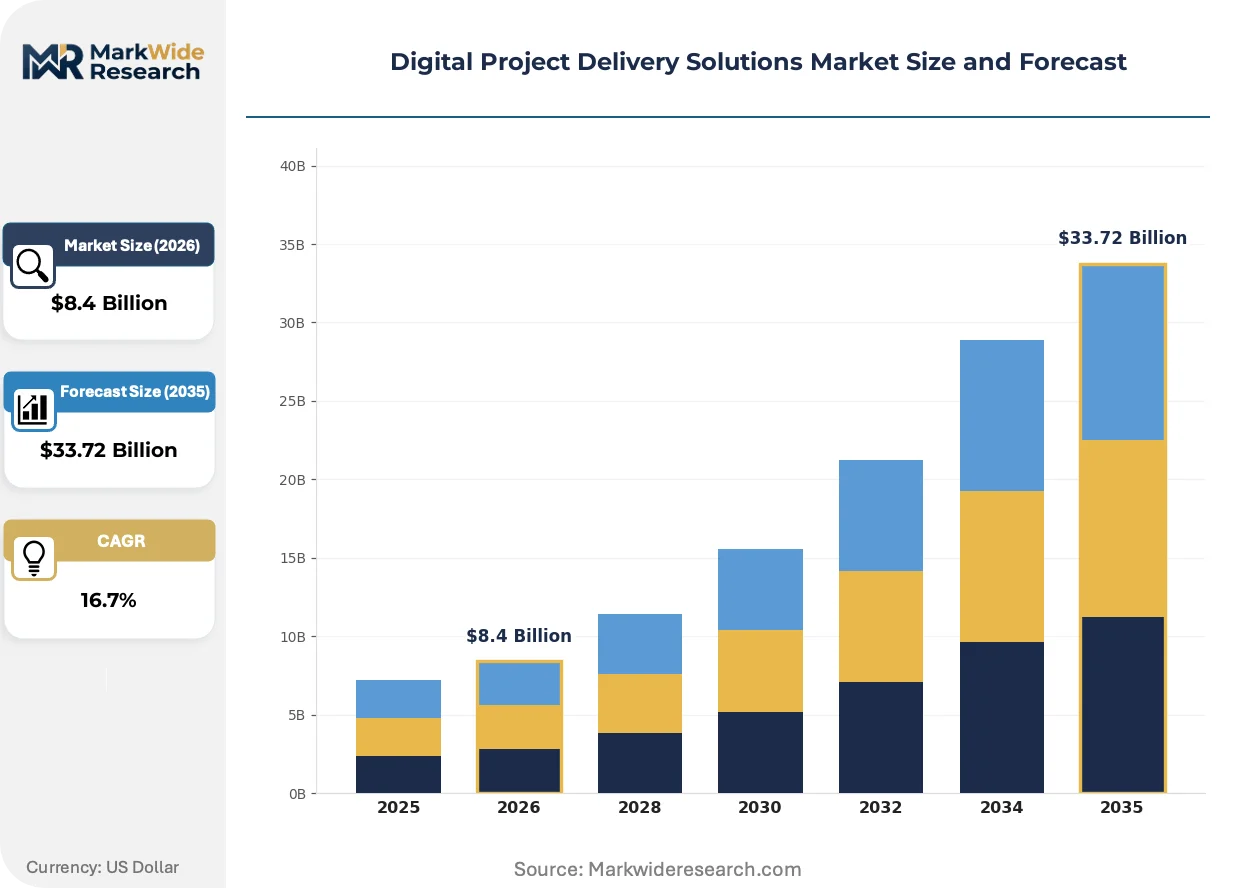
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $33.72 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Building Information Modeling, Cloud-Based Management, Project Management Software, Collaboration Tools Client Type: Construction Firms, Property Developers, Engineering Consultants, Government Agencies Technology: Augmented Reality, Artificial Intelligence, Internet of Things, Virtual Reality End User: Project Managers, Architects, Contractors, Stakeholders |
| Companies Covered | Autodesk Inc., Oracle Corporation, Bentley Systems, Procore Technologies, Trimble Inc., Hexagon AB, InEight Inc., PlanGrid, Viewpoint, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Project Delivery Solutions Market Strategic Shifts
Generative AI is compressing design iteration cycles while regulatory mandates harden software security requirements into procurement specifications.
Digital twin platforms integrating real-time IoT field data with BIM geometry are rendering obsolete static as-built documentation that required manual survey verification. Large-scale commercial developers in the United States are deploying these systems across multi-phase campus expansions. The structural consequence is collapsing handover timelines from months to weeks by maintaining continuous asset registries.
The EU Cyber Resilience Act is mandating embedded vulnerability management and software bill of materials disclosure for infrastructure technology procurement. Vendors must now maintain continuous security update pipelines that extend operational overhead. European public works agencies are responding by consolidating vendor qualification lists around platforms with native compliance tooling.
Subscription-based platform access is displacing perpetual license purchases among mid-tier contractors seeking to eliminate server maintenance capital. Design-build firms in Australia and Canada are piloting usage-based pricing tied to project data volumes rather than seat counts. This shift concentrates vendor risk in customer retention rather than upfront license recovery.
Digital Project Delivery Solutions Market Segmentation
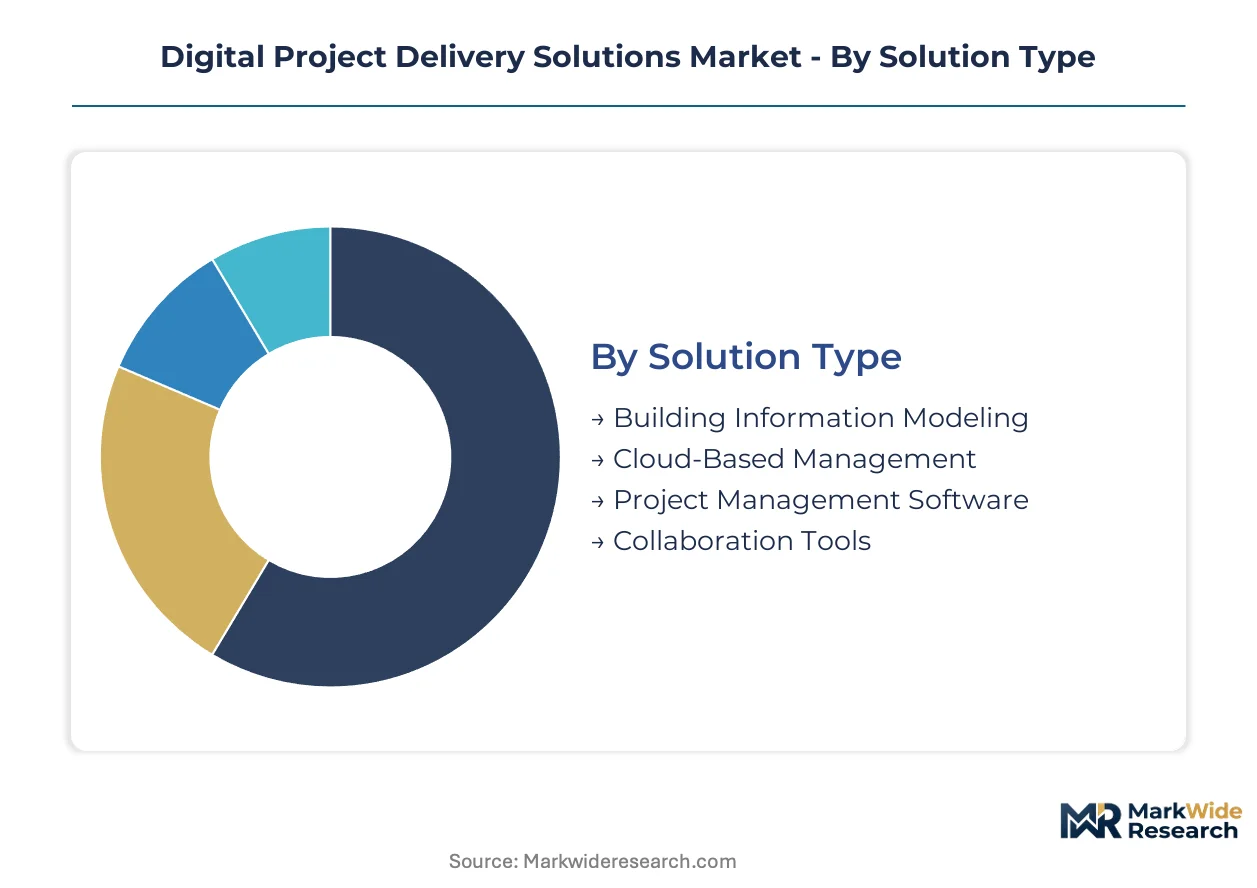
Segmentation in digital project delivery solutions reveals how procurement authority, technical sophistication, and workflow integration requirements fragment demand across incompatible platform architectures. Vendors must align feature roadmaps with distinct buyer capabilities rather than pursuing universal applicability.
Solution Type:
Cost tier differentiation separates enterprise-grade federated systems from lightweight collaboration tools targeting mid-market contractors with limited IT infrastructure.
- Building Information Modeling:Federated model servers coordinate discipline-specific geometry, cost, and schedule data through ISO 19650-compliant common data environments. Public infrastructure mandates in the United Kingdom, Singapore, and Australia concentrate procurement among asset owners requiring digital handover compliance.
- Cloud-Based Management:Multi-tenant SaaS architectures eliminate on-premise server maintenance for regional contractors managing distributed project portfolios. United States mid-tier mechanical and electrical trades drive subscription growth through mobile-first field coordination rather than document-centric workflows.
- Project Management Software:Schedule-critical path engines with resource leveling algorithms serve established contractors with legacy ERP integration requirements.
- Collaboration Tools:Real-time markup and RFQ platforms address subcontractor network density needs without full BIM infrastructure investment.
Building Information Modeling holds installed capacity. Cloud-Based Management is rotating up the share rankings.
Client Type:
Customer type determines platform complexity thresholds, with government procurement mandating compliance tooling that private developers often bypass.
- Construction Firms:General contractors with self-perform capabilities require field-to-office data loops capturing equipment utilization and labor productivity metrics. Large-scale commercial developers in the United States prioritize BIM-to-IoT integration for multi-phase campus expansions.
- Government Agencies:Federal construction programs under NIST and OSHA digitization directives demand traceable safety documentation and algorithmic audit features. Procurement specifications increasingly embed native AI governance requirements before vendor qualification.
- Property Developers:Asset owners seeking operational handover data specify federated model servers at project commencement.
- Engineering Consultants:Design-build coordination drives demand for 4D/5D simulation convergence in fixed-price delivery structures.
Construction Firms command current deployment volumes. Government Agencies are climbing the fastest as regulatory deadlines harden procurement criteria.
Technology:
Application maturity varies sharply, with predictive analytics displacing manual processes while immersive visualization remains pilot-stage for most contractors.
- Artificial Intelligence:Predictive risk analytics and generative design engines compress schedule iteration cycles while satisfying emerging NIST AI Risk Management Framework requirements. Federal construction programs in the United States are mandating native algorithmic audit features as procurement preconditions.
- Internet of Things:Field sensor networks capturing concrete curing data and equipment telemetry maintain continuous as-built documentation without manual survey verification. Real-time telemetry is collapsing handover timelines from months to weeks among large-scale developers.
- Augmented Reality:Overlay visualization for field installation verification remains limited to specialized MEP contractors with VDC technician capacity.
- Virtual Reality:Immersive design review sessions target high-complexity healthcare and laboratory projects with stakeholder alignment challenges.
Internet of Things maintains deployment breadth. Artificial Intelligence is gaining share fastest as compliance tooling becomes mandatory.
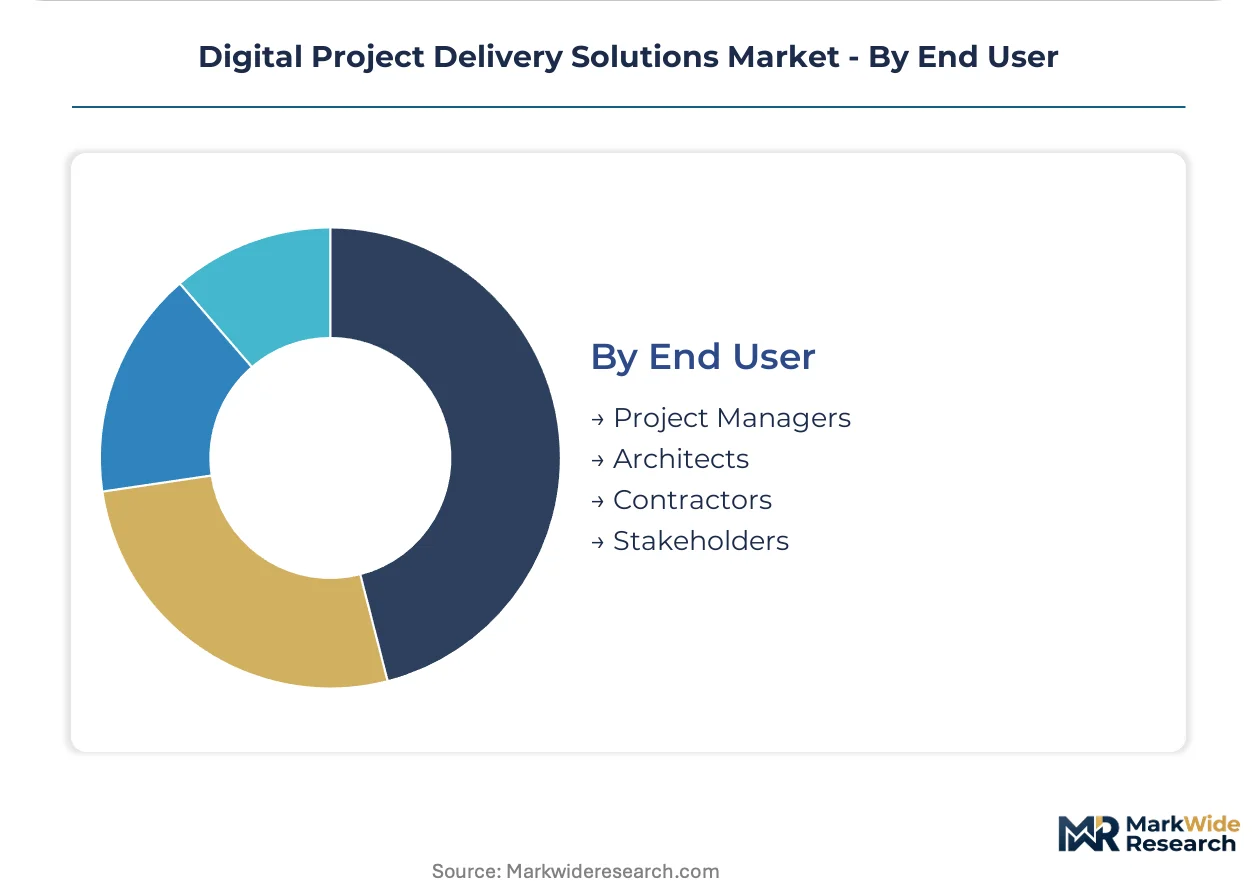
End User:
Workflow role dictates interface complexity, with field personnel requiring mobile-optimized capture tools that clash with office-based analytical dashboards.
- Contractors:Field superintendents and foremen drive mobile-first platform adoption through subcontractor network density rather than top-down enterprise mandates. Real-time schedule feeds and safety documentation capture dominate feature requirements.
- Project Managers:Cross-functional coordination authority creates demand for unified financial and scheduling system integration within cloud environments.
- Architects:Design iteration workflows prioritize BIM interoperability and generative engine compatibility.
- Stakeholders:Non-technical asset owners require simplified visualization interfaces abstracting underlying model complexity.
Contractors anchor field deployment volumes. Project Managers are expanding fastest as cloud-to-edge orchestration fragments legacy architectures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Large-scale commercial developers in the United States concentrate procurement authority for digital project delivery platforms, while government mandates in Europe and Asia-Pacific harden compliance requirements into vendor qualification criteria.
United States
Federal construction programs under NIST and OSHA digitization directives mandate traceable safety documentation and algorithmic audit features. The National Institute of Standards and Technology framework accelerates requirements for federated model servers on infrastructure projects. Large-scale commercial developers in Texas and California deploy BIM-to-IoT integration across multi-phase campus expansions, collapsing handover timelines through continuous asset registries.
United Kingdom
ISO 19650 digital handover mandates force asset owners to procure common data environments before public infrastructure commencement. The Building Safety Regulator enforces stricter software accountability for high-risk building projects. Engineering consultancies in London anchor design-build coordination demand, driving 4D/5D simulation convergence for fixed-price delivery structures.
Germany
Divergent federal-state cloud storage requirements force vendors to maintain region-specific instances that dilute multi-tenant economies. The national implementation of EU Cyber Resilience Act standards elevates embedded security tooling into procurement specifications. Industrial construction clusters in Bavaria and North Rhine-Westphalia prioritize ERP integration with legacy manufacturing execution systems.
Australia
State-level digital engineering mandates in New South Wales and Victoria mirror UK ISO 19650 adoption timelines. The Australian Building Codes Board advances performance-based compliance frameworks requiring continuous as-built documentation. Design-build firms in Sydney and Melbourne pilot usage-based pricing tied to project data volumes rather than seat counts.
Singapore
Building and Construction Authority mandates for digital delivery on public projects concentrate procurement among asset owners requiring BIM compliance. The Smart Nation infrastructure program accelerates IoT sensor deployment for real-time construction monitoring. Developer consortiums in the Greater Southern Waterfront district integrate digital twin platforms across integrated resort and commercial developments.
Digital Project Delivery Solutions Market Competitive Environment
Channel-controlling players compete with product-specialist players across three distinct tiers: enterprise-grade federated platform providers, mid-market SaaS collaborators, and field-centric mobile specialists. Market structure tilts toward consolidation at the top tier where database-centric integration and deep BIM interoperability create switching costs, while fragmentation persists among subcontractor-facing tools. Strategic archetypes include design-to-construction workflow anchors, financial-scheduling system unifiers, and network-density field collaborators. Dominant competitive moves encompass API-first platform modularization and embedded compliance tooling development.
Within the enterprise workflow anchor tier, Autodesk Inc. and Oracle Corporation occupy positions representing divergent integration philosophies. Autodesk exemplifies the design-originating platform archetype leveraging geometry-centric interoperability, while Oracle Corporation sits within the database-native unifier category prioritizing financial and scheduling system consolidation. Procore Technologies represents the field-centric network density model, extending positioning through subcontractor ecosystem penetration rather than top-down enterprise mandates.
| Leading Market Players |
|---|
| Autodesk Inc. |
| Oracle Corporation |
| Bentley Systems |
| Procore Technologies |
| Trimble Inc. |
| Hexagon AB |
| InEight Inc. |
| PlanGrid |
| Viewpoint |
| Others |
Value Chain & Pricing Dynamics
San Francisco Bay Area cloud infrastructure clusters concentrate platform development capacity, concentrating vendor bargaining power over mid-tier contractors seeking multi-tenant SaaS alternatives to on-premise server maintenance. This geographic concentration of engineering talent feeds downstream into subscription pricing tiers that stratify by integration complexity rather than raw feature count.
Pricing Analysis
Cost-plus contracts with labor rate indexation dominate federal construction program procurement, embedding annual escalation clauses tied to Bureau of Labor Statistics data. Three-tier pricing structure across premium, standard, and economy levels separates enterprise federated platforms from mid-market SaaS and lightweight subcontractor tools. Price differentiation hinges on ISO 19650 certification tier and after-sales implementation support depth. Cost compression in the standard tier is intensifying because EU Cyber Resilience Act compliance tooling extends vendor development overhead. Mid-market mechanical and electrical trades exhibit highest price sensitivity, while asset owners mandate premium tiers regardless of cost.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities anchor vendor working capital structures, with platform providers offering 60-90 day terms to large general contractors. Engineering talent concentrates in the United States, United Kingdom, and India, with Bangalore development centers supporting localization for Indian Standard code compliance. Raw material dependencies span cloud compute capacity, IoT sensor hardware, and specialized BIM geometry processing engines. Single-source vulnerability in hyperscaler cloud infrastructure poses structural risk. Distribution runs through direct enterprise sales for federated platforms and channel partners for subcontractor-facing mobile tools.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as ISO 19650 mandates penetrate beyond UK and Singapore into Australia and emerging Asian infrastructure programs. Regulatory deadlines are compressing procurement timelines and forcing first-mover advantages among compliant vendors.
For Market Incumbents: Pre-empt API standardization fragmentation by anchoring federated model server interoperability before proprietary formats harden competitive moats. Defend position by embedding native AI governance tooling that satisfies NIST framework requirements ahead of federal procurement deadlines. Prioritize backward integration into IoT sensor hardware partnerships to secure telemetry data pipeline control. For New Entrants and Emerging Players: Pursue white-space opportunity in India infrastructure digitization, where National Infrastructure Pipeline projects lack localized BIM compliance platforms. Target mid-tier design-build contractors in Australia seeking usage-based pricing alternatives to seat-count subscriptions. Lead with mobile-first field coordination for mechanical and electrical trades rather than top-down enterprise sales. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors field-centric network density platforms over document-centric workflow tools, as subcontractor ecosystem penetration generates stickier retention than feature breadth. Five-to-ten year viability hinges on compliance tooling moats rather than raw functionality. Acquisition targets should demonstrate native EU Cyber Resilience Act and NIST AI Risk Management Framework feature sets. The signal to watch is consolidation of vendor qualification lists around platforms with embedded security update pipelines.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API-first modularization compresses coordination timelines across dispersed construction teams. |
| Acquisition of Specialist Firm | VDC technician capacity scarcity drives consolidation of federated modeling expertise. |
| Strategic Partnership | IoT sensor hardware alliances secure continuous as-built documentation pipelines. |
| Geographic Expansion | India Standard code localization captures National Infrastructure Pipeline procurement. |
| Product Launch | Native AI governance tooling satisfies emerging federal algorithmic audit requirements. |
Study Parameters
Cross-validation between primary stakeholder interviews and secondary regulatory filings anchors the qualitative findings in documented compliance trajectories. Primary fieldwork encompassed platform engineering leads, federal construction program procurement officers, VDC technicians at regional contractors, and BIM compliance consultants. Secondary sources included ISO 19650 implementation guidelines, NIST cybersecurity framework documentation, EU Cyber Resilience Act legislative texts, and national infrastructure agency procurement specifications. Bottom-up project pipeline analysis and top-down regulatory mandate sizing were triangulated against vendor-reported deployment metrics.
Calibration against historical adoption curves in UK and Singapore public infrastructure programs informs the projection framework. The analytical framework segments by solution type, client category, technology application, and end-user workflow role across the modeling period. CAGRs derive from penetration rate assumptions tied to regulatory deadline schedules and cloud infrastructure cost trajectories. Key inputs include ISO 19650 mandate expansion timelines, federal construction program digitization directives, and IoT sensor hardware cost decline curves.
Sensitivities concentrate around regulatory deadline delays, hyperscaler cloud pricing volatility, and VDC technician supply constraints. Forecasts reflect assumptions on mandate enforcement consistency and mid-tier contractor SaaS migration willingness. Macroeconomic contraction in commercial construction, cybersecurity incident liability expansion, or generative AI capability breakthroughs would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Virtual Desktop Infrastructure (VDI) Market
Digital Solutions
Electronic Data Interchange (EDI) Market
Digital Solutions
Serverless Architecture Market
Digital Solutions
Mock Interview Platforms Market
Digital Solutions
Latin America IT Market
Digital Solutions
Cloud Backup and Recovery Market
Digital Solutions
Connected Stadium Solution Market
Digital Solutions
Global Work Order Management Systems Market
Digital Solutions
AQI App Market
Digital Solutions
Multichannel Order Management Market
Digital Solutions
Global Workforce Productivity Systems Market
Digital Solutions
Global Automatic Content Recognition (ACR) Market
Digital Solutions
Japan Digital Twin Market
Digital Solutions
Cloud E-Signature Tools Market
Digital Solutions
Global Process Orchestration Market
Digital Solutions
Device As a Service (Daas) Market