
 Construction Design App Market | 2026-2036
Construction Design App Market Size, Share, and Industry Trends Forecast 2026-2036
Construction Design App Market Insights
Subscription-based software-defined feature layers is recalibrating how construction design platforms monetize capability access. Autodesk leverages its cloud-native infrastructure to anchor enterprise accounts across multi-disciplinary project teams. SketchUp competes through intuitive 3D modeling interfaces that dominate small-to-mid-sized architecture practices. Planner 5D specializes in consumer-adjacent home visualization, extending platform reach beyond professional users into renovation and real estate staging markets.
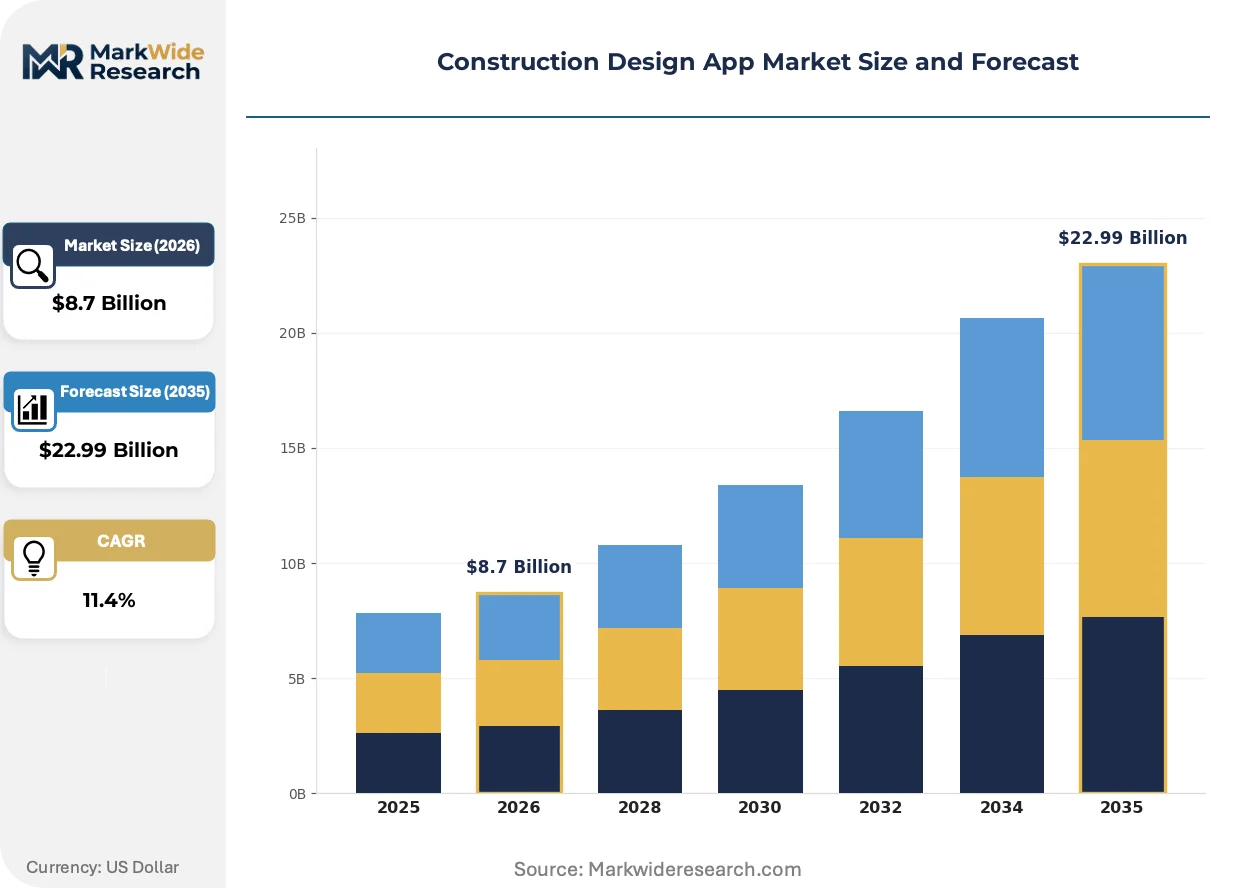
Construction design apps are software platforms that enable architectural visualization, structural calculation, and project coordination through parametric modeling engines, cloud rendering pipelines, and interoperable file formats such as IFC and DWG. Their primary commercial purpose is to compress design iteration cycles while reducing material waste and construction error rates through digital twin pre-validation. Cloud-based deployment now captures the dominant margin pool as vendors shift from perpetual licenses to recurring revenue architectures, while Building Information Modeling applications lead functional adoption due to mandate-driven compliance requirements in public infrastructure procurement. Artificial Intelligence technology segments represent the fastest-expanding capability layer, embedding generative spatial optimization and automated code-checking into core design workflows.
FDA oversight applies where design apps interface with medical facility construction, while OSHA standards shape workplace safety visualization requirements embedded in training modules. The EU AI Act imposes algorithmic transparency obligations on generative design tools deployed across European member states. Stakeholders must monitor how divergent regulatory timelines for AI governance across the United States and European Union reshape platform development roadmaps and cross-border certification costs.
Market Dynamics
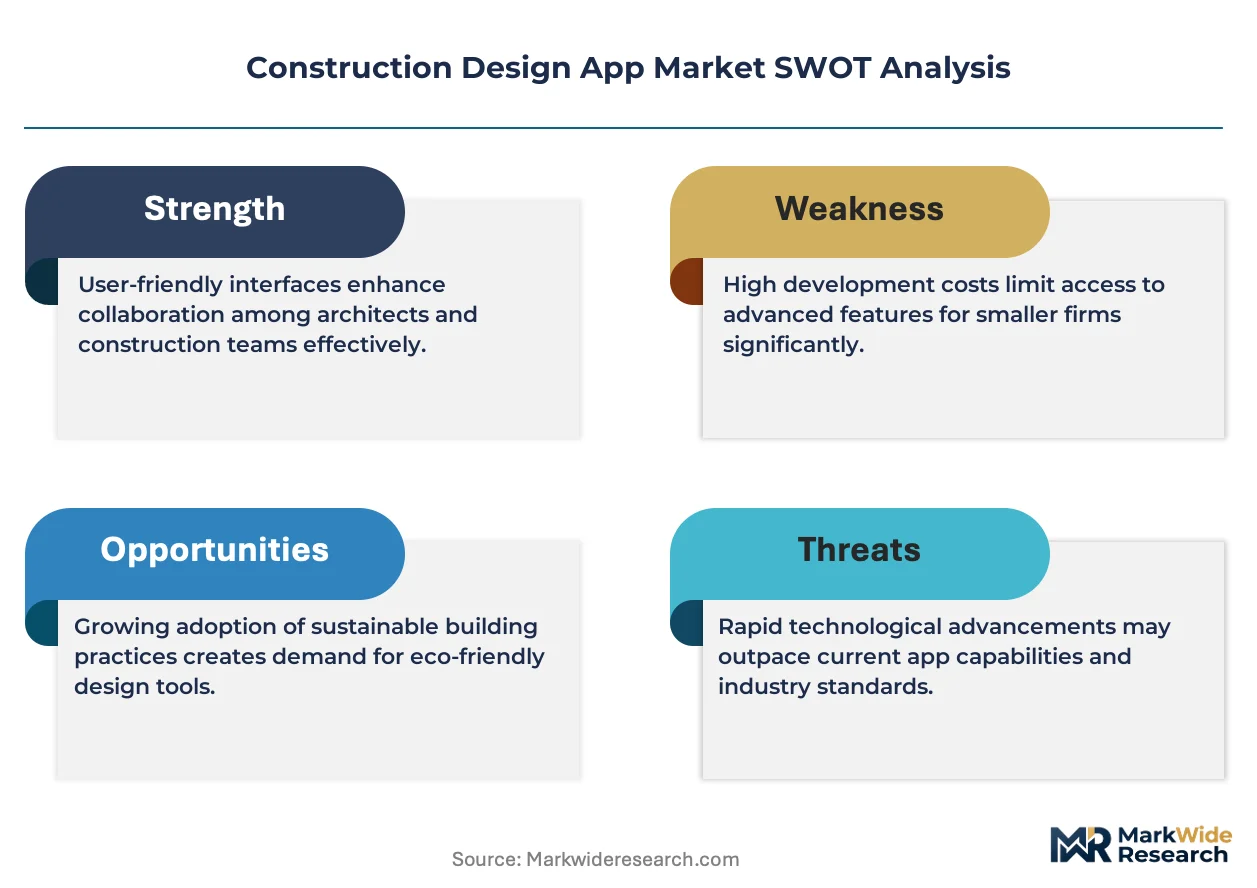
Cloud-native architecture migration is compressing deployment timelines while forcing incumbent vendors to abandon perpetual license revenue models in favor of recurring subscription streams. This structural shift is redistributing margin pools toward platform operators with established multi-tenant infrastructure.
Growth Catalysts
- Federal infrastructure spending:United States appropriations for bridge, transit, and water system modernization mandate digital design deliverables, accelerating BIM platform procurement among regional engineering consultancies.
- EU AI Act compliance frameworks:Algorithmic transparency requirements for generative spatial tools are creating certified vendor preference windows across German, French, and Dutch public procurement channels.
- Parametric modeling engines:Real-time structural optimization embedded in cloud rendering pipelines reduces material waste calculations from days to minutes, compressing pre-construction validation cycles.
Market Restraints
- Specialized cloud compute costs:GPU-intensive rendering workloads tie operating expenditure to volatile semiconductor foundry pricing, squeezing gross margins for mid-tier SaaS providers.
- Interoperability protocol fragmentation:Competing file format standards between IFC, DWG, and proprietary native formats force customers to maintain redundant translation layers, inflating total cost of ownership.
- Cyber-physical liability exposure:Design errors propagated through automated code-checking algorithms create unmapped professional indemnity gaps that insurers in London and Zurich markets have not yet priced.
Strategic Opportunities
- India's Smart Cities Mission:Municipal digitization mandates for urban planning approvals create entry points for cloud-based design platforms in Bangalore, Hyderabad, and Pune metropolitan development authorities.
- Generative AI convergence with IoT sensor feeds:Real-time construction site data streaming into design models enables adaptive specification updates that reduce change order frequency.
- Renovation and retrofit verticals:Existing building stock laser scanning integration opens consumer-adjacent markets beyond traditional architecture practice boundaries.
Industry Challenges
- Computational design literacy gaps:Architecture schools produce graduates proficient in manual drafting workflows but underprepared for node-based parametric scripting environments that employers now require.
- Legacy ERP integration friction:Established project accounting systems in mid-sized construction firms resist API connectivity with modern design platforms, forcing expensive middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Construction Design App Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Mobile, Web Application: Building Information Modeling, Project Collaboration, Cost Estimation, Time Scheduling, Resource Management End User: Architects, Civil Engineers, Structural Designers, Project Managers, Surveyors Technology: 3D Modeling, Virtual Reality, Augmented Reality, Artificial Intelligence, Drone Integration |
| Companies Covered | Autodesk, SketchUp, Archicad, Chief Architect, Planner 5D, Morpholio, Magicplan, Houzz, Home Design 3D, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Construction Design App Market Trends and Innovations
Artificial intelligence is embedding itself into core design workflows faster than regulatory frameworks can stabilize, creating temporary competitive advantage windows for first movers with compliant algorithmic transparency.
Diffusion-model generative design is electrifying spatial layout optimization by translating natural language prompts into code-compliant floor plans within seconds. Mid-sized architecture practices in Scandinavia and the Benelux region are adopting these tools at the fastest clip, compressing schematic design phases from weeks to days and enabling parallel optioneering that was previously economically unfeasible.
The EU AI Act's risk classification system for algorithmic decision-making in built environment applications is forcing vendors to rearchitect black-box optimization engines into interpretable, auditable workflows. German building code authorities now require explainability documentation for automated structural calculations, shifting procurement evaluation criteria toward transparency certifications rather than raw performance benchmarks.
Subscription fatigue among design practice principals is driving unbundling of platform capabilities into modular, usage-metered components. Smaller studios in Portugal and Spain are abandoning comprehensive suites for specialized point solutions connected through open APIs, fragmenting vendor account control and elevating interoperability as a primary purchasing criterion over native feature depth.
Construction Design App Market Segmentation
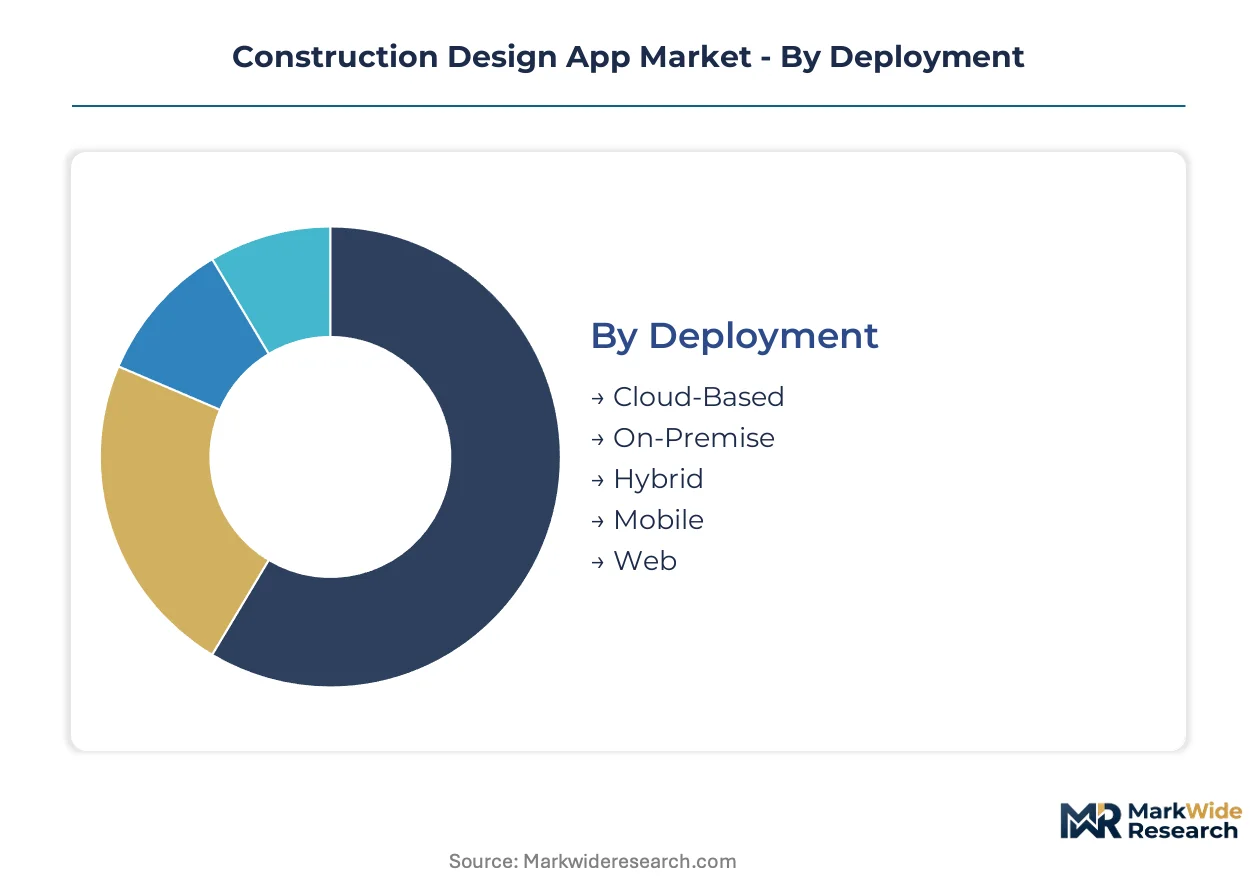
Construction design platforms fragment across deployment architectures, professional workflows, user skill levels, and immersive technologies. Understanding these divides clarifies where procurement budgets concentrate and which capability layers command premium pricing.
Deployment:
Standardization dominates at the infrastructure layer while customization proliferates at the interface tier, creating divergent margin structures across hosting models.
- Cloud-Based:Multi-tenant architectures with GPU-accelerated rendering pipelines serve distributed project teams. United States mid-sized architecture practices drive procurement as federal infrastructure mandates require digital deliverable submission.
- On-Premise:Air-gapped installations with localized compute clusters address data sovereignty requirements in German and French defense-adjacent construction projects. Higher upfront capital expenditure limits adoption to classified infrastructure and nuclear facility design.
- Hybrid:Sensitive model data remains on local servers while collaboration layers sync to cloud instances. Japanese mega-project consortia favor this architecture for Olympic-scale venue coordination.
- Mobile:Lightweight field inspection apps with offline markup capabilities. Site supervisors in India's Smart Cities Mission use these for municipal approval documentation.
- Web:Browser-native parametric editors eliminating client installation. Portuguese and Spanish studios adopt these for subscription flexibility amid platform unbundling trends.
Leading the category by volume: Cloud-Based. Expanding most quickly: Hybrid.
Application:
Functional modules align with project phase sequencing, from schematic conception through construction administration.
- Building Information Modeling:Parametric object libraries with automated clash detection and quantity extraction. Public procurement mandates in Germany, Netherlands, and United Kingdom require BIM deliverables for infrastructure tenders.
- Project Collaboration:Real-time model federation with version-controlled comment threading. Scandinavian multi-disciplinary teams compress design iteration cycles through these platforms.
- Cost Estimation:Quantity takeoff automation linked to regional material pricing databases. Mid-sized United States engineering consultancies deploy these for bridge and transit project bidding.
- Time Scheduling:4D model sequencing with critical path visualization. Australian commercial contractors integrate these with IoT sensor feeds for adaptive milestone tracking.
- Resource Management:Equipment and labor allocation optimization across concurrent projects. Indian metropolitan development authorities in Bangalore and Hyderabad use these for Smart Cities coordination.
BIM commands the largest installed base. Generative spatial tools within design collaboration are gaining share fastest.
End User:
Professional licensing requirements and software literacy gaps create distinct purchasing behaviors across technical disciplines.
- Architects:Schematic design and visualization workflows with emphasis on aesthetic iteration speed. Benelux and Scandinavian practices adopt diffusion-model generative tools for parallel optioneering.
- Civil Engineers:Infrastructure-specific calculation engines for transportation and water systems. United States regional consultancies procure these for federal bridge modernization programs.
- Structural Designers:Code-compliant analysis with automated load path verification. German authorities now mandate explainability documentation for algorithmic structural calculations under EU AI Act frameworks.
- Project Managers:Cross-disciplinary coordination dashboards with budget and schedule integration. Legacy ERP friction in mid-sized United States construction firms limits adoption.
- Surveyors:Point cloud processing and georeferenced model alignment. Laser scanning integration for existing building stock renovation opens consumer-adjacent markets in Spain and Portugal.
Architects represent the deepest penetration. Structural designers are adopting automated code-checking capabilities most rapidly.
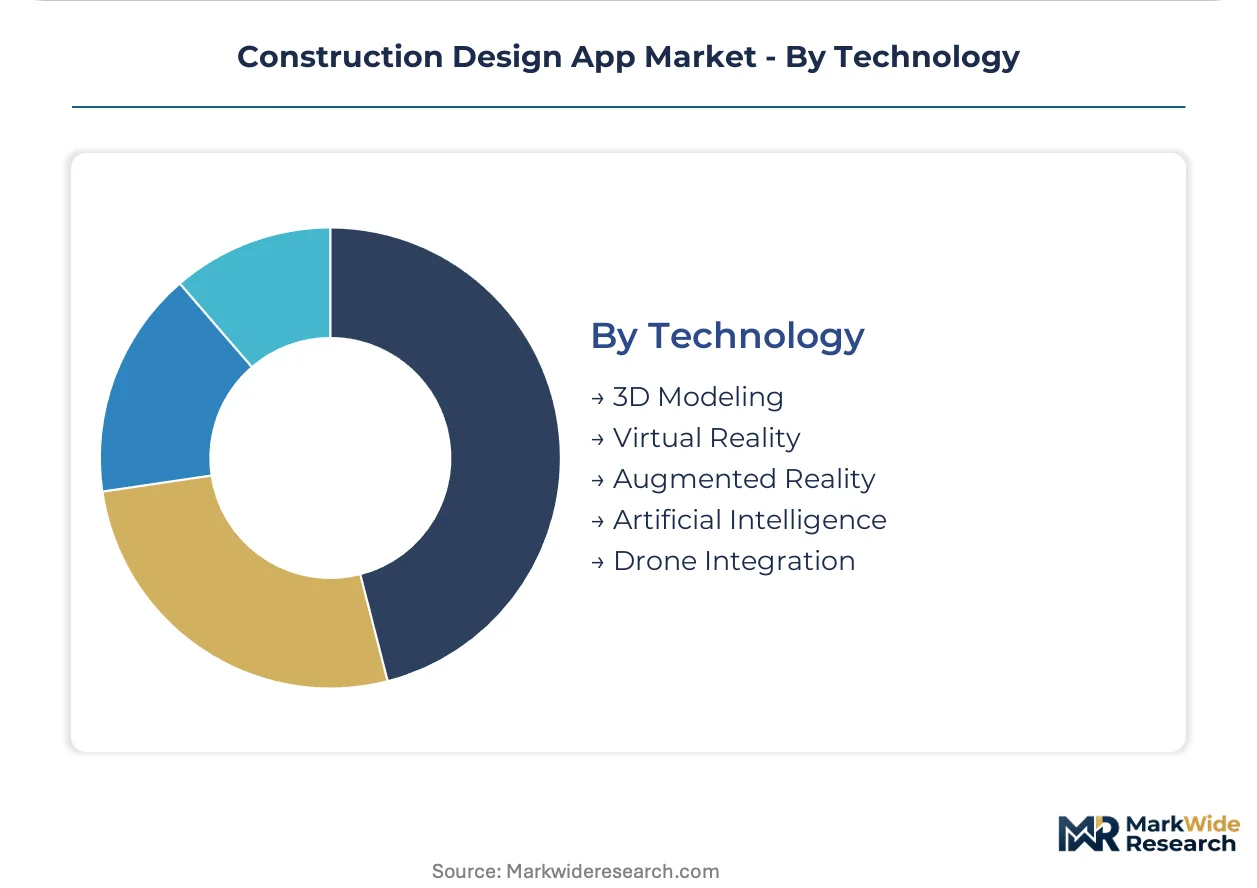
Technology:
Capability maturity varies from established geometric engines to emergent AI layers still awaiting regulatory stabilization.
- 3D Modeling:NURBS and mesh-based geometric kernels with parametric constraint solving. Foundation layer for all downstream visualization and analysis workflows.
- Virtual Reality:Immersive design review with spatial scale perception. Client presentation and stakeholder sign-off applications in high-end commercial projects.
- Augmented Reality:Site-overlay visualization for construction sequencing validation. Field crews in Japanese and South Korean infrastructure projects use these for underground utility avoidance.
- Artificial Intelligence:Generative spatial optimization and automated code-checking. EU AI Act algorithmic transparency requirements are rearchitecting black-box engines into auditable workflows.
- Drone Integration:Photogrammetric site capture with automated progress monitoring. Real-time construction data streaming enables adaptive specification updates reducing change order frequency.
3D Modeling anchors the technology stack. Artificial intelligence capability layers are climbing the fastest as vendors compete for compliant generative design positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
San Francisco anchors North American construction design app deployment, where venture-backed platforms cluster around cloud-native infrastructure development. Federal infrastructure mandates and state-level digitization programs are compressing procurement cycles across mid-sized architecture practices nationwide.
United States
Federal bridge and transit modernization programs mandate BIM deliverables, accelerating platform adoption among regional engineering consultancies. OSHA standards shape workplace safety visualization requirements embedded in training modules. Austin and Denver metropolitan development authorities pilot generative design tools for municipal planning approvals.
Germany
Public procurement channels for infrastructure tenders require BIM compliance, creating certified vendor preference windows. The EU AI Act imposes algorithmic transparency obligations on generative spatial tools deployed nationwide. Munich and Stuttgart engineering clusters adopt explainable structural calculation engines under updated building code frameworks.
India
The Smart Cities Mission drives municipal digitization mandates for urban planning approvals across metropolitan development authorities. BIS standards govern interoperability protocols for public infrastructure design submissions. Bangalore and Hyderabad consortia deploy cloud-based coordination platforms for concurrent multi-project resource allocation.
Japan
Olympic-scale venue coordination established hybrid deployment architectures as standard for mega-project consortia. METI guidelines encourage construction technology adoption through public-private partnership frameworks. Tokyo and Osaka metropolitan authorities integrate augmented reality site-overlay tools for underground utility avoidance.
United Kingdom
Public infrastructure procurement mandates BIM Level 2 compliance, standardizing digital deliverable formats across government tenders. CE marking requirements influence platform certification for cross-border project deployment. London and Manchester architecture practices lead adoption of diffusion-model generative tools for schematic optioneering.
Construction Design App Market Competitive Landscape
Capital-heavy platform operators compete with asset-light specialized developers across deployment architectures and user segments. The market exhibits tiered concentration, with established cloud-native infrastructure providers anchoring enterprise accounts while nimble point-solution vendors fragment mid-market procurement. Three archetypes dominate: comprehensive suite providers with multi-tenant SaaS foundations, intuitive interface specialists targeting small-to-mid-sized practices, and consumer-adjacent visualization platforms extending into renovation markets. Competitive dynamics center on strategic partnerships for ERP integration and portfolio diversification into generative AI capability layers.
Within the comprehensive suite tier, Autodesk and Archicad occupy positions anchoring multi-disciplinary project coordination across enterprise accounts. SketchUp exemplifies the interface-specialist archetype, its accessibility profile dominating small-to-mid-sized architecture practices in North America and Europe. Planner 5D represents the consumer-adjacent extension model, its home visualization tools reaching renovation and real estate staging markets beyond traditional professional boundaries.
| Leading Market Players |
|---|
| Autodesk |
| SketchUp |
| Archicad |
| Chief Architect |
| Planner 5D |
| Morpholio |
| Magicplan |
| Houzz |
| Home Design 3D |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up cloud infrastructure specialists anchor supply-side discipline across North American and European markets, translating GPU cluster ownership into subscription pricing power while compressing margins for asset-light SaaS competitors. Their captive data center investments insulate enterprise-tier vendors from semiconductor foundry volatility, forcing mid-tier providers toward modular, usage-metered unbundling that fragments account control.
Pricing Analysis
Outcome-based pricing anchors enterprise procurement, with platform fees tied to project throughput metrics and cloud rendering volume rather than seat counts. Three-tier pricing structure across premium, standard, and economy levels separates Autodesk's multi-tenant enterprise suites from SketchUp's mid-market accessibility and Planner 5D's consumer-adjacent freemium tiers. Price differentiation hinges on AI capability depth and BIM certification grade, with German and Dutch public procurement channels mandating explainability documentation that commands 15-20% premiums. Pricing pressure stems from subscription fatigue among Portuguese and Spanish studios abandoning comprehensive suites for specialized point solutions. Small-to-mid-sized architecture practices exhibit highest price sensitivity, while federal infrastructure contractors in the United States demonstrate lowest elasticity due to mandate-driven procurement.
Supply Chain Analysis
Freight costs for GPU accelerator shipments from Taiwan and South Korea concentrate supply risk for cloud rendering infrastructure, with semiconductor foundry pricing volatility directly compressing SaaS gross margins. The construction design app supply chain draws from Taiwanese semiconductor fabrication, South Korean memory module production, and United States hyperscaler data center operations. Raw material dependencies span advanced node GPUs, high-bandwidth memory stacks, and specialized optical interconnects. Single-source vulnerability around NVIDIA's AI training silicon creates procurement bottlenecks for generative design feature deployment. Distribution runs through direct enterprise sales teams for comprehensive suites, self-serve web portals for mid-market accessibility, and mobile app stores for consumer-adjacent visualization tools.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The construction design app sector occupies a technology-transition phase where diffusion-model generative AI displaces legacy parametric scripting workflows, compressing schematic design cycles from weeks to days while mandating algorithmic transparency investments.
For Market Incumbents: Extend cloud-native infrastructure moats through backward integration into GPU cluster ownership, insulating enterprise accounts from foundry pricing volatility while accelerating generative feature deployment. Acquire specialized point-solution vendors in laser scanning integration and IoT sensor feed processing to preempt fragmentation of account control. The EU AI Act's explainability mandates threaten black-box optimization engines; certification investment in German and Dutch public procurement channels serves as the priority defensive lever. For New Entrants and Emerging Players: Mid-sized renovation contractors in Spain and Portugal represent an underserved buyer archetype with minimal existing BIM penetration and acute price sensitivity driving platform unbundling adoption. Target municipal planning authorities in India's Smart Cities Mission, where digitization mandates create certified vendor preference windows without entrenched incumbent relationships. Deploy browser-native web editors with open API architectures to capture subscription-fatigued studios abandoning comprehensive suites. For Investors and Strategic Acquirers: Distressed-cycle entries favor vertically integrated cloud infrastructure operators with captive GPU supply in United States and German markets, where federal infrastructure spending and EU AI Act compliance create dual demand tailwinds. Long-term viability hinges on generative AI capability depth and algorithmic transparency certification rather than legacy geometric engine IP. Watch BIM mandate expansion into Indian and Japanese public procurement channels as the inflection signal for geographic diversification returns.| Strategic Initiative | Industry Significance |
|---|---|
| Generative AI Capability Integration | EU AI Act compliance in German public tenders mandates explainable algorithmic transparency documentation. |
| GPU Cluster Backward Integration | Captive infrastructure insulates Autodesk's enterprise accounts from Taiwan foundry pricing volatility. |
| Laser Scanning Point-Solution Acquisition | Existing building stock renovation in Spain and Portugal opens consumer-adjacent market extension. |
| Open API Architecture Deployment | Portuguese and Spanish studios fragment procurement toward modular, usage-metered component unbundling. |
| Indian Smart Cities Channel Partnership | Bangalore and Hyderabad municipal authorities require cloud-based coordination for multi-project resource allocation. |
Research Methodology
Document review covered SEC filings from cloud infrastructure providers, EU regulatory transparency databases, and Indian Smart Cities Mission procurement records, complemented by interviews with platform engineering directors, architecture firm principals, municipal planning authority technology officers, and construction ERP integration specialists. Secondary validation drew from Autodesk and Trimble financial disclosures, BIS interoperability standard publications, and German building code authority algorithmic certification guidelines. Bottom-up segment sizing triangulated against top-down infrastructure spending forecasts across federal, state, and municipal procurement channels.
Cross-referencing historical adoption curves from BIM mandate rollouts with panel input from Scandinavian and Benelux early adopters calibrated generative AI penetration assumptions across the analysis window. Segmentation dimensions modeled deployment architecture, professional workflow application, end-user discipline, and technology capability layer. CAGRs derived from slope-consistency checks against cloud SaaS comparable trajectories and infrastructure software category benchmarks. Industry-specific inputs incorporated EU AI Act implementation timelines and United States federal appropriations cycle phasing.
Revisions become necessary when semiconductor foundry capacity constraints intensify, EU AI Act enforcement timelines accelerate, or Indian municipal digitization mandates expand beyond current metropolitan authority pilots. Forecasts reflect assumptions about algorithmic transparency cost curves and subscription fatigue saturation points. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Canada ICT Market
Digital Solutions
Utility Cases Market
Digital Solutions
Global Corporate Volunteering Platform Market
Digital Solutions
Enterprise Content Management (ECM) Market
Digital Solutions
Asia-Pacific Digital Pen Market
Digital Solutions
Global Enterprise Information Archiving Market
Digital Solutions
Global E-Filing Platforms Market
Digital Solutions
Precision Agriculture Software Market
Digital Solutions
Automatic Identification and Data Capture Market
Digital Solutions
Smart Connected Assets and Operations Market
Digital Solutions
Global Asset Tracking and Inventory Management Solutions Market
Digital Solutions
Transport Management System Market
Digital Solutions
Digital Manufacturing Market
Digital Solutions
Product Lifecycle Management Consumer Packaged Goods and Retail (PLM Cpandr) Market
Digital Solutions
IT Asset Management (ITAM) Software Market
Digital Solutions
Telecom Site Management Software Market