
 Automated Waste Collection System (AWCS) Market | 2026-2036
Automated Waste Collection System (AWCS) Market Size, Share, and Industry Trends Forecast 2026-2036
Automated Waste Collection System (AWCS) Market Intelligence
Procurement for large-scale AWCS projects is hardening around a concentrated group of municipal authorities and major facility management firms. Envac AB leverages its extensive project portfolio in dense urban centers to secure municipal contracts. MariMatic Oy differentiates through its specialization in vacuum conveying systems for unique applications like hospitals and airports. Caverion Corporation competes by integrating AWCS within broader building and industrial service packages for its clients.
An automated waste collection system is an infrastructure solution that transports solid waste through a network of underground or concealed pneumatic tubes. Utilizing powerful vacuum suction, these systems move refuse from multiple inlet points to a central collection station, eliminating manual collection and truck traffic. Within applications, residential complexes and commercial facilities represent the largest deployment areas due to high waste volumes and density. Vacuum suction technology remains the dominant standard, though interest in modular systems for smaller, phased installations is notable.
Regulatory frameworks such as the EU Green Deal, China's dual carbon goals, and US EPA guidelines on solid waste management are compelling municipalities to modernize infrastructure. Urban planning mandates in cities like Singapore and Stockholm often specify the inclusion of AWCS in new large-scale developments. The critical decision for facility management firms and municipal authorities involves balancing high initial capital expenditure against long-term operational savings and environmental benefits.
Market Dynamics
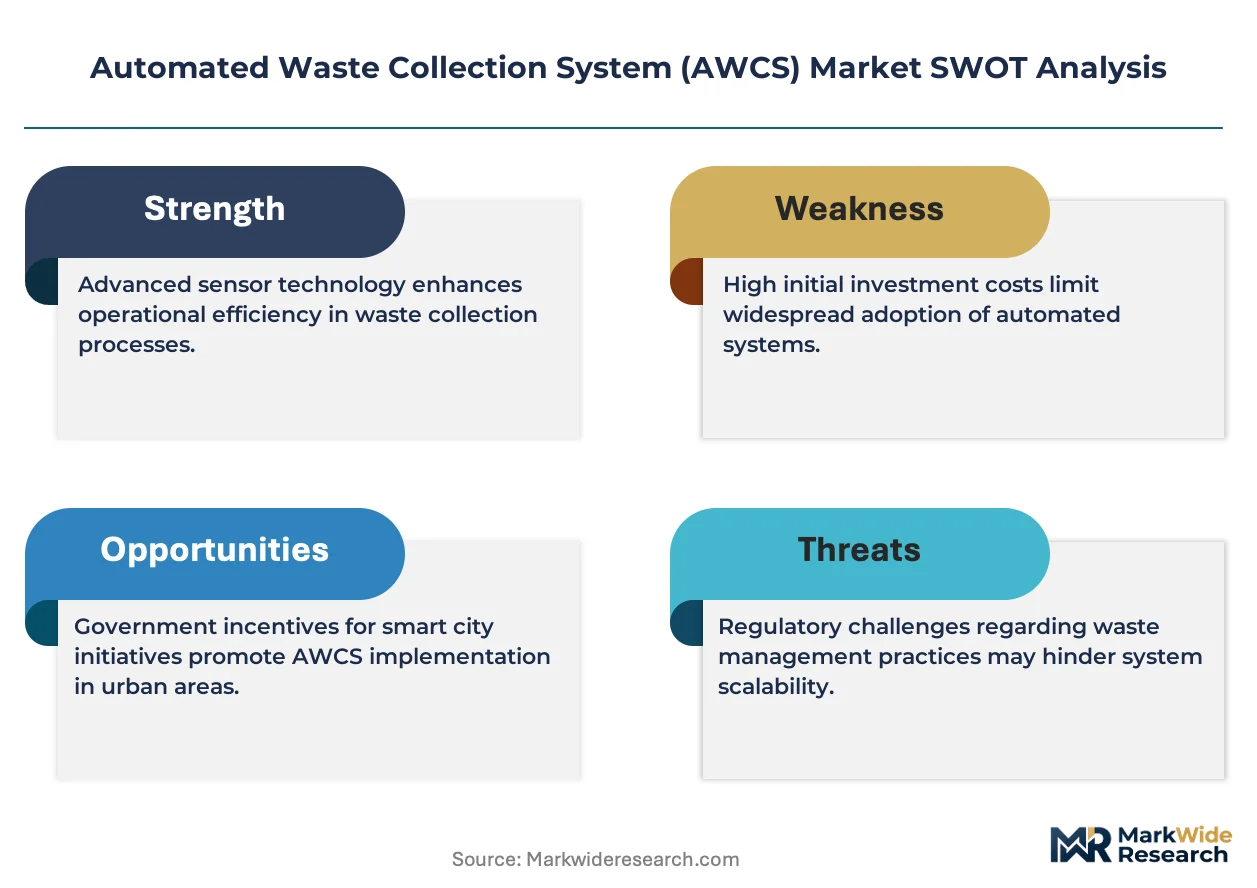
The central tension shaping the market is the balance between the high initial capital investment required for pneumatic infrastructure and the compelling long-term operational savings and environmental compliance demanded by urban sustainability frameworks.
Growth Catalysts
- Urban Planning Mandates:Smart city initiatives in Singapore, Dubai, and Stockholm increasingly require the integration of AWCS in new developments to achieve sanitation and traffic reduction goals.
- Regulatory Frameworks:Stricter waste management targets under policies like the EU Green Deal compel municipalities to adopt advanced collection systems to meet recycling and landfill diversion rates.
- High-Density Applications:Demand concentrates in large-scale residential complexes and commercial facilities, where high waste volumes make automated systems more efficient than manual collection.
Market Restraints
- High Capital Expenditure:The substantial upfront cost of installing extensive underground pneumatic tube networks remains the primary barrier to adoption for many municipalities and private developers.
- Retrofitting Complexity:Integrating AWCS into existing, dense urban areas with established underground utilities is technically challenging, costly, and disruptive, limiting deployment primarily to new construction.
- Supplier Concentration:The market relies on a small pool of specialized system integrators, which can limit competitive bidding and create dependency for maintenance and expansion projects.
Strategic Opportunities
- Modular System Design:Development of smaller, scalable AWCS units offers a path for phased implementation in existing districts or for specialized applications like airports and hospitals.
- Data Integration:The convergence of AWCS with IoT sensors and building management systems creates opportunities for data-driven services like waste analytics and predictive maintenance.
- North American Expansion:Underdeveloped markets in the United States and Canada present significant growth potential as cities begin to prioritize infrastructure modernization and sustainability.
Industry Challenges
- System Integration:Ensuring seamless interoperability between AWCS control software and disparate municipal or building management platforms presents a significant technical hurdle for operators.
- Public and Political Buy-In:Gaining approval for large-scale infrastructure projects requires overcoming skepticism about long-term ROI and demonstrating operational reliability to stakeholders and residents.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automated Waste Collection System (AWCS) Market |
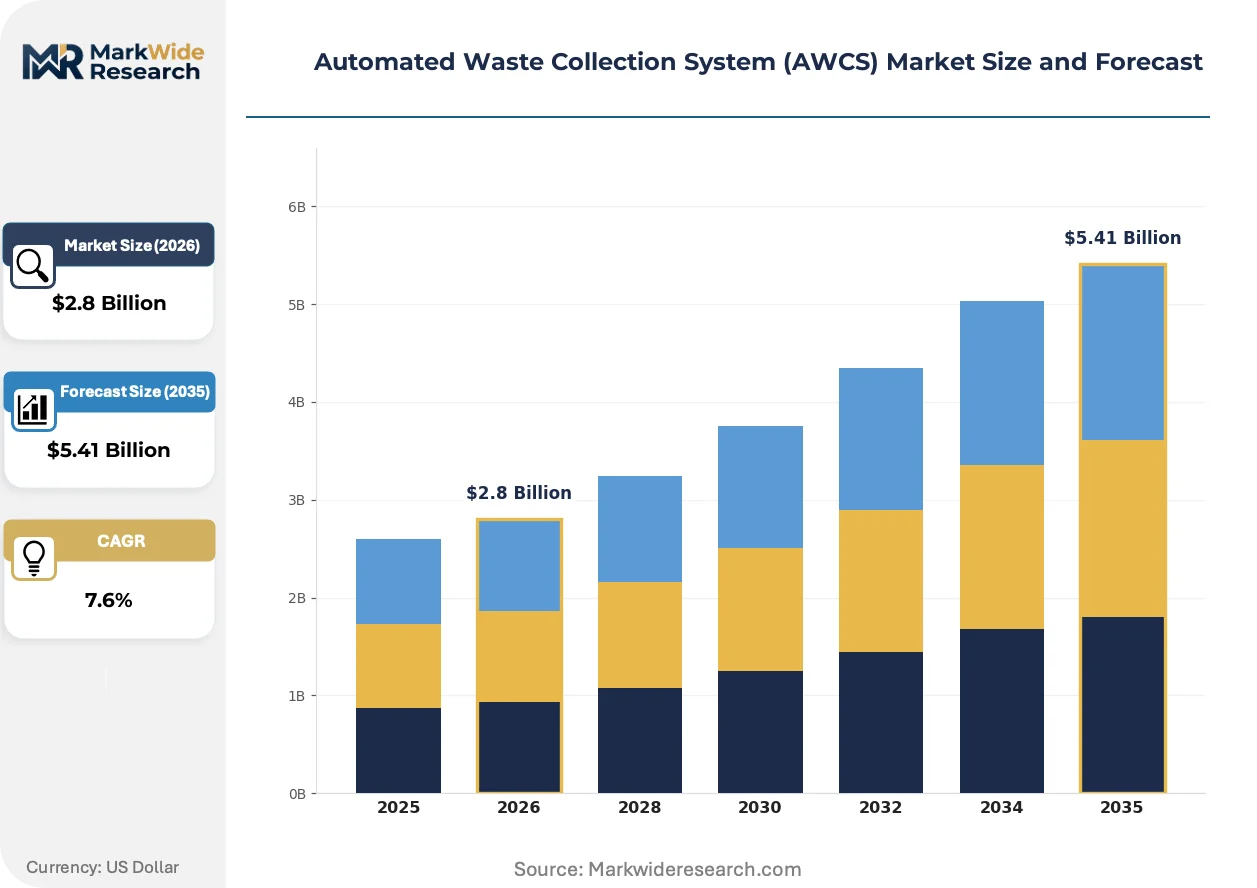
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.41 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Vacuum Suction, Pneumatic Tubes, Conveyor Systems, Robotic Arms, Hydraulic Lifts Application: Residential Complexes, Commercial Facilities, Public Parking, Industrial Parks, Educational Campuses Product Type: Stationary Units, Mobile Units, Semi-Automated, Fully Automated, Modular Systems End User: Municipal Authorities, Facility Management Firms, Event Organizers, Waste Management Operators, Environmental Agencies |
| Companies Covered | Caverion Corporation, MariMatic Oy, Envac AB, Evac Oy, Atreo, AMCS Group, Logiwaste AB, Aerbin ApS, AWC Berhad, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automated Waste Collection System (AWCS) Market Strategic Shifts & Innovations
Data-driven intelligence and modular design principles are reshaping the deployment and operation of automated waste collection systems. This evolution moves the technology beyond simple conveyance to become an integrated component of smart urban infrastructure management.
IoT sensors embedded at inlet points and within collection stations provide real-time data on waste volume and composition. Facility managers and municipal operators are adopting this technology to optimize collection cycles and monitor system performance. The integration of this digital overlay with physical infrastructure is unifying previously siloed functions like waste sorting and system maintenance into a single operational dashboard.
China's national "dual carbon" goals and associated solid waste management policies are compelling urban planners to seek low-emission infrastructure solutions. This regulatory pressure accelerates the evaluation of AWCS in new economic zones and large-scale urban redevelopment projects. Municipalities in rapidly growing cities are most affected, frequently specifying these systems in master plans for new districts.
A shift from single capital projects toward long-term public-private partnership (PPP) models is altering how systems are financed and operated. This approach disrupts the traditional municipal procurement cycle by transferring upfront capital risk to development consortia. The model is most visible in new smart city developments across the Middle East, where integrated infrastructure is funded via such partnerships.
Automated Waste Collection System (AWCS) Market Segmentation
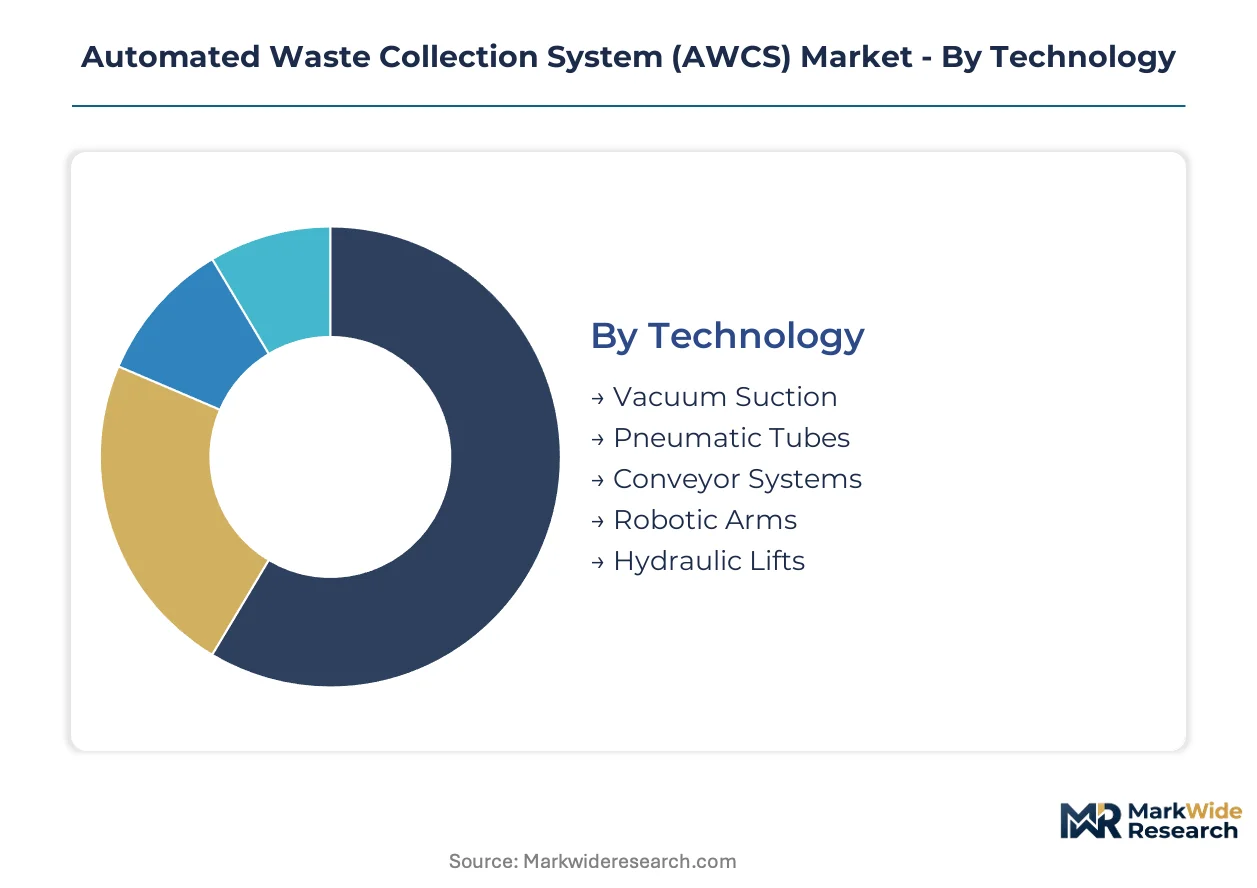
Segmentation within the Automated Waste Collection System (AWCS) market provides a granular view of technology adoption, application areas, product innovation, and procurement dynamics. Understanding these distinctions helps stakeholders identify specific growth pockets and tailor solutions to diverse urban and commercial requirements.
Technology:
The technology landscape in automated waste collection systems spans from highly customized pneumatic networks to standardized modular components, reflecting varying levels of infrastructure commitment.
- Vacuum Suction:This core technology uses powerful airflows to transport waste, ensuring rapid movement and containment within sealed systems. Demand concentrates in dense urban centers like Singapore, where efficiency and hygiene are paramount for managing high waste volumes.
- Pneumatic Tubes:These underground or concealed conduits form the physical network for waste conveyance, requiring significant upfront civil engineering. Deployments in new smart city developments across Dubai prioritize these systems for their integrated infrastructure benefits.
- Conveyor Systems:Mechanical belts or chains move waste over shorter distances, often within a single building or processing facility.
- Robotic Arms:Automated manipulators handle waste sorting or loading tasks at collection points or central stations.
- Hydraulic Lifts:These mechanisms raise or lower waste containers, typically used for underground bin systems or compactors.
Most installed capacity flows through Vacuum Suction. Expansion is steepest in Pneumatic Tubes.
Application:
Application areas for AWCS systems vary significantly based on waste generation volumes and site density, influencing system design and scale.
- Residential Complexes:Large multi-unit dwellings generate consistent, high volumes of mixed waste, making automated systems efficient for continuous collection. New housing developments in Stockholm increasingly integrate AWCS to reduce truck traffic and improve urban sanitation.
- Commercial Facilities:Office buildings, retail centers, and mixed-use developments benefit from automated systems to manage diverse waste streams and maintain cleanliness. Demand in these facilities is driven by operational savings and enhanced tenant experience.
- Public Parking:Waste collection in large parking structures benefits from automation to maintain hygiene and reduce manual labor.
- Industrial Parks:Manufacturing and logistics hubs use AWCS for efficient material handling and waste disposal from production processes.
- Educational Campuses:Universities and schools deploy these systems to manage waste from dormitories, cafeterias, and academic buildings.
High-density urban environments drive demand for AWCS, particularly in new developments. Operational efficiency and public health compliance remain primary motivators for adoption.
Product Type:
Product types reflect the varying stages of automation and infrastructure integration available for waste management, from fixed installations to flexible solutions.
- Fully Automated:These systems operate without human intervention for waste transport, often integrating sensors and control software for optimal performance. Large-scale municipal projects in cities like Singapore favor fully automated solutions for comprehensive coverage and efficiency.
- Modular Systems:Designed for scalability and phased implementation, these units allow for easier integration into existing infrastructure or smaller-scale deployments. Interest in modular designs is notable for specialized applications like hospitals.
- Stationary Units:Fixed installations, typically central collection stations or large compactors, process waste at a single location.
- Mobile Units:These involve automated vehicles or containers that move between collection points, offering flexibility in certain settings.
- Semi-Automated:Systems that combine automated transport with some level of manual intervention, often at inlet points or for specialized waste streams.
Fully automated systems remain the benchmark for efficiency, but modular solutions are gaining traction for their adaptability. Innovation is concentrating on seamless system integration.
End User:
End users for automated waste collection systems are distinguished by their procurement patterns and operational scale, ranging from public entities to private firms.
- Municipal Authorities:City governments and local councils procure AWCS for public sanitation, urban planning, and environmental compliance, driven by regulatory frameworks like the EU Green Deal. Procurement often involves large, long-term infrastructure projects.
- Facility Management Firms:These private companies manage building operations for commercial and residential properties, integrating AWCS to optimize waste handling and reduce operational costs. Their decisions focus on return on investment and service reliability.
- Event Organizers:Temporary waste management solutions are required for large gatherings, where rapid and hygienic collection is essential.
- Waste Management Operators:Companies specializing in waste collection and processing may operate AWCS as part of their service offerings.
- Environmental Agencies:These bodies influence AWCS adoption through policy recommendations, sustainability targets, and regulatory oversight.
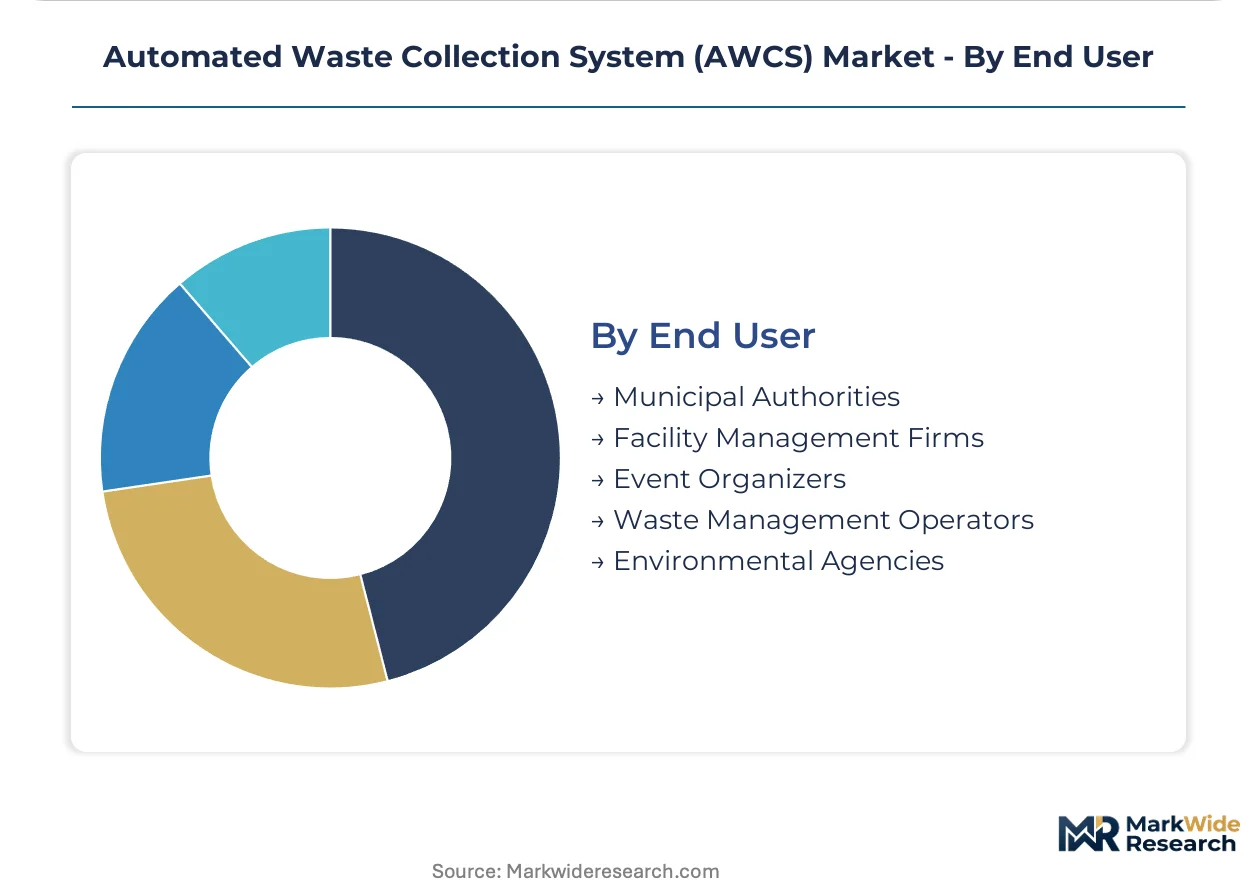
Public sector entities and large private operators represent the primary decision-makers for AWCS deployments. Strategic partnerships are becoming a common financing model for new projects.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
While Singapore prioritizes AWCS for hygiene and dense urban living, the United States is beginning to modernize its waste infrastructure. These distinct approaches highlight varying stages of adoption and regulatory drivers. European cities like Stockholm also demonstrate strong commitment to advanced waste management systems.
Singapore
High-density urban environments and stringent public health standards drive demand for AWCS in Singapore. Urban planning mandates frequently specify AWCS inclusion in new large-scale developments. The city-state of Singapore consistently integrates these systems to manage high waste volumes efficiently. This commitment ensures continuous urban sanitation and reduces truck traffic.
United Arab Emirates
New smart city developments and ambitious sustainability goals propel AWCS adoption across the United Arab Emirates. Integrated infrastructure is often funded via public-private partnership models. Dubai's master plans for new districts frequently specify advanced waste collection systems. This supports the region's vision for smart urban environments.
Sweden
Urban planning mandates in Sweden compel municipalities to integrate AWCS, particularly in new housing developments. Stockholm's initiatives aim to reduce truck traffic and enhance urban sanitation. The EU Green Deal further reinforces these efforts, driving advanced system adoption. These systems contribute to Sweden's broader environmental compliance targets.
China
China's dual carbon goals and associated solid waste management policies accelerate the evaluation of AWCS. Urban planners seek low-emission infrastructure solutions for rapidly growing cities. New economic zones and large-scale urban redevelopment projects frequently specify these systems. This supports China's national environmental objectives.
United States
Infrastructure modernization and increasing sustainability priorities are driving initial AWCS interest in the United States. US EPA guidelines on solid waste management compel cities to explore advanced collection methods. Underdeveloped markets present significant growth potential as metropolitan areas begin to prioritize efficiency. Cities like New York are evaluating these systems for dense urban areas.
Automated Waste Collection System (AWCS) Market Key Industry Players
European producers anchor one tier, specializing in established pneumatic infrastructure and large-scale urban projects, while North American and Asian specialists hold positions in emerging markets with modular solutions. The market structure is concentrated around a few specialized system integrators, limiting competitive bidding. Strategic archetypes include full-service AWCS providers, niche technology developers, and broader building service integrators. Competitive moves involve forming strategic partnerships with developers and expanding geographic reach into new urban development projects.
Specialized technology providers like MariMatic Oy exemplify a focus on vacuum conveying systems for unique applications such as hospitals and airports, demonstrating a niche approach to waste management. Swedish firm Envac AB, another key European player, leverages its extensive project portfolio in dense urban centers to secure municipal contracts and reinforce its market presence. Caverion Corporation, a European entity, occupies a position by integrating AWCS within broader building and industrial service packages for its clients, offering comprehensive solutions to complex infrastructure needs.
| Leading Market Players |
|---|
| Caverion Corporation |
| MariMatic Oy |
| Envac AB |
| Evac Oy |
| Atreo |
| AMCS Group |
| Logiwaste AB |
| Aerbin ApS |
| AWC Berhad |
Cost & Logistics Intelligence
Industrial metals price indices influence the cost of pneumatic tubes and collection stations, cascading into project-based pricing tiers for AWCS deployments. This cost sensitivity impacts the long-term operational savings municipalities anticipate.
Pricing Analysis
Capacity additions in European manufacturing facilities are reshaping price floors for core AWCS components. The dominant pricing model remains project-based, structured around long-term contracts for installation and maintenance. Price differentiation stems from the customization level required for urban integration and the extent of after-sales service bundles. Pricing pressure stems from the high initial capital expenditure for pneumatic infrastructure, making municipal authorities particularly price-sensitive. Facility management firms prioritize long-term operational savings over lowest upfront cost.
Supply Chain Analysis
Logistics and freight costs for large-diameter pneumatic tubes significantly impact overall project budgets for AWCS installations. Core manufacturing concentrates in Sweden, Finland, and Germany, drawing from global suppliers for specialized motors and control electronics. The supply chain relies on steel for extensive underground networks and custom-engineered components for vacuum technology. Single-source vulnerability for advanced vacuum system components represents a structural risk. Distribution runs through direct sales channels to municipal authorities and large-scale property developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Automated Waste Collection System market functions as a stable compounder, driven by increasing urban planning mandates for integrated infrastructure. Long-term operational savings and environmental compliance provide consistent demand.
For Market Incumbents: Anchor existing market share by expanding long-term service contracts and deepening integration with building management systems. Invest in modular system research and development to counter emerging specialized entrants offering flexible solutions. Rising material costs for pneumatic tubes represent a margin pressure point. Leverage comprehensive after-sales service and data analytics platforms to solidify client relationships.
For New Entrants and Emerging Players: Digital platform integration with smart city dashboards offers a viable entry point for new AWCS providers. Target underdeveloped North American metropolitan areas and specialized applications like hospitals, which require adaptable solutions. Focus on modular system designs to offer lower initial capital expenditure and phased implementation. Emphasize a value proposition centered on scalability and rapid deployment for specific use cases.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized technology developers offering data integration or modular AWCS solutions. This market demonstrates decadal viability, driven by global urbanization and stringent sustainability goals. Acquire firms with strong intellectual property in sensor technology or advanced vacuum system components. Watch for increased public-private partnership funding in new smart city developments as an inflection indicator for accelerated adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Supports growing demand for AWCS in new urban developments and smart cities. |
| Technology Licensing | Enables broader market penetration for specialized vacuum components through regional partners. |
| Strategic Partnership | Integrates AWCS with broader building management systems for enhanced operational efficiency. |
| Geographic Expansion | Captures new opportunities in North American markets prioritizing infrastructure modernization. |
| Green Certification Program | Aligns product offerings with stringent environmental mandates like the EU Green Deal. |
Research Approach
Bottom-up residential complex and commercial facility modeling reconciled against top-down system integrator and component manufacturer tracking forms the analytical core. This approach combines primary interviews with municipal planning officials, facility managers, urban developers, and AWCS engineers. Secondary validation draws from EU Green Deal reports, Singapore URA master plans, US EPA guidelines, and company annual reports.
Historical trendline analysis establishes growth trajectories across the analysis window, informing projections for the AWCS market. The quantitative model segments by technology, application, product type, end user, and regional adoption pattern. Compound annual growth rates derive from a weighted average of historical performance and projected future demand. Forecast inputs include urbanization rates, smart city project pipeline, and regulatory enforcement levels.
The model assumes a particular technology adoption path; alternative pathways for modular vacuum systems would alter the outlook. Forecasts reflect assumptions regarding urban development and regulatory stability. Unexpected shifts in public funding or major civil engineering challenges pose risk factors. Stakeholders should weigh assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste Management & Pollution Control
Qatar Solid Waste Management Market
Waste Management & Pollution Control
North America Municipal Solid Waste Management Market
Waste Management & Pollution Control
India E-Waste Management Market
Waste Management & Pollution Control
UAE Biomedical Waste Management Market
Waste Management & Pollution Control
Global Waste Management Software Market
Waste Management & Pollution Control
Nutrient Recycling Market
Waste Management & Pollution Control
China Waste Management Market
Waste Management & Pollution Control
Europe Medical Waste Management Market
Waste Management & Pollution Control
Africa Waste Management Market
Waste Management & Pollution Control
Europe Industrial Waste Management Market
Waste Management & Pollution Control
Middle-East and Africa Hazardous Waste Handling Automation Market
Waste Management & Pollution Control
Smart Waste Sorting Bin Market
Waste Management & Pollution Control
Municipal Solid Waste Incineration Market
Waste Management & Pollution Control
US Municipal Solid Waste Management Market
Waste Management & Pollution Control
Waste Recycling Services Market
Waste Management & Pollution Control
APAC Bio-Medical Waste Management Market