
 Europe Industrial Waste Management Market | 2026-2036
Europe Industrial Waste Management Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Industrial Waste Management Market Insights
Buyer concentration among German and French automotive manufacturers is pivoting toward bundled long-term service contracts with full-asset recovery obligations. Veolia leverages its pan-European incineration network to secure multi-site agreements with OEMs seeking thermal treatment capacity. Suez anchors its position through deep partnerships with petrochemical complexes in Belgium and the Netherlands. Renewi competes aggressively on construction debris sorting technology, differentiating its output streams for cement kiln co-processing.
Europe industrial waste management encompasses the controlled collection, transport, treatment, and final disposition of non-hazardous and hazardous by-products generated by manufacturing, energy, and extractive industries, with thermal treatment systems typically operating at 850–1,100°C to destroy organic contaminants and reduce residue volume by 90%. The primary purpose is regulatory compliance combined with material recovery, converting waste streams into secondary raw materials or energy outputs that re-enter industrial supply chains. Hazardous waste commands premium pricing due to ECHA REACH classification complexity and restricted landfill access under EU directives. Recycling services for e-waste and construction debris are expanding fastest as the EU Green Deal tightens circular economy targets. Collection and disposal segments remain mature with thin margins, while treatment and recycling concentrate value capture.
EMA, ECHA, and the EU Green Deal framework collectively shape market access by mandating waste hierarchy compliance, hazardous substance registration, and binding landfill diversion timelines. Germany's KBA enforces end-of-life vehicle recycling quotas that directly channel automotive scrap into licensed treatment facilities. France's ANSM and environmental prefectures maintain strict pharmaceutical waste tracking that elevates Indaver's specialized incineration demand. Stakeholders must monitor how the EU AI Act and CSRD reporting requirements will integrate waste traceability into broader corporate sustainability disclosures.
Market Dynamics
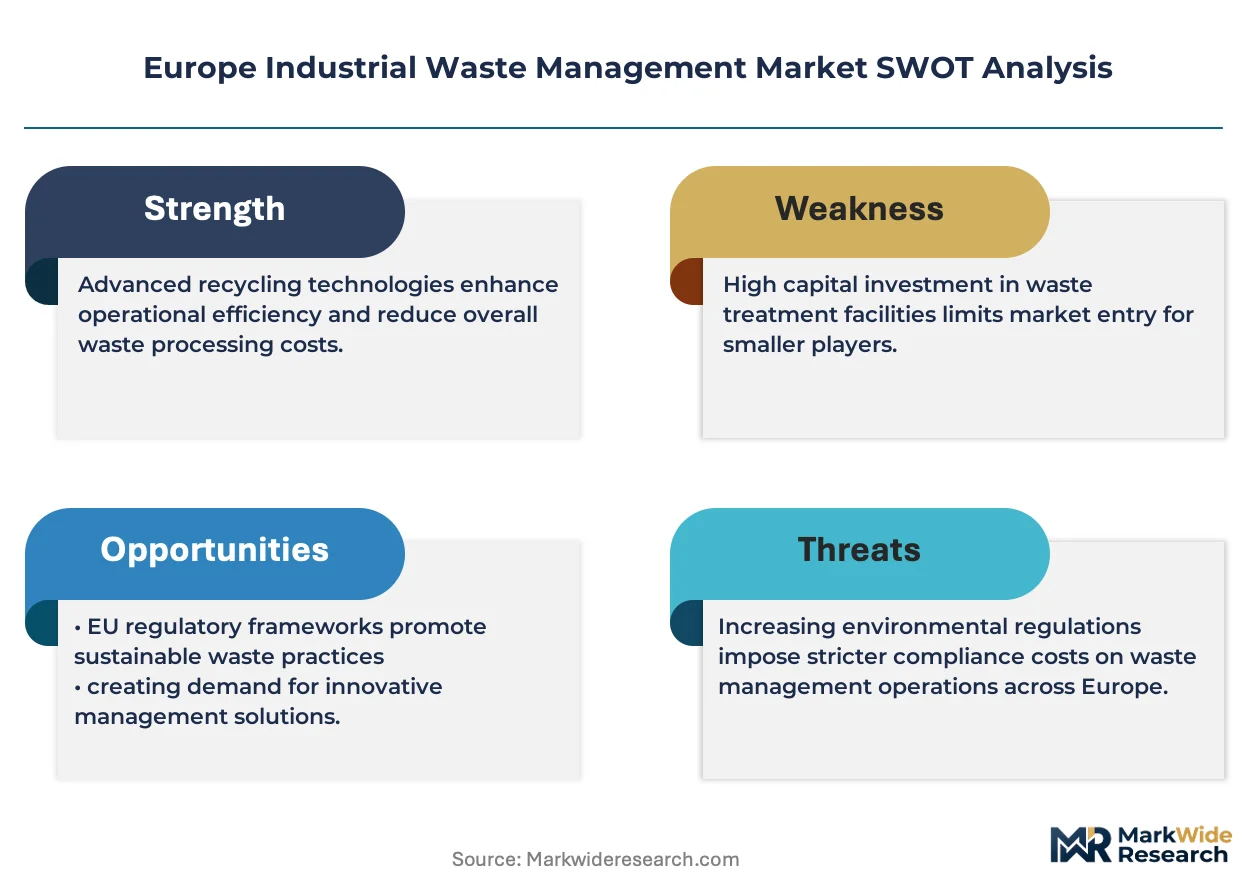
The EU Green Deal's binding landfill diversion timelines are compressing treatment capacity across member states, forcing industrial clusters to secure long-term thermal processing contracts before permit scarcity hardens into structural shortage.
Growth Catalysts
- Automotive outsourcing:German OEMs are expanding asset recovery obligations into bundled service contracts that guarantee feedstock return to secondary materials markets.
- REACH classification complexity:ECHA's hazardous substance registry is restricting landfill access for chemical by-products, channeling waste streams toward licensed incineration and solvent recovery infrastructure.
- Construction debris sorting:Advanced optical separation technology is upgrading demolition waste into cement kiln co-processing feedstock, unlocking circular economy credits under EU circularity mandates.
Market Restraints
- Incineration permit scarcity:New thermal treatment capacity faces 4-7 year approval timelines in Germany and the Netherlands, freezing supply expansion despite queueing demand.
- Energy cost volatility:Natural gas price swings directly compress operating margins at pyrolysis and plasma arc facilities dependent on grid or captive power.
- Cross-border transport friction:Basel Convention paperwork and divergent national waste codes create compliance overhead for multi-site industrial generators seeking optimal-cost disposal routing.
Strategic Opportunities
- Belgian petrochemical corridor:Antwerp-Rotterdam pipeline infrastructure supports integrated chemical waste-to-feedstock loops that bypass traditional disposal economics entirely.
- CSRD traceability mandates:Corporate sustainability reporting requirements are creating premium service tiers for waste processors offering blockchain-verified chain-of-custody documentation.
- AI-powered predictive sorting:Machine vision and robotics convergence is enabling real-time composition analysis that upgrades mixed industrial streams previously routed to low-value recovery.
Industry Challenges
- Specialized technician scarcity:Licensed hazardous waste operators and pyrolysis engineers command wage premiums that inflate facility operating costs across France and Germany.
- Legacy ERP integration:Waste tracking software must interface with decades-old manufacturing execution systems at automotive and chemical plants, extending deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Industrial Waste Management Market |
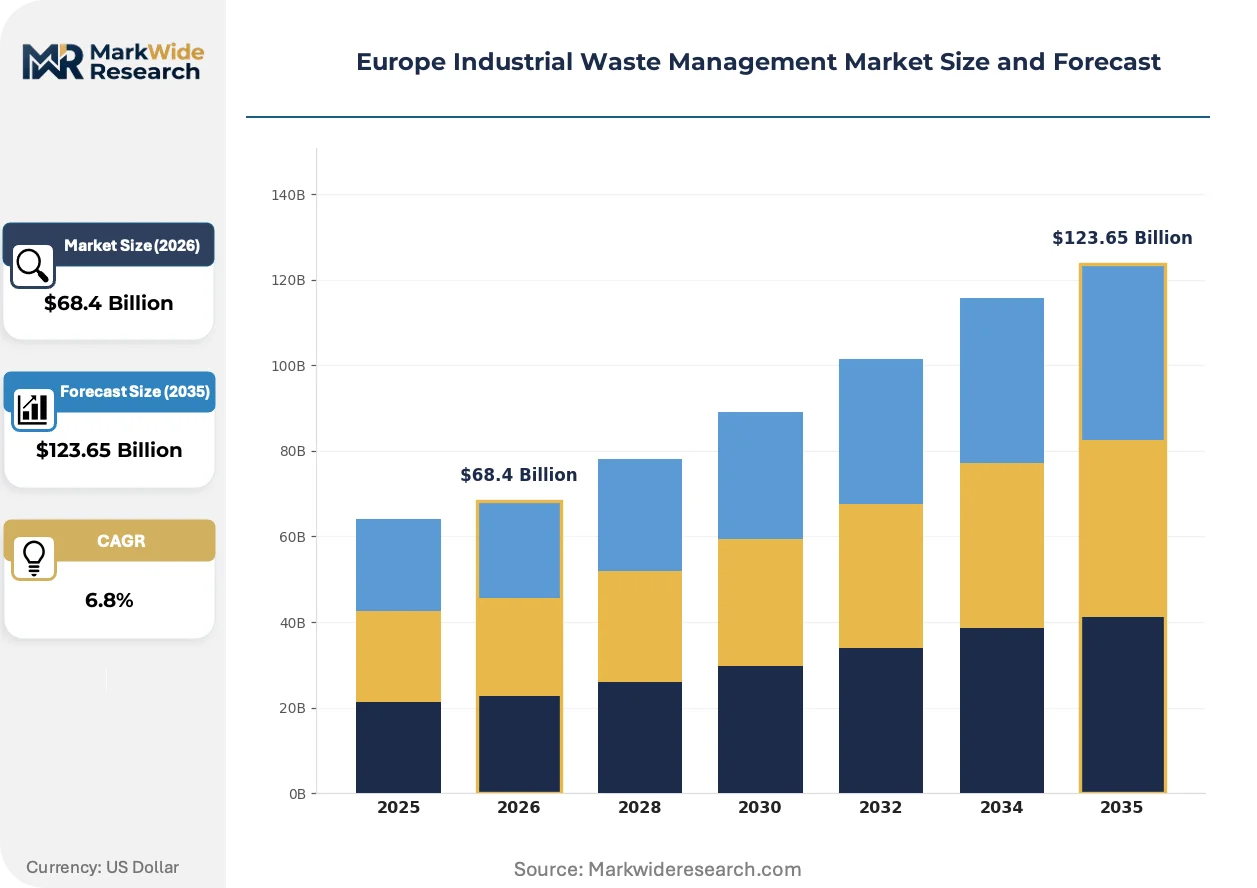
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $123.65 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Waste Type: Hazardous Waste, Non-Hazardous Waste, E-Waste, Construction Debris Service Type: Collection, Treatment, Recycling, Disposal End User: Manufacturing, Automotive, Construction, Energy Technology: Incineration, Landfilling, Anaerobic Digestion, Thermal Treatment |
| Companies Covered | Veolia, Suez, Biffa PLC, Remondis, Prezero International, Urbaser, Indaver, Renewi, FCC Environmental Services, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Industrial Waste Management Market Trends and Innovations
Digital traceability and thermal process intensification are converging to transform how industrial generators contract for disposal, with real-time monitoring replacing periodic compliance reporting as the baseline service expectation.
Plasma gasification is rewriting the economics of hazardous residue destruction by achieving temperatures above 3,000°C that vitrify inorganic contaminants into inert slag. Belgian and Dutch chemical complexes are piloting units for halogenated solvent streams that conventional incineration struggles to handle. The technology is compressing residual waste volumes to 5% of input mass while eliminating landfill liability entirely.
CSRD disclosure requirements are mandating granular waste stream accounting that extends liability upstream to generators. French environmental prefectures are enforcing quarterly reporting thresholds that force pharmaceutical and electronics manufacturers to contract only with processors offering certified data pipelines. The compliance burden is concentrating procurement among integrated service providers with in-house audit capabilities.
Automotive OEMs are unbundling waste management from facilities contracts and negotiating direct relationships with thermal processors. German manufacturers now specify recovery rates and secondary material offtake guarantees as primary selection criteria rather than disposal cost per ton. The purchasing pattern shift is visible across Bavarian and Baden-Württemberg production clusters where multi-site framework agreements dominate new tender activity.
Europe Industrial Waste Management Market Segmentation
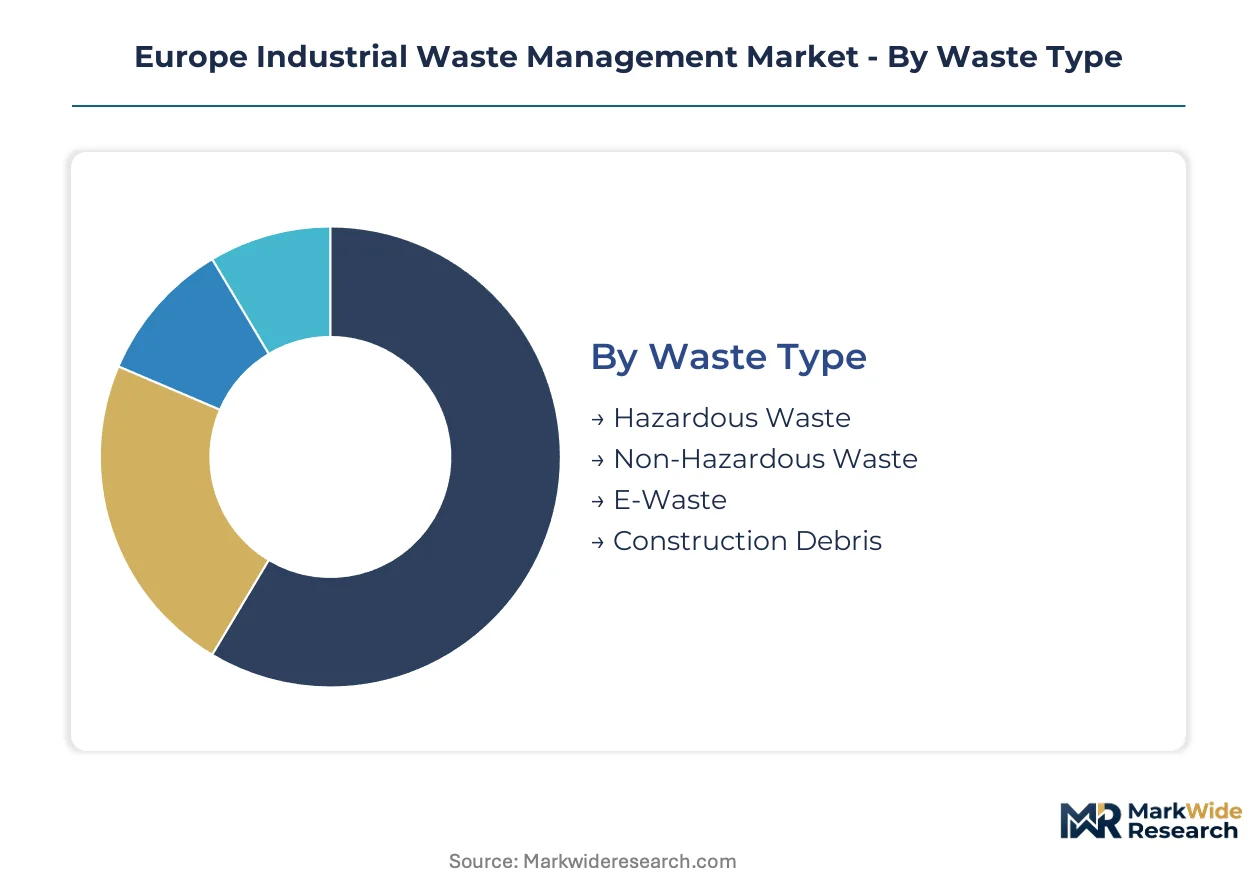
Industrial waste management in Europe fragments across four distinct dimensions that determine service intensity and margin capture. Waste type and service type together dictate regulatory exposure and technology deployment, while end-user concentration and technology choice shape competitive positioning across member states.
Waste Type:
Standalone disposal streams dominate volume, while embedded recovery systems capture premium pricing through circular economy integration.
- Hazardous Waste:Chemical by-products, contaminated solvents, and toxic residues classified under ECHA REACH frameworks require licensed thermal treatment at 850–1,100°C. German automotive and French pharmaceutical clusters drive demand concentration as landfill diversion mandates tighten under EU directives.
- Non-Hazardous Waste:General industrial by-products including packaging, scrap metal, and organic refuse suitable for standard recycling or energy recovery routes. Dutch and Belgian manufacturing corridors generate the highest per-facility volumes, though margin compression limits service differentiation.
- E-Waste:Discarded electronics and circuit boards containing recoverable precious metals and rare earth elements.
- Construction Debris:Demolition concrete, asphalt, and mixed rubble processed through optical sorting for cement kiln feedstock substitution.
Volume placements concentrate in Non-Hazardous Waste; the faster expansion belongs to E-Waste as WEEE directive enforcement intensifies.
Service Type:
Cost tier stratification separates commoditized logistics from high-margin processing, with treatment and recycling commanding price premiums over basic collection.
- Collection:Scheduled pickup and transport of waste from generator sites to processing facilities using specialized vehicle fleets. Thin margins characterize this segment across France and Germany where route density determines profitability.
- Treatment:Chemical, thermal, or biological processing to neutralize hazards or prepare materials for recovery. Antwerp-Rotterdam chemical complexes anchor European demand for integrated treatment infrastructure.
- Recycling:Material recovery and reprocessing into secondary raw materials for re-entry into industrial supply chains.
- Disposal:Final disposition through landfill or incineration of non-recoverable residues.
Revenue concentrates in Treatment; Recycling climbs the fastest as circular economy mandates tighten landfill diversion timelines.
End User:
Application intensity varies by sector, with automotive and energy generators demanding bundled asset-recovery contracts versus construction's project-based procurement.
- Manufacturing:General industrial production facilities generating metal scrap, packaging waste, and process residues. German and French industrial clusters sustain the highest service contract density across Europe.
- Automotive:OEM and supplier facilities producing end-of-life vehicles, manufacturing scrap, and hazardous coating residues. KBA recycling quotas in Germany channel automotive scrap exclusively into licensed treatment networks.
- Construction:Demolition contractors and developers generating concrete, asphalt, and mixed debris streams.
- Energy:Power generation and oil & gas facilities producing ash, slag, and contaminated equipment.
Contract value concentrates in Automotive; Construction gains share fastest as EU Green Deal building renovation targets accelerate demolition activity.
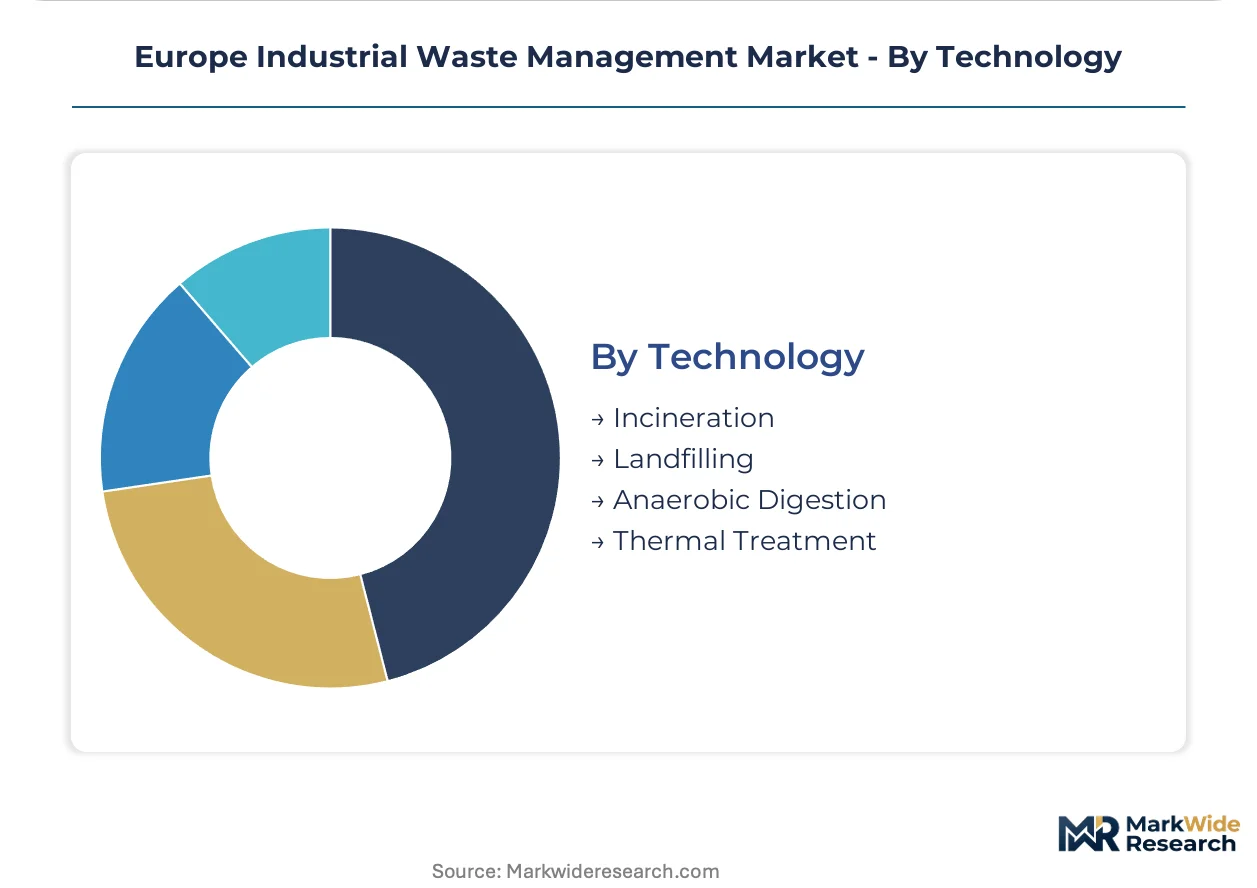
Technology:
Supply concentration clusters in thermal processing, with permit scarcity in Germany and the Netherlands constraining capacity expansion despite queueing demand.
- Incineration:Controlled combustion at 850–1,100°C destroying organic contaminants and reducing residue volume by 90%. Belgian and Dutch chemical complexes anchor European capacity, though German permit timelines extend 4–7 years.
- Landfilling:Engineered disposal in lined facilities for non-recoverable inert residues. Declining access under EU landfill directives restricts this route to final residues only.
- Anaerobic Digestion:Biological breakdown of organic waste streams producing biogas and digestate.
- Thermal Treatment:Advanced pyrolysis, gasification, and plasma arc systems achieving temperatures above 3,000°C for hazardous residue destruction.
Capacity placements concentrate in Incineration; Thermal Treatment expands most quickly as plasma gasification pilots advance in Belgian chemical corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German and French automotive manufacturers concentrate demand for bundled asset-recovery contracts, while Belgian and Dutch chemical corridors anchor thermal treatment capacity. Industrial cluster density across these markets shapes integrated infrastructure investment patterns.
Germany
KBA end-of-life vehicle recycling quotas channel automotive scrap exclusively into licensed treatment networks. The EU Green Deal's landfill diversion mandates compress available capacity, forcing Bavarian and Baden-Württemberg OEMs to secure multi-site framework agreements. Thermal treatment permit timelines extending 4-7 years freeze supply expansion despite queueing demand from manufacturing clusters.
France
ANSM pharmaceutical waste tracking elevates demand for specialized incineration services from drug manufacturers concentrated around Lyon and Paris. CSRD disclosure requirements mandate granular waste stream accounting that extends liability upstream to generators. French environmental prefectures enforce quarterly reporting thresholds concentrating procurement among integrated service providers.
Netherlands
Antwerp-Rotterdam pipeline infrastructure supports integrated chemical waste-to-feedstock loops that bypass traditional disposal economics. REACH classification complexity restricts landfill access for chemical by-products, channeling streams toward licensed incineration. The Rotterdam port complex anchors European capacity for hazardous residue thermal processing.
Belgium
Petrochemical complexes in the Antwerp corridor pilot plasma gasification units for halogenated solvent streams. ECHA hazardous substance registry compliance elevates operating standards for treatment facilities serving pharmaceutical and chemical manufacturers. The Flemish industrial belt concentrates demand for advanced thermal treatment exceeding conventional incineration capabilities.
United Kingdom
Construction debris sorting technology upgrades demolition waste into cement kiln co-processing feedstock, unlocking circular economy credits. Biffa PLC and Renewi compete on optical separation capabilities for mixed industrial streams. London and Midlands manufacturing clusters sustain service contract density despite post-Brexit cross-border transport friction.
Europe Industrial Waste Management Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue digital traceability and AI-powered sorting capabilities. The market consolidates around pan-European incineration networks and specialized regional treatment facilities. Two strategic archetypes dominate: integrated service providers with multi-site framework capabilities, and technology-focused specialists competing on construction debris recovery rates. Competitive moves concentrate on securing scarce thermal treatment permits and deploying predictive sorting systems.
Within the integrated service tier, Veolia and Suez exemplify divergent geographic anchoring strategies. Veolia leverages its incineration network across multiple member states to secure automotive OEM agreements, while Suez anchors through petrochemical corridor partnerships. Renewi occupies a position among technology-differentiated specialists competing aggressively on sorting output quality for cement kiln feedstock substitution. Indaver represents the hazardous waste specialization archetype serving pharmaceutical and chemical manufacturers with licensed thermal treatment capacity.
| Leading Market Players |
|---|
| Veolia |
| Suez |
| Biffa PLC |
| Remondis |
| Prezero International |
| Urbaser |
| Indaver |
| Renewi |
| FCC Environmental Services |
| Others |
Pricing and Supply Chain Analysis
EU Green Deal landfill diversion timelines gate qualified thermal treatment capacity and compress premium-tier pricing access for hazardous waste streams across German and Dutch industrial clusters. German automotive OEMs and French pharmaceutical manufacturers now compete for scarce incineration slots through long-term offtake guarantees that embed circular economy compliance costs into contract structures.
Pricing Analysis
Volume concentrates in commoditized collection and disposal services where route density determines thin margins, while margin capture clusters in treatment and recycling segments where ECHA REACH classification complexity creates pricing power. Three-tier pricing structure across certified hazardous, standard industrial, and non-hazardous economy levels reflects regulatory burden and technology intensity. Cost compression in standard industrial tiers is intensifying because natural gas price volatility feeds directly into pyrolysis facility operating economics. Construction debris generators exhibit highest price sensitivity due to project-based procurement, while automotive OEMs prioritize recovery rate guarantees over per-ton disposal rates.
Supply Chain Analysis
German domestic-content mandates for end-of-life vehicle recycling under KBA quotas reshape sourcing patterns by channeling automotive scrap exclusively into licensed national treatment networks. Thermal processing capacity concentrates in Belgium, the Netherlands, and Germany where Antwerp-Rotterdam pipeline infrastructure supports integrated chemical waste-to-feedstock loops. Pyrolysis and plasma arc facilities rest on natural gas and electricity inputs whose price swings transmit directly to operating margins. Single-source vulnerability characterizes specialized hazardous waste incineration where permit scarcity in Germany and the Netherlands freezes capacity expansion. Distribution runs through pan-European logistics networks with cross-border Basel Convention paperwork creating compliance overhead for multi-site generators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thermal treatment permit scarcity across Germany and the Netherlands props pricing power for qualified incumbents while compressing availability for new industrial generators seeking long-term capacity.
For Market Incumbents: Hedge against permit scarcity by securing multi-site framework agreements with automotive OEMs before queueing demand hardens into structural shortage. Backward integration into plasma gasification technology in Belgian chemical corridors defends margin position against conventional incineration commoditization. CSRD traceability mandates create channel control opportunities through blockchain-verified chain-of-custody investments that smaller competitors cannot replicate. For New Entrants and Emerging Players: Capture white-space in AI-powered predictive sorting for mixed construction debris streams where optical separation technology gaps persist across UK and French demolition markets. Target pharmaceutical waste tracking compliance services in Lyon and Paris clusters where ANSM enforcement elevates demand for specialized data pipeline capabilities. Lead with certified audit capabilities as the go-to-market angle to bypass capital-intensive thermal infrastructure requirements. For Investors and Strategic Acquirers: German KBA quota expansion announcements are the leading indicator that licensed treatment capacity will face accelerated demand pressure across Bavarian automotive clusters. The five-to-ten year viability window favors acquisition of regional specialists with scarce permit holdings in Germany and the Netherlands over greenfield development timelines. Watch plasma gasification pilot results in Antwerp as the signal for whether advanced thermal technology will displace conventional incineration economics in halogenated solvent applications.| Strategic Initiative | Industry Significance |
|---|---|
| Thermal Permit Acquisition | Secures multi-year capacity lock-in ahead of German and Dutch approval timeline bottlenecks. |
| Plasma Gasification Deployment | Antwerp chemical corridor pilots vitrify hazardous residues into inert slag eliminating landfill liability. |
| Blockchain Traceability Integration | CSRD disclosure mandates force pharmaceutical manufacturers toward certified chain-of-custody documentation. |
| AI Sorting Technology Investment | Machine vision upgrades mixed industrial streams previously routed to low-value recovery routes. |
| Petrochemical Corridor Partnership | Antwerp-Rotterdam pipeline infrastructure enables waste-to-feedstock loops bypassing disposal economics. |
Research Methodology
Document review covered ECHA substance registry filings, EU Green Deal implementation progress reports, and national waste code databases, complemented by interviews with thermal facility operators, automotive procurement directors, pharmaceutical environmental compliance officers, and construction debris processors. Secondary validation drew from customs trade data, Cefic chemical industry reports, and SEC filings of publicly traded waste management groups. Bottom-up capacity modeling and top-down demand projection triangulation anchored volume estimates across the analysis window.
Historical capacity utilization patterns were cross-referenced against stakeholder panel input on permit approval timelines and queueing demand intensity. The analytical framework modeled waste type, service tier, end-use industry, and technology choice dimensions throughout the forecast period. CAGRs were derived from segmented growth rate assumptions calibrated to regulatory mandate enforcement schedules and industrial cluster expansion plans. Forecast inputs incorporated KBA recycling quota trajectories and CSRD disclosure phase-in timelines specific to pharmaceutical and automotive verticals.
The model holds under stable EU landfill diversion enforcement and natural gas price bands; deviation in permit approval acceleration or energy cost volatility spikes would shift capacity expansion assumptions and pricing power distributions. Forecasts reflect documented base conditions with acknowledged sensitivity to ECHA classification updates and cross-border transport regulatory friction. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste Management & Pollution Control
Landfill Compactor Market
Waste Management & Pollution Control
Vacuum Waste Systems Market
Waste Management & Pollution Control
Asia Pacific Medical Waste Management Market
Waste Management & Pollution Control
India Commercial Food Waste Decomposer Market
Waste Management & Pollution Control
North America Industrial Waste Management Market
Waste Management & Pollution Control
Rare Earth Recycling Market
Waste Management & Pollution Control
GCC Waste Management Market
Waste Management & Pollution Control
Landfill Gas Market
Waste Management & Pollution Control
Global Automated Marine Debris Collection Equipment Market
Waste Management & Pollution Control
Global Smart Trash Bin Market
Waste Management & Pollution Control
Europe Bio-Medical Waste Management Market
Waste Management & Pollution Control
India Bio-Medical Waste Management Market
Waste Management & Pollution Control
Global Waste Management Software Market
Waste Management & Pollution Control
Qatar Solid Waste Management Market
Waste Management & Pollution Control
Medical Waste Management Equipment Market
Waste Management & Pollution Control
Trash Pump Market