
 UAE Biomedical Waste Management Market | 2026-2036
UAE Biomedical Waste Management Market Size, Share, and Industry Trends Forecast 2026-2036
UAE Biomedical Waste Management Market Insights
Automated segregation systems with embedded RFID tracking is rewriting operational protocols for UAE healthcare waste handlers. Averda leverages its integrated collection-treatment infrastructure across Dubai Healthcare City and Al Ain. Dulsco Waste Management anchors commercial contracts with government hospital networks in Abu Dhabi. Bee'ah competes through its specialized sharps containment and incineration capabilities serving northern emirates.
Biomedical waste management encompasses the controlled handling, treatment, and final disposition of waste streams generated during patient diagnosis, treatment, immunization, or biomedical research, with infectious waste requiring autoclaving at 121°C for minimum 30 minutes or alternative thermal oxidation to achieve 99.9999% pathogen destruction prior to landfill or energy recovery. The service type dimension shows treatment and disposal commanding margin concentration due to capital-intensive incinerator and autoclave infrastructure, while collection and transportation segments face price pressure from route-density competition in Dubai and Abu Dhabi corridors. End user segmentation reveals hospitals generating the highest per-facility waste volumes, though research facilities and specialized laboratories produce disproportionately hazardous waste streams requiring dedicated handling protocols and premium pricing.
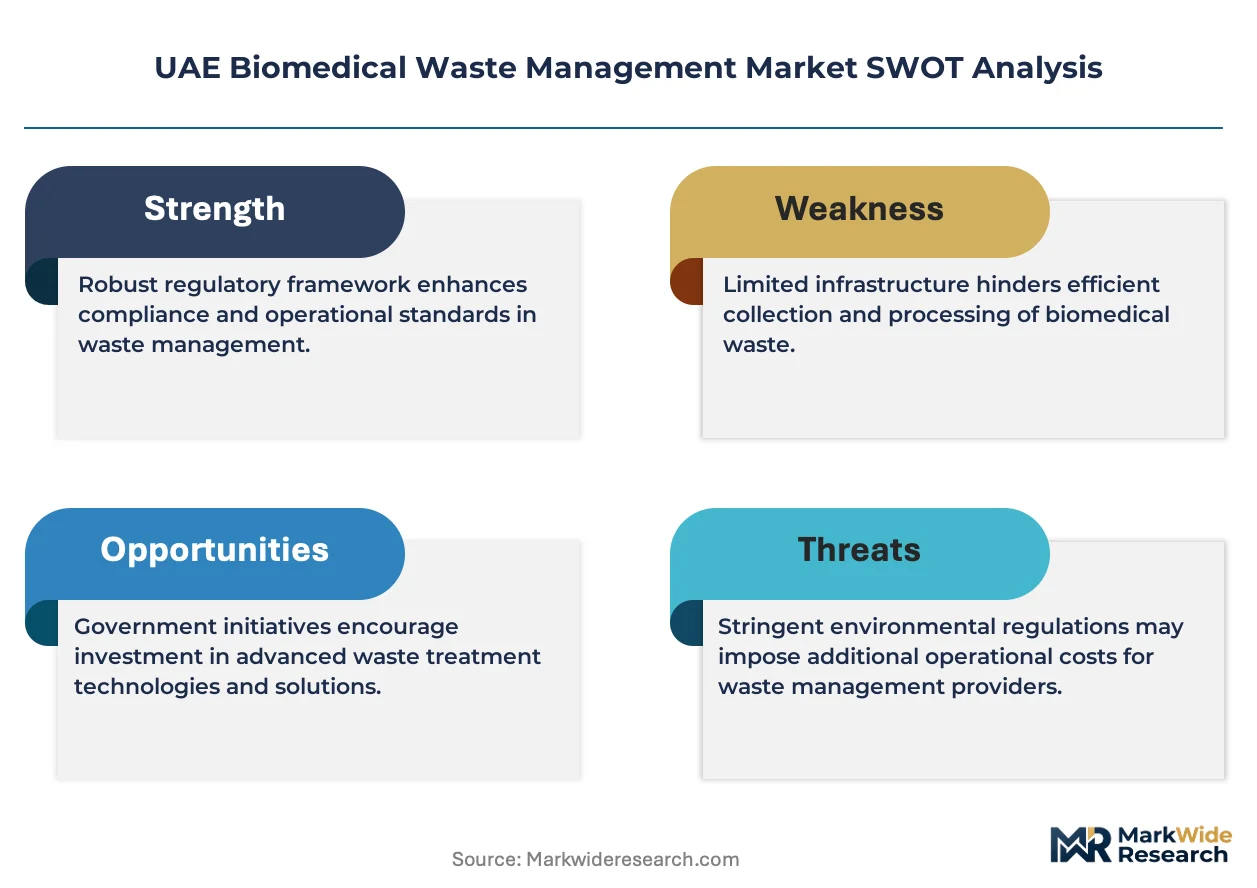
MOHAP enforces biomedical waste protocols through facility licensing and periodic audit regimes, while Dubai Municipality's Waste Management Department coordinates with the Environment Agency Abu Dhabi to standardize cross-emirate transfer documentation. The UAE's alignment with WHO guidelines and pending adoption of ISO 14001 environmental management standards for healthcare facilities tightens compliance thresholds for new market entrants. Stakeholders must monitor enforcement consistency across free zone healthcare clusters versus mainland jurisdictions to anticipate contract renewal patterns and capital deployment timing.
Market Dynamics
MOHAP's third-party treatment verification mandate is compressing operational timelines for UAE waste handlers while forcing capital redeployment toward automated tracking infrastructure. Hospital procurement teams now prioritize vendors with integrated collection-treatment footprints over fragmented service providers.
Growth Catalysts
- Dubai Healthcare City expansion:New hospital clusters generate concentrated waste volumes that reward route-optimized collection networks with density economics.
- ISO 14001 alignment:Pending adoption of environmental management standards for UAE healthcare facilities tightens compliance thresholds and locks in recurring audit revenue streams for certified operators.
- Sharps containment protocols:Specialized handling requirements for infectious waste streams command premium pricing tiers distinct from general biomedical categories.
Market Restraints
- Incinerator capex concentration:Thermal oxidation infrastructure requires 7-10 year depreciation cycles, freezing capital allocation flexibility for mid-scale entrants.
- Autoclave energy input volatility:Steam sterilization systems face margin pressure from natural gas price fluctuations in UAE commercial utility markets.
- Free zone regulatory fragmentation:Dubai Healthcare City and mainland jurisdictions operate under divergent licensing timelines, complicating unified contract structures.
Strategic Opportunities
- Northern emirate penetration:Sharjah, Ras Al Khaimah, and Fujairah show 40% lower service coverage density than Dubai-Abu Dhabi corridors.
- RFID-autoclave convergence:Embedded tracking sensors linked to sterilization cycle verification create auditable chain-of-custody records for liability reduction.
- Research laboratory specialization:Biomedical research facilities generate pathogen-grade waste requiring dedicated handling protocols outside standard hospital contracts.
Industry Challenges
- Hazmat technician certification gaps:UAE vocational pipelines produce insufficient certified operators for autoclave and incinerator supervision roles.
- Cross-emirate transfer documentation:Dubai Municipality and Environment Agency Abu Dhabi maintain non-harmonized manifest systems, creating customs-like friction for inter-emirate waste movement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAE Biomedical Waste Management Market |
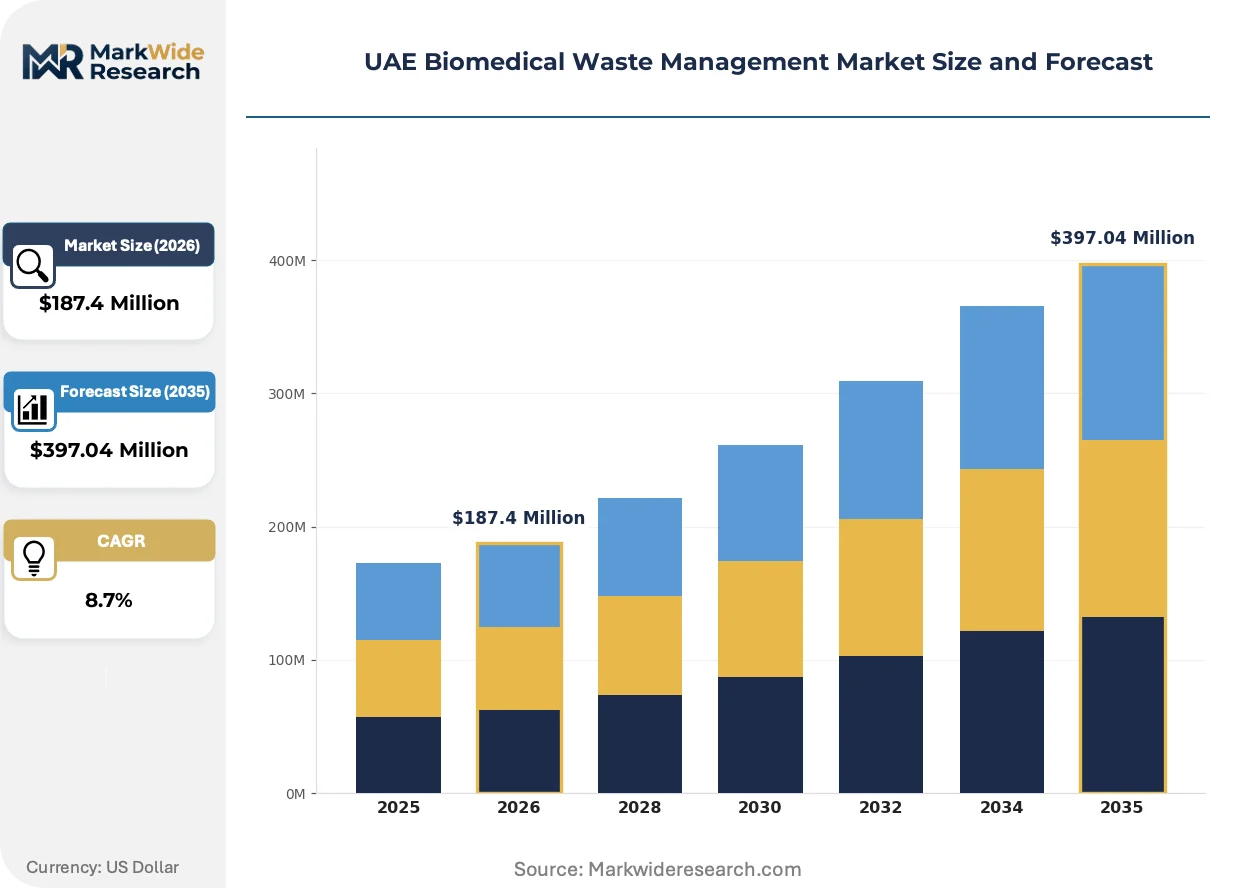
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Waste Type: Infectious Waste, Hazardous Waste, Non-Hazardous Waste, Sharp Waste Service Type: Collection, Transportation, Treatment, Disposal End User: Hospitals, Clinics, Laboratories, Research Facilities Regulatory Compliance: Local Standards, International Guidelines, Industry Regulations, Safety Protocols |
| Companies Covered | Dulsco Waste Management, Averda, Veolia Environment S.A., Suez Environment S.A., Bee'ah, Remondis Medison GmbH, Alserkal Group, Sharpsmart, Ramco Environmental Services, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAE Biomedical Waste Management Market Trends and Innovations
Automation is penetrating waste segregation workflows while regulatory verification requirements harden documentation standards. Procurement criteria now weight technology infrastructure equally with per-kilogram pricing.
RFID-enabled waste containers is digitizing chain-of-custody tracking from hospital ward through final treatment. Dubai hospital networks are mandating sensor-equipped bins for infectious waste streams above 20-liter volumes. This compression of manual documentation steps is enabling same-day audit response and reducing insurance premium loads for high-volume generators.
MOHAP's updated biomedical waste handling protocols now require third-party verification of autoclave cycle parameters. Facility licensing audits now probe treatment logs against RFID timestamp records. Private hospital groups in Abu Dhabi are responding by consolidating vendor relationships to reduce audit surface area.
Long-term service agreements are displacing spot-rate collection contracts across UAE government hospital networks. Procurement teams now bundle transportation, treatment, and compliance reporting into single-source arrangements spanning 5-7 years. This consolidation pattern is most visible in Dubai's Ministry of Health-affiliated facilities, where total-cost-of-ownership models now dominate vendor selection committees.
UAE Biomedical Waste Management Market Segmentation
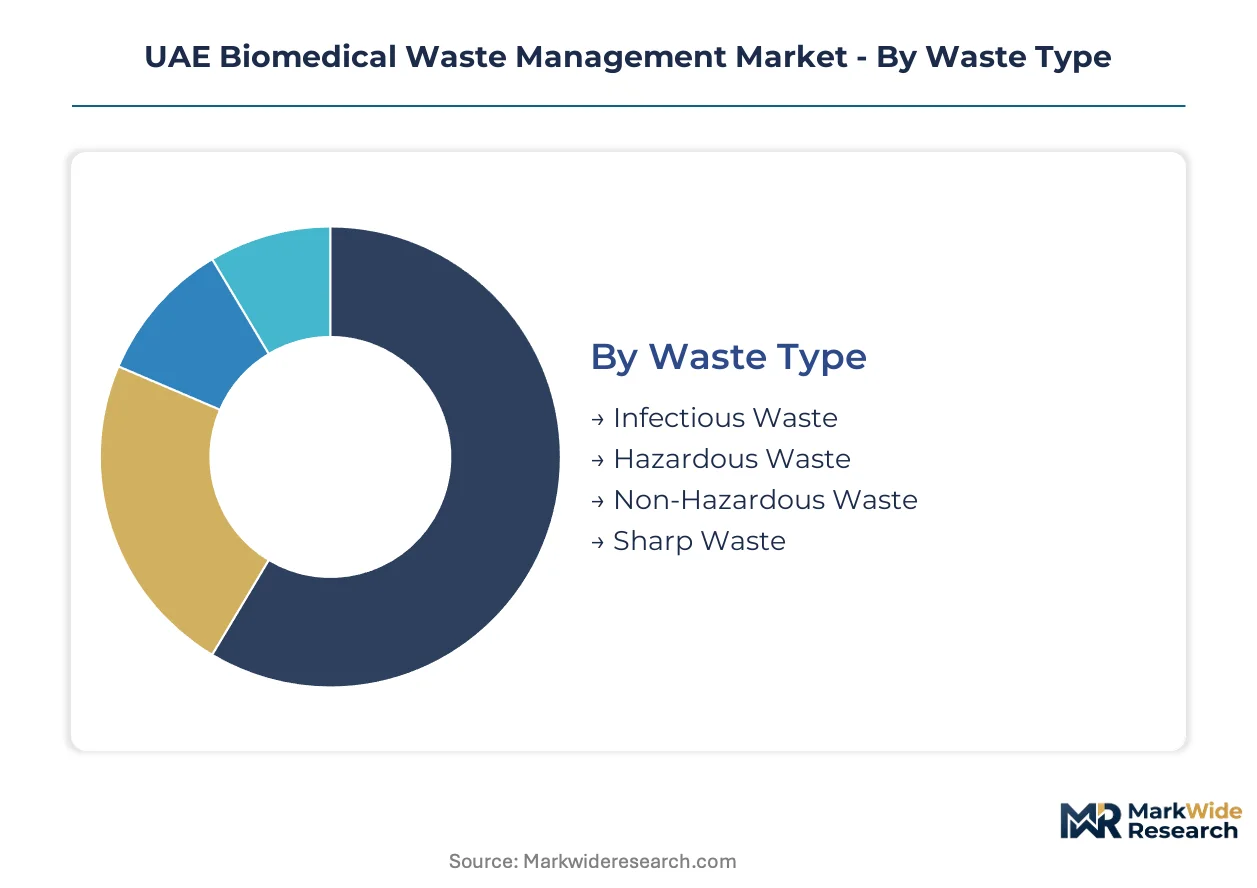
Segmentation in UAE biomedical waste management reveals distinct operational intensities across waste streams and service tiers. Each category carries unique capital requirements, regulatory exposure, and margin profiles that shape vendor positioning and contract structures.
Waste Type:
After-sales service intensity peaks with infectious and sharp waste categories, where treatment verification and liability documentation demand continuous vendor engagement beyond initial collection.
- Infectious Waste:Pathogen-contaminated materials including blood-soaked items, cultures, and patient isolation waste requiring autoclaving at 121°C for minimum 30 minutes or thermal oxidation to achieve 99.9999% pathogen destruction. Dubai hospital networks generate the highest per-facility volumes, with MOHAP's third-party verification mandate forcing handlers to maintain dedicated treatment audit trails.
- Sharp Waste:Needles, scalpels, and piercing instruments capable of causing injury and disease transmission through skin penetration. Research facilities in Abu Dhabi produce disproportionately hazardous streams requiring specialized containment protocols and premium pricing tiers distinct from general biomedical categories.
- Hazardous Waste:Chemical, pharmaceutical, and cytotoxic materials exhibiting toxic, corrosive, or reactive properties. MOHAP licensing audits probe disposal chain documentation for these streams.
- Non-Hazardous Waste:General medical waste excluding infectious, sharp, or hazardous classifications, comprising packaging and uncontaminated materials. Route-density economics in Dubai corridors compress collection margins for this category.
By volume, non-hazardous waste leads. By growth pace, sharp waste is ahead.
Service Type:
Cost tier stratification separates capital-intensive treatment infrastructure from logistics-dependent collection operations with divergent margin profiles.
- Treatment:Thermal oxidation, autoclaving, and chemical disinfection processes achieving regulatory sterilization standards. Incinerator and autoclave infrastructure in Dubai Healthcare City and Al Ain commands margin concentration due to 7-10 year depreciation cycles and energy input volatility.
- Disposal:Final landfill placement or energy recovery following verified pathogen destruction. Abu Dhabi government hospital networks prioritize vendors with integrated treatment-disposal footprints over fragmented providers.
- Collection:Scheduled pickup services from generation points using dedicated biomedical waste vehicles. Dubai's healthcare infrastructure density drives route optimization competition among handlers.
- Transportation:Inter-facility and cross-emirate movement of segregated waste streams. Dubai Municipality and Environment Agency Abu Dhabi maintain non-harmonized manifest systems creating documentation friction.
By revenue concentration, treatment leads. By contract bundling momentum, disposal is expanding most quickly.
End User:
Customer type differentiation separates high-volume hospital generators from specialized research facilities with divergent waste complexity and compliance sensitivity.
- Hospitals:Multi-department acute care facilities producing the highest per-facility waste volumes across all categories. Dubai and Abu Dhabi hospital networks are expanding outsourced waste handling contracts with 5-7 year single-source arrangements.
- Research Facilities:Biomedical and pharmaceutical research operations generating pathogen-grade waste requiring dedicated handling protocols. These facilities command premium pricing outside standard hospital contracts due to specialized containment requirements.
- Laboratories:Diagnostic and clinical testing operations producing concentrated chemical and biological waste streams. MOHAP facility licensing applies stringent audit regimes to laboratory waste documentation.
- Clinics:Outpatient and primary care facilities with lower per-site volumes but distributed geographic footprints. Northern emirates show 40% lower service coverage density for clinic networks compared to Dubai-Abu Dhabi corridors.
By facility count, clinics lead. By revenue per site, research facilities are gaining share fastest.
Regulatory Compliance:
Maturity gradients separate established local standards from emerging international alignment requirements with divergent certification timelines and audit frequencies.
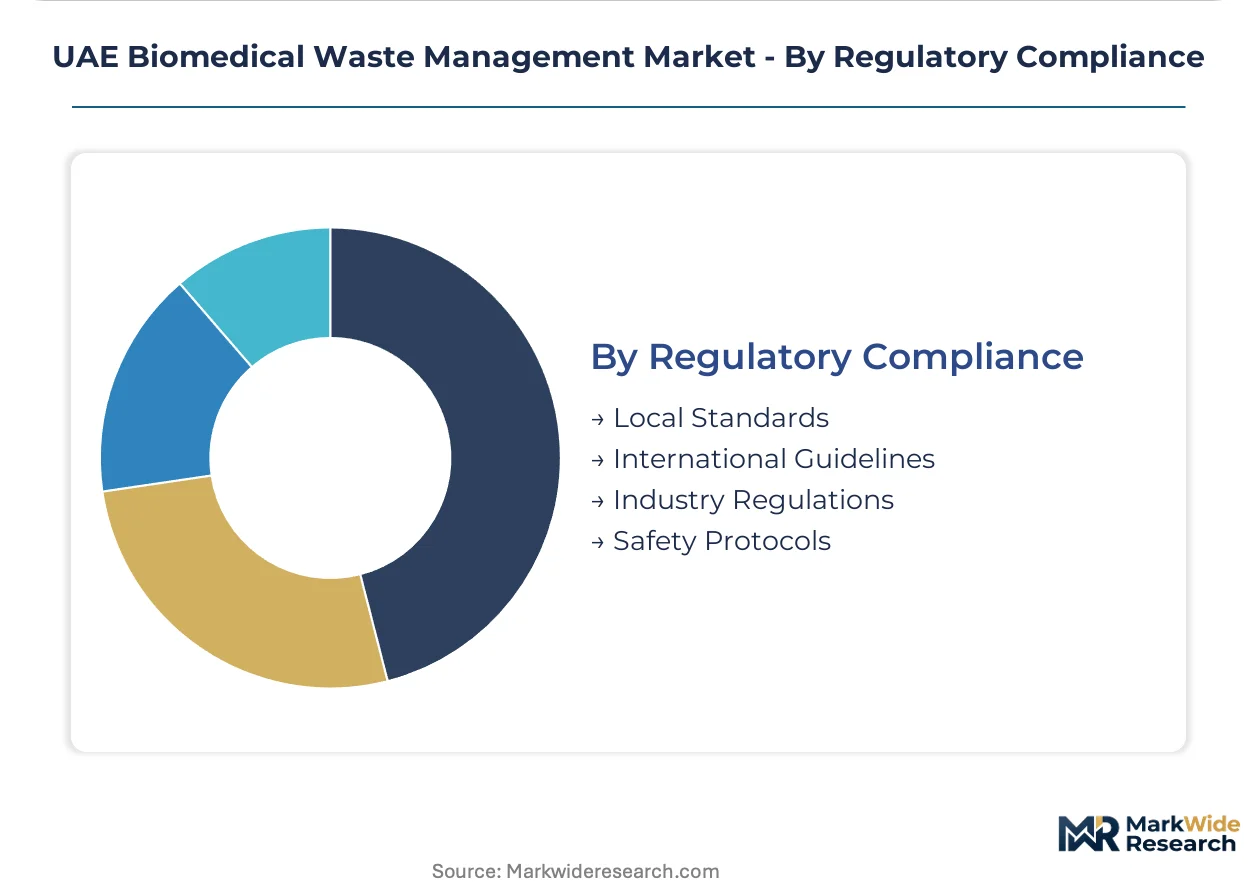
- Local Standards:MOHAP biomedical waste protocols and Dubai Municipality regulations governing facility licensing and periodic audit regimes. These standards enforce third-party treatment verification and RFID-autoclave convergence requirements.
- International Guidelines:WHO biomedical waste management standards and pending ISO 14001 environmental management adoption for UAE healthcare facilities. Alignment with these guidelines tightens compliance thresholds for new market entrants.
- Industry Regulations:Sector-specific protocols from healthcare free zone authorities and professional association codes. Dubai Healthcare City operates under licensing timelines divergent from mainland jurisdictions.
- Safety Protocols:Occupational health requirements for hazmat technician certification and autoclave supervision. UAE vocational pipelines produce insufficient certified operators for current infrastructure needs.
By enforcement consistency, local standards lead. By procurement weighting, international guidelines show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement teams in Dubai and Abu Dhabi dominate buyer concentration, with government-affiliated networks driving contract consolidation toward integrated service providers. Northern emirates present coverage gaps that attract specialized entrants seeking density economics.
Dubai
Dubai Healthcare City expansion generates concentrated infectious waste volumes requiring route-optimized collection networks. Dubai Municipality's Waste Management Department mandates RFID-equipped containers for streams above 20-liter thresholds. Healthcare clusters in Dubai Healthcare City and Jebel Ali Free Zone anchor outsourced handling contracts with 5-7 year terms.
Abu Dhabi
Government hospital networks in Abu Dhabi prioritize vendors with captive treatment infrastructure over fragmented logistics providers. Environment Agency Abu Dhabi coordinates cross-emirate transfer documentation with Dubai counterparts. Medical City and mainland hospital zones are consolidating vendor relationships to reduce audit surface area under MOHAP verification protocols.
Sharjah
Sharjah exhibits 40% lower biomedical waste service coverage density than Dubai-Abu Dhabi corridors, creating penetration opportunities for handlers with northern emirate logistics. Bee'ah anchors specialized sharps containment capabilities serving this jurisdiction. University Hospital Sharjah and government clinic networks are expanding outsourced contracts as infrastructure density improves.
Ras Al Khaimah
Ras Al Khaimah's healthcare infrastructure generates lower per-facility waste volumes but distributed geographic footprints complicate route economics. Saqr Hospital and emerging private clinic clusters require dedicated collection scheduling. The emirate's industrial zones offer alternative treatment access points for handlers with cross-emirate logistics capabilities.
Fujairah
Fujairah's eastern coastal position creates documentation friction for waste movement to Dubai-Abu Dhabi treatment hubs. Dibba and Fujairah City hospital networks face longer transportation legs that compress collection margins. The emirate's port infrastructure could support maritime logistics alternatives for bulk waste transfer to centralized facilities.
UAE Biomedical Waste Management Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three distinct tiers. Integrated collection-treatment operators command premium positioning through captive infrastructure, while logistics-focused handlers face margin compression from route-density competition. Strategic archetypes separate capital-heavy incinerator-autoclave owners, technology-embedded tracking specialists, and regional logistics consolidators. Dominant competitive moves include long-term contract bundling and RFID-autoclave convergence for audit compliance.
Within the integrated infrastructure tier, Averda and Dulsco Waste Management exemplify channel-controlling positioning through collection-treatment footprints across Dubai Healthcare City and Abu Dhabi government networks. Bee'ah occupies a specialization anchor in northern emirates sharps containment. These three handlers represent the archetype spectrum from capital-intensive thermal oxidation to logistics-optimized geographic coverage.
| Leading Market Players |
|---|
| Dulsco Waste Management |
| Averda |
| Veolia Environment S.A. |
| Suez Environment S.A. |
| Bee'ah |
| Remondis Medison GmbH |
| Alserkal Group |
| Sharpsmart |
| Ramco Environmental Services |
| Others |
Pricing and Supply Chain Analysis
Dubai-Abu Dhabi corridor freight economics compress collection margins for northern emirate handlers while rewarding integrated operators with captive treatment infrastructure. Supply concentration around Dubai Healthcare City and Al Ain thermal oxidation facilities enables price differentiation between route-optimized incumbents and logistics-dependent challengers.
Pricing Analysis
Cost-plus contracts with natural gas indexation dominate long-term service agreements between government hospital networks and integrated waste handlers. Three-tier pricing structure across premium, standard, and economy levels separates RFID-autoclave verified treatment from basic collection-only services. Pricing pressure stems from route-density competition in Dubai corridors where Averda and Dulsco leverage infrastructure scale. Government hospital procurement committees show lowest price sensitivity due to MOHAP compliance mandates, while distributed clinic networks in northern emirates negotiate hardest on per-kilogram rates.
Supply Chain Analysis
Tariff exposure between UAE and European autoclave equipment suppliers dominates capital procurement risk for treatment infrastructure expansion. Supply concentration rests on German and Italian sterilization equipment manufacturers, Chinese RFID sensor providers, and domestic steel fabrication for container production. Single-source vulnerability runs through specialized sharps containment resin suppliers in Saudi Arabia and India. Distribution runs through Dubai Healthcare City as the primary consolidation hub, with cross-emirate transfer to Abu Dhabi and northern emirate spokes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent waste handlers face substitution threat from on-site autoclave installations at large hospital networks seeking audit simplification. Defense requires deepening integration into treatment verification technology and geographic coverage density.
For Market Incumbents: Build regulatory compliance moats through ISO 14001 certification investment and RFID-autoclave convergence capabilities. Consolidate vendor relationships across Dubai and Abu Dhabi government hospital networks to reduce audit surface area under MOHAP verification protocols. Expand captive treatment infrastructure into northern emirates before logistics specialists establish density economics. Threat of hospital on-site sterilization capacity requires pre-emptive long-term contract bundling at 5-7 year terms.
For New Entrants and Emerging Players: Pursue northern emirate penetration in Sharjah, Ras Al Khaimah, and Fujairah where service coverage density trails Dubai-Abu Dhabi corridors by substantial margins. Target research laboratory specialization with dedicated pathogen-grade waste handling protocols outside standard hospital contract scopes. Go-to-market angle should emphasize sharps containment expertise and university hospital relationships rather than competing on collection route density against integrated incumbents.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified environmental services parents seeking to monetize UAE healthcare waste verticals. Long-term viability hinges on treatment infrastructure ownership rather than pure logistics positioning across the 5-10 year window. Acquisition focus should center on handlers with Dubai Healthcare City or Al Ain thermal oxidation assets and existing MOHAP audit relationships. Signal to watch is consolidation of government hospital procurement into single-source arrangements, which accelerates vendor selection in favor of integrated operators.
| Strategic Initiative | Industry Significance |
|---|---|
| RFID-Autoclave Convergence | Embedded tracking sensors linked to sterilization cycle verification create auditable chain-of-custody records for liability reduction under MOHAP protocols. |
| Northern Emirate Logistics Expansion | Route optimization in Sharjah and Ras Al Khaimah captures underserved clinic networks and university hospital waste volumes. |
| Research Laboratory Specialization | Dedicated pathogen-grade handling protocols for biomedical research facilities command premium pricing outside standard hospital contracts. |
| Long-Term Contract Bundling | 5-7 year single-source arrangements with government hospital networks reduce audit surface area and lock in recurring revenue streams. |
| ISO 14001 Certification Investment | Environmental management standard alignment tightens compliance thresholds and creates recurring audit revenue for certified operators. |
Research Methodology
Desk research of MOHAP regulatory filings, Dubai Municipality waste management permits, and Environment Agency Abu Dhabi transfer documentation preceded structured interviews with hospital procurement managers, biomedical waste operations directors, hazmat technician training providers, and GPO contract administrators. Secondary validation drew from WHO biomedical waste guidelines, ISO 14001 draft standards for UAE healthcare facilities, and customs records for autoclave and incinerator equipment imports. Bottom-up facility-level waste volume estimates triangulated against top-down emirate healthcare infrastructure spending data.
Assumptions held fixed include MOHAP enforcement consistency across free zone and mainland jurisdictions, natural gas pricing within UAE commercial utility bands, and RFID-autoclave convergence as the dominant technology trajectory. Variables tested across the analysis window encompass northern emirate infrastructure buildout pace, hospital on-site sterilization adoption rates, and ISO 14001 certification timeline acceleration. Segmentation modeling spanned waste type, service tier, end-user category, and regulatory compliance maturity. CAGR derivation rested on facility expansion pipelines, contract renewal patterns, and per-bed waste generation intensity benchmarks.
Macroeconomic conditions sit as an overlay; deviation in UAE healthcare capital expenditure cycles or natural gas pricing volatility would shift the trajectory. Forecasts reflect assumptions about regulatory enforcement continuity and technology adoption curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste Management & Pollution Control
Construction Waste Market
Waste Management & Pollution Control
Scrap Metal Recycling Market
Waste Management & Pollution Control
Hazardous Waste Handling Automation Market
Waste Management & Pollution Control
Polyfluoroalkyl Substances (PFAS) Waste Management Market
Waste Management & Pollution Control
Asia-Pacific Industrial Waste Management Market
Waste Management & Pollution Control
Nutrient Recycling Market
Waste Management & Pollution Control
North America Municipal Solid Waste Management Market
Waste Management & Pollution Control
Saudi Arabia Waste Management Market
Waste Management & Pollution Control
Metal Recycling Equipment Market
Waste Management & Pollution Control
Retail Food Waste-to-Biogas Logistics and Treatment Networks in Europe Market
Waste Management & Pollution Control
Europe Industrial Waste Management Market
Waste Management & Pollution Control
Metal Recycling Baler Market
Waste Management & Pollution Control
Global Waste Oil Market
Waste Management & Pollution Control
Waste Paper Management Market
Waste Management & Pollution Control
North America Waste Management Market
Waste Management & Pollution Control
Waste Compactor Bins Market