
 Waste Recycling Services Market | 2026-2036
Waste Recycling Services Market Size, Share, and Industry Trends Forecast 2026-2036
Waste Recycling Services Market Intelligence
Recycled PET is consolidating share against virgin resin in beverage packaging, compressing collection economics and forcing recyclers to secure tighter feedstock control. Veolia leverages its integrated collection-processing network across France and the UK to lock in municipal contracts. Waste Management anchors North American volume through landfill-gas-to-energy co-location with recycling hubs. Republic Services differentiates via single-stream automation investments that lower contamination penalties.
Waste recycling services encompass the systematic collection, sorting, processing, and reclamation of discarded materials into reusable feedstock, typically requiring contamination rates below 10 percent for mechanical reprocessing viability. These services convert post-consumer and post-industrial waste streams into secondary raw materials for manufacturing substitution. Collection and processing together capture the largest value pools, while chemical recycling represents the fastest-expanding technology segment as it handles mixed and contaminated plastics that mechanical systems reject. Metals recovery maintains mature, margin-stable operations owing to established scrap pricing benchmarks and smelter offtake agreements.
The EPA enforces national recycling contamination standards under the Resource Conservation and Recovery Act, while the EU Green Deal's packaging waste directives mandate minimum recycled content thresholds that reshape importer compliance costs. China's National Sword policy and subsequent GB standards on recyclable imports forced Western operators to build domestic sorting capacity rather than export mixed paper and plastics. Stakeholders must monitor how extended producer responsibility rollouts in additional US states reshape collection financing and processor gate fee structures.
Market Dynamics
The waste recycling services market is undergoing a fundamental restructuring as extended producer responsibility mandates shift collection financing from municipalities to brand owners, forcing processors to renegotiate gate fees and feedstock security simultaneously.
Growth Catalysts
- EU Green Deal packaging directives:Minimum recycled content thresholds for PET bottles and contact-sensitive packaging are tightening offtake agreements between reclaimers and converters across Germany, France, and Italy.
- Optical sorting AI:Near-infrared and robotics integration in materials recovery facilities is cutting contamination rates below 5% for mixed plastics streams previously rejected by mechanical reprocessors.
- Landfill-gas-to-energy co-location:Integrated hub operators in Texas and California are capturing methane revenue streams that subsidize adjacent sorting and processing infrastructure.
Market Restraints
- Feedstock price volatility:Virgin resin price crashes linked to petrochemical overcapacity in the Gulf Coast are eroding recycled polymer premiums and compressing reclaimer margins.
- China's GB standards:Post-National Sword import prohibitions on mixed paper and contaminated plastics have stranded Western export-dependent sorters without domestic outlet infrastructure.
- Chemical recycling capex intensity:Pyrolysis and depolymerization facilities require $200-400 million per plant, limiting deployment to integrated oil majors with balance sheet capacity.
Strategic Opportunities
- India's informal sector formalization:The country's Plastic Waste Management Rules and EPR notifications are creating structured collection partnerships with waste picker cooperatives in Mumbai and Delhi.
- Food-contact rPET certification:FDA and EFSA no-objection letters for advanced recycling outputs are opening beverage and dairy packaging applications previously closed to mechanically recycled resin.
- Digital waste tracking:Blockchain-verified chain-of-custody platforms are emerging as a new channel for proving recycled content claims to CSRD-reporting corporates.
Industry Challenges
- Contamination control expertise:Materials recovery facilities face acute shortages of technicians trained in spectroscopic sorting calibration and polymer identification.
- Legacy MRF retrofit complexity:Single-stream facilities built for 2000s waste streams require $15-30 million upgrades to handle flexible packaging and multi-layer films now entering curbside collection.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Waste Recycling Services Market |
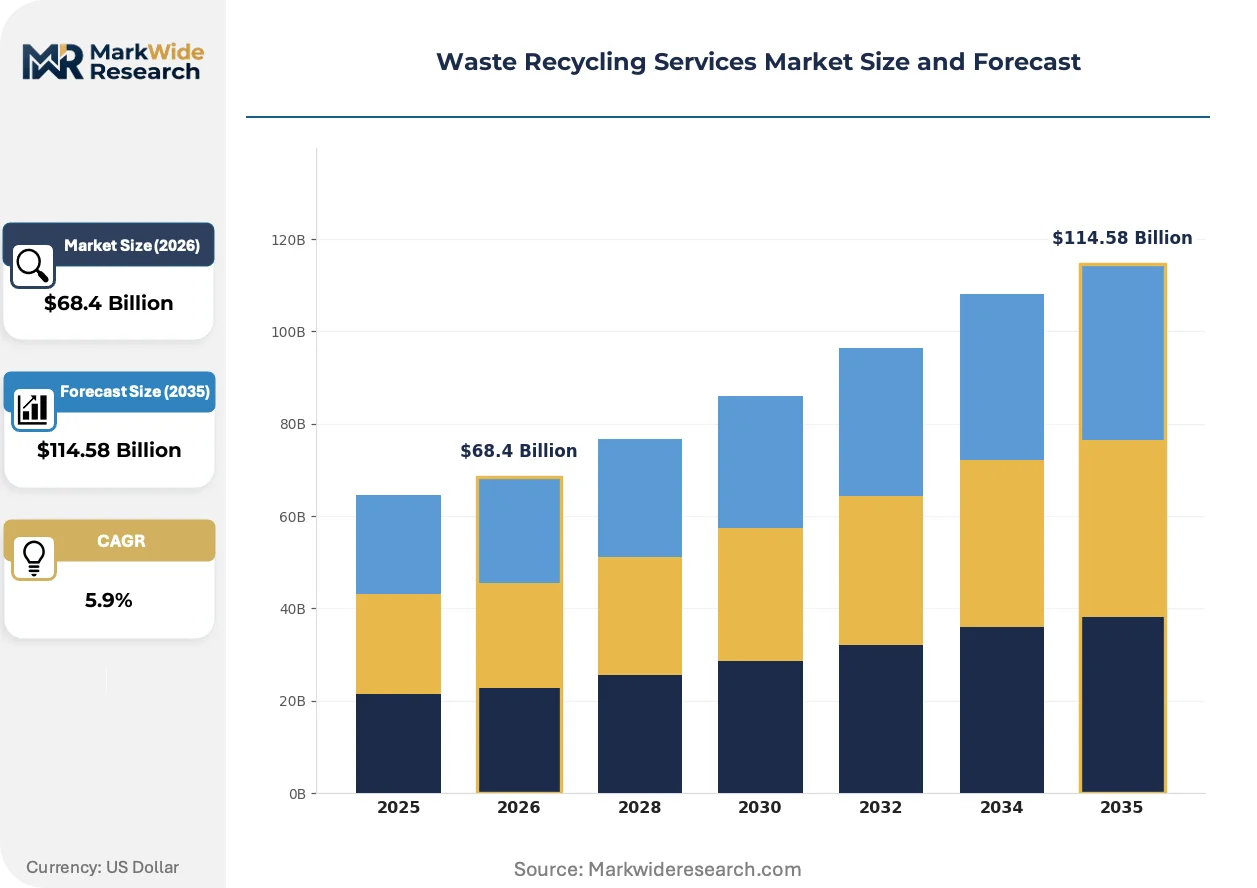
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $114.58 Billion |
| CAGR (2026 – 2036) | 5.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Collection, Sorting, Processing, Disposal Material Type: Plastics, Metals, Glass, Paper End User: Households, Businesses, Municipalities, Industries Technology: Mechanical, Biological, Thermal, Chemical |
| Companies Covered | Veolia, Clean Harbors, Waste Management, China Everbright Environment Group, Casella Waste Systems, Republic Services, GFL Environmental, Cleanaway Waste Management, Waste Connections, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Waste Recycling Services Market Strategic Shifts & Innovations
Technology convergence and regulatory precision are compressing the gap between collection and re-manufacturing, eliminating intermediate trading steps that previously absorbed margin.
Advanced robotics with AI-trained grippers is rewriting the economics of mixed-waste sorting by identifying and extracting film, flexibles, and composite packaging at speeds exceeding human pickers. European MRF operators in the Netherlands and Belgium are deploying these systems at commercial scale. The technology is rewriting labor models and enabling facilities to process streams previously rejected as uneconomical.
The EPA's forthcoming national recycling strategy under the Resource Conservation and Recovery Act is tightening contamination standards for municipal bales shipped across state lines. This regulatory pressure is forcing MRFs to invest in secondary sorting or risk losing access to end-market buyers. The reclaimer segment in the southeastern United States is responding by demanding cleaner inbound material and rejecting loads exceeding 3% non-target residue.
Brand owners are consolidating procurement around vertically integrated recyclers with certified chain-of-custody documentation rather than spot-market traders. This behavioral shift is displacing traditional brokers in polyethylene and polypropylene feedstock sourcing. The pattern is most visible in California and Washington where EPR laws mandate recycled content verification.
Waste Recycling Services Market Segmentation
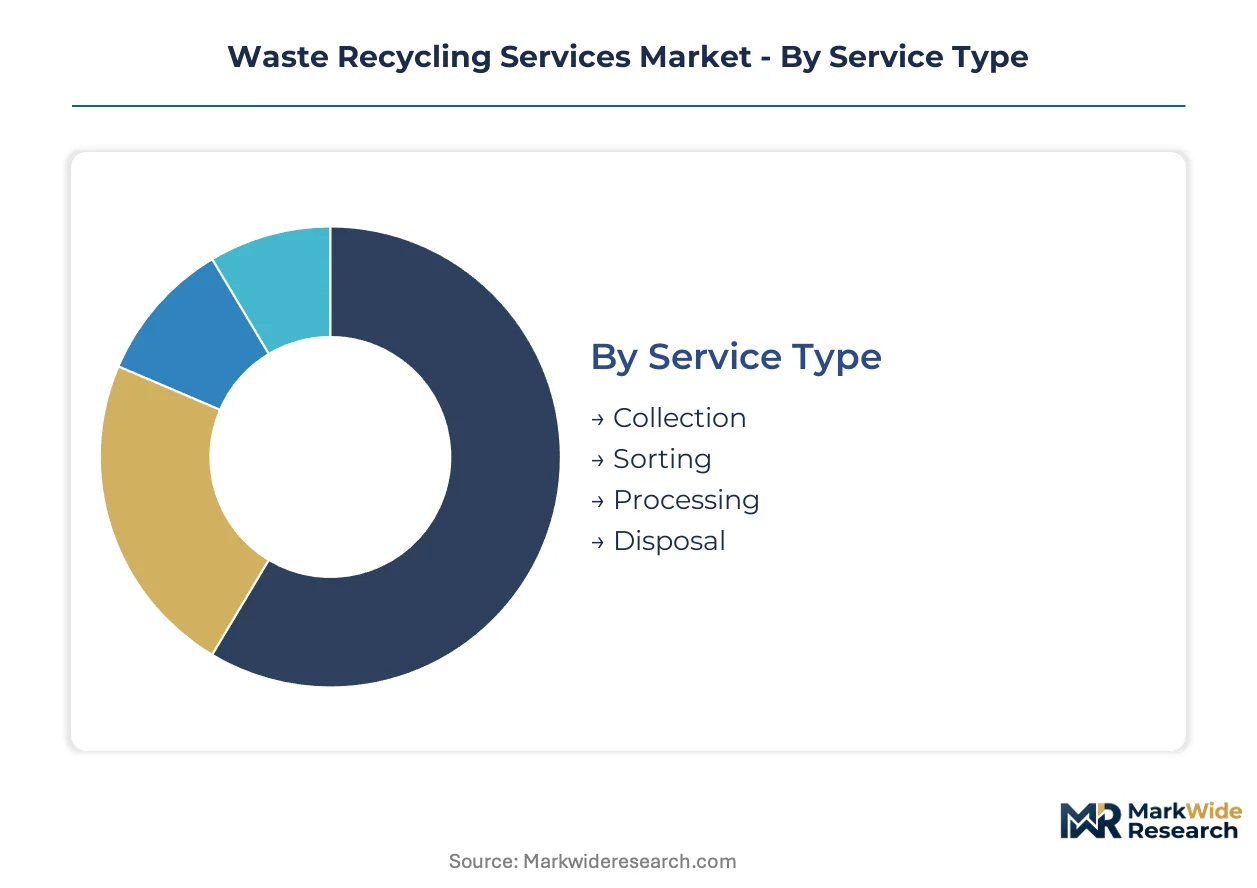
Waste recycling services fragment across four operational dimensions that determine contract structure and capital deployment. Service type dictates asset intensity and labor ratios. Material type governs end-market pricing volatility and contamination tolerance.
Service Type:
Buyers select service tiers based on their internal waste handling capabilities and regulatory compliance burdens.
- Collection:Curbside and commercial pickup operations require fleet assets and route optimization software. Municipal contracts in Germany and France are consolidating under EPR mandates that shift financing from taxpayers to brand owners. Collection margins compress where single-stream programs raise contamination penalties.
- Sorting:Materials recovery facilities employ optical scanners and robotics to separate mixed streams into commodity-grade bales. Advanced AI-driven systems in the Netherlands and Belgium now process flexible packaging previously rejected as uneconomical. Sorting investments determine downstream reclaimer offtake security.
- Processing:Mechanical regrinding, washing, and pelletizing convert sorted feedstock into manufacturing-ready resin. Gulf Coast petrochemical overcapacity erodes recycled polymer premiums, forcing processors toward food-contact certification to capture value.
- Disposal:Landfill operations and waste-to-energy facilities handle residual fractions that fail quality thresholds. Methane capture installations in Texas and California generate revenue streams that subsidize adjacent recycling infrastructure.
Collection leads on scale; sorting leads on momentum.
Material Type:
Material selection hinges on contamination economics and end-market liquidity.
- Plastics:PET, HDPE, and polypropylene streams dominate mechanical reprocessing volumes. FDA and EFSA no-objection letters for advanced recycling outputs are opening beverage and dairy packaging applications previously closed to mechanically recycled resin.
- Metals:Ferrous and non-ferrous scrap maintains mature, margin-stable operations through established pricing benchmarks and smelter offtake agreements. Aluminum recovery from municipal streams concentrates in industrial corridors with foundry proximity.
- Glass:Container cullet requires color separation and beneficiation to meet container-grade specifications. Glass recycling margins narrow where single-stream collection raises ceramic and stone contamination.
- Paper:OCC and mixed paper grades face demand pressure from China's GB standards prohibiting contaminated imports. Domestic mills in the southeastern United States now demand cleaner inbound material, rejecting loads exceeding 3% non-target residue.
Metals deliver margin stability; plastics face the steepest expansion trajectory in food-contact applications.
End User:
Contract structures vary sharply across customer categories.
- Households:Curbside programs generate volume but suffer from aspirational recycling behavior that elevates contamination. EPR rollouts in California and Washington are shifting collection financing from municipal budgets to producer fees.
- Businesses:Commercial generators negotiate service agreements based on waste audit data and diversion rate targets. Corporate sustainability mandates are consolidating procurement around vertically integrated recyclers with certified chain-of-custody documentation.
- Municipalities:Local governments issue RFPs that bundle collection, sorting, and residual disposal. Contract durations are shortening as EPR frameworks reallocate financial responsibility.
- Industries:Manufacturing offcuts and post-industrial scrap offer cleaner, more homogeneous feedstock than post-consumer streams. Automotive and electronics sectors generate specialized metal and plastic fractions with dedicated recovery pathways.
Households anchor volume; industries command premium pricing.
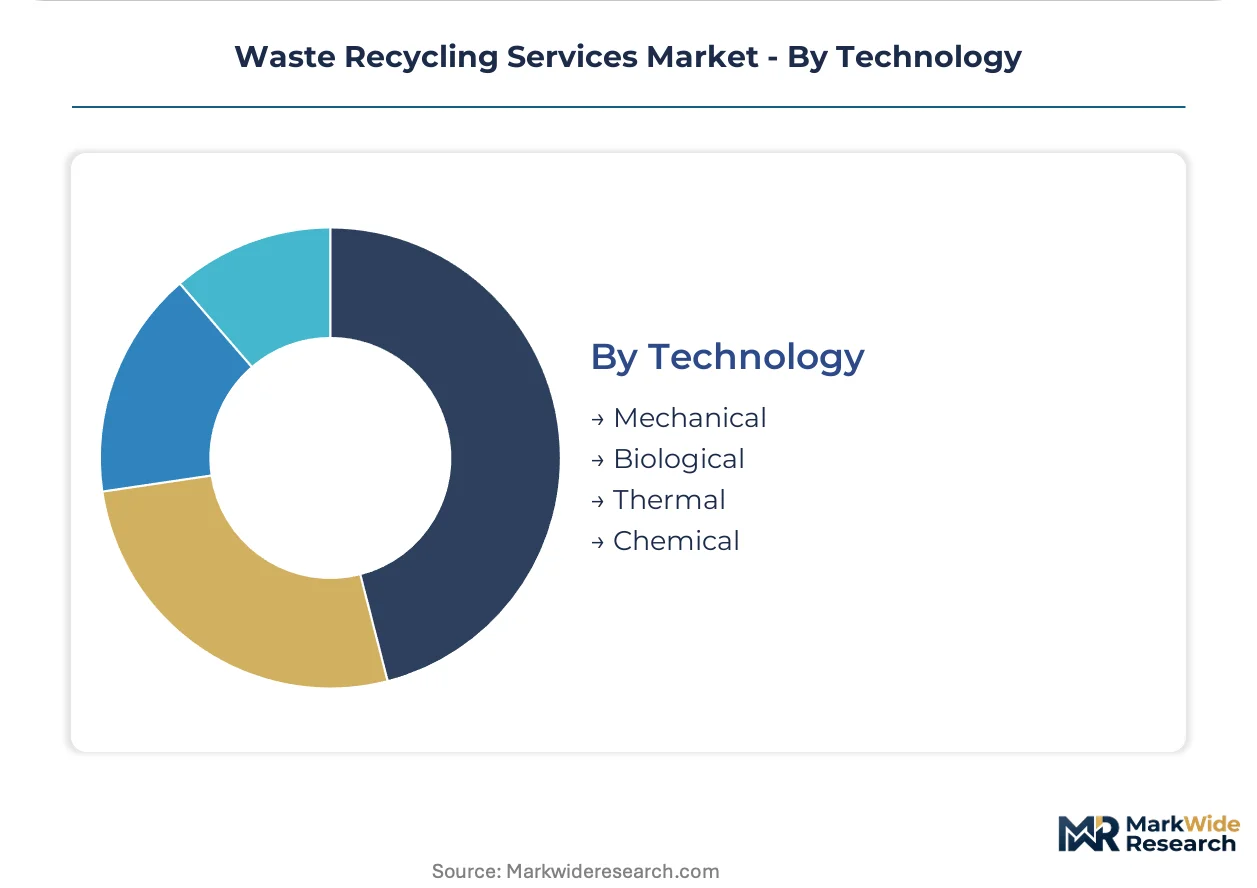
Technology:
Technology selection determines acceptable feedstock quality and output specifications.
- Mechanical:Grinding, washing, and extrusion systems require contamination rates below 10% for viable operation. Legacy MRFs built for 2000s waste streams need $15-30 million upgrades to handle flexible packaging and multi-layer films.
- Biological:Anaerobic digestion and composting process organic fractions into soil amendments and biogas. Facilities co-located with agricultural demand centers capture higher gate fees than standalone operations.
- Thermal:Incineration with energy recovery handles residual waste streams that fail recycling quality thresholds. EPA emission standards under the Clean Air Act constrain facility siting and capital deployment.
- Chemical:Pyrolysis and depolymerization convert mixed, contaminated, and degraded plastics into virgin-equivalent feedstock. Capex intensity of $200-400 million per plant limits deployment to integrated operators with balance sheet capacity.
Mechanical dominates installed capacity; chemical recycling is expanding most quickly as brand owners seek food-contact compliant outputs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Ruhr industrial corridor anchors European recycling infrastructure investment, with integrated sorting and chemical processing clusters driving capacity expansion. Divergent regulatory timelines across major economies are reshaping cross-border feedstock flows and equipment procurement patterns.
United States
Extended producer responsibility laws in California and Washington are restructuring municipal collection financing toward brand-owner fees. The EPA's Resource Conservation and Recovery Act enforcement tightens contamination standards for interstate bale shipments. Texas and California host integrated hub operators co-locating landfill-gas-to-energy with sorting infrastructure.
Germany
Municipalities are expanding source-separated collection programs under EU Green Deal circular economy mandates. The country's packaging waste directives enforce minimum recycled content thresholds for PET bottles. The Rhine-Ruhr corridor concentrates advanced optical sorting deployment in materials recovery facilities.
China
Domestic sorting capacity construction accelerated after National Sword policy and GB standards prohibited contaminated imports. The country's dual carbon goals drive investment in mechanical reprocessing for post-consumer plastics. Yangtze River Delta cities host pyrolysis pilot facilities targeting mixed polymer streams.
India
Plastic Waste Management Rules and EPR notifications are formalizing partnerships with waste picker cooperatives in Mumbai and Delhi. The central pollution control board enforces extended producer responsibility frameworks for brand owners. Gujarat and Maharashtra industrial corridors attract mechanical recycling investments for post-industrial scrap.
Netherlands
Materials recovery facilities in Rotterdam and Amsterdam deploy AI-driven robotics for flexible packaging extraction previously rejected as uneconomical. The EU Green Deal's packaging directives tighten offtake agreements between reclaimers and converters. The Randstad region concentrates chemical recycling pilot investments targeting food-contact rPET certification.
Waste Recycling Services Market Key Industry Players
Global majors compete with regional champions across collection infrastructure and processing technology deployment. The market structures around three tiers: integrated waste-to-energy operators with captive sorting networks, specialized materials recovery facility pure-plays, and municipal contractors with geographic concentration. Two archetypes dominate: vertically integrated hub operators leveraging landfill-gas revenue subsidies, and technology-forward sorters capturing premium feedstock through contamination control. Competitive moves concentrate on municipal contract consolidation and optical sorting automation deployment.
Among French and UK-based integrated operators, Veolia anchors the vertically integrated archetype with municipal contract networks spanning collection through reprocessing. North American volume leaders Waste Management and Republic Services occupy distinct positioning vectors—one leveraging landfill-gas-to-energy co-location economics, the other emphasizing single-stream automation investments that lower contamination penalties. These three exemplify how scale and technology differentiation separate market positions.
| Leading Market Players |
|---|
| Veolia |
| Clean Harbors |
| Waste Management |
| China Everbright Environment Group |
| Casella Waste Systems |
| Republic Services |
| GFL Environmental |
| Cleanaway Waste Management |
| Waste Connections |
| Others |
Cost & Logistics Intelligence
Municipal procurement departments concentrate buying power through multi-year collection and processing contracts, locking in gate-fee structures that favor integrated operators with landfill-gas revenue diversification over pure-play sorters exposed to commodity resin volatility.
Pricing Analysis
Input-cost pass-through dominates contract economics as recyclers index gate fees to virgin resin benchmarks and energy costs. Three-tier pricing structure across food-contact certified, industrial-grade, and non-specification material levels separates premium reclaimers from commodity traders. Pricing pressure stems from Gulf Coast petrochemical overcapacity eroding recycled polymer premiums. Small municipal programs exhibit highest price sensitivity due to taxpayer-funded budget constraints, while Fortune 500 brand owners under EPR mandates show lowest sensitivity when securing certified chain-of-custody documentation.
Supply Chain Analysis
Reverse-logistics networks for post-consumer packaging return flows center on materials recovery facilities in Germany, the Netherlands, and the United States as primary sorting hubs. Feedstock draws from curbside collection fleets, commercial waste brokers, and informal sector aggregators in emerging markets. Single-source vulnerability concentrates in optical sorting equipment where European and Japanese suppliers dominate hardware procurement. Distribution runs through reclaimer offtake agreements with converters rather than spot-market trading, compressing intermediary margins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Waste recycling services function as a regulatory compounder where EU Green Deal packaging directives and proliferating US state EPR laws continuously tighten recycled content thresholds and reshape collection financing mechanics.
For Market Incumbents: Anticipate margin compression from chemical recycling entrants targeting food-contact applications by securing backward integration into municipal collection contracts and investing in FDA no-objection letter pathways for advanced recycling outputs. Lock in long-term offtake agreements with beverage and dairy converters before pyrolysis capacity scales. For New Entrants and Emerging Players: Mid-sized industrial generators in automotive and electronics corridors represent underserved buyers seeking dedicated post-industrial scrap recovery with transparent chain-of-custody documentation. Target Gujarat and Maharashtra industrial zones in India where formalization partnerships with waste picker cooperatives offer low-cost feedstock aggregation. Lead with digital waste tracking platforms to differentiate against legacy brokers. For Investors and Strategic Acquirers: Integrated oil majors with balance sheet capacity for chemical recycling capex are the most active acquirers in this space, consolidating pyrolysis technology developers and feedstock aggregators. Five-to-ten-year viability hinges on EPR rollout pace across additional US states. Acquisition target archetype: materials recovery facilities with optical sorting automation and existing municipal contract networks. Monitor EPA national recycling strategy implementation timelines as inflection indicator for contamination standard tightening and interstate bale shipment restrictions.| Strategic Initiative | Industry Significance |
|---|---|
| Optical Sorting Automation Deployment | AI-driven robotics in Netherlands and Belgium facilities cut contamination below 5% for flexible packaging streams. |
| Chemical Recycling Capacity Buildout | Pyrolysis investments by integrated oil majors unlock food-contact rPET certification previously closed to mechanical reclaimers. |
| Municipal Contract Consolidation | Veolia and Waste Management leverage landfill-gas revenue subsidies to undercut pure-play sorters on gate fees. |
| Digital Chain-of-Custody Platform | Blockchain-verified tracking meets CSRD reporting requirements for brand owners consolidating procurement around certified recyclers. |
| Informal Sector Formalization Partnership | Waste picker cooperative agreements in Mumbai and Delhi unlock low-cost feedstock under India's EPR notification framework. |
Research Approach
Direct dialogue with materials recovery facility operators, municipal procurement officers, brand owner sustainability directors, and chemical recycling technology providers anchored qualitative assessment, cross-referenced against EPA enforcement actions, EU Green Deal directive texts, state-level EPR legislation databases, and reclaimer financial disclosures. Bottom-up and top-down triangulation validated volume estimates across collection, sorting, processing, and disposal service tiers.
Bottom-up modeling built segment-level projections from installed MRF capacity, fleet deployment data, and reclaimer throughput rates, while top-down analysis cross-checked against macro waste generation trends and circular economy policy adoption curves across the projection horizon. Segmentation dimensions included service type, material category, end-user archetype, and technology pathway. CAGRs derived from historical contract value trajectories and announced capacity expansion pipelines, with chemical recycling growth rates tempered by capex intensity constraints.
Underlying measurement precision varies by segment; metals recovery and established mechanical reprocessing carry tighter precision than emerging chemical recycling and informal sector formalization. Forecasts reflect documented assumptions on EPR rollout timing, virgin resin price correlation, and contamination standard enforcement intensity. Practitioners should monitor EPA national recycling strategy publication, additional US state EPR adoptions, and GB standards evolution for Chinese import policy signals as early revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste Management & Pollution Control
Incinerator Market
Waste Management & Pollution Control
China Waste Management Market
Waste Management & Pollution Control
Food Waste Management Market
Waste Management & Pollution Control
India E-Waste Management Market
Waste Management & Pollution Control
Wood Recycling Market
Waste Management & Pollution Control
India Plastic Waste Management Market
Waste Management & Pollution Control
Automated Waste Collection System (AWCS) Market
Waste Management & Pollution Control
Vietnam Waste Management Market
Waste Management & Pollution Control
Biomedical Waste Management Market
Waste Management & Pollution Control
GCC Waste Management Market
Waste Management & Pollution Control
Global Waste Management Equipment Market
Waste Management & Pollution Control
Marine Waste Handling Equipment Market
Waste Management & Pollution Control
North America Industrial Waste Management Market
Waste Management & Pollution Control
Global Smart Trash Bin Market
Waste Management & Pollution Control
Sharp Waste Disposal Market
Waste Management & Pollution Control
Europe Bio-Medical Waste Management Market