
 Global Waste Management Software Market | 2026-2036
Global Waste Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Waste Management Software Market Foresight
Aftermarket service revenue from predictive maintenance modules is rewriting how vendors capture lifetime value in this space. Rubicon leverages its cloud-native architecture to anchor municipal contracts in dense urban corridors. Sphera specializes in environmental compliance workflows that sustain premium pricing among industrial waste handlers. Waste Logics competes through modular deployment options that extend its reach into mid-tier private contractors across multiple continents.
Waste management software encompasses digital platforms that coordinate collection routing, asset monitoring, regulatory reporting, and financial settlement across solid waste value chains, typically integrating GPS telemetry, IoT bin sensors, and ERP APIs through cloud or on-premises infrastructure. Cloud-based deployment leads adoption as municipal IT departments prioritize remote accessibility and reduced capital expenditure over legacy server maintenance. Route optimization commands the largest solution-type margin pool due to fuel cost sensitivity across commercial collection fleets, while compliance management segments show the fastest structural growth as regulators tighten landfill diversion and emissions verification requirements.
The EPA enforces landfill methane reporting standards that compel U.S. operators to adopt automated emissions tracking software, while the EU Green Deal and REACH frameworks mandate granular waste-stream documentation across European member states. Japan's METI circular economy guidelines require digital manifest systems that interface directly with processor ERP platforms. Stakeholders must monitor how interoperability mandates between national waste registries reshape platform architecture decisions and vendor certification requirements.
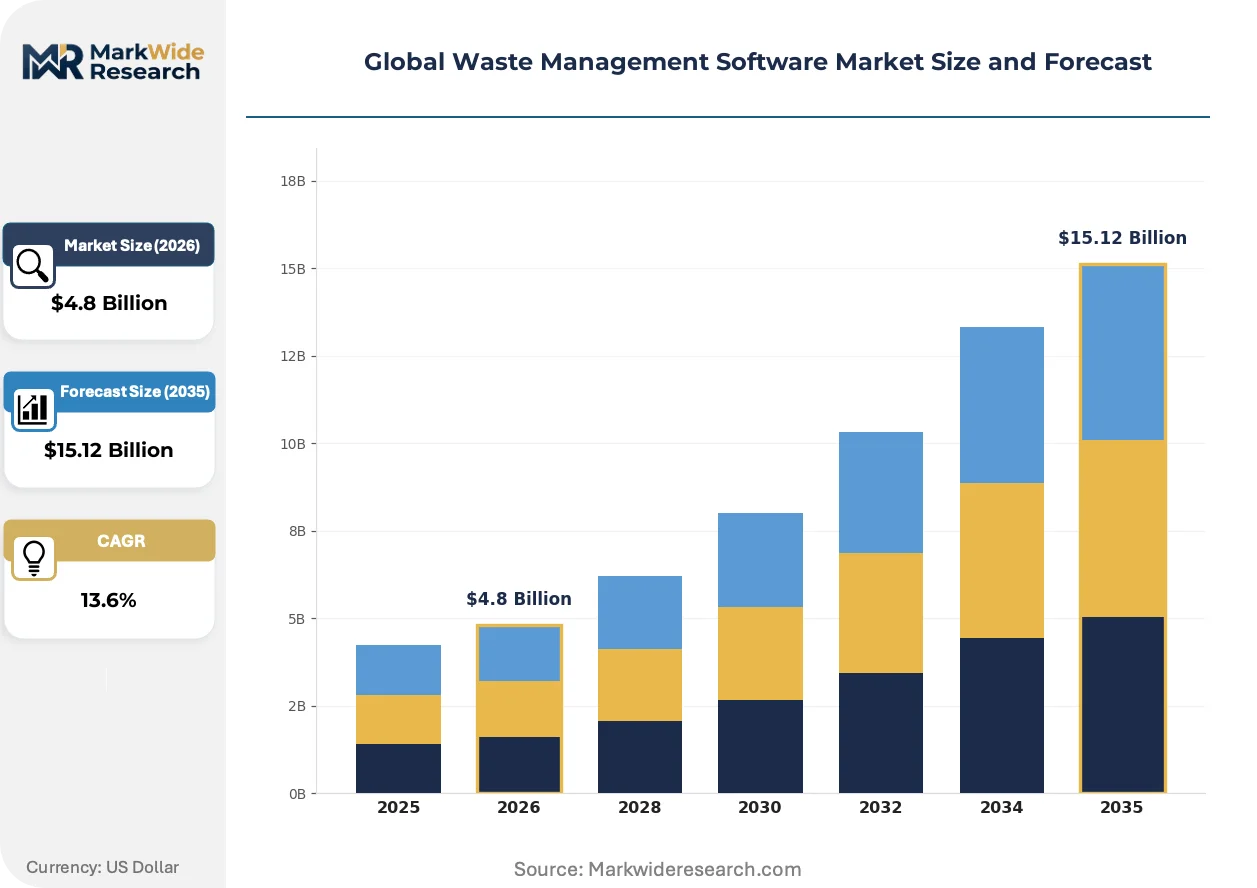
Market Dynamics
Municipal IT departments are consolidating vendor relationships around cloud-native platforms that integrate route optimization, bin-level IoT telemetry, and automated compliance reporting into unified dashboards.
Growth Catalysts
- EU Green Deal waste-tracking mandates:European landfill diversion targets require real-time digital manifest systems that interface with national registries, forcing software replacement cycles among legacy on-premise users.
- IoT sensor cost compression:Ultrasonic fill-level sensors and GPS telemetry modules now deploy at scale across commercial collection fleets, enabling dynamic routing algorithms that cut fuel expenditure.
- Japan METI circular economy guidelines:Digital waste-stream documentation requirements now interface directly with processor ERP platforms, creating demand for middleware integration specialists.
Market Restraints
- Legacy ERP integration friction:Municipal finance systems running SAP or Oracle instances require costly custom API development to connect with modern cloud platforms, extending sales cycles.
- Interoperability certification delays:National waste registry protocols in Germany, France, and Italy lack harmonized data standards, forcing vendors to maintain multiple compliance modules.
- Cybersecurity insurance premiums:Ransomware attacks against critical infrastructure operators have driven coverage costs for cloud-hosted waste management platforms upward by triple-digit percentages.
Strategic Opportunities
- India Smart Cities Mission:Municipal corporations in Bangalore, Pune, and Hyderabad are tendering integrated solid waste management platforms with route optimization and citizen complaint portals.
- AI-powered predictive maintenance:Machine learning models trained on fleet telematics data are creating aftermarket revenue streams that extend customer lifetime value beyond initial licensing.
- Carbon credit verification workflows:Methane capture documentation tools that automate EPA reporting standards are opening premium pricing tiers among landfill gas-to-energy operators.
Industry Challenges
- Embedded systems engineering talent scarcity:Vendors struggle to hire firmware developers capable of integrating low-power wide-area network protocols with legacy vehicle diagnostic ports.
- Multi-jurisdiction compliance versioning:Software releases must simultaneously satisfy EPA landfill methane standards, EU Green Deal tracking mandates, and Japan METI circular economy guidelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Waste Management Software Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.12 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, SaaS, Edge Computing Solution Type: Route Optimization, Asset Tracking, Compliance Management, Billing & Invoicing, Data Analytics Application: Residential Collection, Commercial Collection, Industrial Waste Handling, Recycling Facilities, Landfill Management End User: Municipal Corporations, Private Contractors, Environmental Agencies, Facility Managers, Waste Processors |
| Companies Covered | WAM Software, Quentic, Rubicon, Scrapp, ServiceCore, Trash Flow, Waste Logics, Sphera, Basestation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Waste Management Software Market Shifts & Advancements
Digital twin architectures are compressing the gap between physical collection operations and software-based optimization, enabling real-time simulation of fleet redeployment scenarios.
Digital twin technology is virtualizing waste collection infrastructure by creating software replicas of bin networks, vehicle fleets, and transfer stations that simulate demand fluctuations. Municipal operators in Germany and the Netherlands are deploying these systems to test route changes without disrupting live operations. The technology is virtualizing capital planning decisions by replacing spreadsheet-based fleet sizing with physics-informed simulation models.
EPA landfill methane reporting standards now require automated emissions tracking with quarterly verification against continuous monitoring systems. U.S. operators must submit geospatial methane plume data through centralized portals, compressing reporting timelines from annual to quarterly cycles. Landfill gas-to-energy facilities face the steepest compliance burden, driving demand for sensor-software bundles that automate anomaly detection.
Subscription-based pricing is displacing perpetual licenses across municipal procurement departments that prioritize operational expenditure over capital appropriations. French and Italian waste authorities now specify software-as-a-service terms in fleet logistics tenders, forcing incumbent vendors to restructure revenue recognition. Commercial collection fleets in Japan show similar preference shifts, with METI guidelines encouraging multi-year service contracts that bundle hardware, software, and maintenance.
Global Waste Management Software Market Segmentation
Segmentation in waste management software reveals how procurement priorities diverge across infrastructure maturity levels and regulatory exposure. Deployment architecture and solution specialization determine vendor selection criteria more sharply than in adjacent enterprise software verticals.
Deployment:
Cloud-native platforms now anchor municipal procurement across dense urban corridors, while legacy infrastructure constraints sustain hybrid demand in industrial settings.
- On-Premises:Legacy server installations persist where air-gapped security protocols govern critical infrastructure operations. German municipal utilities and Japanese prefectural authorities maintain these deployments for landfill gas monitoring systems subject to strict data sovereignty requirements.
- Cloud-Based:Multi-tenant SaaS architectures deliver remote accessibility and API extensibility for fleet logistics coordination. U.S. municipal IT departments in California and Texas prioritize these platforms to reduce capital appropriations and accelerate procurement cycles.
- Hybrid:Split architectures separate sensitive compliance data on local servers while routing optimization workloads to cloud instances. Industrial waste handlers in the Netherlands and Belgium favor this model for REACH documentation that must remain within EU jurisdiction.
- SaaS:Subscription licensing bundles software, maintenance, and infrastructure into operational expenditure line items. French and Italian waste authorities now mandate SaaS terms in fleet logistics tenders.
- Edge Computing:Distributed processing nodes enable real-time route recalculation without persistent cloud connectivity. Remote collection routes in Australia and rural Canada deploy these systems where cellular coverage remains intermittent.
The dominant share belongs to Cloud-Based deployments, while Edge Computing is gaining share fastest among geographically dispersed operators.
Solution Type:
Margin concentration tracks fuel cost sensitivity and regulatory verification burden across commercial and industrial waste streams.
- Route Optimization:Dynamic algorithms process GPS telemetry, traffic patterns, and bin fill-level data to minimize fleet mileage. Commercial collection fleets in Germany and the United States absorb premium pricing here due to diesel expenditure sensitivity across high-frequency pickup schedules.
- Compliance Management:Automated reporting modules interface with EPA, EU Green Deal, and METI registry systems to verify landfill diversion and methane capture. European operators face the steepest structural demand acceleration as real-time manifest mandates replace annual documentation cycles.
- Asset Tracking:IoT-enabled monitoring of containers, vehicles, and transfer station equipment supports predictive maintenance workflows. Mid-tier private contractors in India and Brazil leverage these tools to extend equipment lifetime.
- Billing & Invoicing:Weight-based or volume-based settlement engines integrate with municipal ERP systems for residential and commercial accounts. Japanese waste processors utilize these modules for METI-mandated digital manifest reconciliation.
- Data Analytics:Business intelligence dashboards aggregate operational metrics for capital planning and performance benchmarking. Environmental agencies in the United Kingdom deploy these for public transparency reporting.
Route Optimization commands the largest margin pool, though Compliance Management shows the steepest expansion trajectory as regulatory verification tightens.
Application:
Demand intensity correlates with collection frequency, regulatory scrutiny, and material value recovery potential across waste stream categories.
- Residential Collection:Curbside pickup scheduling and citizen complaint portals dominate municipal procurement specifications. Indian Smart Cities Mission tenders in Bangalore and Hyderabad emphasize these capabilities for informal settlement integration.
- Commercial Collection:High-frequency logistics for retail, hospitality, and office complexes drive route density optimization. Dense urban corridors in Japan and Germany absorb premium software tiers here.
- Industrial Waste Handling:Hazardous material tracking and manifest documentation interface with processor ERP platforms. EU REACH compliance mandates sustain specialized demand among chemical and pharmaceutical manufacturers.
- Recycling Facilities:Material stream characterization and contamination monitoring support quality-based pricing negotiations. Netherlands and California operators deploy sensor-software bundles for automated sorting line integration.
- Landfill Management:Methane plume monitoring and gas-to-energy optimization face EPA quarterly reporting requirements. U.S. operators in Texas and Pennsylvania purchase bundled sensor-software systems for emissions verification.
Commercial Collection retains the dominant deployment base, while Recycling Facilities is climbing the fastest as circular economy targets harden.
End User:
Procurement authority and budget cycles diverge sharply between public sector appropriations and private sector operational expenditure models.
- Municipal Corporations:City and county governments issue multi-year fleet logistics tenders with citizen-facing portal requirements. Consolidated vendor relationships favor cloud-native platforms integrating route, asset, and compliance functions.
- Private Contractors:Mid-tier collection companies prioritize modular deployment options that scale with contract portfolio growth. Waste Logics competes aggressively for this segment across multiple continents.
- Environmental Agencies:Regulatory bodies consume analytics and transparency tools for public reporting and enforcement prioritization. EPA and EU member state authorities drive standardization through certification requirements.
- Facility Managers:On-site operations teams at transfer stations and material recovery facilities require real-time bin-level telemetry. These users favor mobile-first interfaces for field workforce coordination.
- Waste Processors:Material conversion facilities need ERP-integrated manifest systems for inbound stream documentation. Japan METI guidelines mandate direct processor platform connectivity.
Municipal Corporations control the dominant procurement volume, though Private Contractors are expanding their software expenditure most rapidly as competitive pressure intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. Germany and Japan prioritize compliance-heavy platforms for circular economy mandates, while the United States and India emphasize cost-driven route optimization and fleet logistics scale.
United States
Commercial collection fleets dominate software procurement, with diesel expenditure sensitivity driving premium adoption of dynamic routing algorithms. The EPA enforces quarterly landfill methane reporting standards that compel operators toward automated emissions tracking systems. Texas and Pennsylvania operators purchase bundled sensor-software packages for geospatial plume verification.
Germany
Municipal utilities anchor demand for air-gapped on-premises deployments governing critical landfill gas monitoring infrastructure. The EU Green Deal mandates real-time digital manifest systems interfacing with national registries, forcing replacement cycles among legacy users. Dense urban corridors in North Rhine-Westphalia deploy cloud-native platforms integrating citizen complaint portals with fleet coordination.
Japan
Material recovery facilities require ERP-integrated manifest systems for inbound stream documentation under METI circular economy guidelines. Digital waste-stream documentation now interfaces directly with processor platforms, creating middleware integration demand. The Kanto region around Tokyo leads deployment of subscription-based fleet logistics contracts bundling hardware, software, and maintenance.
India
Smart Cities Mission tenders in Bangalore, Pune, and Hyderabad specify integrated solid waste management platforms with route optimization and informal settlement integration capabilities. Municipal corporations prioritize citizen-facing complaint portals alongside collection scheduling. Mid-tier private contractors leverage modular deployment options that scale with contract portfolio growth across multiple states.
Netherlands
Industrial waste handlers favor hybrid architectures separating sensitive REACH documentation on local servers while routing optimization workloads to cloud instances. Recycling facility operators deploy sensor-software bundles for automated sorting line integration and contamination monitoring. The Randstad cluster leads material stream characterization investments supporting quality-based pricing negotiations.
Global Waste Management Software Market Competitive Landscape
Capability concentration sits with specialized compliance workflow vendors; scale advantage sits with cloud-native platform providers serving dense urban corridors. The vendor base organizes around three strategic archetypes: municipal-focused fleet logistics specialists, industrial compliance workflow providers, and modular deployment vendors targeting mid-tier private contractors. Dominant competitive moves include cloud architecture migrations displacing perpetual license models and predictive maintenance module development capturing aftermarket revenue streams.
Within the cloud-native tier, Rubicon occupies a position exemplifying municipal contract anchoring in dense urban corridors. Sphera represents the compliance-specialist archetype sustaining premium pricing among industrial waste handlers through environmental workflow depth. Waste Logics sits within the modular deployment category, extending reach into mid-tier private contractors across multiple continents through scalable configuration options.
| Leading Market Players |
|---|
| WAM Software |
| Quentic |
| Rubicon |
| Scrapp |
| ServiceCore |
| Trash Flow |
| Waste Logics |
| Sphera |
| Basestation |
| Others |
Supply & Pricing Matrix
Undercapacity in embedded systems engineering talent across Germany and Japan constrains firmware development pipelines, forcing vendors to bid aggressively for qualified personnel while passing cost premiums through to municipal procurement departments in North Rhine-Westphalia and Tokyo prefectures.
Pricing Analysis
Multi-year SaaS contracts with bundled hardware-software-maintenance terms dominate municipal procurement in France, Italy, and Japan, displacing perpetual license models. Price differentiation hinges on compliance certification depth against EU Green Deal, EPA, and METI standards alongside route optimization algorithm sophistication. Cost compression in IoT sensor hardware is intensifying because ultrasonic fill-level module prices have fallen sharply, enabling mid-tier private contractors in India and Brazil to access previously premium-tier functionality. Municipal corporations in dense urban corridors show least price sensitivity due to regulatory penalty exposure, while rural collection operators in Australia and Canada absorb greatest pricing pressure from intermittent connectivity infrastructure requirements.
Supply Chain Analysis
Export-control restrictions on GPS telemetry modules and LPWAN communication chipsets limit component flows from Taiwan and South Korea into European and North American vendor assembly operations. Software development capacity concentrates in the United States, Germany, and India, with cloud infrastructure provisioning anchored in hyperscaler regions across Virginia, Frankfurt, and Mumbai. Raw material dependencies include semiconductor wafers, rare-earth magnets for vehicle-mounted sensors, and lithium-ion cells for IoT device power management. Single-source vulnerability in ultrasonic sensor fabrication creates procurement risk for vendors serving EPA-mandated landfill methane monitoring contracts. Distribution runs through direct enterprise sales teams for municipal accounts and value-added resellers for mid-tier private contractor segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Waste management software penetration remains in early-cycle expansion as EU Green Deal waste-tracking mandates force replacement cycles among legacy on-premise installations across German, French, and Italian municipal utilities.
For Market Incumbents: Entrench cloud-native platform consolidation by acquiring middleware integration specialists capable of bridging SAP and Oracle ERP instances with modern fleet logistics systems. Prioritize predictive maintenance module development to capture aftermarket revenue streams that extend customer lifetime value beyond initial SaaS licensing. Vertical integration into embedded firmware engineering reduces exposure to talent scarcity constraining competitor roadmap velocity. For New Entrants and Emerging Players: Pursue modular deployment configurations targeting mid-tier private contractors in India's Smart Cities Mission corridors where Waste Logics has established scalable entry patterns. Carbon credit verification workflows for landfill gas-to-energy operators represent the most penetrable white-space segment, with EPA quarterly reporting requirements creating urgent demand unmet by incumbent compliance suites. Go-to-market execution should emphasize rapid API development for national waste registry interoperability. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native platform providers as subscription revenue scales ahead of infrastructure provisioning costs, improving cash conversion profiles. Long-term viability over the next decade rests on compliance workflow depth rather than route optimization commoditization, favoring acquisition targets with EPA, EU Green Deal, and METI certification breadth. The signal to watch is municipal procurement specification language shifting from perpetual license tolerance to exclusive SaaS mandate.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies route optimization, IoT telemetry, and compliance reporting into single municipal dashboards. |
| Acquisition of Specialist Firm | Adds middleware capabilities for SAP and Oracle ERP connectivity in German utility markets. |
| Geographic Expansion | Targets Bangalore, Pune, and Hyderabad tenders under India's Smart Cities Mission. |
| Product Launch | Introduces predictive maintenance modules trained on fleet telematics data for aftermarket revenue. |
| Strategic Partnership | Links sensor-software bundles with landfill gas-to-energy operators facing EPA quarterly reporting. |
Research Methodology
Initial hypotheses were tested against primary input from municipal IT directors, fleet logistics managers, compliance officers at industrial waste handlers, and embedded systems engineers, then refined through secondary validation against EPA enforcement databases, EU Green Deal implementation guidance, METI circular economy policy documents, and municipal procurement tender archives across Germany, the United States, Japan, and India. Bottom-up segment sizing triangulated against top-down macroeconomic indicators anchored the market estimation framework.
Demand-supply balance dynamics across cloud infrastructure provisioning, embedded engineering talent pools, and IoT sensor manufacturing capacity informed the analytical framework throughout the projection horizon. Segmentation dimensions modeled include deployment architecture, solution specialization, waste stream application, and end-user procurement authority alongside regional regulatory adoption patterns. CAGRs were derived from penetration curve analysis calibrated against comparable enterprise software verticals, with forecast inputs incorporating municipal budget appropriation cycles and compliance mandate enforcement timelines.
Sensitivities concentrate around EU member state interoperability harmonization delays, EPA reporting timeline compressions, and IoT sensor cost trajectories. Forecasts reflect assumptions regarding regulatory enforcement consistency and cloud migration willingness among conservative municipal procurement departments. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste Management & Pollution Control
India Commercial Food Waste Decomposer Market
Waste Management & Pollution Control
Sludge Management Equipment Market
Waste Management & Pollution Control
Retail Food Waste-to-Biogas Logistics and Treatment Networks in Europe Market
Waste Management & Pollution Control
Polyfluoroalkyl Substances (PFAS) Waste Management Market
Waste Management & Pollution Control
Global Oil Spill Management Market
Waste Management & Pollution Control
Waste Compactor Bins Market
Waste Management & Pollution Control
North America Bio-Medical Waste Management Market
Waste Management & Pollution Control
Rare Earth Recycling Market
Waste Management & Pollution Control
Industrial Solid Waste Management Market
Waste Management & Pollution Control
Wheeled Bins Market
Waste Management & Pollution Control
Saudi Arabia Medical Waste Management Market
Waste Management & Pollution Control
China Waste Management Market
Waste Management & Pollution Control
Europe Municipal Solid Waste Management Market
Waste Management & Pollution Control
Landfill Compactor Market
Waste Management & Pollution Control
UAE Industrial Waste Management Market
Waste Management & Pollution Control
Hazardous Waste Handling Automation Market