
 Smart Waste Collection Market | 2026-2036
Smart Waste Collection Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Waste Collection Market Outlook
ISO 37120 certification for sustainable cities and communities is collapsing the supplier base to vendors with proven smart-city integration records. Bigbelly, Inc. leverages its solar-compactor footprint across North American downtown districts to sustain recurring service revenue. Enevo anchors European market presence through predictive analytics platforms that optimize collection routing. Sensoneo competes on hardware-agnostic software architecture, allowing rapid retrofit across legacy bin fleets.
Smart waste collection comprises networked sensor arrays, embedded telemetry modules, and cloud-native platforms that measure fill levels, composition, and location parameters in real time, transmitting data over cellular or LoRaWAN protocols to dispatch algorithms that dynamically schedule collection vehicle deployment. The primary purpose is reducing operational expenditure through route optimization while meeting mandated diversion and emissions targets. IoT sensor deployments dominate current infrastructure spend as municipalities prioritize proven ultrasonic and capacitive fill-detection hardware over unproven computer-vision alternatives. Cloud computing architectures capture expanding margin pools by enabling subscription-based SaaS pricing that locks in multi-year municipal contracts. Edge computing remains nascent but grows fastest in industrial settings requiring sub-second compaction triggers without latency tolerance for backhaul transmission.
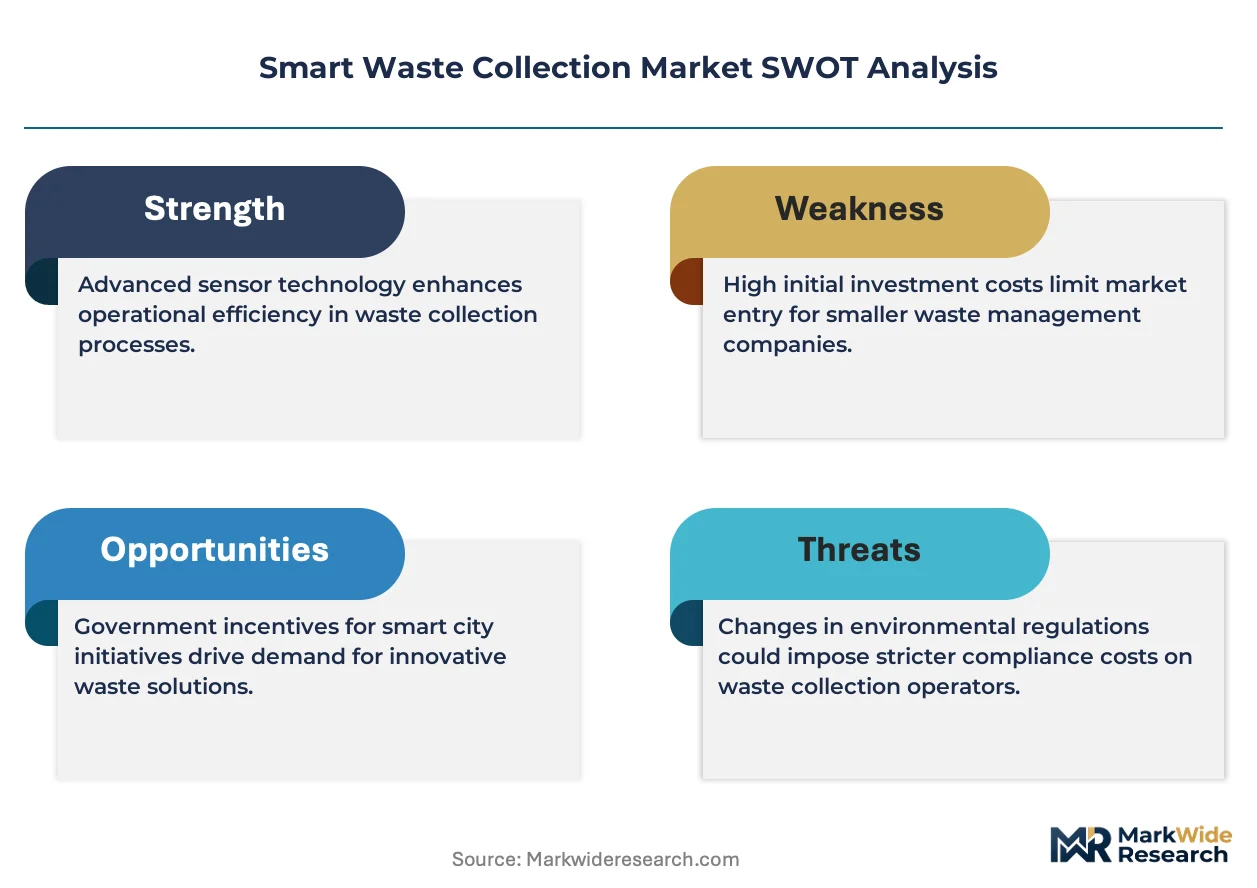
EPA landfill methane regulations and EU Green Deal circular-economy frameworks are mandating measurable waste-stream transparency, forcing municipalities to procure systems with auditable data trails. FCC Part 15 compliance for unlicensed radio devices shapes hardware design constraints for North American equipment suppliers. Stakeholders must evaluate whether platform interoperability standards will consolidate vendor selection around open APIs or fragment procurement across proprietary city-specific ecosystems.
Market Dynamics
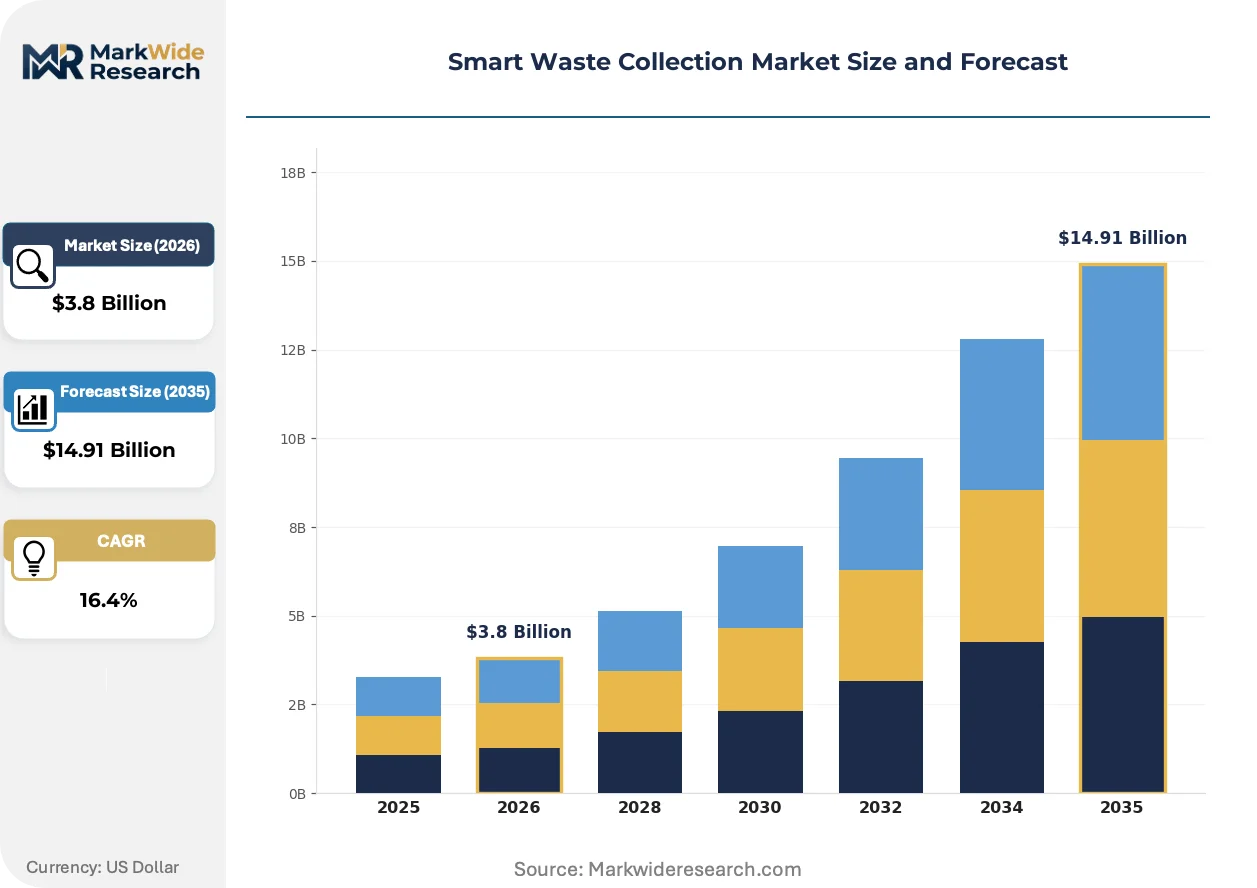
EU Green Deal landfill diversion mandates are compressing municipal procurement cycles as cities face binding 2035 waste-reduction targets. Sensor-to-cloud integration requirements are forcing vendor consolidation around proven interoperability certifications.
Growth Catalysts
- Ultrasonic fill-detection hardware:Municipalities in Germany deploy these sensors under EU Green Deal circular-economy frameworks to achieve real-time bin monitoring.
- EPA methane regulations:US landfill operators must install auditable waste-stream transparency systems, accelerating procurement of telemetry-enabled collection fleets.
- LoRaWAN protocol standardization:Low-power wide-area networks reduce cellular data costs for urban corridors deploying dense sensor grids.
Market Restraints
- Cellular module cost volatility:Semiconductor supply concentration in East Asia creates input price instability for telemetry hardware manufacturers.
- Computer-vision technical limitations:Unproven vision-based fill detection suffers accuracy degradation in low-light and contaminated environments.
- FCC Part 15 compliance friction:Unlicensed radio device certification timelines extend hardware go-to-market cycles for North American suppliers.
Strategic Opportunities
- Edge computing convergence:Integration of on-bin processing with solar-compaction triggers opens industrial settings requiring sub-second response without backhaul latency.
- India smart-city mission:Underpenetrated urban corridors present retrofit demand for hardware-agnostic software architectures compatible with legacy bin fleets.
- CSRD disclosure requirements:EU corporate sustainability reporting mandates create subscription revenue pools for platforms offering auditable waste-diversion metrics.
Industry Challenges
- ISO 37120 certification timelines:Municipal procurement teams lack internal expertise to evaluate vendor smart-city integration records against sustainable-cities standards.
- Legacy fleet integration complexity:Retrofitting existing bin infrastructure with cellular telemetry requires specialized installation labor scarce in secondary cities.
- Interoperability standardization delays:Fragmented municipal API specifications prevent platform portability across city-specific proprietary ecosystems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Waste Collection Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $14.91 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: IoT, Sensor-Based, Cloud Computing, GPS Tracking Deployment: On-Premise, Cloud, Hybrid, Edge Computing End User: Municipalities, Commercial, Industrial, Residential System Type: Automatic, Semi-Automatic, Manual, Integrated |
| Companies Covered | Bigbelly, Inc., Enevo, Ecube Labs, Waste Management, Inc., Sensoneo, Compology, Urbiotica, Rubicon Technologies, Veolia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Waste Collection Market Strategic Shifts
Cloud-native SaaS architectures are capturing recurring revenue pools previously lost to perpetual hardware sales. Municipal buyers now prioritize subscription-based route optimization over capital-intensive fleet replacement.
Ultrasonic and capacitive fill-detection sensors measure bin occupancy through echo-ranging and dielectric variation, transmitting data over cellular or LoRaWAN protocols. Municipalities in Germany and the Netherlands adopt these proven hardware formats while deferring computer-vision pilots. This proven-technology preference is supplanting experimental AI-based alternatives in procurement specifications.
The EU Green Deal circular-economy framework mandates measurable waste-stream transparency with auditable data trails. Landfill operators must document diversion rates and methane capture efficiency to maintain operating permits. European municipalities are responding by specifying ISO-certified platforms with open APIs to ensure multi-vendor interoperability.
Service unbundling separates hardware procurement from route-optimization software subscriptions. Municipal fleet managers now source sensors from hardware specialists while contracting analytics from cloud-native platform vendors. This bifurcation is most visible in North American downtown districts where solar-compactor deployments already exist and cities seek to layer predictive analytics atop installed infrastructure.
Smart Waste Collection Market Segmentation
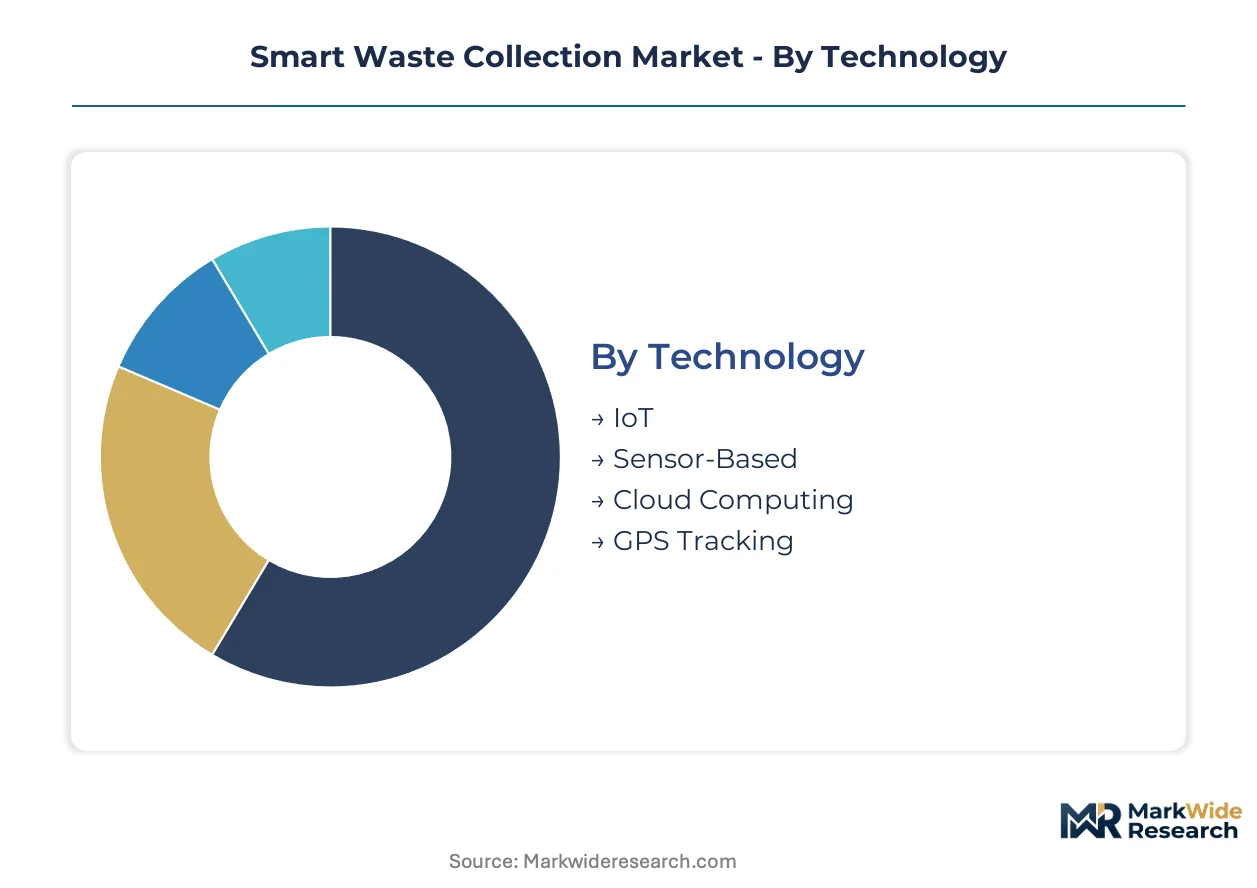
Technology choices in smart waste collection determine capital intensity and operational flexibility. Deployment architecture shapes subscription pricing and data sovereignty compliance. End-user segmentation reveals divergent procurement timelines and performance requirements.
Technology:
IoT sensor arrays face substitution pressure from emerging computer-vision alternatives, though proven reliability sustains current procurement preferences.
- IoT:Networked telemetry modules transmit fill-level, location, and compaction status over cellular or LoRaWAN protocols. German municipalities under EU Green Deal mandates prioritize these deployments for real-time bin monitoring and route optimization.
- Sensor-Based:Ultrasonic and capacitive hardware measures occupancy through echo-ranging and dielectric variation. Demand concentrates in Dutch urban corridors where landfill diversion targets tighten operational requirements for proven detection accuracy.
- Cloud Computing:Native SaaS platforms enable subscription-based route analytics and multi-year municipal contracts.
- GPS Tracking:Vehicle-mounted modules provide fleet location data for dynamic dispatch algorithms.
IoT retains volume leadership; Cloud Computing holds the steepest expansion curve.
Deployment:
Cost tier differentiation separates capital-intensive edge installations from recurring SaaS subscriptions.
- Cloud:Centralized data processing with subscription pricing captures expanding municipal software budgets. North American downtown districts favor this model for layering predictive analytics atop existing solar-compactor infrastructure.
- Edge Computing:On-bin processing enables sub-second compaction triggers without backhaul latency. Industrial settings in Germany adopt these deployments where response-time requirements exclude cloud-dependent architectures.
- On-Premise:Municipal-owned servers address data sovereignty requirements in jurisdictions with strict localization mandates.
- Hybrid:Split architectures process sensitive data locally while routing analytics to cloud platforms.
Cloud deployments dominate municipal procurement; Edge Computing is climbing the fastest in industrial segments.
End User:
Application maturity varies sharply across customer types, with industrial buyers demanding performance guarantees unavailable to municipal procurement cycles.
- Municipalities:City agencies specify ISO 37120-certified platforms with open APIs for multi-vendor interoperability. EU Green Deal landfill diversion mandates compress their procurement timelines as binding waste-reduction targets approach.
- Commercial:Retail and office complex operators prioritize hardware-agnostic software compatible with legacy bin fleets. Indian smart-city missions generate retrofit demand in underpenetrated urban corridors.
- Industrial:Manufacturing and logistics facilities require sub-second response times for compaction triggers.
- Residential:Single-family and multi-unit housing associations represent price-sensitive demand with longer replacement cycles.
Municipalities retain volume leadership; Commercial holds the steepest expansion trajectory.
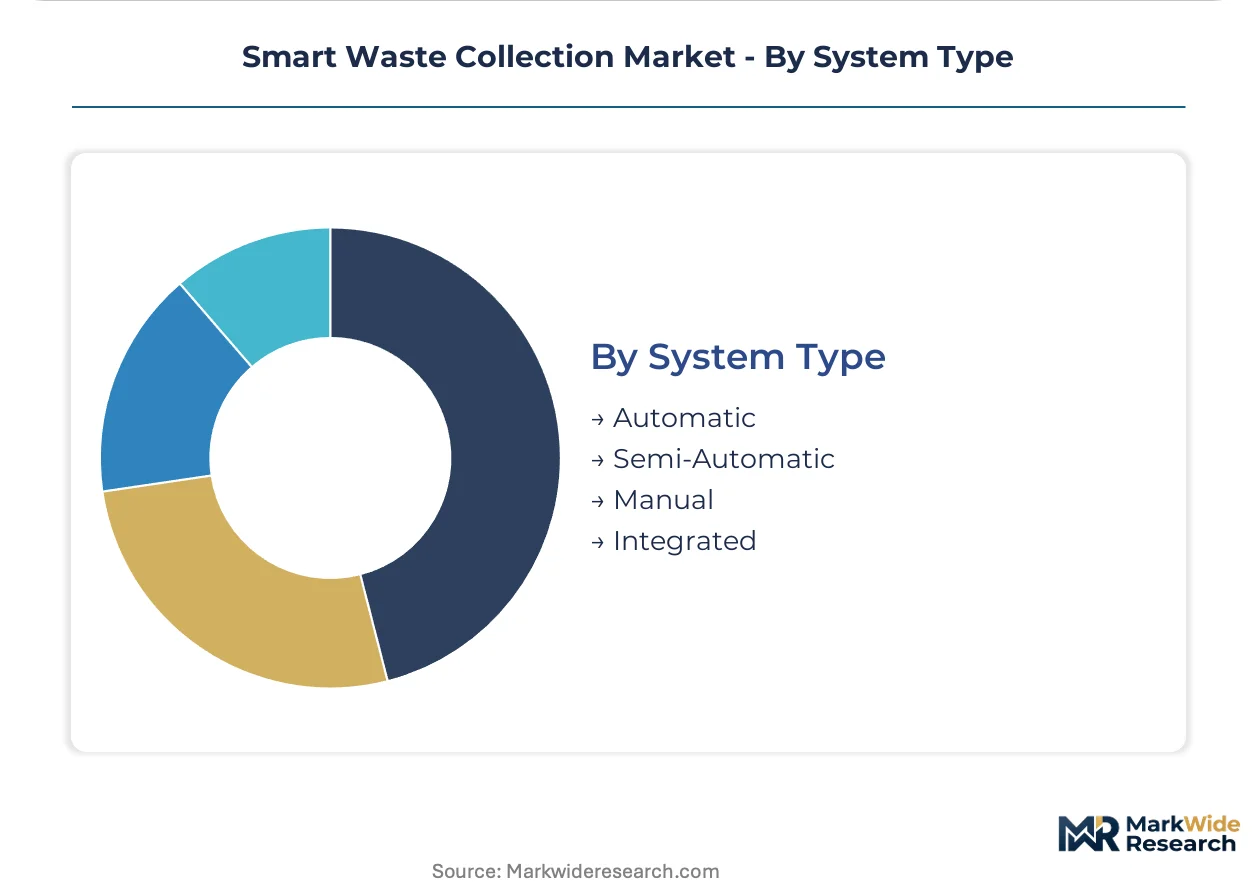
System Type:
Supply concentration in automated hardware manufacturing creates procurement bottlenecks distinct from software-integrated alternatives.
- Automatic:Fully autonomous collection vehicles with sensor-driven routing minimize labor costs. EPA methane regulations accelerate US landfill operator procurement of these telemetry-enabled fleets.
- Integrated:Combined hardware-software platforms from single vendors reduce interoperability friction. CSRD disclosure requirements in Europe drive subscription demand for auditable waste-diversion metrics.
- Semi-Automatic:Sensor-assisted collection retains human oversight for complex urban environments.
- Manual:Traditional collection with retrofitted telemetry modules serves cost-constrained secondary cities.
Automatic systems retain volume leadership; Integrated platforms are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Municipal procurement teams concentrate demand in jurisdictions with binding landfill diversion mandates and established smart-city infrastructure budgets. Germany, the United States, the Netherlands, India, and Japan represent distinct deployment archetypes shaped by regulatory frameworks and urban density patterns.
Germany
EU Green Deal circular-economy mandates compress procurement cycles as cities approach binding 2035 waste-reduction targets. The Federal Environment Agency enforces auditable waste-stream transparency requirements under landfill diversion regulations. Bavarian municipalities in Munich and Nuremberg deploy sensor-equipped bins with ISO 37120-certified platforms for real-time fill monitoring.
United States
EPA methane regulations accelerate telemetry-enabled fleet procurement among landfill operators seeking operating permit compliance. FCC Part 15 certification requirements shape hardware design constraints for unlicensed radio devices. Downtown districts across Chicago and San Francisco layer predictive analytics atop existing solar-compactor infrastructure through subscription-based SaaS contracts.
Netherlands
Landfill diversion targets in Dutch urban corridors tighten operational requirements for proven detection accuracy in sensor deployments. The national environmental regulator mandates measurable waste-stream transparency with auditable data trails. Amsterdam and Rotterdam concentrate demand for ultrasonic fill-detection hardware integrated with cloud-native route optimization platforms.
India
Smart-city mission funding generates retrofit demand for hardware-agnostic software architectures compatible with legacy bin fleets. The Bureau of Indian Standards develops interoperability specifications for municipal IoT deployments. Maharashtra and Gujarat urban corridors in Mumbai and Ahmedabad prioritize rapid sensor retrofit across existing waste infrastructure.
Japan
Industrial facilities in manufacturing belts require sub-second response times for compaction triggers without cloud backhaul latency. METI promotes edge computing convergence for smart-city infrastructure under national digital transformation initiatives. The Kanto region around Tokyo concentrates demand for on-bin processing modules in logistics and manufacturing settings.
Smart Waste Collection Market Competitive Environment
Player mix skews toward integrated platform vendors with proven municipal interoperability certifications. The supplier base consolidates around vendors demonstrating ISO 37120 smart-city integration records. Three archetypes dominate: solar-compactor specialists with recurring service revenue models, predictive analytics platform vendors optimizing collection routing, and hardware-agnostic software providers enabling rapid legacy fleet retrofit. Competitive moves center on strategic partnerships for sensor-to-cloud integration and geographic expansion into underpenetrated Asian urban corridors.
Within the integrated platform tier, Bigbelly, Inc. and Enevo occupy positions representing distinct geographic anchoring strategies. Bigbelly exemplifies the solar-compactor archetype with concentrated presence across North American downtown districts. Enevo sits within the predictive analytics specialization with established European market presence through routing optimization platforms. Sensoneo represents the hardware-agnostic software architecture approach, enabling retrofit deployment across legacy bin fleets without vendor lock-in to specific sensor hardware.
| Leading Market Players |
|---|
| Bigbelly, Inc. |
| Enevo |
| Ecube Labs |
| Waste Management, Inc. |
| Sensoneo |
| Compology |
| Urbiotica |
| Rubicon Technologies |
| Veolia |
| Others |
Value Chain & Pricing Dynamics
ISO 37120 certification gates municipal procurement eligibility while stratifying vendor pricing power between certified integrators and uncertified hardware suppliers. EU Green Deal mandates accelerate this bifurcation as cities specify auditable platforms with proven interoperability records, compressing margins for commodity sensor manufacturers unable to demonstrate smart-city integration credentials.
Pricing Analysis
Cost-plus contracts with semiconductor indexation dominate telemetry hardware procurement, transferring cellular module volatility to municipal buyers through pass-through clauses. Three-tier pricing structure across premium, standard, and economy levels separates ISO-certified platform vendors from hardware-only suppliers and retrofit software providers. Cost compression in cellular-enabled sensors is intensifying because East Asian semiconductor concentration exposes manufacturers to input price instability. Commercial retail operators exhibit highest price sensitivity, deferring upgrades until hardware-agnostic software options reduce retrofit capital requirements.
Supply Chain Analysis
Taiwan Strait transit risk concentrates semiconductor supply vulnerability for cellular telemetry modules bound for North American and European assembly facilities. Hardware manufacturing draws from China, South Korea, and Taiwan for ultrasonic sensors, LoRaWAN chipsets, and solar-compactor components. Single-source vulnerability in MEMS microphone production for fill-detection arrays threatens sensor availability during geopolitical disruptions. Distribution runs through municipal procurement offices and smart-city integrators rather than open-market channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart waste collection sits in early-cycle expansion as landfill diversion mandates force municipal technology refresh across legacy fleet infrastructure. Binding regulatory targets create irreversible procurement commitments regardless of near-term budget pressures.
For Market Incumbents: Compound platform stickiness through API standardization investments that lock municipal customers into multi-year SaaS contracts. Counter hardware-agnostic software entrants by deepening vertical integration into edge computing modules for industrial sub-second response applications. ISO 37120 certification maintenance represents the priority defensive lever as procurement teams consolidate vendor pools around proven integration records. For New Entrants and Emerging Players: Differentiate on retrofit compatibility for legacy bin fleets in Indian smart-city corridors where hardware-agnostic architectures bypass incumbent sensor lock-in. White-space concentration sits with commercial retail operators seeking subscription-based route optimization without capital-intensive fleet replacement. Pursue partnership-led go-to-market models with established municipal integrators lacking software development capabilities. For Investors and Strategic Acquirers: EU CSRD disclosure requirements reshape the acquisition landscape toward platforms with auditable waste-diversion metric capabilities and recurring revenue visibility. Long-term viability centers on SaaS gross margin sustainability rather than hardware shipment volumes. The signal to watch is municipal procurement specification shifts toward open API mandates that erode proprietary platform moats.| Strategic Initiative | Industry Significance |
|---|---|
| API Standardization Investment | ISO 37120-certified open interfaces reduce vendor lock-in friction for municipal procurement teams. |
| Edge Computing Module Development | On-bin processing capabilities capture industrial demand requiring sub-second compaction triggers without cloud latency. |
| Hardware-Agnostic Software Launch | Retrofit compatibility unlocks underpenetrated Indian urban corridors with legacy bin infrastructure. |
| Strategic Partnership with Municipal Integrators | Channel access accelerates deployment velocity in EU Green Deal-mandated procurement cycles. |
| CSRD-Compliant Analytics Platform | Auditable waste-diversion metrics create subscription revenue pools from EU corporate sustainability reporting mandates. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with municipal procurement officers, smart-city integration specialists, and IoT platform engineering leads, combined with secondary validation against EPA regulatory filings, EU Green Deal implementation reports, LoRaWAN Alliance deployment databases, and municipal budget appropriation records. Bottom-up sensor shipment estimates triangulated against top-down municipal technology spend allocations.
Across the analysis window, the forecasting framework modeled technology adoption curves by deployment architecture, end-user procurement maturity, and regional regulatory enforcement intensity. CAGRs derived from segment-level penetration rate trajectories, cross-referenced with landfill diversion target compliance deadlines and smart-city infrastructure budget cycles. Industry-specific inputs included LoRaWAN network coverage expansion timelines and semiconductor supply lead time volatility indices.
Material uncertainties — semiconductor supply disruptions, municipal budget freezes, and interoperability standardization delays — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory enforcement continuity and technology cost reduction curves. Practitioners should keep alternative scenarios live as EU Green Deal implementation timelines and FCC Part 15 certification processing speeds evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Waste Management
North America E-Waste Management Market
E-Waste Management
Europe E-Waste Management Market
E-Waste Management
E-Waste Management Market
E-Waste Management
Smart Waste Management Market
E-Waste Management
Solar Panel Recycling Market
E-Waste Management
Electronic Scrap Recycling Market
E-Waste Management
Global E-Waste Recycling and Reuse Service Market
E-Waste Management
Solar Panel Recycling Management Market
E-Waste Management
Release Liner Recycling Market
E-Waste Management
Aluminum Cans Recycling Market
E-Waste Management
Electronic Waste Recycling Market
E-Waste Management
UAE E-Waste Management Market
E-Waste Management
Packaging Waste Recycling Market
E-Waste Management
Recycling Equipment Market
E-Waste Management
Recycling Equipment and Machinery Market
E-Waste Management
Middle East and Africa Solar Panel Recycling Market