
 Middle-East and Africa Hazardous Waste Handling Automation Market | 2026-2036
Middle-East and Africa Hazardous Waste Handling Automation Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East and Africa Hazardous Waste Handling Automation Market Foresight
Aftermarket service revenue is reshaping profit pools across the Middle-East and Africa Hazardous Waste Handling Automation Market as operators prioritize uptime guarantees over capital expenditure. Konecranes leverages its crane automation heritage to dominate heavy-lift waste handling in Gulf petrochemical zones. Averda anchors its competitive position through integrated waste-to-resource platforms spanning collection, treatment, and disposal across multiple African jurisdictions. PAR Systems specializes in robotic manipulator systems for radiological and chemical waste environments where human exposure risks are prohibitive.
Hazardous waste handling automation encompasses electromechanical systems, sensor networks, and software platforms engineered to identify, segregate, transport, and process toxic, flammable, corrosive, or reactive waste streams with minimal human contact, typically operating within temperature ranges of minus 40 to plus 200 degrees Celsius and pressure ratings up to 10 bar depending on containment specifications. Robotic Systems currently command the largest technology segment as Gulf states deploy articulated arms for drum handling and tank cleaning in oilfield service operations. AI Analytics represents the fastest-expanding technology category, with machine learning models optimizing waste classification accuracy and predicting equipment degradation before containment breaches occur. Waste Treatment Facilities constitute the most penetrated end-user segment, while Manufacturing Plants in Egypt and Morocco are emerging as high-growth adopters seeking to comply with tightening industrial effluent standards.
South Africa's Department of Forestry, Fisheries and the Environment enforces landfill diversion targets that directly accelerate capital deployment in automated sorting and neutralization equipment. Saudi Arabia's General Authority for Meteorology and Environmental Protection aligns enforcement with Vision 2030 industrial diversification goals, creating compliance-driven demand for cloud-based waste tracking systems. The UAE's Ministry of Climate Change and Environment mandates hazardous waste manifest documentation that favors Integrated Platforms combining real-time monitoring with regulatory reporting automation. Stakeholders must weigh the trade-off between standalone system flexibility and platform integration depth as environmental enforcement intensifies across jurisdictions with divergent technical standards and inspection frequencies.
Market Dynamics
Gulf petrochemical operators are retrofitting legacy waste infrastructure with robotic sorting and IoT-enabled containment systems to meet tightening landfill diversion mandates, fundamentally restructuring capital deployment patterns across the Middle-East and Africa Hazardous Waste Handling Automation Market.
Growth Catalysts
- Saudi Vision 2030 industrial diversification:The General Authority for Meteorology and Environmental Protection aligns enforcement with diversification goals, creating compliance-driven demand for cloud-based waste tracking systems in Jubail Industrial City.
- South Africa's landfill diversion targets:The Department of Forestry, Fisheries and the Environment mandates accelerate capital deployment in automated sorting and neutralization equipment for hazardous industrial streams.
- Robotic Systems adoption:Articulated arms for drum handling and tank cleaning are penetrating oilfield service operations as Gulf states automate high-exposure waste handling tasks.
Market Restraints
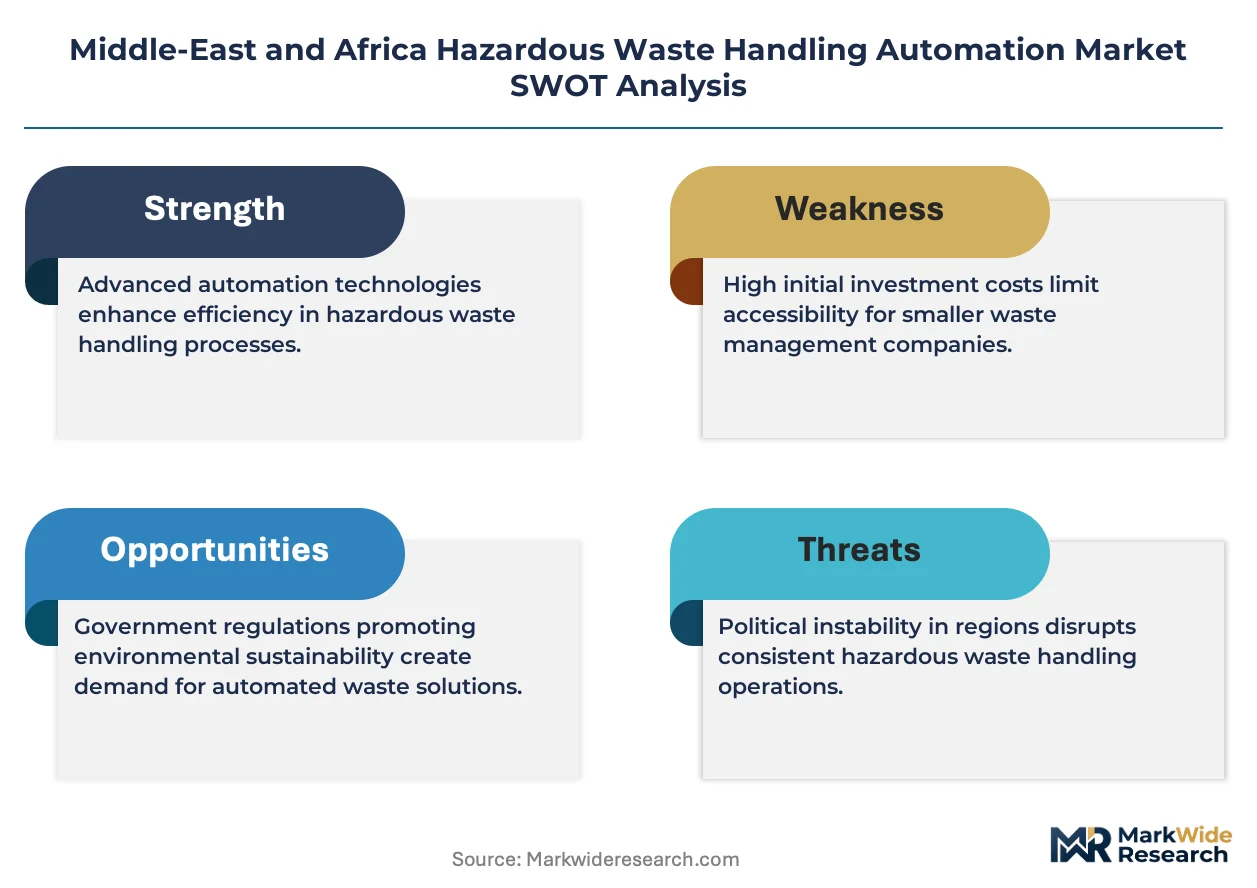
- Input cost volatility:Stainless steel and specialized sensor components face price instability from concentrated Asian supply chains, compressing equipment margins for regional integrators.
- Technical limitation in extreme environments:Automated systems operating in temperatures exceeding 200 degrees Celsius or corrosive chemical atmospheres suffer accelerated component degradation, limiting deployment scope in certain refinery applications.
- Regulatory friction from divergent standards:The UAE's Ministry of Climate Change and Environment mandates documentation protocols incompatible with Saudi manifest systems, forcing redundant compliance investments for multi-jurisdiction operators.
Strategic Opportunities
- Egypt and Morocco manufacturing compliance:Manufacturing Plants in these North African markets are emerging as high-growth adopters seeking automated solutions to meet tightening industrial effluent standards.
- AI Analytics convergence with sensor networks:Machine learning models optimizing waste classification accuracy are creating new service revenue streams through predictive maintenance offerings.
- Integrated platform regulatory tailwind:The UAE's hazardous waste manifest documentation requirements favor platforms combining real-time monitoring with automated regulatory reporting, advantaging vendors with software-hardware integration capabilities.
Industry Challenges
- Specialized technician scarcity:Robotics maintenance and radiological waste handling automation programming require skills concentrated in European and East Asian labor markets, creating recruitment bottlenecks for African operators.
- Legacy system integration complexity:Petrochemical complexes in Jubail and Ras Al-Khair retrofit decades-old waste infrastructure with automated containment, facing protocol mismatches between analog-era equipment and digital control systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East and Africa Hazardous Waste Handling Automation Market |
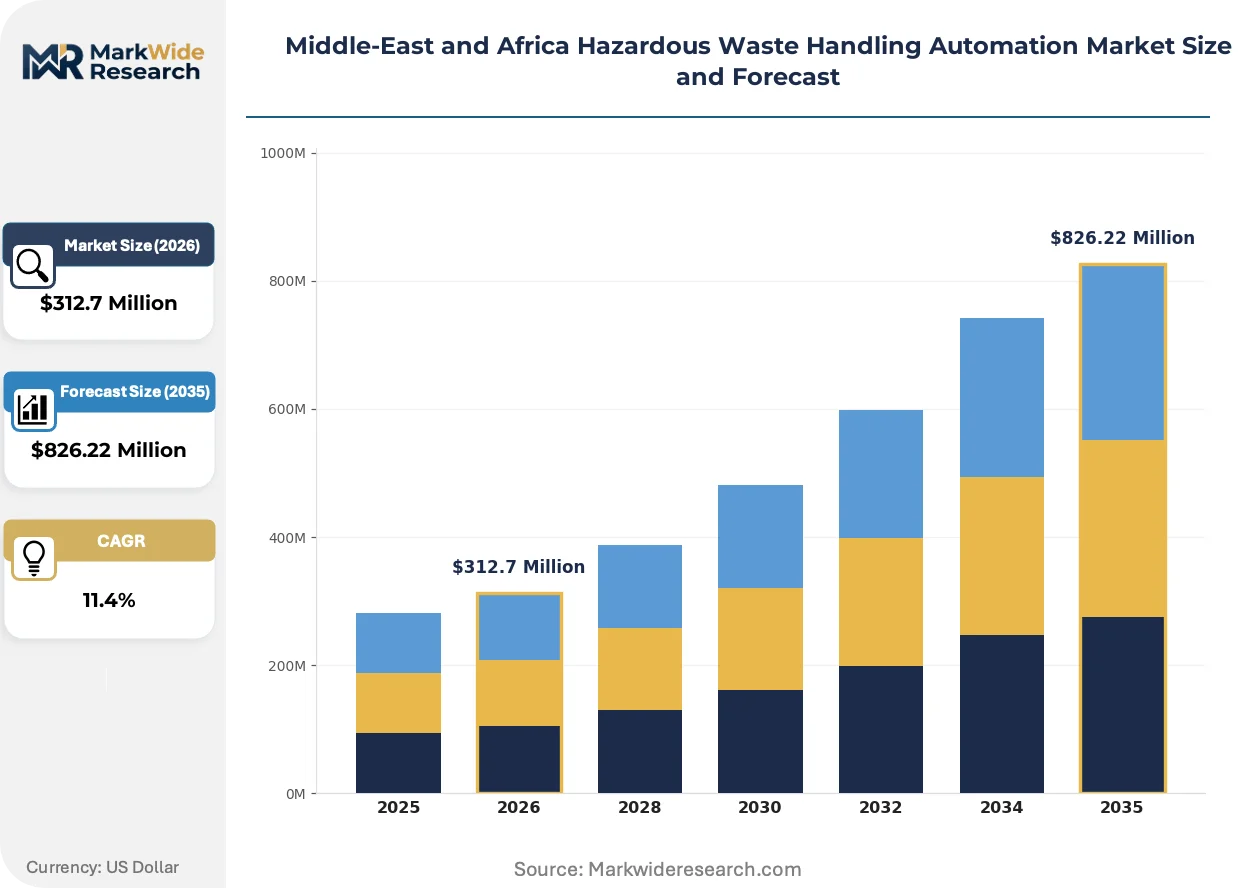
| Market Size in 2026 | $312.7 Million |
| Market Size in 2035 | $826.22 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Robotic Systems, IoT Sensors, Automated Vehicles, AI Analytics Service Type: Consulting, System Integration, Maintenance, Support End User: Manufacturing Plants, Waste Treatment Facilities, Municipalities, Research Institutions System Type: Standalone Solutions, Cloud-Based Systems, Hybrid Systems, Integrated Platforms |
| Companies Covered | PAR Systems, Konecranes, Pallmann Maschinenfabrik GmbH & Co., Hosokawa Micron Powder Systems, Floatograph Technologies, Terex MHPS GmbH, Hiab, PENZ Crane GmbH, Averda, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East and Africa Hazardous Waste Handling Automation Market Shifts & Advancements
Automation architectures across the Middle-East and Africa Hazardous Waste Handling Automation Market are converging around predictive intelligence and remote operation capabilities, compressing the acceptable response window for containment breaches while expanding the geographic range of unmanned facilities.
AI Analytics platforms integrating machine vision with spectral sensors are rendering obsolete manual waste classification protocols in high-throughput treatment facilities. Oil and gas refineries across the Gulf Cooperation Council are deploying these systems at accelerated cadences to meet real-time manifest documentation requirements. The structural consequence is a collapse in acceptable error rates for hazardous material identification, forcing mid-tier automation vendors to acquire computer vision capabilities or exit the segment.
South Africa's National Waste Management Strategy enforcement is tightening landfill diversion mandates for hazardous industrial streams, directly accelerating capital deployment in automated sorting and neutralization equipment. The industrial consequence is a reallocation of waste treatment facility budgets from disposal infrastructure toward preprocessing automation. Mining and metallurgical operations in the Northern Cape and Mpumalanga provinces are most affected, responding with phased automation investments tied to license renewal timelines.
Aftermarket service revenue is displacing upfront equipment margins as the primary profit pool across Gulf petrochemical zones. Operators in Saudi Arabia's industrial cities now prioritize uptime guarantees and predictive maintenance subscriptions over capital expenditure, restructuring vendor relationships toward performance-based contracts. This behavioral shift is most visible in long-term service agreements for robotic manipulator systems deployed in radiological and chemical waste environments where human exposure risks are prohibitive.
Middle-East and Africa Hazardous Waste Handling Automation Market Segmentation
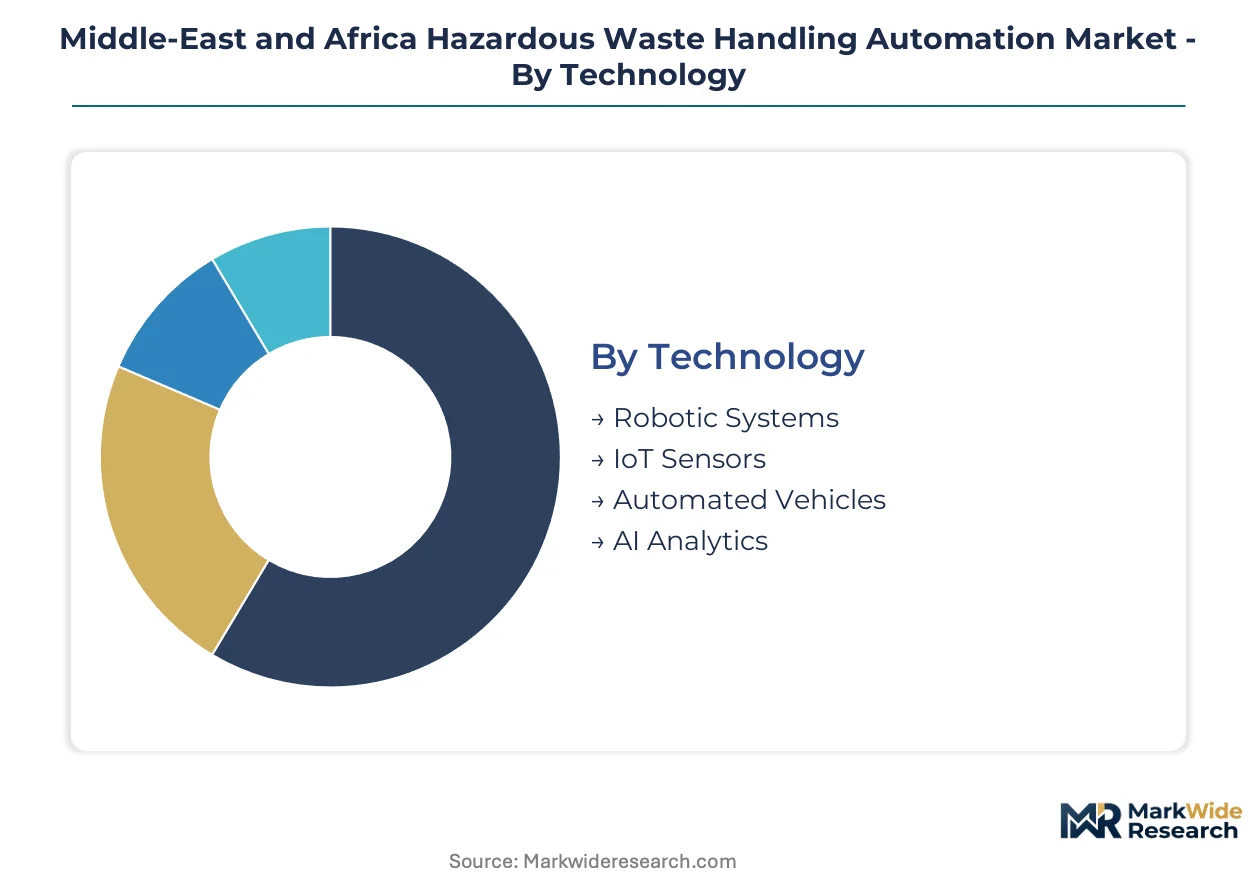
Segmentation in hazardous waste handling automation reveals distinct procurement patterns across technology maturity, integration complexity, and regulatory exposure. Gulf petrochemical operators prioritize predictive capabilities while African municipalities favor phased deployment models.
Technology:
The use-case spectrum spans physical manipulation, environmental sensing, autonomous mobility, and cognitive classification — each commanding different capex profiles and skill requirements.
- Robotic Systems:Articulated arms and gantry configurations handle drum manipulation, tank cleaning, and high-exposure material transfers in Jubail Industrial City refineries. Saudi Aramco suppliers specify IP67-rated actuators for corrosive atmospheres where human exposure is prohibited.
- AI Analytics:Machine vision and spectral analysis platforms classify waste streams in real-time, reducing manifest documentation errors. South African platinum producers deploy these systems to meet Department of Forestry, Fisheries and the Environment diversion mandates.
- IoT Sensors:Distributed temperature, pressure, and chemical detection networks enable containment breach alerts.
- Automated Vehicles:AGVs and teleoperated carriers transport sealed containers across facility zones.
Established volume favors Robotic Systems; emerging adoption favors AI Analytics.
Service Type:
Margin concentration follows the customer transition from capital acquisition to operational assurance.
- Maintenance:Predictive service contracts for robotic manipulators and sensor networks now dominate vendor revenue in Gulf petrochemical zones. Saudi operators prioritize uptime guarantees over spare parts procurement.
- System Integration:Protocol bridging between legacy analog infrastructure and digital control systems commands premium pricing in Jubail and Ras Al-Khair retrofit projects.
- Consulting:Regulatory compliance pathway design for multi-jurisdiction operators.
- Support:Remote diagnostics and software updates for cloud-enabled platforms.
Recurring revenue concentrates in Maintenance; project-based margins favor System Integration.
End User:
Compliance intensity and capital availability diverge sharply across facility types.
- Waste Treatment Facilities:Centralized hazardous waste processors in South Africa's Northern Cape deploy automated sorting and neutralization to meet license renewal conditions tied to landfill diversion targets.
- Manufacturing Plants:Egyptian and Moroccan industrial facilities are retrofitting effluent handling systems as national environmental enforcement tightens.
- Municipalities:Limited capex budgets favor modular, phased automation deployment.
- Research Institutions:Radiological and biological waste handling drives specialized robotic containment requirements.
Penetration depth favors Waste Treatment Facilities; growth velocity favors Manufacturing Plants.
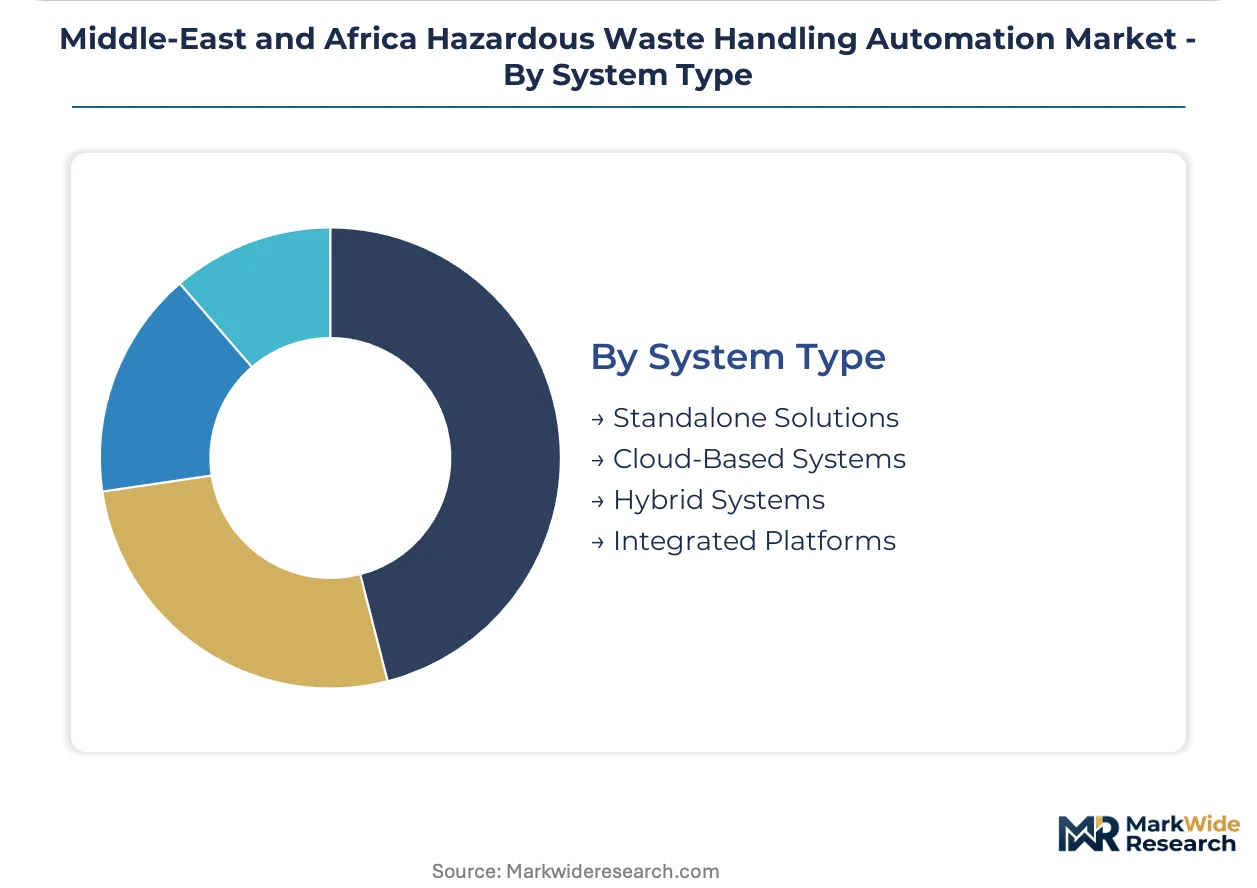
System Type:
Architecture choice reflects trade-offs between flexibility, integration cost, and regulatory audit readiness.
- Integrated Platforms:Real-time monitoring combined with automated manifest reporting satisfies UAE Ministry of Climate Change and Environment documentation mandates. Vendors with software-hardware integration capabilities capture premium positioning.
- Cloud-Based Systems:Remote oversight and predictive analytics reduce on-site technical staffing requirements for African operators facing recruitment bottlenecks.
- Standalone Solutions:Point automation for specific waste stream handling without enterprise integration.
- Hybrid Systems:Local control for safety-critical functions with cloud connectivity for reporting and analytics.
Regulatory tailwinds favor Integrated Platforms; staffing constraints favor Cloud-Based Systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity diverges sharply across the Middle-East and Africa Hazardous Waste Handling Automation Market. Gulf petrochemical operators exhibit low price sensitivity due to compliance-driven procurement mandates, while African municipalities face severe capital constraints that favor modular, phased deployment models.
Saudi Arabia
Jubail Industrial City and Ras Al-Khair host the region's densest concentration of retrofit activity. The General Authority for Meteorology and Environmental Protection enforces manifest documentation protocols aligned with Vision 2030 diversification targets. Saudi Aramco suppliers specify IP67-rated robotic systems for corrosive refinery atmospheres where human exposure is prohibited.
United Arab Emirates
The Ministry of Climate Change and Environment mandates hazardous waste tracking documentation that favors integrated platforms with automated regulatory reporting. Dubai and Abu Dhabi industrial zones deploy cloud-based oversight systems to reduce on-site technical staffing requirements. Jebel Ali petrochemical complexes represent the primary demand concentration for IoT-enabled containment retrofits.
South Africa
The Department of Forestry, Fisheries and the Environment enforces landfill diversion targets that accelerate capital deployment in automated sorting equipment. Mining and metallurgical operations in the Northern Cape and Mpumalanga provinces respond with phased automation investments tied to license renewal timelines. Johannesburg-centered waste treatment facilities dominate procurement volume for neutralization systems.
Egypt
Manufacturing plants in Cairo and Alexandria industrial corridors are retrofitting effluent handling systems as national environmental enforcement tightens. The country's industrial zones face mounting pressure to comply with tightening effluent discharge standards. Suez Canal Economic Zone petrochemical projects incorporate automated waste handling in greenfield designs.
Morocco
Casablanca-Settat and Tangier-Med industrial zones drive North African adoption of automated waste classification systems. Manufacturing facilities serving European export markets face compliance pressure from EU-bound supply chain sustainability requirements. OCP Group mining operations in Khouribga and Youssoufia deploy robotic handling for phosphoric acid waste streams.
Middle-East and Africa Hazardous Waste Handling Automation Market Competitive Landscape
Industrial automation specialists and integrated waste service providers split the Middle-East and Africa Hazardous Waste Handling Automation Market into distinct competitive spheres. Market structure tilts toward solution integration depth rather than component manufacturing scale. Three archetypes dominate: crane automation heritage players leveraging heavy-lift expertise, robotic manipulator specialists targeting radiological containment, and integrated waste-to-resource platforms spanning collection through disposal. Competitive dynamics center on long-term service contract capture and legacy system protocol bridging capabilities.
Among the crane automation heritage players, Konecranes anchors heavy-lift waste handling positioning across Gulf petrochemical zones. PAR Systems occupies the robotic manipulator specialist tier, with its designation indicating focus on high-consequence handling environments. Averda exemplifies the integrated waste-to-resource platform archetype, spanning multiple operational stages across diverse African jurisdictions. These three represent distinct strategic postures rather than direct product competition, with each archetype capturing value through different points in the automation value chain.
| Leading Market Players |
|---|
| PAR Systems |
| Konecranes |
| Pallmann Maschinenfabrik GmbH & Co. |
| Hosokawa Micron Powder Systems |
| Floatograph Technologies |
| Terex MHPS GmbH |
| Hiab |
| PENZ Crane GmbH |
| Averda |
| Others |
Supply & Pricing Matrix
Stainless steel and specialized sensor component price volatility from concentrated Asian supply chains compresses equipment margins for regional integrators while simultaneously widening the spread between premium IP67-rated robotic systems and standard automation tiers across Gulf petrochemical procurement.
Pricing Analysis
Aftermarket service contracts for predictive maintenance and uptime guarantees now capture the dominant share of lifetime value in hazardous waste handling automation, displacing upfront equipment margins as the primary profit pool. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation in corrosion resistance ratings, AI analytics integration depth, and regulatory reporting automation bundled into platform subscriptions. Cost compression in standard-tier robotic manipulators is intensifying because stainless steel input volatility and Asian component sourcing dependencies squeeze integrator margins. Municipal buyers in African jurisdictions exhibit the highest price sensitivity due to capital constraint pressures, while Saudi Aramco suppliers and UAE petrochemical operators demonstrate minimal price elasticity given compliance-driven procurement mandates and human exposure prohibition requirements.
Supply Chain Analysis
Export-control restrictions on advanced robotics controllers and machine vision processors limit technology flows into Middle Eastern and African automation deployments, forcing regional integrators to source through licensed distributors or pursue alternative component architectures. Manufacturing concentration for precision actuators and IP67-rated enclosures centers on Germany, Japan, and South Korea, while spectral sensors and IoT communication modules draw from Taiwanese and Chinese production hubs. Stainless steel alloys, rare-earth magnet components, and specialized optical sensors constitute critical input dependencies. Single-source vulnerability runs through concentrated Asian supply chains for corrosion-resistant sensor housings. Distribution runs through authorized regional integrators and OEM service networks rather than direct manufacturer-to-end-user channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
AI Analytics convergence with sensor networks is accelerating waste classification accuracy improvements while collapsing acceptable error rates for hazardous material identification, creating a high-growth disruption window for vendors with integrated software-hardware capabilities.
For Market Incumbents: Build switching-cost moats through long-term predictive maintenance subscriptions and legacy system protocol bridging expertise that locks in Jubail Industrial City and Ras Al-Khair retrofit contracts. Threats from emerging robotic manipulator specialists and cloud-native analytics platforms necessitate accelerated computer vision capability acquisition through targeted R&D or partnership structures. Backward integration into corrosion-resistant component supply reduces exposure to Asian stainless steel price volatility. For New Entrants and Emerging Players: Establish a beachhead in Egyptian and Moroccan manufacturing plant automation where tightening industrial effluent standards create compliance-driven demand without entrenched incumbent relationships. North African manufacturing corridors present the most penetrable geography given limited legacy automation infrastructure and phased procurement patterns favoring modular deployment. Go-to-market positioning should emphasize cloud-based regulatory reporting automation that satisfies tightening documentation requirements without heavy on-site technical staffing. For Investors and Strategic Acquirers: South Africa's National Waste Management Strategy enforcement reshapes the acquisition landscape by accelerating capital deployment timelines for automated sorting and neutralization equipment tied to license renewal conditions. Long-term viability concentrates on vendors with integrated platform architectures spanning real-time monitoring, predictive analytics, and automated manifest documentation. Acquisition targets should demonstrate software-hardware integration depth and recurring service revenue concentration. The signal to watch is UAE-Saudi regulatory harmonization progress on hazardous waste manifest protocols, which would eliminate redundant compliance investments and favor scaled platform operators.| Strategic Initiative | Industry Significance |
|---|---|
| AI Analytics Platform Integration | Machine vision and spectral sensor convergence collapses error rates for hazardous waste classification in Jubail refineries. |
| Predictive Maintenance Service Expansion | Uptime guarantee subscriptions displace equipment margins as primary profit pool across Saudi Aramco supplier relationships. |
| Legacy System Protocol Bridging | Digital-analog integration expertise commands premium pricing in decades-old Jubail and Ras Al-Khair retrofit projects. |
| Cloud-Based Regulatory Reporting Automation | UAE Ministry of Climate Change and Environment documentation mandates favor integrated platforms with real-time monitoring. |
| Corrosion-Resistant Component Supply Control | IP67-rated actuator sourcing from German and Japanese manufacturers reduces Asian supply chain volatility exposure. |
Research Methodology
Desk research of trade customs databases, industrial automation equipment import records, and national environmental enforcement filings preceded structured interviews with maintenance directors at Gulf petrochemical complexes, aftermarket service heads at regional integrators, procurement officers at South African mining operations, and regulatory compliance leads at waste treatment facilities. Primary intelligence combined with secondary validation from SEC filings of listed automation vendors, EPC contractor project databases, and national waste management strategy documentation. Bottom-up equipment shipment analysis triangulated against top-down capital expenditure tracking across identified industrial zones.
Assumptions held fixed include current UAE Ministry of Climate Change and Environment documentation protocols, Saudi General Authority for Meteorology and Environmental Protection enforcement alignment with Vision 2030, and South African Department of Forestry, Fisheries and the Environment landfill diversion target trajectories. The analytical framework modeled technology adoption curves, service type revenue mix shifts, and end-user penetration depth across the projection horizon. Segmentation dimensions incorporated robotic system configurations, AI analytics integration levels, maintenance versus integration service types, and facility-specific compliance intensity. CAGRs derived from equipment deployment run-rates, license renewal timelines, and retrofit project backlogs.
Sensitivities concentrate around regulatory harmonization between Saudi and UAE manifest systems, Asian component supply disruptions, and petrochemical capital expenditure cycle turns. Forecasts reflect documented assumptions on enforcement intensity and technology substitution rates. Material shifts in Gulf Cooperation Council environmental prosecution patterns or export-control expansion on robotics controllers would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste Management & Pollution Control
Compostable and Biodegradable Refuse Bags Market
Waste Management & Pollution Control
Smart Waste Sorting Bin Market
Waste Management & Pollution Control
UAE Biomedical Waste Management Market
Waste Management & Pollution Control
Waste Compactor Bins Market
Waste Management & Pollution Control
Saudi Arabia Waste Management Market
Waste Management & Pollution Control
Global Smart Trash Bin Market
Waste Management & Pollution Control
Landfill Gas Market
Waste Management & Pollution Control
North America Municipal Solid Waste Management Market
Waste Management & Pollution Control
Metal Recycling Equipment Market
Waste Management & Pollution Control
India Recycling Market
Waste Management & Pollution Control
Asia Pacific Medical Waste Management Market
Waste Management & Pollution Control
North America Waste Management Market
Waste Management & Pollution Control
Europe Waste Recycling Services Market
Waste Management & Pollution Control
Global Oil Spill Management Market
Waste Management & Pollution Control
GCC Industrial Waste Management Market
Waste Management & Pollution Control
Sludge Management Equipment Market