
 PET Recycling Market | 2026-2036
PET Recycling Market Size, Share, and Industry Trends Forecast 2026-2036
PET Recycling Market Outlook
Food-grade pellet specifications is unwinding legacy mechanical recycling margins and pushing capital toward chemical purification assets. Indorama Ventures Public Company Limited anchors Asian rPET supply through integrated bottle-to-resin operations. Plastipak Holdings, Inc. specializes in closed-loop food-contact recycling systems tied to major beverage contracts. Evergreen dominates North American bottle reclamation with scale infrastructure across multiple collection zones.
PET recycling encompasses the collection, sorting, cleaning, and reprocessing of polyethylene terephthalate waste into reusable resin with intrinsic viscosity targets between 0.72 and 0.82 dL/g for bottle-grade applications. The process serves primarily to displace virgin petrochemical feedstock in packaging, textiles, and engineered materials. Post-consumer waste streams command structural priority as deposit-return schemes and extended producer responsibility laws expand collection volumes. Chemical recycling methods represent the fastest-growing segment as brand mandates for food-contact rPET outstrip mechanical output purity limits. Packaging end-use absorbs the dominant margin pool, though textile offtake for polyester fiber grows as a volume outlet for lower-specification flake.
The US FDA issues letters of no objection for challenged post-consumer recycling processes, while EU REACH restricts substances in recycled materials and the EU Green Deal mandates minimum recycled content thresholds. These frameworks compel processors to validate decontamination performance and traceability chains. Stakeholders must weigh chemical recycling capital commitments against mechanical line upgrades as regulatory thresholds for food-contact approval diverge across jurisdictions.
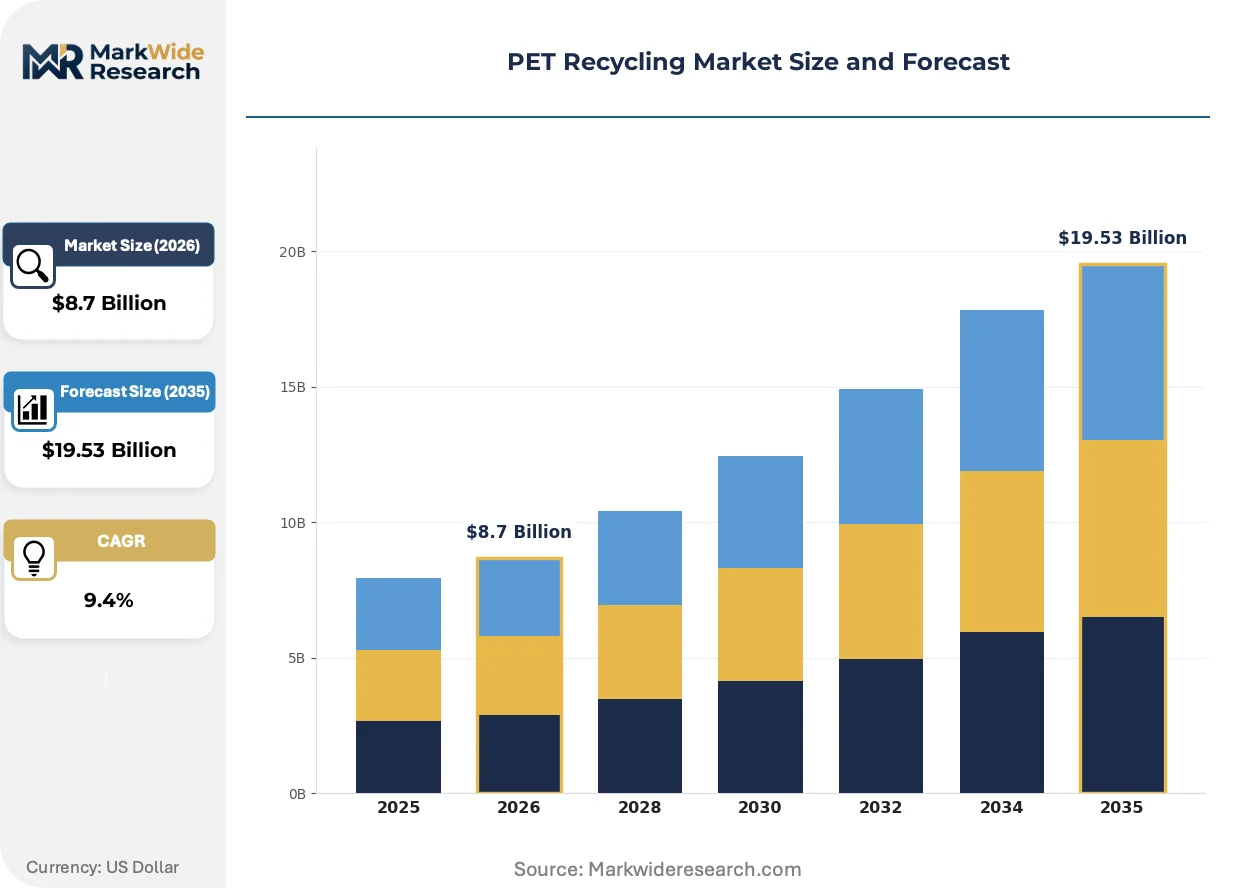
Market Dynamics
Food-grade rPET certification requirements are compressing mechanical recycling margins and redirecting capital toward chemical purification infrastructure capable of meeting EFSA and FDA contamination thresholds.
Growth Catalysts
- EU Green Deal recycled content mandates:Minimum thresholds for post-consumer material in beverage packaging are pulling virgin substitution demand forward across European bottling operations.
- Chemical recycling scale-up:Purification technologies achieving intrinsic viscosity targets above 0.80 dL/g are unlocking food-contact applications previously closed to mechanically reprocessed flake.
- Germany:Bottle-to-bottle collection density and EFSA-approved decontamination lines anchor regional supply security for major beverage contracts.
Market Restraints
- Feedstock cost volatility:Post-consumer bale prices fluctuate with crude oil parity and virgin PET pricing, compressing processor spreads during energy price spikes.
- Collection infrastructure concentration:Deposit-return scheme coverage remains uneven, leaving supply gaps in jurisdictions without legislated extended producer responsibility frameworks.
- Mechanical purity ceiling:Legacy reprocessing lines cannot consistently achieve EFSA challenge test thresholds for food-contact approval, stranding capacity in lower-margin fiber applications.
Strategic Opportunities
- India:BIS standards for recycled plastics in food contact remain under development, creating first-mover positioning for processors establishing chemical purification ahead of formal mandates.
- Textile-to-textile circularity:Polyester fiber reclaim from post-consumer garments offers volume outlets for lower-specification flake displaced from packaging by food-grade purity requirements.
- Blockchain traceability integration:Digital chain-of-custody systems are qualifying material for premium pricing tiers tied to verified recycled content claims.
Industry Challenges
- Decontamination engineering talent scarcity:Process validation for FDA letters of no objection requires specialized expertise in migration modeling and challenge testing protocols.
- Multi-jurisdictional certification timelines:Divergent EFSA and FDA approval pathways for novel recycling technologies extend commercialization cycles by 18-36 months.
- Legacy flake-to-fiber asset stranding:Mechanical recycling lines configured for textile output face margin compression as food-grade pellet premiums widen.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PET Recycling Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pre-Consumer Waste, Post-Consumer Waste, Bottles, Trays Recycling Method: Mechanical, Chemical, Thermal, Solvent-Based End Use Industry: Packaging, Textiles, Construction, Automotive Market Channel: Direct Sales, Online Retail, Distributors, Recyclers |
| Companies Covered | Phoenix Technologies International LLC, PFR Nord GmbH, Indorama Ventures Public Company Limited, Alpek, Plastipak Holdings, Inc., Evergreen, Krones AG, UltrePET, LLC, PetStar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PET Recycling Market Strategic Shifts
Advanced purification technologies and digitized traceability systems are restructuring competitive advantage around certification depth rather than collection scale alone.
Enzymatic depolymerization is displacing conventional glycolysis for bottle-grade resin production. Nestlé and Coca-Cola procurement teams have qualified enzymatically processed rPET for European bottling contracts. This biotechnology is displacing thermal depolymerization capital allocations among Asian resin producers seeking EFSA-compliant output without methanolysis infrastructure.
REACH restrictions on substances of very high concern in recycled materials are tightening decontamination performance standards. ECHA guidance now requires demonstration of <0.1 mg/kg migration limits for legacy contaminants across all recycling technologies. German processors with established super-clean mechanical lines are upgrading to hybrid chemical-mechanical systems to maintain certification.
Beverage brand procurement contracts now specify mass-balance certification over simple recycled content percentages. Unilever and PepsiCo sourcing teams are auditing collection zone provenance and reprocessing chain integrity. This verification-driven purchasing is most visible in Northern European markets where consumer-facing sustainability claims face advertising authority scrutiny.
PET Recycling Market Segmentation
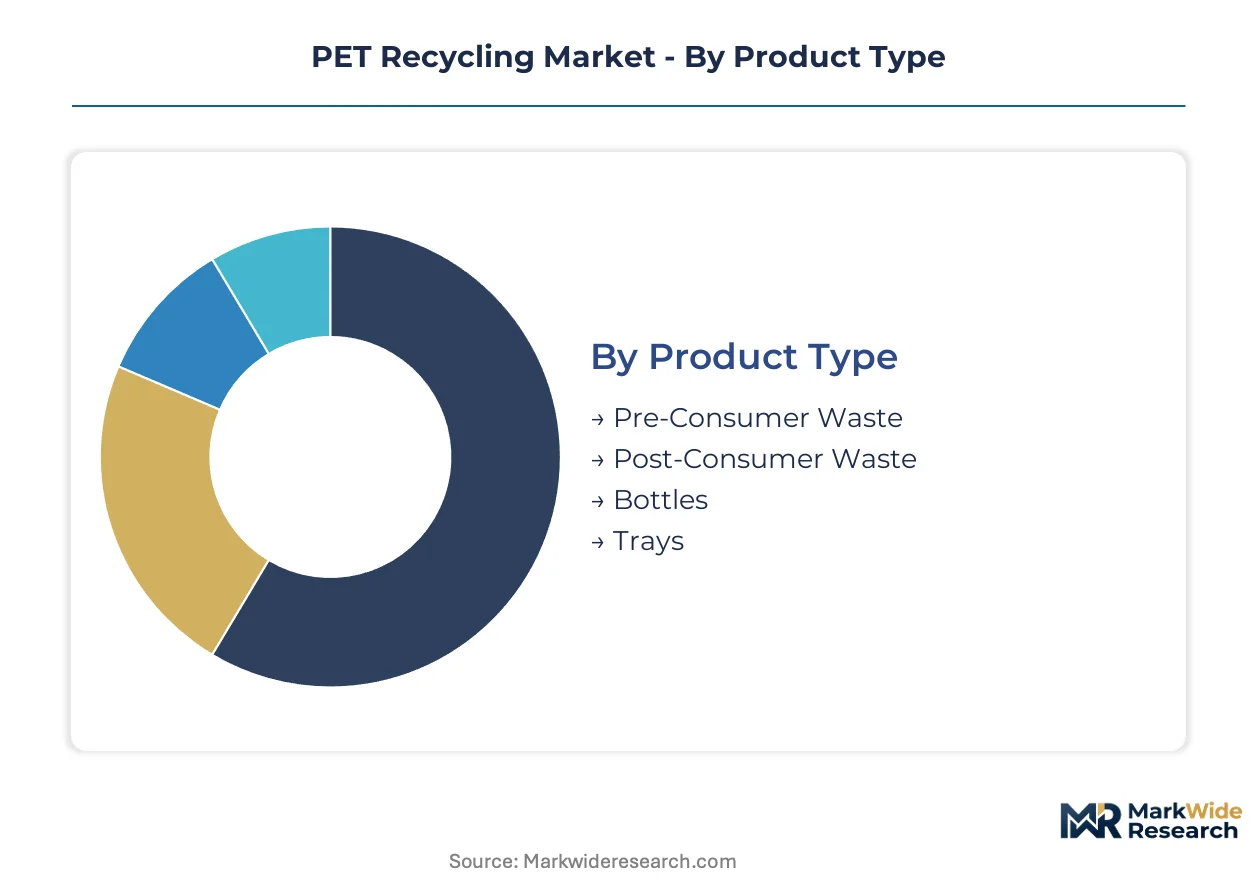
PET recycling market segmentation reflects divergent purity requirements and capital intensity thresholds across processing technologies. Regulatory approval pathways for food-contact applications split mechanical from chemical methods, while end-use specifications determine resin viscosity targets and decontamination rigor.
Product Type:
EU REACH substance restrictions and FDA letters of no objection create divergent feedstock qualification tiers based on contamination risk and collection provenance.
- Post-Consumer Waste:Discarded bottles, containers, and packaging recovered through municipal collection and deposit-return schemes. Beverage bottlers in Germany and California concentrate procurement here due to established chain-of-custody documentation supporting EFSA and FDA food-contact approvals.
- Pre-Consumer Waste:Industrial scrap from resin production, sheet extrusion, and thermoforming operations with minimal contamination and known provenance. Textile fiber producers in South Carolina and Gujarat prioritize this stream for lower decontamination costs and predictable intrinsic viscosity.
- Bottles:Curbside and deposit-system collections dominated by carbonated soft drink and water packaging formats. Collection density in Michigan and Norway generates bale volumes sufficient to justify dedicated bottle-to-bottle purification lines.
- Trays:Thermoformed food packaging, clamshells, and non-bottle rigid containers with higher additive loads and barrier layer complexity. Mechanical recyclers in Spain and Italy process trays into lower-specification sheet and strapping applications.
Post-Consumer Waste handles the majority of throughput; Chemical recycling of bottle-grade material is expanding most quickly on share.
Recycling Method:
Capital deployment patterns split between mechanical asset upgrades and greenfield chemical purification plants based on end-use margin premiums.
- Chemical:Depolymerization to monomers followed by repolymerization to virgin-quality resin with intrinsic viscosity above 0.80 dL/g. Enzymatic processes developed by French biotechnology firms are displacing thermal glycolysis for European beverage contracts requiring EFSA-compliant food-contact certification.
- Mechanical:Sorting, washing, and re-melting of flake without molecular breakdown, constrained by 0.72-0.78 dL/g viscosity ceilings and residual contaminant carryover. German processors with super-clean lines are hybridizing with chemical steps to maintain certification as REACH thresholds tighten.
- Thermal:Pyrolysis and gasification routes producing feedstock for chemical synthesis rather than direct resin output. Japanese engineering firms are piloting thermal depolymerization for mixed-plastic streams unsuited to mechanical sorting.
- Solvent-Based:Selective dissolution and precipitation achieving higher purity than conventional mechanical methods without full depolymerization. Dutch technology providers are commercializing solvent purification for polyolefin-contaminated PET bales.
Mechanical recycling retains volume dominance; Chemical methods are gaining share fastest as food-grade premiums widen.
End Use Industry:
Application specifications determine resin grade requirements and the economic viability of purification investments.
- Packaging:Bottle, sheet, and thermoformed container applications demanding 0.72-0.82 dL/g intrinsic viscosity and sub-0.1 mg/kg contaminant migration limits. EU Green Deal minimum recycled content mandates are pulling rPET procurement forward among beverage brand owners.
- Textiles:Polyester staple fiber and filament production accepting lower viscosity and broader contamination tolerances. Garment reclaim operations in Turkey and Vietnam are creating volume outlets for flake displaced from packaging by food-grade purity requirements.
- Construction:Geotextiles, insulation, and composite reinforcement applications with minimal purity requirements. Road base stabilization projects in Texas and Queensland absorb lower-specification regrind.
- Automotive:Interior trim, under-hood components, and carpet backing requiring moderate viscosity control and thermal stability. Tier-1 suppliers in Michigan and Stuttgart are qualifying rPET for non-structural interior panels.
Packaging commands the dominant margin pool; Textile offtake is climbing the fastest as fiber applications absorb displaced mechanical flake.
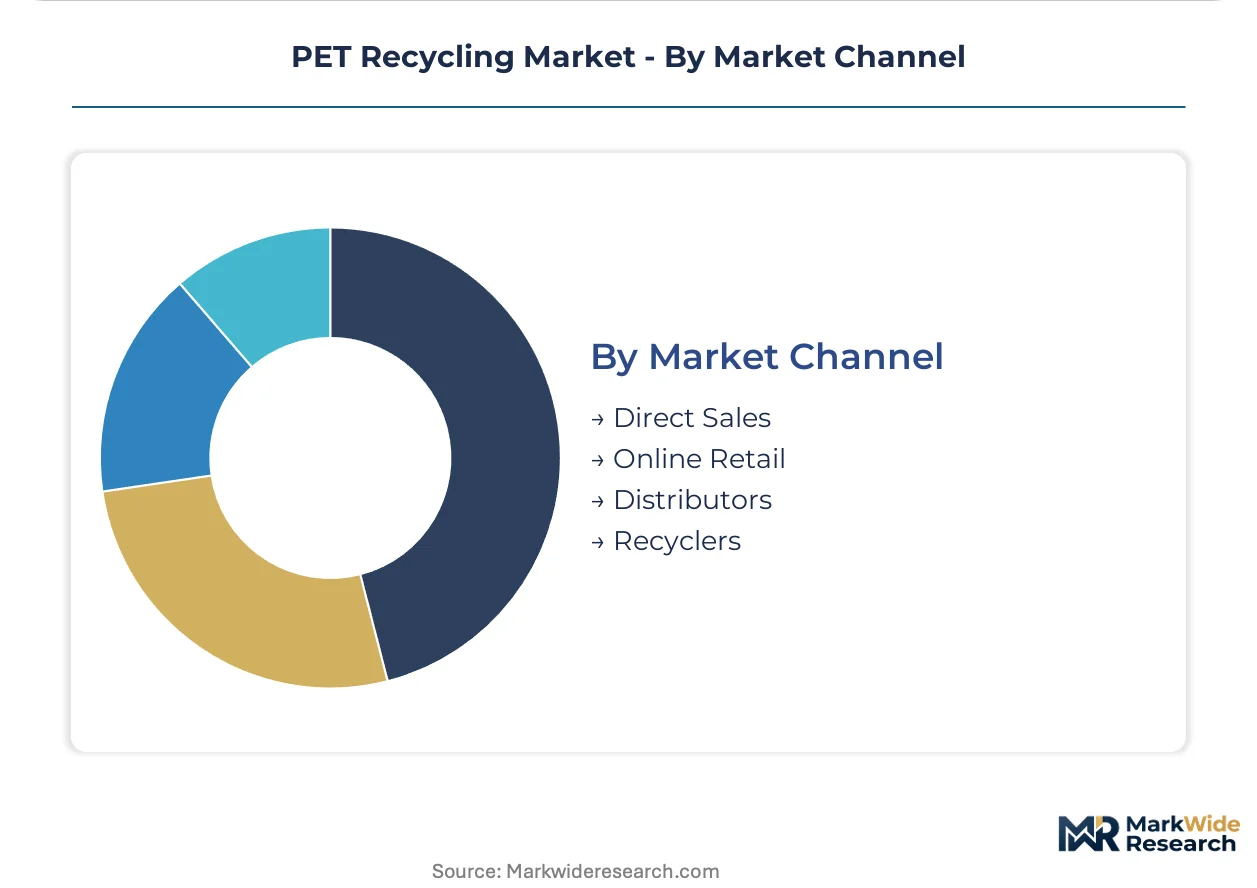
Market Channel:
Transaction structures vary by buyer scale, certification requirements, and geographic proximity to processing assets.
- Direct Sales:Long-term contracts between resin producers and beverage brand owners with specified mass-balance certification and audit rights. Nestlé and Coca-Cola procurement teams in Switzerland and Atlanta negotiate multi-year supply agreements with traceability mandates.
- Distributors:Regional intermediaries aggregating flake and pellet volumes for mid-scale converters lacking direct mill relationships. Distributor networks in São Paulo and Bangkok bridge collection zones to extrusion operations.
- Online Retail:Spot market platforms for standard-grade flake with limited certification documentation. Digital marketplaces in Shanghai and Rotterdam facilitate price discovery for lower-specification material.
- Recyclers:Integrated processors selling captive output from owned collection through reprocessing operations. Closed-loop systems operated by Plastipak in Michigan and Indorama in Thailand internalize margin across the value chain.
Direct Sales handles the majority of food-grade volume; Distributors are gaining share fastest among mid-cap converters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports rPET pellets to beverage bottlers across Northern Europe while importing post-consumer bales from neighboring collection zones. Trade flows concentrate around EFSA-certified decontamination corridors, with regional price spreads widening as food-grade certification premiums diverge.
Germany
Bottle-to-bottle collection density and EFSA-approved decontamination lines anchor regional supply security for major beverage contracts. The EU Green Deal mandates minimum recycled content thresholds that pull virgin substitution demand forward across German bottling operations. The Rhineland cluster hosts super-clean mechanical lines upgrading to hybrid chemical-mechanical systems as REACH thresholds tighten.
United States
Deposit-return schemes in Michigan and California generate bale volumes sufficient to justify dedicated bottle-to-bottle purification lines. FDA letters of no objection for challenged post-consumer recycling processes compel processors to validate decontamination performance and traceability chains. The Southeast textile belt absorbs lower-specification flake displaced from packaging by food-grade purity requirements.
India
BIS standards for recycled plastics in food contact remain under development, creating first-mover positioning for processors establishing chemical purification ahead of formal mandates. The DGFT regulates import flows of post-consumer scrap while domestic collection networks expand in Maharashtra and Gujarat. Ahmedabad and Surat house mechanical recyclers configuring lines for textile fiber output pending food-contact regulatory clarity.
China
Dual carbon goals and MIIT circular economy directives accelerate chemical recycling capital deployment for virgin-quality resin output. NMPA-equivalent food-contact standards for rPET remain less stringent than EFSA benchmarks, limiting export qualification for European beverage contracts. The Yangtze River Delta concentrates glycolysis and methanolysis capacity serving domestic packaging converters.
Brazil
ANVISA pharmaceutical-grade purity protocols create indirect pressure on PET recyclers to demonstrate contaminant control capabilities. Extended producer responsibility frameworks under development in São Paulo and Rio de Janeiro expand collection volumes for mechanical reprocessing. The São Paulo state cluster hosts integrated processors selling captive output from owned collection through extrusion operations.
PET Recycling Market Competitive Environment
Listed leaders compete with private specialists across certification depth and collection infrastructure integration. The vendor base splits between integrated resin producers with captive bottle-to-resin operations and independent recyclers focused on flake-to-fiber conversion. Three archetypes dominate: chemical purification specialists, closed-loop beverage contract holders, and mechanical scale players serving textile offtake. Competitive moves concentrate on backward integration into collection zones and technology licensing for EFSA-compliant decontamination.
Within the integrated resin tier, Indorama Ventures Public Company Limited and Alpek represent archetypes of Asian and Latin American scale concentration. Plastipak Holdings, Inc. occupies a position exemplifying closed-loop food-contact recycling systems tied to major beverage contracts. Evergreen anchors North American bottle reclamation with multi-zone collection infrastructure. These three names illustrate how geographic coverage and certification depth separate premium-tier positioning from commodity flake supply.
| Leading Market Players |
|---|
| Phoenix Technologies International LLC |
| PFR Nord GmbH |
| Indorama Ventures Public Company Limited |
| Alpek |
| Plastipak Holdings, Inc. |
| Evergreen |
| Krones AG |
| UltrePET, LLC |
| PetStar |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts between beverage brand procurement teams and EFSA-certified processors lock in both supply access and price visibility for food-grade rPET across Northern European bottling corridors. These agreements tie pellet premiums to decontamination performance validation and mass-balance certification depth rather than virgin PET spot parity alone.
Pricing Analysis
Industrial OEM buyers anchor food-grade pellet procurement through multi-year supply agreements with specified migration limits and audit rights. Three-tier pricing structure across EFSA-certified premium, FDA-cleared standard, and non-food-contact economy levels reflects decontamination rigor and traceability documentation depth. Cost compression in mechanical flake tiers is intensifying because REACH threshold tightening strands legacy capacity in lower-margin textile applications. Mid-scale converters lacking direct mill relationships exhibit highest price sensitivity, while Nestlé and Coca-Cola procurement teams absorb premium tiers for compliance security.
Supply Chain Analysis
EFSA-approved decontamination line capacity in Germany underwrites food-grade pellet supply security for European beverage contracts. Post-consumer bale sourcing draws from Michigan deposit-return schemes, California curbside collections, and Norwegian bottle-to-bottle infrastructure. Single-source vulnerability concentrates in enzymatic depolymerization enzyme supply from French biotechnology specialists. Distribution runs through direct sales channels for certified material and regional distributor networks for standard-grade flake.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as EU Green Deal mandates pull virgin substitution demand forward faster than integrated processors can expand EFSA-certified capacity, creating niches for specialist decontamination operators.
For Market Incumbents: Compound certification depth through hybrid chemical-mechanical line upgrades to maintain EFSA compliance as REACH thresholds tighten. Threat of enzymatic depolymerization specialists capturing European beverage contracts demands backward integration into collection zone control across multiple jurisdictions. Priority lever rests on decontamination engineering talent retention for FDA letter of no objection validation. For New Entrants and Emerging Players: FDA fast-track approval for novel chemical purification technologies opens white-space positioning in India ahead of formal BIS food-contact mandates. Most penetrable target sits with mid-cap textile converters in Vietnam and Turkey seeking displaced mechanical flake from packaging grade compression. Go-to-market angle emphasizes blockchain traceability integration for premium pricing tier qualification. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among processors with captive collection-through-resin operations and long-term beverage brand contracts. Long-term viability favors integrated resin producers with multi-jurisdictional certification portfolios over standalone mechanical recyclers facing asset stranding. Signal to watch is divergence between EFSA and FDA approval timelines for novel recycling technologies extending commercialization cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Collection Zones | Secures post-consumer bale supply for EFSA-certified decontamination lines in Germany and Michigan. |
| Hybrid Chemical-Mechanical Line Upgrade | Maintains food-contact certification as REACH migration limits tighten below 0.1 mg/kg thresholds. |
| Enzymatic Depolymerization Scale-Up | Unlocks EFSA-compliant resin output without methanolysis infrastructure for European beverage contracts. |
| Blockchain Traceability Integration | Qualifies material for premium pricing tiers under Unilever and PepsiCo mass-balance audit requirements. |
| Textile-to-Textile Circularity Partnership | Creates volume outlets for lower-specification flake displaced from packaging by food-grade purity requirements. |
Study Parameters
Initial hypotheses were tested against primary input from decontamination process engineers, beverage brand procurement directors, EFSA compliance consultants, and textile fiber plant managers and refined through secondary validation. Bottom-up triangulation combined customs trade data for post-consumer bale flows, SEC filings from integrated resin producers, EU ECHA guidance documents, and FDA letter of no objection databases. Top-down cross-checks anchored market sizing to EU Green Deal mandate implementation timelines and deposit-return scheme coverage expansion.
Variance decomposition across the projection horizon isolates volume drivers by recycling method, end-use industry, and regional regulatory cluster. Segmentation modeling spans chemical versus mechanical purification routes, packaging versus textile versus automotive offtake, and EFSA-cleared versus FDA-cleared versus non-food-contact certification tiers. CAGRs derive from elasticity analysis linking virgin PET price parity to rPET substitution rates and brand owner recycled content commitment trajectories. Forecast inputs include enzymatic depolymerization capacity buildout announcements and BIS standard development timelines for Indian food-contact approval.
Decision-makers should treat outputs as directional under base assumptions of sustained EU Green Deal enforcement and REACH threshold tightening; material deviation in regulatory implementation pace would warrant model refresh. Practitioners should keep alternative scenarios live as FDA and EFSA approval pathway divergence and crude oil price volatility evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste Management & Pollution Control
GCC Industrial Waste Management Market
Waste Management & Pollution Control
US Medical Waste Management Market
Waste Management & Pollution Control
Asia-Pacific Municipal Solid Waste Management Market
Waste Management & Pollution Control
Wheeled Bins Market
Waste Management & Pollution Control
North America Bio-Medical Waste Management Market
Waste Management & Pollution Control
ASEAN Waste Management Market
Waste Management & Pollution Control
India Recycling Market
Waste Management & Pollution Control
Global Smart Trash Bin Market
Waste Management & Pollution Control
India Waste-To-Energy Market
Waste Management & Pollution Control
Metal Recycling Equipment Market
Waste Management & Pollution Control
Reusable Oil Absorbents Market
Waste Management & Pollution Control
Global Oil Spill Management Market
Waste Management & Pollution Control
Recycled Waste Management Market
Waste Management & Pollution Control
Europe Waste Recycling Services Market
Waste Management & Pollution Control
Solid Waste Management Market
Waste Management & Pollution Control
China Waste Management Market