
 Carbon Credit Retail Consumer Platform Market | 2026-2036
Carbon Credit Retail Consumer Platform Market Size, Share, and Industry Trends Forecast 2026-2036
Carbon Credit Retail Consumer Platform Market Insights
EU Green Deal compliance thresholds is consolidating the competitive landscape for retail carbon credit access. Xpansiv leverages its commodity exchange infrastructure to bridge institutional and retail liquidity pools. South Pole anchors its position through project origination capabilities across forestry and renewable energy portfolios. Gold Standard differentiates via its certification rigor, which commands premium pricing among environmentally conscious consumer segments.
A carbon credit retail consumer platform constitutes a digital marketplace infrastructure that connects verified emission reduction projects with individual and small-business buyers through API-driven transaction engines, blockchain-based provenance tracking, and automated retirement registries. These platforms execute the primary commercial purpose of fractionalizing tonne-scale carbon offsets into consumer-denominated purchases while ensuring transparent retirement and non-double-counting. Mobile application deployments currently lead platform type adoption due to embedded finance integrations and wallet-native user experiences, while subscription plans within service offerings represent the fastest-expanding revenue pool as recurring offset commitments replace one-time voluntary purchases. Peer-to-peer trading functionality remains structurally immature but holds concentrated margin potential where localized supply-demand matching reduces intermediary fee extraction.
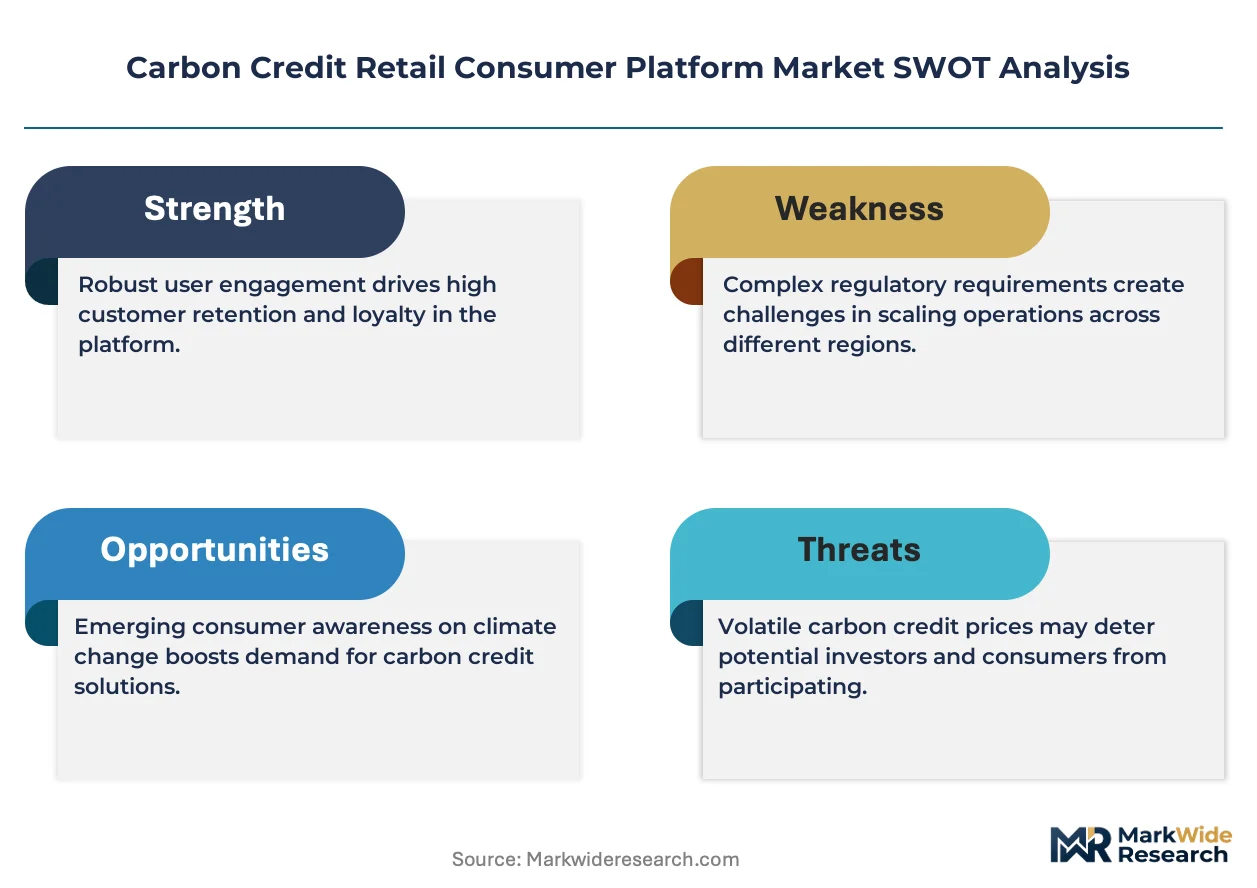
Verra and Gold Standard operate as de facto gatekeepers of demand eligibility through their registry and certification protocols, which determine which credits qualify for corporate net-zero claims and consumer-facing product integrations. The EU AI Act and GDPR impose algorithmic transparency and data governance requirements on automated carbon footprint calculators and personalized offset recommendations. Stakeholders must monitor whether emerging national carbon accounting standards fragment certification recognition or converge toward mutual equivalence, as this will determine platform inventory fungibility and geographic expansion economics.
Market Dynamics
Embedded finance integrations are collapsing transaction friction for voluntary carbon purchases, with API-native platforms capturing wallet-native users through banking and travel booking interfaces. This infrastructure shift is compressing the path from intent to retirement, concentrating liquidity around platforms with direct registry connections.
Growth Catalysts
- EU Green Deal compliance thresholds:The expanding carbon border adjustment mechanism is pushing consumers toward verified offset platforms as compliance standards tighten across member states.
- Airline checkout flow integration:Travel booking platforms are embedding voluntary offset options directly into purchase workflows, creating frictionless demand activation at transaction moments.
- Blockchain provenance tracking:Distributed ledger infrastructure is eliminating double-counting risks and enabling transparent retirement registries that satisfy institutional audit requirements.
Market Restraints
- Registry concentration risk:Verra and Gold Standard certification protocols operate as de facto gatekeepers, determining credit eligibility and creating single-point-of-failure dependency for platform inventory.
- GDPR algorithmic transparency requirements:The EU AI Act imposes data governance burdens on automated carbon footprint calculators, increasing compliance costs for personalized offset recommendation engines.
- Project origination bottlenecks:Verified emission reduction supply concentrates in forestry and renewable energy portfolios with lengthy development timelines, constraining platform inventory fungibility.
Strategic Opportunities
- German banking app penetration:Retail carbon product adoption through fintech integrations in Germany is outpacing other European markets, creating a template for geographic expansion.
- Subscription plan migration:Recurring offset commitments are displacing one-time voluntary purchases, generating predictable revenue streams and improving customer lifetime value metrics.
- Peer-to-peer trading infrastructure:Localized supply-demand matching functionality remains structurally immature but holds concentrated margin potential where intermediary fee extraction compresses.
Industry Challenges
- Certification timeline compression:Gold Standard and Verra verification protocols require extended project validation periods, delaying credit issuance and platform inventory refresh cycles.
- API integration complexity:Legacy banking and travel booking systems demand custom middleware development for carbon offset embedding, stretching technical implementation resources.
- Algorithmic audit skill scarcity:The EU AI Act's explainability requirements for automated recommendation engines outpaces available talent pools in machine learning transparency engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carbon Credit Retail Consumer Platform Market |
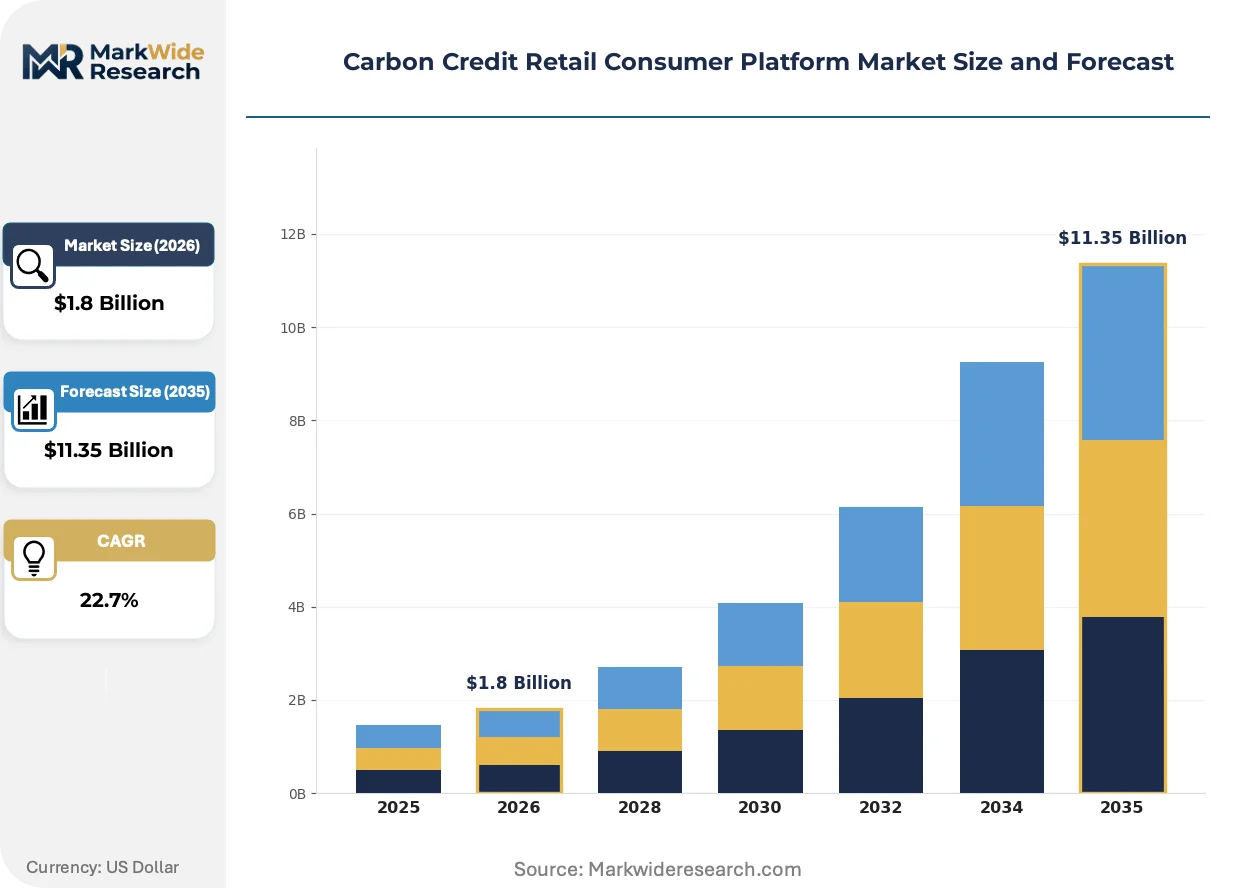
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $11.35 Billion |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Platform Type: Web-Based, Mobile Application, Hybrid, Desktop Client Service Offering: Carbon Offset Purchase, Carbon Footprint Tracking, Trading Marketplace, Advisory Services, Subscription Plans End User: Individual Consumers, Small Businesses, Non-Profit Organizations, Educational Institutions Purchase Method: One-Time Purchase, Recurring Purchase, Auction Bidding, Peer-to-Peer Trading |
| Companies Covered | Xpansiv, Carbon Trade Exchange, AirCarbon Exchange, Climate Impact X, Carbonplace, Verra, Gold Standard, South Pole, ClimeCo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carbon Credit Retail Consumer Platform Market Trends and Innovations
Digital infrastructure is fragmenting tonne-scale carbon offsets into consumer-denominated purchases while embedding verification directly into transaction flows. This convergence of financial technology and environmental accounting is reshaping how retail buyers access and retire emission reductions.
Blockchain-based retirement registries are modularizing carbon credit provenance into interoperable verification layers. Airlines and neobanks are adopting these systems to embed transparent offset workflows within existing payment interfaces. This modularization is compressing the verification chain from project origination to consumer retirement into single-click experiences.
The EU AI Act is mandating algorithmic transparency for automated carbon footprint calculators used in personalized offset recommendations. Platform operators must now document decision logic for emission estimates and retrofit explainability into legacy recommendation engines. German fintech integrations are responding fastest, deploying auditable calculation methodologies ahead of enforcement timelines.
Recurring subscription commitments are displacing one-time voluntary purchases as the dominant procurement model for retail carbon offsets. Banking apps in Germany are bundling monthly offset plans with transaction round-up features, capturing sustained engagement rather than episodic climate guilt transactions. This shift is most visible in urban consumer segments with existing digital wallet adoption.
Carbon Credit Retail Consumer Platform Market Segmentation
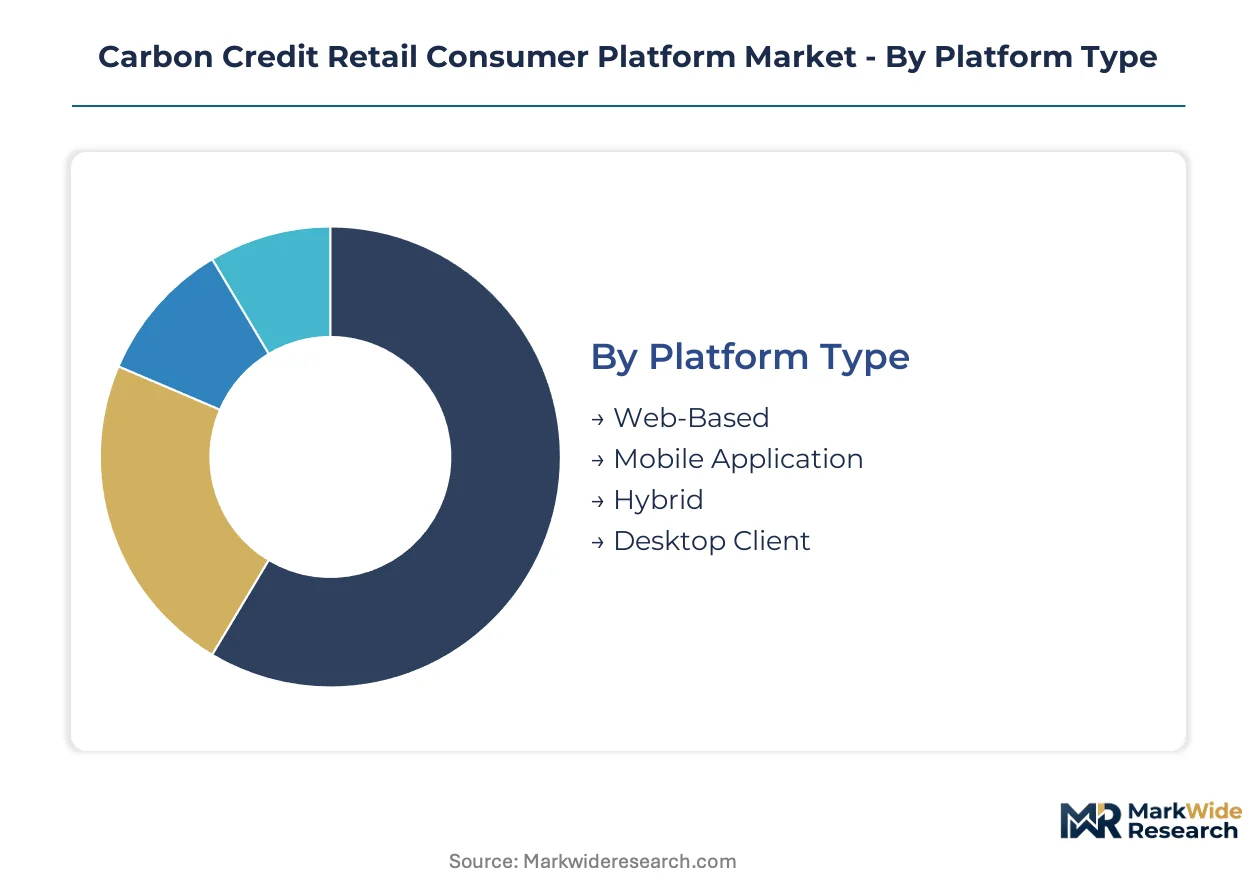
Platform architecture and service packaging determine how carbon credits reach retail buyers. Each segmentation dimension reveals distinct margin structures and user acquisition economics that shape competitive positioning.
Platform Type:
Volume concentrates in mobile-first deployments, while premium pricing attaches to hybrid infrastructure with institutional connectivity.
- Mobile Application:Native iOS and Android deployments dominate user acquisition through embedded finance partnerships. German neobanks and travel booking platforms in the United Kingdom route offset purchases through these interfaces, compressing transaction friction to single-click retirement.
- Web-Based:Browser-accessible platforms serve desktop-oriented small business procurement workflows with dashboard-heavy analytics. France and Netherlands corporate sustainability teams favor these for multi-user license management and audit trail documentation.
- Hybrid:Cross-platform architectures bridge retail convenience with institutional registry APIs. Belgium and Austria platforms deploy these to serve both consumer mobile wallets and corporate treasury offset programs through unified backend infrastructure.
- Desktop Client:Downloadable software targets high-volume traders and portfolio managers requiring offline calculation capabilities. Spain and Italy host concentrated demand from agricultural cooperative technical staff managing collective offset pools.
Today's leader: Mobile Application. Tomorrow's challenger: Hybrid.
Service Offering:
Recurring revenue models are displacing transactional economics as subscription plans lock in predictable offset commitments.
- Subscription Plans:Monthly recurring commitments bundle automatic footprint calculation with pre-scheduled credit retirement. Banking apps in Germany embed these with transaction round-up features, capturing sustained engagement rather than episodic climate guilt purchases.
- Carbon Offset Purchase:Direct tonne-scale fractionalization remains the core revenue driver across all platform types. Denmark and Sweden platforms optimize these for immediate retirement with blockchain-verified provenance documentation.
- Carbon Footprint Tracking:Automated emission calculators integrate transaction data, utility APIs, and travel itineraries. GDPR compliance costs from the EU AI Act's algorithmic transparency requirements concentrate development resources in France and Germany.
- Trading Marketplace:Secondary market infrastructure enables price discovery and liquidity for verified credits. Poland and Czech Republic platforms experiment with these for small business portfolio rebalancing.
- Advisory Services:Consultative offset strategy and net-zero pathway planning attach premium fees. Finland and Norway platforms bundle these with corporate ESG reporting for mid-market enterprises.
Subscription Plans are climbing the fastest as recurring commitments displace one-time voluntary purchases across Northern Europe.
End User:
Individual consumers drive transaction volume, while small businesses command higher average order values and longer platform retention.
- Individual Consumers:Retail buyers activate through embedded checkout flows in travel and banking applications. Ireland and Portugal show highest per-capita adoption rates among EU member states with mature digital wallet penetration.
- Small Businesses:Companies under 250 employees purchase offsets for scope 3 emissions and supply chain compliance. Luxembourg and Switzerland platforms target these with simplified audit documentation and bulk retirement tools.
- Non-Profit Organizations:Mission-driven entities seek verified credits for operational neutrality and donor-facing impact reports. Greece and Croatia host growing demand from environmental NGOs with EU funding disclosure requirements.
- Educational Institutions:Universities and research centers offset travel emissions and campus operations. Slovenia and Estonia platforms serve these with academic discount tiers and student engagement modules.
Small Businesses are gaining share fastest as compliance pressure from the EU Green Deal expands beyond large corporates.
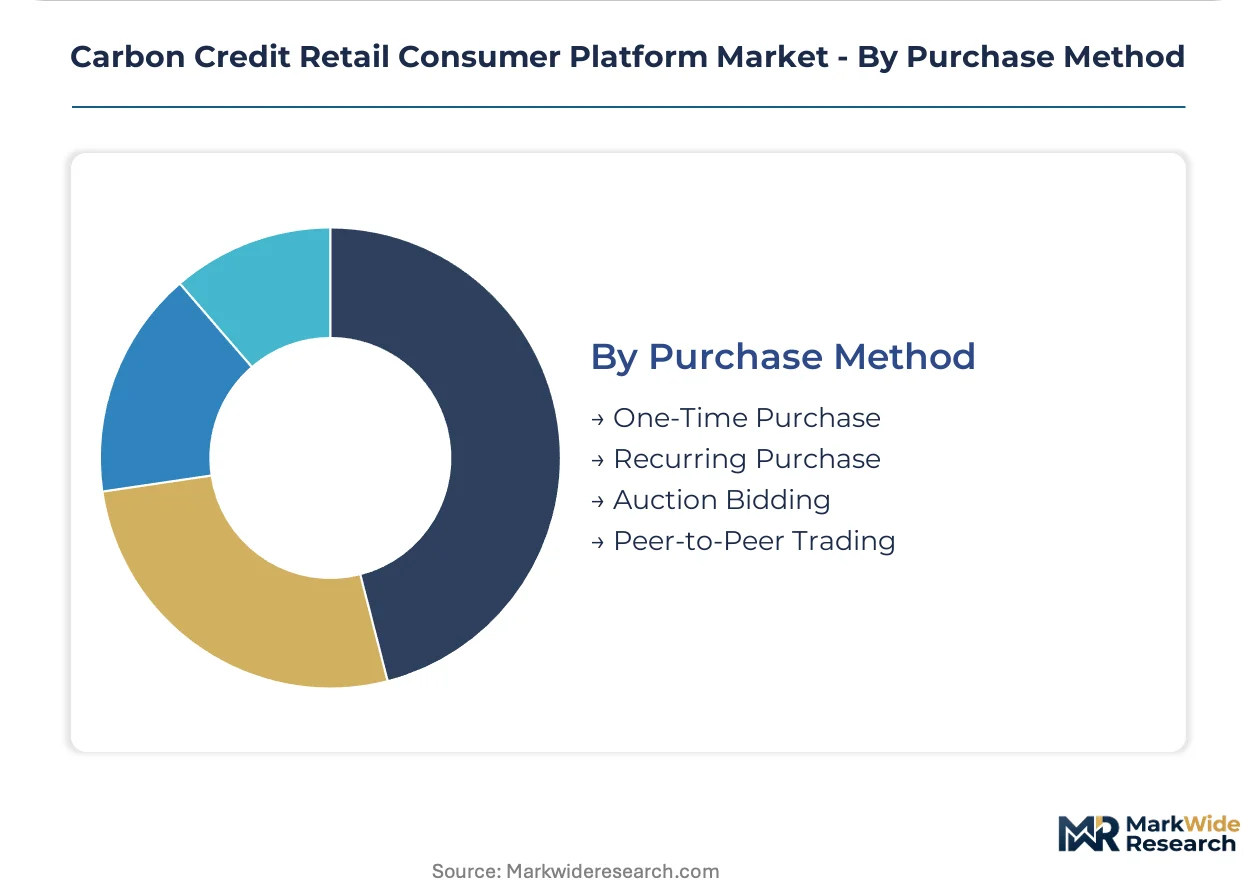
Purchase Method:
Recurring purchase infrastructure captures lifetime value, while peer-to-peer trading remains structurally immature with concentrated margin potential.
- Recurring Purchase:Automated scheduling of monthly or quarterly offset commitments with payment method on file. Hungary and Slovakia platforms deploy these with variable pricing tied to real-time credit availability.
- One-Time Purchase:Episodic transactions triggered by specific events such as flights or vehicle registration. Latvia and Lithuania platforms optimize checkout conversion through localized payment method integration.
- Auction Bidding:Competitive price discovery for bulk credit acquisitions by institutional buyers. Bulgaria and Romania platforms pilot these for renewable energy certificate aggregation.
- Peer-to-Peer Trading:Direct matching between local project developers and retail buyers with reduced intermediary extraction. Malta and Cyprus platforms test these for community-based forestry credit distribution.
Recurring Purchase dominates current revenue composition. Peer-to-Peer Trading holds the steepest expansion trajectory if regulatory clarity on retail trading frameworks emerges.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Carbon credit retail platforms first achieved commercial scale in European banking integrations, with German fintech partnerships establishing the template for embedded offset purchasing that later spread to travel and utility sectors worldwide.
Germany
Neobank partnerships drive platform penetration through transaction round-up features and automated monthly offset commitments. The EU Green Deal's expanding carbon border adjustment mechanism tightens compliance expectations for consumer-facing products. Berlin and Frankfurt clusters host concentrated API development for banking-embedded carbon retirement workflows.
United States
Airline checkout flow integrations activate voluntary offset demand at transaction moments across major carriers. The Inflation Reduction Act's climate disclosure provisions elevate consumer awareness of emission accountability. California's sustainability-focused consumer base anchors West Coast platform adoption through travel and lifestyle application partnerships.
United Kingdom
Travel booking platforms embed offset options into flight and hotel purchase workflows, compressing friction from intent to retirement. GDPR and emerging algorithmic transparency requirements shape automated footprint calculator development. London's fintech corridor concentrates platform engineering talent for hybrid retail-institutional infrastructure.
France
Corporate sustainability teams favor web-based platforms with multi-user license management for scope 3 offset procurement. The EU AI Act imposes explainability requirements on personalized recommendation engines that estimate individual carbon footprints. Paris hosts advisory-service bundling with ESG reporting for mid-market enterprise clients.
Singapore
Climate Impact X anchors regional liquidity for nature-based carbon credits with blockchain-verified provenance tracking. The Monetary Authority of Singapore's green finance taxonomy shapes credit eligibility standards for retail-accessible products. The city-state's commodity trading heritage supports secondary marketplace infrastructure for verified offset price discovery.
Carbon Credit Retail Consumer Platform Market Competitive Landscape
The competitive structure tilts toward registry-gatekeeper dominance with platform intermediaries competing for liquidity access. Verra and Gold Standard certification protocols determine credit eligibility for corporate net-zero claims and consumer product integrations. Three archetypes populate the field: commodity exchange infrastructure providers, project origination specialists with captive supply, and API-native retail platforms with embedded finance partnerships. Strategic moves concentrate on direct registry API connections and subscription plan migration from transactional offset purchases.
Within the exchange infrastructure tier, Xpansiv occupies a position bridging institutional and retail liquidity pools through its commodity marketplace architecture. South Pole exemplifies the project origination archetype with forestry and renewable energy portfolio capabilities. Gold Standard represents certification-rigor differentiation that commands premium positioning among environmentally conscious consumer segments. These three entities anchor distinct competitive vectors that shape how retail buyers access verified emission reductions.
| Leading Market Players |
|---|
| Xpansiv |
| Carbon Trade Exchange |
| AirCarbon Exchange |
| Climate Impact X |
| Carbonplace |
| Verra |
| Gold Standard |
| South Pole |
| ClimeCo |
| Others |
Pricing and Supply Chain Analysis
API-native registry connections anchor both supply position and pricing power for retail carbon platforms, with direct Verra and Gold Standard integrations compressing intermediary margins while enabling premium capture for verified provenance. This infrastructure choice concentrates procurement leverage among platforms with automated retirement registries, leaving widget-dependent intermediaries exposed to cost pressure from embedded finance competitors.
Pricing Analysis
Bundled subscription plans command premium positioning against unbundled transactional purchases, with monthly recurring commitments generating predictable revenue streams that one-time voluntary offsets cannot match. Price differentiation hinges on certification rigor—Gold Standard credits fetch premiums over Verra-registered alternatives—and embedded finance integration depth, where banking app partnerships reduce customer acquisition costs. Pricing pressure stems from API commoditization as neobanks and travel platforms internalize offset functionality, compressing standalone platform margins. Individual consumers exhibit highest price sensitivity, while small businesses under EU Green Deal compliance pressure accept premium tiers for audit-ready documentation.
Supply Chain Analysis
Verified emission reduction supply rests on forestry and renewable energy project origination concentrated in Brazil, Indonesia, and Kenya, with lengthy validation timelines constraining inventory refresh cycles. Platform operators draw from Verra and Gold Standard registries as primary credit sources, supplemented by direct South Pole origination agreements for captive supply. Single-registry dependency creates structural vulnerability should certification protocols diverge under emerging national carbon accounting standards. Distribution runs through embedded API integrations with German neobanks, UK travel booking platforms, and French corporate sustainability dashboards, compressing traditional marketplace intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where Gold Standard certification rigor and direct registry API access separate viable platforms from margin-compressed intermediaries, with demand shifting decisively toward subscription-based recurring commitments that embed climate action into everyday financial workflows.
For Market Incumbents: Hedge registry concentration risk by diversifying certification partnerships beyond Verra and Gold Standard as emerging national carbon accounting standards threaten inventory fungibility. Deepen captive project origination through South Pole-style vertical integration into forestry portfolios, securing supply priority ahead of validation bottlenecks that delay credit issuance to competitors. For New Entrants and Emerging Players: Embedded finance API routes offer the most penetrable entry vector, with German banking app integrations demonstrating template scalability across Northern European markets. Target peer-to-peer trading infrastructure for localized supply-demand matching, where regulatory clarity on retail trading frameworks remains immature and intermediary fee compression holds concentrated margin potential. Launch with carbon footprint tracking bundled into subscription plans, capturing sustained engagement rather than episodic climate guilt transactions. For Investors and Strategic Acquirers: Roll-up economics work for API-native platforms with direct registry connections because embedded finance partnerships create customer acquisition moats that widget-dependent competitors cannot replicate. Platform consolidation around hybrid retail-institutional infrastructure offers viable five-to-ten-year positioning as compliance pressure expands beyond large corporates to small businesses. Watch for EU AI Act enforcement timelines as the inflection indicator—algorithmic transparency requirements for automated footprint calculators will concentrate development resources and accelerate attrition among undercapitalized entrants.| Strategic Initiative | Industry Significance |
|---|---|
| Direct Registry API Integration | Eliminates intermediary latency for Verra and Gold Standard credit retirement, compressing transaction friction to single-click experiences. |
| Subscription Plan Migration | Replaces episodic voluntary purchases with recurring offset commitments, improving customer lifetime value metrics for German neobank partners. |
| Project Origination Backward Integration | Captive supply from forestry and renewable energy portfolios insulates platforms from Gold Standard validation timeline compression. |
| Embedded Finance Partnership Expansion | Banking app and travel booking integrations activate demand at transaction moments, reducing customer acquisition costs versus standalone marketplaces. |
| Blockchain Provenance Modularization | Distributed ledger retirement registries satisfy EU AI Act audit requirements while enabling transparent offset workflows for institutional buyers. |
Research Methodology
Multiple input streams—primary interviews with platform engineering leads, carbon project developers, and banking partnership directors; secondary validation through Gold Standard registry disclosures, EU regulatory filings, and embedded finance API documentation; plus customs data on carbon credit trade flows—were reconciled through bottom-up and top-down triangulation. Stakeholder consultations spanned CTOs at API-native retail platforms, sustainability officers at German neobanks, Verra certification auditors, and South Pole origination specialists to capture supply-side constraints and demand-side integration economics.
Data-stream reconciliation anchored the analytical framework across platform type, service offering architecture, end-user segmentation, and purchase method dimensions, with growth trajectories derived from subscription plan adoption curves and embedded finance penetration rates. Modeled inputs included EU Green Deal compliance threshold expansion, airline checkout flow integration velocity, and blockchain provenance modularization timelines, with CAGRs calibrated against banking app deployment rates and travel platform partnership announcements.
The model assumes a particular technology adoption path for blockchain-based retirement registries; alternative pathways for distributed ledger interoperability would alter the outlook for platform inventory fungibility. Forecasts reflect assumptions around certification protocol convergence, GDPR algorithmic transparency enforcement pacing, and neobank offset feature standardization. A small set of triggers—national carbon accounting standard fragmentation, EU AI Act explainability requirement tightening, and peer-to-peer trading regulatory clarity—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environment & Sustainability
Agricultural Wastewater Treatment Market
Environment & Sustainability
PET Bottle Recycling Market
Environment & Sustainability
Eco Flooring Market
Environment & Sustainability
Marine Waste Handling Equipment Market
Environment & Sustainability
Tertiary Water and Wastewater Treatment Equipment Market
Environment & Sustainability
Russia Cloud Seeding Market
Environment & Sustainability
Anti-Pollution Toner Market
Environment & Sustainability
North America Green Cement Market
Environment & Sustainability
UAE Biomedical Waste Management Market
Environment & Sustainability
Water Aeration System Market
Environment & Sustainability
Point of Use Water Treatment Systems Market
Environment & Sustainability
Home Water Filtration Unit Market
Environment & Sustainability
Green Silica Market
Environment & Sustainability
Construction Waste Management Market
Environment & Sustainability
Storm Water Cleaning Services Market
Environment & Sustainability
Incinerator Market