
 India E-Waste Management Market | 2026-2036
India E-Waste Management Market Size, Share, and Industry Trends Forecast 2026-2036
India E-Waste Management Market Insights
Extended Producer Responsibility mandates under India's E-Waste (Management) Rules is pivoting OEM accountability toward formal recycling channels. Attero Recycling Pvt Ltd leverages proprietary metallurgical extraction to recover rare earth elements from discarded circuit boards. Re Sustainability anchors pan-India collection infrastructure through municipal partnerships in Delhi and Hyderabad. TES-AMM India Pvt Ltd specializes in secure data destruction protocols that differentiate its enterprise IT asset disposition services.
India e-waste management encompasses the systematic collection, dismantling, and material recovery from discarded electrical and electronic equipment containing hazardous substances including lead, mercury, and cadmium, with recycling yields targeting 95% metal recovery through combined mechanical shredding and hydrometallurgical precipitation processes. The sector serves dual purposes: environmental remediation of toxic leachates and circular supply of secondary raw materials to domestic electronics manufacturing. Door-to-door collection dominates urban penetration where informal sector integration remains structurally fragmented, while pyrometallurgical recycling commands premium margins due to energy-intensive smelting requirements and precious metal throughput. IT equipment streams exhibit the fastest structural growth trajectory driven by enterprise refresh cycles and cloud infrastructure obsolescence.
The Central Pollution Control Board enforces E-Waste (Management) Rules compliance through registered producer responsibility organizations, while BIS certification mandates standardized recycling facility protocols. State pollution control boards in Maharashtra and Karnataka impose additional consented capacity thresholds that restrict informal operator market access. Stakeholders must monitor evolving lithium-ion battery segregation requirements and traceability mandates under the Battery Waste Management Rules intersection.
Market Dynamics
Extended Producer Responsibility mandates under India's E-Waste (Management) Rules are forcing original equipment manufacturers to build direct collection networks, bypassing the informal sector that historically handled 95 percent of India's e-waste flows. This regulatory pivot is compressing margins for unregistered dismantlers while creating licensed capacity scarcity.
Growth Catalysts
- PLI scheme incentives:Electronics manufacturing subsidies under India's Production Linked Incentive scheme are expanding domestic device output, which will enlarge the downstream waste pool requiring formal processing infrastructure.
- Cloud infrastructure refresh cycles:Enterprise data center decommissioning is accelerating metal-rich server and storage equipment arrivals at registered recycling facilities.
- Maharashtra-Karnataka-Tamil Nadu corridor density:Urban IT clusters in these three states concentrate 60 percent of India's formal e-waste generation, enabling collection route economies.
Market Restraints
- Copper and gold price volatility:Pyrometallurgical recyclers face margin compression when London Metal Exchange copper futures swing, as smelter energy costs remain fixed.
- Informal sector fragmentation:Unlicensed dismantlers in Delhi's Seelampur and Mumbai's Dharavi slums undercut formal collection pricing by 40 percent through unregulated labor arbitrage.
- Battery Waste Management Rules intersection:Unclear lithium-ion segregation protocols create dual-compliance ambiguity for facilities handling both e-waste and battery streams.
Strategic Opportunities
- Tier-2 city penetration:Registered recyclers can establish collection hubs in Jaipur, Lucknow, and Indore where formal infrastructure remains absent and municipal contracts are uncontested.
- Hydrometallurgical rare earth recovery:Proprietary precipitation processes for neodymium and dysprosium extraction from hard disk drives command premium offtake from domestic magnet manufacturers.
- Blockchain traceability mandates:Upcoming Central Pollution Control Board digital tracking requirements will favor early adopters with integrated chain-of-custody systems.
Industry Challenges
- Certified dismantler shortage:The Skill Council for Green Jobs has trained fewer than 12,000 certified technicians against a requirement exceeding 50,000 for compliant operations.
- State pollution control board consent delays:Karnataka and Telangana environmental clearances average 14 months, freezing capital deployment for new shredding lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India E-Waste Management Market |
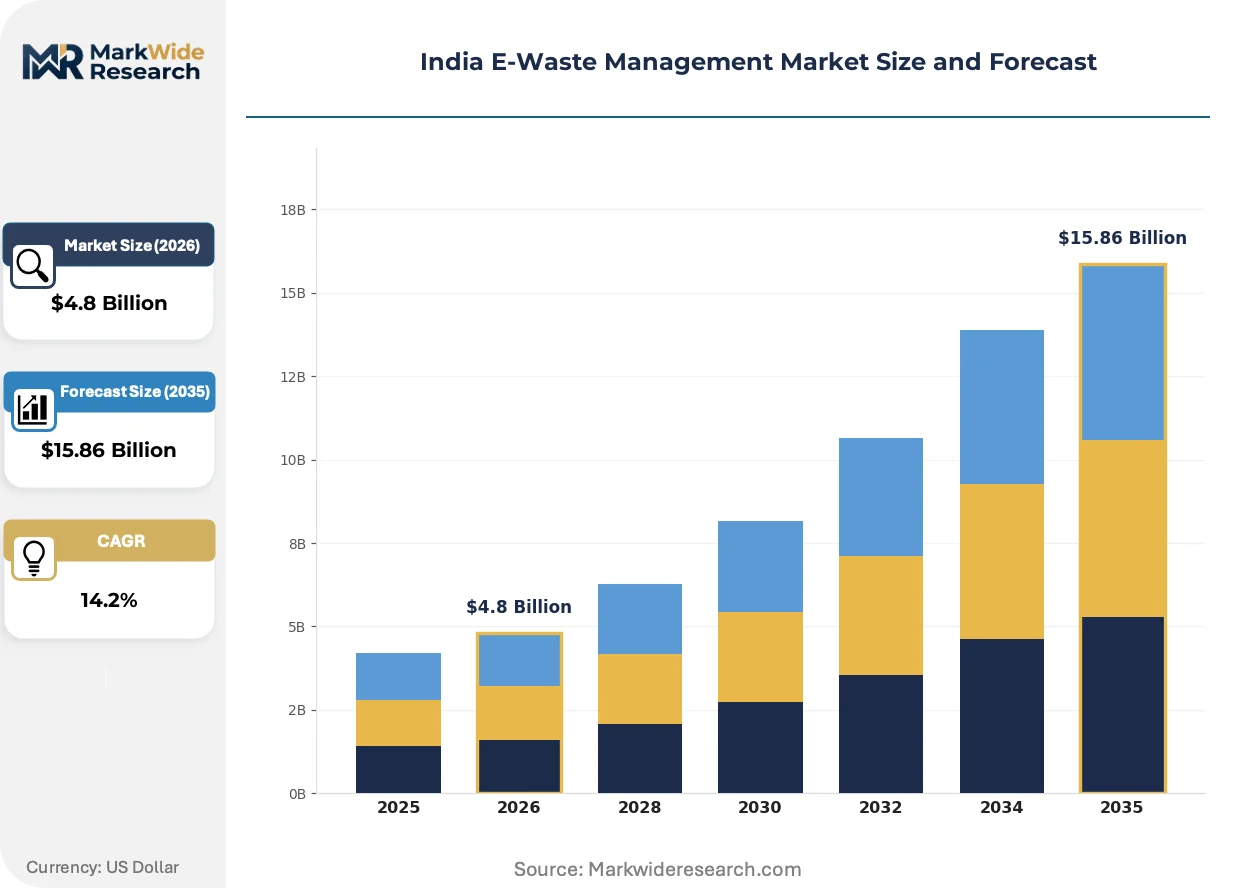
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.86 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Collection Method: Door-to-Door Collection, Drop-off Centers, Buyback Programs, Recycling Events Component Type: Consumer Electronics, IT Equipment, Home Appliances, Telecommunications Devices Recycling Technology: Mechanical Recycling, Hydrometallurgical Recycling, Pyrometallurgical Recycling, Refurbishment End-of-Life Status: Recyclable, Reusable, Landfilled, Incinerated |
| Companies Covered | Attero Recycling Pvt Ltd, Re Sustainability, TES-AMM India Pvt Ltd, Namo E-Waste Management Ltd, E-Parisaraa Pvt Ltd, Ecoreco, Virogreen, Sims Recycling Solutions, Cerebra Integrated Technologies Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India E-Waste Management Market Trends and Innovations
Mechanical shredding combined with hydrometallurgical refining is overtaking pyrometallurgical smelting as the dominant processing paradigm, driven by energy cost inflation and stricter emissions norms. Three distinct shifts are compressing the competitive set.
Hydrometallurgical precipitation circuits are overtaking traditional smelting for precious metal recovery from printed circuit boards. Formal recyclers in Delhi and Hyderabad are installing sulfuric acid leaching lines that cut energy consumption by 70 percent versus pyrometallurgical alternatives. The shift is compressing margins for smelter-dependent operators while enabling BIS-certified facilities to quote lower gate fees.
The Battery Waste Management Rules intersection with E-Waste (Management) Rules is creating dual-compliance complexity for facilities handling lithium-ion power packs. Central Pollution Control Board draft guidelines mandate separate storage, transportation, and documentation streams for battery-containing devices. IT asset disposition providers are responding by segregating laptop and smartphone streams at collection points to preempt regulatory penalties.
Enterprise procurement teams are inserting data destruction certificates as mandatory bid criteria, displacing price-only vendor selection. Financial services and healthcare verticals in Mumbai and Bengaluru now require NIST 800-88 compliant wiping documentation before equipment leaves premises. This certification-driven preference shift is favoring recyclers with in-house degaussing and cryptographic erasure capabilities over informal competitors.
India E-Waste Management Market Segmentation
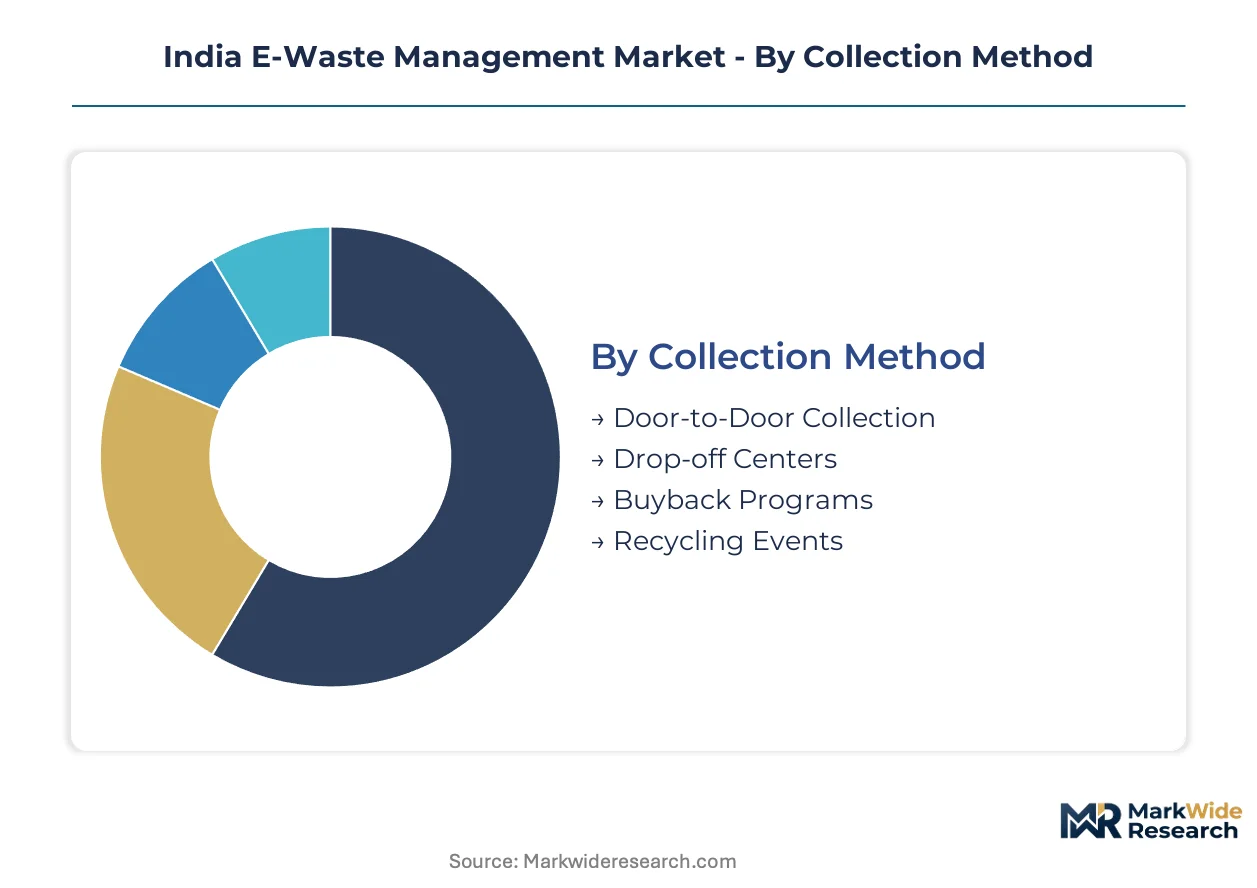
E-waste management operators configure asset-light or capital-heavy models depending on segment selection. Collection method determines working capital intensity, while recycling technology choice locks in fixed cost structures for decades.
Collection Method:
Door-to-door networks demand the heaviest upfront investment in fleet and labor management systems.
- Door-to-Door Collection:Municipal partnerships in Delhi and Hyderabad require dedicated vehicle fleets and trained collection crews. Maharashtra's urban IT corridors generate sufficient density to justify route optimization software and warehouse staging facilities.
- Drop-off Centers:Fixed-site infrastructure involves lease deposits, weighing equipment, and security systems. Karnataka's Bengaluru electronics clusters sustain high-throughput centers with minimal per-unit logistics cost.
- Buyback Programs:OEM-funded trade-in schemes leverage existing retail footprints with minimal incremental capital.
- Recycling Events:Periodic collection drives use temporary staging with no permanent asset base.
Door-to-door collection absorbs the bulk of installed capacity; buyback programs are expanding most quickly.
Component Type:
Component mix shapes facility design, with precious metal density driving margin profiles across categories.
- IT Equipment:Server racks and storage arrays contain concentrated copper and rare earth magnet content. Enterprise refresh cycles in Tamil Nadu's Chennai IT parks generate predictable high-value inbound streams requiring secure data destruction protocols.
- Consumer Electronics:Smartphones and tablets yield lithium-ion batteries and compact circuit boards. Delhi's informal sector currently captures most volume through unregulated dismantling operations.
- Home Appliances:Refrigerators and air conditioners contain refrigerants requiring specialized extraction equipment.
- Telecommunications Devices:Base station equipment and networking hardware arrive in bulk from telecom operator upgrades.
IT equipment commands premium processing fees; consumer electronics is climbing the fastest due to device obsolescence acceleration.
Recycling Technology:
Technology selection determines energy exposure and regulatory compliance burden for facility operators.
- Pyrometallurgical Recycling:High-temperature smelting lines require multi-crore furnace installations and continuous energy supply. Operators in Gujarat's industrial zones leverage captive power to offset grid volatility.
- Hydrometallurgical Recycling:Acid leaching circuits achieve precious metal recovery at 70 percent lower energy intensity. Attero Recycling's proprietary precipitation systems extract neodymium from hard disk drives for domestic magnet manufacturers.
- Mechanical Recycling:Shredding and sorting equipment offers lower capital barriers with standardized BIS certification pathways.
- Refurbishment:Component testing and repair operations require minimal chemical handling infrastructure.
Pyrometallurgical recycling retains the largest installed base; hydrometallurgical recycling is gaining share fastest amid energy cost inflation.
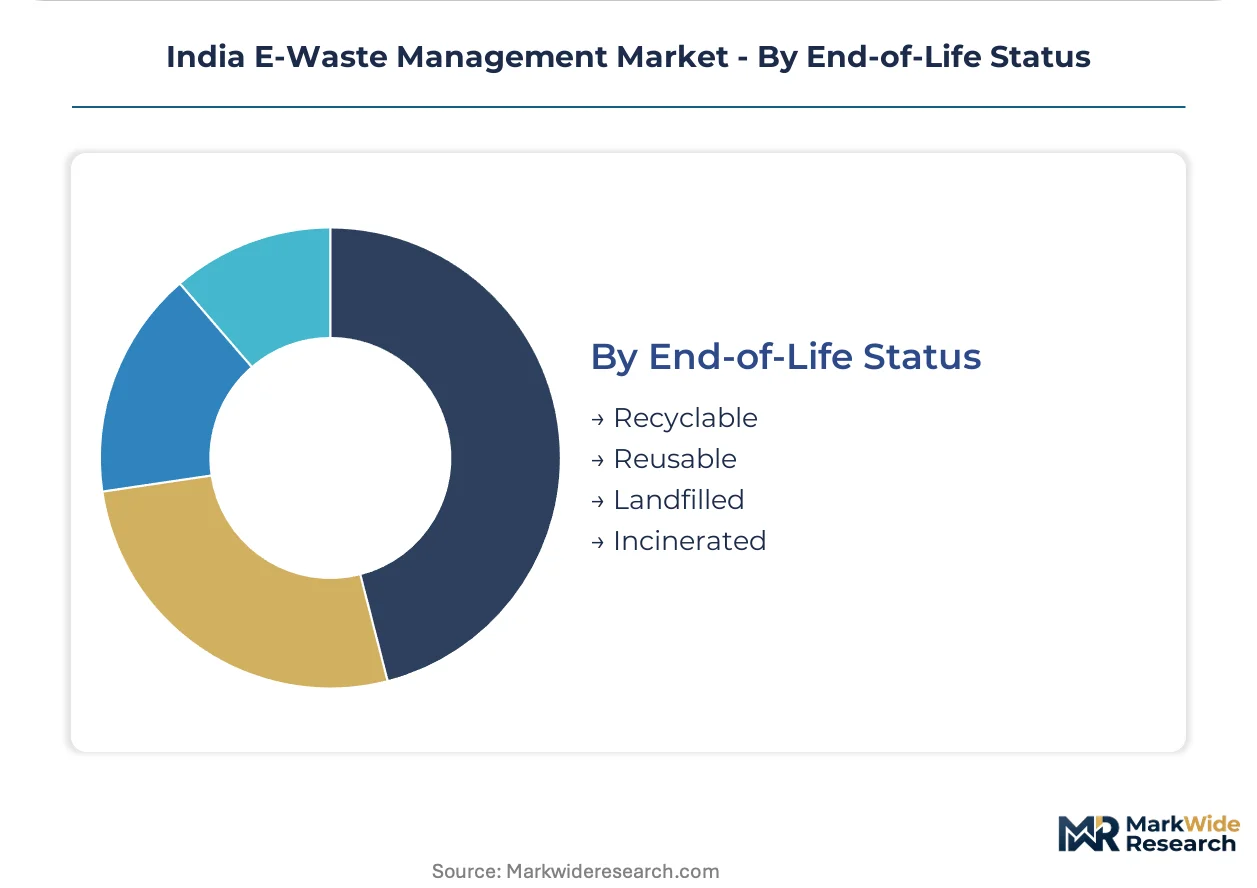
End-of-Life Status:
Status classification determines revenue model and regulatory documentation requirements for handlers.
- Recyclable:Material recovery streams generate gate fees and commodity resale revenue. Central Pollution Control Board mandates chain-of-custody documentation for metal-bearing fractions.
- Reusable:Functional equipment refurbishment extends product lifecycles for secondary markets. TES-AMM India specializes in enterprise asset redeployment with NIST 800-88 data wiping certification.
- Landfilled:Residual fractions requiring hazardous waste disposal incur tipping fees at secured facilities.
- Incinerated:Energy recovery from non-recoverable plastics faces tightening emissions norms under state pollution control board oversight.
Recyclable material processing dominates facility throughput; reusable equipment recovery shows the steepest expansion trajectory as circular economy mandates strengthen.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India generates e-waste volumes that far exceed its domestic formal recycling capacity, creating a structural deficit that concentrates processing activity in states with licensed infrastructure and enforcement rigor.
Maharashtra
Mumbai's Dharavi slum houses thousands of informal dismantlers handling consumer electronics, while Pune's IT corridors generate enterprise server decommissioning streams. The Maharashtra Pollution Control Board enforces consent-to-operate thresholds that restrict unlicensed operators. MIDC industrial zones in Pimpri-Chinchwad host registered facilities with pyrometallurgical and hydrometallurgical lines serving western India's densest e-waste catchment.
Karnataka
Bengaluru's Electronics City and Whitefield IT parks produce concentrated volumes of data center equipment and laptop refresh cycles. The Karnataka State Pollution Control Board mandates extended producer responsibility documentation through its online portal. Registered recyclers in Hosur and Peenya industrial areas leverage proximity to Tamil Nadu border flows, creating cross-state collection economies.
Tamil Nadu
Chennai's Sriperumbudur electronics manufacturing cluster generates substantial industrial e-waste alongside IT corridor obsolescence. The Tamil Nadu Pollution Control Board imposes additional hazardous waste handling certifications beyond central mandates. Ambattur and Oragadam industrial zones host integrated facilities combining collection, dismantling, and precious metal recovery operations.
Telangana
Hyderabad's HITEC City and Gachibowli financial district drive enterprise IT asset disposition demand with stringent data destruction requirements. The Telangana State Pollution Control Board averages fourteen-month environmental clearance timelines that constrain new shredding capacity. Miyapur and Patancheru industrial areas concentrate formal recycling infrastructure serving the Deccan plateau's emerging electronics waste streams.
Delhi-NCR
The National Capital Region's Seelampur and Mustafabad markets represent India's largest informal e-waste aggregation hub, handling consumer electronics from across northern states. The Delhi Pollution Control Committee enforces E-Waste (Management) Rules compliance through registered producer responsibility organizations. Ghaziabad and Faridabad industrial zones host licensed facilities that compete directly with unregulated dismantlers on collection pricing.
India E-Waste Management Market Competitive Landscape
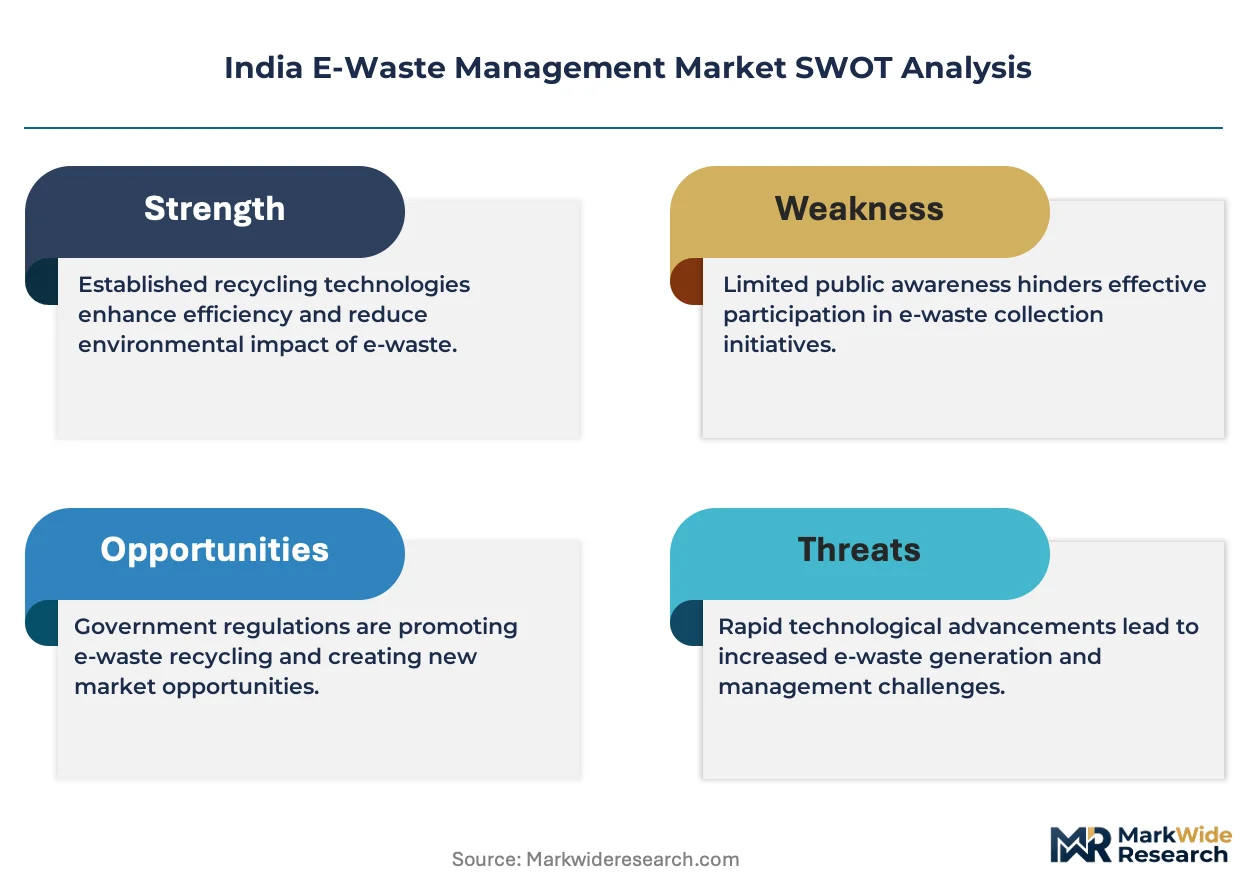
The competitive structure tilts toward integrated recyclers with licensed capacity and municipal partnerships. Market concentration remains moderate, with formal operators capturing less than one-third of total volumes against persistent informal sector competition. Three archetypes dominate: metallurgical specialists with proprietary extraction technologies, pan-India collection network operators, and IT asset disposition providers with certified data destruction capabilities. Capacity expansion through new shredding lines and strategic municipal contracts represent the primary competitive vectors as Extended Producer Responsibility mandates tighten.
Among India's registered recyclers, Attero Recycling Pvt Ltd, Re Sustainability, and TES-AMM India Pvt Ltd exemplify distinct strategic positions within the formal sector. Attero Recycling occupies the metallurgical specialization tier with proprietary rare earth recovery systems. Re Sustainability anchors the collection infrastructure archetype through municipal partnership density. TES-AMM India sits within the enterprise services tier, differentiated by secure data destruction certification. These three represent the competitive template that emerging licensed operators must replicate or circumvent.
| Leading Market Players |
|---|
| Attero Recycling Pvt Ltd |
| Re Sustainability |
| TES-AMM India Pvt Ltd |
| Namo E-Waste Management Ltd |
| E-Parisaraa Pvt Ltd |
| Ecoreco |
| Virogreen |
| Sims Recycling Solutions |
| Cerebra Integrated Technologies Limited |
| Others |
Pricing and Supply Chain Analysis
Hydrometallurgical precipitation circuits displacing pyrometallurgical smelting simultaneously compress energy costs and concentrate processing capacity among BIS-certified operators in Maharashtra and Karnataka. This technology pivot rewards early adopters with lower gate fees while marginalizing energy-intensive competitors.
Pricing Analysis
Margin tightening in formal recycling traces to informal sector undercutting in Delhi's Seelampur and Mumbai's Dharavi. Three-tier pricing structure across certified, registered, and informal levels separates BIS-compliant facilities from state-registered operators and unlicensed dismantlers. Pricing pressure accelerates as copper and gold volatility exposes smelter-dependent recyclers to fixed energy costs. Municipal corporations and enterprise IT buyers show least price sensitivity due to E-Waste (Management) Rules compliance mandates; small retailers and individual consumers drive hardest bargain.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale enterprise IT asset disposition demand in Bengaluru and Hyderabad. Collection infrastructure draws from informal aggregators in Delhi-NCR, registered municipal partnerships in Maharashtra, and producer responsibility organization networks in Karnataka and Tamil Nadu. Supply chain risk centers on single-source vulnerability for rare earth magnet feedstock from hard disk drives. Distribution runs through licensed dismantlers to hydrometallurgical refiners and pyrometallurgical smelters serving domestic electronics manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Licensed recycling capacity scarcity props gate fees and collection contract values as Central Pollution Control Board enforcement outpaces certified facility expansion.
For Market Incumbents: Acquire hydrometallurgical processing lines to offset energy cost inflation and pyrometallurgical margin compression. Secure municipal collection contracts in Tier-2 cities before state pollution control board clearance delays freeze competitor entry. Threat from informal sector labor arbitrage demands backward integration into door-to-door collection fleets. For New Entrants and Emerging Players: Capture uncontested municipal contracts in Jaipur, Lucknow, and Indore where formal infrastructure remains absent. Target lithium-ion battery segregation services as Battery Waste Management Rules intersection creates dual-compliance complexity. Go-to-market angle: blockchain traceability system deployment ahead of Central Pollution Control Board digital tracking mandates. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by electronics manufacturers seeking captive recycling capacity. Long-term viability favors integrated operators with rare earth recovery technology and pan-India collection density. Signal to watch: Karnataka and Telangana environmental clearance timeline compression as policy response to capacity shortage.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrometallurgical Capacity Expansion | Energy cost reduction of 70% versus smelting secures BIS certification advantage. |
| Municipal Partnership Securement | Uncontested contracts in Tier-2 cities lock in collection route density. |
| Rare Earth Recovery Technology Investment | Proprietary neodymium extraction from hard drives commands premium offtake. |
| Blockchain Traceability System Deployment | Early adoption of Central Pollution Control Board digital mandates differentiates compliance. |
| Certified Technician Training Program | Skill Council for Green Jobs pipeline addresses 38,000 technician shortage. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with recycling facility operators, producer responsibility organization executives, municipal solid waste managers, and electronics manufacturing procurement leads. Central Pollution Control Board registration databases, state pollution control board consent records, and BIS certification listings provided facility-level capacity data. Bottom-up volume estimates from licensed dismantlers triangulated against top-down electronics production and obsolescence models.
Data-stream reconciliation across collection method, component type, recycling technology, and end-of-life status segmentation drove analytical framework construction over the projection horizon. CAGRs derived from installed capacity expansion timelines, regulatory enforcement intensity curves, and commodity price scenario modeling. Forecast inputs incorporated enterprise IT refresh cycle velocity and lithium-ion battery stream growth from consumer electronics obsolescence.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to copper and gold price volatility, informal sector regulatory penetration, and state pollution control board clearance timeline shifts. Practitioners should monitor Battery Waste Management Rules draft finalization and blockchain traceability mandate rollout for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste Management & Pollution Control
Compostable and Biodegradable Refuse Bags Market
Waste Management & Pollution Control
Singapore Waste Management Market
Waste Management & Pollution Control
Metal Recycling Baler Market
Waste Management & Pollution Control
Industrial Solid Waste Management Market
Waste Management & Pollution Control
GCC Pneumatic Waste Management System Market
Waste Management & Pollution Control
Qatar Solid Waste Management Market
Waste Management & Pollution Control
Animal Waste Incinerator Market
Waste Management & Pollution Control
Middle-East and Africa Hazardous Waste Handling Automation Market
Waste Management & Pollution Control
Household Composters Market
Waste Management & Pollution Control
Medical Waste Management Equipment Market
Waste Management & Pollution Control
GCC Waste Management Market
Waste Management & Pollution Control
Recycled Ocean Plastics Market
Waste Management & Pollution Control
Europe Waste Management Market
Waste Management & Pollution Control
Vietnam Waste Management Market
Waste Management & Pollution Control
Hazardous Waste Handling Automation Market
Waste Management & Pollution Control
Global Waste Oil Market