
 Europe Medical Waste Management Market | 2026-2036
Europe Medical Waste Management Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Medical Waste Management Market Insights
Subscription-based compliance monitoring is recalibrating how European healthcare facilities procure waste management services. Veolia Environnement S.A. leverages its integrated environmental service platform to bundle collection, treatment, and regulatory reporting across multiple countries. SUEZ Group anchors its position through specialized hazardous waste infrastructure that handles complex pharmaceutical residues. REMONDIS SE & Co. KG competes via dense logistics networks that enable high-frequency collection schedules for urban hospital clusters.
Medical waste management encompasses the controlled handling, treatment, and disposal of waste materials generated by healthcare facilities, with infectious waste requiring steam sterilization at minimum 121 degrees Celsius or thermal destruction exceeding 850 degrees Celsius to neutralize pathogens. The primary purpose is preventing disease transmission, environmental contamination, and occupational exposure while ensuring regulatory traceability. Infectious waste commands the largest share of hazardous handling volumes due to persistent generation from surgical and diagnostic procedures. Autoclaving leads technology deployment because of lower emissions profiles and operational flexibility compared to legacy incineration. Collection and transportation services represent mature margin pools where route density and fleet specialization determine profitability.
The EU Waste Framework Directive, REACH, and national regulators such as Germany's Federal Environment Agency shape treatment technology choices and cross-border waste movement protocols across Europe. EMA guidelines on pharmaceutical waste classification directly influence segregation requirements at hospital pharmacies and manufacturing sites. Stakeholders must monitor evolving national transpositions of the EU Green Deal's waste hierarchy mandates and assess treatment technology swaps before regulatory deadlines tighten disposal standards.
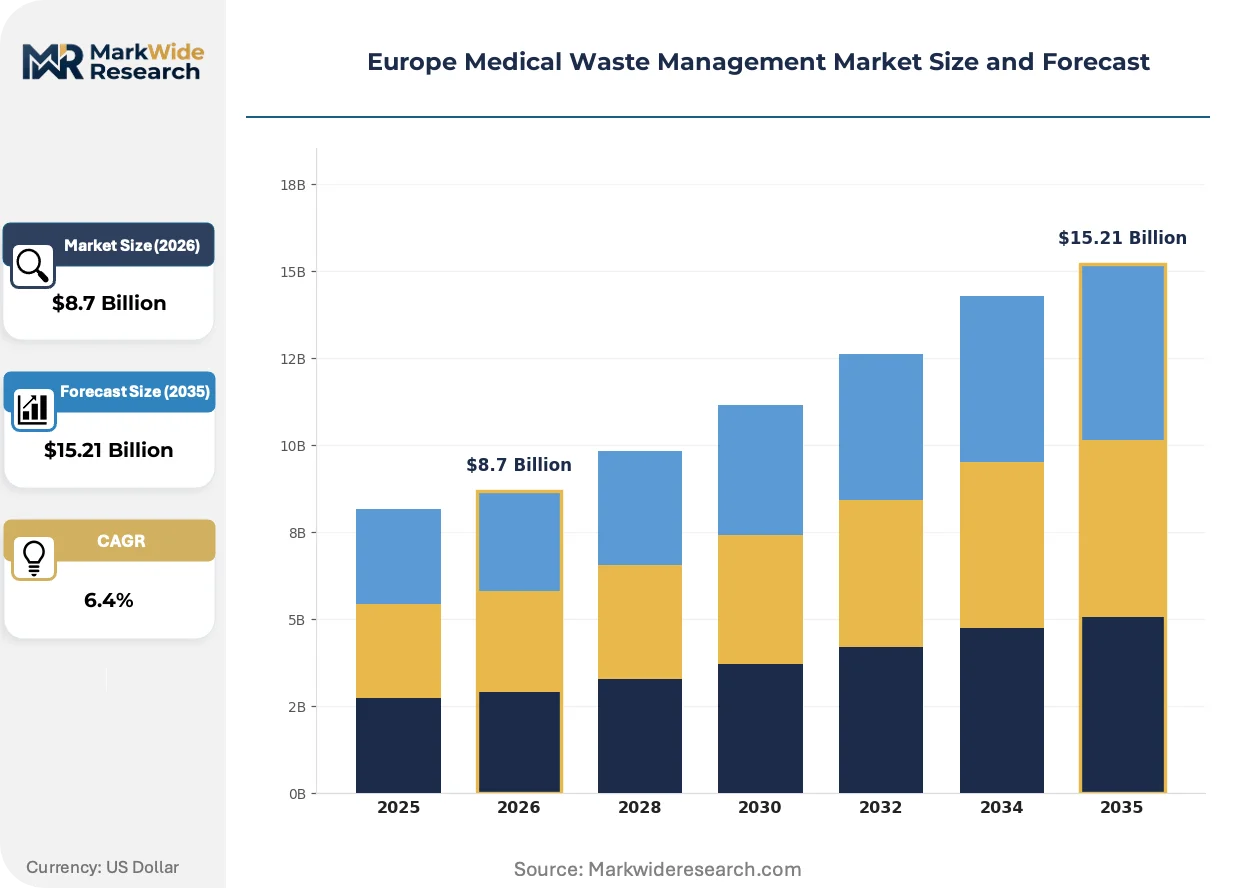
Market Dynamics
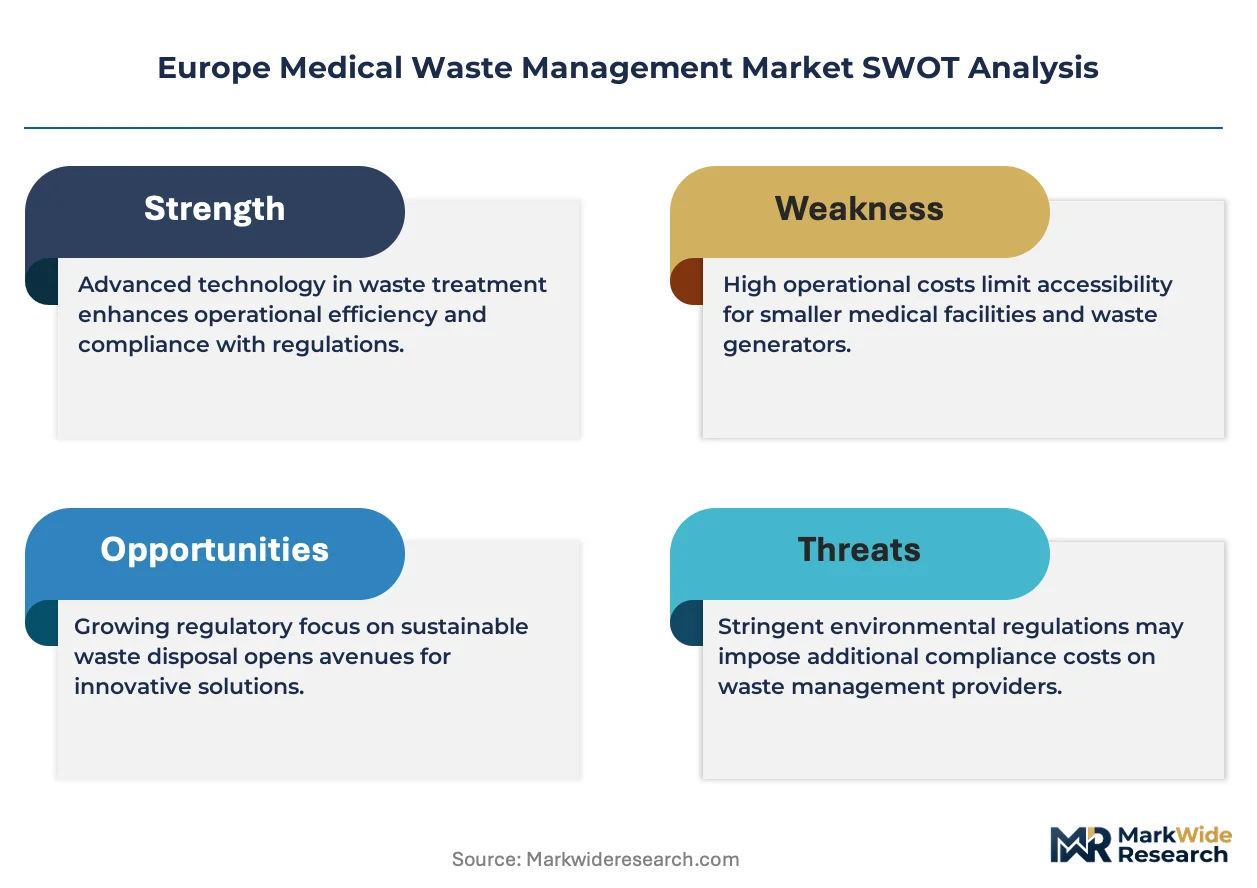
The EU Waste Framework Directive's tightening disposal standards are forcing healthcare facilities across Germany, France, and the United Kingdom to abandon basic incineration in favor of advanced steam sterilization and thermal destruction systems. This regulatory compression is reshaping procurement patterns and vendor selection criteria throughout the region.
Growth Catalysts
- EU Green Deal waste hierarchy mandates:National transpositions are compelling hospital networks to upgrade treatment infrastructure ahead of compliance deadlines, generating sustained equipment and service demand.
- Dense urban hospital clusters:Metropolitan concentration in Paris, Berlin, and London creates route-density economics that enable high-frequency collection schedules and contracted service expansion.
- Steam sterilization technology:Autoclaving's lower emissions profile and operational flexibility are displacing legacy incineration as the preferred pathogen-neutralization method for infectious waste streams.
Market Restraints
- Specialized fleet capital intensity:Refrigerated transport vehicles and leak-proof containment systems require substantial upfront investment, limiting new entrant participation.
- Cross-border waste movement protocols:REACH and national transposition complexities create regulatory friction for service providers seeking to optimize treatment capacity across European jurisdictions.
- Complex pharmaceutical residue handling:Hazardous waste infrastructure scarcity concentrates treatment capacity with specialized operators, creating supply bottleneck risks.
Strategic Opportunities
- Eastern European hospital modernization:Poland, Romania, and Bulgaria present underpenetrated demand as EU structural funds accelerate healthcare infrastructure investment.
- Subscription-based compliance monitoring:Bundled collection, treatment, and regulatory reporting services are displacing transactional procurement models among multi-site hospital networks.
- EMA pharmaceutical waste classification convergence:Harmonized segregation requirements are creating standardization tailwinds for integrated service platforms spanning manufacturing and pharmacy operations.
Industry Challenges
- Certified technician scarcity:ADR-licensed drivers and hazardous waste operators require specialized training that outpaces workforce pipeline development.
- Legacy incineration asset stranding:Hospitals face write-down pressure on existing thermal destruction equipment as emissions standards tighten.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Medical Waste Management Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Waste Type: Hazardous Waste, Non-Hazardous Waste, Infectious Waste, Pharmaceutical Waste Service Type: Collection, Transportation, Treatment, Disposal End User: Hospitals, Clinics, Laboratories, Dental Practices Technology: Autoclaving, Incineration, Chemical Treatment, Microbial Treatment |
| Companies Covered | Veolia Environnement S.A., SUEZ Group, Stericycle Inc., REMONDIS SE & Co. KG, Daniels Health, Sharpsmart Europe, PHS Group Limited, Rentokil Initial plc, SRCL Limited, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Medical Waste Management Market Trends and Innovations
Advanced treatment technologies and digital traceability systems are compressing operational margins for basic service providers while rewarding integrated platforms with regulatory reporting capabilities. These shifts favor vendors capable of spanning collection, treatment, and compliance documentation.
Microwave disinfection technology is expanding into mid-scale hospital applications across Germany and the Netherlands. Regional healthcare procurement consortia are piloting these systems for surgical waste streams that fall below centralized autoclave batch thresholds. The technology's modular footprint and rapid cycle times are compressing capital deployment timelines for facilities with space constraints.
REACH Annex XVII restrictions on persistent organic pollutants are forcing incineration operators to install advanced flue gas treatment systems. Germany's Federal Environment Agency enforcement intensity has accelerated retrofit deadlines, concentrating upgrade demand among Rhine-Ruhr industrial corridor facilities. Pharmaceutical manufacturing sites in Basel and Frankfurt are responding by diverting high-residue waste streams toward specialized chemical-physical treatment infrastructure.
Consolidated purchasing by hospital networks is compressing vendor margins and extending contract durations. French regional health agencies are bundling waste management into broader facility services tenders, displacing standalone procurement. This concentration is most visible in the Île-de-France and Auvergne-Rhône-Alpes regions, where multi-year framework agreements now lock in pricing and service-level specifications.
Europe Medical Waste Management Market Segmentation
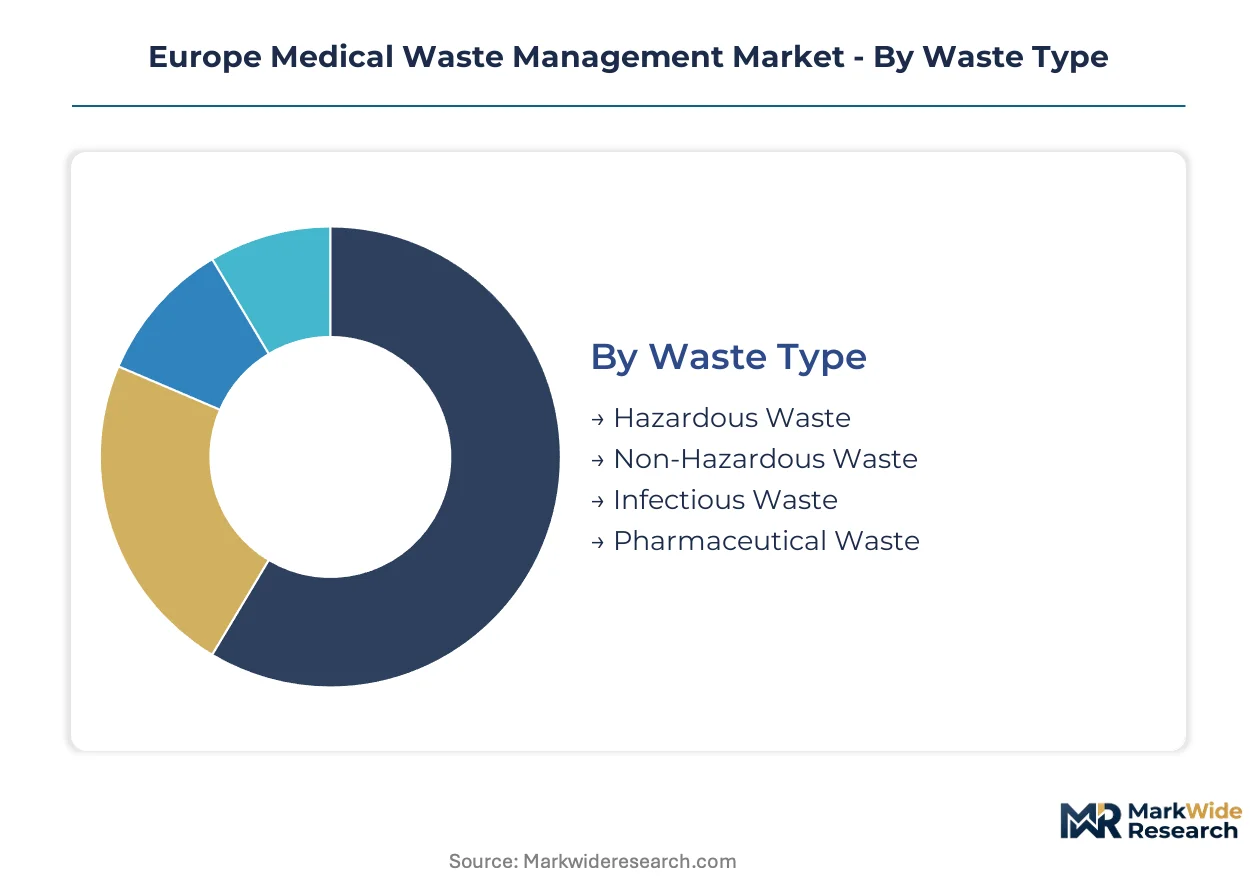
Segmentation in European medical waste management reveals how regulatory stringency and treatment complexity fragment procurement patterns across healthcare facilities. Each dimension—waste classification, service modality, end-user scale, and neutralization technology—creates distinct margin profiles and vendor specialization requirements.
Waste Type:
Standardization dominates hazardous and infectious streams through EU-wide classification protocols, while pharmaceutical residues demand customized handling pathways tied to specific chemical profiles.
- Infectious Waste:Surgical and diagnostic procedures generate persistent volumes requiring steam sterilization at minimum 121 degrees Celsius or thermal destruction exceeding 850 degrees Celsius. Paris, Berlin, and London hospital clusters drive concentrated demand as EU Waste Framework Directive enforcement intensifies segregation mandates.
- Pharmaceutical Waste:Complex chemical residues from manufacturing and pharmacy operations require specialized hazardous infrastructure. EMA classification guidelines directly influence segregation protocols at Basel and Frankfurt pharmaceutical sites, creating supply bottlenecks where treatment capacity concentrates with specialized operators.
- Hazardous Waste:Sharps, pathological specimens, and cytotoxic materials fall under ADR transport regulations and REACH disposal restrictions.
- Non-Hazardous Waste:General healthcare refuse including packaging and administrative materials follows standard municipal waste protocols with lower compliance overhead.
Leading the category by volume: Infectious Waste. Expanding most quickly: Pharmaceutical Waste.
Service Type:
Route density economics favor integrated providers in metropolitan corridors, while rural facilities fragment procurement across specialized operators.
- Collection:High-frequency scheduled pickups from dense urban hospital networks generate mature margin pools where fleet specialization determines profitability. Île-de-France regional health agencies now bundle collection into multi-year framework agreements.
- Treatment:Autoclaving infrastructure dominates capital deployment as Germany's Federal Environment Agency accelerates incineration retrofit deadlines. Microwave disinfection pilots in Dutch mid-scale facilities are compressing deployment timelines for space-constrained sites.
- Transportation:Refrigerated vehicles and leak-proof containment systems require substantial ADR-licensed driver investment.
- Disposal:Final residue placement follows national transpositions of EU waste hierarchy mandates with tightening landfill diversion targets.
Commanding the highest margins: Treatment. Growing fastest: Collection.
End User:
Scale concentration among multi-site hospital networks is displacing transactional procurement with subscription-based compliance monitoring models.
- Hospitals:Western European tertiary facilities are expanding contracted waste management services to meet stricter disposal standards. Auvergne-Rhône-Alpes and Rhine-Ruhr corridors show dense procurement concentration.
- Laboratories:Diagnostic and research facilities generate specialized chemical and biological waste streams requiring traceable chain-of-custody documentation.
- Clinics:Smaller outpatient facilities fragment volume across regional service providers with less negotiating leverage.
- Dental Practices:Amalgam and sharps disposal follows sector-specific protocols with localized collection networks.
Dominating procurement volume: Hospitals. Gaining share fastest: Laboratories.
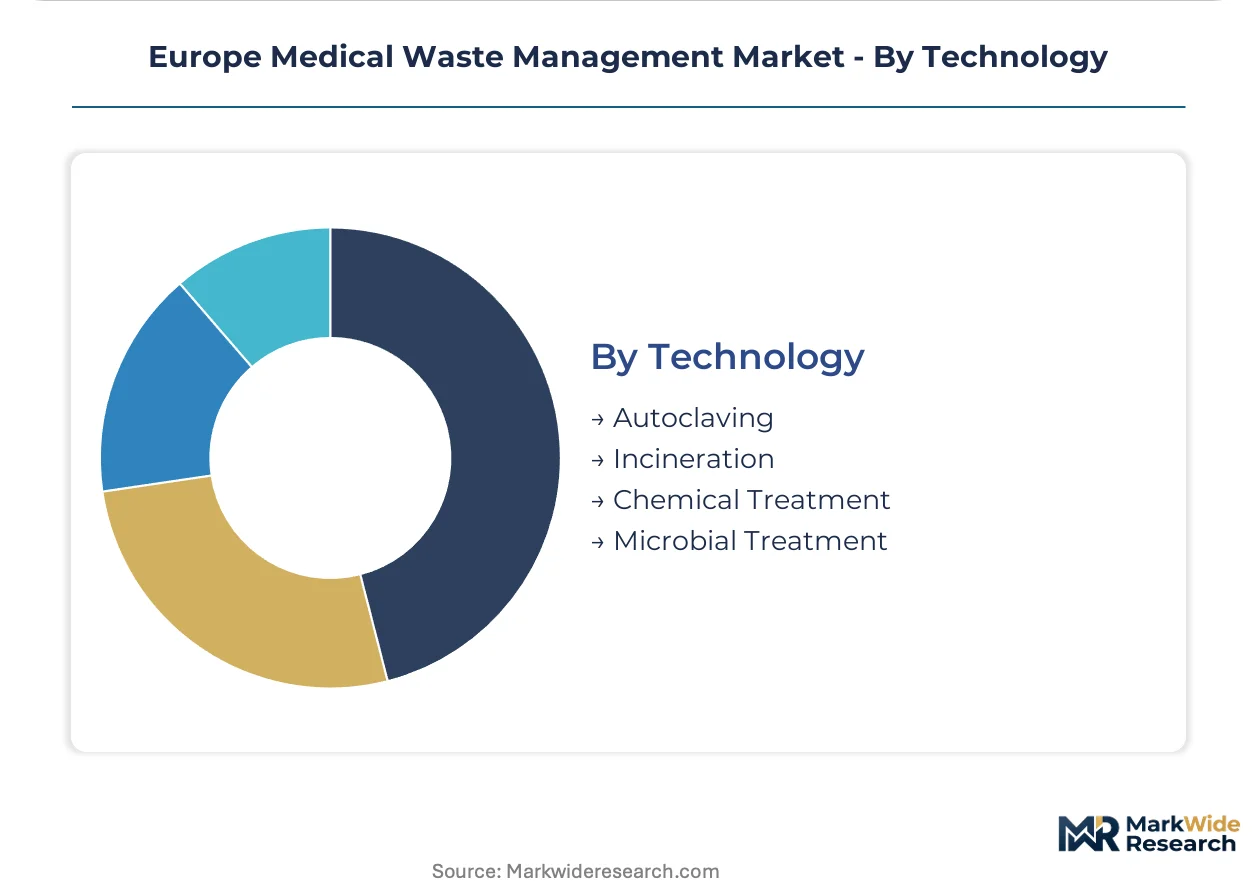
Technology:
Emissions compliance timelines are forcing technology swaps before regulatory deadlines strand legacy assets.
- Autoclaving:Steam sterilization leads deployment across Europe due to lower emissions profiles and operational flexibility compared to thermal destruction. Modular systems enable rapid scaling for facilities with space constraints.
- Incineration:Legacy installations face write-down pressure as REACH Annex XVII restrictions on persistent organic pollutants mandate advanced flue gas treatment retrofits.
- Chemical Treatment:Pharmaceutical residue neutralization concentrates in specialized infrastructure near Basel and Frankfurt manufacturing corridors.
- Microbial Treatment:Biological digestion methods remain niche for specific organic waste streams with limited European deployment.
Leading deployment by installed base: Autoclaving. Climbing the fastest: Chemical Treatment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Ruhr corridor anchors European medical waste management demand through dense hospital networks and concentrated pharmaceutical manufacturing. Paris, Berlin, and London metropolitan clusters generate route-density economics that sustain high-frequency collection schedules. National transpositions of the EU Waste Framework Directive are forcing treatment infrastructure upgrades ahead of compliance deadlines.
Germany
Federal Environment Agency enforcement intensity accelerates incineration retrofit deadlines across Rhine-Ruhr and Bavarian hospital networks. The country's waste hierarchy mandates under EU Green Deal transpositions compel steam sterilization adoption. Frankfurt and Basel-adjacent pharmaceutical corridors concentrate specialized chemical-physical treatment capacity for complex residue streams.
France
Regional health agencies in Île-de-France and Auvergne-Rhône-Alpes bundle waste management into multi-year facility services frameworks. ANSM pharmaceutical waste classifications tighten segregation protocols at hospital pharmacies. Paris hospital clusters drive contracted service expansion as disposal standards intensify.
United Kingdom
London metropolitan concentration enables logistics optimization for urban hospital networks. Environment Agency permitting timelines compress procurement cycles for treatment technology upgrades. NHS procurement consortia extend contract durations and lock in service-level specifications across Southeast and Midlands regions.
Netherlands
Microwave disinfection pilots in mid-scale Dutch facilities compress capital deployment for space-constrained sites. REACH Annex XVII enforcement on persistent organic pollutants diverts waste streams from legacy incineration. Rotterdam and Amsterdam hospital clusters test modular treatment systems for surgical waste below centralized autoclave thresholds.
Poland
EU structural funds accelerate healthcare infrastructure investment across Warsaw and Kraków hospital networks. National transpositions of EU waste hierarchy mandates lag Western European timelines but tighten procurement requirements. Underpenetrated service markets attract Western European operators seeking capacity expansion.
Europe Medical Waste Management Market Competitive Landscape
Capital-heavy integrated environmental service platforms compete with specialized hazardous waste operators and asset-light logistics specialists. The market consolidates around three strategic tiers: multinational conglomerates bundling collection, treatment, and compliance reporting; regional specialists concentrating complex pharmaceutical residue handling; and urban logistics networks optimizing high-frequency collection density. Dominant competitive moves include framework agreement expansion with multi-site hospital networks and backward integration into specialized treatment infrastructure.
Among France-based integrated service platforms, Veolia Environnement S.A. represents the multinational conglomerate archetype spanning environmental services across multiple European jurisdictions. SUEZ Group occupies a position within specialized hazardous waste infrastructure handling. REMONDIS SE & Co. KG exemplifies the German logistics-intensive model with dense urban collection networks.
| Leading Market Players |
|---|
| Veolia Environnement S.A. |
| SUEZ Group |
| Stericycle Inc. |
| REMONDIS SE & Co. KG |
| Daniels Health |
| Sharpsmart Europe |
| PHS Group Limited |
| Rentokil Initial plc |
| SRCL Limited |
| Others |
Pricing and Supply Chain Analysis
Steam sterilization technology adoption across German and French hospital networks simultaneously compresses per-tonne treatment costs and concentrates procurement power with integrated service platforms capable of bundling collection, treatment, and regulatory reporting. This technological transition rewards operators with dense logistics networks while marginalizing standalone incineration providers facing stranded asset risk from EU Green Deal waste hierarchy mandates.
Pricing Analysis
Subscription-based compliance monitoring anchors value-based pricing for multi-site hospital networks, with three-tier pricing structure across premium, standard, and economy levels differentiated by traceability depth and reporting frequency. Cost compression in standard-tier collection services is intensifying because French regional health agencies bundle waste management into broader facility services tenders. Price sensitivity peaks among outpatient clinics fragmenting volume across regional providers, while tertiary hospital networks in Paris and Berlin corridors prioritize uptime guarantees over unit economics.
Supply Chain Analysis
Freight cost intensity from ADR-licensed driver scarcity and specialized refrigerated fleet requirements elevates route density economics as the decisive competitive variable. Supply concentrates in Germany, France, and the Netherlands, with treatment capacity drawing from stainless steel autoclave vessels, advanced flue gas scrubbers, and leak-proof containment systems. Single-source vulnerability concentrates around certified hazardous waste technicians, whose training pipelines lag enforcement intensity from Germany's Federal Environment Agency. Distribution runs through contracted service agreements with multi-year framework lock-ins rather than spot procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Waste Framework Directive's tightening disposal standards erect a formidable cost-of-compliance barrier, with national transposition timelines favoring incumbents that have already deployed advanced treatment infrastructure ahead of regulatory deadlines.
For Market Incumbents: Acquire specialized chemical-physical treatment assets near Basel and Frankfurt pharmaceutical corridors to capture high-margin residue streams from manufacturing sites. Backward integration into ADR-certified driver training programs defends against workforce pipeline constraints threatening collection frequency commitments. Consolidate framework agreement share in Île-de-France and Auvergne-Rhône-Alpes before regional health agencies complete procurement bundling.
For New Entrants and Emerging Players: Mid-scale Dutch hospitals piloting microwave disinfection systems represent an underserved buyer archetype seeking modular alternatives to centralized autoclave infrastructure. Polish and Romanian hospital networks present penetrable demand as EU structural funds accelerate infrastructure investment ahead of waste hierarchy mandate transpositions. A go-to-market angle anchored to rapid deployment timelines and space-constrained site optimization bypasses incumbent route-density advantages in saturated Western European corridors.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by integrated environmental service platforms seeking hazardous waste specialization. Long-term viability favors operators with captive treatment capacity and multi-year contracted revenue visibility across the analysis window. The signal to watch is EMA pharmaceutical waste classification convergence, which will standardize segregation requirements and potentially commoditize specialized handling premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Advanced Treatment Technology Deployment | Autoclaving and microwave systems displace legacy incineration as EU emissions standards tighten. |
| Framework Agreement Expansion | Multi-year bundled contracts with French regional health agencies lock in pricing and service levels. |
| Hazardous Infrastructure Backward Integration | Captive chemical-physical treatment capacity captures pharmaceutical residue margins near Basel. |
| Certified Workforce Pipeline Investment | ADR-licensed driver training programs defend collection frequency commitments in urban clusters. |
| Digital Traceability Platform Development | Regulatory reporting capabilities differentiate integrated platforms from basic service providers. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across waste management operations directors, hospital procurement managers, biomedical engineering leads, and hazardous transport fleet supervisors. ECHA substance restriction databases, EU Waste Framework Directive national transposition documents, German Federal Environment Agency enforcement records, and hospital GPO contract databases supplied validation triangulation. Bottom-up service provider capacity assessments and top-down healthcare waste generation estimates were reconciled through iterative cross-checking.
Granularity-level modeling segmented the market by waste classification, service modality, neutralization technology, and end-user scale, with regional regulatory cluster intensity as an additional dimension. CAGRs were derived from treatment capacity expansion timelines aligned with compliance deadline schedules and healthcare infrastructure investment flows across the projection horizon. Forecast inputs incorporated autoclave deployment rates, incineration retrofit completion curves, and pharmaceutical manufacturing site expansion plans.
Revisions become necessary when EU Green Deal waste hierarchy mandate transpositions accelerate beyond baseline timelines or when EMA pharmaceutical waste classifications diverge from harmonization trajectories. Forecasts reflect assumptions about enforcement intensity continuity and technology substitution elasticity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste Management & Pollution Control
Saudi Arabia Waste Management Market
Waste Management & Pollution Control
India Waste Management Market
Waste Management & Pollution Control
GCC Pneumatic Waste Management System Market
Waste Management & Pollution Control
ASEAN Waste Management Market
Waste Management & Pollution Control
Global Pharmaceutical Waste Management Market
Waste Management & Pollution Control
Reusable Sediment Control Wattles Market
Waste Management & Pollution Control
Saudi Arabia Medical Waste Management Market
Waste Management & Pollution Control
Hazardous Waste Management Market
Waste Management & Pollution Control
China Waste Management Market
Waste Management & Pollution Control
Reusable Oil Absorbents Market
Waste Management & Pollution Control
Biomedical Waste Management Market
Waste Management & Pollution Control
Waste Management Market
Waste Management & Pollution Control
GCC Industrial Waste Management Market
Waste Management & Pollution Control
Sharp Waste Disposal Market
Waste Management & Pollution Control
Compostable Straws Market
Waste Management & Pollution Control
India Plastic Waste Management Market