
 GCC Pneumatic Waste Management System Market | 2026-2036
GCC Pneumatic Waste Management System Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Pneumatic Waste Management System Market Insights
Aftermarket service revenue is reconfiguring margin capture across the GCC pneumatic waste ecosystem. Envac AB leverages its long-tenured installed base in Nordic exports to sustain premium service contracts across Gulf municipal clients. MariMatic Oy anchors its regional position through deep specialization in vacuum system engineering for high-rise residential clusters. Logiwaste AB competes on manufacturing scale, while Aerbin ApS differentiates through compact system designs tailored to Middle Eastern climatic conditions.
A pneumatic waste management system transports municipal refuse through underground tube networks using differential air pressure, typically operating at conveying velocities between 18-25 meters per second with polyethylene or steel pipe diameters ranging from 400mm to 600mm. These systems eliminate curbside collection vehicles from dense urban cores, reducing surface traffic congestion and odor emissions in climate-controlled environments. Vacuum systems dominate current GCC installations due to proven reliability in sand-prone environments, while hybrid configurations represent the fastest-expanding segment as developers seek operational flexibility across mixed-use districts. Application demand skews heavily toward residential buildings and commercial facilities, where facility managers prioritize labor cost reduction and hygiene standards.
Saudi Arabia's Saudi Standards, Metrology and Quality Organization and the UAE's Ministry of Climate Change and Environment shape product certification requirements for imported pneumatic infrastructure, with both jurisdictions tightening material specifications for underground durability. The Gulf Standardization Organization harmonizes technical compliance across member states, streamlining cross-border procurement for multinational contractors. Facility managers and municipal procurement officers must monitor evolving national building codes that increasingly mandate automated waste handling in new master plans.
Market Dynamics
Aftermarket service revenue is reconfiguring margin capture across the GCC pneumatic waste ecosystem, as municipal clients extend asset lifecycles and demand predictive maintenance capabilities from incumbent suppliers.
Growth Catalysts
- Vision 2030 sustainability mandates:Saudi Arabia's national transformation program mandates automated waste infrastructure in new master-planned developments, directing procurement specifications toward concealed pneumatic networks.
- High-rise residential density:Master-planned communities across Dubai and Doha prioritize underground waste logistics to eliminate surface collection vehicles and reduce ambient temperatures in climate-controlled environments.
- Polyethylene pipe specifications:Advancements in corrosion-resistant materials extend system durability in sand-prone environments, reducing lifecycle replacement costs for municipal operators.
Market Restraints
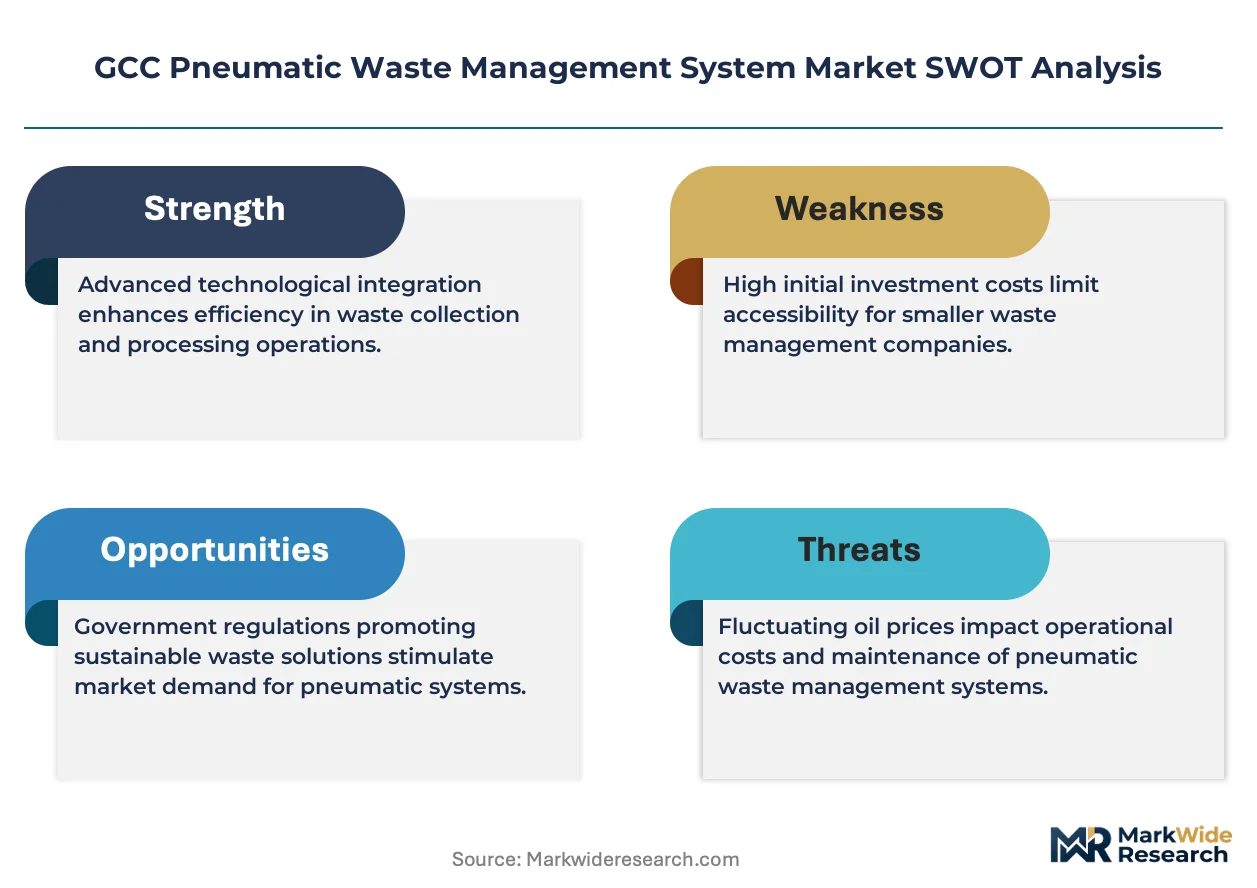
- Capital intensity for underground installation:Trenching and civil works consume substantial upfront investment, limiting deployment to greenfield developments rather than retrofit contexts.
- Specialized contractor scarcity:Vacuum system engineering expertise concentrates among Nordic-origin suppliers, creating procurement bottlenecks during peak construction cycles.
- Hybrid configuration complexity:Developers seeking operational flexibility across mixed-use districts face integration challenges between vacuum and gravity-assisted subsystems.
Strategic Opportunities
- Qatar's infrastructure pipeline:Preparations for sustained urban expansion create demand for district-scale pneumatic networks in Lusail and Msheireb developments.
- Building-integrated waste handling:National building codes across the UAE increasingly mandate automated collection in new commercial towers above specified floor counts.
- AI-enabled predictive maintenance:Convergence of IoT sensors and machine learning platforms allows suppliers to offer uptime guarantees, shifting revenue toward subscription-based service models.
Industry Challenges
- Vacuum system commissioning expertise:Qualified technicians for differential pressure calibration remain scarce across Gulf municipal workforces, extending project handover timelines.
- Gulf Standardization Organization harmonization:Evolving technical compliance requirements across member states create certification friction for multinational contractors bidding cross-border projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Pneumatic Waste Management System Market |
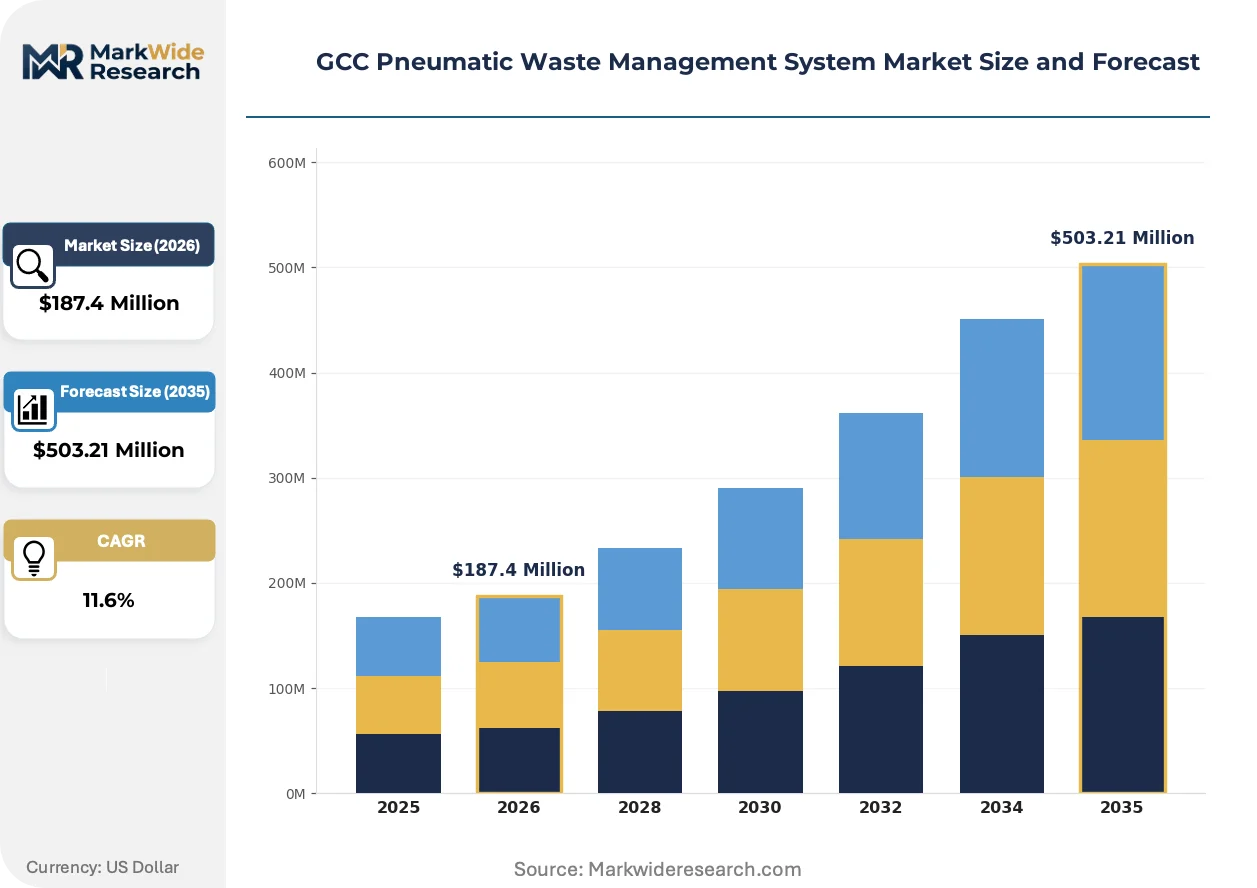
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Vacuum Systems, Pressure Systems, Hybrid Systems, Pneumatic Conveying Systems Application: Residential Buildings, Commercial Facilities, Healthcare Institutions, Industrial Parks End User: Waste Management Companies, Municipal Corporations, Facility Managers, Environmental Agencies Installation Type: Indoor Systems, Outdoor Systems, Mobile Systems, Custom-Built Solutions |
| Companies Covered | MariMatic Oy, Envac AB, Logiwaste AB, Aerbin ApS, Stream Environment Sdn Bhd, URD, ATREO, Ros Roca Envirotec, Ecosir Group Oy, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Pneumatic Waste Management System Market Trends and Innovations
Smart city infrastructure investments are reshaping how Gulf municipalities specify waste logistics, with specification committees prioritizing concealed systems that reduce surface traffic and odor emissions in dense urban cores.
Steel pipe infrastructure is migrating from conventional welded configurations to modular flange-connected segments. Facility managers in Riyadh's financial district developments favor rapid-installation systems that minimize excavation duration. This shift is compressing project timelines from 18-month cycles toward 12-month deployments, enabling developers to accelerate tenant occupancy schedules.
Saudi Standards, Metrology and Quality Organization specifications for underground durability are tightening material thickness requirements and corrosion testing protocols. Industrial consequence includes elevated qualification barriers for imported polyethylene and steel components. Manufacturers serving the Eastern Province industrial corridor are responding by establishing local testing partnerships to accelerate certification timelines.
Service contract unbundling is fragmenting traditional procurement packages across Dubai's master-planned communities. Facility management consortia now separate equipment supply from long-term maintenance obligations, creating specialized vendor tiers. This pattern concentrates most visibly in commercial mixed-use districts where asset ownership structures complicate unified vendor selection.
GCC Pneumatic Waste Management System Market Segmentation
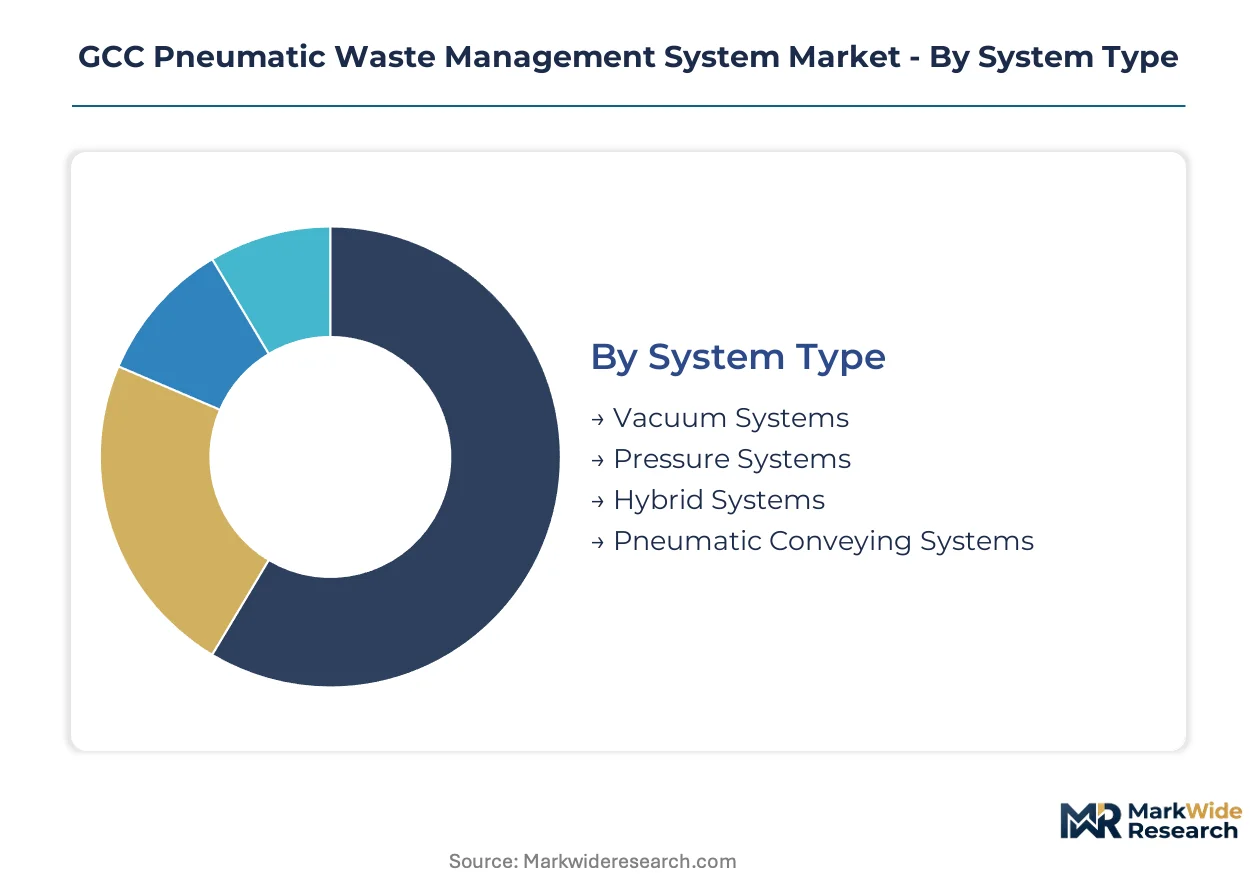
Segmentation in the GCC pneumatic waste ecosystem reveals how procurement specifications diverge across project scales and institutional buyer types. Understanding these divides allows suppliers to align engineering capabilities with the distinct technical and commercial requirements of municipal versus private sector deployment.
System Type:
Cost tiers across system architectures determine capital allocation patterns and lifecycle service revenue potential for installed bases.
- Vacuum Systems:Differential pressure transport using centrifugal blowers achieves conveying velocities of 18-25 meters per second through polyethylene or steel piping. Riyadh's financial district developments specify vacuum configurations for proven reliability in sand-prone environments where particulate infiltration threatens mechanical seals.
- Hybrid Systems:Integrated vacuum-gravity architectures enable operational flexibility across mixed-use districts with varying waste density profiles. Dubai's master-planned communities are rotating procurement specifications toward hybrid configurations as developers seek unified infrastructure serving residential towers alongside retail podiums.
- Pressure Systems:Positive-pressure blowers push waste through sealed networks for high-volume industrial applications.
- Pneumatic Conveying Systems:Generalized transport infrastructure without vacuum specialization serves legacy retrofit contexts.
Vacuum Systems hold installed capacity. Hybrid Systems is rotating up the share rankings.
Application:
End-use environments impose divergent hygiene standards and throughput requirements that shape subsystem specifications.
- Residential Buildings:High-rise clusters above 15 floors deploy vertical chute networks with automated discharge valves. Doha's Lusail development mandates concealed pneumatic logistics in residential towers to eliminate surface collection vehicles and reduce ambient heat absorption in climate-controlled districts.
- Commercial Facilities:Mixed-use towers require segregated waste streams with separate pneumatic lines for recyclables and general refuse. Facility managers in Dubai International Financial Centre prioritize labor cost reduction through automated handling systems that minimize manual collection in premium office environments.
- Healthcare Institutions:Infection control protocols demand sealed transport with dedicated medical waste separation.
- Industrial Parks:Bulk material handling applications favor high-capacity pressure configurations.
Residential Buildings anchors procurement volume. Commercial Facilities is climbing the fastest in share rankings.
End User:
Customer type determines contract structures, with public procurement favoring bundled long-term service agreements versus private sector unbundling.
- Municipal Corporations:Public sector buyers across Saudi Arabia's Vision 2030 developments specify 15-20 year concession frameworks combining construction, operation, and maintenance obligations. Riyadh Municipality directs master-planned community procurement toward concealed pneumatic networks as mandatory infrastructure in new district approvals.
- Facility Managers:Private sector operators in Dubai's commercial mixed-use districts increasingly separate equipment supply from maintenance contracts. Asset ownership fragmentation in multi-investor developments complicates unified vendor selection and extends procurement cycles.
- Waste Management Companies:Specialized operators bid for municipal concession contracts with performance-linked payment structures.
- Environmental Agencies:Regulatory oversight bodies influence technical specifications through certification requirements rather than direct procurement.
Municipal Corporations hold installed capacity. Facility Managers is rotating up the share rankings.
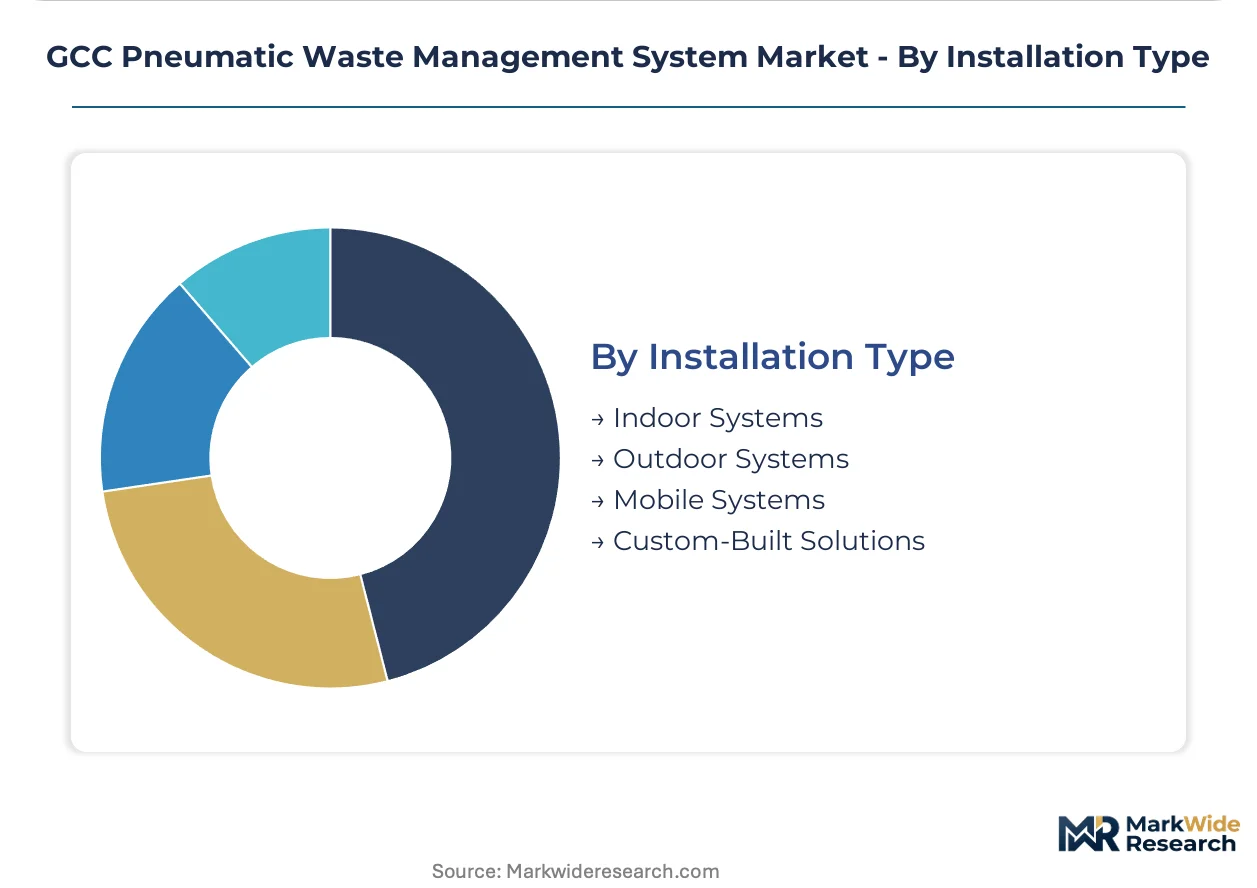
Installation Type:
Deployment context shapes civil engineering intensity and project timeline compression potential.
- Outdoor Systems:Underground pipe networks with surface-mounted collection points serve district-scale developments. Saudi Arabia's Eastern Province industrial corridor favors rapid-installation modular flange-connected segments that minimize excavation duration in greenfield contexts.
- Indoor Systems:Building-integrated vertical chutes with basement consolidation stations dominate high-rise residential specifications. UAE Ministry of Climate Change and Environment building codes increasingly mandate automated collection in new commercial towers above specified floor counts.
- Mobile Systems:Trailer-mounted vacuum units serve temporary construction site or event-based waste logistics.
- Custom-Built Solutions:Bespoke engineering addresses non-standard site constraints or heritage retrofit limitations.
Outdoor Systems holds installed capacity. Indoor Systems is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across the Gulf Cooperation Council diverge sharply by development phase. Saudi Arabia drives volume through state-mandated master plans, while the UAE and Qatar concentrate procurement in high-density commercial clusters. Kuwait and Oman represent emerging pockets where pilot installations test scalability.
Saudi Arabia
Riyadh's financial district and NEOM developments anchor regional demand for concealed pneumatic networks. Saudi Standards, Metrology and Quality Organization specifications tighten material thickness requirements for underground durability. The Eastern Province industrial corridor favors rapid-installation modular flange-connected segments that compress project timelines.
United Arab Emirates
Dubai's master-planned communities and Abu Dhabi's new commercial towers prioritize automated waste handling to eliminate surface collection vehicles. The Ministry of Climate Change and Environment mandates automated collection in commercial towers above specified floor counts. Dubai International Financial Centre facility managers specify segregated waste streams with separate pneumatic lines.
Qatar
Lusail and Msheireb developments drive district-scale pneumatic procurement for high-rise residential clusters. The country's national standardization body harmonizes technical compliance with Gulf Standardization Organization frameworks. Doha's climate-controlled districts mandate concealed logistics to reduce ambient heat absorption.
Kuwait
Sabah Al Ahmad Sea City and other greenfield developments test pneumatic viability in lower-density contexts. The country's public works authority evaluates concession frameworks modeled on Saudi Vision 2030 structures. Kuwait City's emerging commercial corridor sees initial indoor system specifications in premium office towers.
Oman
Duqm Special Economic Zone and Muscat's new urban districts represent pilot markets for vacuum system technology. The national building code authority studies UAE and Saudi regulations for future harmonization. Salalah's port-adjacent developments explore mobile pneumatic units for temporary logistics needs.
GCC Pneumatic Waste Management System Market Competitive Landscape
Capability concentration sits with Nordic-origin engineering specialists; scale advantage sits with diversified infrastructure contractors bidding turnkey packages. The vendor base organizes around three archetypes: vacuum system engineering specialists, manufacturing-scale fabricators, and climate-adapted compact system designers. Consolidation pressure operates through long-term service contract bundling and local certification partnership requirements.
Within the engineering-specialist tier, MariMatic Oy and Envac AB occupy positions defined by installed base tenure and aftermarket service reach. Logiwaste AB exemplifies the manufacturing-scale archetype competing on production capacity. Aerbin ApS represents the compact-system specialization vector addressing Middle Eastern climatic constraints. These four names anchor competitive dynamics without exhausting the participant set.
| Leading Market Players |
|---|
| MariMatic Oy |
| Envac AB |
| Logiwaste AB |
| Aerbin ApS |
| Stream Environment Sdn Bhd |
| URD |
| ATREO |
| Ros Roca Envirotec |
| Ecosir Group Oy |
| Others |
Pricing and Supply Chain Analysis
Single-source dependency on Nordic vacuum system engineering expertise compresses pricing tier spreads while elevating procurement timelines for GCC municipal clients. Saudi Standards, Metrology and Quality Organization certification requirements for underground durability simultaneously widen premium-standard pricing gaps and force supply chain localization investments.
Pricing Analysis
Long-term concession frameworks dominate municipal procurement, bundling construction, operation, and maintenance across 15-20 year contracts. Price differentiation rests on certification grade against GSO harmonized standards and aftermarket service bundling depth. Cost compression in mid-tier vacuum configurations is intensifying because facility management consortia now unbundle equipment supply from maintenance obligations. Municipal corporations exhibit highest price sensitivity due to budget cycle constraints, while private facility managers prioritize uptime guarantees over capital outlay minimization.
Supply Chain Analysis
Contract manufacturing concentration among Nordic-origin specialists—MariMatic Oy, Envac AB, and Logiwaste AB—anchors regional capacity for vacuum blower assemblies and polyethylene pipe fabrication. Component sourcing draws from Germany for precision-engineered valves, South Korea for corrosion-resistant steel alloys, and the UAE for localized flange-connection fabrication. Single-source vulnerability concentrates in qualified differential pressure calibration technicians, extending project handover timelines. Distribution runs through turnkey infrastructure contractors bidding Saudi Vision 2030 and Qatar Lusail developments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The GCC pneumatic waste ecosystem sits in early-cycle expansion, with smart city infrastructure mandates across Riyadh, Dubai, and Doha creating irreversible procurement tailwinds for concealed automated systems.
For Market Incumbents: Harden aftermarket service moats through predictive maintenance platform deployment and localized technician training partnerships with Saudi technical institutes. Envac AB's premium contract retention demonstrates how long-tenured installed base access defends against emerging compact-system specialists. Capacity addition in the Eastern Province industrial corridor captures procurement acceleration from modular flange-connected segment demand. For New Entrants and Emerging Players: Kuwait's Sabah Al Ahmad Sea City and Oman's Duqm Special Economic Zone represent white-space markets where pilot installation viability remains untested. Facility manager procurement unbundling in Dubai commercial mixed-use districts creates entry paths for specialized maintenance vendors without full system engineering capabilities. Go-to-market positioning should emphasize rapid-installation value propositions that compress project timelines toward 12-month deployment cycles. For Investors and Strategic Acquirers: The market sits at an infrastructure-buildout phase that favors engineering-specialist acquisition targets with demonstrated GSO certification navigation and established municipal concession relationships. Long-term viability over the next decade hinges on AI-enabled predictive maintenance subscription revenue displacing capital equipment sales. Watch for hybrid system specification adoption rates in Dubai master-planned communities as inflection indicator for operational flexibility premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| Local Certification Partnership | Saudi Standards, Metrology and Quality Organization compliance accelerates procurement eligibility for Eastern Province developments. |
| Predictive Maintenance Platform | IoT sensor convergence with machine learning enables uptime guarantees shifting revenue toward subscription models. |
| Modular Flange-Connected Systems | Riyadh financial district developers favor rapid-installation configurations that minimize excavation duration. |
| Hybrid System Engineering | Dubai mixed-use districts seek unified infrastructure serving residential towers alongside retail podiums. |
| Technician Training Consortium | Gulf municipal workforce scarcity in differential pressure calibration extends project handover timelines without intervention. |
Research Methodology
Operator-level perspectives from municipal procurement officers, facility management consortium leads, vacuum system commissioning engineers, and infrastructure contractor project directors anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through Gulf Standardization Organization technical documentation, Saudi Standards, Metrology and Quality Organization certification protocols, UAE Ministry of Climate Change and Environment building code amendments, and municipal concession contract filings. Bottom-up installation database construction triangulated against top-down infrastructure spending forecasts across the analysis window.
Scenario-bracketing framed volume projections across vacuum, hybrid, pressure, and pneumatic conveying system architectures. Segmentation dimensions modeled include system type, application environment, end-user procurement structure, and installation context. CAGRs derived from fitted growth curves incorporating master-planned development pipeline data, national building code amendment trajectories, and aftermarket service contract renewal patterns. Analysis window projections integrate Saudi Vision 2030 sustainability mandate implementation pace and Qatar Lusail infrastructure completion schedules.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by manufacturing-scale fabricators or accelerated GSO harmonization would shift outcomes. Quarterly review of municipal concession award announcements, hybrid system specification adoption rates, and localized certification partnership formations is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste Management & Pollution Control
Marine Waste Handling Equipment Market
Waste Management & Pollution Control
Recyclate PET Market
Waste Management & Pollution Control
Mining Waste Management Market
Waste Management & Pollution Control
Automated Waste Collection System (AWCS) Market
Waste Management & Pollution Control
China Waste Management Market
Waste Management & Pollution Control
Europe Waste Management Market
Waste Management & Pollution Control
GCC Industrial Waste Management Market
Waste Management & Pollution Control
Rare Earth Recycling Market
Waste Management & Pollution Control
India Waste Management Market
Waste Management & Pollution Control
Europe Plastic Waste Management Market
Waste Management & Pollution Control
Food Waste Management Market
Waste Management & Pollution Control
Smart Waste Sorting Bin Market
Waste Management & Pollution Control
Paper Recycling Market
Waste Management & Pollution Control
Scrap Metal Recycling Market
Waste Management & Pollution Control
Municipal Solid Waste Incineration Market
Waste Management & Pollution Control
Biomedical Waste Management Market