
 AI in Environmental Sustainability Market | 2026-2036
AI in Environmental Sustainability Market Size, Share, and Industry Trends Forecast 2026-2036
AI in Environmental Sustainability Market Insights
Platform bundling of climate analytics with carbon accounting software is expanding buyer choice across enterprise segments. Microsoft Corporation leverages its cloud infrastructure to anchor sustainability workloads for large industrial clients. IBM Corporation competes through specialized consulting layers that integrate machine learning models with legacy environmental databases. C3.ai differentiates via pre-built AI applications targeting energy-intensive manufacturing verticals.
AI in Environmental Sustainability denotes computational systems that process multisource environmental data through machine learning algorithms, computer vision pipelines, and reinforcement learning frameworks to optimize resource flows, predict ecological disruptions, and automate emissions monitoring with precision thresholds measured in parts per million. These systems serve industrial and commercial purposes by transforming satellite imagery, sensor networks, and enterprise operational data into actionable conservation and efficiency directives. Climate Modeling and Energy Management command the largest current revenue pools, while Pollution Control applications demonstrate the fastest trajectory as regulatory enforcement tightens across jurisdictions. Machine Learning dominates the technology stack due to mature toolchains and interpretability requirements, though Computer Vision is gaining ground in wildlife monitoring and deforestation detection use cases where spatial analysis proves critical.
The EPA enforces emissions disclosure standards that compel industrial facilities to adopt automated monitoring systems, while the EU Green Deal and its CSRD framework mandate granular sustainability reporting that only scalable AI platforms can deliver cost-effectively. ISO 14001 environmental management standards further shape product specifications by requiring auditable data lineage in certified operations. Stakeholders must weigh deployment mode trade-offs between cloud scalability and edge latency as regulatory latency requirements tighten for real-time pollution alerts.
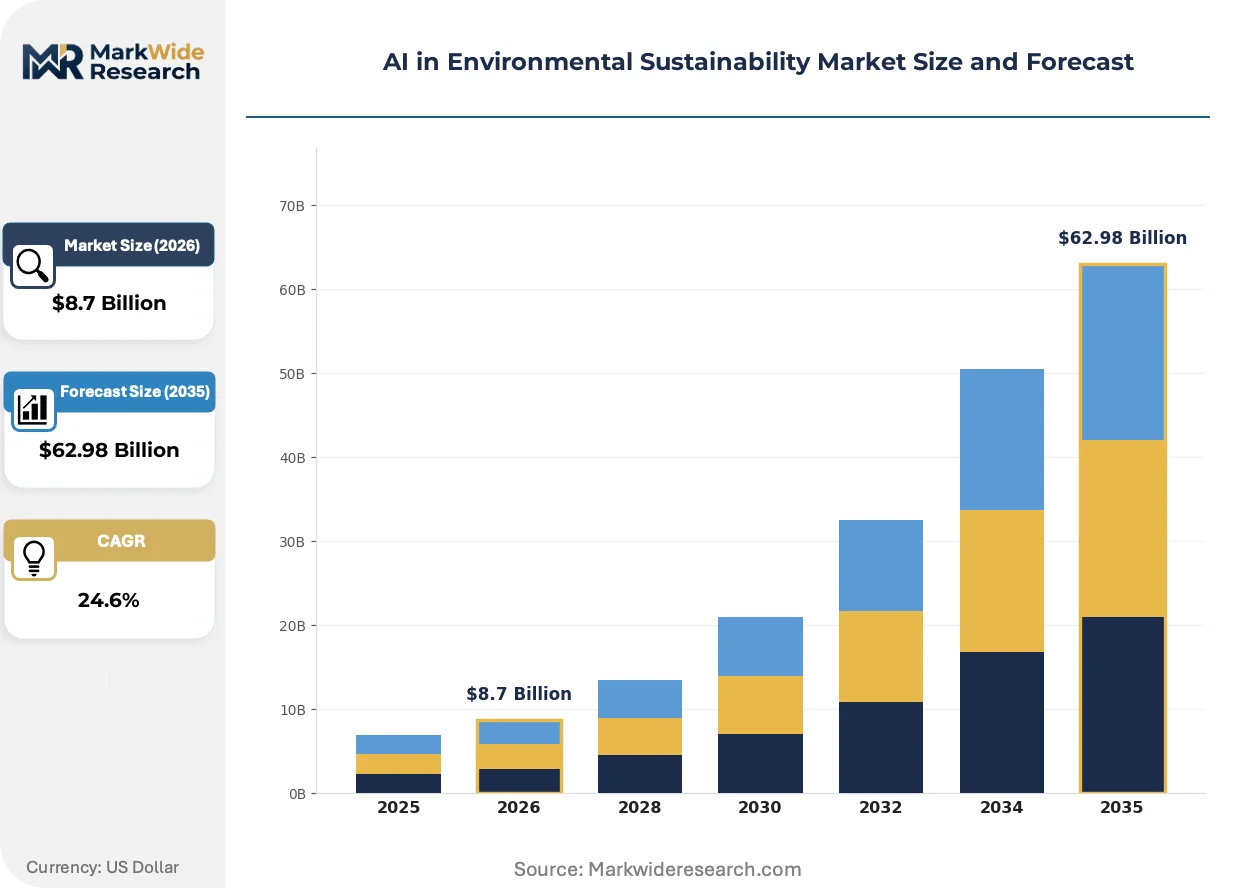
Market Dynamics
CSRD disclosure mandates across the European Union are compressing deployment timelines for emissions tracking platforms, forcing industrial buyers to prioritize pre-integrated AI solutions over custom builds.
Growth Catalysts
- EU Green Deal enforcement:The CSRD framework requires granular sustainability reporting that only scalable AI platforms can deliver cost-effectively, accelerating procurement cycles for automated monitoring systems.
- Renewable energy operational demands:Wind and solar farm operators deploy machine learning models to forecast generation volatility and optimize grid dispatch, reducing curtailment losses.
- German industrial clustering:Dense concentrations of automotive and chemical manufacturing in the Ruhr and Bavaria create concentrated demand for pollution control AI with real-time alert capabilities.
Market Restraints
- Edge hardware cost volatility:Specialized GPU and TPU chipsets for field-deployed environmental sensors face supply concentration risks from Taiwan-based foundries, inflating unit economics for distributed monitoring networks.
- Data interoperability friction:Legacy SCADA systems in heavy industry lack standardized APIs, forcing expensive middleware development before AI analytics layers can ingest operational telemetry.
- Regulatory latency requirements:EPA real-time pollution alert mandates impose sub-second response thresholds that strain cloud-to-edge transmission architectures in remote monitoring deployments.
Strategic Opportunities
- India industrial corridor penetration:The PLI scheme for clean technology manufacturing creates subsidy-backed entry points for AI-powered energy optimization platforms in Gujarat and Tamil Nadu chemical parks.
- Computer vision-wildlife monitoring convergence:Satellite imagery analysis paired with acoustic sensors opens conservation funding streams from multilateral climate finance mechanisms previously inaccessible to industrial AI vendors.
- Japan METI carbon neutrality roadmap:Mandatory emissions reduction targets for steel and cement producers generate demand for predictive maintenance AI that simultaneously cuts energy intensity and extends asset life.
Industry Challenges
- Environmental data science talent scarcity:The intersection of atmospheric chemistry, remote sensing, and machine learning engineering remains thinly staffed, elongating implementation timelines for complex pollution forecasting deployments.
- ISO 14001 audit trail complexity:Certification bodies demand immutable data lineage for AI-generated emissions calculations, requiring blockchain or equivalent provenance infrastructure that most platforms lack natively.
- Multi-source sensor fusion integration:Harmonizing satellite, drone, ground-based, and enterprise ERP data streams demands bespoke pipeline architecture that fragments vendor scalability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI in Environmental Sustainability Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $62.98 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Climate Modeling, Resource Optimization, Pollution Control, Wildlife Conservation, Energy Management AI Technology: Machine Learning, Natural Language Processing, Computer Vision, Reinforcement Learning, Expert Systems End User Type: Environmental Agencies, Research Institutes, Agribusinesses, Renewable Energy Firms, Urban Planners Deployment Mode: Cloud-based, On-premise, Edge Computing, Hybrid Solutions, Mobile Platforms |
| Companies Covered | Microsoft Corporation, IBM Corporation, Google LLC, Amazon Web Services, Siemens AG, Schneider Electric, Oracle Corporation, SAP SE, C3.ai, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI in Environmental Sustainability Market Trends and Innovations
Foundation models trained on planetary-scale climate datasets are compressing the development cycle for specialized environmental applications, enabling smaller teams to deploy predictive capabilities previously requiring national laboratory resources.
Reinforcement learning frameworks for energy grid optimization are converging with digital twin architectures, allowing utilities to simulate demand response scenarios before physical deployment. European transmission system operators in Germany and Denmark lead adoption, driven by F-Gas Regulation pressures to minimize sulfur hexafluoride leakage from switchgear. The structural consequence compresses R&D timelines for hardware-software co-designed efficiency systems.
EPA enforcement of updated Clean Air Act monitoring rules is mandating continuous emissions surveillance at refinery and petrochemical complexes, eliminating periodic stack testing regimes. Facilities in the US Gulf Coast petrochemical corridor face the steepest compliance cliffs, accelerating procurement of computer vision-based flare monitoring systems that replace manual inspection protocols.
Consolidated procurement of climate analytics through cloud marketplaces is displacing direct vendor relationships for mid-market industrial buyers. Energy-intensive manufacturers in Brazil and South Korea now source pre-integrated sustainability workloads through AWS and Azure storefronts, bypassing traditional systems integrator channels. This channel shift concentrates pricing power with hyperscale infrastructure providers.
AI in Environmental Sustainability Market Segmentation
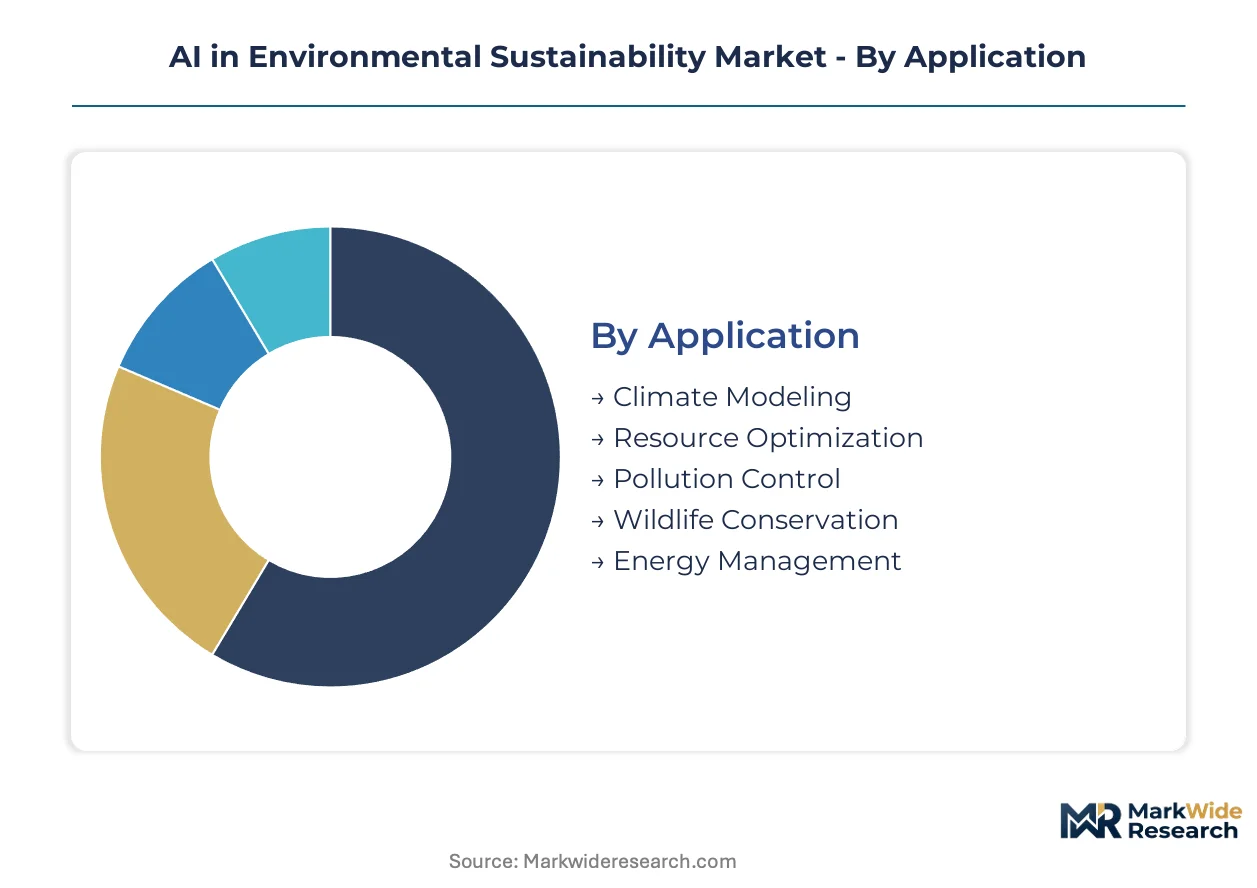
Environmental AI deployments fragment across four critical dimensions: application purpose, underlying AI technology, institutional buyer type, and infrastructure deployment mode. Each axis reveals distinct margin structures, implementation timelines, and regulatory exposure profiles that shape vendor strategy.
Application:
Climate Modeling and Energy Management anchor current revenue volumes through renewable energy procurement cycles, while Pollution Control commands premium pricing from regulatory compliance mandates.
- Climate Modeling:Foundation models process petabyte-scale atmospheric datasets to project regional precipitation patterns and extreme weather probabilities. European transmission system operators in Germany and Denmark deploy these systems for grid resilience planning under F-Gas Regulation pressures.
- Energy Management:Reinforcement learning algorithms optimize dispatch schedules across wind and solar portfolios, reducing curtailment losses. Wind farm operators in the US Gulf Coast and Tamil Nadu industrial corridors drive procurement concentration.
- Pollution Control:Real-time emissions monitoring using computer vision-based flare detection.
- Wildlife Conservation:Satellite imagery analysis paired with acoustic sensor networks for habitat monitoring.
- Resource Optimization:Water and waste stream efficiency algorithms for manufacturing facilities.
Today's leader: Energy Management. Tomorrow's challenger: Pollution Control.
AI Technology:
Machine Learning dominates implementation volumes through mature Python toolchains, while Computer Vision gains ground in regulatory enforcement applications requiring spatial precision.
- Machine Learning:Supervised and unsupervised algorithms for predictive maintenance and demand forecasting. Interpretability requirements from EPA emissions audits favor decision-tree architectures over black-box neural networks.
- Computer Vision:Convolutional neural networks process satellite and drone imagery for deforestation detection and industrial emissions verification. CSRD disclosure mandates in the European Union accelerate procurement from steel and cement producers.
- Reinforcement Learning:Grid optimization and autonomous resource allocation systems.
- Natural Language Processing:Automated sustainability report generation and regulatory document parsing.
- Expert Systems:Rule-based environmental compliance engines for legacy facility retrofits.
Machine Learning captures the dominant share. Computer Vision climbs the fastest as enforcement tightens.
End User Type:
Renewable Energy Firms drive volume procurement through operational efficiency mandates, while Environmental Agencies concentrate premium spending on enforcement-grade monitoring systems.
- Renewable Energy Firms:Wind and solar operators deploy forecasting and optimization AI to minimize curtailment and maximize grid dispatch revenue.
- Environmental Agencies:National regulators including the EPA and EU member state authorities mandate continuous emissions monitoring, procuring sub-second alert systems for refinery complexes.
- Agribusinesses:Precision agriculture and supply chain emissions tracking.
- Research Institutes:Climate modeling and ecological simulation platforms.
- Urban Planners:Smart city resource optimization and heat island mitigation.
Renewable Energy Firms dominate transaction volume. Environmental Agencies set technical specifications that cascade downstream.
Deployment Mode:
Cloud-based architectures capture mid-market efficiency seekers, while Edge Computing commands premium pricing from facilities facing sub-second regulatory latency requirements.
- Cloud-based:Scalable analytics workloads hosted on hyperscale infrastructure. Brazilian and South Korean manufacturers source pre-integrated sustainability tools through AWS and Azure marketplaces, bypassing traditional integrators.
- Edge Computing:Field-deployed GPU and TPU chipsets process sensor data locally to meet EPA real-time pollution alert thresholds. Supply concentration from Taiwan-based foundries inflates unit economics.
- On-premise:Air-gapped systems for classified or critical infrastructure environments.
- Hybrid Solutions:Tiered processing with edge ingestion and cloud analytics.
- Mobile Platforms:Field inspection and citizen science data collection applications.
Cloud-based solutions dominate accessibility. Edge Computing expands most quickly as latency regulations tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Environmental AI applications first achieved commercial scale in European industrial corridors where regulatory stringency created early demand for automated compliance systems. The technology has since diffused across manufacturing clusters in Asia-Pacific and North America, with deployment patterns tightly coupled to local emissions enforcement regimes and renewable energy procurement cycles.
United States
Petrochemical complexes along the US Gulf Coast drive concentrated demand for real-time emissions monitoring as EPA enforcement of updated Clean Air Act rules eliminates periodic stack testing. The Inflation Reduction Act channels federal investment into grid modernization AI for wind and solar operators. Houston and Baton Rouge industrial corridors anchor procurement for computer vision-based flare detection systems.
Germany
Ruhr Valley chemical manufacturers and Bavarian automotive clusters generate Europe's densest concentration of pollution control AI deployments. The EU Green Deal's CSRD disclosure mandates compress procurement timelines for integrated sustainability platforms. Berlin-based transmission operators deploy reinforcement learning for grid optimization under F-Gas Regulation pressures to minimize switchgear leakage.
China
Dual carbon goals and MEE enforcement protocols accelerate AI adoption across steel and cement production bases. Yangtze River Delta manufacturing hubs deploy machine learning for energy intensity reduction alongside provincial emissions trading schemes. Shenzhen and Shanghai smart city initiatives integrate environmental AI into urban resource optimization frameworks.
India
PLI scheme subsidies for clean technology manufacturing create entry points for energy optimization platforms in Gujarat and Tamil Nadu chemical parks. CEA grid codes mandate forecasting accuracy standards that wind and solar operators address through machine learning procurement. Maharashtra industrial corridors concentrate demand for predictive maintenance AI that cuts energy intensity.
Japan
METI carbon neutrality roadmaps mandate emissions reduction targets for steel and cement producers that predictive maintenance AI simultaneously addresses. Kanto region utilities deploy digital twin architectures for demand response simulation before physical grid upgrades. Osaka-based manufacturers integrate environmental AI with legacy SCADA systems through specialized middleware layers.
AI in Environmental Sustainability Market Competitive Landscape
Premium-margin players sit above commodity-margin players across the deployment complexity spectrum, with hyperscale cloud providers capturing efficiency-seeking mid-market buyers while specialized consultancies command premium pricing for legacy system integration. The vendor base stratifies into three tiers: infrastructure-anchored platforms, vertical-specialized application vendors, and systems integration consultancies. Consolidation pressure concentrates in the middle tier as cloud marketplaces displace direct procurement relationships. Dominant competitive moves include strategic partnerships between hardware sensor manufacturers and analytics platforms, plus geographic expansion into subsidy-backed industrial corridors.
Among hyperscale infrastructure providers, Microsoft Corporation and Amazon Web Services anchor cloud-based sustainability workloads for industrial clients seeking pre-integrated procurement channels. IBM Corporation occupies a position within the consultancy-heavy tier, exemplifying the legacy integration archetype that bridges machine learning models with established environmental databases. C3.ai represents the vertical-specialized application vendor, sitting within the pre-built AI segment targeting energy-intensive manufacturing deployments.
| Leading Market Players |
|---|
| Microsoft Corporation |
| IBM Corporation |
| Google LLC |
| Amazon Web Services |
| Siemens AG |
| Schneider Electric |
| Oracle Corporation |
| SAP SE |
| C3.ai |
| Others |
Pricing and Supply Chain Analysis
GPU and TPU chipset price indices from Taiwan-based foundries cascade through environmental AI supply chains, compressing margins for edge-deployed pollution monitoring systems while hyperscale cloud providers absorb volatility through volume purchasing power.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates enforcement-grade edge systems from cloud-based SaaS tools and open-source middleware. Price differentiation hinges on ISO 14001 certification tier and real-time latency guarantees under EPA alert mandates. Pricing pressure stems from Taiwan semiconductor supply concentration inflating field hardware costs. Mid-market renewable energy operators exhibit highest price sensitivity, while Gulf Coast petrochemical complexes accept premium tiers for compliance certainty.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for integrated sustainability platforms, while systems integrators serve legacy industrial retrofit projects. Hardware supply concentrates in Taiwan, South Korea, and USA for specialized AI chipsets. Component dependencies include NVIDIA GPU architectures, satellite imagery feeds, and industrial IoT sensor arrays. Single-source vulnerability in Taiwan-based foundry capacity creates procurement risk for distributed monitoring networks. Distribution runs through cloud marketplaces for mid-market segments and direct enterprise sales for compliance-critical deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Environmental AI vendors face a geographic-arbitrage play between German regulatory stringency and Indian subsidy-backed industrial corridors, where PLI scheme support cuts effective deployment costs by half relative to European compliance premiums.
For Market Incumbents: Hedge against hyperscale cloud commoditization by deepening proprietary data moats around sector-specific emissions baselines. Prioritize backward integration into sensor hardware partnerships to offset Taiwan chipset volatility. Defend margin position through ISO 14001-certified audit trail infrastructure that generic platforms cannot replicate. For New Entrants and Emerging Players: Enter via India PLI-subsidized chemical parks in Gujarat and Tamil Nadu, where procurement cycles remain less saturated than European markets. Target wildlife conservation applications funded by multilateral climate finance, a segment incumbent industrial vendors underserve. Pursue acoustic-sensor satellite convergence as a differentiated go-to-market angle. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier vertical specialists lack cloud marketplace presence and face displacement by AWS and Azure sustainability storefronts. Five-to-ten year viability favors platforms with immutable data lineage infrastructure for CSRD disclosure mandates. Acquisition targets include computer vision specialists with EPA enforcement relationships. Watch for EPA real-time monitoring rule expansion as inflection signal for flare detection system demand.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration with Legacy SCADA | Middleware development unlocks brownfield chemical and steel plant deployments in Germany's Ruhr Valley. |
| Geographic Expansion into India PLI Corridors | Gujarat and Tamil Nadu chemical parks offer subsidy-backed entry points for energy optimization vendors. |
| Strategic Partnership with Satellite Operators | Acoustic sensor fusion with orbital imagery opens conservation funding streams from multilateral climate mechanisms. |
| Acquisition of Computer Vision Specialists | EPA flare monitoring mandates create concentrated demand for visual emissions verification capabilities. |
| Green Certification Program for AI Workloads | ISO 14001-aligned data lineage addresses CSRD audit requirements cascading from EU Green Deal enforcement. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with sustainability officers at renewable energy firms, environmental compliance leads at petrochemical complexes, EPA enforcement coordinators, and cloud marketplace procurement managers. Secondary validation drew from EPA enforcement databases, EU CSRD implementation guidance, hyperscaler sustainability disclosure filings, and industrial emissions trading registries. Bottom-up deployment counts and top-down regulatory mandate scaling were triangulated to anchor market size estimates.
Comparable historical periods anchored the projection horizon across technology adoption curves from adjacent industrial software markets. Segmentation modeling covered application purpose, AI technology type, deployment mode, and end-user institutional category alongside regional regulatory framework clusters. CAGRs were derived from regression analysis of enforcement timeline compression and renewable energy procurement cycles. Forecast inputs included Taiwan semiconductor supply forecasts and EPA rulemaking calendars.
Inputs from EPA and EU regulatory filings were available through the study window; gaps in real-time edge deployment cost data from private industrial facilities introduce uncertainty bands around hardware-intensive pollution control projections. Forecasts reflect assumptions about CSRD disclosure timeline adherence and PLI scheme continuity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environment & Sustainability
Municipal Solid Waste Management Market
Environment & Sustainability
Water Quality Analyzer Market
Environment & Sustainability
China Cloud Seeding Market
Environment & Sustainability
Sewage Treatment Service Market
Environment & Sustainability
Global Waste Disposal Equipment Market
Environment & Sustainability
Global Microbiological Testing of Water Market
Environment & Sustainability
US Municipal Solid Waste Management Market
Environment & Sustainability
Global Indoor Air Quality Solutions Market
Environment & Sustainability
Carbon Monoxide Analyzers Market
Environment & Sustainability
Environmental Software Market
Environment & Sustainability
India Plastic Waste Management Market
Environment & Sustainability
Global SCADA in Water and Wastewater Management Market
Environment & Sustainability
Polyfluoroalkyl Substances (PFAS) Waste Management Market
Environment & Sustainability
Marine Waste Handling Equipment Market
Environment & Sustainability
Carbon-Aware Slot Booking and Delivery Windows Platforms Market
Environment & Sustainability
Wastewater Clarifier Market