
 Singapore Air Purifier Market | 2026-2036
Singapore Air Purifier Market Size, Share, and Industry Trends Forecast 2026-2036
Singapore Air Purifier Market Insights
Multi-source procurement for HEPA filtration media is recalibrating how Singapore distributors manage component inflows from regional suppliers. Dyson Ltd leverages its proprietary cyclone and filtration R&D to command premium positioning in the residential segment. Koninklijke Philips NV anchors its presence through extensive retail partnerships across electronics chains and e-commerce platforms. Daikin Industries Ltd extends its building systems expertise into integrated HVAC-purifier solutions for commercial developments.
An air purifier is an electromechanical device designed to remove particulate matter, volatile organic compounds, and biological contaminants from indoor air through forced circulation across filtration media, typically achieving CADR ratings of 240-400 cubic meters per hour for residential units. Its primary purpose is to maintain breathable indoor environments in enclosed spaces where natural ventilation proves inadequate or external pollution intrudes. Standalone and portable units dominate household sales due to plug-and-play deployment and minimal installation requirements, while HVAC-integrated systems capture margin pools in new commercial construction where building codes mandate centralized air handling. HEPA filter technology leads the technology dimension with established efficacy certification, though UV-C Light modules gain traction in hospital and school end-use settings where pathogen suppression ranks as a procurement priority.
Singapore's National Environment Agency sets ambient air quality benchmarks that directly influence building design standards and equipment specifications across the city-state. The Building and Construction Authority mandates Green Mark certification criteria incorporating indoor environmental quality metrics that drive specification of high-efficiency filtration in new developments. The Energy Market Authority oversees grid efficiency standards that constrain power consumption profiles for continuously operating units. Stakeholders must monitor how NEA haze advisories trigger demand surges and whether BCA code revisions will tighten filtration performance thresholds for commercial retrofits.
Market Dynamics
NEA haze advisories and BCA Green Mark certification mandates are compressing procurement cycles and elevating filtration performance thresholds across Singapore's built environment. Building operators now face simultaneous pressure to upgrade legacy systems and certify new installations.
Growth Catalysts
- Recurring transboundary haze episodes:Indonesian forest fire smoke triggers acute indoor air quality alerts. Residential and commercial buyers accelerate replacement cycles during PSI spikes.
- BCA Green Mark certification expansion:Indoor environmental quality credits now require documented filtration efficacy. Developers specify certified units to secure building ratings.
- UV-C Light module integration:Healthcare and education facilities prioritize pathogen suppression. Hospitals retrofit wards with combined HEPA-UV systems.
Market Restraints
- HEPA media import concentration:Singapore distributors rely on limited regional suppliers for filtration substrate. Disruptions in Malaysian or Indonesian component flows stall assembly lines.
- Energy consumption constraints:EMA grid efficiency standards cap continuous operating power. Premium high-CADR units face deployment friction in price-sensitive segments.
- Filter replacement cost burden:Annual consumables expenditure often exceeds 40% of unit purchase price. Households defer upgrades to avoid recurring outlays.
Strategic Opportunities
- HVAC-integrated system penetration:New commercial construction mandates centralized air handling. System integrators capture margin pools in premium CBD developments.
- Subscription filter replacement services:E-commerce platforms automate consumable replenishment. Direct-to-consumer channels bypass traditional electronics retail.
- Sensor-enabled predictive maintenance:IoT modules monitor filter saturation and air quality metrics. Facility managers optimize replacement timing and reduce waste.
Industry Challenges
- CADRA certification timeline compression:Third-party testing facilities face backlog during haze season. Product launches delay as queue times extend.
- Cross-border component documentation:Regional suppliers struggle with consistent material traceability. NEA verification requirements reject non-compliant shipments.
- Skilled installation technician scarcity:Commercial HVAC-purifier integration demands specialized expertise. Training pipelines lag behind retrofit demand.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Singapore Air Purifier Market |
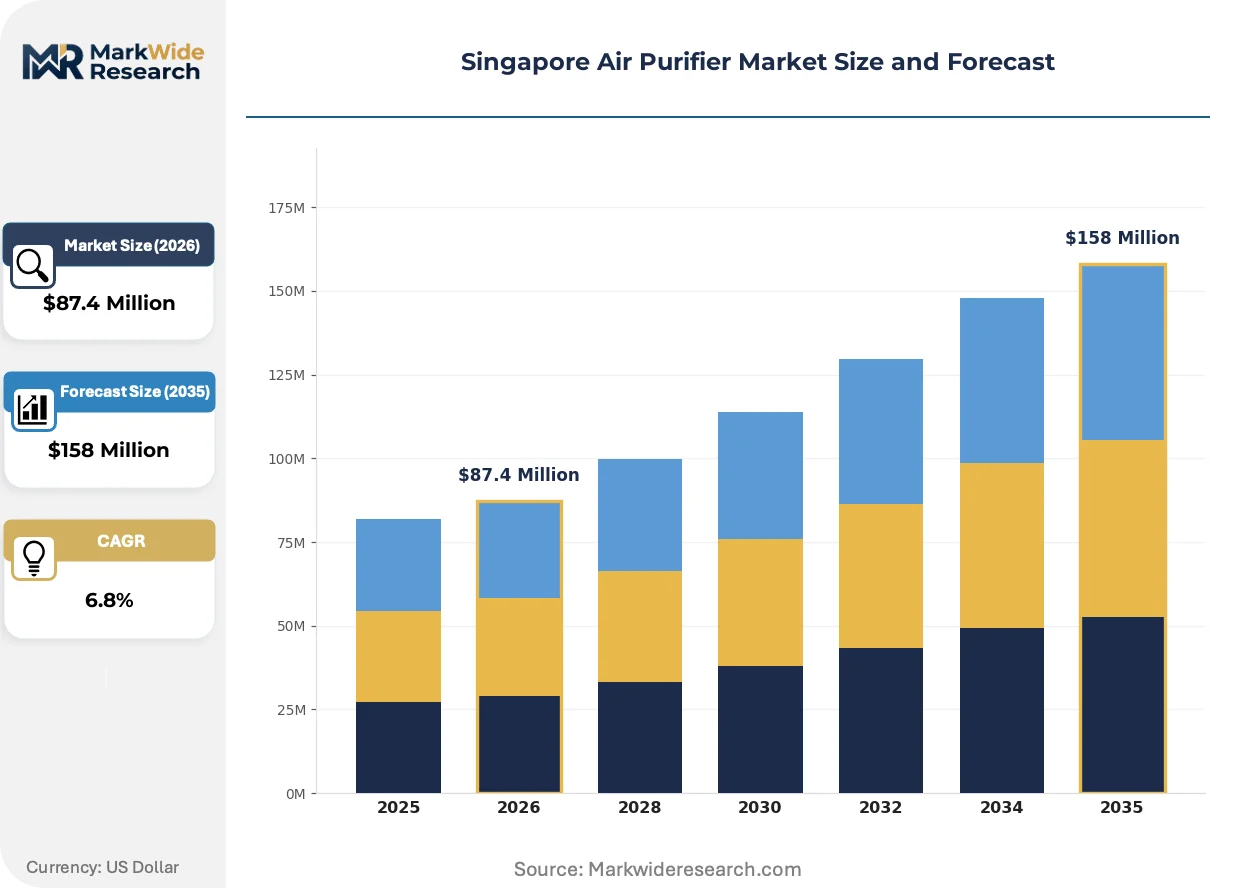
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $158 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone, Portable, HVAC Systems, Integrated Technology: HEPA Filter, Activated Carbon, UV-C Light, Ionizer Application: Residential, Commercial, Industrial, Automotive End User: Households, Offices, Hospitals, Schools |
| Companies Covered | Dyson Ltd, Koninklijke Philips NV, Daikin Industries Ltd, IQAir, Samsung Electronics Co Ltd, LG Electronics Inc, Sharp Corporation, WINIX Inc, Panasonic Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Singapore Air Purifier Market Trends and Innovations
Singapore's air purifier sector is consolidating around intelligent filtration systems that merge hardware performance with data-driven service models. Technology vendors and building operators are renegotiating their value exchange.
Smart filtration platforms are unifying particulate sensing, filter monitoring, and automated airflow adjustment into single-device architectures. Premium residential developments in the Orchard Road corridor specify these systems as standard fit-outs. The technology is unifying what were previously separate hardware and service revenue streams into recurring subscription relationships.
NEA indoor air quality guidelines are tightening enforcement mechanisms for commercial premises above 5,000 square meters. Building operators must now submit quarterly filtration performance audits. Food and beverage establishments in high-traffic zones are accelerating HVAC-purifier upgrades to pre-empt inspection failures.
Corporate procurement teams are consolidating vendor relationships through framework agreements covering multiple properties. Real estate investment trusts with portfolios across the Central Region negotiate volume pricing and standardized maintenance protocols. This concentration is visible in the CBD, where facility managers prioritize single-source accountability over fragmented point solutions.
Singapore Air Purifier Market Segmentation
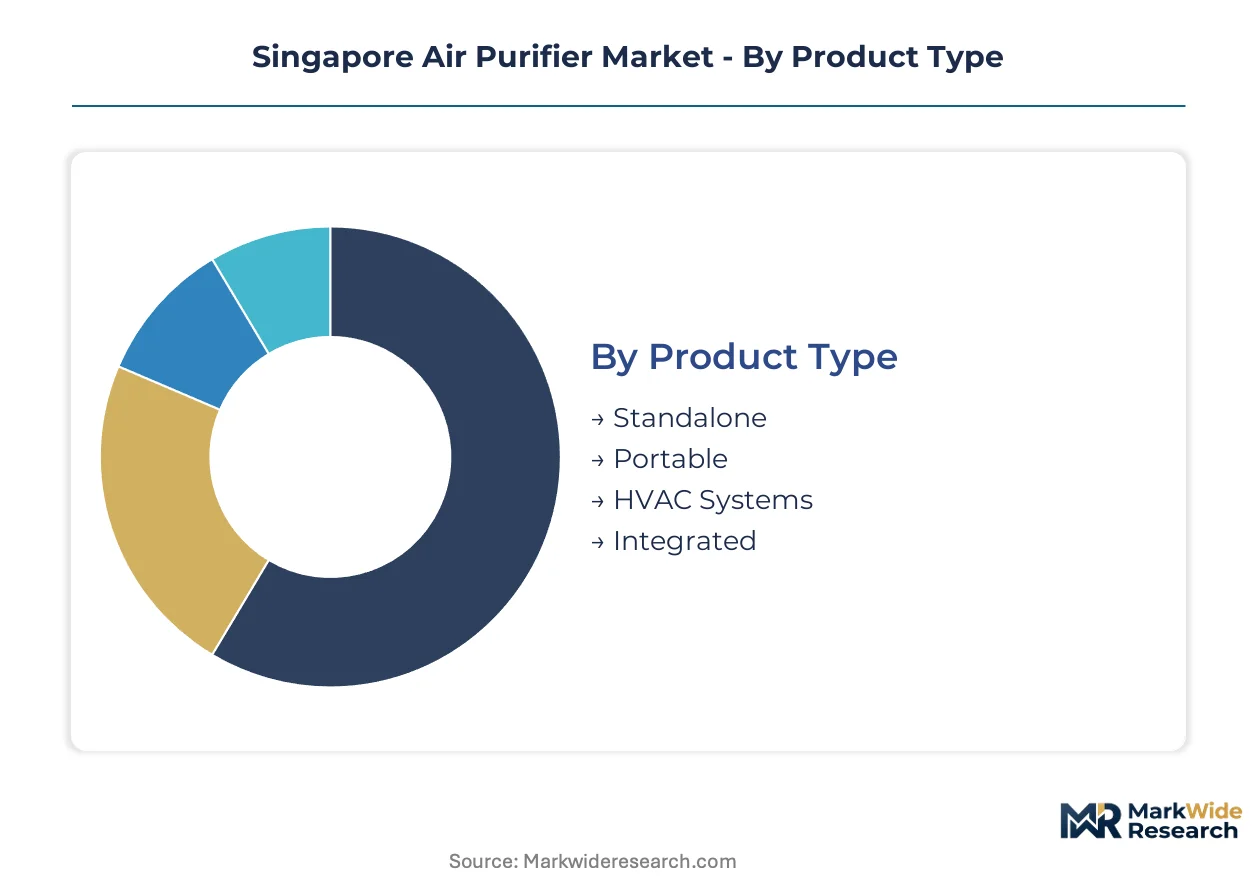
Singapore's air purifier market fragments across four distinct dimensions that shape procurement behavior and margin structures. Product architecture determines installation complexity and replacement economics. Technology choice reflects efficacy certification requirements against pathogen suppression priorities. Application context separates plug-and-play household deployment from integrated building system mandates. End-user concentration in the Central Region drives specification clustering around NEA compliance thresholds.
Product Type:
Standardization dominates portable and standalone categories, while HVAC-integrated systems demand deep customization to building infrastructure.
- Standalone:Fixed-position units with CADR ratings of 240-400 cubic meters per hour serve living rooms and master bedrooms. Demand concentrates in HDB estates and condominium clusters in Tampines and Jurong West during haze advisories. NEA indoor air quality guidelines compel households to maintain continuous operation during PSI spikes.
- Portable:Lightweight units with casters and plug-and-play deployment dominate rental households and temporary workspace configurations. Offices in the CBD deploy these for hot-desking zones where permanent installation proves impractical. BCA Green Mark certification credits now document portable unit efficacy for commercial retrofits.
- HVAC Systems:Centralized filtration modules integrate with building air handling infrastructure.
- Integrated:Multi-zone architectures unify sensing, filtration, and climate control through single management platforms.
Leading the category by volume: Standalone. Expanding most quickly: HVAC Systems.
Technology:
Cost tiers separate certified HEPA media from emerging UV-C modules, with activated carbon occupying a mid-tier positioning for odor-specific applications.
- HEPA Filter:Pleated mechanical media capturing 99.97% of particles at 0.3 microns remains the baseline specification for residential and commercial procurement. Singapore distributors source substrate primarily from Malaysian suppliers, creating concentration risk during regional supply disruptions. NEA verification requirements reject non-compliant shipments lacking material traceability documentation.
- UV-C Light:Germicidal irradiation modules at 253.7 nanometers destroy pathogen DNA in healthcare and education settings. Hospitals in the Novena medical cluster retrofit wards with combined HEPA-UV systems to suppress nosocomial transmission. Installation technician scarcity delays deployment timelines despite acute demand.
- Activated Carbon:Porous carbon pellets adsorb volatile organic compounds and cooking odors in food and beverage establishments.
- Ionizer:Electrostatic precipitation generates charged particles that settle on surfaces rather than filtering air directly.
Dominating procurement by certification compliance: HEPA Filter. Gaining share fastest: UV-C Light.
Application:
Customer type separates price-sensitive residential replacement cycles from specification-driven commercial mandates with documented performance audits.
- Residential:Urban households in high-density towers prioritize indoor air quality amid recurring transboundary haze. Orchard Road corridor premium developments specify smart filtration platforms as standard fit-outs. Filter replacement cost burden often exceeds 40% of unit purchase price, causing deferred upgrades.
- Commercial:Building operators above 5,000 square meters face quarterly filtration performance audits under tightened NEA enforcement. Food and beverage establishments in high-traffic zones accelerate HVAC-purifier upgrades to pre-empt inspection failures. Corporate procurement teams consolidate vendor relationships through multi-property framework agreements.
- Industrial:Manufacturing facilities with process-specific contamination requirements deploy heavy-duty extraction systems.
- Automotive:Cabin air filtration in premium vehicle segments addresses commuter exposure during peak haze periods.
Generating highest unit volume: Residential. Steepest expansion trajectory: Commercial.
End User:
Geography concentrates demand in the Central Region, where high-density commercial towers and premium residential developments cluster around the CBD.
- Households:Multi-generational units in mature estates like Toa Payoh and Ang Mo Kio drive replacement demand during PSI alerts. E-commerce platforms automate filter replenishment through subscription services, bypassing traditional electronics retail. Annual consumables expenditure creates sticker shock that stalls upgrade decisions.
- Offices:Real estate investment trusts with portfolios across Marina Bay and Raffles Place negotiate volume pricing and standardized maintenance protocols. Facility managers prioritize single-source accountability over fragmented point solutions. IoT-enabled predictive maintenance optimizes replacement timing and reduces waste.
- Hospitals:Acute care facilities in the Novena and Outram clusters mandate combined HEPA-UV systems for ward retrofits.
- Schools:Ministry of Education institutions specify pathogen suppression capabilities for classroom deployment.
Commanding largest installed base: Households. Climbing the fastest: Offices.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Malaysian filtration substrate suppliers anchor component inflows into Singapore's assembly ecosystem. HEPA media concentration across the Johor Strait creates vulnerability during regional supply disruptions.
Central Region
High-density commercial towers around Marina Bay and Raffles Place drive specification clustering for integrated HVAC-purifier systems. NEA quarterly filtration performance audits compel building operators above 5,000 square meters to maintain documented efficacy records. Orchard Road corridor premium residential developments specify smart filtration platforms as standard fit-outs.
East Region
Tampines and Bedok HDB estates generate concentrated replacement demand during PSI spikes from transboundary haze. Households in mature public housing prioritize plug-and-play standalone units with CADR ratings of 240-400 cubic meters per hour. E-commerce subscription services automate filter replenishment for multi-generational units.
West Region
Jurong West and Jurong East condominium clusters experience acute demand surges coinciding with NEA haze advisories. Jurong Island industrial facilities with process-specific contamination requirements deploy heavy-duty extraction systems separate from consumer-grade procurement cycles. BCA Green Mark certification mandates influence new development specifications.
North Region
Woodlands and Yishun residential zones exhibit price-sensitive procurement patterns where filter replacement cost burden stalls upgrade decisions. Ang Mo Kio mature estates drive replacement cycles for aging standalone units. Ministry of Education institutions in the northern corridor specify pathogen suppression capabilities for classroom deployment.
Novena Medical Cluster
Acute care facilities in the Novena and Outram districts mandate combined HEPA-UV systems for ward retrofits. Hospital procurement teams prioritize germicidal irradiation modules at 253.7 nanometers to suppress nosocomial transmission. Installation technician scarcity delays deployment timelines despite acute demand from healthcare operators.
Singapore Air Purifier Market Competitive Landscape
Global majors compete with regional champions across distribution channel architecture in Singapore's air purifier sector. The vendor base stratifies into three tiers: premium technology licensors with proprietary R&D, mass-market electronics conglomerates with retail scale, and specialized filtration pure-plays with certification depth. Strategic moves concentrate on HVAC integration partnerships and direct-to-consumer channel bypass.
Among premium-tier technology vendors, Dyson Ltd and Koninklijke Philips NV occupy positions defined by cyclone filtration R&D and retail partnership density respectively. Daikin Industries Ltd exemplifies the building systems integrator archetype, extending climate control expertise into centralized air handling solutions. These three anchors represent distinct competitive vectors: proprietary hardware, channel ubiquity, and infrastructure integration.
| Leading Market Players |
|---|
| Dyson Ltd |
| Koninklijke Philips NV |
| Daikin Industries Ltd |
| IQAir |
| Samsung Electronics Co Ltd |
| LG Electronics Inc |
| Sharp Corporation |
| WINIX Inc |
| Panasonic Corporation |
| Others |
Pricing and Supply Chain Analysis
Corporate real estate investment trusts with multi-property portfolios across Singapore's Central Region negotiate framework agreements that anchor contract-based long-term procurement pricing. Their volume concentration shifts bargaining power toward standardized maintenance protocols and single-source accountability rather than fragmented point solutions.
Pricing Analysis
Warranty and filter replacement bundling separates premium positioning from unbundled economy tiers. Three-tier pricing structure across premium, standard, and economy levels reflects CADR performance certification and after-sales service inclusion. Cost compression in the portable segment intensifies as e-commerce platforms automate consumable replenishment and bypass traditional electronics retail. Households in mature HDB estates exhibit highest price sensitivity due to annual consumables expenditure exceeding initial unit costs, while integrated HVAC-purifier specifications in CBD commercial towers show lowest sensitivity.
Supply Chain Analysis
Dual-sourcing qualification requirements from NEA verification protocols compel distributors to maintain redundant HEPA media suppliers across Malaysia and Indonesia. Assembly operations draw from Malaysian filtration substrate, Indonesian carbon pellet feedstock, and Chinese UV-C diode components. Single-source vulnerability concentrates in Malaysian pleated mechanical media during regional haze season demand spikes. Distribution runs through electronics chains and direct-to-consumer e-commerce platforms with increasing subscription service penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Singapore's air purifier market operates as a supply-constrained environment where installation technician scarcity props pricing for commercial HVAC-purifier integration. Capacity bottlenecks in skilled labor create defendable margin pools for qualified system integrators.
For Market Incumbents: Extend certification depth into combined HEPA-UV systems to capture hospital ward retrofit demand in the Novena medical cluster. Build captive supply of filtration media through backward integration into Malaysian substrate operations to offset regional supply disruption risk. Channel control through direct-to-consumer subscription platforms defends against e-commerce platform disintermediation.
For New Entrants and Emerging Players: E-commerce platforms represent the most penetrable channel for subscription filter replacement services targeting multi-generational households in Tampines and Jurong West. White-space exists in sensor-enabled predictive maintenance for facility managers seeking optimized replacement timing. Food and beverage establishments in high-traffic zones offer specification entry points through BCA Green Mark certification compliance.
For Investors and Strategic Acquirers: The window for entry favors specialized filtration pure-plays with NEA certification depth and established regional supplier relationships. Long-term viability hinges on HVAC integration partnerships with premium CBD developers rather than standalone residential hardware. The signal to watch is BCA code revisions tightening filtration performance thresholds for commercial retrofits above 5,000 square meters.
| Strategic Initiative | Industry Significance |
|---|---|
| Subscription Filter Replacement Service | E-commerce platforms automate consumable replenishment for HDB households in Tampines and Bedok. |
| HVAC-Purifier Integration Partnership | System integrators capture margin pools in Marina Bay and Raffles Place commercial developments. |
| Sensor-Enabled Predictive Maintenance | IoT modules optimize filter replacement timing for facility managers under NEA quarterly audit requirements. |
| Combined HEPA-UV Certification Investment | Hospitals in Novena and Outram clusters mandate germicidal irradiation for nosocomial transmission suppression. |
| Regional Supplier Qualification Expansion | Dual-sourcing Malaysian and Indonesian filtration substrate reduces concentration risk during haze season spikes. |
Research Methodology
Document review covered NEA indoor air quality guidelines, BCA Green Mark certification criteria, and EMA grid efficiency standards, complemented by interviews with facility managers at commercial developments above 5,000 square meters, procurement leads at real estate investment trusts, HVAC system integrators in the CBD corridor, and distributors managing regional component inflows. Secondary validation drew from customs records tracking Malaysian and Indonesian filtration substrate shipments, electronics chain retail audit data, and hospital procurement databases in the Novena medical cluster. Bottom-up unit shipment estimates triangulated against top-down market value reconstruction.
Segment-level projections across product type, technology, application, and end user dimensions produced volume and value trajectories throughout the forecast period. The analytical framework modeled residential replacement cycles against PSI alert frequency, commercial retrofit mandates under tightened enforcement mechanisms, and healthcare facility pathogen suppression priorities. CAGRs derived from regression analysis of historical demand elasticity during transboundary haze episodes and correlation with BCA certification expansion timelines.
Caveats apply where NEA haze advisory frequency, BCA code revision timing, or regional supply disruption severity could materially shift the outlook. Deviation in Malaysian filtration substrate export restrictions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Air Quality Control Systems
Green Emissions Analyzers Market
Air Quality Control Systems
Middle-East and Africa Industrial Air Quality Control Systems Market
Air Quality Control Systems
Europe Industrial Air Quality Control Systems Market
Air Quality Control Systems
Indoor Air Purification Market
Air Quality Control Systems
Asia-Pacific Indoor Air Purification Market
Air Quality Control Systems
Air Pollution Control Equipment Market
Air Quality Control Systems
Desiccant Air Breather Market
Air Quality Control Systems
Air Quality Control Systems Market
Air Quality Control Systems
Southeast Asia Air Purifier Market
Air Quality Control Systems
Emission Management Software Market
Air Quality Control Systems
Anti-Pollution Toner Market
Air Quality Control Systems
Environmental Control System (ECS) Market
Air Quality Control Systems
Air Quality Monitoring Software Market
Air Quality Control Systems
Nitrogen Oxide Control Systems Market
Air Quality Control Systems
Asia-Pacific Air Quality Control System Market
Air Quality Control Systems
Sustainable Air Filter Market