
 Smart Waste Sorting Bin Market | 2026-2036
Smart Waste Sorting Bin Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Waste Sorting Bin Market Insights
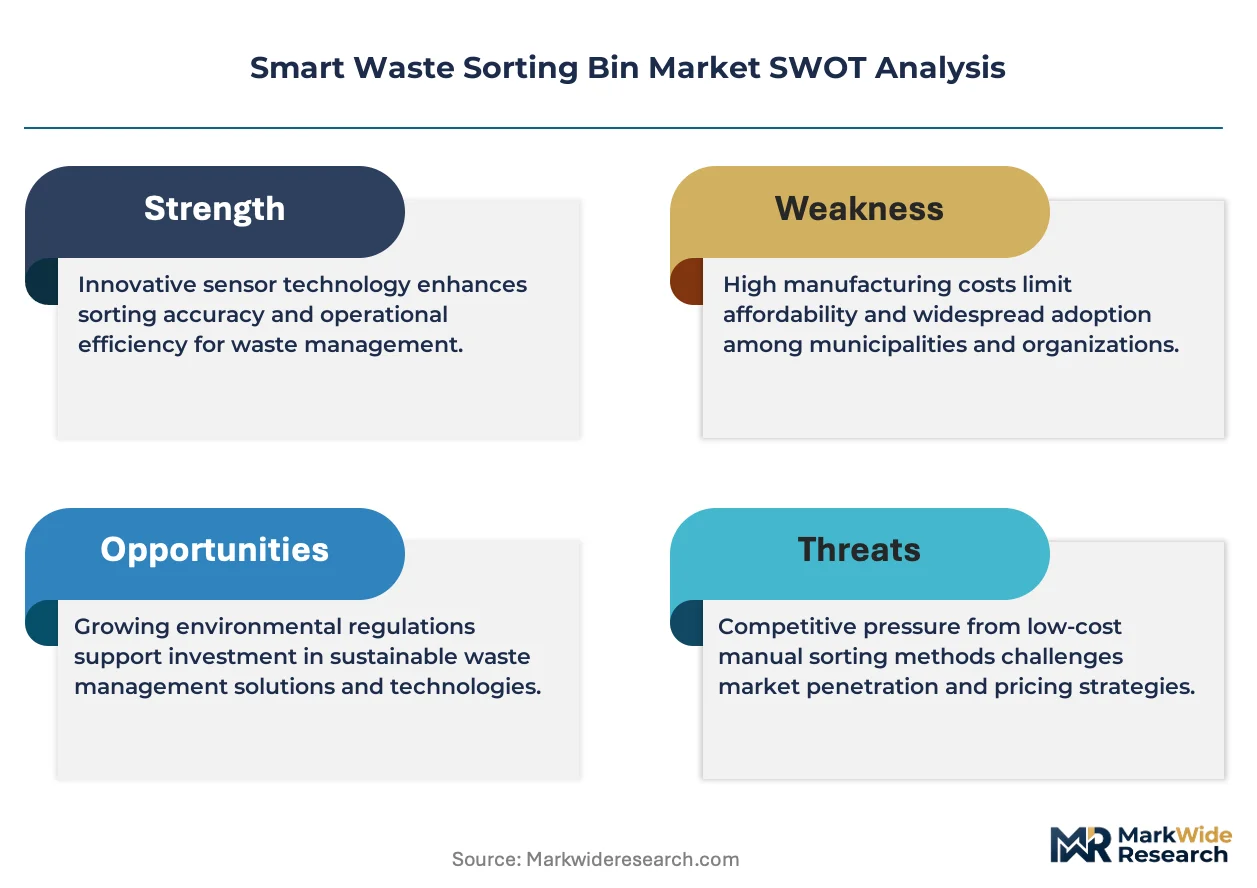
The EU Green Deal is realigning the cost-of-entry calculus for smart waste sorting bin vendors across European municipalities. Bigbelly leverages its solar-compaction heritage to anchor municipal contracts in dense urban corridors. CleanRobotics specializes in AI-powered sorting accuracy, differentiating its TrashBot systems for high-contamination waste streams. Evreka sustains its position through integrated software-hardware platforms that control fleet logistics and fill-level monitoring across Turkish and Middle Eastern deployments.
A smart waste sorting bin is an electromechanical receptacle equipped with computer vision, weight sensors, and wireless connectivity to automatically identify, classify, and route discarded materials into segregated compartments. These units typically incorporate near-infrared spectroscopy or convolutional neural networks to distinguish plastics by resin code, with compaction mechanisms reducing collection frequency by up to eighty percent. Commercial installations currently dominate unit shipments, as office complexes and retail parks seek to reduce contamination penalties under extended producer responsibility schemes. AI-powered technology segments command premium positioning due to higher sorting precision and reduced manual oversight, while sensor-based units occupy mid-tier municipal tenders where budget constraints limit computational investment.
The EPA's waste reduction targets and state-level bottle bill expansions in California and Oregon shape procurement specifications for North American vendors. BIS certification requirements in India and China's GB standards for smart city infrastructure create parallel compliance tracks for manufacturers seeking Asian market access. Stakeholders must monitor how fragmented national e-waste directives evolve into harmonized testing protocols, as this convergence will determine which sensor and AI architectures achieve cross-border scale.
Market Dynamics
The EU Green Deal's waste hierarchy mandates are compressing landfill diversion timelines and forcing municipalities to accelerate AI-powered sorting infrastructure procurement, fundamentally altering vendor qualification criteria and contract structures.
Growth Catalysts
- Extended Producer Responsibility Schemes:Office complexes and retail parks across Germany face contamination penalties under the Packaging Act, driving demand for automated sorting accuracy.
- Solar-Compaction Integration:Dense urban corridors deploy electromechanical receptacles with photovoltaic power and wireless fill-level monitoring to reduce collection frequency.
- Near-Infrared Spectroscopy:Convolutional neural networks now distinguish plastics by resin code in high-contamination waste streams, enabling premium positioning for AI-powered segments.
Market Restraints
- Sensor Component Concentration:Supply of weight sensors and computer vision modules concentrates among East Asian contract manufacturers, creating single-source vulnerability.
- GB Standards Compliance Costs:China's smart city infrastructure certification requires parallel testing tracks, extending product validation cycles for vendors seeking Asian market access.
- Manual Sorting Substitution:Informal waste picker networks in emerging economies undercut automated solutions on labor cost, limiting price-competitive deployment.
Strategic Opportunities
- Dual Systems Payment Flows:Germany's structured material recovery compensation creates predictable revenue streams for sorted output, anchoring vendor business models.
- AI-Logistics Convergence:Integration of fleet management software with hardware platforms controls collection routing across Turkish and Middle Eastern deployments.
- State-Level Bottle Bill Expansion:California and Oregon procurement specifications reward sorting precision, opening municipal tender opportunities for computer vision-enabled units.
Industry Challenges
- Fragmented E-Waste Directives:Divergent national testing protocols for sensor architectures and AI modules complicate cross-border product standardization.
- Legacy Bin Integration:Retrofitting existing municipal waste infrastructure with automated routing and wireless connectivity requires custom mechanical adapters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Waste Sorting Bin Market |
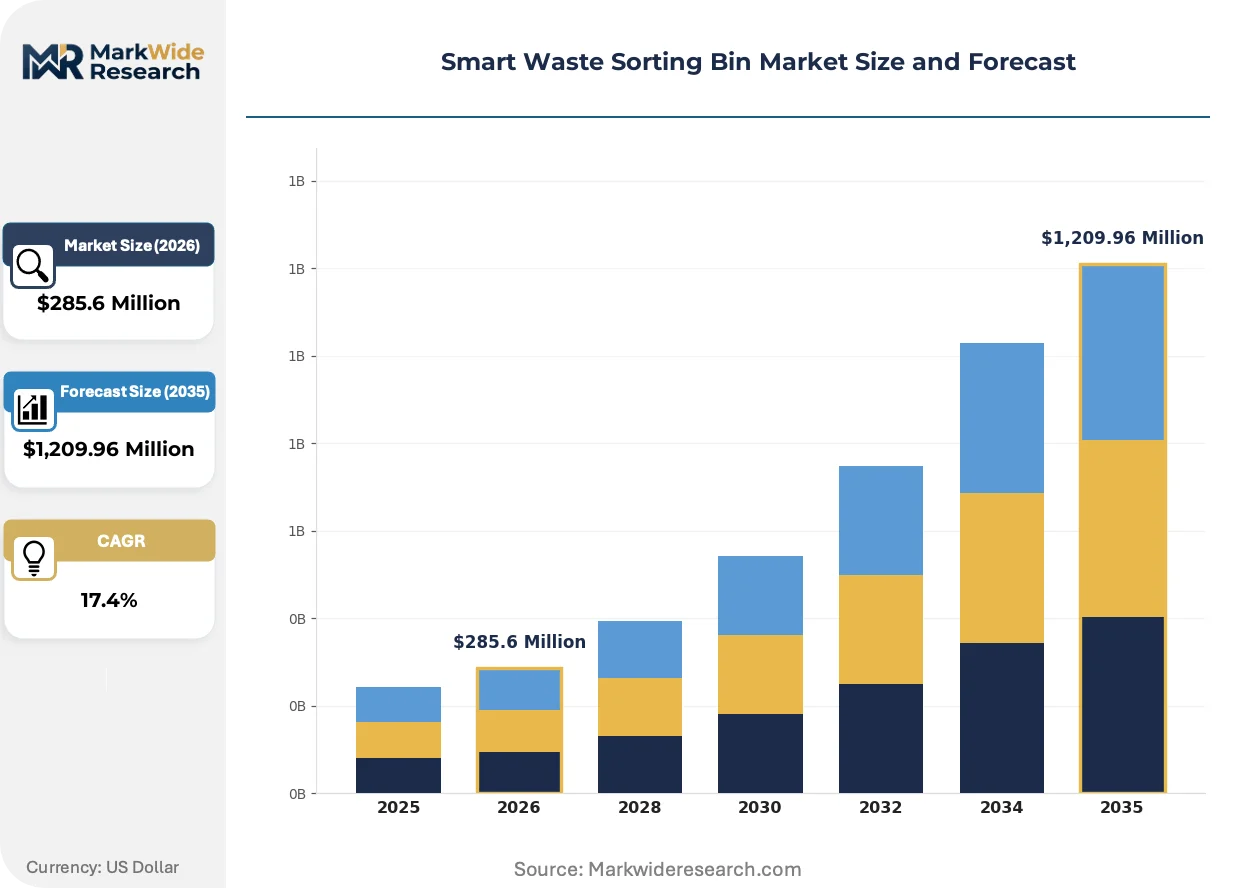
| Market Size in 2026 | $285.6 Million |
| Market Size in 2035 | $1,209.96 Million |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Residential, Commercial, Industrial, Public Spaces Technology: AI-Powered, Sensor-Based, IoT-Enabled, Manual End User: Municipalities, Waste Management Companies, Retailers, Households Installation: Ground Mounted, Wall Mounted, Mobile Units, Integrated Systems |
| Companies Covered | Bigbelly, Ecube Labs, iTouchless Housewares and Products, Simplehuman, CleanRobotics, Evreka, Compology, BIN-e, Ausko Pte Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Waste Sorting Bin Market Trends and Innovations
Computer vision algorithms and electromechanical routing systems are actively displacing static receptacle designs, while regulatory pressure on contamination rates compresses acceptable error margins for material classification.
Convolutional neural networks with near-infrared spectroscopy cores are expanding into high-throughput commercial installations. Airport terminals and convention centers in the United States adopt these systems to meet EPA waste reduction targets. The technology is expanding into mid-tier municipal tenders previously served by basic sensor-based units, compressing price positioning across hardware tiers.
REACH compliance requirements for electronic waste processing are tightening material traceability obligations across European deployments. Vendors must document resin-code accuracy and end-of-life disposal pathways for embedded sensors. Germany's dual systems operators now mandate certification documentation as a contract precondition, filtering out uncertified hardware providers.
Buyer preference is consolidating around integrated software-hardware platforms that bundle fill-level monitoring with collection logistics. Municipal procurement teams in North America disaggregate traditional equipment-only contracts in favor of performance-based service agreements. This pattern is most visible in Oregon state tenders, where outcome metrics for contamination reduction determine vendor selection over unit price alone.
Smart Waste Sorting Bin Market Segmentation
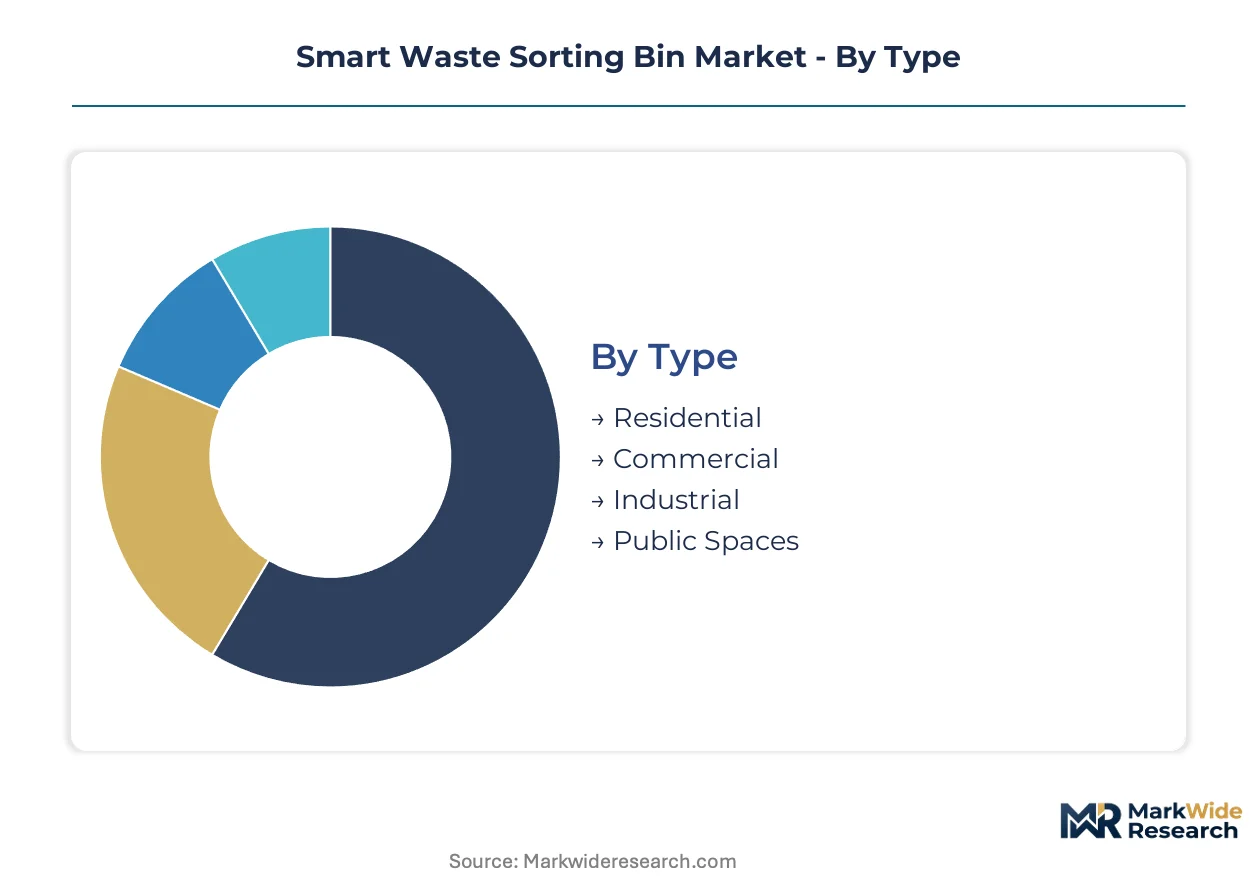
Segmentation in smart waste sorting bins reveals how technology tier and deployment context determine procurement economics. Municipal buyers prioritize integrated platforms with logistics software, while commercial operators emphasize contamination reduction to avoid extended producer responsibility penalties.
Technology:
Computer vision depth and sensor fusion density separate premium positioning from commodity tiers in vendor qualification protocols.
- AI-Powered:Convolutional neural networks with near-infrared spectroscopy distinguish plastics by resin code in high-contamination streams. Germany's Packaging Act mandates drive municipal procurement here, as dual systems operators require certified sorting accuracy for material recovery compensation. Contamination penalties under extended producer responsibility schemes compress acceptable error margins below three percent.
- Sensor-Based:Weight sensors and fill-level monitors without AI classification occupy mid-tier tenders where budget constraints limit computational investment. Turkish municipalities deploy these units for fleet logistics integration through Evreka's software-hardware platforms, prioritizing collection frequency reduction over material purity.
- IoT-Enabled:Wireless connectivity modules transmit compaction status and route optimization data to centralized fleet management systems.
- Manual:Basic electromechanical routing without automated classification serves price-sensitive deployments in emerging economies where informal waste picker networks dominate labor economics.
Mature deployment sits with Sensor-Based units in Turkish and Middle Eastern logistics networks. Newer deployment is concentrated in AI-Powered systems across German and North American municipal corridors.
Type:
Volume throughput and contamination exposure shape hardware specification requirements across installation environments.
- Commercial:Office complexes and retail parks in California and Oregon face contamination penalties under state-level bottle bill expansions, demanding automated sorting accuracy. Bigbelly anchors contracts in dense urban corridors with solar-compaction heritage, reducing collection frequency by up to eighty percent through photovoltaic power integration.
- Public Spaces:Airport terminals and convention centers adopt high-throughput electromechanical receptacles to meet EPA waste reduction targets. Near-infrared spectroscopy cores expand into these installations previously served by basic sensor units, compressing price positioning across hardware tiers.
- Residential:Single-family and multi-unit housing deployments emphasize compact footprints and wireless fill-level monitoring for municipal collection optimization.
- Industrial:Manufacturing facilities and distribution centers require heavy-duty routing mechanisms for bulk material streams with predictable composition profiles.
Commercial installations command premium positioning through performance-based service agreements. Residential procurement remains equipment-focused with shorter contract horizons.
End User:
Contract structure and outcome accountability diverge sharply between public procurement and private operational control.
- Municipalities:North American procurement teams disaggregate traditional equipment-only contracts in favor of outcome metrics for contamination reduction. Oregon state tenders determine vendor selection based on sorting precision rather than unit price alone.
- Waste Management Companies:Fleet operators integrate fill-level monitoring with collection logistics across Turkish deployments, controlling routing through software-hardware convergence.
- Retailers:Extended producer responsibility schemes in Germany create structured payment flows for sorted material recovery, anchoring vendor business models in predictable revenue streams.
- Households:Direct consumer purchases concentrate in premium residential installations with aesthetic integration and mobile app connectivity.
Waste Management Companies represent the fastest-growing trajectory as logistics integration becomes a procurement prerequisite. Municipalities retain the largest installed base with longest replacement cycles.
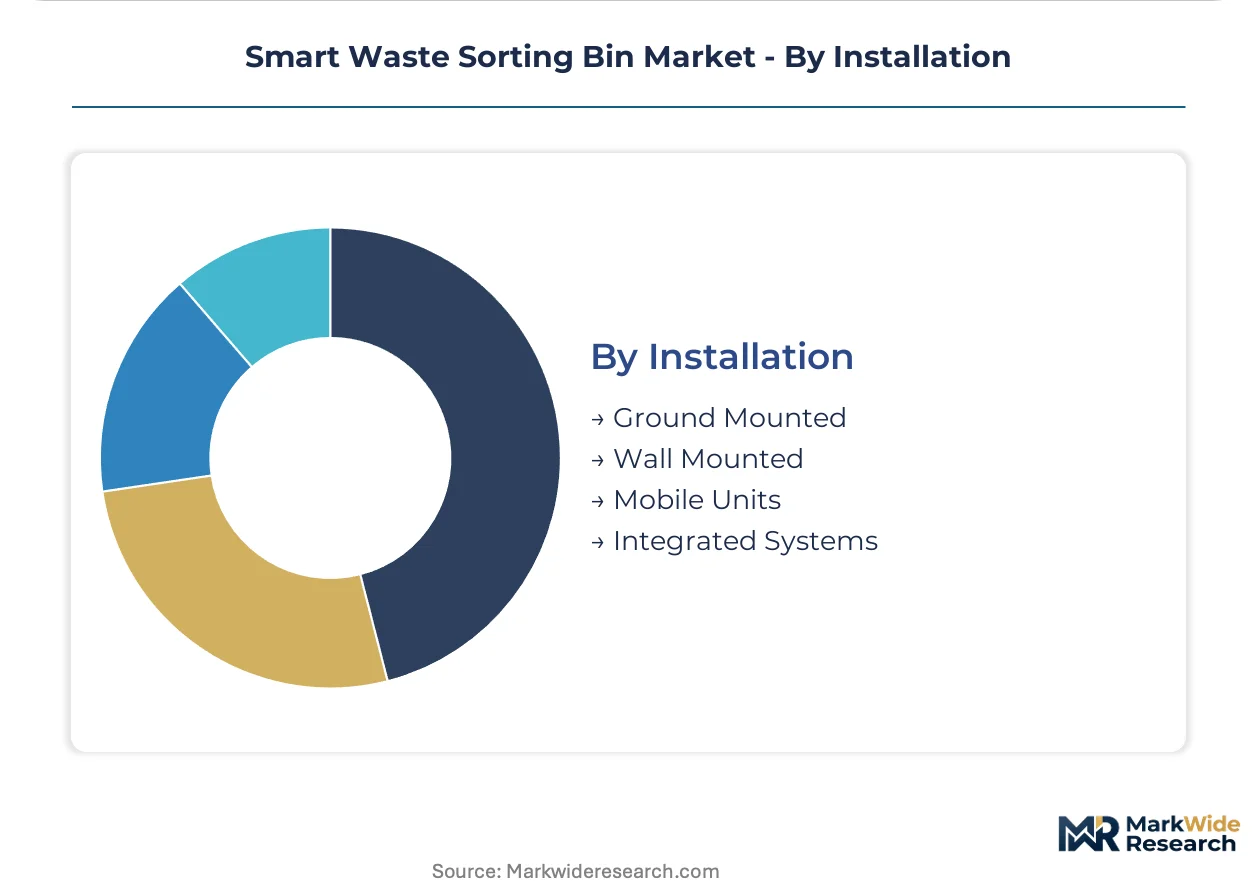
Installation:
Physical mounting constraints determine solar exposure, connectivity reliability, and mechanical routing complexity.
- Ground Mounted:Standard electromechanical receptacles with photovoltaic panels and wireless modules dominate municipal sidewalk and park deployments across German cities.
- Integrated Systems:Built-in architectural installations serve airport terminals and convention centers with concealed routing mechanisms and centralized waste chutes.
- Wall Mounted:Compact units with limited compaction capacity target retail interiors and office building common areas with space constraints.
- Mobile Units:Temporary deployments for events and construction sites prioritize rapid relocation over permanent connectivity infrastructure.
Ground Mounted systems anchor municipal procurement with proven solar-compaction economics. Integrated Systems are gaining share fastest in high-throughput commercial specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free economic zones in the UAE and Saudi Arabia concentrate smart city infrastructure investment, accelerating procurement timelines for AI-powered waste management systems across Middle Eastern municipal corridors.
United States
California and Oregon procurement specifications reward computer vision-enabled sorting precision under state-level bottle bill expansions. EPA waste reduction targets shape municipal tender requirements. Greater Boston anchors dense urban deployments with solar-compaction heritage contracts reducing collection frequency.
Germany
The Packaging Act and dual systems create structured payment flows for sorted material recovery, anchoring vendor business models in predictable revenue streams. EU Green Deal waste hierarchy mandates compress landfill diversion timelines. Bavarian municipalities lead AI-powered infrastructure procurement with certified sorting accuracy requirements below three percent contamination.
China
GB standards for smart city infrastructure certification extend product validation cycles for vendors seeking Asian market access. MIIT digital infrastructure programs channel investment toward integrated software-hardware platforms. Yangtze River Delta clusters concentrate manufacturing of weight sensors and computer vision modules.
Turkey
Municipalities deploy sensor-based units for fleet logistics integration through software-hardware platforms, prioritizing collection frequency reduction over material purity. Evreka sustains position controlling routing across Turkish and Middle Eastern deployments. Istanbul anchors procurement concentration with integrated fill-level monitoring systems.
India
BIS certification requirements create parallel compliance tracks for manufacturers seeking market access. Smart city mission programs accelerate municipal procurement of electromechanical receptacles with wireless connectivity. Maharashtra and Karnataka sub-regions concentrate pilot deployments of AI-powered sorting infrastructure.
Smart Waste Sorting Bin Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across technology tiers, producing a bifurcated structure where solar-compaction heritage anchors municipal contracts and AI-sorting precision commands premium positioning. The vendor base clusters around three strategic archetypes: integrated software-hardware platform operators, computer vision specialists, and solar-powered compaction legacy providers. Dominant competitive moves include strategic partnerships with dual systems operators and geographic expansion through certified compliance with national smart city standards.
Within the AI-powered sorting tier, CleanRobotics exemplifies convolutional neural network specialization for high-contamination waste streams, while Evreka occupies a position exemplifying integrated logistics-software convergence across Turkish deployments. Bigbelly anchors the solar-compaction heritage archetype in dense North American urban corridors. These three represent distinct competitive vectors: algorithmic precision, fleet management integration, and photovoltaic power heritage.
| Leading Market Players |
|---|
| Bigbelly |
| Ecube Labs |
| iTouchless Housewares and Products |
| Simplehuman |
| CleanRobotics |
| Evreka |
| Compology |
| BIN-e |
| Ausko Pte Ltd |
| Others |
Pricing and Supply Chain Analysis
Municipal procurement teams in Germany and North America anchor pricing power through multi-year performance-based service agreements, compressing transactional equipment sales into subscription models that bundle hardware, software, and maintenance. This buyer concentration forces vendors to absorb upfront sensor and AI module costs while recovering margins through contamination-reduction outcome fees.
Pricing Analysis
Short lead-time premiums apply to AI-powered units with near-infrared spectroscopy cores, while spot inventory of sensor-based mid-tier hardware trades at discounts. Three-tier pricing structure across premium, standard, and economy levels separates certified sorting accuracy above three percent contamination from uncertified units. Cost compression in the sensor-based tier is intensifying because Turkish and Middle Eastern municipalities prioritize fleet logistics over material purity. Waste management companies show highest price sensitivity due to thin collection margins, whereas German dual systems operators accept premium positioning for certified resin-code accuracy.
Supply Chain Analysis
Dual-sourcing requirements from North American and European procurement teams mandate qualified suppliers for weight sensors and computer vision modules across China, South Korea, and Taiwan. Component sourcing draws from Yangtze River Delta clusters for electromechanical routing mechanisms and photovoltaic integration subsystems. Single-source vulnerability concentrates in near-infrared spectroscopy cores, where qualified vendors remain limited. Distribution runs through municipal tender platforms and waste management fleet operators, with software-hardware platforms bypassing traditional equipment distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal waste hierarchy mandates are forcing consolidation as compliance costs filter out uncertified hardware providers, concentrating vendor share among integrated platform operators with dual systems certification.
For Market Incumbents: Anchor municipal contract renewal through backward integration into sensor manufacturing, reducing exposure to East Asian supply concentration. Invest in REACH documentation capabilities as Germany's certification requirements tighten, defending against emerging pure-play AI specialists lacking compliance infrastructure. For New Entrants and Emerging Players: Launch via software-as-a-service models targeting Turkish and Middle Eastern waste management companies seeking fleet logistics integration without hardware replacement. Penetrate India's BIS certification pipeline early, as smart city mission procurement accelerates electromechanical receptacle deployment in Maharashtra and Karnataka sub-regions. For Investors and Strategic Acquirers: The window for entry favors integrated software-hardware platform operators with established municipal relationships and certified sorting accuracy below three percent contamination. Long-term viability hinges on dual systems operator partnerships in Germany and state-level bottle bill jurisdictions in California and Oregon. Watch EPA waste reduction target tightening as the signal for accelerated procurement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Dual Systems Operator Partnership | Secures predictable revenue streams through Germany's structured material recovery compensation flows. |
| Backward Integration into Sensor Manufacturing | Reduces single-source vulnerability from East Asian contract manufacturers for computer vision modules. |
| REACH Compliance Documentation Investment | Filters competition as Bavarian municipalities mandate certification preconditions for tender eligibility. |
| Fleet Logistics Software Expansion | Captures Turkish and Middle Eastern demand for collection routing optimization through integrated platforms. |
| State-Level Bottle Bill Certification | Unlocks municipal procurement in California and Oregon where sorting precision determines vendor selection. |
Research Methodology
Multi-period observation of municipal tender awards, contamination penalty structures, and dual systems payment flows anchored the trend analysis, supplemented by interviews with smart city procurement officers, waste management fleet operators, dual systems compliance managers, and sensor module sourcing directors. Secondary validation drew from EU Green Deal implementation reports, EPA waste reduction target disclosures, BIS certification registries, and GB standards documentation. Bottom-up unit shipment estimates triangulated against top-down municipal budget allocations for AI-powered infrastructure.
Segment-weighting across technology tiers, installation types, and end-user categories shaped the analytical framework over the projection horizon. Deployment context, certification requirements, and software-hardware integration depth formed the core segmentation dimensions. CAGRs derived from logistic diffusion curves fitted to municipal procurement velocity and commercial contamination penalty escalation. Near-infrared spectroscopy adoption rates and solar-compaction heritage contract renewal patterns served as industry-specific forecast inputs.
Regulatory enforcement delays, sensor module supply disruptions, and informal waste picker network persistence are the dominant revision risks to the outlook. Deviation in EU Green Deal landfill diversion timeline enforcement would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste Management & Pollution Control
Industrial Waste Management Market
Waste Management & Pollution Control
United States Trash Bags Market
Waste Management & Pollution Control
Singapore Waste Management Market
Waste Management & Pollution Control
India Municipal Solid Waste Management Market
Waste Management & Pollution Control
Household Composters Market
Waste Management & Pollution Control
Wood Recycling Market
Waste Management & Pollution Control
Automated Waste Collection System (AWCS) Market
Waste Management & Pollution Control
Marine Waste Handling Equipment Market
Waste Management & Pollution Control
Asia-Pacific Hazardous Waste Handling Automation Market
Waste Management & Pollution Control
Global Automated Marine Debris Collection Equipment Market
Waste Management & Pollution Control
GCC Industrial Waste Management Market
Waste Management & Pollution Control
Waste Sorting Equipment Market
Waste Management & Pollution Control
Hazardous Waste Management Market
Waste Management & Pollution Control
Global Oil Spill Management Market
Waste Management & Pollution Control
Compostable and Biodegradable Refuse Bags Market
Waste Management & Pollution Control
Saudi Arabia Waste Management Market