
 US Municipal Solid Waste Management Market | 2026-2036
US Municipal Solid Waste Management Market Size, Share, and Industry Trends Forecast 2026-2036
US Municipal Solid Waste Management Market Analysis
Commercial waste generation from retail and food service is recalibrating collection frequency and container sizing across metropolitan markets. Waste Management Inc. dominates residential and commercial routes through dense urban infrastructure networks. Republic Services Inc. leverages vertically integrated landfill and recycling assets in Sun Belt growth corridors. GFL Environmental Inc. competes aggressively on price in secondary markets where contract renewals occur frequently.
US municipal solid waste management encompasses the collection, transportation, processing, and disposal of refuse generated by households, businesses, and institutions, with modern facilities achieving landfill gas capture rates exceeding 75% through engineered liner systems and active extraction wells. Collection services anchor revenue stability through long-term municipal contracts with inflation-indexed pricing. Recycling operations face structural margin compression from contaminated feedstreams and volatile commodity markets. Energy recovery from thermal treatment represents the fastest-expanding technology segment as utilities seek dispatchable renewable power sources.
EPA landfill methane rules under the Clean Air Act, state-level extended producer responsibility frameworks, and OSHA collection safety standards collectively elevate compliance costs while accelerating capital deployment toward diversion infrastructure. The Department of Transportation hours-of-service regulations constrain route density optimization for haulers operating across state lines. Stakeholders must monitor emerging per- and polyfluoroalkyl substances disposal restrictions that threaten existing landfill acceptance protocols and leachate treatment capabilities.
Market Dynamics
EPA methane capture mandates under the Clean Air Act are forcing capital reallocation from landfill expansion toward anaerobic digestion and gas-to-energy infrastructure, compressing traditional disposal economics while elevating diversion technology valuations.
Growth Catalysts
- Extended Producer Responsibility frameworks:California, Maine, and Oregon enact packaging stewardship laws that shift financial responsibility upstream, stimulating investment in sorting and reprocessing capacity.
- Food service sector consolidation:National restaurant chains are centralizing waste contracts with single haulers, driving route density improvements and container standardization across metropolitan markets.
- Landfill gas-to-energy systems:Engineered extraction wells and membrane bioreactor leachate treatment are expanding renewable natural gas output for utility offtake agreements.
Market Restraints
- Contaminated single-stream feedstock:Non-recyclable material intrusion at 25-30% rates degrades bale quality and compresses MRF operating margins below breakeven thresholds.
- Permitting timelines for new landfill capacity:NIMBY opposition and state environmental review processes in the Northeast extend development cycles to 7-10 years, constraining disposal optionality.
- Diesel fuel price volatility:Collection fleets consume 15-20% of operating budgets, exposing route economics to petroleum market swings without full pass-through mechanisms.
Strategic Opportunities
- Texas Sun Belt corridors:Rapid population growth in Dallas-Fort Worth and Houston metro areas outpaces installed collection infrastructure, creating whitespace for contract capture.
- Pyrolysis and chemical recycling:Thermal depolymerization of mixed plastics is converging with refinery offtake agreements to unlock previously non-recyclable polymer streams.
- OSHA silica exposure standards:Stricter collection vehicle maintenance protocols are accelerating demand for automated side-loaders and cab filtration retrofits.
Industry Challenges
- CDL driver shortage:Waste haulers compete with long-haul freight and construction for commercial driver's license holders, constraining route expansion and overtime management.
- Legacy scale integration:Weighbridge data systems, route optimization software, and customer billing platforms require costly middleware development for unified fleet management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Municipal Solid Waste Management Market |
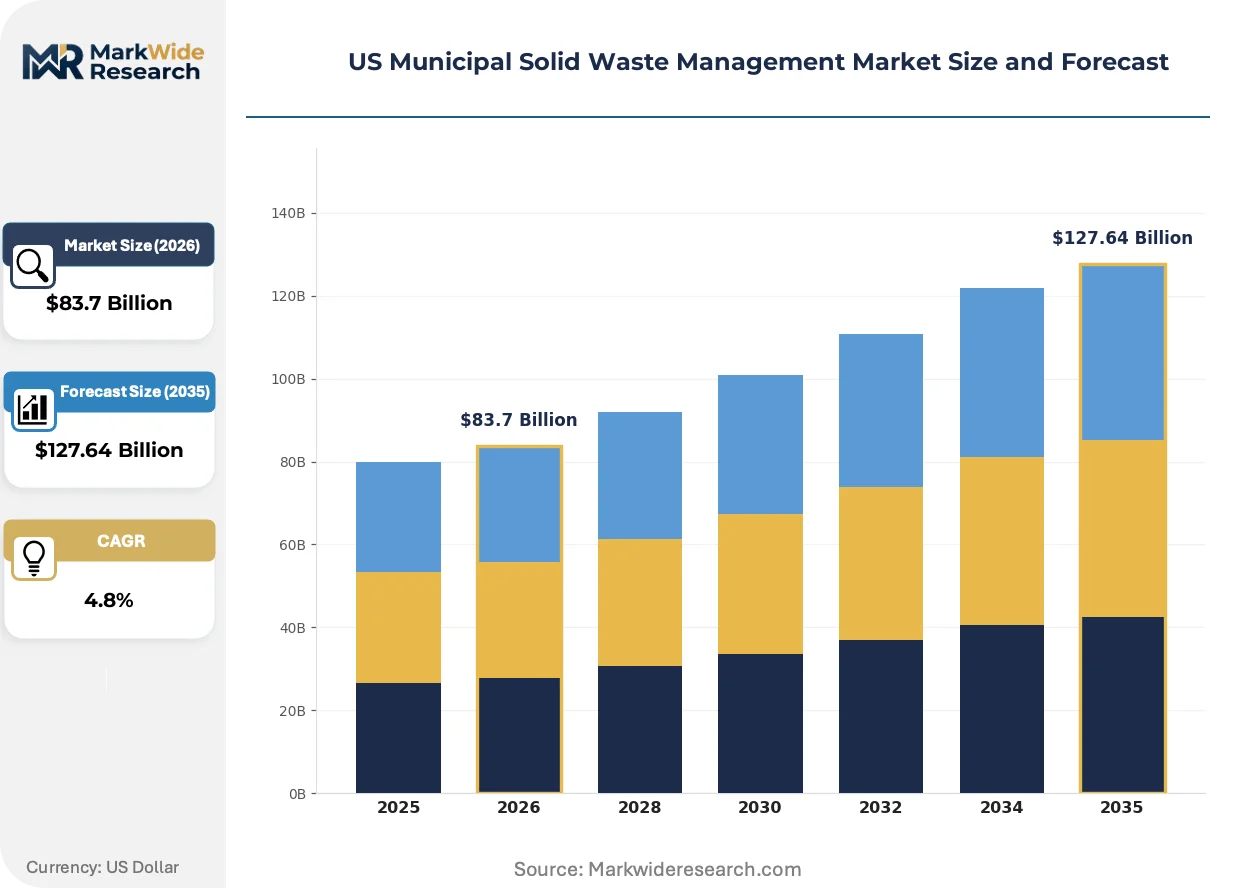
| Market Size in 2026 | $83.7 Billion |
| Market Size in 2035 | $127.64 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Collection, Recycling, Landfilling, Composting End User: Residential, Commercial, Industrial, Institutional Technology: Mechanical Processing, Biological Treatment, Thermal Treatment, Energy Recovery Material Type: Organic Waste, Plastic Waste, E-Waste, Hazardous Waste |
| Companies Covered | GFL Environmental Inc., Clean Harbors Inc., Waste Management Inc., Stericycle Inc., Veolia North America, Republic Services Inc., Casella Waste Systems Inc., Rumpke Waste & Recycling, Waste Connections Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Municipal Solid Waste Management Market Emerging Trajectories
Digital route optimization and sensor-enabled container monitoring are compressing collection cycle times while elevating asset utilization rates across dense urban networks.
Optical sorting robotics equipped with near-infrared spectrometry and artificial vision is expanding into materials recovery facilities processing commercial and residential commingled streams. MRF operators in California and the Northeast are retrofitting lines at pace to handle flexible packaging and film contamination. This expansion is enabling higher purity bales for domestic reprocessors, reducing export dependence for mixed paper and plastics.
EPA New Source Performance Standards for municipal solid waste landfills are tightening methane emission thresholds and mandating surface emission monitoring. Facilities exceeding 450 megagrams annual non-methane organic compound generation must install gas collection systems within 30 months. Texas and Florida landfills are responding with accelerated wellfield expansion and geomembrane cap repairs to maintain operational permits.
Retail and food service buyers are consolidating waste spend under enterprise procurement functions, displacing site-level vendor selection with national framework agreements. Contract structures are shifting from per-pull pricing to fixed-fee unlimited service with weight band adjustments. This concentration is most visible in quick-service restaurant chains operating across the Southeast and Midwest, where procurement teams negotiate three-year master service agreements with inflation escalators.
US Municipal Solid Waste Management Market Segmentation
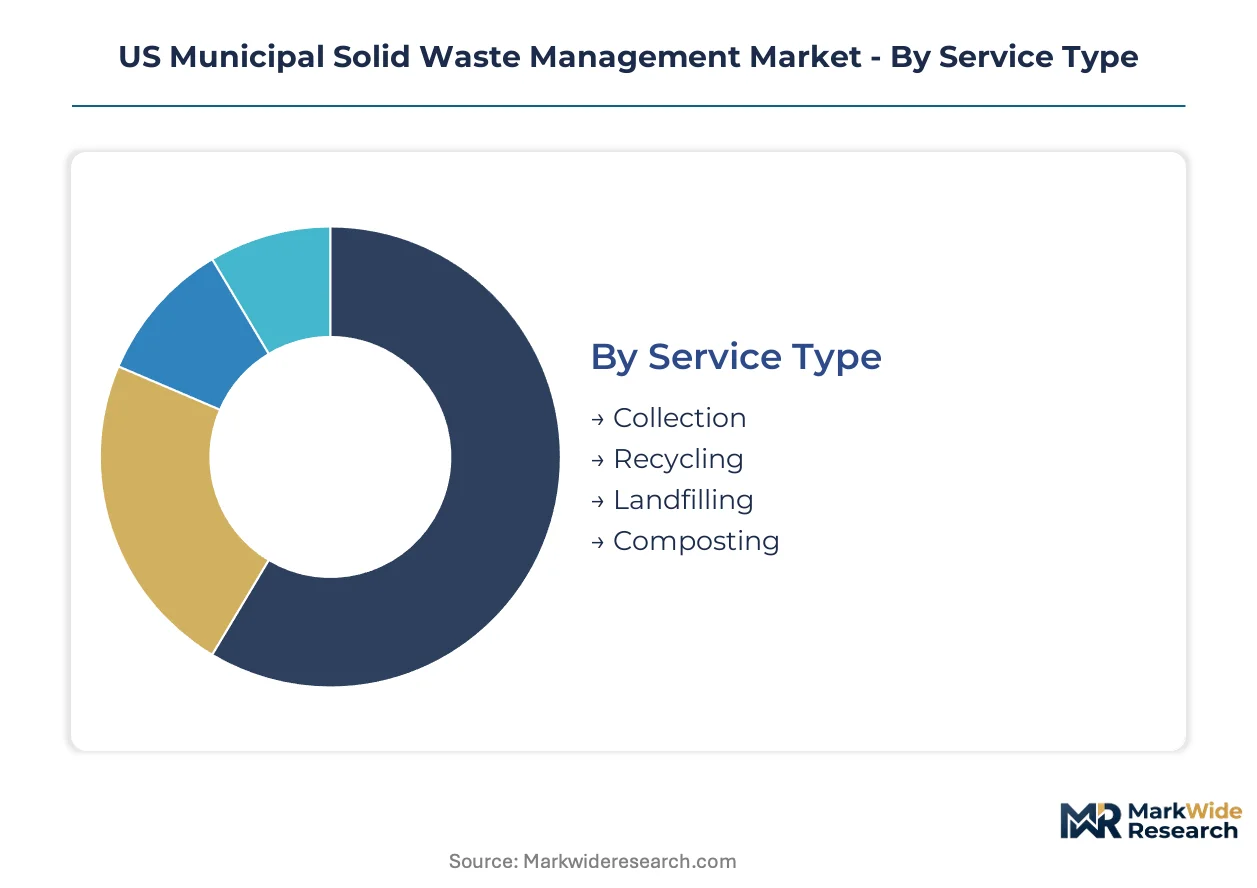
Segmentation in US municipal solid waste management reveals how service configurations, customer profiles, and processing technologies align with distinct regulatory and economic pressures. Understanding these divisions clarifies where capital deployment and contract pricing diverge across the value chain.
Service Type:
Route density upgrades and container replacement cycles drive service selection, with haulers optimizing fleet composition against fuel cost exposure and labor availability.
- Collection:Curbside and commercial container services form the revenue foundation through long-term municipal contracts with inflation-indexed pricing. Demand clusters in Texas Sun Belt corridors and California metro areas where population density justifies automated side-loader deployment.
- Recycling:Materials recovery facilities process commingled streams using optical sorting robotics, though contaminated feedstock at 25-30% intrusion rates compresses operating margins below breakeven in secondary markets.
- Landfilling:Engineered disposal cells with geomembrane liners and leachate collection systems remain the dominant destination for non-recyclable refuse, constrained by 7-10 year permitting timelines in the Northeast.
- Composting:Aerobic and anaerobic digestion facilities process organic fractions, expanding fastest in states with food waste diversion mandates.
Volume placements concentrate in Collection; the faster expansion belongs to Composting.
End User:
Customer type determines contract structure, payment security, and contamination risk exposure across route networks.
- Residential:Municipal ratepayer funding provides revenue stability through franchise agreements, though per-household waste generation has plateaued in mature Northeast markets.
- Commercial:Retail and food service consolidation under enterprise procurement functions is displacing site-level vendor selection with national framework agreements.
- Industrial:Manufacturing generators produce high-volume, low-contamination material streams suitable for direct mill or reprocessor offtake.
- Institutional:Schools, hospitals, and government facilities represent stable contracted volumes with standardized container protocols and predictable seasonal patterns.
Commercial contracts command premium pricing; institutional accounts deliver the most predictable cash flow.
Technology:
Capital replacement cycles favor technologies with regulatory compliance benefits and renewable energy revenue attachments.
- Mechanical Processing:Shredding, screening, and density separation equipment handles construction debris and bulky waste streams with lower capital intensity than thermal alternatives.
- Biological Treatment:Anaerobic digesters and composting tunnels process organic waste under EPA and state air quality permits, producing renewable natural gas for utility injection in California and Texas.
- Thermal Treatment:Mass-burn and refuse-derived fuel facilities face siting challenges but dispatch baseload power to grid operators seeking renewable portfolio compliance.
- Energy Recovery:Landfill gas-to-energy systems with membrane bioreactor leachate treatment are expanding fastest as EPA methane rules tighten emission thresholds.
Mechanical Processing dominates installed capacity; Energy Recovery is climbing the fastest as utilities seek dispatchable renewable sources.
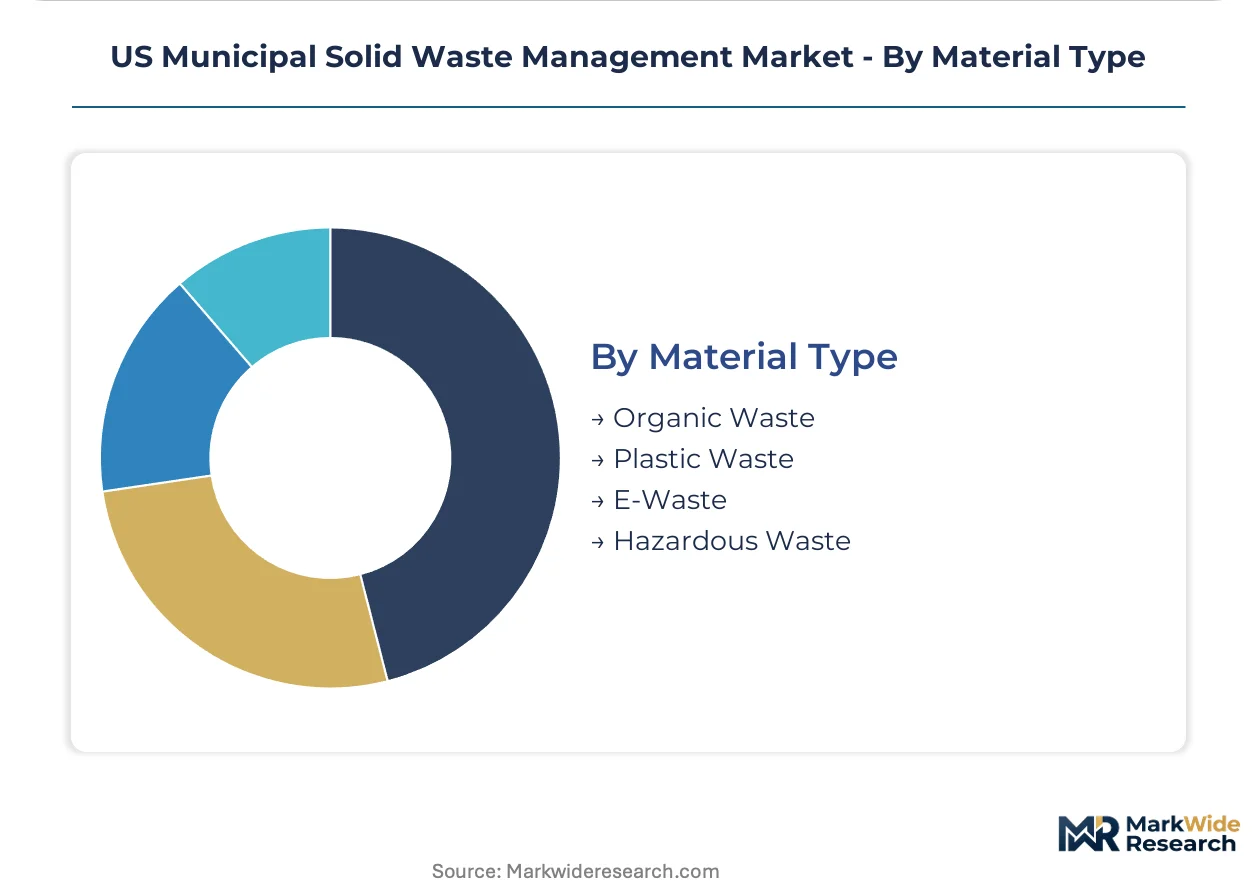
Material Type:
Acceptance protocols and disposal restrictions determine processing pathway economics and liability exposure.
- Organic Waste:Food scraps and yard trimmings drive anaerobic digester feedstock demand in states with landfill diversion mandates, though collection logistics remain fragmented.
- Plastic Waste:Flexible packaging and film contamination challenges optical sorting systems, pushing investment toward pyrolysis and chemical recycling for previously non-recyclable polymer streams.
- E-Waste:Discarded electronics require specialized handling under state producer responsibility frameworks, with California's SB 20 program establishing collection infrastructure standards.
- Hazardous Waste:Industrial chemicals and medical refuse demand permitted treatment facilities with manifest tracking, concentrated in Texas and Louisiana petrochemical corridors.
Organic Waste generates the highest diversion policy attention; Plastic Waste presents the steepest technology investment requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Texas Enterprise Zones and California Recycling Market Development Zones concentrate capital deployment through property tax abatements and infrastructure grants. These incentive structures accelerate landfill gas-to-energy installations and anaerobic digestion capacity in high-growth corridors.
California
Food waste diversion mandates under SB 1383 drive anaerobic digester construction across the Central Valley. CalRecycle administers $180 million in organic waste infrastructure grants through 2025. The Los Angeles-San Diego corridor hosts the densest concentration of materials recovery facilities retrofitting optical sorting lines for flexible packaging.
Texas
Rapid population influx in Dallas-Fort Worth and Houston metro areas outpaces installed collection infrastructure. The Texas Commission on Environmental Quality streamlined permitting for landfill gas capture systems under 30 TAC Chapter 115. The Permian Basin corridor attracts waste-by-rail volumes from neighboring states seeking lower disposal costs.
Northeast Corridor
Extended producer responsibility laws in Maine, Oregon, and California (with New York pending) shift financial responsibility upstream to packaging producers. EPA Region 1 enforces stringent landfill methane monitoring under Clean Air Act New Source Performance Standards. The Boston-Washington megalopolis faces 7-10 year permitting timelines for new landfill capacity, elevating waste export volumes to Pennsylvania and Ohio.
Florida
Tourism and retirement migration sustain per-capita waste generation above national averages. The Florida Department of Environmental Protection mandates 75% statewide recycling goals through 2025. The Orlando-Tampa corridor concentrates C&D debris processing capacity serving Sun Belt construction activity.
Pacific Northwest
Oregon's 2021 Plastic Pollution and Recycling Modernization Act establishes producer responsibility for packaging waste. The Washington State Department of Ecology enforces strict leachate discharge standards under NPDES permits. The Seattle-Portland corridor leads national adoption of automated side-loader fleets and sensor-enabled container monitoring.
US Municipal Solid Waste Management Market Vendor Landscape
Top-tier vendors anchor national route networks and vertically integrated landfill assets, while regional specialists compete on price in secondary markets with frequent contract renewals. The market structure concentrates around three to four integrated players controlling dense urban infrastructure. Strategic archetypes include: (1) national scale operators with captive disposal capacity, (2) regional price competitors leveraging acquisition-led growth, and (3) specialized hazardous and medical waste handlers with permitted treatment assets. Dominant competitive moves encompass route density optimization through municipal contract consolidation and capital deployment toward renewable natural gas infrastructure.
Among North American integrated operators, Waste Management Inc., Republic Services Inc., and GFL Environmental Inc. occupy distinct positions across the competitive spectrum. Waste Management exemplifies the national scale archetype through dense urban infrastructure networks. Republic Services represents vertically integrated landfill and recycling asset deployment in Sun Belt growth corridors. GFL Environmental sits within the aggressive price-competition tier targeting secondary market contract capture.
| Leading Market Players |
|---|
| GFL Environmental Inc. |
| Clean Harbors Inc. |
| Waste Management Inc. |
| Stericycle Inc. |
| Veolia North America |
| Republic Services Inc. |
| Casella Waste Systems Inc. |
| Rumpke Waste & Recycling |
| Waste Connections Inc. |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up regional haulers anchor supply consolidation across secondary Sun Belt markets, compressing contract renewal pricing while forcing asset-heavy incumbents toward longer-term municipal lock-ins to defend margin stability.
Pricing Analysis
Short lead-time premiums for emergency commercial container swaps command 15-40% uplifts over standard scheduled service, while spot inventory discounts apply to underutilized landfill airspace in Texas and Florida corridors. The market operates on fixed-fee unlimited service with weight band adjustments, differentiating by container size tier and route density economics. Cost compression in recycling operations is intensifying because contaminated feedstock degrades bale quality below domestic mill specifications. Quick-service restaurant chains operating under national framework agreements exhibit highest price sensitivity, whereas institutional accounts with mandated diversion targets show lowest elasticity.
Supply Chain Analysis
Domestic-content mandates under California's SB 1383 and Texas enterprise zone requirements are reshaping sourcing toward in-state anaerobic digester construction and local equipment fabrication. Supply concentrates in the United States, Canada, and Mexico through cross-border waste-by-rail corridors serving Permian Basin disposal capacity. The chain draws from diesel fuel markets, automated side-loader chassis, and geomembrane liner systems as critical inputs. Single-source vulnerability concentrates in specialized leachate treatment chemical suppliers. Distribution runs through municipal procurement offices, national account management teams, and regional route depots.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
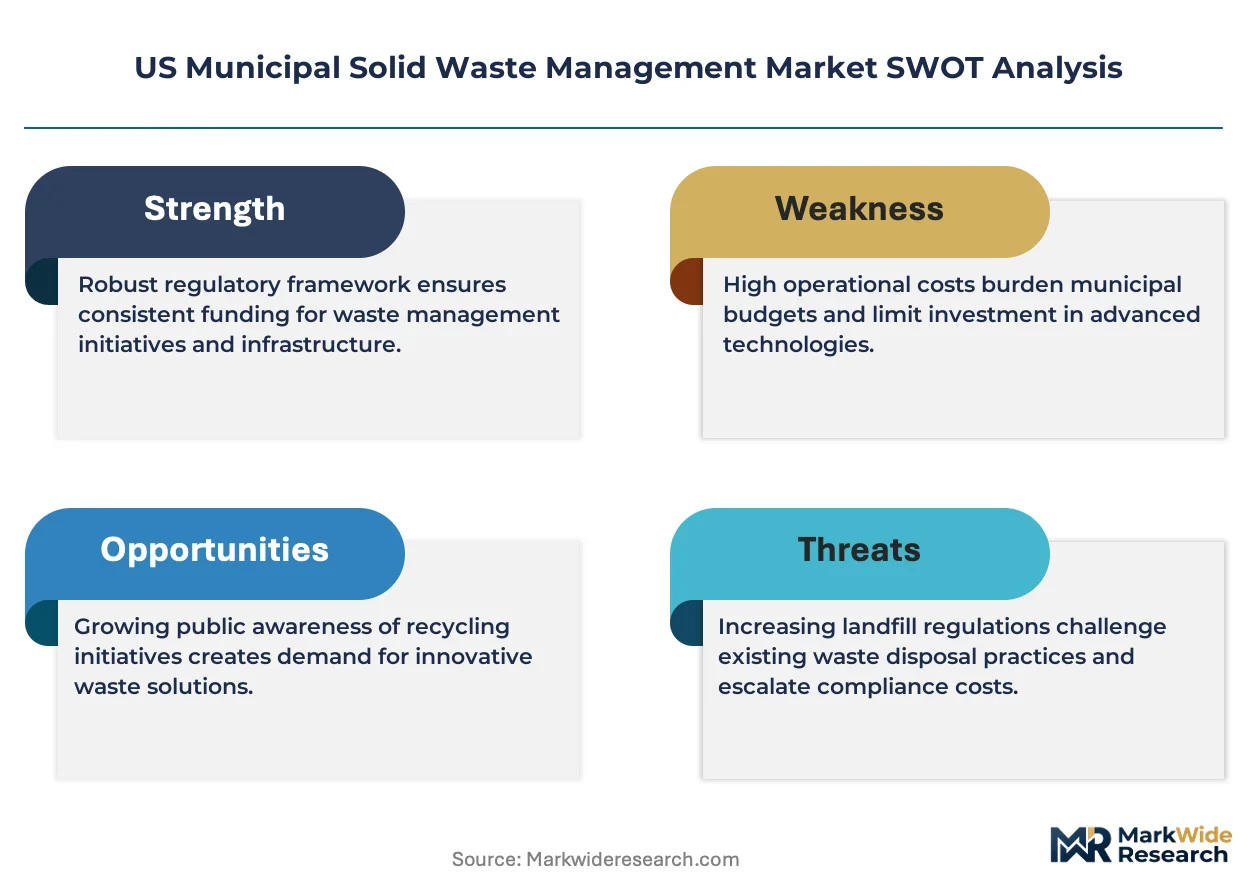
This market functions as a consolidation play. EPA methane capture mandates and legacy scale integration burdens are forcing sub-scale operators toward exit or acquisition.
For Market Incumbents: Lock in route density through municipal contract consolidation in Texas Sun Belt corridors where population growth outpaces installed infrastructure. Prioritize renewable natural gas infrastructure deployment to capture utility offtake premiums under tightening EPA emission thresholds. Defend against price competitors by embedding inflation-indexed pricing into franchise renewals.
For New Entrants and Emerging Players: Capture whitespace in secondary metropolitan markets with frequent contract renewals where GFL Environmental's aggressive pricing has created service gaps. Target food waste collection logistics for independent restaurants outside national chain procurement umbrellas. Lead with sensor-enabled container monitoring as a differentiated service layer.
For Investors and Strategic Acquirers: CDL driver shortage resolution through automated fleet deployment is the leading indicator that operational leverage will shift toward capital-intensive players. Position for five-to-ten year viability around vertically integrated landfill-to-energy assets with permitted capacity in constrained Northeast corridors. Watch for anaerobic digester construction permit acceleration in California Central Valley as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Route Density Optimization | Automated side-loader deployment in Dallas-Fort Worth reduces per-stop labor hours below manual collection economics. |
| Renewable Natural Gas Infrastructure | Landfill gas-to-energy systems with membrane bioreactor leachate treatment secure EPA compliance and utility offtake revenue. |
| Optical Sorting Retrofit | Near-infrared spectrometry expansion in California MRFs enables flexible packaging processing for domestic reprocessor acceptance. |
| National Account Consolidation | Enterprise procurement functions at quick-service restaurant chains displace site-level vendor selection with three-year master agreements. |
| Anaerobic Digester Construction | Central Valley facilities process SB 1383-mandated food waste streams into renewable natural gas for California utility injection. |
Methodological Framework
Multi-period observation of EPA enforcement actions, state legislative calendars, and landfill permitting timelines anchored the trend analysis, supplemented by interviews with municipal solid waste directors, commercial account managers at integrated haulers, route operations supervisors, and landfill gas facility engineers. Secondary validation drew from EPA New Source Performance Standards filings, state environmental agency permit databases, Department of Transportation hours-of-service regulatory updates, and municipal procurement contract disclosures. Bottom-up service revenue modeling triangulated against top-down macro waste generation forecasts.
Segment-weighting across service type, end user, technology, and material type dimensions structured the analytical framework throughout the projection horizon. CAGRs derived from installed capacity expansion rates, contract renewal pricing trajectories, and regulatory compliance cost pass-through assumptions. Industry-specific inputs incorporated diesel fuel price volatility exposure, CDL labor market tightness, and contamination rate trends at materials recovery facilities.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EPA per- and polyfluoroalkyl substances disposal restrictions, state extended producer responsibility implementation pacing, and waste export flow disruptions from Northeast capacity constraints. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste Management & Pollution Control
Global Waste Oil Market
Waste Management & Pollution Control
Metal Recycling Equipment Market
Waste Management & Pollution Control
India Bio-Medical Waste Management Market
Waste Management & Pollution Control
Compostable and Biodegradable Refuse Bags Market
Waste Management & Pollution Control
Mining Waste Management Market
Waste Management & Pollution Control
Household Composters Market
Waste Management & Pollution Control
Hazardous Waste Handling Automation Market
Waste Management & Pollution Control
US Medical Waste Management Market
Waste Management & Pollution Control
GCC Industrial Waste Management Market
Waste Management & Pollution Control
Industrial Solid Waste Management Market
Waste Management & Pollution Control
North America Municipal Solid Waste Management Market
Waste Management & Pollution Control
UAE Biomedical Waste Management Market
Waste Management & Pollution Control
Middle-East and Africa Hazardous Waste Handling Automation Market
Waste Management & Pollution Control
Incinerator Market
Waste Management & Pollution Control
Hazardous Waste Management Market
Waste Management & Pollution Control
India Commercial Food Waste Decomposer Market