
 Qatar Solid Waste Management Market | 2026-2036
Qatar Solid Waste Management Market Size, Share, and Industry Trends Forecast 2026-2036
Qatar Solid Waste Management Market Analytics
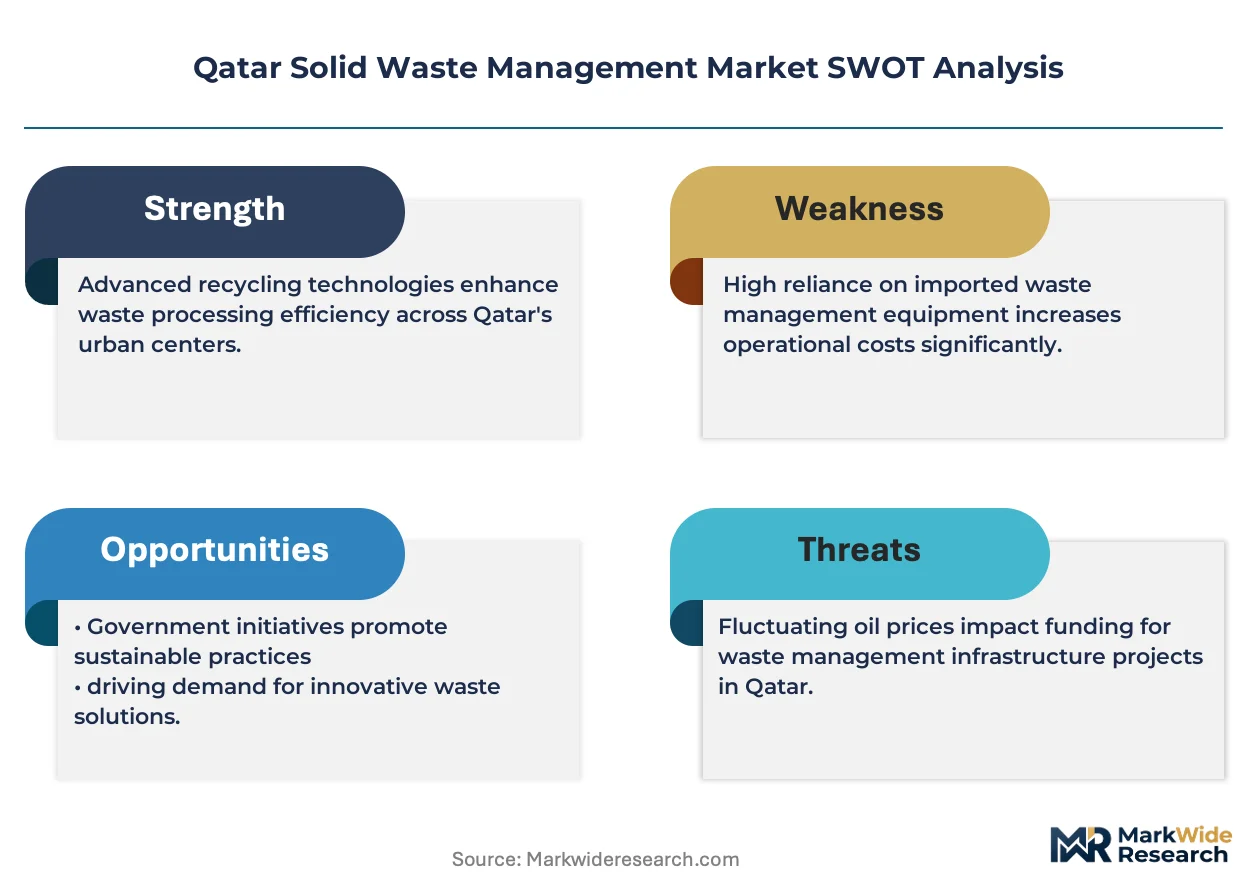
Aftermarket service revenue in treatment and recycling operations is tilting toward integrated operators with long-term municipal contracts. Veolia leverages its multi-service platform to capture recurring maintenance and technology upgrade cycles across Qatar's waste infrastructure. Dulsco Qatar anchors its position through workforce-intensive collection networks serving construction and commercial zones. Bee'ah Qatar differentiates via advanced sorting and material recovery capabilities aligned with national sustainability targets.
Qatar solid waste management encompasses the systematic handling of discarded materials from residential, commercial, industrial, and institutional sources through collection, transportation, processing, and final disposal or recovery, typically operating within arid climate constraints that limit biological decomposition rates and elevate leachate management complexity. The primary purpose centers on minimizing environmental contamination, recovering recyclable and organic fractions, and ensuring public health protection across densely populated urban centers and rapidly expanding industrial zones. Municipal solid waste collection and recycling services currently occupy the largest service type share, reflecting Qatar's concentrated population distribution and the government's push to reduce landfill dependency under national environmental strategies. Hazardous waste treatment commands premium pricing due to stringent handling protocols and limited licensed facility capacity, while anaerobic digestion technology is gaining traction for organic fraction processing given the country's substantial food service and hospitality waste streams.
Qatar's Ministry of Municipality and Environment sets landfill diversion mandates and waste sorting requirements that directly shape operator licensing and facility investment priorities. The Supreme Committee for Delivery and Legacy enforced construction waste management protocols during infrastructure buildout, creating compliant demand for specialized collection and recycling services. Stakeholders must monitor evolving extended producer responsibility frameworks and carbon accounting rules that will redefine competitive positioning in Qatar's waste value chain.
Market Dynamics
Qatar's landfill diversion mandates under the National Environment and Climate Change Strategy are forcing operators to reconfigure collection networks toward material recovery facilities and anaerobic digestion plants. This regulatory compression is restructuring contract economics away from tonnage-based disposal fees toward output-linked recycling performance.
Growth Catalysts
- Lusail City construction pipeline:Mega-project waste volumes are mandating dedicated construction and demolition debris recycling infrastructure.
- Anaerobic digestion technology:Hospitality and food service organic waste streams are creating viable biogas feedstock economics.
- Ministry of Municipality and Environment sorting requirements:Source-separation mandates are expanding residential recycling participation rates.
Market Restraints
- Limited licensed hazardous waste capacity:Specialized treatment facility scarcity concentrates disposal options and elevates compliance costs for industrial generators.
- Arid climate decomposition constraints:Biological waste breakdown rates lag temperate benchmarks, complicating landfill design and leachate containment protocols.
- Construction labor dependency:Collection workforce intensity ties operating margins to visa and accommodation policy volatility.
Strategic Opportunities
- Extended producer responsibility frameworks:Pending packaging and electronics take-back regulations will create reverse logistics service demand.
- Industrial symbiosis platforms:Waste-to-resource exchanges between Ras Laffan industrial zone and urban construction sites remain underdeveloped.
- Carbon accounting integration:National climate disclosure requirements will prioritize operators with verified emissions tracking and offset generation capabilities.
Industry Challenges
- Equipment technician scarcity:Automated sorting and digestion plant maintenance requires specialized mechanical and controls expertise that local training pipelines undersupply.
- Legacy collection fleet integration:Route optimization software deployment faces compatibility barriers with existing vehicle telematics and depot management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Qatar Solid Waste Management Market |
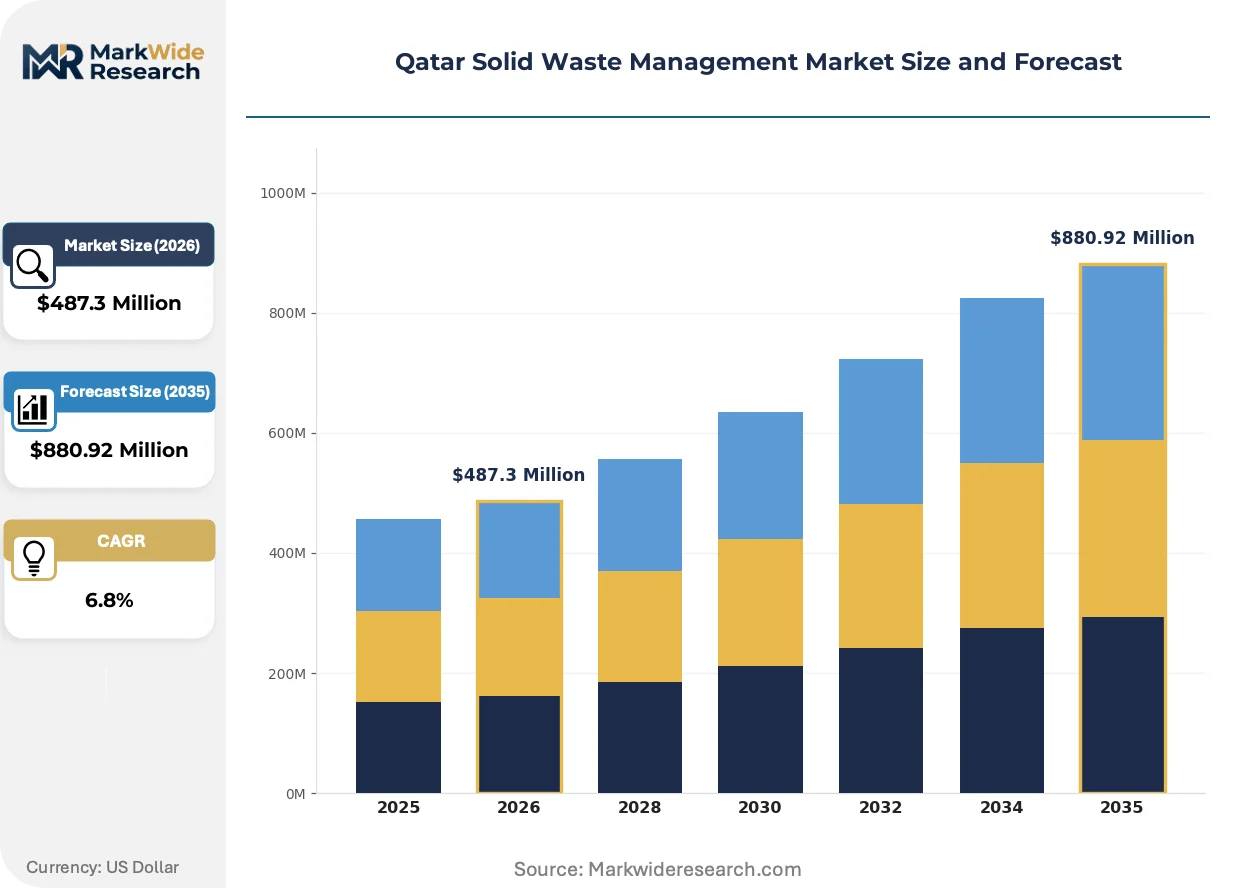
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Waste Type: Municipal Solid Waste, Hazardous Waste, Industrial Waste, E-waste Service Type: Collection, Recycling, Treatment, Disposal Technology: Composting, Incineration, Anaerobic Digestion, Landfilling End User: Residential, Commercial, Government, Educational Institutions |
| Companies Covered | Dulsco Qatar, Al Haya Environmental Group, Veolia, Elite Waste Management, Power Waste Management & Transport Co. WLL, Averda Environmental Services, Bee'ah Qatar, Green Waste Management Sewerage Services LLC, Seashore Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Qatar Solid Waste Management Market Evolving Landscape
Near-infrared spectroscopy and robotics are transforming Qatar's material recovery facility economics by enabling higher-purity output streams with reduced manual sorting labor. These capital-intensive upgrades are compressing margins for operators locked into conventional mechanical separation.
Automated optical sorting systems paired with artificial intelligence classification are rendering obsolete manual picking stations in Doha's largest recycling facilities. The Ministry of Municipality and Environment is prioritizing grant funding for operators deploying these technologies. Output quality premiums now justify capital recovery periods below five years for high-volume municipal contracts.
Qatar's National Environment and Climate Change Strategy is embedding circular economy procurement criteria into government facility management contracts. Public sector waste service tenders now require documented recycling rates and material recovery certificates. This policy lever is accelerating private operator investment in downstream processing capacity ahead of commercial market development.
Long-term performance-based service contracts are displacing traditional per-tonne collection fees among Lusail and Education City institutional clients. Facility managers are transferring operational risk to integrated operators in exchange for guaranteed diversion metrics. This contracting evolution concentrates revenue with vendors possessing in-house treatment assets rather than pure logistics providers.
Qatar Solid Waste Management Market Segmentation
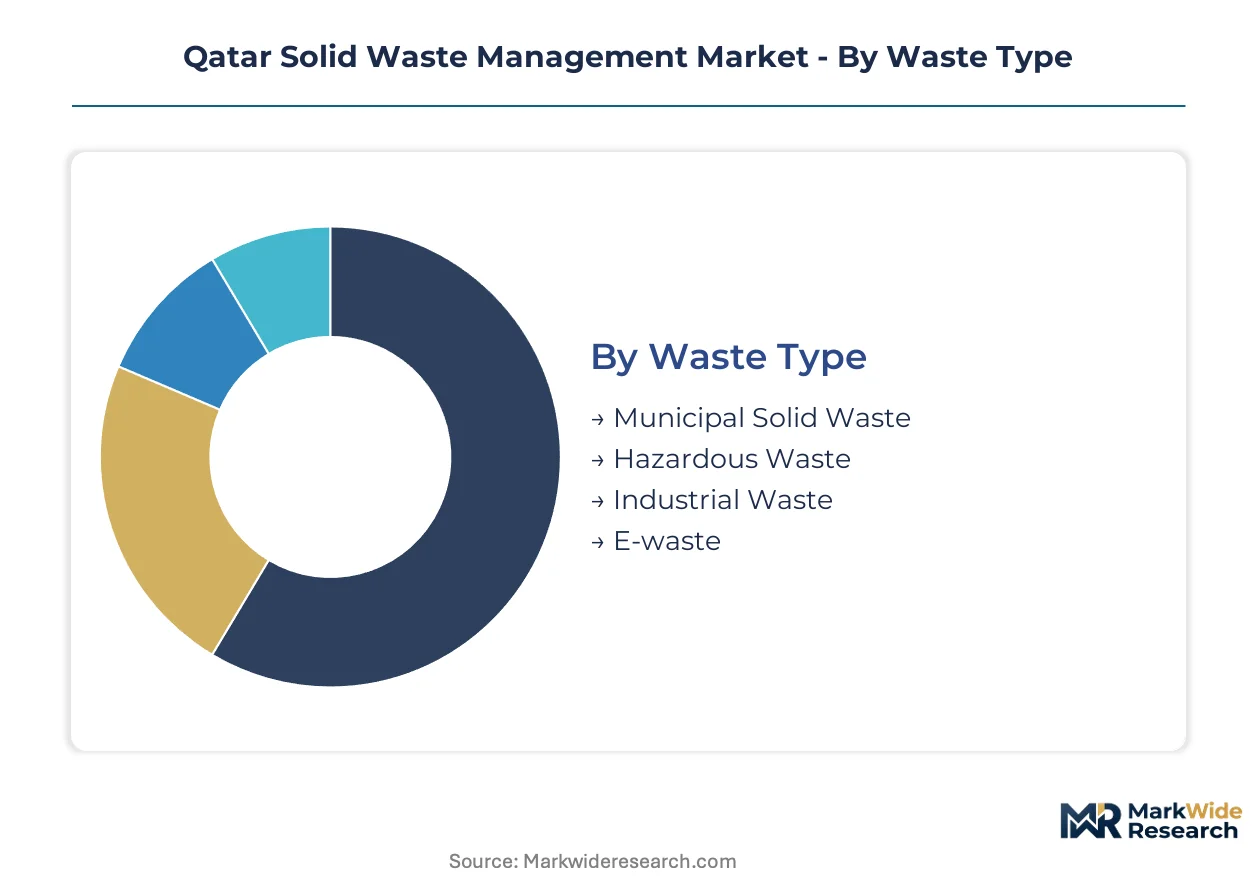
Qatar's waste management segmentation reflects the country's concentrated urban population, industrial zone clustering, and regulatory mandates for landfill diversion. Waste streams, service modalities, and processing technologies each command distinct investment profiles and contract structures across Doha, Lusail, and Ras Laffan.
Waste Type:
The use-case spectrum spans residential consumption patterns, industrial process outputs, and specialized hazardous streams requiring licensed handling protocols.
- Municipal Solid Waste:Comprises household, commercial, and institutional discards including food waste, packaging, and paper. Doha's dense residential corridors and Lusail's expanding population generate the bulk of collection contract volumes under Ministry of Municipality and Environment diversion mandates.
- Hazardous Waste:Encompasses chemical, medical, and industrial byproducts requiring specialized treatment and limited licensed facility capacity. Ras Laffan industrial zone and healthcare clusters drive premium-priced disposal demand constrained by regulatory scarcity.
- Industrial Waste:Includes manufacturing byproducts, construction debris, and process residues from Qatar's energy and petrochemical sectors. Infrastructure buildout in Lusail and Education City sustains heavy-volume collection requirements.
- E-waste:Covers discarded electronics, batteries, and electrical equipment with recoverable precious metals. Commercial and government upgrade cycles generate intermittent but high-value material recovery opportunities.
Established volume favors Municipal Solid Waste; emerging adoption favors E-waste as extended producer responsibility frameworks advance.
Service Type:
Cost tier differentiation separates labor-intensive logistics from capital-heavy processing operations with diverging margin profiles.
- Collection:Door-to-door pickup, containerized hauling, and transfer station logistics using fleet-based operations. Workforce-intensive networks serving Doha's commercial zones face visa policy volatility and accommodation cost pressures.
- Recycling:Material recovery, sorting, and commodity preparation for reprocessing markets. Near-infrared spectroscopy and robotic sorting are compressing labor costs at Doha's largest facilities while purity premiums justify capital deployment.
- Treatment:Physical, chemical, or biological processing to neutralize hazards or prepare waste for final disposal. Hazardous waste treatment commands scarcity pricing due to limited licensed capacity under Ministry oversight.
- Disposal:Landfilling, engineered containment, and final deposition with leachate management. Arid climate constraints elevate containment complexity and extend design lifecycles for Qatar's engineered landfill cells.
High-frequency logistics anchor Collection revenue; value-capture upside concentrates in Recycling as commodity markets mature.
Technology:
Application suitability varies by waste composition, moisture content, and energy recovery potential across Qatar's climate conditions.
- Composting:Aerobic biological decomposition of organic fractions to produce soil amendments. Low moisture availability and extreme temperatures limit decomposition rates below temperate benchmarks, constraining throughput economics.
- Incineration:High-temperature combustion with energy recovery for residual waste streams. Limited deployment in Qatar reflects air quality concerns and competing priorities for landfill gas capture.
- Anaerobic Digestion:Oxygen-free biological processing generating biogas from organic waste. Hospitality and food service waste streams in Doha's hotel and restaurant clusters create viable feedstock economics for biogas generation.
- Landfilling:Engineered containment with leachate collection and gas management systems. Remains the dominant disposal pathway though National Environment and Climate Change Strategy mandates are compressing allowable volumes.
Mature infrastructure dominates Landfilling; steepest expansion trajectory belongs to Anaerobic Digestion aligned with circular economy procurement criteria.
End User:
Customer type segmentation maps to contract scale, payment security, and regulatory compliance requirements.
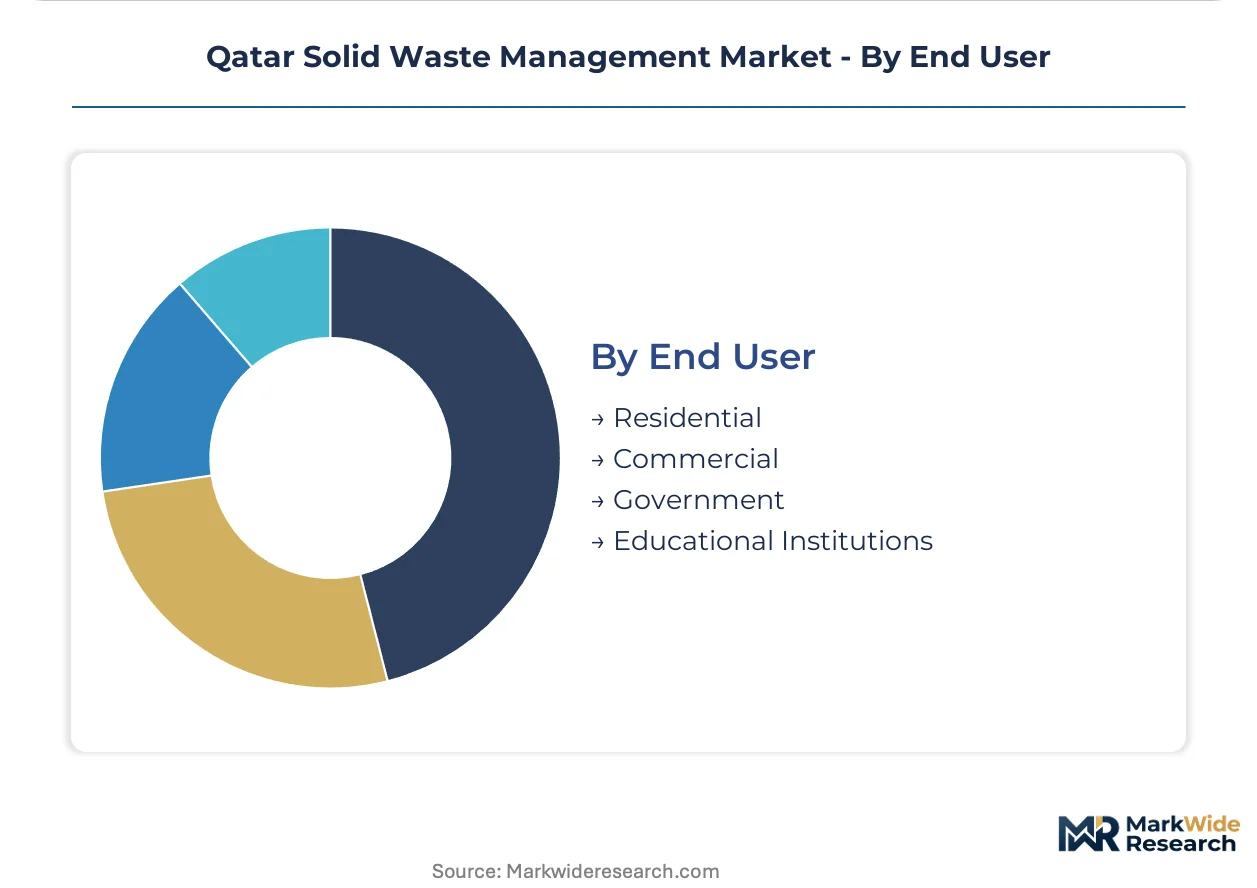
- Residential:Household waste generation tied to Doha and Lusail population density. Source-separation mandates under Ministry sorting requirements are expanding recycling participation rates in municipal collection zones.
- Commercial:Retail, hospitality, and office waste streams with heterogeneous composition. Food service organic waste and packaging materials dominate volume, driving demand for segregated collection infrastructure.
- Government:Public facility and infrastructure waste managed through performance-based service contracts. Circular economy procurement criteria now require documented recycling rates and material recovery certificates.
- Educational Institutions:Campus waste from Qatar Foundation and university clusters with sustainability visibility requirements. Long-term performance contracts with guaranteed diversion metrics are displacing per-tonne fee structures.
Contract reliability favors Government accounts; sustainability-driven procurement innovation centers on Educational Institutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Qatar's waste management consumption mix diverges from temperate markets through its reliance on engineered landfilling and mechanical sorting rather than biological decomposition, with arid climate constraints elevating leachate containment and material recovery priorities over organic processing pathways.
Doha Metropolitan Area
Doha's dense residential corridors and commercial zones generate the bulk of municipal collection volumes under Ministry of Municipality and Environment diversion mandates. Source-separation requirements are expanding recycling participation rates across municipal collection zones. The capital's hospitality and food service clusters create viable feedstock economics for anaerobic digestion facilities processing organic waste streams.
Lusail City
Mega-project construction pipelines in Lusail are mandating dedicated construction and demolition debris recycling infrastructure at scale. The Supreme Committee for Delivery and Legacy enforced compliant waste management protocols during infrastructure buildout. Long-term performance-based service contracts with guaranteed diversion metrics are displacing traditional per-tonne fee structures among institutional clients.
Al Wakrah and Al Rayyan Municipalities
Expanding residential populations in these southern and western municipalities are extending collection network coverage beyond Doha's core. Ministry sorting requirements are driving deployment of segregated collection infrastructure into newly developed zones. Workforce-intensive logistics operations serving these areas face visa policy volatility and accommodation cost pressures.
Ras Laffan Industrial Zone
Qatar's energy and petrochemical hub generates industrial process residues and hazardous byproducts requiring specialized treatment. Limited licensed hazardous waste facility capacity concentrates disposal options and elevates compliance costs for industrial generators. Industrial symbiosis platforms linking waste-to-resource exchanges between Ras Laffan and urban construction sites remain underdeveloped.
Education City and Qatar Foundation Cluster
Campus waste from university and research facilities carries sustainability visibility requirements driving procurement innovation. Circular economy procurement criteria now require documented recycling rates and material recovery certificates in public sector tenders. Automated optical sorting systems paired with artificial intelligence classification are rendering obsolete manual picking stations in facilities serving this cluster.
Qatar Solid Waste Management Market Competitive Landscape
Capability concentration sits with integrated operators possessing in-house treatment assets; scale advantage sits with workforce-intensive collection networks serving construction and commercial corridors. The vendor base organizes around three strategic archetypes: multi-service environmental platforms, specialized hazardous waste handlers, and regional logistics specialists with municipal contract anchoring. Competitive dynamics center on long-term performance-based contracting and technology upgrade cycles rather than price-based tonnage competition.
Within the integrated platform tier, Veolia leverages its multi-service positioning across Qatar's waste infrastructure value chain. Dulsco Qatar anchors workforce-intensive collection networks serving construction zones and commercial districts. Bee'ah Qatar occupies a position aligned with advanced sorting capabilities and national sustainability targets. These three exemplify contrasting pathways for capturing recurring maintenance and technology upgrade revenue under evolving landfill diversion mandates.
| Leading Market Players |
|---|
| Dulsco Qatar |
| Al Haya Environmental Group |
| Veolia |
| Elite Waste Management |
| Power Waste Management & Transport Co. WLL |
| Averda Environmental Services |
| Bee'ah Qatar |
| Green Waste Management Sewerage Services LLC |
| Seashore Group |
| Others |
Value Network & Pricing Analysis
European sorting equipment manufacturers anchor Qatar's material recovery facility upgrade cycle, concentrating capital expenditure leverage with Veolia and Bee'ah Qatar as integrated operators capture recurring technology refresh revenue. Ministry of Municipality and Environment grant funding for optical sorting deployments tilts contract economics toward output-linked performance fees rather than traditional tonnage-based collection rates.
Pricing Analysis
Long-term performance-based service contracts dominate Qatar's institutional waste management procurement, displacing per-tonne disposal fees among Lusail and Education City clients. Price differentiation rests on diversion rate guarantees and material recovery certification tiers mandated under circular economy procurement criteria. Cost compression in workforce-intensive collection operations stems from visa policy volatility and accommodation cost pressures. Municipal accounts exhibit highest price sensitivity due to budgetary constraints, while hazardous waste generators accept premium pricing given limited licensed facility capacity.
Supply Chain Analysis
Tariff exposure between Germany and Qatar elevates capital costs for automated sorting and anaerobic digestion plant imports. Equipment sourcing concentrates in Germany, Italy, and the Netherlands for optical sorting systems and mechanical processing units. Raw material dependencies span specialized steel alloys for containment vessels, membrane technologies for leachate management, and control systems for robotics integration. Single-source vulnerability concentrates around European OEMs for near-infrared spectroscopy components. Distribution runs through Ministry-licensed facility operators and EPC contractors serving Ras Laffan and Lusail infrastructure projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qatar's solid waste management market rewards service-attach revenue models, with aftermarket maintenance and technology upgrade cycles expanding faster than initial collection fleet deployment. Recurring performance-based contracts now outpace equipment sales growth among integrated operators.
For Market Incumbents: Insulate contract renewal rates by embedding automated optical sorting assets within municipal collection zones before competitive bidding cycles. Ministry grant funding windows favor early movers with deployed capacity. Backward integration into anaerobic digestion plant operations secures captive biogas offtake revenue. Defend against pure logistics specialists by transferring operational risk through guaranteed diversion metric structures. For New Entrants and Emerging Players: Pursue hazardous waste treatment licensing gaps in Ras Laffan industrial zone, where regulatory scarcity concentrates premium disposal demand. Industrial symbiosis platforms linking petrochemical byproducts to construction material recovery remain underdeveloped white space. Target performance-based contracting at Qatar Foundation campus clusters, where sustainability visibility requirements justify technology-forward positioning. Lead with circular economy certification capabilities to differentiate from incumbent collection networks. For Investors and Strategic Acquirers: Secondary-cycle assets sit with workforce-intensive regional logistics specialists lacking in-house treatment infrastructure. Long-term viability across the analysis window favors operators with anaerobic digestion or advanced sorting capabilities aligned with National Environment and Climate Change Strategy mandates. Acquisition targets should demonstrate documented material recovery rates and existing municipal contract anchoring. Watch for extended producer responsibility framework announcements as inflection indicators for reverse logistics service demand.| Strategic Initiative | Industry Significance |
|---|---|
| Anaerobic Digestion Capacity Buildout | Captures biogas revenue from Doha's hospitality waste streams under Ministry diversion mandates. |
| Automated Sorting Technology Licensing | Near-infrared spectroscopy deployment qualifies operators for output quality premiums and grant funding. |
| Hazardous Waste Treatment Joint Venture | Limited licensed capacity in Ras Laffan creates scarcity pricing for compliant industrial disposal. |
| Performance-Based Service Contracting | Transfers operational risk while locking in recurring revenue from Lusail mega-project clients. |
| Extended Producer Responsibility Partnership | Positions operators for packaging and electronics take-back regulations under pending frameworks. |
Research Methodology
The analysis maps collection logistics, material recovery facilities, treatment operations, and disposal infrastructure, each validated through facility managers, municipal procurement officers, EPC contractors, and aftermarket service heads. Primary interviews with Ministry of Municipality and Environment licensing officials and Supreme Committee for Delivery and Legacy compliance officers combined with secondary validation from customs records, project development databases, and SEC filings of listed environmental services operators. Bottom-up contract volume analysis and top-down regulatory mandate sizing provided triangulation across the Qatar market.
Assumptions held fixed include Ministry landfill diversion targets and Lusail construction pipeline completion timelines, while anaerobic digestion feedstock economics and extended producer responsibility implementation pace were varied across sensitivity scenarios. Segmentation modeling spanned waste type, service modality, processing technology, and end-user contract structure. CAGRs derived from installed capacity expansion rates and per-capita waste generation elasticities tied to urbanization patterns. Forecast inputs included hospitality sector organic waste stream volumes and optical sorting equipment deployment schedules.
Sensitivities concentrate around Ministry grant funding continuity, European equipment import cost fluctuations, and hazardous waste licensing timeline revisions. Forecasts reflect documented regulatory mandates and disclosed project pipelines without assuming acceleration beyond announced policy frameworks. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste Management & Pollution Control
Saudi Arabia Medical Waste Management Market
Waste Management & Pollution Control
Recyclate PET Market
Waste Management & Pollution Control
Asia-Pacific Hazardous Waste Handling Automation Market
Waste Management & Pollution Control
Hazardous Waste Management Market
Waste Management & Pollution Control
Paper Recycling Market
Waste Management & Pollution Control
North America Trash Bags Market
Waste Management & Pollution Control
North America Municipal Solid Waste Management Market
Waste Management & Pollution Control
Biomedical Waste Management Market
Waste Management & Pollution Control
Singapore Waste Management Market
Waste Management & Pollution Control
Asia-Pacific Municipal Solid Waste Management Market
Waste Management & Pollution Control
Vacuum Waste Systems Market
Waste Management & Pollution Control
Compostable and Biodegradable Refuse Bags Market
Waste Management & Pollution Control
Europe Industrial Waste Management Market
Waste Management & Pollution Control
Waste Paper Management Market
Waste Management & Pollution Control
US Municipal Solid Waste Management Market
Waste Management & Pollution Control
Construction and Demolition Waste Management Market