
 China Waste Management Market | 2026-2036
China Waste Management Market Size, Share, and Industry Trends Forecast 2026-2036
China Waste Management Market Outlook
Buyer concentration among municipal governments and large industrial parks is rebalancing as county-level administrations gain procurement autonomy under China's decentralized environmental enforcement reforms. China Everbright Environment Group leverages its incineration technology platform to anchor projects across the Pearl River Delta. Beijing Enterprises Environment Group sustains dominance in northern China through integrated collection-to-disposal contracts. Zhejiang Weiming Environment Protection specializes in small-scale municipal systems, competing aggressively for county-level tenders in Zhejiang and Fujian provinces.
China waste management encompasses the systematic collection, transportation, treatment, and disposal of municipal solid waste, industrial byproducts, hazardous materials, and electronic scrap, with modern facilities achieving thermal efficiency above 25% in waste-to-energy incinerators and leachate containment systems meeting GB 16889 discharge standards. The primary purpose is to reduce environmental contamination while recovering energy and recyclable materials for reinsertion into industrial supply chains. Municipal solid waste commands the largest volume pool under current treatment method segmentation, though hazardous waste processing extracts premium margins due to stringent MEE permitting requirements and limited licensed facility capacity. Incineration is displacing landfilling as the dominant treatment method in eastern provinces where land scarcity and Shanghai's zero-landfill policy have eliminated disposal site availability.
MEE enforces waste classification mandates and emission limits that dictate facility design standards and operating permits across all provincial jurisdictions. SAMR coordinates with GB standard-setting bodies to align product recyclability rules with treatment infrastructure capabilities, tightening market access for equipment suppliers lacking certification compliance. NMPA intersects indirectly through pharmaceutical waste handling protocols that flow into hazardous waste streams. Stakeholders must monitor how provincial carbon intensity targets reshape tipping fee structures and incinerator tariff negotiations.
Market Dynamics
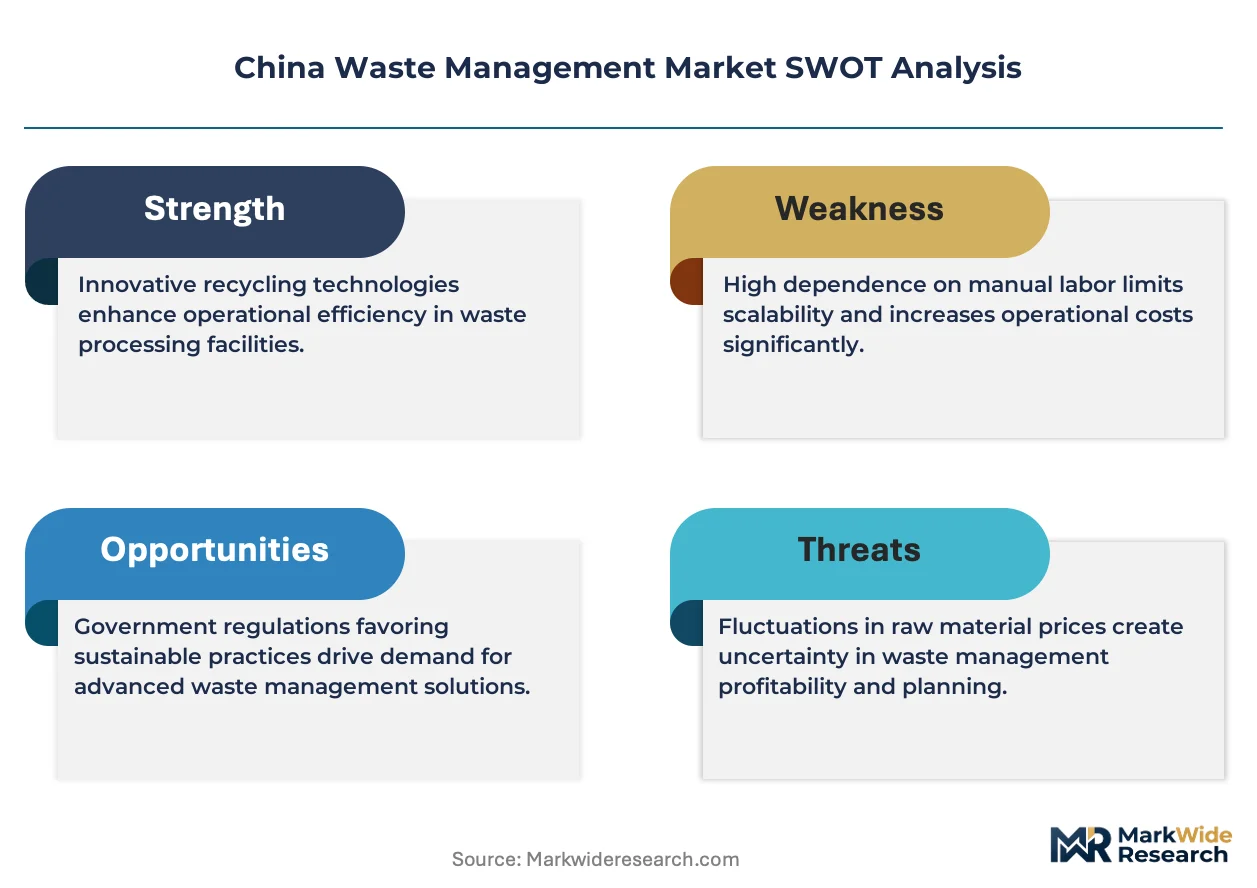
China's dual carbon goals are compressing landfill capacity and forcing municipal governments to accelerate incineration buildouts, with MEE emission limits tightening faster than operator upgrade cycles can absorb.
Growth Catalysts
- MEE emission standard tightening:GB 18485-2014 revisions are forcing facility retrofits that expand equipment replacement demand across the Yangtze River Delta.
- County-level procurement autonomy:Decentralized environmental enforcement reforms are unlocking tender volumes previously captured by provincial SOEs.
- Smart collection systems:IoT-enabled bin monitoring is reducing collection fleet mileage by twenty-five percent in pilot Shanghai districts.
Market Restraints
- Land scarcity in eastern provinces:Shanghai's zero-landfill policy has eliminated greenfield disposal site availability, capping landfill-dependent operator expansion.
- Licensed hazardous waste facility concentration:MEE permitting bottlenecks restrict treatment capacity for pharmaceutical and chemical sector byproducts.
- Natural gas price volatility:Auxiliary fuel costs for incinerator startup and emission control are squeezing operator margins in Jiangsu province.
Strategic Opportunities
- Zhejiang county-level tender waves:Small-scale municipal system contracts are proliferating as fiscal decentralization reaches township administrations.
- Waste-to-energy tariff renegotiation:Provincial carbon intensity targets are reshaping grid connection pricing for incinerator output.
- Construction and demolition waste streams:Urban renewal projects in tier-one cities are generating recyclable aggregate volumes lacking dedicated processing infrastructure.
Industry Challenges
- Leachate treatment operator certification:GB 16889 discharge compliance requires specialized technical staff that county-level facilities struggle to retain.
- Incinerator grate technology integration:Imported combustion systems demand retrofit compatibility with domestic flue gas cleaning trains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Waste Management Market |
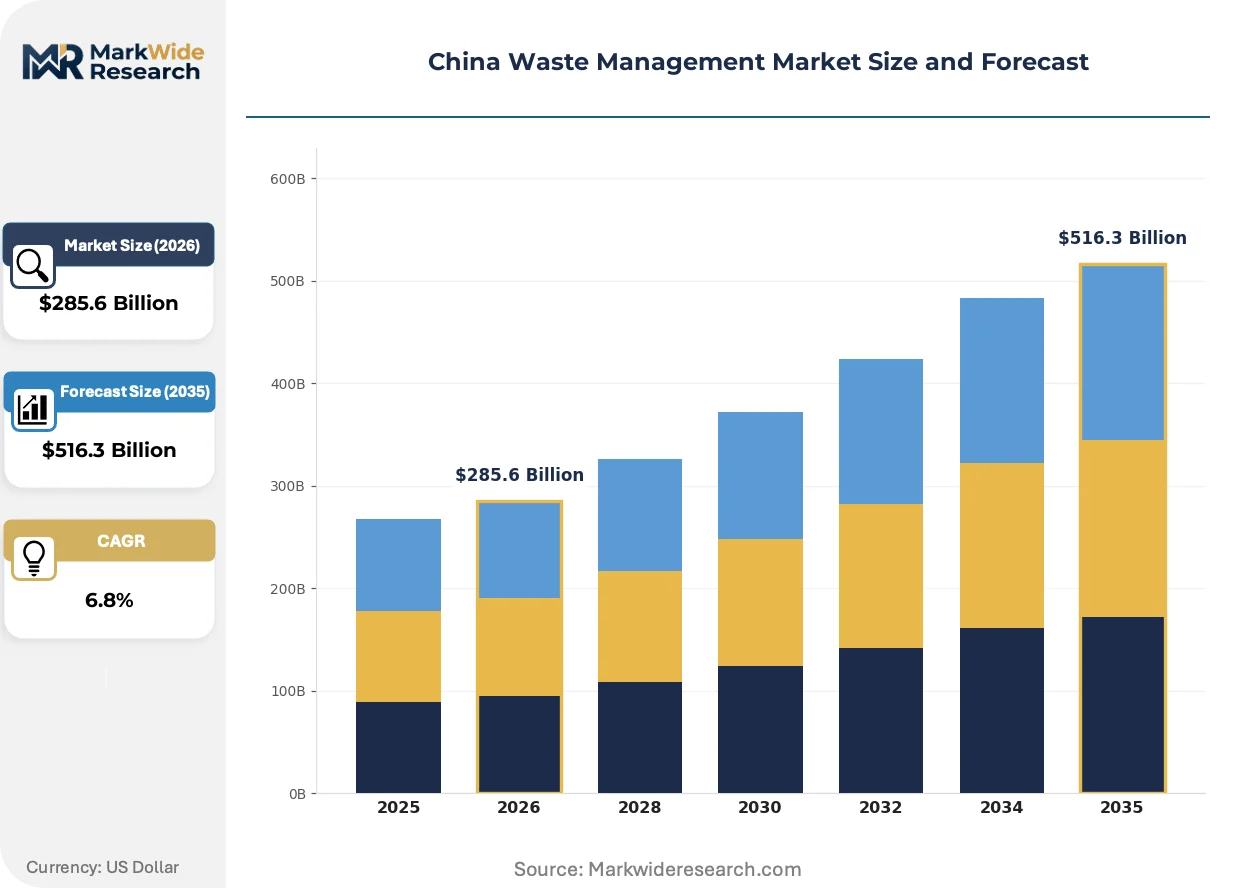
| Market Size in 2026 | $285.6 Billion |
| Market Size in 2035 | $516.3 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Waste Type: Municipal Solid Waste, Industrial Waste, Hazardous Waste, Electronic Waste Treatment Method: Recycling, Incineration, Landfilling, Composting Application Sector: Residential, Commercial, Industrial, Institutional Service Type: Collection, Transportation, Disposal, Treatment |
| Companies Covered | China Everbright Environment Group Ltd., Beijing Enterprises Environment Group Ltd., Zhejiang Weiming Environment Protection Co. Ltd., Chongqing Sanfeng Environment Group Corp Ltd., Qingdao Huicheng Environmental Technology Co. Ltd., Tus-Sound Environmental Resources Co., Ltd., Capital Environmental Holdings Ltd., Veolia Environnement S.A., Sembcorp Industries Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Waste Management Market Strategic Shifts
Digitalization and carbon accounting are converging to transform how waste streams are tracked, priced, and valorized across China's municipal and industrial treatment infrastructure.
Grate combustion systems with integrated AI-based combustion control are modularizing project deployment timelines. Municipal operators in Jiangsu province are piloting containerized incinerator units that slash civil works duration. This modularizing architecture is compressing the traditional eighteen-month construction cycle into nine-month phases.
MEE's carbon emission accounting framework for waste treatment facilities is mandating continuous monitoring equipment installation. Incinerator operators must now report Scope 1 and Scope 2 emissions to provincial environmental bureaus quarterly. Northern China operators are responding by retrofitting heat recovery systems to capture previously vented thermal energy.
County governments are unbundling collection and disposal contracts that provincial SOEs previously held as integrated concessions. Tender documents in Fujian province now specify separate performance metrics for collection frequency versus treatment throughput. This fragmentation is most visible in Zhejiang's municipal waste sector, where township-level procurement autonomy is accelerating competitive bidding cycles.
China Waste Management Market Segmentation
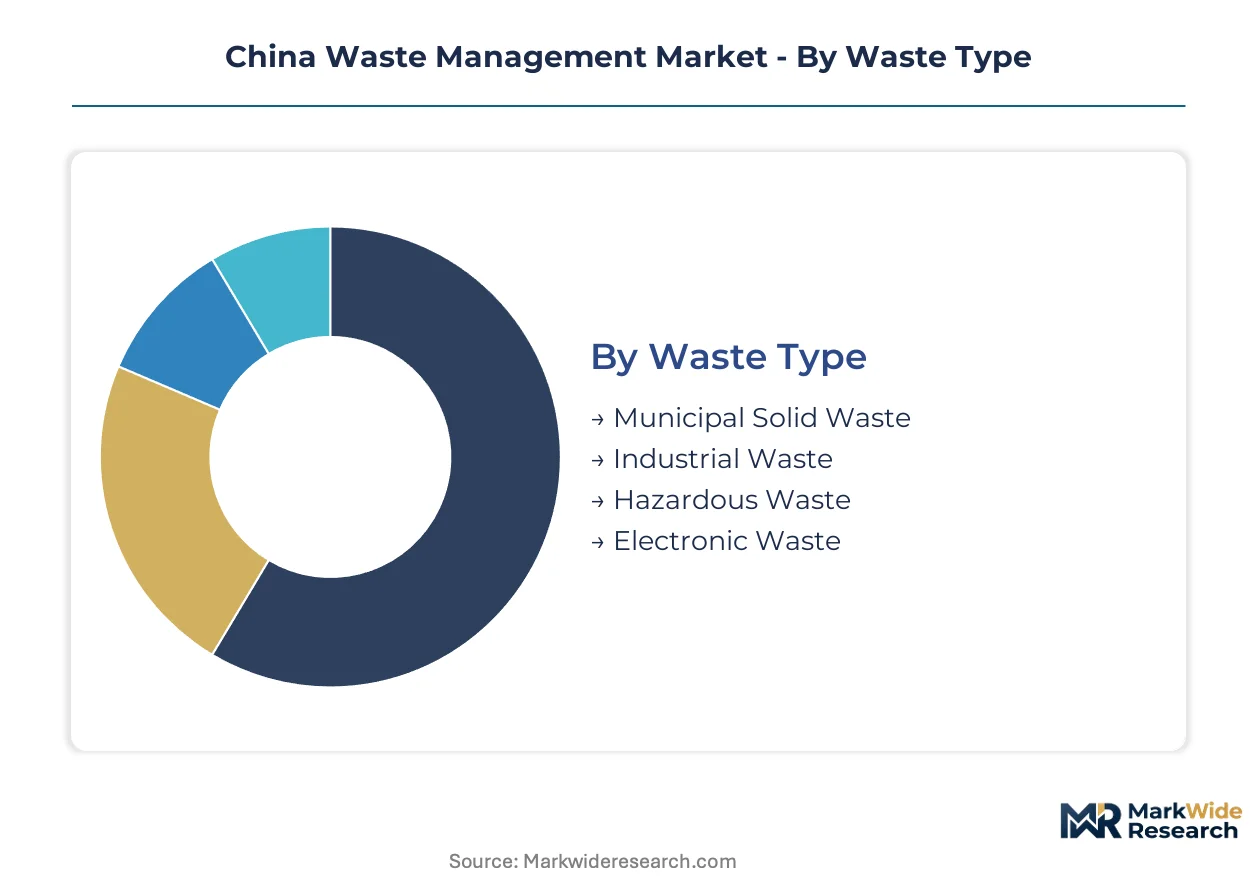
Waste type classification determines MEE permitting pathways and facility investment thresholds across China's provincial jurisdictions. Treatment method segmentation directly shapes carbon intensity accounting under dual carbon compliance frameworks.
Waste Type:
MEE licensing requirements escalate sharply from municipal through hazardous categories, with electronic waste demanding MIIT registration alongside environmental permits.
- Municipal Solid Waste:Comprises household-generated refuse, food scraps, and packaging materials with moisture content typically exceeding 50%. Demand concentrates in Shanghai and Jiangsu province where zero-landfill mandates have eliminated disposal alternatives and forced incinerator capacity expansion.
- Hazardous Waste:Encompasses chemical residues, medical byproducts, and contaminated solvents requiring specialized containment and thermal destruction above 1100°C. Pharmaceutical manufacturers in Zhejiang province generate concentrated volumes that outstrip licensed treatment facility capacity, creating persistent MEE permitting bottlenecks.
- Industrial Waste:Includes manufacturing slag, process wastewater solids, and non-hazardous production discards from heavy industry clusters.
- Electronic Waste:Covers discarded circuit boards, batteries, and consumer electronics containing recoverable rare earth elements and precious metals.
Leading the category by volume: Municipal Solid Waste. Growing fastest: Electronic Waste.
Treatment Method:
Capital intensity and operating margins diverge sharply across methods, with incineration demanding the highest upfront investment but capturing premium tariffs under renewable energy pricing mechanisms.
- Incineration:Grate combustion systems achieve thermal efficiency above 25% while generating grid-connected electricity. Yangtze River Delta municipalities are prioritizing this method as Shanghai's zero-landfill policy eliminates land-based disposal alternatives.
- Recycling:Mechanical and chemical recovery processes extract ferrous metals, plastics, and paper fibers for reinsertion into industrial supply chains. Zhejiang province hosts the densest concentration of integrated recycling parks serving Yangtze Delta manufacturing clusters.
- Landfilling:Engineered containment with leachate collection systems remains prevalent in western provinces where land availability persists.
- Composting:Aerobic biological decomposition of organic fractions produces soil amendments for agricultural applications.
Highest capital requirement: Incineration. Steepest expansion trajectory: Recycling.
Application Sector:
Procurement autonomy and contract structures vary substantially across sectors, with industrial generators negotiating directly while residential services remain municipal mandates.
- Residential:Household waste generation tied to urban population density and consumption patterns. Tier-one cities are deploying IoT-enabled smart collection systems that reduce fleet mileage.
- Commercial:Retail, hospitality, and office complexes generate heterogeneous waste streams with high recyclable content. Shanghai commercial districts are piloting source-separation mandates with financial penalties for non-compliance.
- Industrial:Manufacturing facilities produce volume-intensive process waste requiring customized collection frequencies.
- Institutional:Schools, hospitals, and government buildings generate regulated medical and confidential document destruction streams.
Largest contract value concentration: Industrial. Fastest procurement decentralization: Residential.
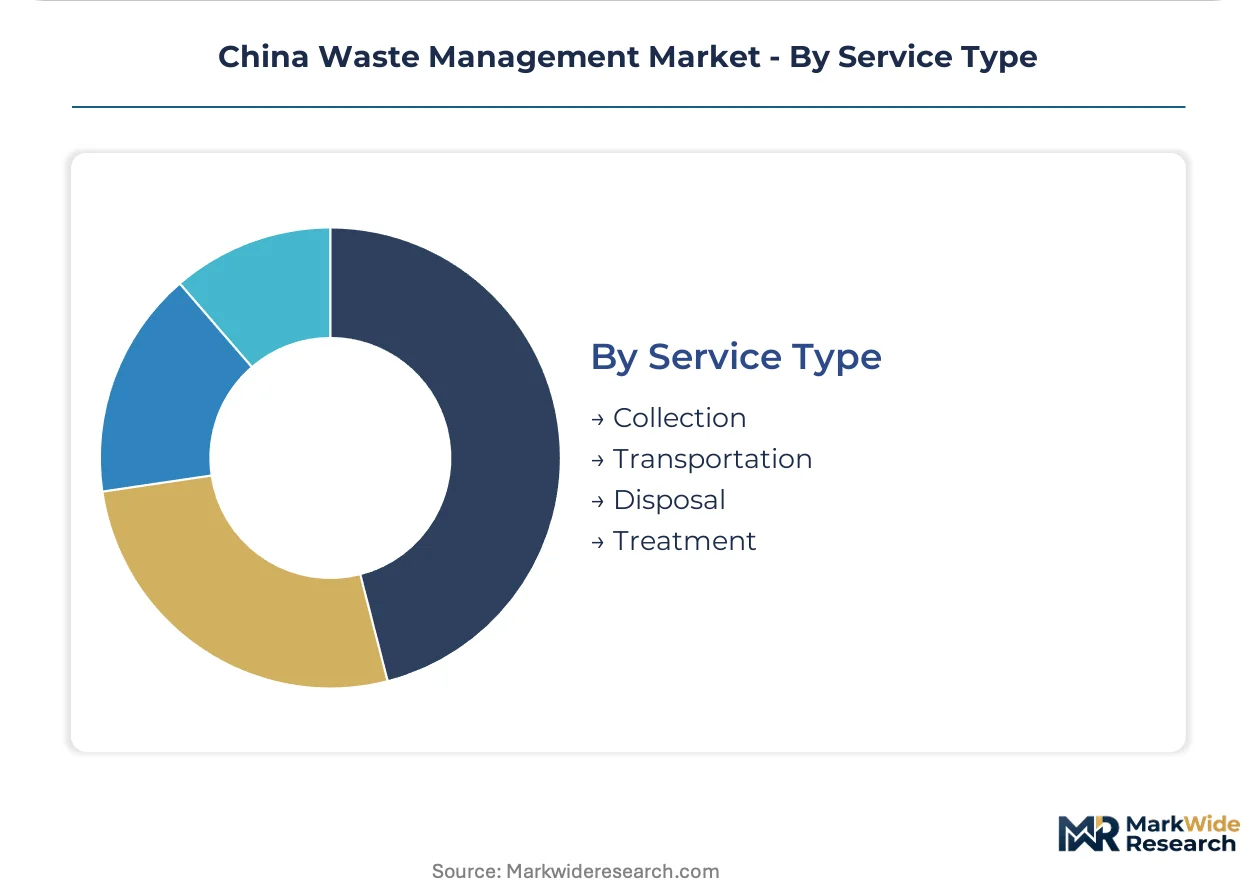
Service Type:
Unbundling of integrated concessions is fragmenting the value chain, with county governments now separating collection tenders from disposal operations.
- Collection:Fleet-based pickup services with route optimization through GPS and bin-level sensors. Jiangsu province operators are achieving twenty-five percent mileage reductions through smart monitoring deployment.
- Treatment:Physical, chemical, and thermal processing to reduce volume and recover materials or energy. MEE emission standards for treatment facilities are tightening faster than upgrade cycles can absorb.
- Transportation:Specialized vehicle fleets with sealed containment for hazardous and medical waste categories.
- Disposal:Final placement in landfills or ash residue repositories meeting GB 16889 discharge standards.
Greatest margin pressure: Transportation. Fastest technology adoption: Collection.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Yangtze River Delta municipalities anchor procurement volume for smart collection systems and incineration capacity. Provincial environmental bureaus enforce divergent MEE emission timelines that reshape equipment replacement cycles.
Yangtze River Delta
Shanghai's zero-landfill policy and Jiangsu's incineration buildout drive equipment demand. MEE's GB 18485-2014 revisions force facility retrofits across the cluster. Suzhou and Hangzhou municipal governments are unbundling collection tenders from disposal operations.
Pearl River Delta
Guangdong province's manufacturing density generates industrial waste volumes exceeding licensed treatment capacity. SAMR coordinates GB standard alignment with waste classification infrastructure. Shenzhen and Dongguan are piloting IoT-enabled bin monitoring systems.
Beijing-Tianjin-Hebei
Capital region air quality mandates accelerate incinerator emission control upgrades. Dual carbon goals compress landfill capacity in Hebei province. Tianjin port logistics support hazardous waste import processing for northern chemical clusters.
Sichuan-Chongqing
Western land availability sustains landfill-dependent operations longer than eastern provinces. Provincial carbon intensity targets reshape grid connection pricing for waste-to-energy facilities. Chengdu municipality is deploying containerized incinerator units.
Shandong Peninsula
Heavy industry concentration in Qingdao and Yantai generates construction and demolition waste streams lacking dedicated processing infrastructure. County-level fiscal decentralization unlocks tender volumes previously captured by provincial SOEs. Jinan is expanding procurement autonomy for township administrations.
China Waste Management Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue smart collection technology and modular incineration systems. The market structures around three player tiers: state-owned enterprises with integrated concessions, specialized municipal system providers, and international operators with technology licensing platforms. Strategic archetypes include scale-driven incineration specialists, county-level tender competitors, and digital infrastructure integrators. Competitive moves concentrate on unbundling historically integrated contracts and retrofitting emission control systems ahead of MEE deadline tightening.
Within the state-owned enterprise tier, China Everbright Environment Group Ltd. and Beijing Enterprises Environment Group Ltd. occupy positions anchored across coastal megacity clusters. Zhejiang Weiming Environment Protection Co. Ltd. exemplifies the county-level specialist archetype competing for decentralized tenders. These three entities represent divergent scale-positioning strategies: the first two anchor multi-province integrated concessions, while the third pursues fragmentation opportunities in township procurement.
| Leading Market Players |
|---|
| China Everbright Environment Group Ltd. |
| Beijing Enterprises Environment Group Ltd. |
| Zhejiang Weiming Environment Protection Co. Ltd. |
| Chongqing Sanfeng Environment Group Corp Ltd. |
| Qingdao Huicheng Environmental Technology Co. Ltd. |
| Tus-Sound Environmental Resources Co., Ltd. |
| Capital Environmental Holdings Ltd. |
| Veolia Environnement S.A. |
| Sembcorp Industries Ltd. |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between MEE-licensed hazardous waste operators and unlicensed landfill contractors manifests in both tariff structures and equipment sourcing networks. Premium incineration facilities command grid-connected electricity tariffs under renewable energy pricing mechanisms, while county-level landfill operators face compressed tipping fees as eastern provinces eliminate disposal site availability.
Pricing Analysis
Warranty and long-term service bundling separate premium grate combustion system suppliers from commodity equipment vendors in procurement negotiations. Three-tier pricing structure across premium, standard, and economy levels tracks MEE emission compliance tiers, with GB 18485-2014 retrofit mandates accelerating price differentiation by certification grade. Pricing pressure stems from natural gas volatility squeezing auxiliary fuel budgets in Jiangsu province incinerator operations. County-level municipal governments exhibit highest price sensitivity due to fiscal decentralization constraints, while Yangtze River Delta megacity clusters prioritize technology performance over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with German and Japanese grate combustion technology licensors dominating high-efficiency incinerator core components. Domestic Chinese fabrication anchors flue gas cleaning trains and leachate containment systems. Raw material dependencies center on specialty steel alloys, ceramic refractory linings, and emission control catalysts. Tariff exposure on imported combustion systems amplifies total installed cost volatility for eastern province operators. Distribution runs through provincial SOE procurement channels and county-level tender platforms with diverging technical specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where MEE emission standard tightening constructs a barrier-to-entry moat favoring operators with pre-installed continuous monitoring infrastructure and licensed hazardous waste capacity.
For Market Incumbents: Lock in county-level collection concessions before township procurement autonomy fragments tender volumes further. Secure backward integration into smart bin sensor manufacturing to capture IoT-enabled fleet optimization margins. Threat substitution looms from modular containerized incinerator units compressing traditional eighteen-month construction cycles. Priority lever rests on heat recovery system retrofits to capture Scope 1 emissions value under provincial carbon accounting frameworks. For New Entrants and Emerging Players: County-level hazardous waste treatment gaps in Zhejiang pharmaceutical corridors represent the most penetrable white-space target. Construction and demolition waste recycling infrastructure in Shandong Peninsula urban renewal zones offers second-mover positioning ahead of dedicated processing buildouts. Go-to-market angle centers on containerized unit deployment partnerships with Chengdu and Chongqing municipalities seeking accelerated commissioning timelines. For Investors and Strategic Acquirers: Re-rating potential sits with county-level specialists holding MEE hazardous waste licenses given pharmaceutical sector volume growth outpacing licensed facility capacity. Long-term viability framing favors operators with integrated collection-to-disposal contracts in northern China where Beijing Enterprises Environment Group dominance faces decentralization pressure. Signal to watch is provincial carbon intensity target revisions reshaping waste-to-energy grid connection tariffs.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Incinerator Deployment | Containerized units compress Jiangsu construction cycles from eighteen to nine months. |
| Smart Collection System Integration | IoT-enabled bin monitoring reduces Shanghai district fleet mileage by twenty-five percent. |
| Heat Recovery Retrofit Investment | Scope 1 capture aligns with MEE quarterly carbon reporting mandates for northern operators. |
| County-Level Tender Pursuit | Fujian unbundling of collection and disposal contracts fragments historical SOE concessions. |
| Hazardous Waste License Acquisition | MEE permitting bottlenecks in Zhejiang pharmaceutical corridors constrain competitor entry. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with MEE regional enforcement officers, municipal procurement directors, incinerator plant managers, and hazardous waste facility operators combined with bottom-up installation database triangulation. Secondary sources included GB standard revision documents, provincial environmental bureau emission disclosures, SAMR certification registries, and Yangtze River Delta tender announcement archives.
Data-stream reconciliation across waste volume generation statistics, treatment capacity utilization rates, and equipment import manifests calibrated segmentation outputs. Modeled dimensions spanned waste type classification, treatment method capital intensity, application sector procurement autonomy, and service type unbundling progression across the analysis window. CAGRs derived from provincial buildout pipeline tracking and carbon intensity target trajectory modeling. Industry-specific inputs incorporated MEE permitting queue lengths and county-level fiscal decentralization implementation schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to MEE emission deadline acceleration and natural gas price volatility. Forecasts reflect documented assumptions regarding provincial carbon accounting framework adoption rates and county-level administrative capacity for tender unbundling. Specific risk factors include GB standard revision timing unpredictability and pharmaceutical sector waste volume growth variance. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste Management & Pollution Control
Landfill Compactor Market
Waste Management & Pollution Control
Saudi Arabia Medical Waste Management Market
Waste Management & Pollution Control
Compostable Straws Market
Waste Management & Pollution Control
Medical Waste Management Equipment Market
Waste Management & Pollution Control
Rare Earth Recycling Market
Waste Management & Pollution Control
Wood Recycling Market
Waste Management & Pollution Control
Landfill Gas Market
Waste Management & Pollution Control
UAE Biomedical Waste Management Market
Waste Management & Pollution Control
Waste Compactor Bins Market
Waste Management & Pollution Control
Global Pharmaceutical Waste Management Market
Waste Management & Pollution Control
Trash Rakes Market
Waste Management & Pollution Control
India E-Waste Management Market
Waste Management & Pollution Control
Household Composters Market
Waste Management & Pollution Control
Municipal Solid Waste Management Market
Waste Management & Pollution Control
Europe Municipal Solid Waste Management Market
Waste Management & Pollution Control
Compostable and Biodegradable Refuse Bags Market