
 Automated Material Handling Systems Market | 2026-2036
Automated Material Handling Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Automated Material Handling Systems Market Intelligence
The EU Green Deal is repositioning warehouse energy standards across European logistics networks, compelling facility operators to retrofit with energy-efficient conveyor systems and electrified transport. Daifuku Co. Ltd leverages its manufacturing scale to dominate high-throughput airport baggage and factory automation installations. SSI Schaefer anchors European distribution with dense shuttle-based storage architectures. Toyota Industries Corporation competes through in-house production of core electromechanical components.
Automated material handling systems integrate mechanical conveyance, robotic manipulation, and sensor-guided vehicles to move, sort, and store goods with minimal human intervention, typically operating at throughput rates exceeding manual methods by an order of magnitude. These systems serve manufacturing lines, distribution centers, and parcel hubs where labor cost volatility and order accuracy requirements intensify operational pressure. Conveyor systems and automated guided vehicles constitute the installed base majority, though vision systems and machine learning layers are capturing expanding margin pools as intelligence migrates from centralized controllers to edge devices. E-commerce fulfillment applications outpace warehouse automation in growth velocity, reflecting direct-to-consumer shipment proliferation and same-day delivery service level agreements.
FDA facility requirements shape pharmaceutical cleanroom material handling specifications, while OSHA ergonomic mandates accelerate palletizer deployment in consumer goods distribution. The EU Machinery Directive and CE marking enforce functional safety standards for robotic arms and sortation systems entering European logistics markets. Stakeholders must evaluate whether their technology roadmaps align with emerging carbon disclosure obligations and evolving interoperability protocols before committing to platform investments.
Market Dynamics
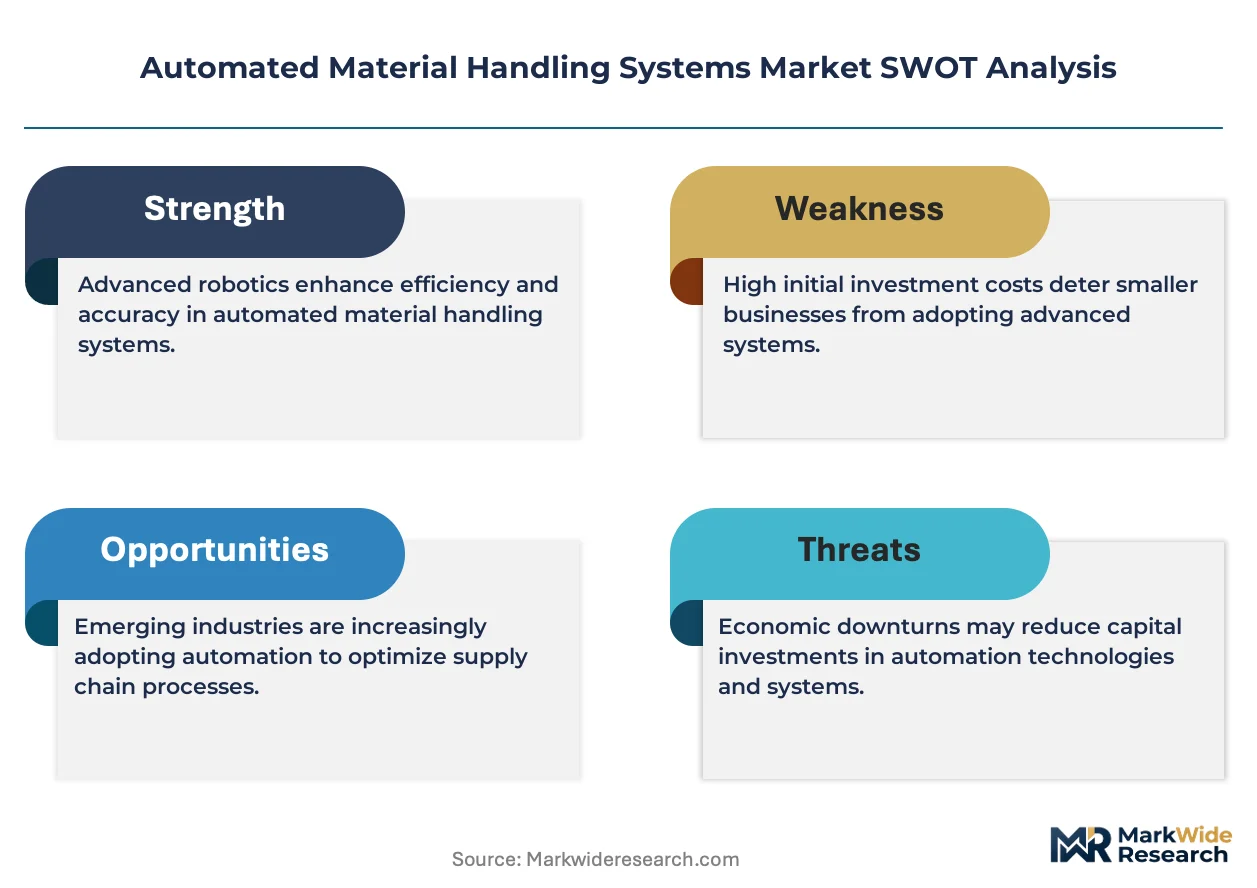
E-commerce fulfillment velocity is compressing warehouse automation procurement cycles, forcing operators to prioritize throughput-per-square-meter over ten-year depreciation schedules. Labor cost volatility in parcel hubs and pharmaceutical distribution is accelerating capital redeployment toward robotic sortation and autonomous mobile robots.
Growth Catalysts
- EU Green Deal carbon mandates:Warehouse operators in Germany and France face binding energy-efficiency targets, compelling retrofit investments in electrified conveyor networks and regenerative drive systems.
- Pharmaceutical cold-chain integrity:FDA facility requirements for temperature-controlled material handling are expanding automated guided vehicle deployments in vaccine distribution centers.
- Same-day delivery SLAs:Consumer goods retailers in the United States are procuring shuttle-based storage architectures to compress order cycle times below four hours.
Market Restraints
- Steel and rare-earth input volatility:Permanent magnet costs for linear motor conveyors fluctuate with Chinese export quotas, squeezing system integrator margins.
- CE marking timeline friction:EU Machinery Directive compliance testing extends delivery schedules by four to six months for robotic arm deployments.
- Legacy warehouse infrastructure:Low-clearance facilities built before 2010 cannot accommodate high-bay shuttle systems without structural reinforcement.
Strategic Opportunities
- India warehouse automation gap:Third-party logistics penetration remains below fifteen percent, creating first-mover advantage for automated storage and retrieval system vendors.
- Battery-electric forklift convergence:Lithium-ion traction systems are converging with opportunity-charging infrastructure to displace propane fleets in food distribution.
- US Inflation Reduction Act credits:Clean energy manufacturing incentives subsidize domestic production of conveyor components and automated guided vehicle assemblies.
Industry Challenges
- Mechatronics technician scarcity:Maintenance of sensor-guided vehicles requires PLC programming and machine vision calibration skills that vocational pipelines have not scaled.
- Multi-vendor integration complexity:Harmonizing warehouse management software with third-party robotic arms demands custom middleware development that extends commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automated Material Handling Systems Market |
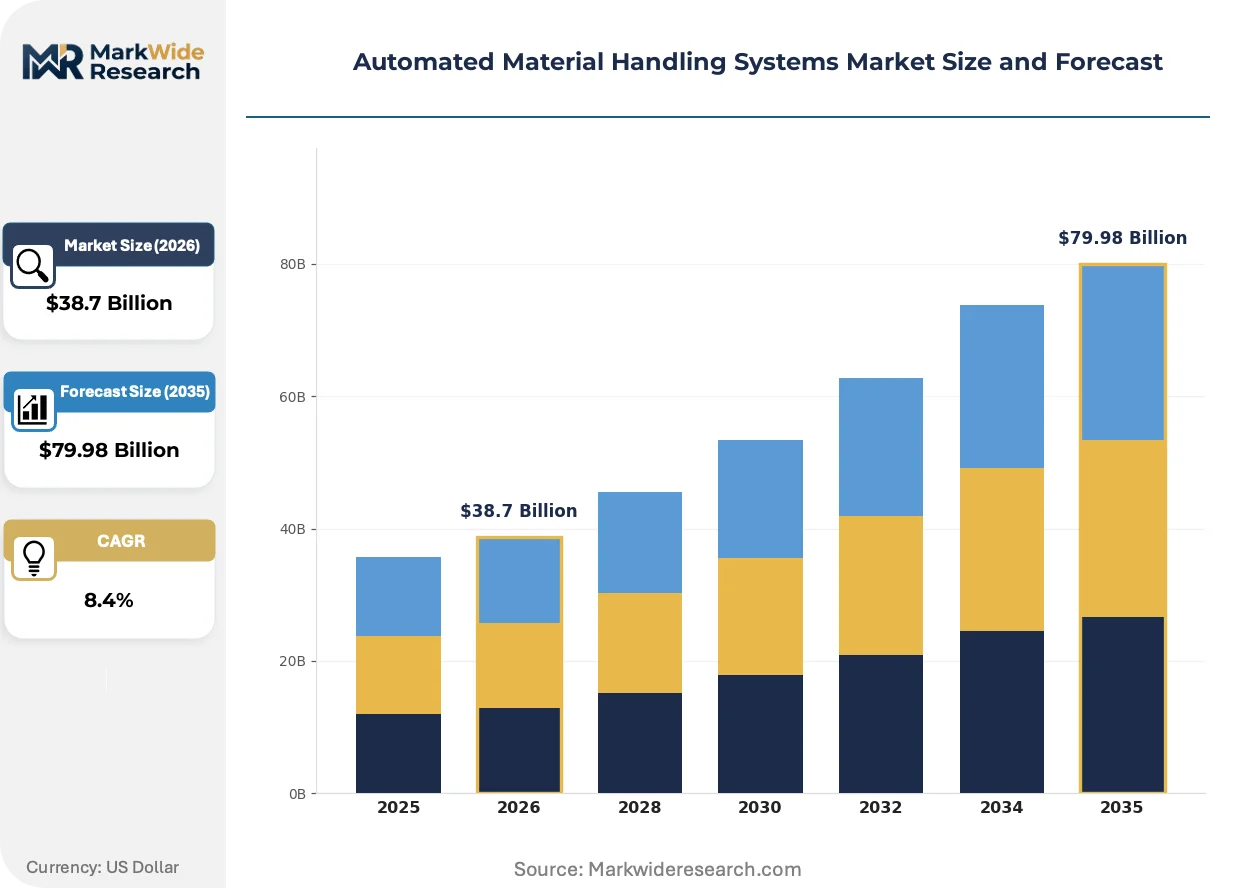
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $79.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conveyor Systems, Automated Guided Vehicles, Sortation Systems, Robotic Arms, Palletizers Technology: Barcode Scanning, Radio Frequency Identification, Vision Systems, Laser Guidance, Machine Learning Application: Warehouse Automation, Parcel Handling, Manufacturing Lines, Food Processing, E-commerce Fulfillment End User Industry: Logistics Providers, Consumer Electronics, Pharmaceuticals, Automotive Suppliers, Third-Party Logistics |
| Companies Covered | Daifuku Co. Ltd, KION Group, SSI Schaefer, Toyota Industries Corporation, Dematic, Honeywell Intelligrated, Jungheinrich AG, Swisslog, BEUMER Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automated Material Handling Systems Market Strategic Shifts & Innovations
Machine learning inference is migrating from cloud servers to edge devices mounted on conveyor frames and autonomous vehicles, enabling millisecond-level sortation decisions without network latency exposure. This architectural shift is compressing the hardware-software boundary in material handling procurement.
Computer vision systems are converging with predictive maintenance algorithms to identify bearing wear and belt misalignment before catastrophic failure. Parcel hubs in the United States are deploying these edge-AI packages to sustain twenty-three-hour daily operations. The technology is converging with digital twin simulations to compress commissioning timelines for greenfield distribution centers.
REACH chemical restrictions and RoHS substance limits are banning specific lubricants and coatings used in conveyor bearings and pneumatic actuators. European system integrators are reformulating component specifications to maintain CE marking eligibility. Pharmaceutical cleanroom material handling in Germany and Switzerland faces the strictest substitution timelines, driving demand for dry-running polymer bearings.
Leasing structures for automated material handling equipment are displacing traditional capital purchase models among mid-market third-party logistics providers. Monthly per-pallet pricing aligns vendor revenue with customer throughput, transferring utilization risk to equipment financiers. This shift is most visible in United States e-commerce fulfillment, where seasonal volume spikes punish fixed-asset balance sheets.
Automated Material Handling Systems Market Segmentation
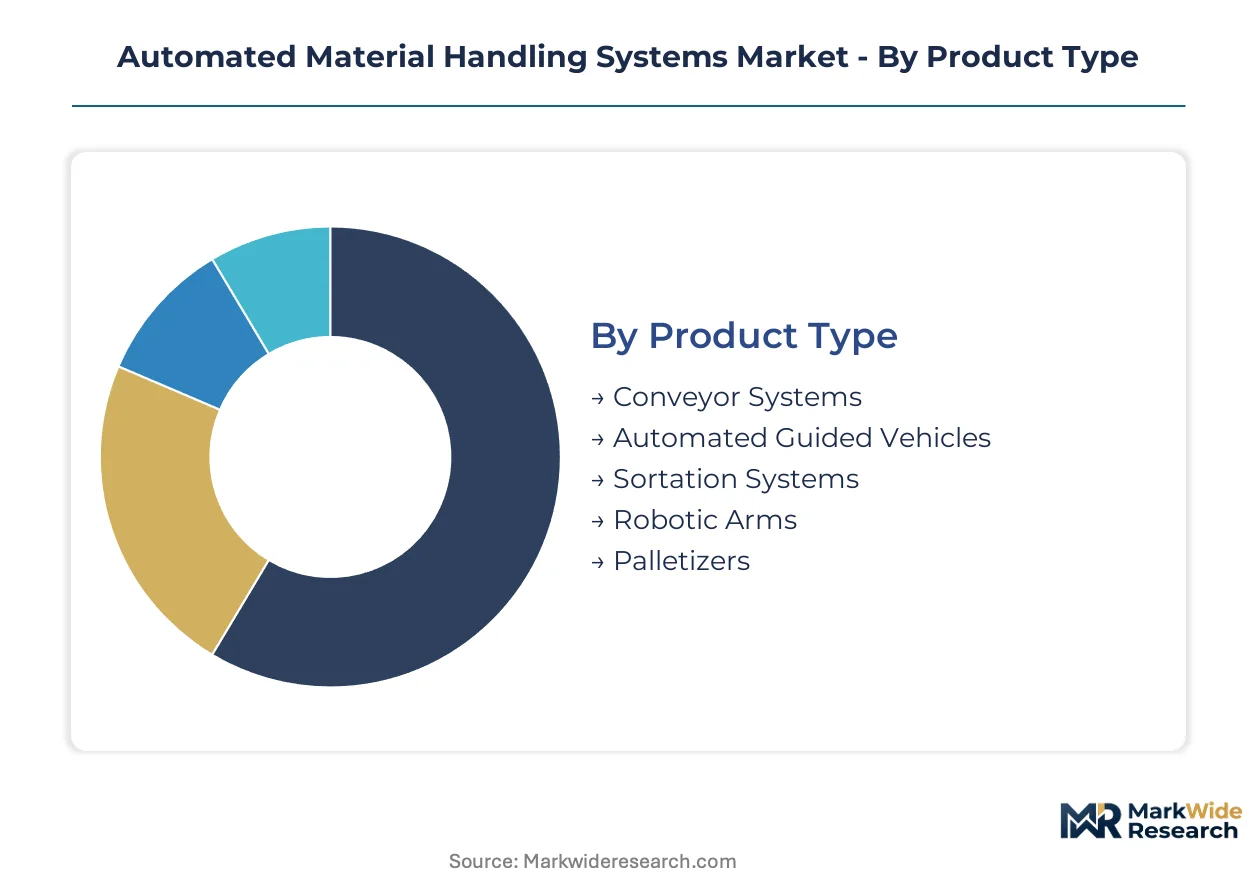
Material handling procurement diverges sharply across operational contexts, with throughput density requirements and labor cost structures dictating technology selection. Buyers prioritize different performance metrics—speed, accuracy, flexibility, or payload capacity—based on facility type and competitive pressure.
Product Type:
Facility operators select equipment based on throughput-per-square-meter targets and existing infrastructure constraints rather than technology novelty alone.
- Conveyor Systems:Belt and roller configurations transport cartons and totes through sortation and accumulation zones at sustained velocities. Demand concentrates in German automotive supplier plants and United States parcel hubs where OSHA ergonomic mandates accelerate palletizer deployment alongside dense conveyor networks.
- Automated Guided Vehicles:Laser-guided and vision-guided mobile platforms execute point-to-point transport without fixed infrastructure. Pharmaceutical distribution centers in Switzerland and Germany deploy these for FDA-compliant cold-chain integrity, with regenerative drive systems satisfying EU Green Deal energy targets.
- Sortation Systems:Cross-belt and tilt-tray mechanisms direct parcels to destination chutes at rates exceeding manual methods.
- Robotic Arms:Articulated and SCARA configurations execute pick-and-place operations with repeatability precision.
- Palletizers:Layer-forming and robotic palletizing systems stack unit loads for shipping efficiency.
Volume sits with Conveyor Systems; growth tilts toward Automated Guided Vehicles.
Technology:
Intelligence layers are migrating from centralized controllers to edge-mounted devices, compressing the hardware-software boundary in procurement decisions.
- Barcode Scanning:Linear and 2D imagers decode package identifiers at conveyor junctions with millisecond latency. Legacy warehouse infrastructure in France and Italy retains this technology where low-clearance facilities cannot accommodate vision system mounting heights.
- Vision Systems:Camera arrays with embedded GPUs execute dimensioning, damage detection, and OCR without host system dependency. United States e-commerce fulfillment centers deploy these for same-day delivery SLA compliance, with edge-AI packages sustaining twenty-three-hour daily operations.
- Radio Frequency Identification:UHF passive tags enable bulk reading of palletized inventory without line-of-sight constraints.
- Laser Guidance:LIDAR-based navigation enables AGV path planning in dynamic environments.
- Machine Learning:Predictive algorithms optimize batch sequencing and maintenance scheduling.
Barcode Scanning dominates installed base; Vision Systems are climbing the fastest.
Application:
End-use context determines capital intensity and payback period expectations, with e-commerce applications demanding highest automation density.
- E-commerce Fulfillment:Shuttle-based storage architectures and robotic picking cells compress order cycle times below four hours. United States retailers deploy these systems where seasonal volume spikes punish fixed-asset balance sheets and leasing structures displace traditional purchase models.
- Warehouse Automation:AS/RS and conveyor networks optimize cubic utilization in distribution facilities. German third-party logistics providers retrofit electrified systems to meet binding national carbon mandates under EU Green Deal frameworks.
- Parcel Handling:High-speed sortation and singulation equipment processes irregular polybags and boxes.
- Manufacturing Lines:Synchronized conveyor and AGV systems feed assembly stations with just-in-time precision.
- Food Processing:Stainless steel conveyors and washdown-rated robotics comply with sanitary design standards.
Warehouse Automation claims largest capital deployment; E-commerce Fulfillment shows steepest expansion trajectory.
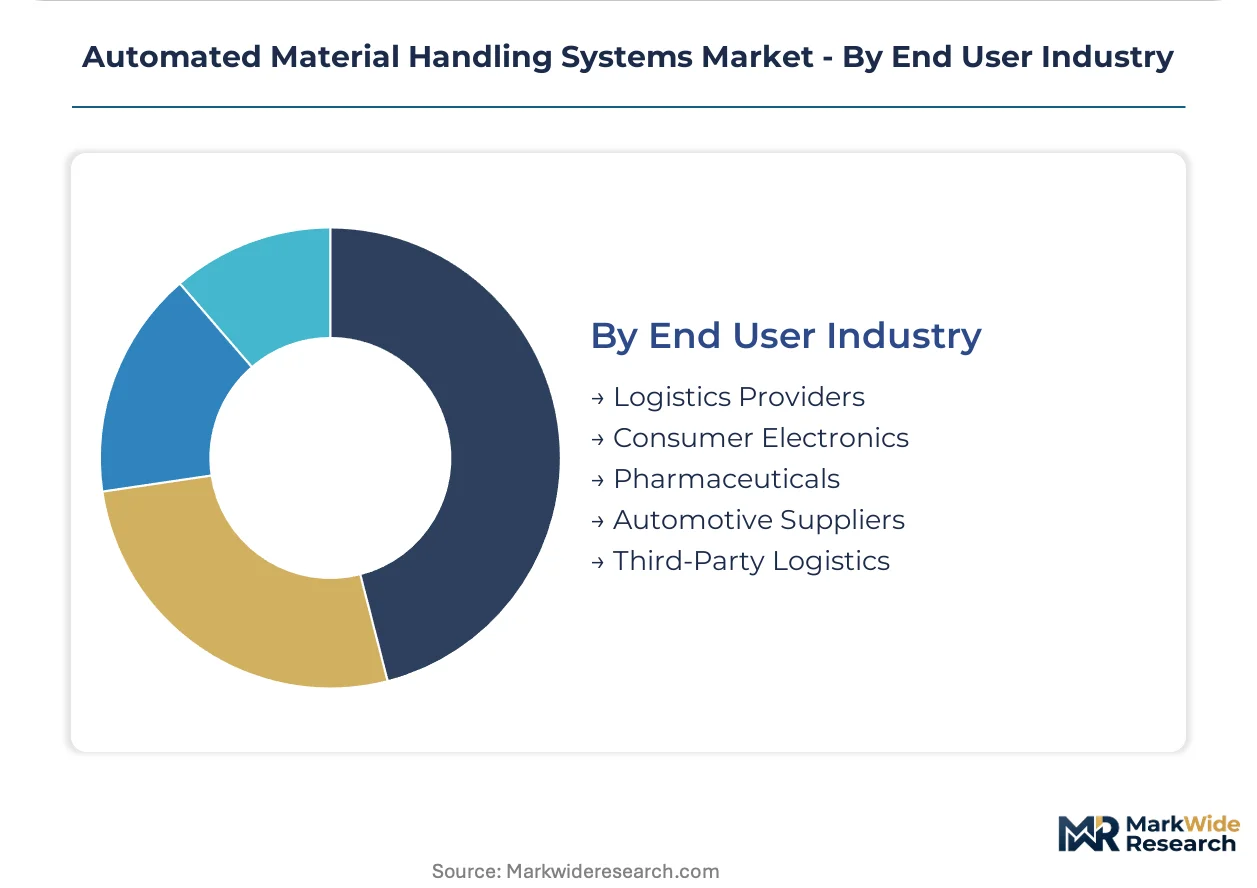
End User Industry:
Regulatory exposure and labor cost volatility create divergent automation urgency across vertical purchasing centers.
- Third-Party Logistics:Contract operators serving multiple clients require flexible automation that adapts to SKU proliferation and volume seasonality. India warehouse automation penetration below fifteen percent creates first-mover opportunity for system vendors targeting this customer type.
- Pharmaceuticals:Cleanroom-rated conveyors and temperature-controlled AGVs satisfy FDA facility requirements and EMA good distribution practice. German and Swiss facilities face strictest REACH chemical substitution timelines for lubricants and coatings.
- Logistics Providers:Integrated parcel and freight networks balance automation investment across hub-and-spoke infrastructure.
- Consumer Electronics:High-velocity fulfillment of small, high-value items demands precision sortation.
- Automotive Suppliers:Sequenced parts delivery to assembly plants requires synchronous material flow.
Third-Party Logistics drives equipment volume; Pharmaceuticals commands premium pricing tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing scale concentrates in Germany, China, and the United States, while consumption spreads across logistics networks in Switzerland, India, and France. Production clusters serve export demand for conveyor systems and automated guided vehicles. Facility operators in consuming regions prioritize retrofit compatibility over greenfield installations.
Germany
Automotive supplier plants in Bavaria and Baden-Württemberg drive conveyor system procurement for sequenced parts delivery. The EU Green Deal binds warehouse operators to national carbon mandates, compelling retrofit investments in electrified transport networks. Dense shuttle-based storage architectures dominate third-party logistics facilities in the Ruhr industrial corridor.
China
E-commerce fulfillment centers in the Yangtze River Delta and Pearl River Delta compress order cycle times below four hours. SAMR enforces GB standards for robotic system safety in logistics applications. Shenzhen and Hangzhou host the highest concentration of vision-guided vehicle deployments for parcel sortation.
United States
Parcel hubs across the Midwest and Southeast deploy high-speed sortation for same-day delivery SLAs. OSHA ergonomic mandates accelerate palletizer deployment in consumer goods distribution. Chicago and Dallas-Fort Worth anchor the largest automated storage and retrieval system installations serving retail networks.
Switzerland
Pharmaceutical distribution centers in Basel and Zurich deploy temperature-controlled automated guided vehicles for cold-chain integrity. Swissmedic and EMA good distribution practice requirements shape cleanroom material handling specifications. The country's precision manufacturing base supplies dry-running polymer bearings for REACH-compliant conveyor systems.
India
Third-party logistics penetration below fifteen percent creates first-mover opportunity for automated storage vendors. The PLI scheme subsidizes domestic production of conveyor components and battery-electric forklift assemblies. Maharashtra and Karnataka host emerging fulfillment center clusters serving e-commerce volume growth.
Automated Material Handling Systems Market Key Industry Players
The competitive structure tilts toward diversified industrial conglomerates with captive electromechanical component production. Tier-one players manufacture conveyor systems, automated guided vehicles, and robotic arms through in-house production networks. Mid-scale specialists compete on retrofit expertise for legacy warehouse infrastructure. Dominant competitive moves include backward integration into linear motor and sensor manufacturing, plus strategic partnerships with warehouse management software vendors.
Among Japanese industrial conglomerates, Daifuku Co. Ltd and Toyota Industries Corporation exemplify scale-driven archetypes with integrated manufacturing footprints. SSI Schaefer anchors the European specialist tier with dense shuttle-based storage architectures. These three occupy positions spanning airport baggage systems, factory automation, and distribution center retrofit markets.
| Leading Market Players |
|---|
| Daifuku Co. Ltd |
| KION Group |
| SSI Schaefer |
| Toyota Industries Corporation |
| Dematic |
| Honeywell Intelligrated |
| Jungheinrich AG |
| Swisslog |
| BEUMER Group |
| Others |
Cost & Logistics Intelligence
Captive in-house production of linear motors and sensor arrays anchors supply positioning for tier-one system integrators while insulating their pricing power against rare-earth volatility. This backward integration into electromechanical components allows dominant players to maintain margin stability when Chinese export quotas squeeze competitors dependent on spot-market magnet procurement.
Pricing Analysis
Margin tightening in mid-market conveyor systems traces to steel input volatility and the squeeze on system integrators without captive component production. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked European configurations from basic Asian imports and refurbished legacy installations. Pricing pressure accelerates in AGV segments as battery-electric forklift convergence commoditizes traction hardware. Third-party logistics providers show highest price sensitivity due to seasonal volume spikes, while pharmaceutical cleanroom operators absorb premium tiers for FDA-compliant temperature-controlled configurations.
Supply Chain Analysis
Domestic-content mandates under the US Inflation Reduction Act and India's PLI scheme are reshaping sourcing patterns for conveyor components and battery assemblies. Manufacturing gravity centers on Germany, China, and the United States, with precision bearings sourced from Switzerland and linear motor magnets drawing from Chinese rare-earth processing. Single-source vulnerability concentrates in permanent magnet supply chains subject to export quota disruption. Distribution runs through direct OEM sales for large installations and equipment financiers for mid-market leasing structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mechatronics technician scarcity constrains maintenance capacity across installed bases, propping system pricing for vendors with captive service networks. This supply bottleneck sustains premium capture for integrated solution providers.
For Market Incumbents: Cement market position through backward integration into edge-AI chipsets and regenerative drive manufacturing, insulating against rare-earth cost spikes. Acquire specialist vision-system vendors to close capability gaps in pharmaceutical cleanroom deployments. Expand captive technician training pipelines to lock in aftermarket service revenue.
For New Entrants and Emerging Players: Enter via India's sub-fifteen-percent warehouse automation penetration, targeting third-party logistics providers with modular shuttle systems engineered for low-clearance retrofit. Pursue battery-electric forklift convergence opportunities in food distribution through opportunity-charging infrastructure partnerships. Lead with leasing-based pricing to align with seasonal volume patterns.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified industrial conglomerates seeking warehouse automation exposure. Long-term viability favors vendors with software-defined architectures capable of absorbing machine learning inference migration. Target acquisition archetype: mid-scale specialists with proven retrofit expertise for legacy infrastructure. Monitor CE marking timeline friction as inflection signal—vendors with pre-certified modular platforms command scarcity premium.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Linear Motors | Captive magnet supply insulates margins from Chinese export quota volatility. |
| Edge-AI Hardware Migration | Millisecond sortation decisions reduce cloud dependency and network latency exposure. |
| Leasing Structure Expansion | Per-pallet pricing transfers utilization risk to equipment financiers in seasonal markets. |
| CE Marking Pre-Certification | Modular platforms compress four-to-six-month compliance timelines for robotic deployments. |
| Technician Training Pipeline Investment | PLC programming and machine vision skills scarcity creates captive service revenue lock-in. |
Research Approach
Trade association filings, customs import records, and SEC equipment manufacturer disclosures formed the secondary backbone, cross-referenced against primary interviews with warehouse operations directors, system integration engineers, and equipment procurement managers at third-party logistics providers. Bottom-up and top-down triangulation validated installation counts against capital expenditure disclosures and facility footprint expansions.
Analytical lenses combined bottom-up facility-level automation intensity modeling with top-down industrial construction spending flows across the projection horizon. Segmentation dimensions spanned product type, technology layer, application context, and end-user industry vertical. CAGRs derived from fitted growth curves anchored to disclosed backlog data and announced capacity expansions, with e-commerce fulfillment velocity and EU Green Deal retrofit mandates serving as primary demand-side inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sustained rare-earth export restriction or accelerated REACH chemical substitution timelines. Forecasts reflect assumptions regarding labor cost volatility persistence and interoperability protocol standardization. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Dry Bulk Handling System Market
Material Handling Equipment
Silo Bin Activators Market
Material Handling Equipment
Heavy Hex Nuts Market
Material Handling Equipment
Resistance Welding Products Market
Material Handling Equipment
High Pressure Grease Hose Market
Material Handling Equipment
Hi Lift Jack Market
Material Handling Equipment
Slag Handling Equipment Market
Material Handling Equipment
Reach Stacker Market
Material Handling Equipment
Electric Hoist Market
Material Handling Equipment
Global Tension Control Market
Material Handling Equipment
Scissor Lift Market
Material Handling Equipment
Conveying Equipment Market
Material Handling Equipment
Global Hydraulic Equipment Market
Material Handling Equipment
East Africa Elevator and Escalator Market
Material Handling Equipment
Copper and Aluminum Welding Bar Market
Material Handling Equipment
Circular Stacker and Reclaimer Market