

Copper and Aluminum Welding Bar Market Size, Share, and Industry Trends Forecast 2026-2036
Copper and Aluminum Welding Bar Market Insights
Renewable energy developers and electric vehicle battery manufacturers are rotating toward copper-aluminum composite bars as they seek weight reduction without conductivity loss. Lincoln Electric leverages its electrode alloy expertise to supply precision welding consumables for busbar fabrication. ESAB sustains competitive positioning through integrated R&D across resistance and laser welding process lines. Kobelco Welding anchors Asia-Pacific supply security with captive smelter relationships and JIS-certified product ranges.
Copper and aluminum welding bars are extruded or drawn metal sections, typically 8–50 mm in diameter, engineered with controlled oxide layers and trace element composition to ensure arc stability and fusion integrity during automated joining operations. Their primary purpose is to create permanent, low-resistance electrical connections in high-current infrastructure. Copper-aluminum alloy bars and composite bars command widening specification sheets as OEMs pursue galvanic corrosion resistance and thermal expansion matching in transformer and motor manufacturing applications. Laser welding technology is gaining fastest among fabrication methods, though resistance welding retains volume leadership due to legacy equipment installed across rail transport and power generation facilities.
ISO 18278 governs resistance welding quality parameters for electrical applications, while REACH and RoHS frameworks in Europe restrict cadmium and lead content in bar coatings and filler materials, directly shaping alloy formulation decisions by producers. China's GB standards and NMPA-aligned industrial quality certifications dictate market access for imported welding bar stock. Stakeholders must monitor how dual carbon goals in Beijing and the EU Green Deal's embodied carbon reporting rules redirect sourcing decisions toward low-carbon primary metal and recycled content verification systems.
Market Dynamics
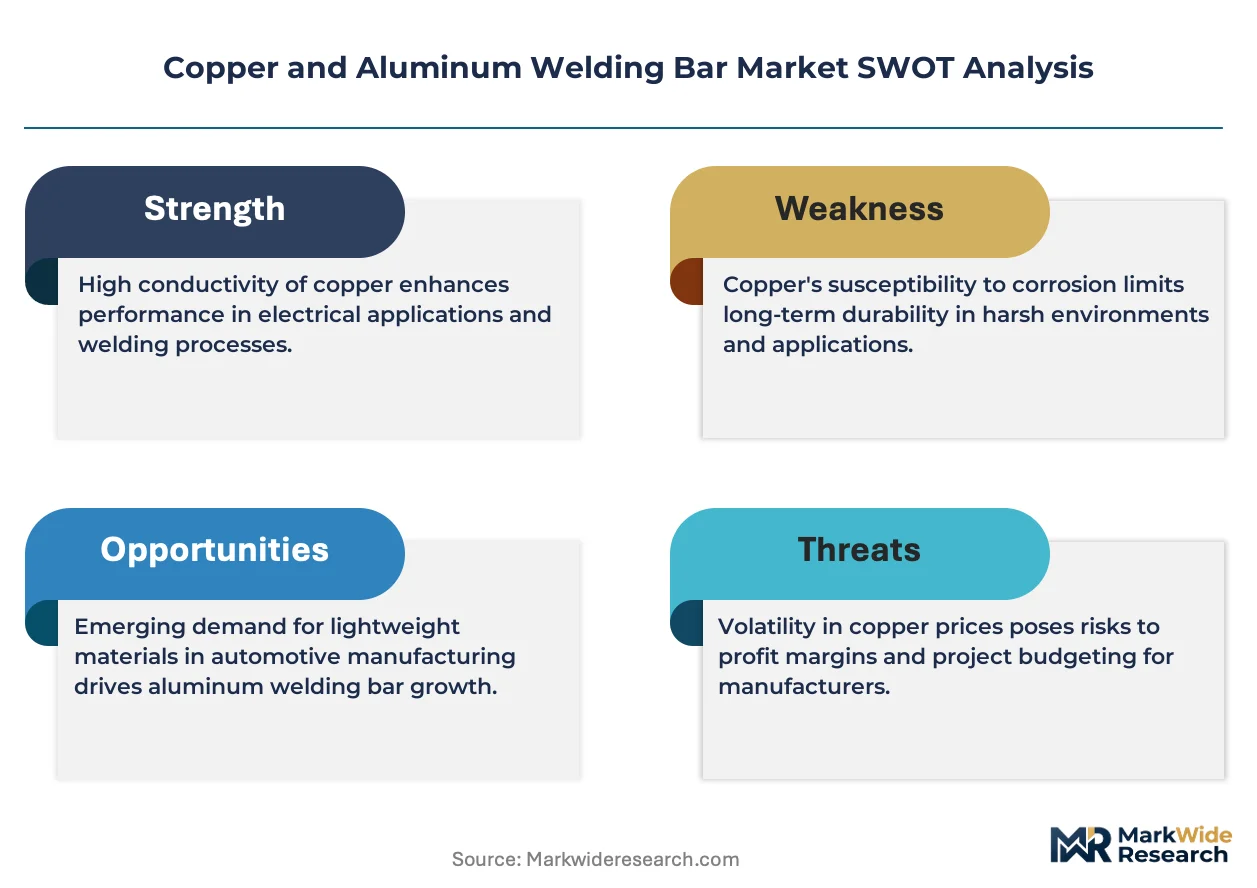
Laser welding systems are compressing specification cycles across OEM supply chains as energy-efficiency mandates force faster obsolescence of resistance welding infrastructure in heavy electrical manufacturing.
Growth Catalysts
- Power grid modernization in China:State Grid Corporation's ultra-high voltage transmission buildout consumes precision copper-aluminum composite bars for busbar assemblies in substation switchgear.
- EU Green Deal embodied carbon rules:The framework's Scope 3 reporting requirements redirect transformer manufacturers toward low-carbon primary metal and recycled content verification in welding bar procurement.
- Electric vehicle battery plant construction:Gigafactory ramp-ups in multiple geographies drive specification of laser-weldable copper-aluminum joints for thermal management systems and current collectors.
Market Restraints
- Primary aluminum price volatility:Smelter energy cost fluctuations in China and Europe transmit directly to welding bar input cost structures, compressing fabricator margins.
- Galvanic corrosion incompatibility:Direct copper-aluminum contact without engineered barrier layers creates electrochemical degradation risks that limit deployment in coastal or high-humidity infrastructure.
- REACH substance restrictions:ECHA's evolving candidate list for cadmium and lead compounds forces alloy reformulation timelines that lag equipment qualification cycles.
Strategic Opportunities
- India's PLI scheme for electrical equipment:Domestic manufacturing incentives for transformers and switchgear create localized demand for JIS-certified welding bar stock with captive smelter partnerships.
- Offshore wind nacelle manufacturing:Generator and transformer integration in turbine assemblies requires corrosion-resistant composite busbar connections with matched thermal expansion coefficients.
- Hybrid laser-arc welding convergence:Process combination enables single-pass joining of dissimilar thickness copper-aluminum sections, opening specification in motor manufacturing previously reserved for solid-state welding.
Industry Challenges
- Laser welding technician scarcity:The specialized optics and parameter tuning knowledge required for copper-aluminum dissimilar metal joining outpaces vocational training program output in industrial fabrication hubs.
- Multi-standard certification burden:Simultaneous compliance with ISO 18278 resistance welding parameters and emerging laser welding quality frameworks extends product qualification timelines for export markets.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Copper and Aluminum Welding Bar Market Trends and Innovations
Specification engineering for copper-aluminum welding bars is pivoting toward process-specific alloy design as fabrication technology diverges across end-use verticals with incompatible performance requirements.
Ultrafine grain copper-aluminum composite bars with engineered oxide interlayers are fragmenting the traditional homogeneous alloy segment. Automotive battery manufacturers specify these materials for laser welding compatibility in cell-to-pack architectures. The technology is fragmenting procurement categories that previously consolidated around resistance-weldable standard grades.
China's GB standards evolution under MIIT supervision now mandates trace element disclosure in welding consumables for electrical infrastructure. Manufacturers serving State Grid and Southern Grid tenders must demonstrate full material lineage. The regulatory shift most affects imported bar stock suppliers without captive smelter relationships or NMPA-aligned certification pathways.
Buyers are consolidating welding bar procurement under long-term alloy development agreements with single-source suppliers. Tier-one electrical equipment OEMs bypass distributors to secure dedicated extrusion capacity and collaborative R&D access. This pattern concentrates most visibly in Germany, where Siemens Energy and comparable manufacturers lock in multi-year copper-aluminum composite supply for transformer platform standardization.
Copper and Aluminum Welding Bar Market Segmentation
Segmentation in the copper and aluminum welding bar market reveals how regulatory frameworks and fabrication technologies split procurement decisions across incompatible specification requirements. Understanding these divisions exposes where alloy formulation, welding process compatibility, and end-use certification create distinct commercial battlegrounds.
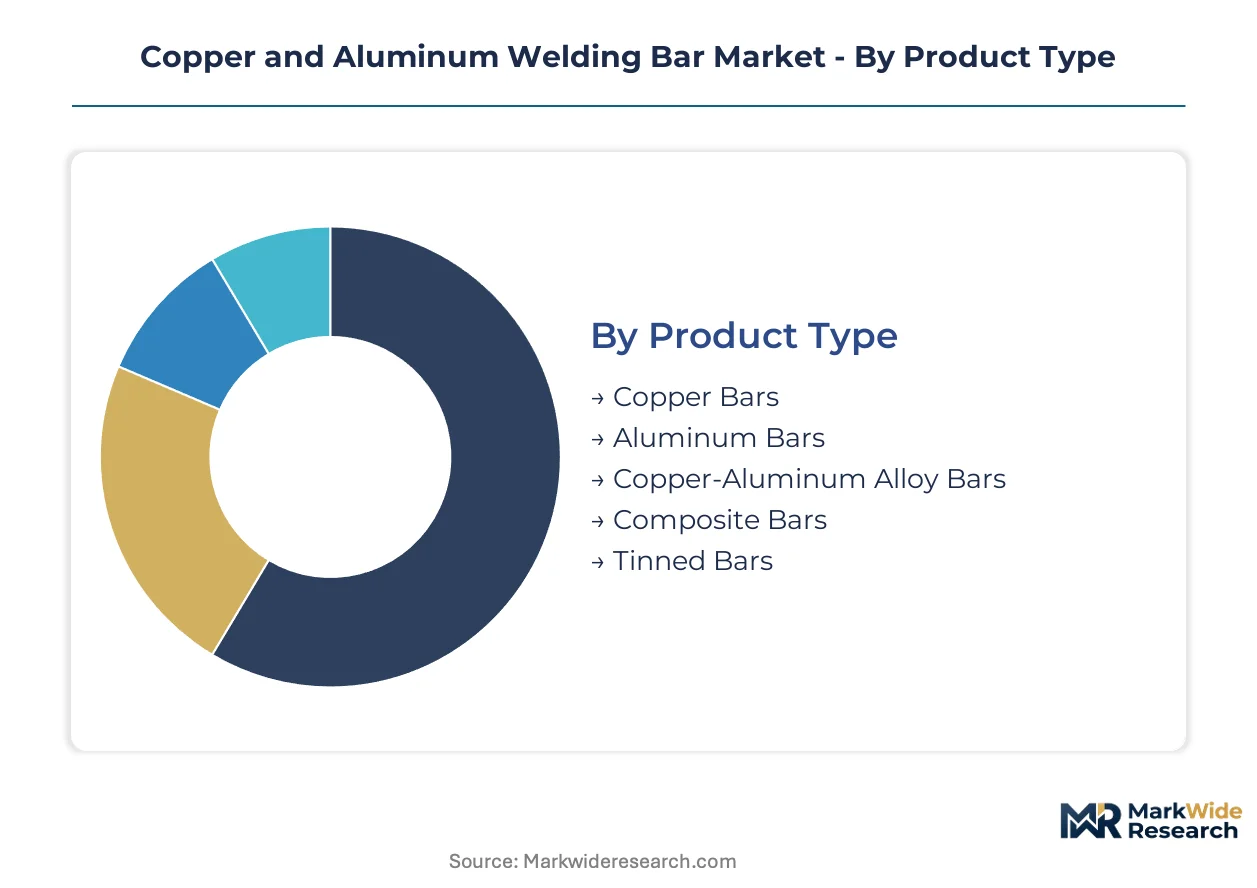
Product Type:
REACH and RoHS substance restrictions in Europe, alongside China's GB standards on trace element disclosure, fragment alloy formulation strategies across product categories.
- Copper Bars:High-purity electrolytic copper sections with controlled oxygen content below 10 ppm ensure arc stability in resistance welding of busbar assemblies. Power Generation equipment manufacturers in Germany specify these for transformer winding connections under ECHA-compliant cadmium-free coating mandates.
- Aluminum Bars:Extruded 6xxx and 1xxx series aluminum with magnesium-silicon balancing delivers lightweight conductivity for rail transport overhead line equipment. India's CEA grid code revisions for ultra-high voltage transmission are redirecting procurement toward aluminum-dominated composite designs in domestic switchgear.
- Copper-Aluminum Alloy Bars:Metallurgically homogeneous bars with 8-12% aluminum content provide intermediate thermal expansion coefficients for motor manufacturing stator windings.
- Composite Bars:Mechanically bonded copper-aluminum bimetallic sections with engineered oxide interlayers enable laser welding compatibility in electric vehicle battery thermal management systems.
- Tinned Bars:Hot-dipped or electroplated tin coatings suppress galvanic corrosion in coastal infrastructure applications subject to humid salt exposure.
Composite bars handle the majority of throughput in new energy vehicle procurement; copper-aluminum alloy bars are expanding most quickly on share as motor manufacturers pursue thermal expansion matching.
Technology:
Cost tier differentiation separates legacy resistance welding infrastructure from capital-intensive laser system adoption, with mid-range arc processes capturing retrofit demand.
- Resistance Welding:Pressure-assisted ohmic heating joins overlapping bar sections using copper-chrome or copper-zirconium electrodes. Rail transport maintenance facilities across France and Germany retain this technology for field repair of legacy rolling stock electrical systems.
- TIG Welding:Non-consumable tungsten electrode processes with argon shielding gas deliver precision control for aerospace manufacturing busbar assemblies requiring X-ray inspection qualification.
- MIG Welding:Continuous wire feed systems with pulsed arc control achieve deposition rates suited for construction sector electrical infrastructure field installation.
- Ultrasonic Welding:High-frequency mechanical vibration bonding creates solid-state joints without bulk heating for electronics manufacturing ribbon-to-terminal connections.
- Laser Welding:Fiber laser systems with beam wobble optics manage dissimilar metal heat input for copper-aluminum joints in battery plant automated production lines.
Resistance welding commands the installed base volume; laser welding is climbing the fastest as gigafactory construction mandates single-pass dissimilar metal capability.
Application:
Customer type concentration splits specification authority between OEM engineering departments and utility procurement committees with divergent qualification timelines.
- Electrical Equipment:Broad category encompassing switchgear, distribution panels, and control systems requiring weldable busbar stock with IEC 61439 short-circuit withstand certification.
- Busbars:Rigid conductive assemblies in substations and data centers specify copper-aluminum composite bars for weight reduction in elevated installation configurations.
- Switchgears:Circuit breaker and isolator integration demands welding bar stock with precise hardness control to maintain contact surface integrity under mechanical operation cycles.
- Transformers:Winding conductor connections and tap changer assemblies utilize tinned bars for oil compatibility and long-term corrosion resistance in sealed tank environments.
- Motor Manufacturing:Stator winding terminations and rotor bar assemblies require matched thermal expansion coefficients to prevent fatigue failure through operating temperature cycles.
Electrical equipment absorbs the dominant procurement volume; motor manufacturing is gaining share fastest as electrification multiplies industrial drive system demand.
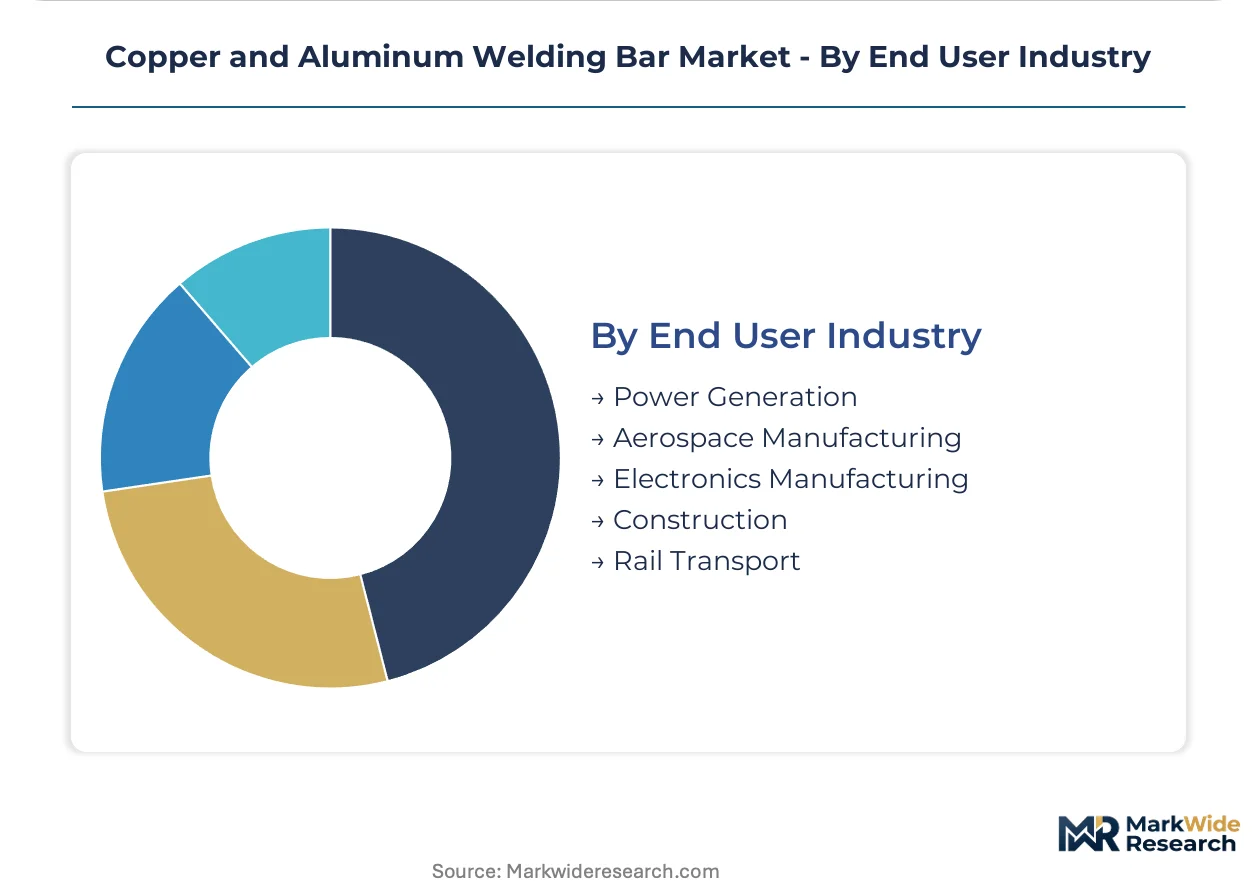
End User Industry:
Supply concentration in primary metal smelting creates geographic lock-in effects that shape end user procurement patterns by region.
- Power Generation:Utility-scale generation and grid infrastructure projects specify JIS-certified or GB-compliant welding bar stock with full material lineage documentation.
- Aerospace Manufacturing:Aircraft electrical distribution systems demand aerospace-grade alloy bars with AMS or MIL-spec certification and lot-level chemical assay records.
- Electronics Manufacturing:Consumer and industrial electronics assembly lines utilize ultrasonic-weldable fine-diameter bars for miniature connector and terminal applications.
- Construction:Commercial and residential building electrical infrastructure procurement prioritizes cost-optimized standard grades through distributor channels.
- Rail Transport:Rolling stock OEMs and maintenance depots specify legacy-compatible resistance-weldable bars for interoperability with existing repair equipment.
Power Generation represents the largest demand sink; electronics manufacturing is expanding most quickly as battery and power semiconductor packaging multiplies precision welding applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China exports copper-aluminum composite bar stock to transformer manufacturers across Germany and India, while Japanese fabricators supply precision welding consumables to Southeast Asian battery plants.
China
State Grid Corporation's ultra-high voltage transmission buildout and electric vehicle battery plant construction consume elevated volumes of precision welding bar stock. MIIT-supervised GB standards evolution mandates trace element disclosure in welding consumables for electrical infrastructure. Yangtze River Delta industrial clusters around Shanghai host extrusion facilities supplying State Grid and Southern Grid tenders with full material lineage documentation.
Germany
Siemens Energy and comparable manufacturers lock in multi-year copper-aluminum composite supply for transformer platform standardization. ECHA's REACH framework restricts cadmium and lead content in bar coatings, forcing alloy reformulation timelines. Bavaria and North Rhine-Westphalia industrial corridors concentrate busbar fabrication facilities serving European grid modernization projects.
India
The PLI scheme for electrical equipment creates localized demand for JIS-certified welding bar stock in domestic transformer and switchgear manufacturing. CEA grid code revisions for ultra-high voltage transmission redirect procurement toward aluminum-dominated composite designs. Maharashtra and Gujarat industrial zones host emerging fabrication capacity targeting captive smelter partnerships.
United States
Rail transport maintenance facilities retain resistance welding infrastructure for legacy rolling stock electrical system repairs. FERC grid interconnection standards and state-level clean energy procurement rules shape utility-scale transformer specifications. Texas and California industrial corridors concentrate electrical equipment OEM engineering departments with divergent qualification timelines.
Japan
METI industrial policy and JIS certification requirements anchor Asia-Pacific supply security for precision welding consumables. Kobelco Welding maintains captive smelter relationships serving domestic and export markets. Kansai and Chubu industrial regions host integrated R&D facilities across resistance and laser welding process lines.
Copper and Aluminum Welding Bar Market Competitive Landscape
Player mix skews toward integrated welding consumable specialists with captive metallurgical capabilities and regional alloy certification depth. Market structure concentrates around three to five dominant suppliers with multi-decade electrode expertise and established OEM qualification pathways. Strategic archetypes include integrated metallurgical conglomerates with smelter-to-fabrication control, specialized welding consumable houses with process-specific R&D depth, and regional champions leveraging domestic standard compliance. Capacity expansion and strategic partnerships dominate competitive moves as fabricators secure dedicated extrusion lines and collaborative alloy development access.
Among integrated welding specialists, Lincoln Electric, ESAB, and Kobelco Welding occupy positions that exemplify divergent geographic and technological positioning. Lincoln Electric represents North American electrode alloy expertise applied to precision consumables for electrical fabrication. ESAB sits within the European integrated fabrication equipment and consumable supply tier with process line breadth. Kobelco Welding anchors Asia-Pacific supply security through JIS-certified product ranges and metallurgical integration.
| Leading Market Players |
|---|
| Lincoln Electric |
| ESAB |
| Voestalpine Böhler Welding |
| Kobelco Welding |
| Kiswel |
| Sumitomo Electric Industries |
| Hobart Brothers |
| Weldcoa |
| Jinglei Welding |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization rates at Yangtze River Delta extrusion facilities determine price floors across copper-aluminum composite bar categories, concentrating margin power with integrated producers possessing captive smelter relationships and NMPA-aligned certification pathways.
Pricing Analysis
Laser-weldable composite bars command substantial premiums over resistance-weldable standard grades, while next-generation ultrafine grain formulations with engineered oxide interlayers price at the apex tier. Three-tier pricing structure across premium laser-grade, standard resistance-grade, and economy construction-tier segments reflects certification complexity and volume scale. Cost compression in standard resistance-grade bars is intensifying because primary aluminum price volatility transmits directly through smelter energy cost fluctuations. Construction sector procurement through distributor channels exhibits highest price sensitivity; automotive battery manufacturers demonstrate lowest sensitivity given qualification timeline investments.
Supply Chain Analysis
China and Japan anchor primary metal supply and precision fabrication capacity for copper-aluminum welding bar production. The supply chain draws from electrolytic copper cathodes, primary aluminum ingots, and trace element additives for oxide layer engineering. Single-source vulnerability concentrates in Yangtze River Delta extrusion clusters serving State Grid tenders. Distribution runs through direct long-term alloy development agreements between tier-one electrical equipment OEMs and integrated welding consumable specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
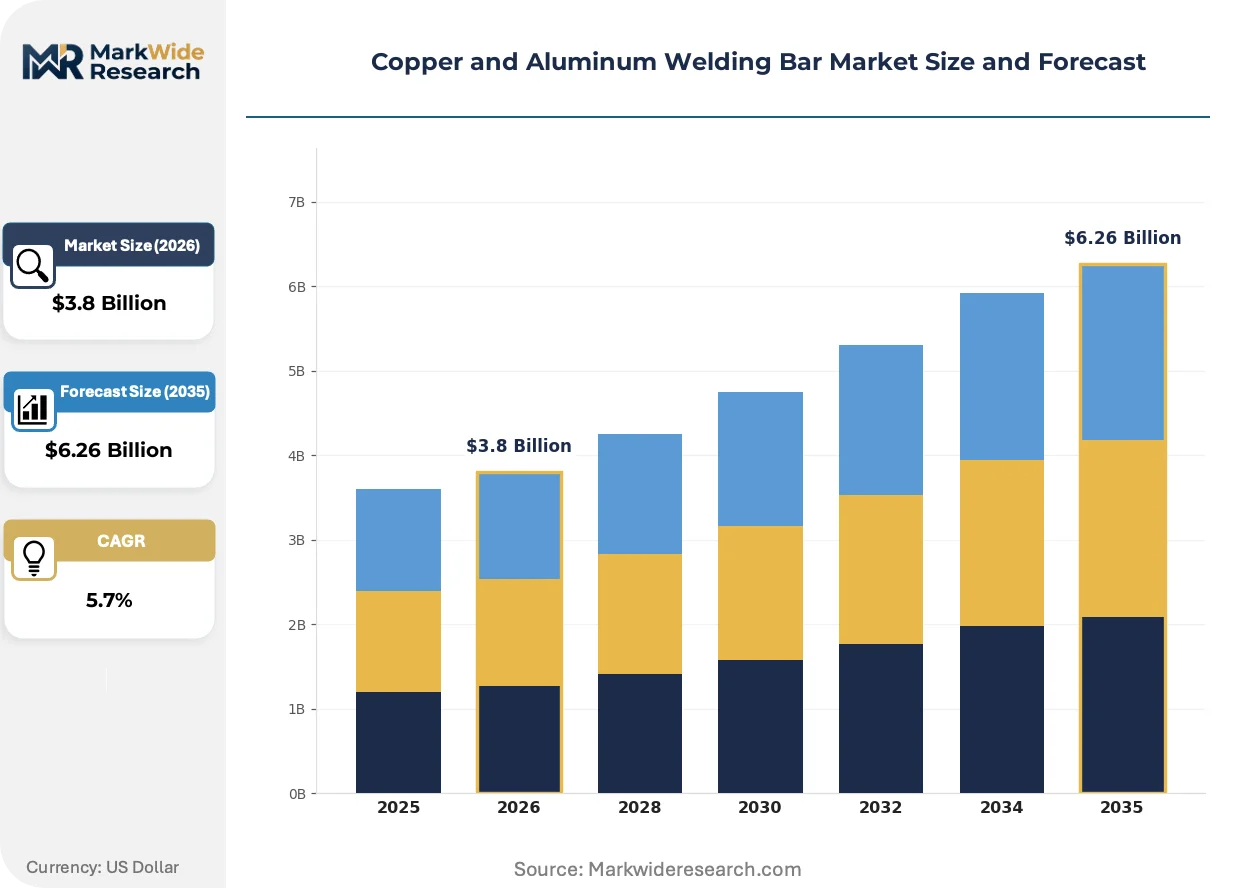
The copper and aluminum welding bar market sits in early-cycle recovery as power grid modernization and electric vehicle battery plant construction reactivate capacity expansion plans deferred during prior investment pauses.
For Market Incumbents: Compound metallurgical integration advantages by locking dedicated extrusion capacity with State Grid and Southern Grid through multi-year material lineage documentation commitments. Deepen captive smelter relationships to buffer primary aluminum price volatility exposure. Prioritize collaborative R&D access with Siemens Energy-class OEMs for transformer platform standardization. For New Entrants and Emerging Players: Lead with JIS-certified product ranges targeting India's PLI scheme for electrical equipment, where domestic manufacturing incentives create localized demand without established supplier entrenchment. Penetrate offshore wind nacelle manufacturing specifications for corrosion-resistant composite busbar connections. Pursue qualification partnerships with emerging battery plant developers in Southeast Asia seeking second-source security. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated welding consumable specialists with resistance-to-laser process line breadth and established OEM qualification pathways. Five-to-ten year viability hinges on laser welding technician training infrastructure development outpacing vocational program output gaps. Monitor hybrid laser-arc welding convergence adoption rates in motor manufacturing as inflection indicator for composite bar specification shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Primary Metal Supply | Captive smelter relationships buffer ECHA REACH reformulation timelines and input cost volatility. |
| Laser Welding Process Qualification Investment | Single-pass dissimilar metal capability unlocks gigafactory procurement specifications previously reserved for solid-state welding. |
| Long-Term Alloy Development Agreement | Direct OEM engineering department access bypasses distributor margin compression in electrical equipment procurement. |
| NMPA-Aligned Certification Pathway Establishment | GB standards compliance enables State Grid and Southern Grid tender participation for imported bar stock suppliers. |
| Hybrid Laser-Arc Welding R&D Partnership | Process convergence opens motor manufacturing applications with unmatched thermal expansion coefficient matching. |
Research Methodology
The analysis maps resistance welding infrastructure, laser welding adoption, and hybrid process convergence segments, each validated through procurement directors at electrical equipment OEMs, technical R&D leads at welding consumable specialists, plant managers at extrusion facilities, and quality assurance officers at battery plant developers. Primary interview findings triangulate against secondary sources including MIIT GB standards documentation, ECHA REACH candidate list updates, State Grid tender specifications, and customs trade data for copper-aluminum composite bar flows. Bottom-up segment sizing reconciles with top-down market boundary analysis.
Consistency checks validate volume and value outputs against external benchmarks across the projection horizon. The analytical framework models product type, technology compatibility, application vertical, and end-user industry dimensions. CAGRs derive from segment-level growth trajectory analysis incorporating power grid capital expenditure cycles, battery plant construction pipelines, and regulatory compliance timeline impacts.
Forecasts assume regulatory continuity in ECHA REACH frameworks and MIIT-supervised GB standards evolution; material policy shifts affecting cadmium compound restrictions or trace element disclosure mandates would require re-modeling. Specific risks include primary aluminum smelter energy cost volatility, laser welding technician scarcity, and multi-standard certification burden extensions. Recalibration cycles align with material shifts in power grid procurement volumes and battery plant qualification timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.