
 Global Tension Control Market | 2026-2036
Global Tension Control Market Size, Share, and Industry Trends Forecast 2026-2036
Global Tension Control Market Outlook
Multi-source procurement for load cells and servo actuators is hardening across OEM supply chains. Nireco leverages its Japanese manufacturing base to sustain precision sensor output for Asian converter equipment makers. Dover Flexo Electronics anchors North American demand through specialized web-handling integration. Maxcess International differentiates via global service density across slitting and lamination lines.
Tension control encompasses closed-loop systems that regulate mechanical stress on continuous materials—typically maintaining web tension between 50 N and 5,000 N through feedback from piezoelectric or strain-gauge sensors driving pneumatic or electromechanical actuators. These systems prevent wrinkles, breaks, and gauge variation in roll-to-roll processes across printing, packaging, and metal forming. Controllers capture the largest margin pool due to embedded software complexity and calibration dependency, while sensors represent the fastest-expanding hardware category as Industry 4.0 architectures demand real-time data streams. Electrical technology leads installed base share, though pneumatic systems retain cost advantages in explosive environments and heavy-gauge metal processing.
FDA machinery safety guidelines, EU Machinery Directive 2006/42/EC, and Japan's JIS B 9700 standards collectively shape product certification requirements and cross-border equipment acceptance. OEMs must align sensor accuracy classes and emergency-stop response thresholds with these frameworks to avoid market exclusion. Stakeholders should monitor how IEC 62061 functional-safety updates and emerging carbon-footprint disclosure rules in Europe alter component sourcing and system redesign priorities.
Market Dynamics
Closed-loop digital architectures are displacing pneumatic and manual tension systems across automotive battery electrode coating and flexible packaging lines, driven by EU Machinery Directive 2006/42/EC compliance deadlines and zero-defect manufacturing mandates from German and Japanese OEMs.
Growth Catalysts
- EU Machinery Directive 2006/42/EC:Emergency-stop response thresholds and functional-safety requirements are compelling European converters to upgrade from open-loop to closed-loop digital control systems ahead of certification deadlines.
- Lithium-ion battery electrode coating:Gigafactory expansions in Germany, Japan, and the United States are installing precision tension systems to maintain coating uniformity across copper and aluminum foils at micron-level tolerances.
- Strain-gauge sensor miniaturization:Piezoelectric load cells with embedded edge-computing capability are enabling real-time web tension adjustments without controller latency, accelerating adoption in high-speed slitting operations.
Market Restraints
- Semiconductor component concentration:Servo drive ICs and high-resolution ADC chips for sensor signal conditioning concentrate in Taiwanese and South Korean foundries, exposing OEMs to allocation volatility.
- Pneumatic system cost advantage:Compressed-air tension brakes retain 30-40% lower installed cost than electromechanical alternatives in heavy-gauge metal stamping, slowing electrification in explosive-environment applications.
- Calibration labor intensity:Controller-encoder alignment requires certified technicians averaging 8-12 hours per installation, constraining deployment velocity in regions with scarce automation service networks.
Strategic Opportunities
- India packaging machinery:Domestic flexible packaging converters in Gujarat and Maharashtra are retrofitting gravure presses with entry-level closed-loop systems as BIS certification requirements tighten.
- Carbon-footprint disclosure alignment:EU CSRD reporting obligations are creating specification preference for tension systems with embedded energy-monitoring and predictive maintenance modules.
- AI-driven tension prediction:Machine learning models trained on historical web-break patterns are converging with edge-deployed controllers to enable anticipatory rather than reactive tension adjustments.
Industry Challenges
- Functional-safety certification timelines:IEC 62061 SIL 2/3 validation for safety-integrated tension systems extends product development cycles by 14-18 months, compressing margin recovery windows.
- Legacy pneumatic infrastructure integration:Retrofitting closed-loop electromechanical actuators onto existing press frames requires mechanical redesign of dancer arm geometries, complicating upgrade economics for mid-life equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Tension Control Market |
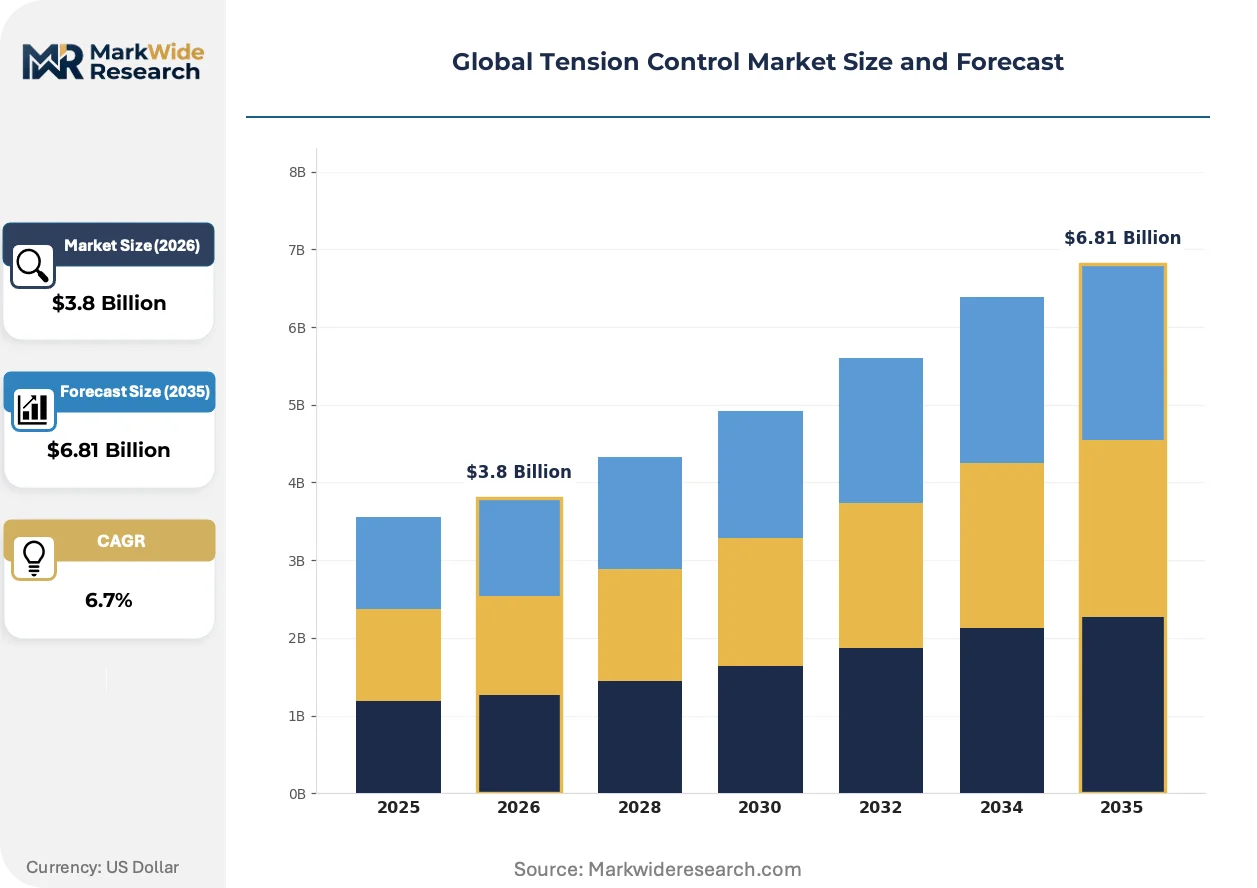
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Controllers, Sensors, Transducers, Actuators End User: Aerospace, Automotive, Manufacturing, Robotics Technology: Hydraulic, Electrical, Mechanical, Pneumatic Application: Web Tensioning, Wire Production, Textile Processing, Printing |
| Companies Covered | Nireco, Dover Flexo Electronics, Maxcess International, Comptrol, FMS Force Measuring Systems, Montalvo Corporation, Double E Company, Nexen Group, Erhardt + Leimer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Tension Control Market Strategic Shifts
Digital twin deployment and edge-native controller architectures are compressing commissioning timelines and enabling predictive maintenance models that unbundle traditional service contracts.
Brushless DC servo actuators with integrated torque ripple compensation are overtaking traditional AC induction motor drives in high-precision battery electrode coating lines. Korean and German battery equipment makers specify these systems for tension windows below 200 N. The technology is overtaking pneumatic alternatives in cleanroom environments where compressed air contamination risks disqualify legacy systems.
Japan's METI has issued updated JIS B 9700 interpretations that mandate documented risk assessment for web-handling machinery with automatic tension adjustment. Japanese OEMs must now submit third-party validation of emergency-stop response times below 500 milliseconds. Converter equipment exports to ASEAN markets face parallel certification requirements, forcing design standardization across product families.
Buyers in North American flexible packaging are unbundling after-sales service from initial equipment procurement, favoring third-party calibration providers over captive OEM service networks. Distributor-led technical training programs in Wisconsin and Ohio are capturing maintenance contract volumes previously held by manufacturers. This disintermediation is most visible in narrow-web label printing, where regional integrators now specify multi-brand sensor and actuator combinations.
Global Tension Control Market Segmentation
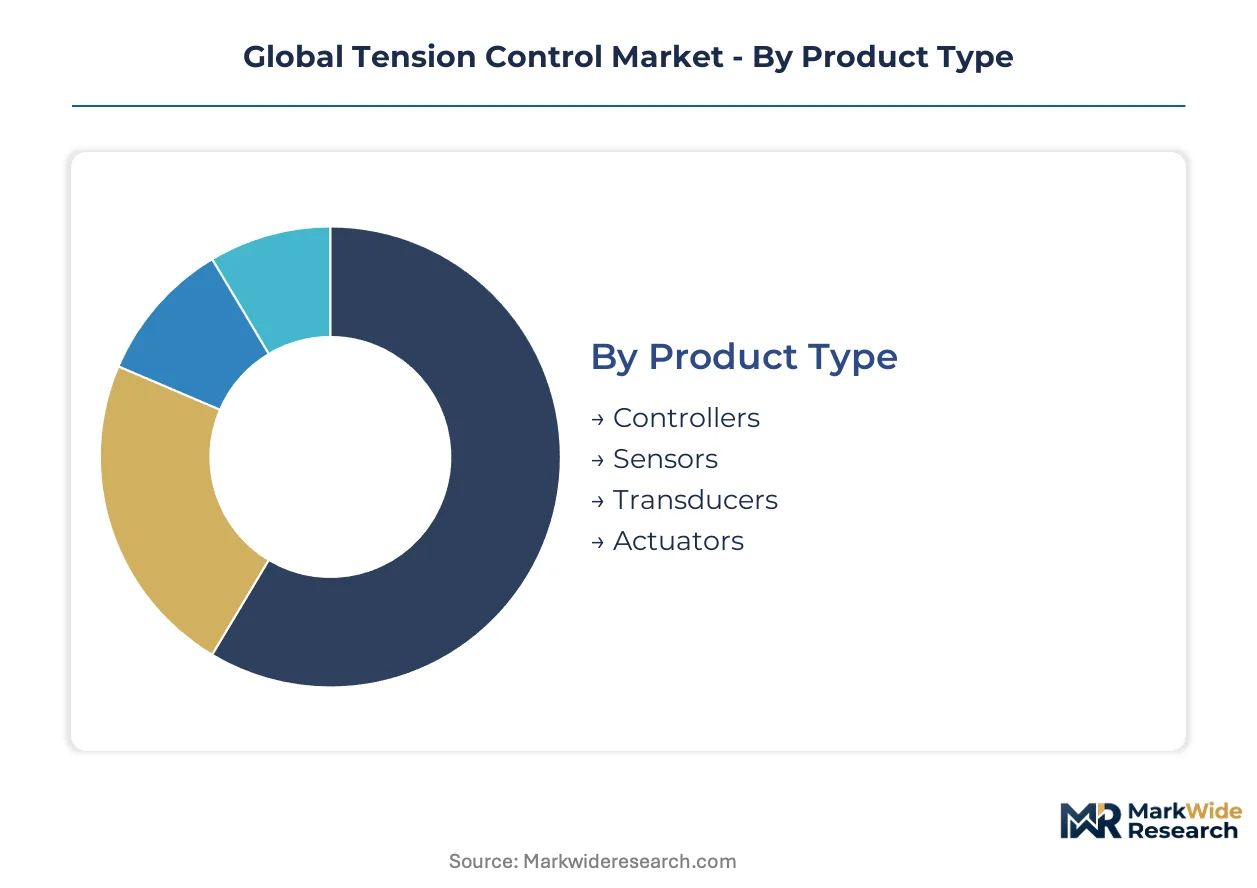
Tension control markets fragment across four critical dimensions: hardware composition, customer operational requirements, power transmission methodology, and material processing workflow. Each segmentation axis reveals distinct procurement patterns, margin structures, and technology substitution dynamics that shape supplier strategy.
Product Type:
Capital intensity varies sharply across hardware categories, with embedded software and calibration dependency concentrating investment in controller architectures while sensor manufacturing benefits from modular, scalable production lines.
- Controllers:Embedded software platforms with multi-axis synchronization capability and real-time PID algorithms command premium positioning due to calibration dependency and functional-safety certification requirements. German automotive OEMs and Japanese battery equipment makers specify these systems for electrode coating lines where tension windows fall below 200 N.
- Sensors:Piezoelectric and strain-gauge load cells with edge-computing capability are displacing legacy analog designs across high-speed slitting operations in Wisconsin and Ohio. Demand concentrates where Industry 4.0 architectures mandate real-time data streams without controller latency.
- Transducers:Signal conditioning modules bridge analog sensor outputs to digital control networks, serving retrofit markets where legacy pneumatic systems require closed-loop upgrades without full controller replacement.
- Actuators:Pneumatic brakes and electromechanical servo drives deliver mechanical force to web-handling systems, with brushless DC variants overtaking AC induction designs in cleanroom battery manufacturing environments.
Controllers absorb the bulk of installed capacity; sensors are expanding most quickly.
End User:
Customer sophistication and specification authority determine technology adoption velocity, with automotive and aerospace buyers driving closed-loop digital migration while manufacturing segments balance upgrade economics against legacy infrastructure.
- Automotive:Stamping press OEMs and battery gigafactory operators in Germany, Japan, and the United States mandate precision tension systems for copper and aluminum foil coating at micron-level tolerances. EU Machinery Directive compliance deadlines accelerate procurement cycles.
- Manufacturing:Flexible packaging converters across Gujarat and Maharashtra retrofit gravure presses with entry-level closed-loop systems as BIS certification requirements tighten, representing volume-driven demand with price-sensitive procurement.
- Aerospace:Composite material processing and wire harness production require certified tension control for carbon fiber placement and specialty cable manufacturing, with FAA and EASA traceability requirements shaping supplier qualification.
- Robotics:Automated material handling systems integrate tension modules for cable and filament management, serving industrial robot OEMs in South Korea and Germany where precision motion control convergence drives specification.
Automotive absorbs the bulk of installed capacity; manufacturing is climbing the fastest.
Technology:
Power transmission methodology segments by environmental compatibility and precision requirements, with electrical systems gaining share in cleanroom applications while pneumatic retention persists in explosive atmospheres.
- Electrical:Brushless DC servo actuators with integrated torque ripple compensation deliver precision below 200 N tension windows for battery electrode coating. Korean and German equipment makers specify these for cleanroom environments where compressed air contamination risks disqualify alternatives.
- Pneumatic:Compressed-air tension brakes retain 30-40% lower installed cost than electromechanical alternatives in heavy-gauge metal stamping and explosive-environment applications, slowing electrification in chemical processing and mining equipment.
- Hydraulic:High-force tension systems for steel rolling and heavy-gauge metal forming leverage fluid power density where electromechanical torque density proves insufficient.
- Mechanical:Dancer arm and manual adjustment systems persist in legacy equipment and emerging market installations where capital constraints limit digital upgrade feasibility.
Electrical technology absorbs the bulk of installed capacity; hydraulic systems are gaining share fastest in heavy-gauge applications.
Application:
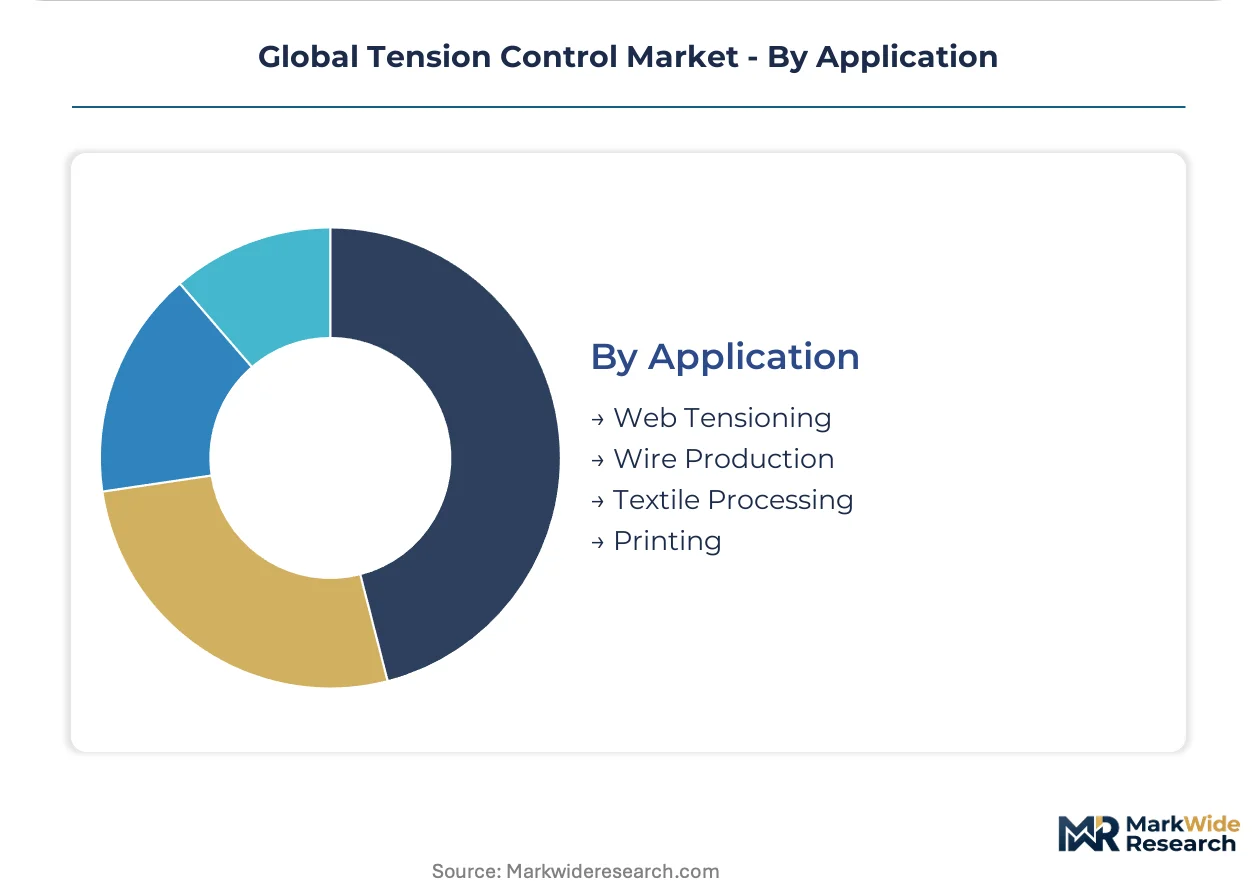
Material processing workflow determines sensor specification, control loop architecture, and integration complexity, with continuous web processes demanding the most sophisticated closed-loop implementations.
- Web Tensioning:Roll-to-roll processing for flexible packaging, battery electrodes, and printed electronics requires multi-zone tension control with dancer roll or load cell feedback. Japanese OEMs face METI-mandated risk assessments for automatic adjustment systems with emergency-stop response below 500 milliseconds.
- Printing:Narrow-web label presses and wide-format gravure systems in North American flexible packaging are unbundling after-sales service from initial procurement, favoring third-party calibration providers over captive OEM networks.
- Wire Production:Cable stranding and drawing operations tension metallic and optical fibers through capstan and dancer configurations, with telecommunications infrastructure investment driving specification in South Korea and Germany.
- Textile Processing:Weaving and knitting machinery tension yarns and technical textiles, serving fashion and industrial fabric producers in India and Italy where speed-precision tradeoffs shape technology selection.
Web tensioning absorbs the bulk of installed capacity; printing applications are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive stamping clusters and Japanese battery electrode coating facilities anchor precision tension system demand. Raw material processing corridors in Gujarat and Maharashtra drive retrofit installations across flexible packaging lines.
United States
Automotive stamping press OEMs in Michigan and Ohio mandate closed-loop digital upgrades for copper and aluminum foil handling. OSHA machinery safety enforcement tightens emergency-stop response requirements across Detroit-area production lines. Wisconsin and Ohio distributors now capture maintenance contracts previously held by manufacturers.
Germany
Battery gigafactory operators specify tension windows below 200 N for electrode coating uniformity. EU Machinery Directive 2006/42/EC compliance deadlines accelerate procurement ahead of certification cutoff dates. Stuttgart and Munich precision manufacturing clusters align capital equipment replacement cycles with zero-defect mandates.
Japan
METI updated JIS B 9700 interpretations mandate documented risk assessment for web-handling machinery with automatic tension adjustment. Converter equipment exports to ASEAN markets face parallel certification requirements. Nagoya and Osaka industrial zones standardize design families across product lines to satisfy third-party validation below 500-millisecond emergency-stop thresholds.
India
Domestic flexible packaging converters in Gujarat and Maharashtra retrofit gravure presses with entry-level closed-loop systems. BIS certification requirements tighten procurement specifications for regional equipment makers. Mumbai and Ahmedabad processing corridors concentrate demand as brand owners enforce traceability standards.
South Korea
Korean battery equipment makers specify brushless DC servo actuators for cleanroom environments where compressed air contamination risks disqualify legacy systems. MFDS-aligned machinery safety protocols shape supplier qualification for pharmaceutical packaging lines. Busan-Ulsan manufacturing zones integrate tension modules for cable and filament management in automated material handling systems.
Global Tension Control Market Competitive Environment
Global majors compete with regional champions across sensor fabrication and controller software integration. The vendor base stratifies into three tiers: precision sensor specialists, integrated web-handling system providers, and pneumatic component fabricators serving explosive-environment applications. Dominant competitive moves include strategic partnerships for semiconductor supply security and geographic expansion through distributor-led technical training programs.
Within the precision sensor tier, Nireco leverages its Japanese manufacturing base to sustain output for Asian converter equipment makers. Dover Flexo Electronics anchors North American demand through specialized web-handling integration. Maxcess International occupies a position defined by global service density across slitting and lamination lines. These three exemplify how regional manufacturing footprints and application-specific expertise shape competitive positioning without requiring scale-driven consolidation.
| Leading Market Players |
|---|
| Nireco |
| Dover Flexo Electronics |
| Maxcess International |
| Comptrol |
| FMS Force Measuring Systems |
| Montalvo Corporation |
| Double E Company |
| Nexen Group |
| Erhardt + Leimer |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up specialists with consolidated controller portfolios are exercising pricing discipline through bundled calibration contracts and multi-year service lock-ins, while family-owned pneumatic component fabricators in Germany and Japan defend margin pools via captive aftermarket networks. This ownership fragmentation creates divergent supply behaviors: financial sponsors prioritize recurring revenue streams from software-enabled controllers, whereas generational manufacturers extract value from legacy spare part dependency.
Pricing Analysis
Warranty and service bundling separates premium controller OEMs from unbundled sensor suppliers, with German automotive stampers and Japanese battery equipment makers paying 15-25% premiums for SIL-certified systems with embedded predictive maintenance. Three-tier pricing structure across premium, standard, and economy levels stratifies by functional-safety certification grade and calibration labor inclusion. Cost compression in entry-level pneumatic retrofits is intensifying because Indian flexible packaging converters demand stripped-down closed-loop systems without OEM service attachments. Manufacturing segments in Gujarat and Maharashtra exhibit highest price sensitivity; aerospace composite processors show lowest due to FAA traceability mandates.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from German battery gigafactories and Japanese converter equipment makers, while distributor-led technical training programs in Wisconsin and Ohio capture maintenance contract volumes for mid-tier flexible packaging lines. Taiwanese and South Korean foundries supply servo drive ICs and high-resolution ADC chips for sensor signal conditioning, with Japanese load cell specialists and German precision actuator fabricators anchoring upstream component flows. Single-source vulnerability concentrates in semiconductor signal conditioning chips. Distribution runs through authorized system integrators for complex multi-axis installations and direct procurement for standardized retrofits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around functional-safety certification capabilities, with IEC 62061 SIL 2/3 validation timelines compressing margin recovery windows and forcing mid-tier pneumatic specialists toward strategic exits or acquisition.
For Market Incumbents: Lock in semiconductor supply security through strategic partnerships with Taiwanese foundries and South Korean ADC chip fabricators to mitigate allocation volatility exposure. Deepen backward integration into strain-gauge sensor manufacturing to capture Industry 4.0 data stream demand from Wisconsin and Ohio slitting operations. Certify emergency-stop response thresholds below 500 milliseconds across entire product families to satisfy METI-mandated JIS B 9700 interpretations for ASEAN export eligibility. For New Entrants and Emerging Players: Launch via third-party calibration provider partnerships to exploit disintermediation trends in North American narrow-web label printing, where regional integrators now specify multi-brand sensor combinations. Target India's Gujarat and Maharashtra flexible packaging corridors with entry-level closed-loop systems priced for BIS certification compliance without OEM service bundling. White-space exists in AI-driven tension prediction modules that converge machine learning models with edge-deployed controllers for anticipatory adjustment capabilities. For Investors and Strategic Acquirers: Distressed-cycle entries favor family-owned pneumatic component specialists in Germany with established explosive-environment customer relationships and captive spare part revenue streams. Long-term viability hinges on electrification transition speed in heavy-gauge metal stamping applications. Watch brushless DC servo actuator adoption rates in Korean and German battery cleanroom specifications as inflection indicator for pneumatic displacement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Functional-Safety Certification Investment | IEC 62061 SIL 2/3 validation opens German automotive and Japanese battery equipment procurement channels. |
| Edge-Computing Sensor Integration | Piezoelectric load cells with embedded processing eliminate controller latency for Wisconsin high-speed slitting lines. |
| Semiconductor Supply Partnership | Strategic alliances with Taiwanese foundries secure servo drive IC allocation for OEM production continuity. |
| Aftermarket Service Unbundling | Third-party calibration capture in Ohio and Wisconsin disrupts traditional OEM maintenance contract structures. |
| AI-Driven Tension Prediction Development | Machine learning convergence with edge controllers enables anticipatory adjustment for zero-defect battery electrode coating. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, with primary interviews conducted among tension control system OEM procurement directors, plant engineers at German automotive stamping facilities, aftermarket service heads at Wisconsin distributor networks, and calibration technicians at Ohio narrow-web label operations. FDA machinery safety guidelines, EU Machinery Directive 2006/42/EC implementation documents, METI JIS B 9700 interpretation notices, and BIS certification requirement circulars provided regulatory validation. Bottom-up unit economics from sensor, controller, and actuator bill-of-materials were triangulated against top-down OEM revenue disclosures.
Granularity-level modeling disaggregated hardware composition by embedded software complexity and calibration dependency, technology by power transmission methodology and environmental compatibility, and application by material processing workflow and control loop architecture. End-user segmentation captured procurement authority variation across German battery gigafactories, Indian flexible packaging converters, and North American aerospace composite processors. CAGRs were derived from replacement cycle timing, regulatory compliance deadline clustering, and capital equipment investment patterns across the analysis window. Forecast inputs incorporated Industry 4.0 architecture penetration rates and functional-safety certification adoption curves.
Semiconductor allocation volatility, EU carbon-footprint disclosure rule evolution, and AI-driven tension prediction technology maturation are the dominant revision risks to installed base and technology substitution assumptions. Forecasts reflect documented base-case assumptions regarding regulatory compliance timeline adherence and capital equipment replacement cycle synchronization. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Clinching Machines Market
Material Handling Equipment
Reach Trucks Market
Material Handling Equipment
Asia Pacific Mobile Crane Market
Material Handling Equipment
North America Forklift Market
Material Handling Equipment
Silo Bin Activators Market
Material Handling Equipment
Global Mechanical Seals Market
Material Handling Equipment
Industrial Static Equipment Market
Material Handling Equipment
Tube Rotator Market
Material Handling Equipment
East Africa Elevator and Escalator Market
Material Handling Equipment
Pneumatic Conveying Diverters Market
Material Handling Equipment
Stacker Crane Market
Material Handling Equipment
Port Material Handling Equipment Vehicle Market
Material Handling Equipment
Robotic Palletizers Market
Material Handling Equipment
Eye and Eye Turnbuckle Market
Material Handling Equipment
Slow Speed Shredding Machines Market
Material Handling Equipment
Linear Slides Market