
 East Africa Elevator and Escalator Market | 2026-2036
East Africa Elevator and Escalator Market Size, Share, and Industry Trends Forecast 2026-2036
East Africa Elevator and Escalator Market Analysis
Market Context with Strategic Players
Steel-reinforced composite cab panels are replacing traditional aluminum enclosures, expanding cost efficiency for mid-rise installations across East Africa. Otis Elevator Company leverages its regional service footprint to anchor maintenance contracts in Nairobi's commercial district. KONE Corporation competes through gearless traction specialization for high-rise residential towers in Addis Ababa. Schindler Group sustains brand positioning via localized assembly partnerships that reduce import duty exposure.
Technical Definition and Structural Segments
An elevator is a vertical transportation apparatus comprising a car, counterweight, hoisting mechanism, and safety systems designed to move passengers or freight between building levels at controlled speeds typically ranging from 1.0 to 10.0 meters per second. Escalators employ a continuous loop of articulated steps driven by an electric motor and chain system to transport pedestrians between floors at a constant incline of 30 or 35 degrees, primarily serving retail complexes, transit terminals, and dense commercial environments where pedestrian volume exceeds stair capacity. Passenger elevators dominate current revenue pools across East African capitals, while machine room-less traction technology captures the fastest growth trajectory due to space-constrained urban construction. Maintenance and modernization services now constitute the most resilient margin segment, as installed bases age and building owners prioritize uptime over capital replacement.
Regulatory Frame and Forward-Looking Close
Kenya's National Construction Authority enforces elevator safety inspections and load-testing protocols that directly shape vendor qualification requirements and aftermarket service demand. Ethiopia's Ministry of Urban Development and Construction mandates accessibility standards for public buildings, while Tanzania's Energy and Water Utilities Regulatory Authority governs electrical safety certification for vertical transport equipment. Uganda's national standards body applies East African Community harmonized technical regulations for mechanical lifting appliances, creating cross-border compliance obligations for suppliers. Stakeholders must monitor how divergent national enforcement capacities affect warranty terms and service network deployment priorities across the region.
Market Dynamics
Machine room-less traction systems are compressing mechanical footprints in Nairobi and Dar es Salaam high-rises, forcing incumbent vendors to retool service capabilities around compact drive architectures.
Growth Catalysts
- Kenya's National Construction Authority accessibility mandates:New building codes require elevator retrofits in commercial structures above four stories, expanding aftermarket service pipelines.
- Addis Ababa state-led infrastructure corridor:Ethiopia's centralized procurement for government towers and transit terminals concentrates demand for high-capacity passenger units.
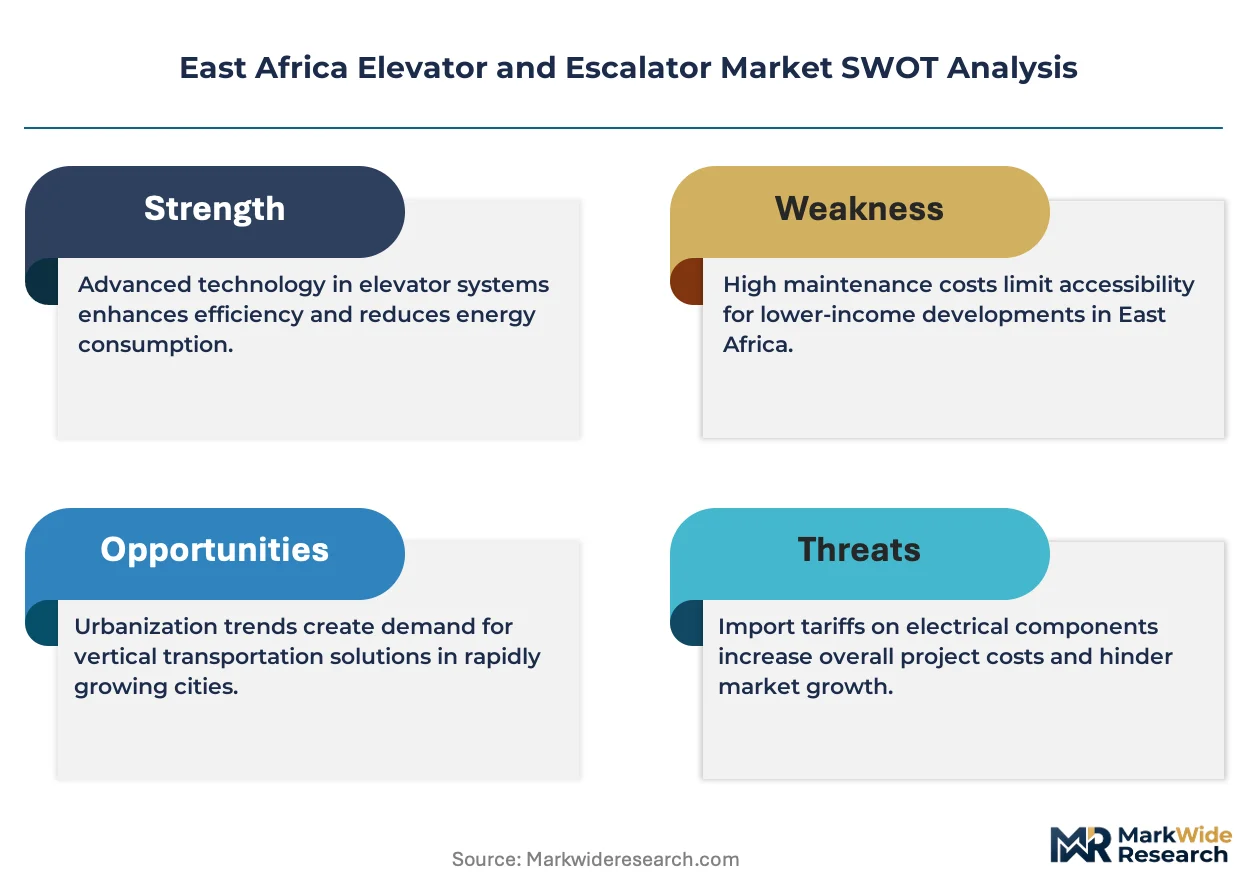
- Steel-reinforced composite cab panels:These materials reduce installation weight by approximately one-third compared to aluminum, lowering structural reinforcement costs for mid-rise developers.
Market Restraints
- Import duty exposure on control systems:Elevator controllers and variable frequency drives face steep tariffs at Mombasa and Dar es Salaam ports, inflating landed costs for European and Asian OEMs.
- Generator backup requirements:Unreliable grid supply in secondary cities forces developers to specify dual-power systems, adding capex that delays project approvals.
- Skilled technician scarcity:Certified elevator mechanics concentrate in Nairobi and Addis Ababa, leaving Kampala and Kigali with six-month service response lags.
Strategic Opportunities
- Uganda's underpenetrated hospital segment:Kampala's private healthcare construction boom lacks vertical transport specialists, creating first-mover advantage for maintenance contract bundlers.
- Tanzania's Energy and Water Utilities Regulatory Authority certification streamlining:Proposed electrical safety reciprocity with Kenya would reduce dual-testing burdens for cross-border suppliers.
- Predictive maintenance convergence:IoT sensor integration with existing elevator controllers enables remote diagnostics, cutting unplanned downtime for commercial landlords.
Industry Challenges
- Counterweight safety system recertification:Kenya's National Construction Authority now requires annual third-party load-testing, compressing vendor margins on legacy maintenance contracts.
- Legacy hydraulic system parts obsolescence:Manufacturers have discontinued piston seal specifications for pre-2010 installations, forcing building owners toward full modernization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | East Africa Elevator and Escalator Market |
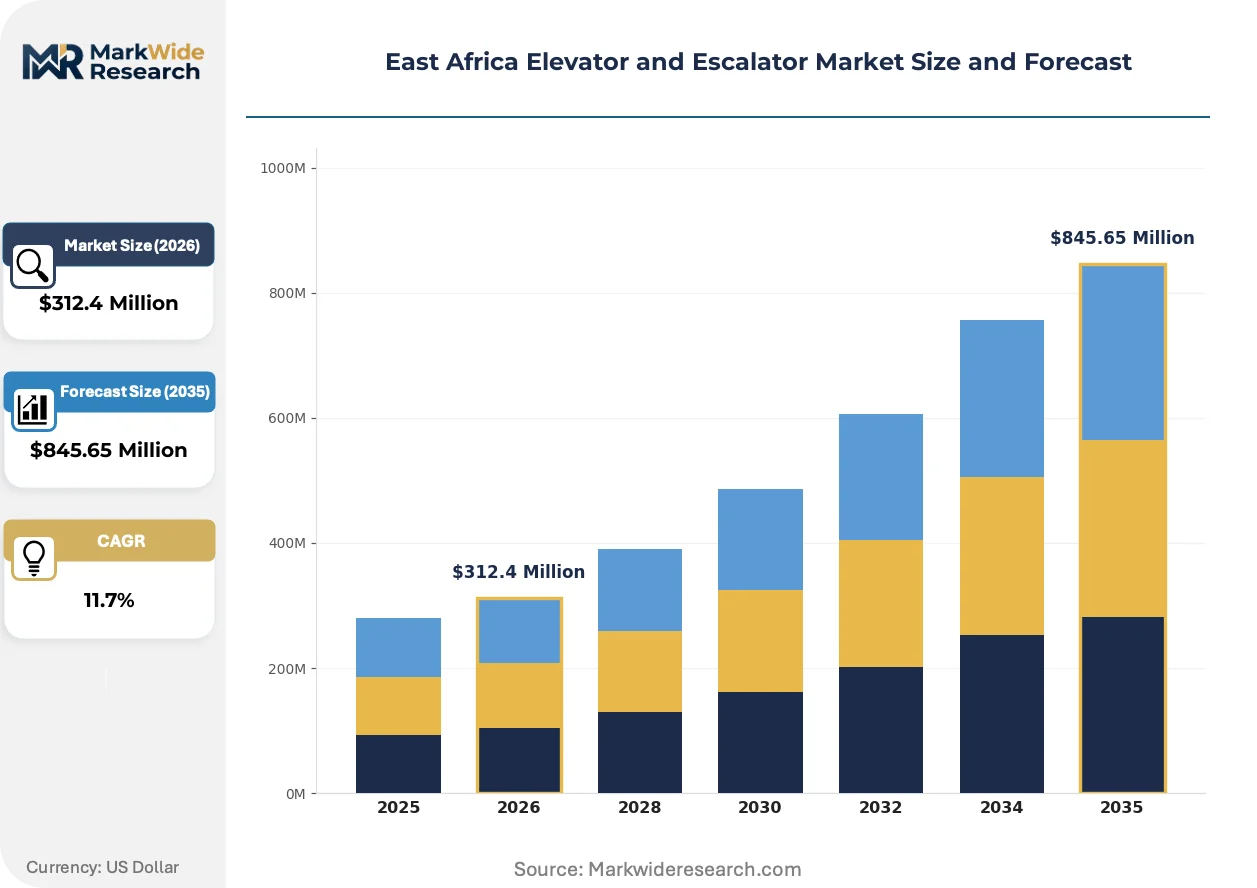
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $845.65 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Passenger Elevators, Freight Elevators, Escalators, Moving Walkways Installation Type: New Installation, Modernization, Maintenance, Repair End User: Residential Buildings, Commercial Complexes, Transport Hubs, Industrial Facilities Driving Technology: Hydraulic, Traction, Machine Room-Less, Gearless |
| Companies Covered | Otis Elevator Company, Schindler Group, KONE Corporation, Mitsubishi Electric, Fujitec, Hitachi Elevator Technologies, East Africa Elevators, Multitech Elevator Services Ltd, SKYMAX ELEVATOR LIMITED, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
East Africa Elevator and Escalator Market Emerging Trajectories
Digitalization of maintenance workflows and material substitution in cab construction are redrawing competitive boundaries between full-service OEMs and independent service providers.
Regenerative drive technology is absorbing kinetic energy from descending cars and feeding it back into building electrical systems. Nairobi commercial developers are specifying these units in new Class A office towers to offset generator fuel consumption. This efficiency architecture is compressing total cost-of-ownership calculations for landlords comparing traction against hydraulic alternatives.
Ethiopia's Ministry of Urban Development and Construction has tightened accessibility compliance timelines for public buildings, requiring elevator installation in all new structures exceeding three stories. Contractors face penalties for certificate delays, accelerating pre-qualification of vendors with local assembly partnerships. Addis Ababa's state housing agency is prioritizing bids from suppliers with Ethiopian-registered service subsidiaries.
Building owners are unbundling maintenance from original equipment procurement, signing separate multi-year service agreements with specialized providers. This disintermediation fragments revenue streams for traditional OEMs while opening margin pools for independent technicians with controller-agnostic diagnostic tools. Dar es Salaam's retail mall operators pioneered this split-contract model, with Kampala hospitality developers now adopting similar structures.
East Africa Elevator and Escalator Market Segmentation
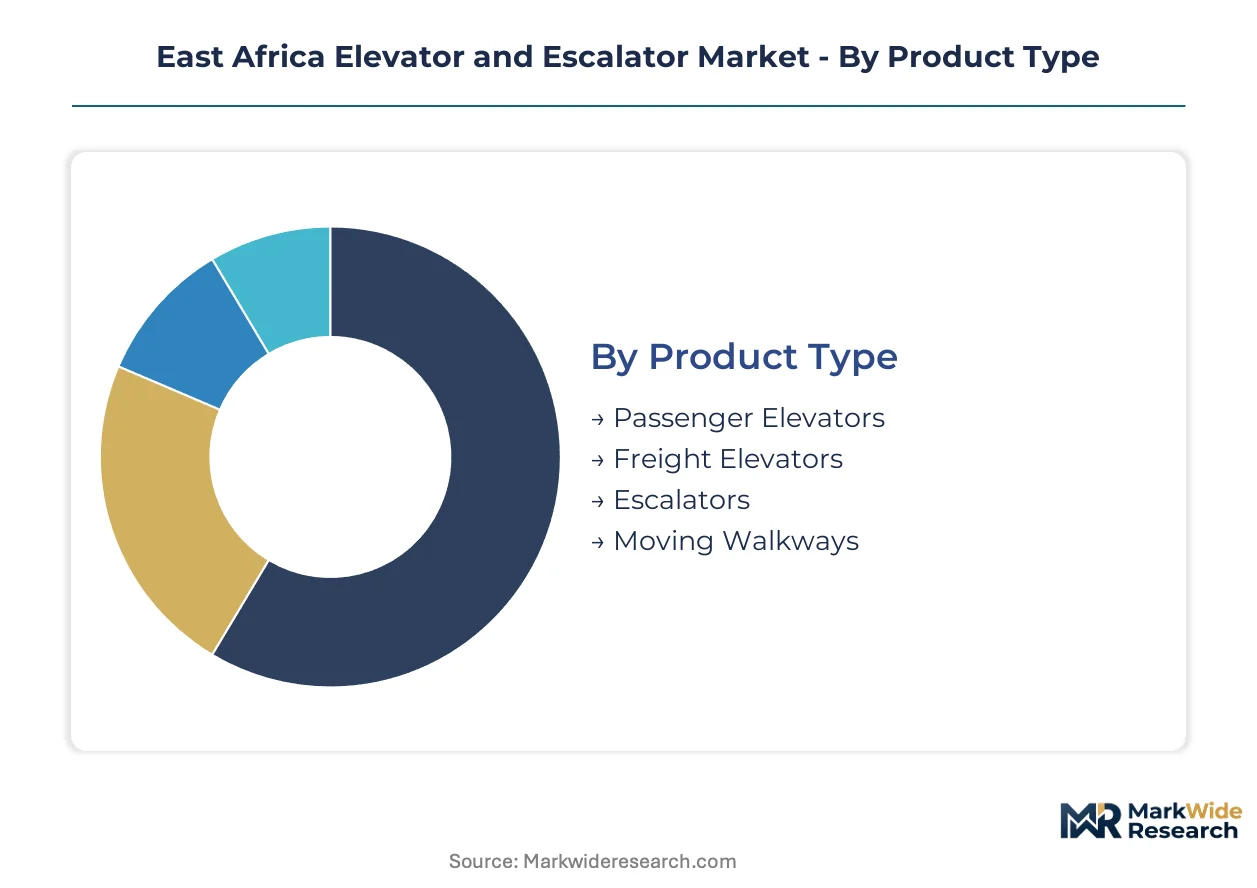
Segmentation reveals how procurement priorities diverge across East African capitals. Building owners in Nairobi and Addis Ababa weight lifecycle costs differently than Dar es Salaam developers, reshaping vendor product mix and service bundling strategies.
Product Type:
Replacement cycles vary dramatically by vertical transport category, with aging hydraulic systems in 1990s-era commercial towers creating upgrade windows that outpace new construction demand.
- Passenger Elevators:These units incorporate microprocessor-based dispatch algorithms and variable voltage variable frequency drives to optimize traffic flow in high-rise residential towers. Demand concentrates most intensely in Addis Ababa's state housing corridor, where Ethiopia's Ministry of Urban Development and Construction mandates three-story minimum elevator requirements for accessibility compliance.
- Freight Elevators:Reinforced platform designs accommodate palletized goods and heavy equipment with load ratings typically exceeding 2,500 kilograms. Industrial zone developers in Nairobi's Tatu City and Dar es Salaam's Kigamboni precinct specify these units for manufacturing and logistics facilities facing just-in-time delivery pressures.
- Escalators:Continuous loop step systems serve retail complexes and transit terminals where pedestrian volume exceeds 4,000 persons per hour. Installation concentrates in Kampala's emerging shopping mall developments and Mombasa's ferry terminal modernization.
- Moving Walkways:Horizontal or shallow-incline conveyors bridge extended distances in airport terminals and exhibition centers. Entebbe International Airport's expansion and Jomo Kenyatta International Airport's Terminal 1B retrofit constitute primary demand nodes.
Volume placements concentrate in passenger elevators; the faster expansion belongs to escalators.
Installation Type:
Cost tier differentiation separates capital-intensive new construction from recurring-revenue service streams, with maintenance contracts delivering superior margin stability across volatile building cycles.
- New Installation:Complete system deployment encompasses shaft construction, car assembly, controller programming, and safety certification. Nairobi's Kilimani and Westlands commercial districts drive specification of machine room-less traction systems for Class A office towers seeking LEED-equivalent efficiency ratings.
- Modernization:Partial or full system overhaul replaces controllers, drives, door operators, and safety mechanisms while retaining existing structural elements. Aging installed bases in Mombasa's 1980s hotel stock and Dar es Salaam's early-2000s commercial buildings generate retrofit pipelines as Kenyan and Tanzanian regulators tighten inspection protocols.
- Maintenance:Scheduled inspection, lubrication, adjustment, and component replacement programs ensure code compliance and operational uptime. Building owners in Addis Ababa increasingly unbundle these contracts from original equipment procurement, fragmenting OEM revenue streams.
- Repair:Unscheduled corrective interventions address component failures, entrapment incidents, and safety system malfunctions. Response time guarantees differentiate service providers in secondary cities where certified technician scarcity extends downtime risks.
Maintenance captures the largest revenue pool; modernization is climbing the fastest as regulatory deadlines force upgrades.
End User:
Application-specific requirements reshape technical specifications, with transport hubs demanding highest-duty cycles and residential towers prioritizing acoustic performance.
- Residential Buildings:Mid-rise and high-rise apartment towers specify gearless traction or machine room-less systems with noise-dampened cab enclosures. Ethiopia's state-led condominium program in Addis Ababa anchors volume demand, while private developers in Nairobi's Upper Hill district compete on luxury finishes and destination dispatch technology.
- Commercial Complexes:Office towers, retail malls, and mixed-use developments require high-availability systems with traffic management software and regenerative drive capability. Two Rivers Mall in Nairobi and Mlimani City in Dar es Salaam exemplify specification standards for premium retail environments.
- Transport Hubs:Airports, railway terminals, and bus stations demand heavy-duty escalators and elevators with 20-hour daily operating capacity. Addis Ababa's light rail transit integration and Mombasa's standard gauge railway terminus concentrate procurement for high-volume passenger handling.
- Industrial Facilities:Manufacturing plants, warehouses, and distribution centers utilize freight elevators with reinforced platforms and explosion-proof controllers. Special economic zones in Tanzania's Bagamoyo and Kenya's Naivasha attract vertical transport investment tied to export processing incentives.
Commercial complexes dominate current placements; transport hubs are gaining share fastest as infrastructure corridors mature.
Driving Technology:
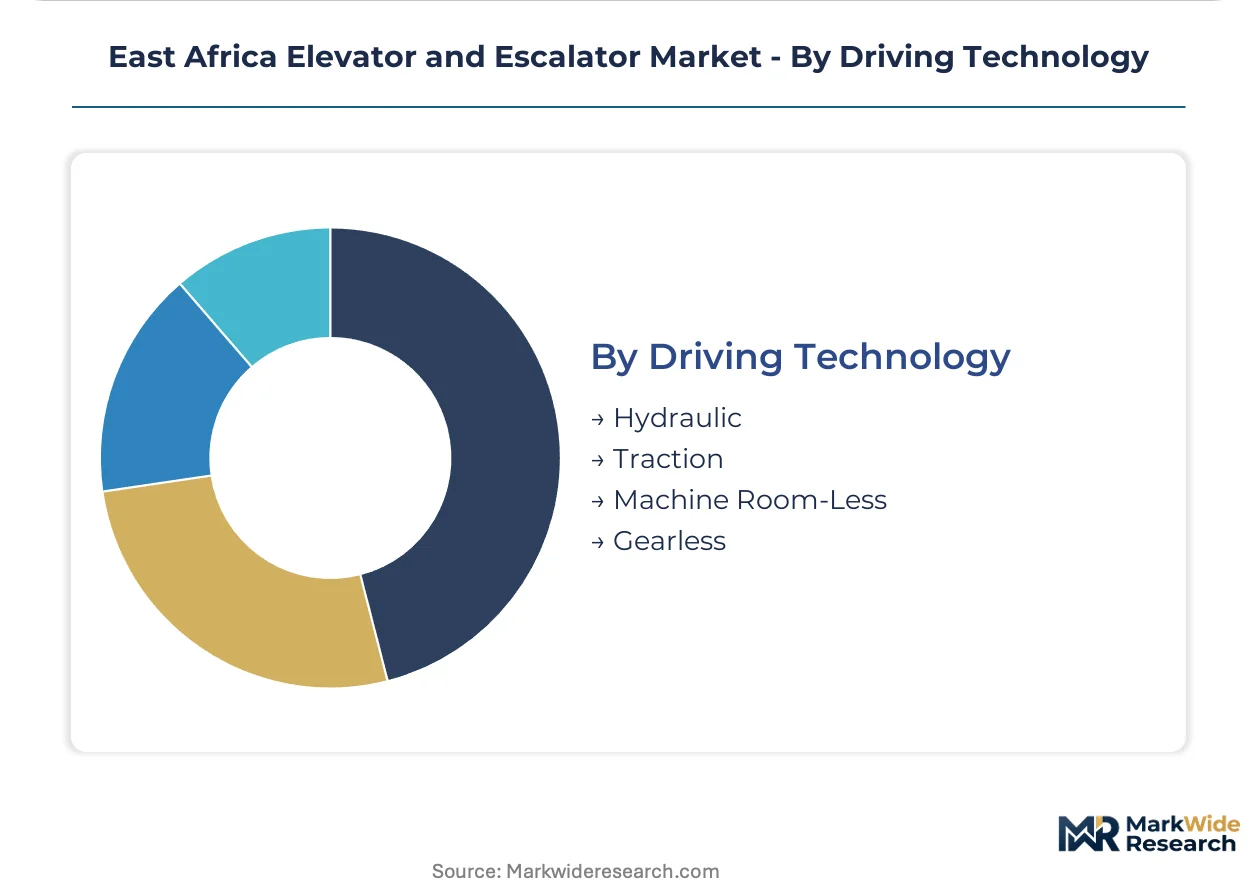
Technology maturity curves separate legacy hydraulic installations from next-generation gearless systems, with building height and grid reliability dictating optimal architecture selection.
- Hydraulic:Piston-driven systems serve low-rise applications up to six stories with minimal overhead requirements and lower initial capital outlay. Pre-2010 installations across Kampala's commercial core face obsolescence pressure as manufacturers discontinue seal specifications.
- Traction:Rope-and-sheave mechanisms with counterweight balancing accommodate mid-rise and high-rise structures with energy efficiency superior to hydraulic alternatives. Kenyan National Construction Authority load-testing mandates accelerate replacement of aging traction controllers in Nairobi's 1990s office stock.
- Machine Room-Less:Compact permanent-magnet motors integrated within the hoistway eliminate dedicated mechanical floors, reclaiming leasable square footage. Space-constrained developments in Dar es Salaam's Msasani Peninsula and Nairobi's Westlands district specify these systems for premium rent optimization.
- Gearless:Direct-drive permanent-magnet synchronous motors eliminate gearbox maintenance and enable speeds exceeding 2.5 meters per second for high-rise towers. Addis Ababa's government tower construction and private luxury residential developments specify gearless traction for superior ride quality and energy recovery.
Traction systems retain the largest installed base; machine room-less technology shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates most intensely in Ethiopia's Addis Ababa corridor, where state-led infrastructure expansion is reshaping vertical transport procurement. Kenya's commercial districts and Tanzania's port cities follow as secondary demand nodes. Regulatory divergence across national jurisdictions fragments vendor compliance strategies.
Ethiopia
Addis Ababa's government tower construction and state housing condominium program anchor regional volume demand. Ethiopia's Ministry of Urban Development and Construction mandates elevator installation in all new structures exceeding three stories, with penalty enforcement for certificate delays. The state housing agency prioritizes bids from suppliers with Ethiopian-registered service subsidiaries.
Kenya
Nairobi's Kilimani and Westlands commercial districts drive specification of machine room-less traction systems for Class A office towers. Kenya's National Construction Authority enforces annual third-party load-testing protocols and accessibility retrofits for commercial structures above four stories. Mombasa's 1980s hotel stock generates modernization pipelines as inspection protocols tighten.
Tanzania
Dar es Salaam's Msasani Peninsula developments specify compact drive architectures to reclaim leasable square footage. Tanzania's Energy and Water Utilities Regulatory Authority governs electrical safety certification for vertical transport equipment, with proposed reciprocity with Kenya to reduce dual-testing burdens. Mlimani City retail complex exemplifies premium escalator specifications for high-volume pedestrian handling.
Uganda
Kampala's private healthcare construction boom lacks vertical transport specialists, creating first-mover advantage for maintenance contract bundlers. Uganda's national standards body applies East African Community harmonized technical regulations for mechanical lifting appliances, creating cross-border compliance obligations. Certified technician scarcity extends service response lags to six months.
Rwanda
Kigali's emerging commercial tower stock imports specifications from Nairobi and Addis Ababa construction standards. The country's national construction regulator applies phased accessibility compliance timelines modeled on Ethiopian and Kenyan precedents. Secondary city developments face generator backup requirements that inflate capex and delay project approvals.
East Africa Elevator and Escalator Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with full-service OEMs dominating new installation while independent providers capture unbundled maintenance contracts. The vendor base concentrates around multinational traction technology suppliers with regional assembly partnerships and localized service subsidiaries. Three archetypes define competitive positioning: integrated OEMs with captive maintenance networks, controller-agnostic independent service providers, and emerging regional fabricators with import duty advantages. Geographic expansion through Ethiopian-registered subsidiaries and strategic partnerships for localized assembly represent the dominant competitive moves.
Among integrated OEMs with established East African footprints, Otis Elevator Company, KONE Corporation, and Schindler Group exemplify the full-service archetype. These entities anchor maintenance contract penetration in Nairobi's commercial district, compete through gearless traction specialization for Addis Ababa high-rise residential towers, and sustain positioning via localized assembly partnerships that reduce import duty exposure. East Africa Elevators and Multitech Elevator Services Ltd represent regional independent service providers unbundling maintenance from original equipment procurement.
| Leading Market Players |
|---|
| Otis Elevator Company |
| Schindler Group |
| KONE Corporation |
| Mitsubishi Electric |
| Fujitec |
| Hitachi Elevator Technologies |
| East Africa Elevators |
| Multitech Elevator Services Ltd |
| SKYMAX ELEVATOR LIMITED |
| Others |
Supply Flow & Price Mechanics
Certification-grade bifurcation between NCA-compliant systems and non-certified alternatives splits procurement budgets across Nairobi and Addis Ababa, compressing margins on entry-level traction units while premium gearless installations command structural reinforcement cost absorption. This tier divergence feeds directly into supply chain configurations, with certified component distributors concentrating in Mombasa and Dar es Salaam ports while gray-market controllers filter through secondary channels.
Pricing Analysis
Volume placements in passenger elevators run on thin project margins while maintenance contracts deliver superior margin stability. Pricing stratifies across premium gearless traction, standard machine room-less systems, and economy hydraulic tiers, with certification grade and after-sales service bundling as primary differentiation drivers. Cost compression in economy hydraulic retrofits is intensifying because Kenya's National Construction Authority mandates accelerate replacement timelines. Public sector procurement in Addis Ababa shows least price sensitivity; Kampala private hospital developers exhibit highest.
Supply Chain Analysis
Single-source vulnerability sits with permanent-magnet motor controllers sourced predominantly from China, South Korea, and Germany. Steel-reinforced composite cab panels, variable frequency drives, and safety brake assemblies anchor raw material dependencies. Tariff exposure at Mombasa and Dar es Salaam ports constitutes the dominant structural risk. Distribution runs through Nairobi-based OEM service subsidiaries with cross-border technician deployment to Addis Ababa and Kampala.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from Kenya's National Construction Authority certification mandates is forcing independent service providers without NCA audit credentials toward exit or acquisition.
For Market Incumbents: Acquire certified technician teams to lock in maintenance contract pipelines. Otis and KONE anchor positions through gearless traction specialization; smaller independents face margin compression from annual third-party load-testing requirements. Backward integration into controller-agnostic diagnostic tools defends against disintermediation. For New Entrants and Emerging Players: Predictive maintenance IoT convergence offers technology-first entry into Uganda's underpenetrated hospital segment. Kampala's six-month service response lags represent the most penetrable white-space. Partner with Ethiopian-registered assembly facilities to bypass import duty exposure. For Investors and Strategic Acquirers: Re-rating potential sits with controller-agnostic independent service providers given unbundling trends in Addis Ababa and Dar es Salaam. Long-term viability favors technicians with NCA and Tanzania Energy and Water Utilities Regulatory Authority dual certification. Watch for reciprocity agreement finalization between Kenyan and Tanzanian electrical safety regulators as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Ethiopian-Registered Service Subsidiary Establishment | Addis Ababa's state housing agency prioritizes bids from locally registered vendors. |
| Predictive Maintenance Platform Deployment | IoT sensor integration cuts unplanned downtime for Nairobi commercial landlords. |
| Localized Assembly Partnership Formation | Dar es Salaam port proximity reduces import duty exposure on control systems. |
| Dual-Certification Technician Training Program | Kenya-Tanzania regulatory reciprocity would enable cross-border service deployment. |
| Controller-Agnostic Diagnostic Tool Development | Maintenance unbundling fragments OEM revenue streams for independent capture. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs. Primary interviews with elevator maintenance directors, National Construction Authority compliance officers, hospital procurement managers, and aftermarket service heads combined with Kenya Bureau of Standards technical regulations, Ethiopia Ministry of Urban Development construction permits, and East African Community harmonized tariff schedules. Bottom-up installation tracking and top-down construction spend estimates were triangulated.
Granularity-level modeling ran product type, installation category, end-user application, and driving technology dimensions at country-city cluster resolution. CAGRs were derived from fitted growth curves across the projection horizon. Gearless traction penetration rates, regulatory compliance deadline phasing, and state housing procurement pipeline visibility served as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including currency devaluation scenarios affecting import-dependent control systems and grid reliability improvements that could alter generator backup specification rates. Forecasts reflect documented assumptions about enforcement continuity for accessibility mandates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Hoist Chains Market
Material Handling Equipment
Middle East Conveyor Belts Market
Material Handling Equipment
Drag Chain for Machine Market
Material Handling Equipment
Hydraulic Fittings Market
Material Handling Equipment
Global Tension Control Market
Material Handling Equipment
Rotary Indexer Market
Material Handling Equipment
Ship Loader and Unloader Market
Material Handling Equipment
Asia-Pacific Forklift Rental Market
Material Handling Equipment
Global Rolling Mill Rolls Market
Material Handling Equipment
Industrial Bag Dust Filter Market
Material Handling Equipment
Cable Conduit Market
Material Handling Equipment
Electric Single Beam Crane Market
Material Handling Equipment
Carry Deck Crane Market
Material Handling Equipment
Shaft Shredder Market
Material Handling Equipment
Europe Conveyors Market
Material Handling Equipment
Global Industrial Weighing Equipment Market