
 Europe Forklift Truck Market | 2026-2036
Europe Forklift Truck Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Forklift Truck Market Analytics
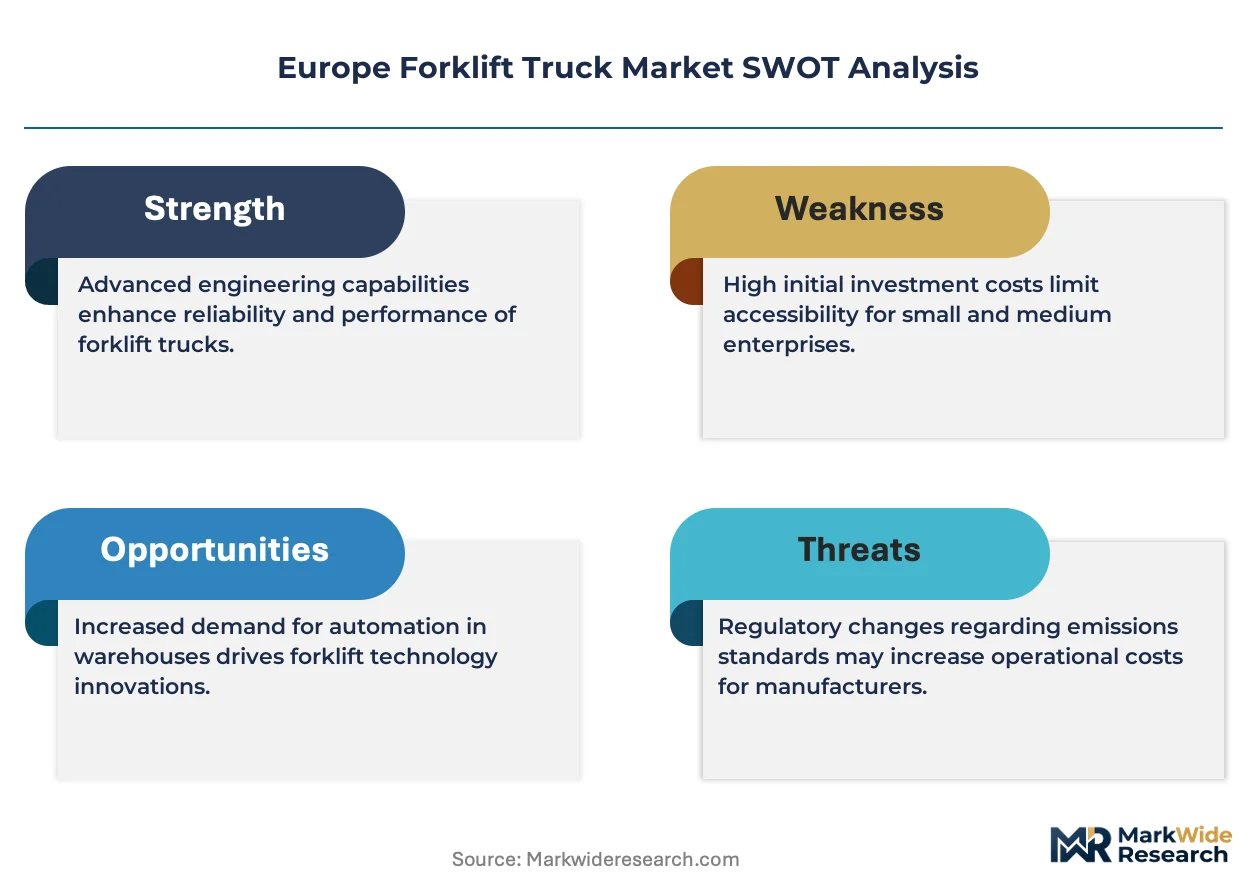
The EU F-Gas Regulation is pivoting total cost-of-ownership calculations toward electric powertrains by penalizing refrigerant-intensive internal combustion designs. Jungheinrich AG leverages its German manufacturing base to anchor premium electric forklift supply across Central European warehousing networks. KION Group AG competes through vertical integration into automation software, pairing hardware with warehouse control systems. Toyota Material Handling sustains brand strength in lean-manufacturing environments where reliability metrics dominate procurement criteria.
A forklift truck is a powered industrial vehicle equipped with hydraulic lifting mechanisms and fork attachments designed to transport palletized loads across distances typically under 50 meters, with load capacities ranging from one to over ten metric tons depending on mast configuration and counterweight design. Electric forklifts now dominate new order intake as lithium-ion battery packs eliminate the maintenance burden and charging downtime associated with lead-acid chemistry. The warehousing end-user segment leads absolute volume, while smart technology integration represents the fastest-expanding margin pool as telematics and fleet optimization software command premium pricing. Capacity demand clusters in the 1-3 ton range for retail distribution, with heavier 4-6 ton units sustaining manufacturing floor operations.
CE marking requirements under the EU Machinery Directive establish mandatory safety and electromagnetic compatibility standards that shape product design cycles for all suppliers accessing European markets. ECHA's REACH framework restricts hazardous substances in battery components and hydraulic fluids, directly influencing material selection and supplier qualification processes. Germany's KBA enforces type-approval protocols for road-capable forklift variants that cross public thoroughfares between industrial zones. Stakeholders must monitor how the EU AI Act's risk-classification rules will apply to autonomous navigation systems before committing capital to fully automated fleet deployments.
Market Dynamics
The EU F-Gas Regulation's hydrofluorocarbon phase-down is compressing the total cost-of-ownership gap between electric and internal combustion powertrains across European warehousing networks. Battery chemistry advances and port-connected logistics clusters in the Rhine-Ruhr corridor are accelerating fleet electrification timelines.
Growth Catalysts
- Lithium-ion energy density gains:Higher throughput distribution centers in the Netherlands are eliminating lead-acid maintenance burdens and charging downtime, shortening fleet turnover cycles.
- EU Green Deal decarbonization mandates:Logistics operators face binding emissions reduction targets that favor zero-emission material handling equipment in cross-dock facilities.
- Port-connected warehousing clusters:Belgium's Antwerp-Rotterdam corridor demands rapid fleet electrification to maintain throughput velocity under tightening environmental compliance.
Market Restraints
- Critical mineral supply concentration:Lithium and cobalt processing capacity concentrates in limited geographies, exposing European battery pack assemblers to input cost volatility and geopolitical disruption.
- Charging infrastructure capex requirements:High-voltage depot charging installations demand substantial upfront capital that strains mid-sized third-party logistics operators.
- REACH substance restrictions:ECHA's evolving hazardous substance frameworks complicate hydraulic fluid formulations and battery component qualification timelines.
Strategic Opportunities
- Autonomous navigation convergence:Sensor fusion and warehouse management system integration create white space for self-guided forklift deployments in Polish distribution centers.
- Telematics-as-a-service monetization:Fleet optimization software bundled with hardware contracts commands premium pricing in French retail distribution networks.
- Italian manufacturing floor electrification:Underpenetrated heavy-duty segments in automotive assembly plants present volume expansion potential for 4-6 ton electric configurations.
Industry Challenges
- High-voltage technician certification gaps:Lithium-ion battery maintenance and thermal runaway response protocols require specialized training that outpaces current workforce development pipelines.
- CE marking electromagnetic compatibility testing:Extended validation cycles under the EU Machinery Directive delay product launch timelines for autonomous navigation variants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Forklift Truck Market |
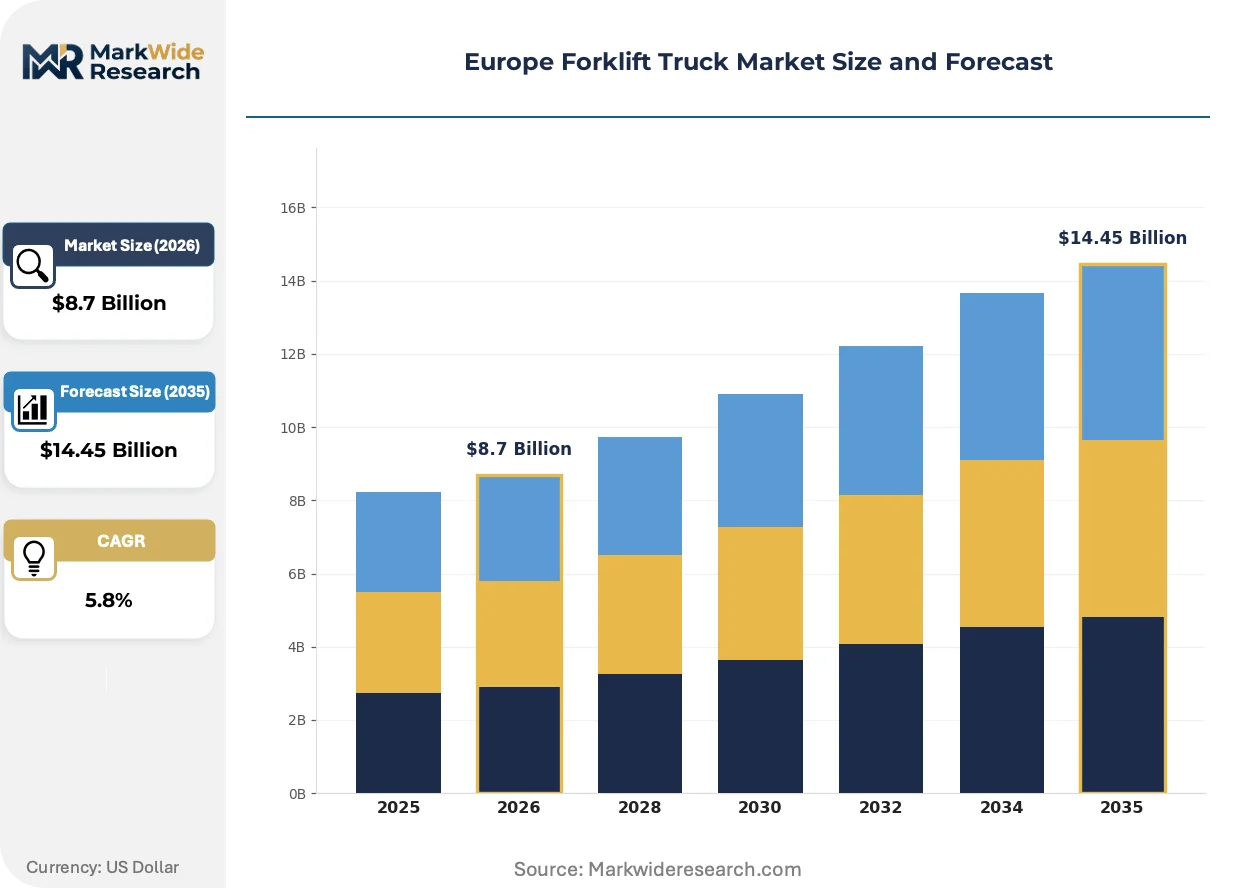
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Forklifts, Diesel Forklifts, LPG Forklifts, Reach Trucks End User: Warehousing, Manufacturing, Construction, Retail Technology: Automation, Manual, Semi-Automatic, Smart Technology Capacity: 1-3 Ton, 4-6 Ton, 7-10 Ton, Above 10 Ton |
| Companies Covered | Hyster-Yale Group, Mitsubishi Logisnext, Jungheinrich AG, Hangcha Group, Clark Material Handling Company, KION Group AG, Crown Equipment Corporation, Komatsu Ltd, Toyota Material Handling, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Forklift Truck Market Evolving Landscape
Electrification and automation are converging to redefine equipment specifications and procurement criteria across European material handling operations. Three developments dominate competitive positioning.
Lithium-ion battery packs are overtaking lead-acid configurations as the default power source for high-rotation warehouse fleets. Retail distribution operators in Germany and the Netherlands are specifying lithium-ion for all new 1-3 ton capacity orders, compressing maintenance cost structures and enabling opportunity charging that eliminates shift-change battery swaps.
REACH substance restrictions are tightening material selection protocols for hydraulic fluids and battery electrolytes. Suppliers must reformulate components to eliminate restricted substances, extending qualification timelines and forcing dual-sourcing strategies for critical chemistries. Battery pack assemblers face the most acute compliance burden as ECHA expands the candidate list of substances of very high concern.
Telematics-enabled fleet optimization is restructuring service relationships between equipment suppliers and end-users. Real-time utilization data allows usage-based pricing models that displace traditional lease structures, with French and Belgian logistics operators leading adoption. Hardware margins compress while software and analytics revenue pools expand, reshaping supplier economics.
Europe Forklift Truck Market Segmentation
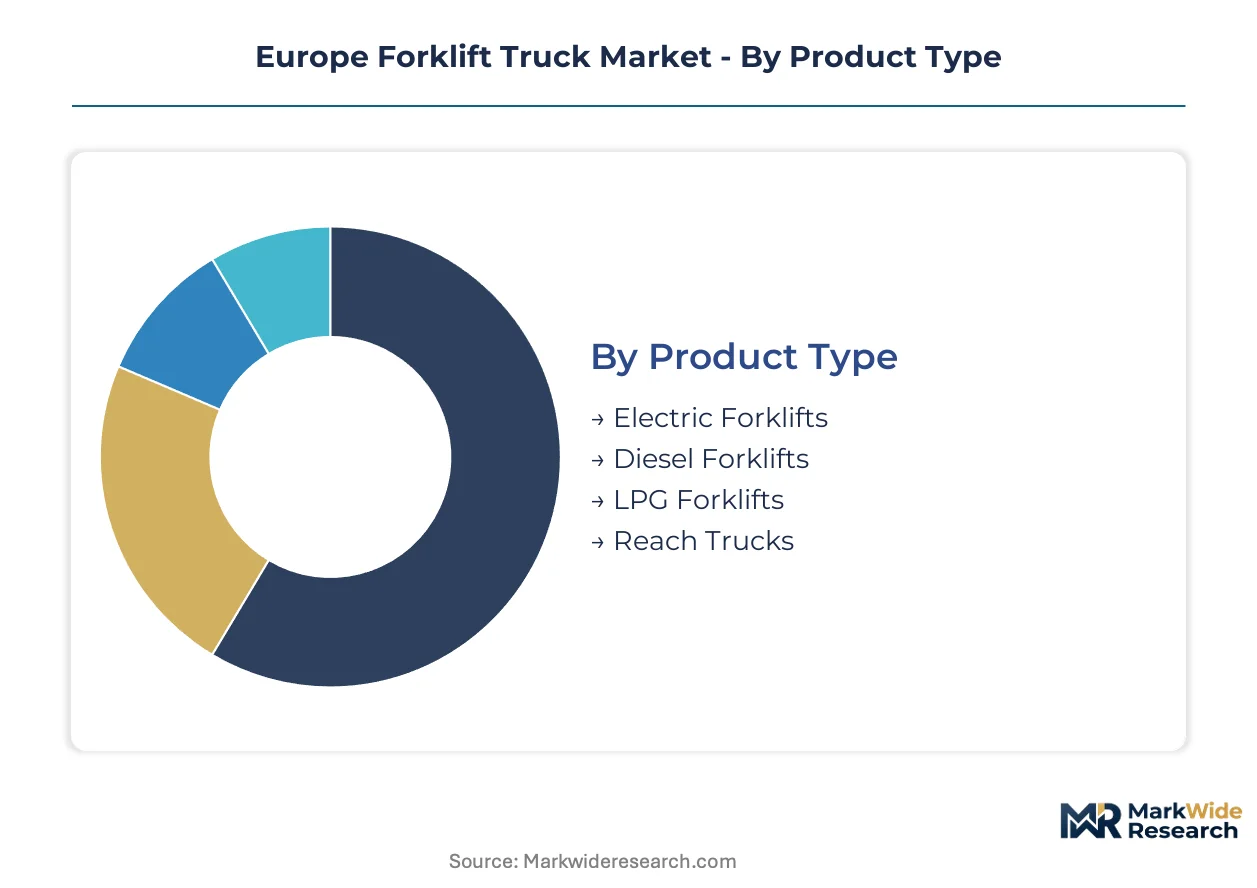
Procurement patterns across European material handling networks diverge sharply by operational intensity and regulatory exposure. Fleet managers prioritize electrification timelines and automation readiness over upfront capital metrics when segmenting purchase decisions.
Product Type:
Replacement cycles accelerate where total cost-of-ownership calculations incorporate carbon pricing and maintenance burden reduction.
- Electric Forklifts:Lithium-ion battery packs deliver energy density improvements that eliminate shift-change battery swaps in high-rotation German distribution centers. Rhine-Ruhr port-connected warehousing clusters specify electric configurations exclusively to comply with EU F-Gas Regulation phase-down schedules.
- Diesel Forklifts:Internal combustion powertrains retain residual demand in outdoor yard operations and heavy-lift applications where charging infrastructure remains absent. Belgian construction logistics operators specify diesel for 7-10 ton capacity requirements in greenfield project sites lacking grid connections.
- LPG Forklifts:Dual-fuel configurations serve transitional fleet strategies in Italian manufacturing floors where electrification capex strains mid-tier operators.
- Reach Trucks:Narrow-aisle variants maximize cubic utilization in Dutch cold-storage facilities with vertical racking exceeding twelve meters.
Volume placements concentrate in Electric Forklifts; the faster expansion belongs to Reach Trucks.
End User:
Margin capture varies by operational complexity and software integration requirements across customer archetypes.
- Warehousing:Third-party logistics operators in France demand telematics-enabled fleet optimization bundled with hardware contracts. E-commerce fulfillment velocity drives specification of 1-3 ton lithium-ion configurations with opportunity charging capability.
- Manufacturing:Automotive assembly plants in Spain require 4-6 ton electric units for just-in-time component delivery to production lines. Toyota Production System environments prioritize reliability metrics over acquisition cost in procurement criteria.
- Construction:Infrastructure project timelines in Poland favor diesel and LPG rough-terrain variants for material staging in unimproved site conditions.
- Retail:Big-box distribution networks in the Netherlands specify compact electric forklifts for back-of-store inventory management with rapid turnover requirements.
Revenue concentration sits with Warehousing; Manufacturing delivers the steepest expansion trajectory as electrification penetrates heavy-duty segments.
Technology:
Adoption velocity depends on workforce technical readiness and warehouse management system maturity.
- Automation:Sensor fusion and autonomous navigation systems enable self-guided forklift deployments in Polish distribution centers with standardized rack configurations. EU AI Act risk-classification rules delay capital commitment timelines for fully automated fleet deployments.
- Manual:Operator-controlled equipment dominates replacement purchases in small-fleet logistics operators with limited IT infrastructure. Spanish regional distributors specify manual configurations for 1-3 ton capacity requirements in secondary market segments.
- Semi-Automatic:Assisted steering and load-height optimization reduce operator fatigue in high-bay Belgian cold-storage operations.
- Smart Technology:Real-time utilization data enables usage-based pricing models that displace traditional lease structures in French retail distribution networks.
Deployment volumes favor Manual systems; Smart Technology gains share fastest as telematics monetization restructures supplier economics.
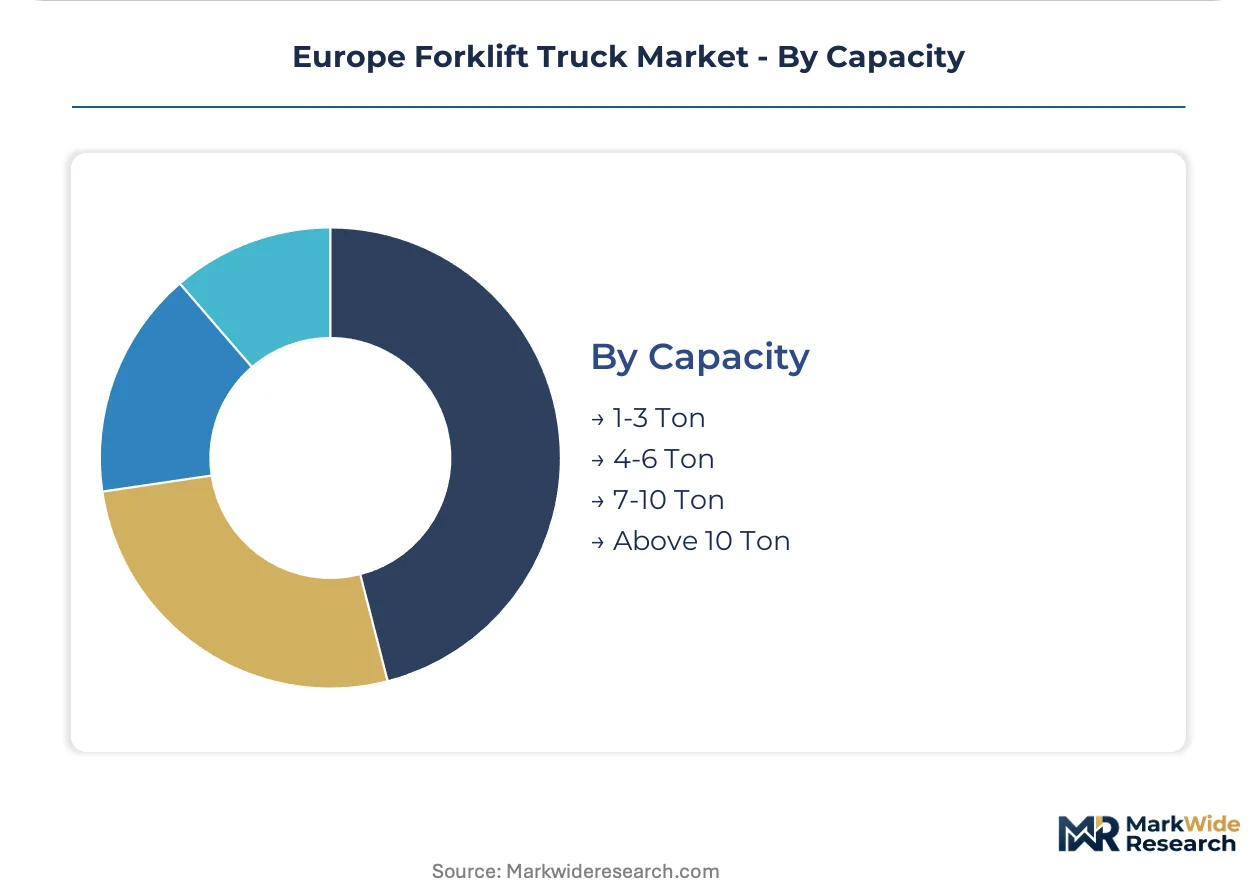
Capacity:
Specification patterns track load density and vertical racking requirements across facility types.
- 1-3 Ton:Compact electric units serve retail distribution and light manufacturing with rapid acceleration and tight turning radius requirements. German e-commerce fulfillment centers specify this range exclusively for aisle widths below three meters.
- 4-6 Ton:Heavy-duty electric configurations penetrate Italian automotive assembly plants previously served by diesel powertrains. Battery thermal management advances enable sustained duty cycles in high-throughput manufacturing floors.
- 7-10 Ton:Port logistics operators in Belgium deploy this range for container stuffing and cross-dock consolidation of dense commodities.
- Above 10 Ton:Specialized steel and paper handling applications in the Netherlands require reinforced mast configurations for extreme load centers.
Order intake concentrates in 1-3 Ton; 4-6 Ton climbs the fastest as electrification extends into manufacturing floor operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for forklift trucks concentrates in port-connected logistics corridors where electrification mandates intersect with high-throughput warehousing operations. The Rhine-Ruhr logistics cluster anchors volume placement across the region.
Germany
E-commerce fulfillment velocity and automotive just-in-time delivery networks drive specification of lithium-ion electric configurations. KBA enforces type-approval protocols for road-capable variants crossing between industrial zones. The Rhine-Ruhr corridor warehouses specify electric fleets exclusively to comply with EU F-Gas Regulation phase-down schedules.
Netherlands
Rotterdam-Antwerp port logistics operators demand rapid fleet turnover to maintain throughput velocity under tightening environmental compliance. EU Green Deal decarbonization mandates bind logistics operators to emissions reduction targets favoring zero-emission equipment. Distribution centers in the Randstad specify compact electric units for high-rotation fulfillment operations.
France
Third-party logistics operators seek telematics-enabled fleet optimization bundled with hardware contracts. REACH substance restrictions complicate hydraulic fluid formulations and battery component qualification timelines. Retail distribution networks in the Île-de-France region command premium pricing for software-integrated equipment.
Italy
Automotive assembly plants require heavy-duty electric units for manufacturing floor operations previously served by diesel powertrains. ECHA's evolving hazardous substance frameworks extend supplier qualification timelines for battery pack assemblers. Underpenetrated heavy-duty segments in Lombardy and Piedmont automotive clusters present volume expansion potential.
Belgium
Antwerp port logistics operators deploy 7-10 ton capacity units for container stuffing and cross-dock consolidation. CE marking requirements under the EU Machinery Directive establish mandatory safety standards shaping product design cycles. Cold-storage facilities in the Flanders region specify narrow-aisle reach trucks for vertical racking exceeding twelve meters.
Europe Forklift Truck Market Competitive Landscape
German producers anchor the premium-tier supply base; Japanese and American specialists hold positions across lean-manufacturing and reliability-focused procurement channels. The vendor base organizes around three strategic archetypes: integrated automation-hardware bundlers, pure-play electric powertrain specialists, and diversified industrial conglomerates with captive material handling divisions. Consolidation pressure intensifies as software monetization restructures supplier economics. Geographic expansion into Central European warehousing networks and backward integration into battery pack assembly represent dominant competitive moves.
Within the integrated automation tier, Jungheinrich AG and KION Group AG exemplify European-based fabricators pairing hardware with warehouse control systems. Toyota Material Handling occupies a position emphasizing reliability metrics in lean-manufacturing procurement environments. These three anchors illustrate how competitive positioning diverges between software-forward bundling strategies and manufacturing-floor dependability positioning.
| Leading Market Players |
|---|
| Hyster-Yale Group |
| Mitsubishi Logisnext |
| Jungheinrich AG |
| Hangcha Group |
| Clark Material Handling Company |
| KION Group AG |
| Crown Equipment Corporation |
| Komatsu Ltd |
| Toyota Material Handling |
| Others |
Value Network & Pricing Analysis
Lithium-ion battery pack assembly lines migrating from China to Eastern Europe simultaneously compress logistics costs and redistribute supplier bargaining power across the European forklift truck market. This production-method transition tightens margin structures for battery-integrated equipment while amplifying price competition among lead-acid dependent incumbents.
Pricing Analysis
Volume placements concentrate in standard-tier electric configurations while premium margins accrue to automation-ready lithium-ion bundles with telematics integration. Price differentiation separates CE-marked warehouse fleets from economy-tier yard trucks lacking electromagnetic compatibility certification. Cost compression in the standard tier intensifies because Chinese manufacturers exploit tariff loopholes through Turkish trans-shipment hubs. Third-party logistics operators exhibit highest price sensitivity; automotive OEMs prioritize total cost-of-ownership reliability metrics over acquisition discounts.
Supply Chain Analysis
Battery refurbishment flows from German distribution centers back to Polish assembly plants are creating closed-loop material recovery channels that reduce virgin lithium dependency. Component sourcing draws from China for battery cells, Germany for precision hydraulics, and South Korea for power electronics modules. Single-source vulnerability concentrates in lithium carbonate processing capacity. Distribution runs through port-connected warehousing clusters in the Rhine-Ruhr corridor before radiating to secondary markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The European forklift truck market sits in a powertrain-transition phase where lithium-ion chemistry displaces lead-acid configurations across high-rotation warehouse fleets. This technology substitution compresses legacy supplier margins while opening white space for battery-integrated automation bundles.
For Market Incumbents: Hedge against battery supply disruption by securing long-term offtake agreements with Polish and Hungarian cell assemblers before REACH substance restrictions tighten further. Defensive consolidation into charging infrastructure services offsets hardware margin erosion. Backward integration into battery thermal management systems represents the critical capability lever for sustaining premium positioning against Chinese cost competition.
For New Entrants and Emerging Players: Direct-to-fleet telematics platforms offer the lowest-friction entry path for software-native competitors lacking manufacturing scale. Italian automotive assembly plants present the most penetrable white space for 4-6 ton electric configurations previously served by diesel incumbents. A usage-based pricing model bundled with predictive maintenance analytics bypasses capital-intensive equipment financing barriers.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by automation conglomerates seeking warehouse control system integration. Long-term viability favors suppliers with captive battery pack assembly and software monetization infrastructure. Monitor EU AI Act risk-classification finalization as the inflection signal for autonomous navigation capital deployment timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Pack Assembly Localization | Polish and Hungarian production hubs reduce exposure to Chinese lithium processing concentration. |
| Telematics Platform Integration | French third-party logistics operators command premium pricing for real-time fleet optimization software. |
| Autonomous Navigation Certification | CE marking under EU Machinery Directive delays product launches for sensor-fusion variants. |
| Charging Infrastructure Partnership | Belgian port-connected clusters require high-voltage depot installations to maintain throughput velocity. |
| REACH Compliance Reformulation | ECHA substance restrictions force dual-sourcing strategies for hydraulic fluid chemistries. |
Research Methodology
Trade flow databases, EU regulatory filings, and OEM procurement disclosures formed the secondary backbone of this analysis. Primary interviews with fleet managers at German third-party logistics operators, maintenance directors at Dutch distribution centers, procurement leads at Italian automotive plants, and aftermarket service heads at Belgian port terminals combined with secondary validation. Bottom-up equipment placement estimates triangulated against top-down warehousing capacity expansion data.
Historical trendline analysis of lithium-ion adoption rates and lead-acid displacement patterns anchored the projection framework across the analysis window. Segmentation dimensions modeled include powertrain type, end-use industry, automation technology tier, and capacity class. CAGRs derived from equipment replacement cycle compression and electrification mandate compliance schedules. Battery energy density improvement curves and charging infrastructure deployment timelines served as industry-specific forecast inputs.
The model holds under stable EU F-Gas Regulation phase-down schedules and REACH substance restriction timelines; deviation in lithium carbonate price volatility or geopolitical disruption of Chinese cell supply would shift fleet turnover projections. Practitioners should monitor ECHA candidate list expansions and Polish battery assembly capacity buildout for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Floor Scrubber Machine Market
Material Handling Equipment
Air Classifying Mill Market
Material Handling Equipment
Global Conveyor System Market
Material Handling Equipment
Cherry Picker Crane Market
Material Handling Equipment
Hydraulic Fittings Market
Material Handling Equipment
Debris Loaders Market
Material Handling Equipment
Asia Pacific Automated Material Handling and Storage Systems Market
Material Handling Equipment
Can Racks Market
Material Handling Equipment
Forklift Work Platforms Market
Material Handling Equipment
Gas Connectors and Gas Hoses Market
Material Handling Equipment
Canada Forklift Market
Material Handling Equipment
Global Industrial Weighing Equipment Market
Material Handling Equipment
Material Handling Automation Market
Material Handling Equipment
Mining Hoses Market
Material Handling Equipment
Australia Forklift Market
Material Handling Equipment
Helical Gear Market