
 France HVAC Market | 2026-2036
France HVAC Market Size, Share, and Industry Trends Forecast 2026-2036
France HVAC Market Insights
Aftermarket service revenue is fragmenting across independent contractors and OEM-certified networks as building owners seek lifecycle cost reductions. Daikin Industries Ltd. leverages its VRV technology leadership to capture premium service contracts in the Ile-de-France corridor. Carrier Corporation anchors its position through extensive distributor relationships with French commercial contractors. Johnson Controls International PLC differentiates via integrated building automation platforms that bundle HVAC with energy management.
France HVAC encompasses climate control systems for heating, ventilation, air conditioning, and refrigeration, typically operating with refrigerants at pressures between 15 and 450 psi and designed to maintain indoor conditions across seasonal temperature ranges from -15°C to 45°C. These systems serve commercial, residential, and industrial facilities by regulating thermal comfort, air quality, and process cooling requirements. Air conditioning units command the largest installed base but face accelerated replacement pressure under refrigerant phase-down mandates. Smart HVAC technology captures disproportionate margin growth as French building codes tighten energy performance requirements. Variable refrigerant flow systems compete aggressively in the commercial retrofit segment where spatial flexibility drives specification decisions.
ANSM enforces refrigerant handling certifications that constrain technician supply and elevate service pricing throughout France. The EU F-Gas Regulation and France's national low-carbon strategy jointly mandate progressive hydrofluorocarbon reductions, reshaping equipment procurement criteria across all end-use sectors. RE2020 building standards impose stringent thermal performance thresholds that filter allowable HVAC technologies in new construction. Stakeholders must monitor refrigerant pricing volatility and technician training pipeline adequacy as the primary operational variables determining competitive positioning.
Market Dynamics
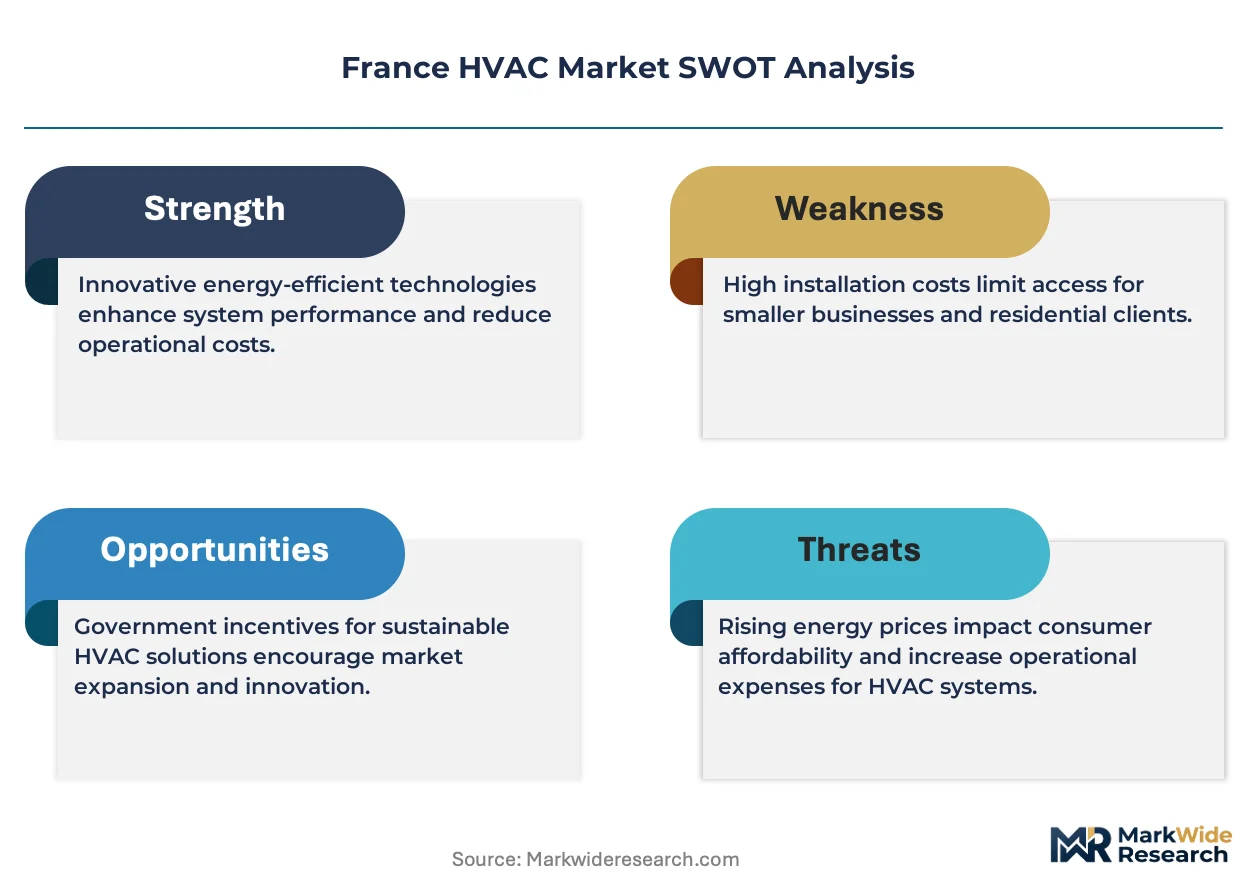
The EU F-Gas Regulation's refrigerant phase-down timeline is compressing equipment replacement cycles and elevating lifecycle cost calculations for French building operators across commercial and industrial portfolios.
Growth Catalysts
- RE2020 Building Standards:France's tightened thermal performance mandates for new construction are filtering allowable HVAC technologies toward high-efficiency heat pumps and smart climate systems.
- Greater Paris Renovation Pipeline:Large-scale retrofit programs across Ile-de-France office and residential stock are generating concentrated demand for replacement chiller and VRF installations.
- Lower-GWP Refrigerant Transitions:Hydrofluorocarbon reductions under EU policy are pulling forward capital expenditure on next-generation equipment compatible with R-32 and R-290 alternatives.
Market Restraints
- Technician Supply Constraints:ANSM certification requirements for refrigerant handling limit qualified installer availability, elevating service pricing and extending project timelines.
- Copper and Aluminum Input Volatility:Raw material price swings for heat exchanger metals compress equipment margins and complicate long-term contract pricing.
- Legacy System Inertia:Embedded R-410A and R-134a infrastructure in Lyon and Marseille commercial buildings delays full-system replacements despite regulatory pressure.
Strategic Opportunities
- Building Automation Convergence:Integration of HVAC controls with energy management platforms creates bundled service contracts for facility managers seeking unified operational dashboards.
- Smart Thermostat Retrofit Channels:Direct-to-consumer and contractor-direct distribution models for connected climate controls bypass traditional distributor markups in residential segments.
- Industrial Process Cooling:Data center and pharmaceutical manufacturing expansion around Strasbourg and Toulouse opens specialized chiller and precision cooling specifications.
Industry Challenges
- Multi-Refrigerant Inventory Complexity:Service contractors must maintain parallel parts and handling protocols for phasedown refrigerants alongside legacy stocks, elevating working capital requirements.
- Interoperability with Existing BMS:New smart HVAC installations face integration friction with proprietary building management systems common in 1990s-era French commercial properties.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France HVAC Market |
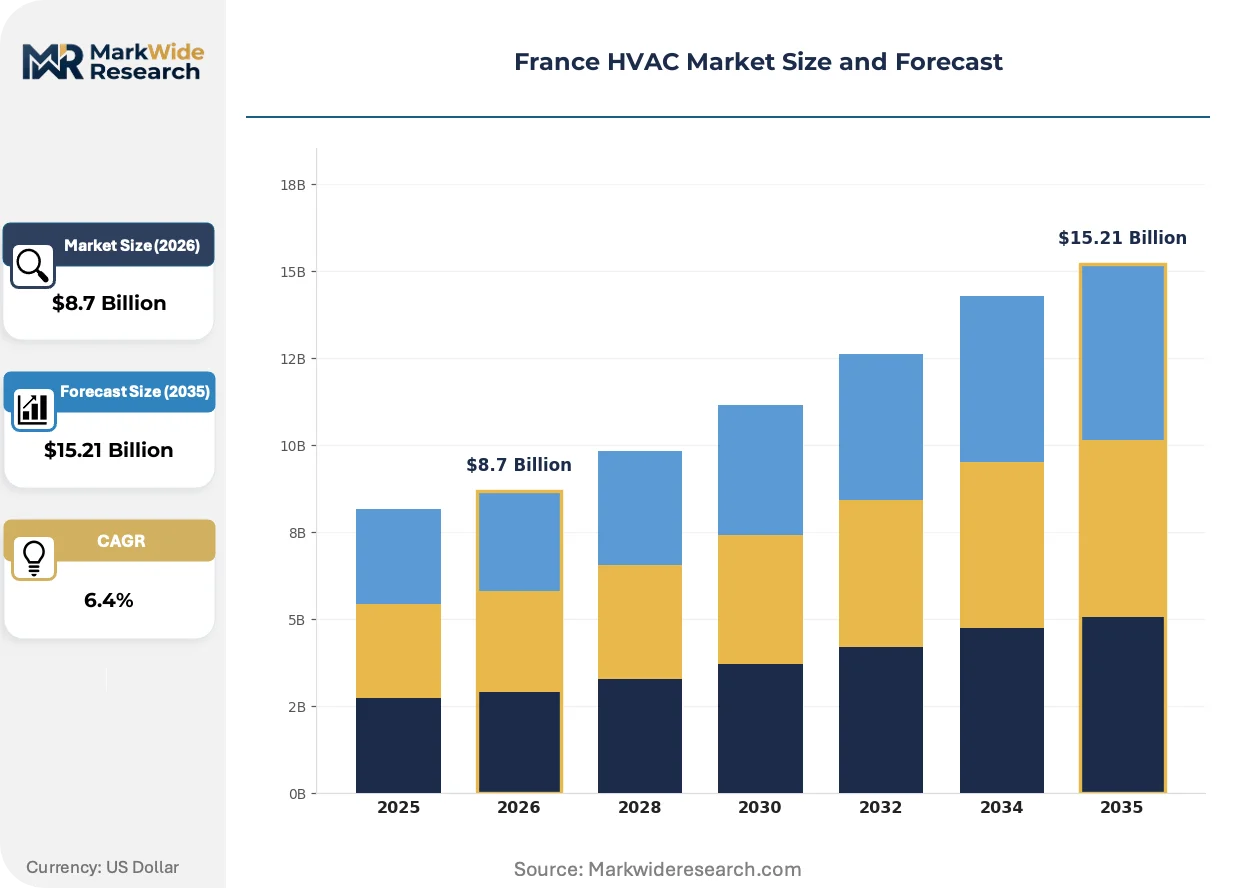
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heating Systems, Ventilation Equipment, Air Conditioning Units, Refrigeration Systems End User: Residential, Commercial, Industrial, Educational Technology: Smart HVAC, Variable Refrigerant Flow, Geothermal, Hybrid Systems Installation Type: New Construction, Retrofits, Upgrades, Replacement |
| Companies Covered | Daikin Industries Ltd., Johnson Controls International PLC, Carrier Corporation, Robert Bosch GmbH, Trane Technologies PLC, LG Electronics Inc., Honeywell International Inc., Mitsubishi Electric Corporation, Danfoss Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France HVAC Market Trends and Innovations
Refrigerant chemistry transitions, digital control architectures, and compressed buyer decision cycles are restructuring how French building operators evaluate and procure climate systems.
Variable refrigerant flow technology with zonal temperature control is rendering obsolete fixed-capacity split systems in commercial retrofit applications. Facility managers in Lyon and Marseille office complexes specify VRF for spatial flexibility during tenant reconfigurations. The technology's modular capacity matching eliminates oversizing penalties that plagued traditional chiller specifications.
France's national low-carbon strategy tightens operational carbon thresholds for public buildings, mandating heat pump priority over fossil fuel heating in municipal procurement. Public sector facility managers accelerate electrification timelines to meet 2030 decarbonization checkpoints. Hospital and university campuses in the Rhône-Alpes region front-load capital programs to capture available transition financing.
Service contract unbundling fragments aftermarket relationships as building owners disaggregate installation, maintenance, and energy optimization across specialized providers. Independent contractors capture routine maintenance while OEM-certified networks retain warranty-critical repairs. This pattern concentrates in the Ile-de-France corridor where large portfolio owners negotiate multi-site service agreements.
France HVAC Market Segmentation
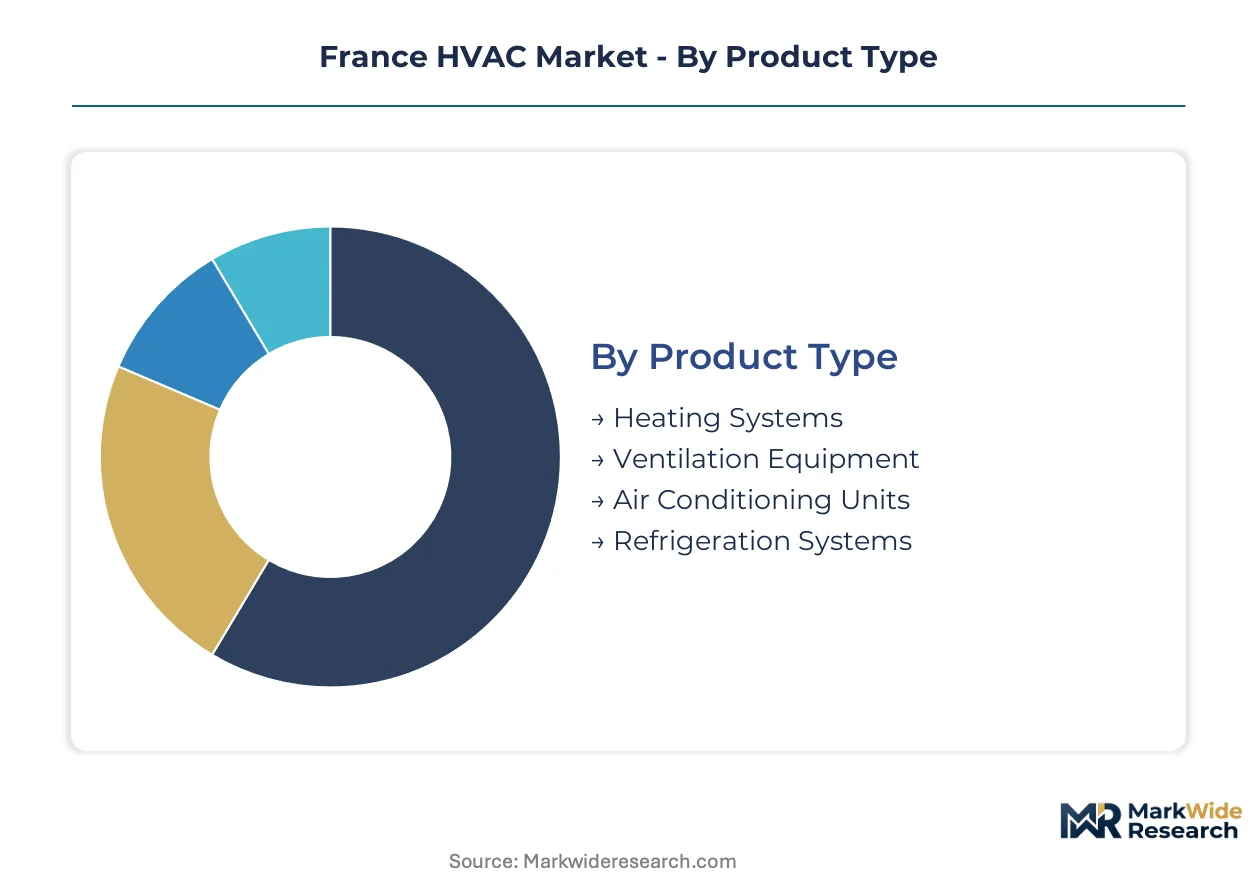
Equipment procurement patterns in the French market diverge sharply across building vintages and regulatory exposure. Segmentation reveals how RE2020 compliance, F-Gas phase-down timelines, and after-sales service intensity reshape vendor prioritization and margin capture across distinct customer clusters.
Product Type:
After-sales service intensity varies dramatically across equipment categories, with refrigeration systems demanding specialized refrigerant handling and chiller systems requiring continuous monitoring contracts.
- Air Conditioning Units:These systems dominate installed base volume across French commercial and residential portfolios. Demand concentrates in the Greater Paris region's large-scale renovation pipeline, where RE2020 energy performance thresholds accelerate replacement of fixed-capacity splits with variable-output alternatives.
- Heating Systems:Heat pump configurations are displacing fossil fuel boilers under France's national low-carbon strategy mandates. Public sector facility managers in the Rhône-Alpes region front-load capital programs to capture transition financing for municipal building electrification.
- Ventilation Equipment:Heat recovery ventilation systems integrate with airtight building envelopes under tightened thermal regulations.
- Refrigeration Systems:Industrial chillers and commercial cold chain equipment face compressed replacement cycles from hydrofluorocarbon phase-down requirements.
Air Conditioning Units holds the largest share; momentum sits with Heating Systems.
End User:
Customer procurement sophistication spans from price-sensitive residential homeowners to institutional buyers with lifecycle cost modeling capabilities.
- Commercial:Office and retail portfolio owners in Lyon and Marseille negotiate multi-site service agreements that unbundle installation, maintenance, and energy optimization. These buyers specify VRF technology for spatial flexibility during tenant reconfigurations, eliminating oversizing penalties that plagued traditional chiller specifications.
- Residential:Single-family and multi-unit building owners drive smart thermostat retrofit channels through direct-to-consumer distribution. Connected climate controls bypass traditional distributor markups as homeowners prioritize operational visibility over upfront equipment discounts.
- Industrial:Data center and pharmaceutical manufacturing expansion around Strasbourg and Toulouse opens specialized chiller specifications.
- Educational:University campuses face RE2020 compliance deadlines for new construction and major renovation.
Commercial captures the deepest service contract value; residential is expanding most quickly through smart technology penetration.
Technology:
Margin structures stratify between commodity equipment and digitally integrated platforms that bundle hardware with ongoing optimization services.
- Variable Refrigerant Flow:Zonal temperature control architectures render obsolete fixed-capacity systems in commercial retrofit applications. Facility managers specify modular capacity matching that eliminates energy waste from partial-load operation common in traditional centralized systems.
- Smart HVAC:Digital control architectures capture disproportionate margin growth as French building codes tighten energy performance requirements. Integration friction with proprietary building management systems from the 1990s-era commercial stock creates implementation delays for legacy properties.
- Geothermal:Ground-source heat pump adoption concentrates in new construction with available land area for loop field installation.
- Hybrid Systems:Dual-fuel configurations bridge electrification transitions in regions with constrained grid capacity.
Variable Refrigerant Flow holds the largest share; momentum sits with Smart HVAC.
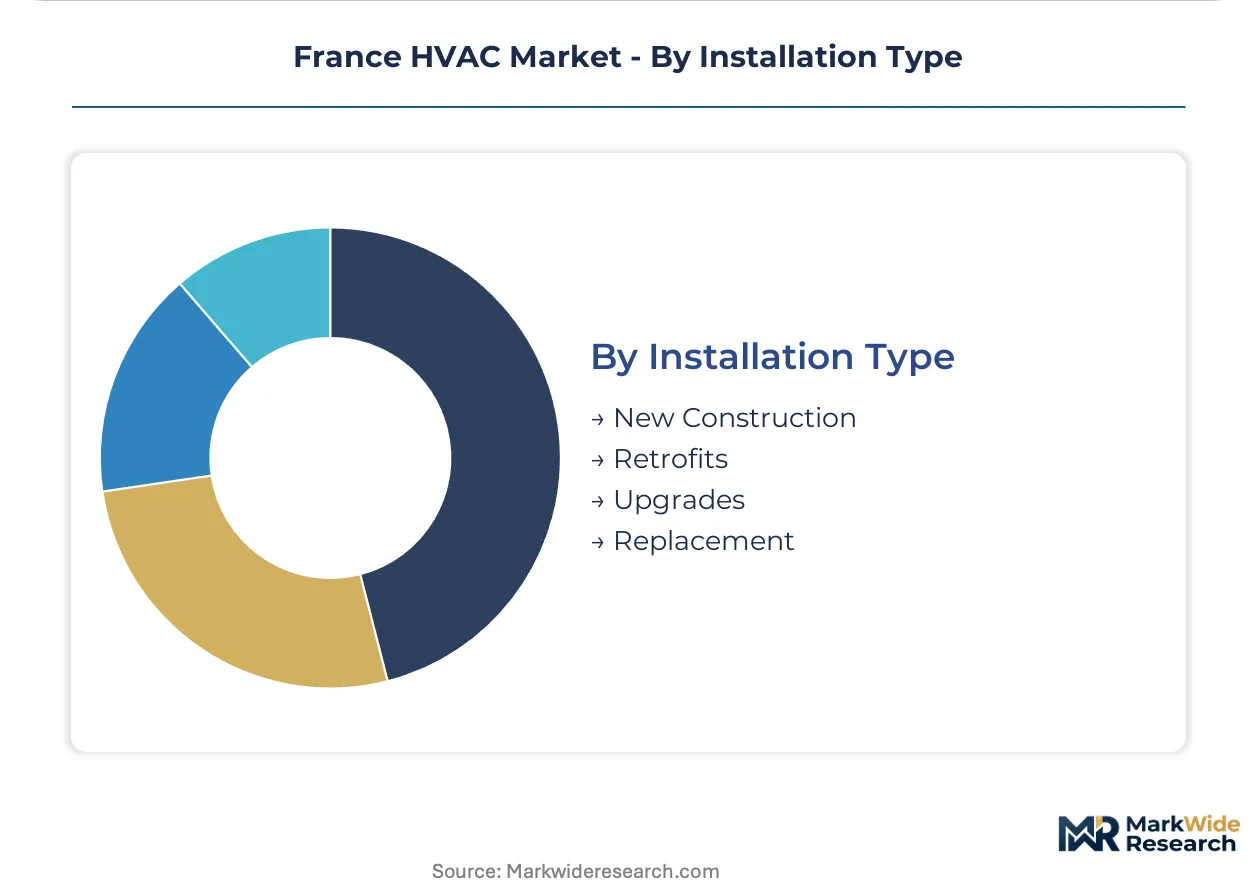
Installation Type:
Project origination channels fragment between new construction specifications controlled by general contractors and retrofit decisions driven by facility managers with operating budget authority.
- Retrofits:Aging chiller replacement cycles accelerate in Lyon and Marseille commercial buildings as EU F-Gas Regulation compresses equipment lifecycles. Building owners seek lifecycle cost reductions through independent contractor networks for routine maintenance while retaining OEM-certified relationships for warranty-critical repairs.
- New Construction:RE2020 building standards filter allowable HVAC technologies toward high-efficiency heat pumps and smart climate systems in ground-up development. General contractors face compressed bid timelines that favor standardized specifications over customized engineering.
- Replacement:Emergency failure-driven procurement prioritizes speed over optimization, constraining technology selection.
- Upgrades:Partial system enhancements target energy performance improvements without full infrastructure replacement.
Retrofits holds the largest share; momentum sits with New Construction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Facility managers in Île-de-France demonstrate the lowest price elasticity, accepting premium lifecycle cost models, while residential buyers in peripheral regions prioritize upfront equipment discounts over operational efficiency.
Île-de-France
Large-scale renovation pipelines across Paris and surrounding departments concentrate replacement demand for chillers and VRF systems. ANSM certification requirements constrain technician supply, elevating service pricing throughout the corridor. Commercial portfolio owners in La Défense and central Paris negotiate multi-site service agreements that unbundle installation from energy optimization.
Auvergne-Rhône-Alpes
Hospital and university campuses front-load capital programs to capture transition financing for municipal building electrification. France's national low-carbon strategy mandates heat pump priority over fossil fuel heating in public procurement. Lyon commercial real estate developers accelerate replacement cycles for aging chiller systems as EU F-Gas Regulation compresses equipment lifecycles.
Provence-Alpes-Côte d'Azur
Marseille commercial buildings face compressed replacement timelines despite embedded R-410A infrastructure delaying full-system overhauls. RE2020 building standards filter allowable HVAC technologies toward high-efficiency configurations in new construction. Facility managers specify VRF technology for spatial flexibility during tenant reconfigurations in Aix-en-Provence office complexes.
Hauts-de-France
Industrial process cooling demand concentrates around pharmaceutical manufacturing expansion near Lille. The EU F-Gas Regulation's hydrofluorocarbon phase-down pulls forward capital expenditure on next-generation equipment compatible with lower-GWP alternatives. Data center operators in the region specify specialized chiller configurations for precision cooling requirements.
Occitanie
Toulouse industrial zones generate specialized chiller and precision cooling specifications for aerospace and pharmaceutical manufacturing. Smart thermostat retrofit channels penetrate residential segments through contractor-direct distribution models. Ground-source heat pump adoption concentrates in new construction with available land area for loop field installation around Montpellier.
France HVAC Market Competitive Landscape
Integrated building automation providers and refrigerant-technology specialists split the market between bundled energy management platforms and equipment-centric service models. The vendor base stratifies into three tiers: multinational conglomerates with full HVAC portfolios, regional specialists in heat pump or VRF technologies, and independent service contractors capturing routine maintenance. Consolidation pressure intensifies as lifecycle cost calculations favor single-source accountability. Dominant competitive moves include strategic partnerships between equipment manufacturers and energy management software providers, plus geographic expansion through distributor network acquisitions.
Within the multinational tier, Daikin Industries Ltd., Carrier Corporation, and Johnson Controls International PLC exemplify divergent strategic positioning. Daikin anchors the refrigerant-technology specialist archetype through its VRV platform. Carrier occupies a position tied to extensive distributor relationships with French commercial contractors. Johnson Controls represents the building automation convergence play, bundling HVAC with integrated energy management platforms. These three entities collectively illustrate how vendor selection criteria have shifted from equipment specifications toward lifecycle service accountability under tightening regulatory compliance requirements.
| Leading Market Players |
|---|
| Daikin Industries Ltd. |
| Johnson Controls International PLC |
| Carrier Corporation |
| Robert Bosch GmbH |
| Trane Technologies PLC |
| LG Electronics Inc. |
| Honeywell International Inc. |
| Mitsubishi Electric Corporation |
| Danfoss Inc. |
| Others |
Pricing and Supply Chain Analysis
Copper and aluminum price volatility for heat exchanger metals determines both equipment margin compression and distributor inventory strategies across French HVAC procurement channels. This raw material exposure widens pricing spreads between premium OEM-certified networks and independent contractor channels while forcing working capital reallocation toward speculative metal hedging.
Pricing Analysis
After-sales service revenue tiers—spanning routine maintenance contracts, warranty-critical repairs, and energy optimization subscriptions—drive lifetime value capture for French HVAC vendors. Three-tier pricing structure across premium OEM-certified, standard distributor-aligned, and economy independent contractor levels reflects ANSM certification requirements and service bundling intensity. Cost compression in the economy tier is intensifying because independent contractors bypass distributor markups through direct-to-consumer smart thermostat channels. Residential buyers in peripheral regions exhibit highest price sensitivity, while commercial portfolio managers in Île-de-France accept premium lifecycle cost models.
Supply Chain Analysis
Extended payment terms from equipment manufacturers to certified distributor networks anchor working capital flows across French HVAC procurement channels. Manufacturing concentration in Germany, Italy, and China for compressors, heat exchangers, and electronic control modules creates import dependency for French distributors. Copper coil and aluminum fin stock sourcing rests on commodity exchange pricing that amplifies margin volatility during construction seasonality. Single-source vulnerability concentrates in specialized refrigerant handling equipment where ANSM certification limits qualified supplier pools. Distribution runs through regional distributor networks that maintain parallel inventory for legacy R-410A and transition R-32 refrigerant systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service contract unbundling fragments aftermarket relationships across installation, maintenance, and energy optimization specialists, creating white-space niches for focused entrants. Building owners disaggregating lifecycle accountability generates demand for pure-play service providers.
For Market Incumbents: Harden refrigerant-technology leadership through captive technician training pipelines that constrain competitor access to ANSM-certified labor pools. Deepen backward integration into heat exchanger manufacturing to offset copper and aluminum price volatility compressing equipment margins. Consolidate distributor relationships in the Île-de-France corridor where multi-site service agreements concentrate premium contract value. For New Entrants and Emerging Players: Occitanie's residential smart thermostat retrofit channels offer underpenetrated entry points through contractor-direct distribution bypassing established distributor markups. Industrial process cooling specifications around Toulouse pharmaceutical manufacturing present specialized chiller white space with lower incumbent saturation. Target municipal building electrification programs in Auvergne-Rhône-Alpes where transition financing accelerates heat pump procurement timelines. For Investors and Strategic Acquirers: The market sits at a regulatory compression phase that favors building automation convergence plays bundling HVAC with energy management platforms. Long-term viability over the next decade hinges on software-integrated service models capturing recurring revenue from RE2020 compliance mandates. Acquisition targets should demonstrate refrigerant transition readiness and established ANSM-certified technician networks. Monitor F-Gas Regulation enforcement intensity as the inflection signal determining replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Technician Certification Pipeline Investment | ANSM-qualified labor scarcity constrains competitor expansion across French service territories. |
| Refrigerant Transition Inventory Positioning | Parallel R-32 and R-410A stocks capture replacement cycle compression under EU F-Gas mandates. |
| Building Automation Platform Integration | Johnson Controls and Honeywell demonstrate bundled energy-HVAC contracts commanding premium pricing. |
| Regional Distributor Network Acquisition | Île-de-France corridor relationships gate access to multi-site commercial portfolio agreements. |
| Smart Thermostat Direct Distribution Channel | Residential bypass models in Occitanie and Provence-Alpes-Côte d'Azur circumvent traditional markups. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with facility managers at Lyon and Marseille commercial portfolios, ANSM-certified refrigeration technicians, HVAC distributor procurement leads, and building automation integration specialists. Secondary validation drew from EU F-Gas Regulation implementation documents, RE2020 technical standards, French customs trade data for HVAC equipment imports, and SEC filings of multinational equipment manufacturers. Bottom-up equipment shipment analysis and top-down construction spend triangulation anchored market sizing across the projection horizon.
Calibration against historical replacement cycle data and regulatory phase-down timelines shaped the analytical framework. Segmentation modeling incorporated product type, end-user category, technology tier, and installation channel dimensions alongside refrigerant chemistry transition status. CAGRs were derived from equipment lifecycle compression rates and renovation pipeline visibility across French regional construction permits. Forecast inputs included copper and aluminum price trajectory assumptions and ANSM certification pipeline expansion rates.
Practitioners should monitor refrigerant pricing volatility and technician training pipeline adequacy for early signals of competitive positioning shifts. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and construction activity levels. Macroeconomic deviation, F-Gas Regulation amendment, or technological disruption in heat pump efficiency would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Strip Warmer Market
HVAC Equipment
Screw Compressor Market
HVAC Equipment
Global Radiant Floor Heating Market
HVAC Equipment
Refrigeration and Air Conditioning Compressors Market
HVAC Equipment
Equipment Fan Filter Unit (EFU) Market
HVAC Equipment
Industrial Air Heaters Market
HVAC Equipment
Heat Moisture Exchanger Market
HVAC Equipment
North America Commercial Heating, Ventilation, and Air Conditioning (HVAC) Equipment Market
HVAC Equipment
Industrial Air Blower Market
HVAC Equipment
United Kingdom Heating Equipment Market
HVAC Equipment
Germany Commercial HVAC Market
HVAC Equipment
HVAC Fan and Evaporator Coil Market
HVAC Equipment
Centrifugal Fan Wheels Market
HVAC Equipment
Middle East and Africa Commercial HVAC Market
HVAC Equipment
Global HVAC Linesets Market
HVAC Equipment
Global Smart Vent Market