
 Dry Bulk Handling System Market | 2026-2036
Dry Bulk Handling System Market Size, Share, and Industry Trends Forecast 2026-2036
Dry Bulk Handling System Market Insights
Australia's Pilbara mining corridor is rewriting capital deployment patterns for heavy bulk infrastructure. Buhler leverages its Swiss-engineered process technology to dominate food-grade pneumatic conveying installations across Southeast Asian grain terminals. TAKRAF sustains its position in ultra-class apron feeder systems through captive supply of engineered drive components. Bruks Siwertell competes aggressively in ship-unloading niche applications with enclosed screw-type designs that minimize dust emissions.
Dry bulk handling systems encompass mechanical and pneumatic equipment engineered to transport, store, load, and unload particulate solids with throughput capacities ranging from hundreds to thousands of tonnes per hour. These systems integrate belt conveyors, screw mechanisms, pneumatic pipelines, and bucket elevators to move materials such as ores, grains, cement, and coal across industrial facilities and logistics nodes. Belt conveyors anchor the product mix in high-volume mining corridors where single-flight distances exceed several kilometers. Smart handling solutions represent the fastest-expanding technology segment as operators integrate sensor networks and predictive maintenance algorithms to reduce unplanned downtime. Pneumatic conveyors occupy specialized margin pools in food processing and pharmaceutical-grade applications where contamination control dictates equipment selection.
The US Mine Safety and Health Administration enforces dust exposure limits that directly shape enclosure and ventilation specifications for surface and underground bulk transfer points. China's Ministry of Ecology and Environment implements emission standards that accelerate replacement of open belt systems with covered conveyors and dust-suppression-equipped loading stations. The EU Machinery Directive mandates CE conformity for automated bulk handling installations entering European ports and processing facilities. Stakeholders must monitor how carbon border adjustments and green procurement criteria reshape equipment specification priorities across import-dependent economies.
Market Dynamics
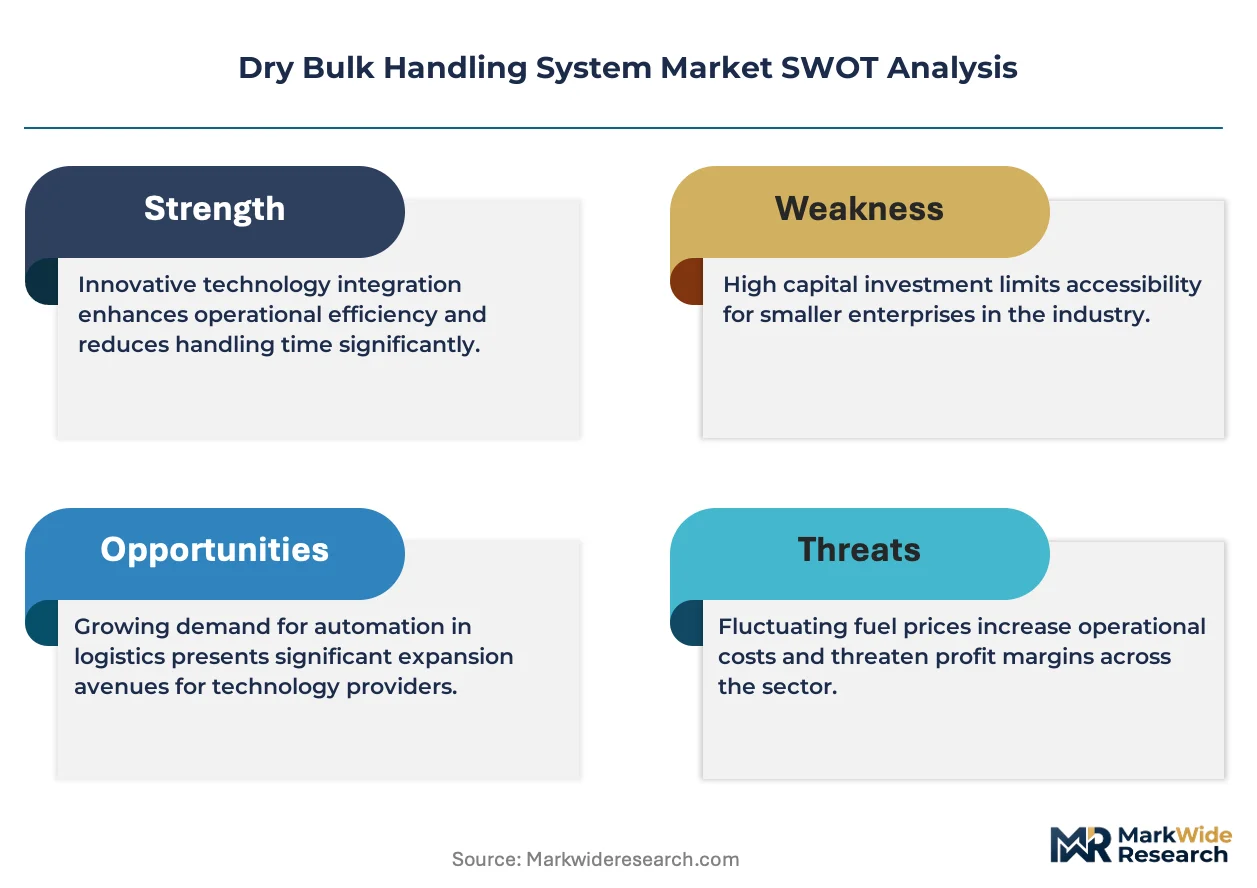
Automation retrofit cycles in established mining corridors are compressing replacement timelines for mechanical conveying equipment, while pneumatic system demand pivots toward food-grade and pharmaceutical specifications.
Growth Catalysts
- EU F-Gas Regulation:Phasedown of hydrofluorocarbon refrigerants in pneumatic compressors is accelerating equipment turnover toward low-GWP alternatives in European grain terminals and cement plants.
- Australia's Pilbara corridor:Rio Tinto and BHP are expanding autonomous haulage integration with fixed conveying infrastructure, creating pull for smart sensor networks and predictive maintenance platforms.
- China's coastal port modernization:MEE emission standards for bulk cargo handling are mandating enclosed ship unloaders and dust-suppression systems at Qingdao, Ningbo-Zhoushan, and Tangshan port clusters.
Market Restraints
- Specialized alloy supply:Austenitic manganese steel for high-wear apron feeder components concentrates among Nordic and German foundries, exposing buyers to lead time volatility.
- Compressed air energy intensity:Pneumatic conveying systems consume 3-7x more electricity per tonne-kilometer than mechanical alternatives, constraining adoption in markets with industrial electricity price spikes.
- US MSHA dust exposure limits:Underground coal transfer point enclosures must meet 1.5 mg/m³ respirable silica standards, adding engineering cost and certification timeline friction.
Strategic Opportunities
- India's eastern mineral belt:Odisha and Jharkhand iron ore expansion lacks integrated rail-to-port conveying, creating greenfield demand for overland systems exceeding 15km single-flight distances.
- CE marking convergence:EU Machinery Directive harmonization with ISO 5048 for bulk conveyor safety is simplifying cross-border equipment certification for modular system suppliers.
- Digital twin integration:Physics-based simulation of material flow dynamics is converging with IoT vibration monitoring to enable virtual commissioning before physical installation.
Industry Challenges
- Mechatronics talent scarcity:Integration of mechanical conveying with PLC programming and edge computing requires hybrid skill sets that mining maintenance departments struggle to recruit.
- Legacy SCADA interoperability:Brownfield sites running 1990s-era control architectures face protocol translation complexity when retrofitting wireless sensor networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dry Bulk Handling System Market |
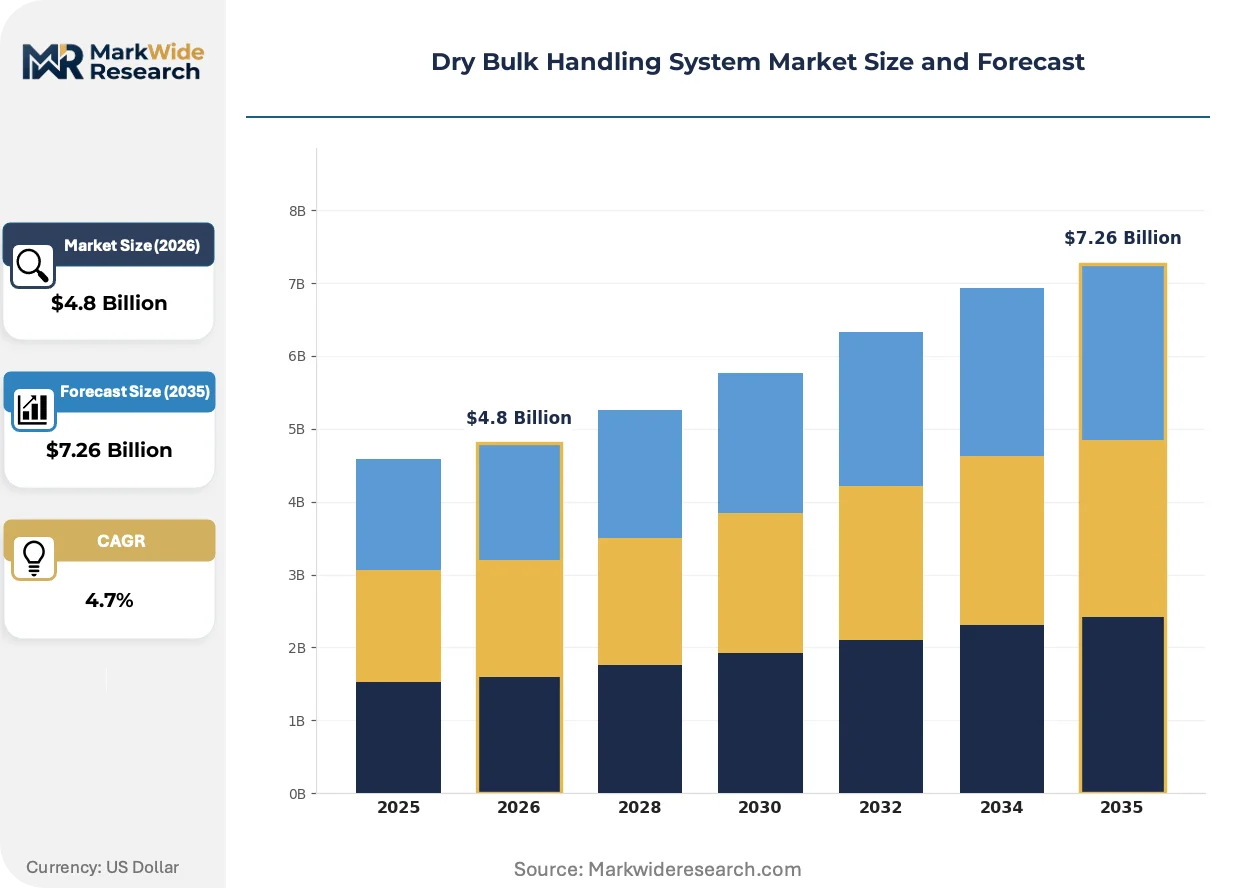
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.26 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Belt Conveyors, Screw Conveyors, Pneumatic Conveyors, Bucket Elevators End User: Mining, Agriculture, Construction, Food Processing Technology: Automated Systems, Semi-Automated Systems, Manual Systems, Smart Handling Solutions Application: Material Transport, Storage Solutions, Loading Operations, Unloading Operations |
| Companies Covered | Buhler, TAKRAF, Metso Outotec, Bruks Siwertell, Beumer Group, Thyssenkrupp, VIGAN Engineering, Bedeschi, FLSmidth & Co. A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dry Bulk Handling System Market Trends and Innovations
Material flow intelligence is displacing static capacity planning as the dominant value driver, with operators prioritizing real-time throughput optimization over nameplate equipment specifications.
Continuous weighing instrumentation embedded in belt conveyor idlers is collapsing the distinction between transport and measurement functions. Iron ore producers in Western Australia are deploying these load-cell arrays at 50-meter intervals to eliminate separate weighbridge infrastructure. This convergence is compressing capital allocation toward integrated sensor-conveyor packages rather than standalone components.
China's MEE is tightening particulate emission limits for coal handling facilities in the Yangtze River Economic Belt. Covered conveyor galleries with negative-pressure dust collection are becoming mandatory for new port investments. Cement producers in Jiangsu and Zhejiang are responding with enclosed bucket elevator retrofits that exceed baseline compliance.
Lifecycle service contracting is displacing transactional spare parts purchasing in Southeast Asian grain terminals. Cargill and Wilmar facilities in Vietnam and Indonesia are bundling 10-year maintenance agreements with initial equipment procurement. This shift compresses vendor selection criteria toward service network density rather than upfront capital cost.
Dry Bulk Handling System Market Segmentation
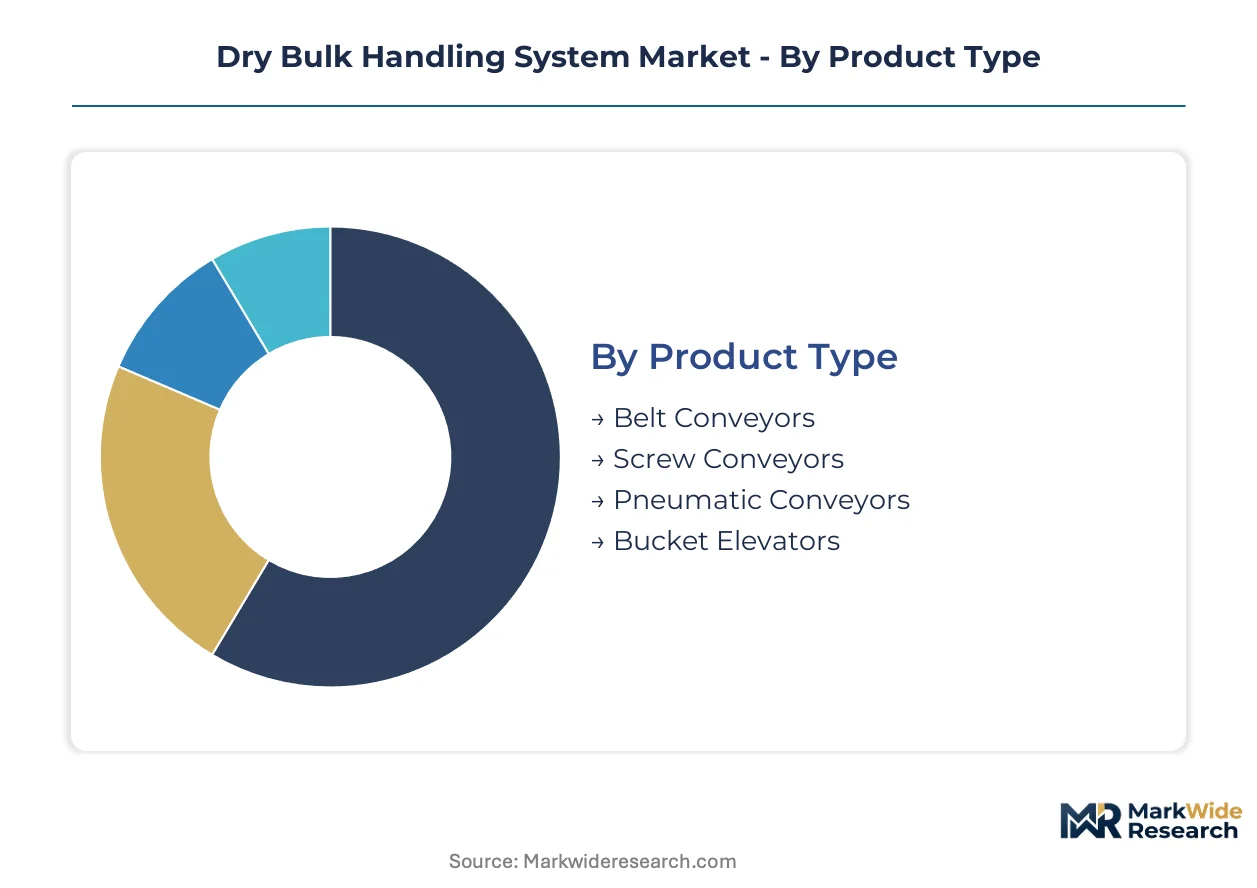
Equipment selection in dry bulk handling hinges on throughput requirements, material characteristics, and regulatory constraints. Segmentation reveals how capital cycles and replacement timelines vary dramatically across product categories and end-use applications.
Product Type:
Replacement cycles diverge sharply: mechanical systems endure 15-25 years in mining corridors while pneumatic compressors turn over every 8-12 years under F-Gas phasedown pressure.
- Belt Conveyors:Steel-cord and fabric-reinforced designs handle single-flight distances exceeding 10km in Pilbara iron ore operations. Australian mining corridors drive specification toward 6,000 tonnes per hour capacity ratings with modular idler frames for rapid maintenance access.
- Pneumatic Conveyors:Lean-phase and dense-phase systems transport food-grade powders through sealed pipelines under negative pressure. European grain terminals accelerate replacement schedules to comply with EU F-Gas refrigerant phasedown mandates for compressor units.
- Screw Conveyors:Enclosed helical mechanisms move cohesive materials like cement and fly ash at angles up to 45 degrees.
- Bucket Elevators:Centrifugal and continuous-chain designs lift abrasive ores and fragile grains through vertical shafts exceeding 50 meters.
Belt conveyors anchor the volume base while pneumatic systems gain share at the steepest rate.
End User:
Capital intensity and automation readiness separate sectors: mining deploys $50-200 million integrated systems while food processing prioritizes sanitary design over throughput scale.
- Mining:Surface and underground operations demand abrasion-resistant components for iron ore, copper concentrate, and coal transport. Australia's autonomous haulage integration creates pull for sensor networks and predictive maintenance platforms on fixed conveying infrastructure.
- Agriculture:Grain terminals and oilseed processing facilities require gentle handling to preserve commodity value. Southeast Asian port modernization in Vietnam and Indonesia drives enclosed ship unloader specifications with dust suppression systems.
- Construction:Cement plants and aggregate distribution networks utilize high-incline conveyors and covered galleries.
- Food Processing:Dairy powders, flour, and sugar installations mandate stainless steel contact surfaces and CIP washdown capability.
Mining anchors the volume base while food processing gains share at the steepest rate.
Technology:
Control architecture sophistication determines margin structure: manual installations compete on steel tonnage while smart systems command software and service premiums.
- Smart Handling Solutions:IoT-enabled platforms integrate continuous weighing, vibration monitoring, and digital twin simulation for virtual commissioning. Western Australian iron ore producers deploy load-cell arrays at 50-meter intervals to eliminate separate weighbridge infrastructure.
- Automated Systems:PLC-controlled material flow with minimal operator intervention dominates high-volume corridors. China's coastal ports mandate automated ship unloaders with enclosed dust collection at Qingdao and Ningbo-Zhoushan.
- Semi-Automated Systems:Operator-supervised control with localized sensor feedback serves mid-scale grain terminals.
- Manual Systems:Basic electromechanical drives with local pushbutton stations persist in developing market retrofits.
Automated systems anchor the volume base while smart handling solutions gain share at the steepest rate.
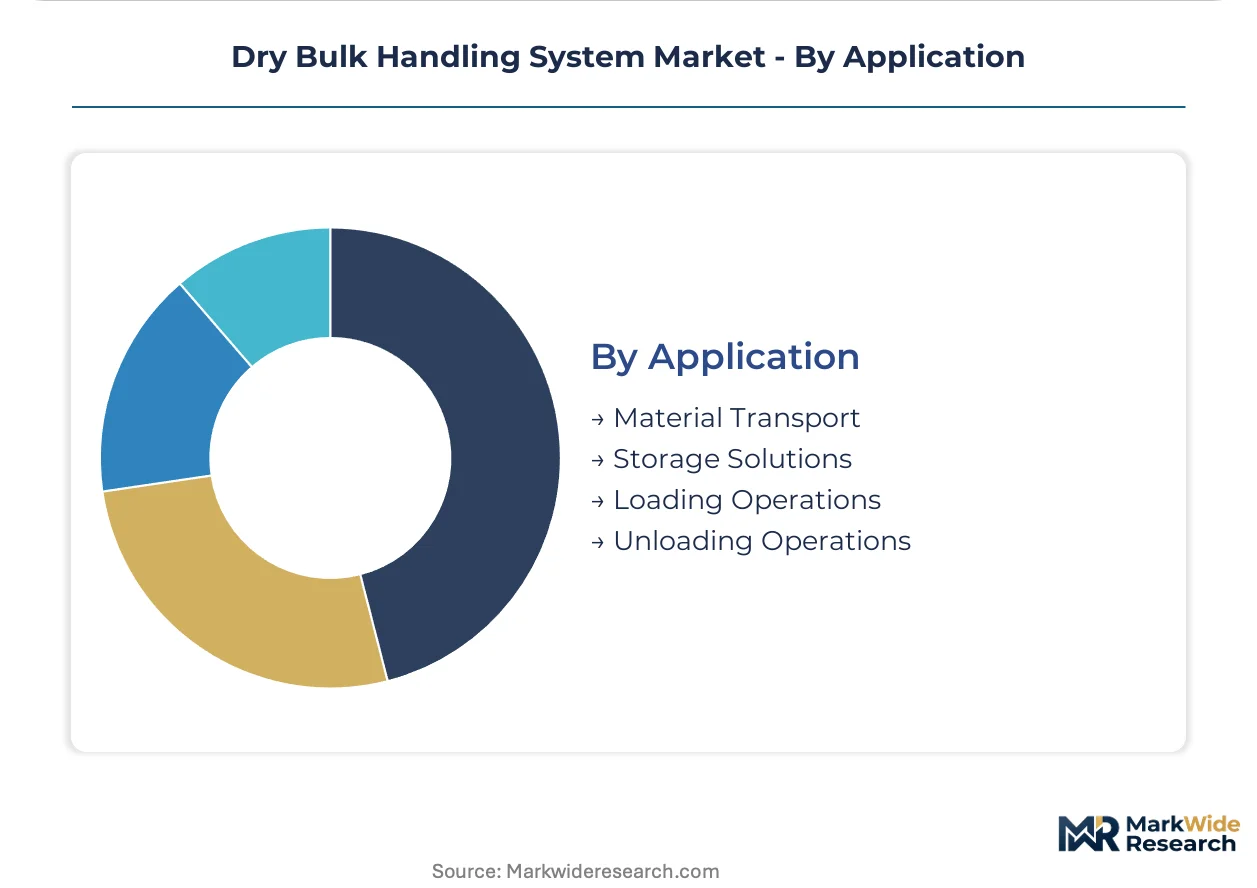
Application:
Functional specialization shapes equipment mix: continuous transport commands longest asset lives while intermittent loading operations concentrate wear and drive replacement demand.
- Material Transport:Overland and in-plant conveying systems constitute the core capital deployment in mining and port infrastructure. India's eastern mineral belt in Odisha and Jharkhand creates greenfield demand for single-flight systems exceeding 15km.
- Loading Operations:Rail car and vessel loading spouts with telescopic chutes and dust suppression serve high-frequency dispatch points. China's MEE emission standards mandate covered galleries and negative-pressure collection at Yangtze River coal terminals.
- Storage Solutions:Silo reclaim systems and stockpile stacking equipment manage buffer inventory between transport modes.
- Unloading Operations:Ship unloaders and rail car dumpers handle inbound material reception with high intermittent duty cycles.
Material transport anchors the volume base while loading operations gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MEE emission standards anchor demand concentration in China, where coastal port modernization and mining corridor automation reshape equipment procurement across three continents. Regulatory tightening in Europe and Australia accelerates replacement cycles for pneumatic and mechanical systems respectively.
China
Qingdao, Ningbo-Zhoushan, and Tangshan port clusters drive enclosed ship unloader demand under MEE particulate mandates. The Yangtze River Economic Belt requires negative-pressure dust collection for coal terminals. Jiangsu and Zhejiang cement producers retrofit enclosed bucket elevators to exceed baseline compliance.
Australia
Rio Tinto and BHP expand autonomous haulage integration with fixed conveying infrastructure in the Pilbara mining corridor. TGA-equivalent mining safety protocols govern dust exposure at surface transfer points. Western Australian iron ore producers deploy continuous weighing instrumentation at 50-meter intervals to eliminate separate weighbridge infrastructure.
Germany
EU F-Gas Regulation phases down hydrofluorocarbon refrigerants in pneumatic compressors at grain terminals and cement plants. CE marking convergence with ISO 5048 simplifies cross-border certification for modular system suppliers. Industrial clusters in North Rhine-Westphalia concentrate engineering expertise for high-wear apron feeder components.
India
Odisha and Jharkhand iron ore expansion lacks integrated rail-to-port conveying, creating greenfield demand for overland systems exceeding 15km single-flight distances. CEA power sector directives influence energy efficiency specifications for bulk handling installations. Paradip and Visakhapatnam port modernization programs prioritize dust-suppression-equipped loading stations.
United States
MSHA enforces 1.5 mg/m³ respirable silica standards for underground coal transfer point enclosures. Appalachian and Powder River Basin mining operations face compressed replacement timelines for mechanical conveying equipment. Gulf Coast grain terminals automate ship loading operations to reduce labor exposure at high-frequency dispatch points.
Dry Bulk Handling System Market Competitive Landscape
Capability concentration sits with engineering-intensive specialists; scale advantage sits with diversified industrial conglomerates. The market structures around three tiers: premium process technology providers, mid-scale modular system fabricators, and regional maintenance-service integrators. Dominant competitive moves include backward integration into engineered drive components and lifecycle service contracting that bundles decade-long maintenance with initial procurement.
Within the premium process technology tier, Buhler and TAKRAF exemplify divergent specialization paths. Buhler leverages Swiss-engineered process technology positioning in food-grade pneumatic conveying. TAKRAF occupies a position in ultra-class apron feeder systems through captive supply of engineered drive components. Bruks Siwertell anchors the enclosed screw-type ship unloader niche where dust emission minimization dictates specification.
| Leading Market Players |
|---|
| Buhler |
| TAKRAF |
| Metso Outotec |
| Bruks Siwertell |
| Beumer Group |
| Thyssenkrupp |
| VIGAN Engineering |
| Bedeschi |
| FLSmidth & Co. A/S |
| Others |
Pricing and Supply Chain Analysis
Nordic and German foundry concentration for austenitic manganese steel in high-wear apron feeder components anchors margin capture in the premium equipment tier, compressing pricing power for mid-scale fabricators dependent on spot alloy procurement. This upstream chokepoint forces downstream buyers into long-term offtake agreements or captive foundry investments to stabilize input costs.
Pricing Analysis
European pneumatic compressor replacement premiums under EU F-Gas Regulation run 15-25% above baseline mechanical conveying equipment in comparable throughput classes. Three-tier pricing structure across premium CE-marked smart systems, standard automated installations, and economy manual configurations separates buyers by certification burden and service bundling intensity. Cost compression in the economy tier is intensifying because Indian and Southeast Asian grain terminal procurement prioritizes upfront capital minimization over lifecycle service contracts. Mining operators in Australia's Pilbara corridor exhibit lowest price sensitivity due to unplanned downtime costs exceeding equipment purchase multiples.
Supply Chain Analysis
Tariff exposure between China and Australia dominates supply chain risk planning for steel-cord conveyor belt manufacturers serving Pacific bulk commodity corridors. Component sourcing draws from Germany for engineered drive systems, Sweden for wear-resistant alloys, and China for fabricated structural steel and electric motors. Single-source vulnerability concentrates in ultra-class apron feeder gearboxes where TAKRAF's captive production limits alternative supplier qualification timelines. Distribution runs through OEM-direct project contracting for mining integrated systems and regional distributor networks for aftermarket spare parts in agricultural and construction applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dry bulk handling incumbents face substitution pressure from modular containerized logistics and slurry pipeline alternatives in iron ore corridors, requiring defensive capability investments that extend beyond equipment sales into integrated material flow services.
For Market Incumbents: Pre-empt slurry pipeline displacement in Pilbara and Brazil iron ore routes by bundling predictive maintenance platforms with conveying infrastructure, locking in lifecycle revenue streams that commodity logistics alternatives cannot replicate. Deepen backward integration into sensor hardware and edge computing modules to capture software-margin pools currently leaking to industrial IoT specialists. CE marking convergence with ISO 5048 creates regulatory moat opportunities for early certifiers against late-adapting regional competitors.
For New Entrants and Emerging Players: Establish a beachhead in India's eastern mineral belt overland conveyor gap, where Odisha and Jharkhand iron ore expansion lacks integrated rail-to-port infrastructure and incumbent service networks remain thin. Target food-grade pneumatic conveying in Vietnam and Indonesia grain terminals, where lifecycle service contracting is displacing transactional procurement and creates recurring revenue attachment points for new vendors. Lead with digital twin commissioning capabilities that reduce project risk for first-time automation adopters in developing market port modernization.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mid-scale modular fabricators in European grain handling and North American mining aftermarket services, where sponsor exit timelines converge with replacement cycle acceleration. Long-term viability hinges on software and service revenue mix expansion rather than steel-tonnage growth. Monitor F-Gas Regulation enforcement intensity as inflection signal for pneumatic system replacement demand velocity and compressor technology obsolescence risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Wear Components | Captive supply of austenitic manganese steel castings insulates TAKRAF and Metso Outotec from Nordic foundry lead time volatility. |
| Lifecycle Service Contracting | Ten-year maintenance bundling at Cargill and Wilmar Southeast Asian terminals compresses vendor selection toward network density over upfront cost. |
| Digital Twin Integration | Physics-based simulation with IoT vibration monitoring enables Beumer Group virtual commissioning that reduces project risk for brownfield retrofits. |
| Smart Sensor Network Deployment | Continuous weighing instrumentation at 50-meter intervals eliminates separate weighbridge infrastructure for Western Australian iron ore producers. |
| CE Marking Convergence Investment | Early ISO 5048 alignment creates regulatory moat for Buhler and Bruks Siwertell against late-adapting regional competitors in European port procurement. |
Research Methodology
A spread of perspectives from maintenance directors at Pilbara mining operations, port engineers at China's Qingdao and Ningbo-Zhoushan clusters, grain terminal procurement leads in Vietnam and Indonesia, and aftermarket service heads at European OEMs converged on the working assumptions for automation retrofit timelines and pneumatic replacement cycles. Primary fieldwork combined with secondary validation from SEC filings of listed industrial conglomerates, MEE emission standard enforcement records, EU F-Gas Regulation implementation reports, and customs trade data for bulk handling equipment imports. Bottom-up equipment unit economics and top-down market sizing triangulated on segment-level revenue estimates.
Demand-supply balance framing anchored the analytical framework across the projection horizon, modeling belt conveyor, pneumatic, screw, and bucket elevator product categories against mining, agriculture, construction, and food processing end-use demand. Technology segmentation incorporated smart handling solutions, automated, semi-automated, and manual control architectures. CAGRs derived from replacement cycle compression in Australia's autonomous haulage integration and China's MEE-mandated port modernization, cross-referenced against pneumatic compressor turnover schedules under refrigerant phasedown pressure.
Sensitivities concentrate around EU F-Gas Regulation enforcement acceleration, China MEE emission standard tightening velocity, and Australian mining automation capex cycle amplitude. Forecasts reflect documented assumptions on regulatory implementation timelines and commodity price-linked capital deployment patterns. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Loader Crane Market
Material Handling Equipment
Cut-To-Length Line Systems Market
Material Handling Equipment
Hooklifts Market
Material Handling Equipment
Circular Stacker and Reclaimer Market
Material Handling Equipment
Wagon Tipplers Market
Material Handling Equipment
Global Screw Conveyors Market
Material Handling Equipment
Hydraulic Seals Market
Material Handling Equipment
North America Utility Locator Market
Material Handling Equipment
Resistance Welding Products Market
Material Handling Equipment
Modular Conveyor System Market
Material Handling Equipment
Belt Scales Market
Material Handling Equipment
Crane Mats Market
Material Handling Equipment
Industrial Carts Market
Material Handling Equipment
High Pressure Grease Hose Market
Material Handling Equipment
Hydraulics Components Market
Material Handling Equipment
Middle East and Africa Conveyors Market