
 Conveying Equipment Market | 2026-2036
Conveying Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Conveying Equipment Market Analysis
Buyer consolidation among third-party logistics providers is repositioning procurement leverage toward fleet-standardization contracts. Daifuku Co., Ltd. leverages its vertical integration into control software and automated storage to sustain premium positioning in airport baggage and factory automation. Fives Group anchors its competitiveness through specialized high-temperature and bulk-handling designs for cement and mining clients. BEUMER Group differentiates via deep domain expertise in curved belt systems and overland conveying for extractive industries.
Conveying equipment comprises mechanical systems engineered to transport bulk materials or discrete items across fixed paths, typically employing fabricated steel frames, polymer or metal belts, precision rollers, and variable-frequency electric drives rated for continuous-duty cycles. Belt conveyors dominate installed base volumes due to their adaptability across horizontal and inclined routes, while automation-enabled electric drive segments capture expanding margin pools as end users prioritize predictive maintenance integration. Roller conveyors remain mature in parcel distribution, though modular portable installations are gaining traction in seasonal warehousing operations where reconfiguration speed outweighs fixed-capital efficiency.
The EU Machinery Directive and CE marking requirements shape product design and market access for equipment sold across European member states, while OSHA standards in the United States govern worker safeguarding and emergency stop protocols. China's GB standards and MIIT energy efficiency directives are tightening motor and drive system specifications for domestic and export-bound manufacturers. Stakeholders must monitor how diverging regional safety and efficiency codes affect platform development costs and cross-border certification timelines.
Market Dynamics
Automation retrofits in existing warehousing infrastructure are compressing replacement cycles as facility operators prioritize throughput density over equipment longevity. Labor availability constraints in logistics hubs accelerate capital redeployment toward continuous-flow systems.
Growth Catalysts
- EU Machinery Directive compliance mandates:CE marking requirements for safety-integrated control systems compel facility operators across Germany, France, and Italy to upgrade legacy mechanical interlocks with programmable safety relays.
- E-commerce fulfillment center expansion:Parcel sortation hubs in the Netherlands and Poland deploy high-speed cross-belt sorters to handle peak-season volume spikes exceeding baseline capacity by factors of four.
- Steel roller precision manufacturing:Tolerance improvements in CNC-machined bearing housings reduce belt drift incidents, cutting unplanned downtime in cement clinker transport applications.
Market Restraints
- Neodymium magnet supply concentration:Permanent magnet motors for high-efficiency drives depend on rare earth processing concentrated in China, exposing European manufacturers to export quota volatility.
- Structural steel price cyclicality:Fabricated frame costs fluctuate with scrap metal and energy input indices, compressing margin visibility on fixed-price installation contracts.
- Overland conveying substitution:Rail-truck intermodal investments in Australian and Brazilian mining corridors displace some long-distance belt systems for bulk ore transport.
Strategic Opportunities
- India warehouse automation penetration:Third-party logistics operators in Maharashtra and Karnataka states lack automated material handling density comparable to European benchmarks, creating greenfield deployment potential.
- EU Green Deal energy efficiency incentives:Motor upgrade subsidies under national recovery plans accelerate variable-frequency drive retrofits in food processing and automotive assembly plants.
- Predictive maintenance convergence:Vibration sensor arrays fused with edge computing platforms enable condition-based roller replacement, shifting revenue streams from equipment sales to performance-guaranteed service agreements.
Industry Challenges
- Mechatronics technician scarcity:Control system commissioning requires cross-trained personnel fluent in both mechanical alignment and PLC programming, a skill combination undersupplied in vocational pipelines.
- Legacy analog integration friction:Digital retrofit kits encounter signal incompatibility with 1990s-era relay logic in brownfield cement and steel installations, extending commissioning timelines.
- Multi-jurisdiction certification lag:Simultaneous OSHA, CE, and GB standard compliance testing stretches product launch schedules for modular conveyor platforms targeting export markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Conveying Equipment Market |
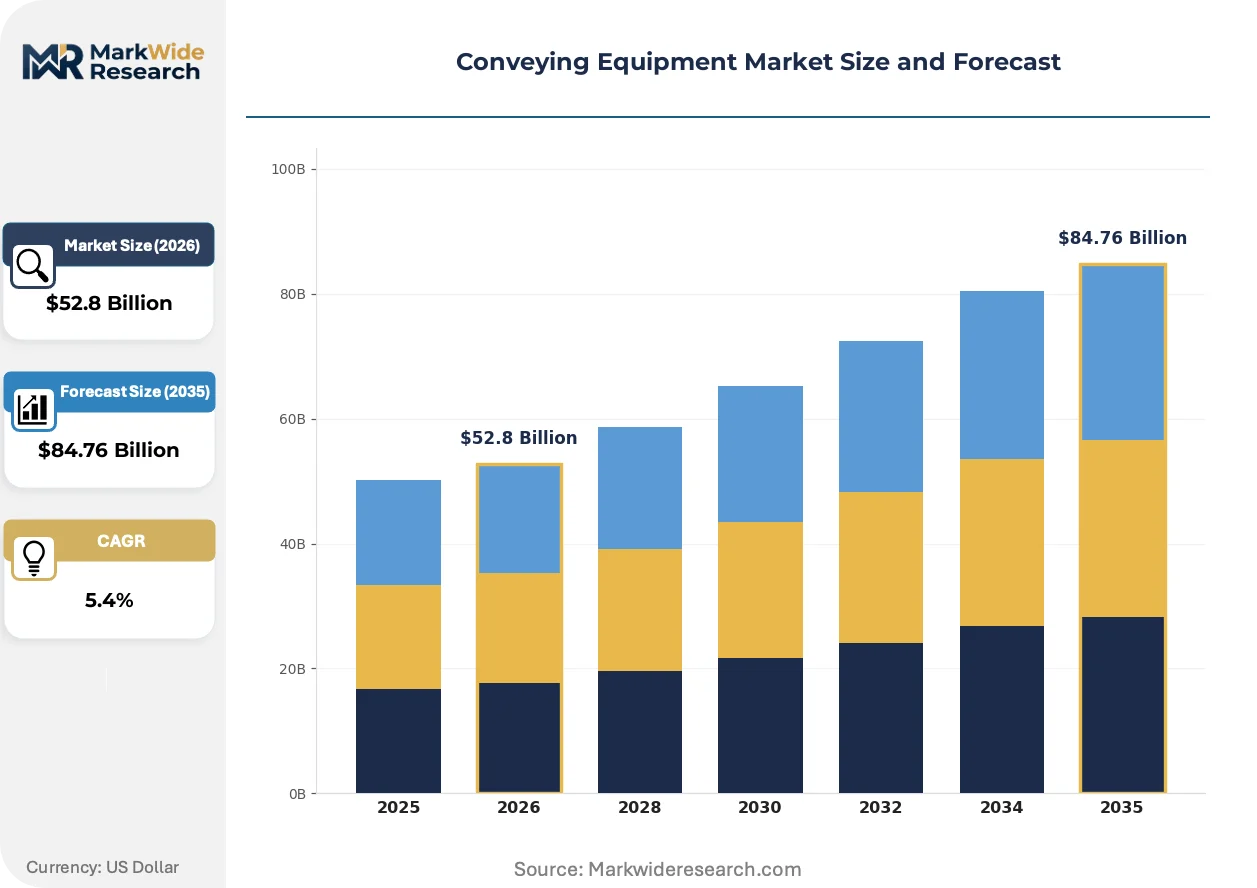
| Market Size in 2026 | $52.8 Billion |
| Market Size in 2035 | $84.76 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Belt Conveyors, Bucket Elevators, Screw Conveyors, Roller Conveyors Technology: Hydraulic Systems, Pneumatic Systems, Electric Drives, Automation End User: Agriculture, Chemical Processing, Mining, Food Production Installation: Onsite, Modular, Fixed, Portable |
| Companies Covered | Daifuku Co., Ltd., Fives Group, BEUMER Group, Interroll Group, Continental AG, Emerson Electric Co., Honeywell International Inc., FlexLink, Bastian Solutions, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Conveying Equipment Market Emerging Trajectories
Electrification architectures and data-layer integration are compressing the boundary between mechanical transport and autonomous material flow management. Equipment suppliers reposition around software-defined performance guarantees.
Condition monitoring hardware is unifying vibration, thermal, and acoustic signatures into single-edge processing units mounted at drive pulley stations. Mining operators in Chile and Australia deploy these integrated sensor packages to eliminate redundant inspection rounds. The technology is unifying maintenance scheduling across previously siloed mechanical and electrical vendor responsibilities, forcing traditional roller manufacturers to develop firmware competencies.
REACH substance restrictions on per- and polyfluoroalkyl substances compel belt manufacturers to reformulate friction coatings and release agents. Industrial consequence includes accelerated qualification cycles for alternative polymer compounds in food-grade applications. Bakery and dairy processing segments in Denmark and the Netherlands face compressed compliance timelines as legacy PTFE-coated belts approach regulatory sunset dates.
Buyer consolidation among pan-European logistics providers concentrates specification authority at headquarters procurement functions. Regional equipment distributors lose influence as standardization mandates flow from central engineering teams in Düsseldorf and Rotterdam. This pattern concentrates order volume with vendors capable of multi-site installation management and spare parts pooling across national boundaries.
Conveying Equipment Market Segmentation
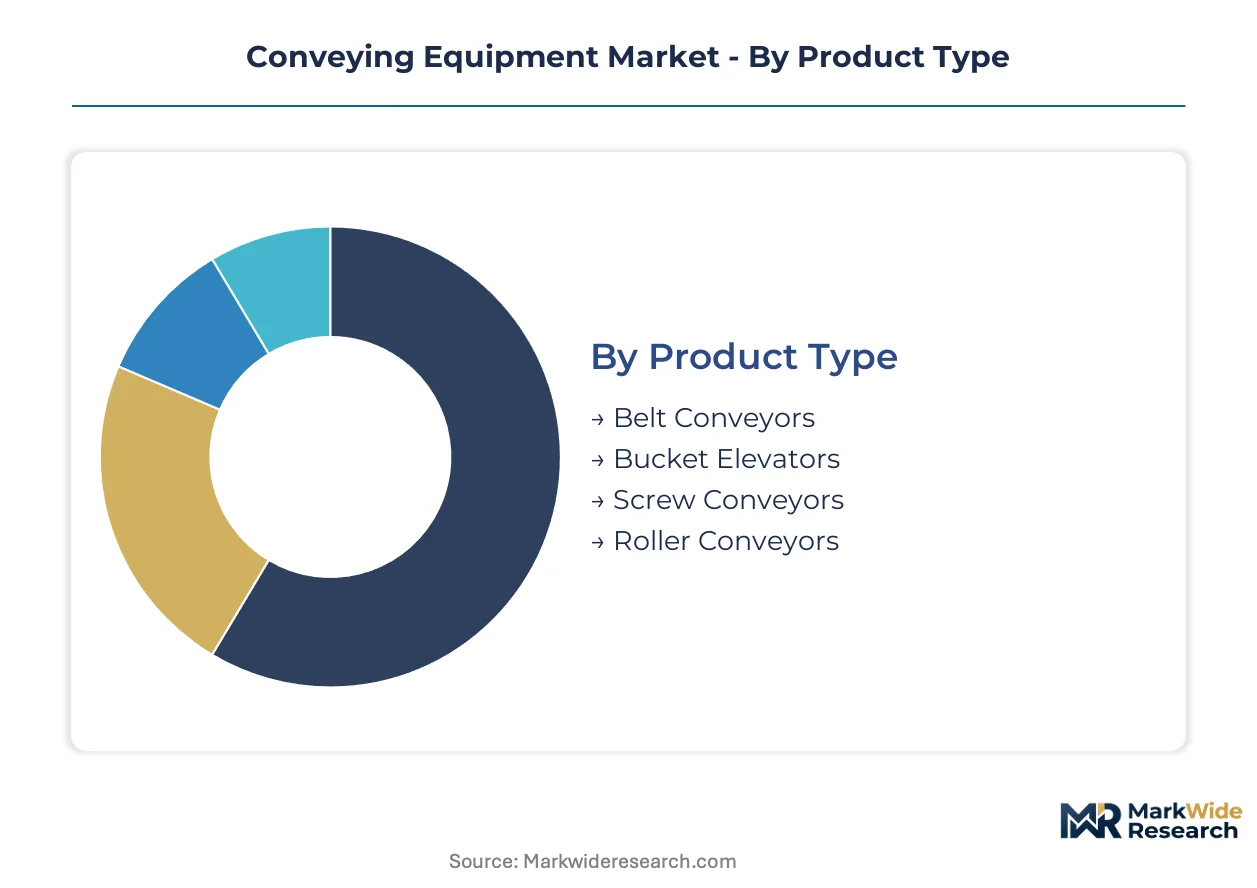
Equipment selection in conveying systems traces directly to duty-cycle intensity, material abrasiveness, and facility reconfiguration frequency. Procurement patterns diverge sharply between heavy-industry capital projects and logistics operators prioritizing seasonal flexibility.
Product Type:
Replacement-cycle timing varies dramatically across mechanical architectures, with belt systems demanding more frequent component refresh than rigid-frame alternatives.
- Belt Conveyors:Fabricated steel frames support polymer or metal-reinforced belts rated for continuous horizontal and inclined transport. German automotive assembly plants and Dutch parcel hubs anchor demand as throughput density requirements climb.
- Bucket Elevators:Centrifugal or continuous-bucket configurations lift bulk materials vertically through enclosed housings. Cement clinker handling in Poland and grain processing in France concentrate procurement for high-abrasion vertical transport.
- Screw Conveyors:Helical flighting within tubular troughs moves semi-fluid or granular materials.
- Roller Conveyors:Precision-machined steel cylinders with bearing assemblies handle discrete parcels and totes.
Belt conveyors sit at the top of the volume ranking, with bucket elevators climbing the fastest as mining and cement operators expand vertical material handling capacity.
Technology:
Capital allocation tilts toward electrification and sensor integration as energy efficiency mandates tighten across European member states.
- Electric Drives:Variable-frequency motor controllers enable precise speed modulation and regenerative braking. Food processing facilities in Denmark retrofit legacy mechanical drives to capture EU Green Deal efficiency subsidies.
- Automation:PLC-controlled sortation and autonomous flow management compress labor dependency in high-throughput environments. Polish e-commerce fulfillment centers deploy vision-guided diverters to handle peak-season volume surges.
- Hydraulic Systems:Fluid-power actuation delivers high torque density for heavy-load starting conditions.
- Pneumatic Systems:Compressed-air transport suits fine particulate and fragile material handling.
Electric drives command the largest installed base, while automation systems gain share fastest as predictive maintenance integration becomes a procurement prerequisite.
End User:
Industry-specific material properties and contamination protocols dictate equipment specification authority.
- Mining:Overland and curved belt systems transport bulk ore across extreme distances and elevation changes. Australian iron ore corridors and Chilean copper extraction anchor demand for abrasion-resistant belting and heavy-duty idler assemblies.
- Food Production:Stainless steel construction and washdown-rated drives satisfy hygiene mandates. Dutch dairy processors and Danish bakery operations face compressed timelines for PTFE-free belt reformulation under REACH restrictions.
- Chemical Processing:Corrosion-resistant materials and explosion-proof enclosures handle hazardous bulk solids.
- Agriculture:Grain handling and feed processing applications prioritize throughput over precision control.
Mining represents the largest end-use segment by capital expenditure, with food production expanding most quickly as automation penetrates European processing facilities.
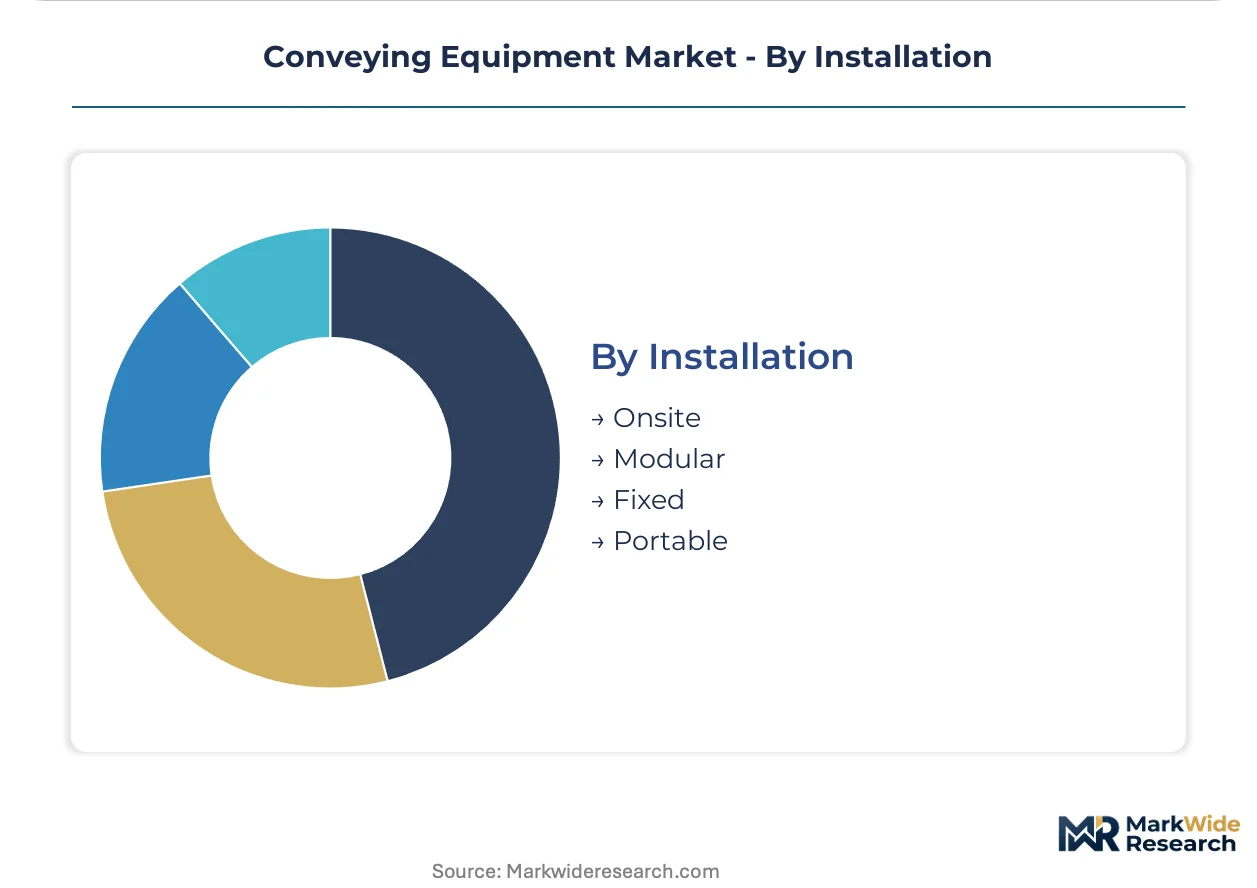
Installation:
Deployment architecture determines total cost of ownership through relocation flexibility versus structural permanence.
- Fixed:Permanent steel foundations and embedded electrical infrastructure maximize uptime for continuous-process industries. German automotive paint shops and French cement plants favor immovable capital-intensive configurations.
- Modular:Standardized frame sections with plug-and-drive connections enable rapid reconfiguration. Seasonal warehousing operators in the Netherlands and Belgium deploy modular roller systems to match capacity with demand volatility.
- Onsite:Custom-fabricated and welded installations for unique spatial constraints.
- Portable:Skid-mounted or wheel-based units for temporary construction and quarry applications.
Fixed installations retain the dominant share of cumulative investment, with modular systems gaining traction fastest among third-party logistics providers managing multi-tenant facilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's industrial corridor commands premium equipment specifications while India's logistics hubs chase automation density from a lower installed base. Capital deployment patterns diverge sharply between mature regulatory environments and emerging warehouse markets.
Germany
Automotive paint shops and parcel distribution centers drive demand for precision belt systems with integrated safety controls. The EU Machinery Directive and CE marking requirements force facility operators to replace legacy mechanical interlocks with programmable safety relays. The Rhine-Ruhr industrial cluster anchors procurement for cement clinker handling and factory automation retrofits.
United States
E-commerce fulfillment centers and third-party logistics providers compress replacement cycles for seasonal warehousing infrastructure. OSHA standards govern worker safeguarding and emergency stop protocols across distribution networks. The Chicago-Milwaukee corridor concentrates demand for high-throughput sortation systems serving cross-border freight flows.
China
Domestic mining operations and port logistics expand overland conveying capacity for bulk ore and container handling. MIIT energy efficiency directives and GB standards tighten motor and drive system specifications for export-bound manufacturers. The Yangtze River Delta industrial belt drives procurement for curved belt systems and heavy-duty idler assemblies.
India
Third-party logistics operators in Maharashtra and Karnataka lack automated material handling density comparable to European benchmarks. BIS certification requirements and PLI scheme incentives accelerate domestic manufacturing of variable-frequency drive components. The Mumbai-Pune logistics corridor attracts greenfield deployment of modular roller systems for multi-tenant facilities.
Australia
Iron ore extraction and bulk mineral transport sustain demand for abrasion-resistant belting across extreme distances. The country's national mining safety regulator mandates continuous-duty cycle ratings for overland conveyor installations. The Pilbara region anchors capital deployment for curved belt systems and predictive maintenance sensor integration.
Conveying Equipment Market Vendor Landscape
German and Japanese producers anchor one tier; French and American specialists hold differentiated positions in automation software and control systems. The vendor base organizes around three strategic archetypes: vertically integrated system integrators, component-focused precision manufacturers, and software-defined automation platforms. Consolidation pressure concentrates order volume with vendors capable of multi-site installation management. Geographic expansion and technology licensing represent the dominant competitive moves as regional distributors lose influence to centralized procurement functions.
Within the integrated system tier, Daifuku Co., Ltd. and Fives Group exemplify contrasting geographic and specialization profiles. BEUMER Group occupies a position emphasizing curved belt expertise and extractive industry applications. Among component and control specialists, Interroll Group and Continental AG represent the precision manufacturing archetype with bearing housing and belting competencies. The automation platform segment includes Emerson Electric Co. and Honeywell International Inc., which anchor positions in predictive maintenance integration and edge computing convergence.
| Leading Market Players |
|---|
| Daifuku Co., Ltd. |
| Fives Group |
| BEUMER Group |
| Interroll Group |
| Continental AG |
| Emerson Electric Co. |
| Honeywell International Inc. |
| FlexLink |
| Bastian Solutions, Inc. |
| Others |
Supply Flow & Price Mechanics
Mechatronics technician concentration in Germany's Rhine-Ruhr corridor compresses commissioning labor costs for premium-tier systems, widening the spread between CE-certified integrated solutions and economy-grade modular imports.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for variable-frequency drive components. Three-tier pricing structure across premium, standard, and economy levels separates safety-integrated control systems from basic mechanical interlocks and portable roller configurations. Price differentiation hinges on CE marking compliance and predictive maintenance sensor bundling. Cost compression in economy-tier belt systems is intensifying because Indian domestic manufacturers exploit PLI scheme incentives, while German automotive integrators show lowest price sensitivity due to throughput-density mandates.
Supply Chain Analysis
India's PLI scheme domestic-content thresholds are reshaping sourcing patterns for motor and drive assemblies. Fabricated steel frames draw from China, Germany, and India; polymer belting feeds from Continental AG's European plants and specialized Asian compounders; precision bearing housings rest on German and Japanese CNC machining capacity. Single-source vulnerability concentrates in neodymium magnet processing anchored in China. Distribution runs through authorized system integrators with regional spare-parts pooling agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The conveying equipment market compounds steadily as e-commerce fulfillment automation sustains replacement-cycle compression across logistics infrastructure.
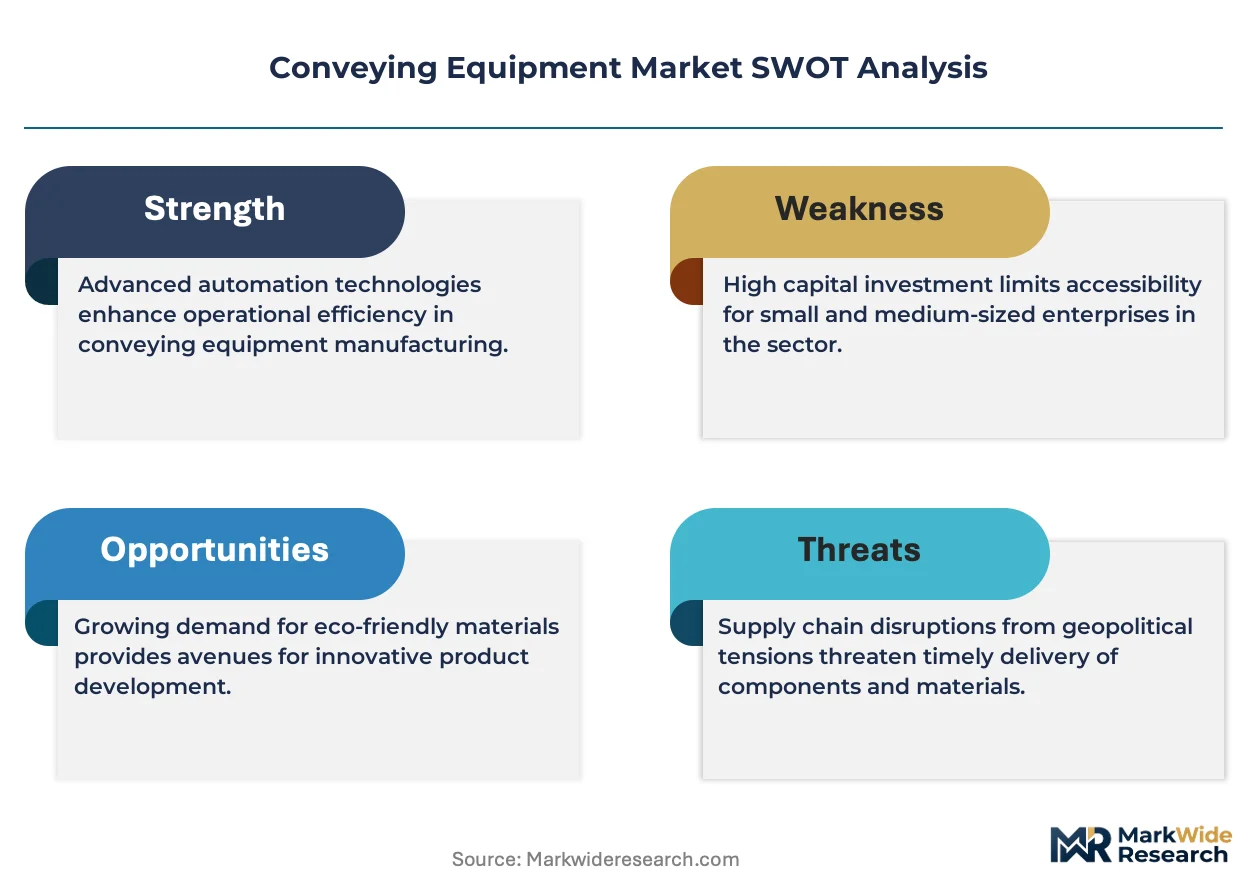
For Market Incumbents: Extend predictive maintenance service agreements to capture recurring revenue streams as hardware margins compress. Consolidate procurement leverage through multi-site installation management contracts spanning pan-European logistics providers. Counter hydraulic drive substitution in heavy-load mining applications by accelerating regenerative braking integration. For New Entrants and Emerging Players: EU Green Deal energy efficiency subsidies in Denmark and France open a window for variable-frequency drive retrofit specialists lacking established service footprints. Penetrate India's Maharashtra warehouse automation gap through modular roller systems with rapid reconfiguration capabilities. Pursue OEM partnerships with domestic Indian manufacturers to satisfy BIS certification requirements. For Investors and Strategic Acquirers: Valuations sit cheapest among component-focused precision manufacturers lacking firmware competencies for sensor integration. Five-to-ten-year viability favors vendors with captive control software development and aftermarket parts logistics density. Monitor EU Machinery Directive amendment timelines as inflection signals for safety-system upgrade demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Control Software | Daifuku's in-house automated storage programming sustains premium positioning against hardware-only competitors. |
| Predictive Maintenance Sensor Deployment | Vibration-thermal fusion at Chilean mining sites shifts revenue from equipment sales to performance-guaranteed contracts. |
| CE Marking Acceleration | Programmable safety relay retrofits in German automotive plants compress replacement cycles for legacy mechanical interlocks. |
| Modular System Standardization | Dutch seasonal warehousing operators prioritize plug-and-drive configurations over fixed-capital efficiency. |
| REACH-Compliant Belt Reformulation | Danish dairy processors face compressed timelines for PTFE-free polymer qualification under substance restrictions. |
Methodological Framework
Direct dialogue with maintenance directors at German automotive plants, aftermarket service heads at mining operators, OEM procurement teams in China, and plant engineers across cement and food processing facilities grounded qualitative insights. Secondary validation drew from SEC 10-K filings, EU Machinery Directive implementation reports, customs trade data for fabricated steel and polymer belting, and MIIT energy efficiency disclosures. Bottom-up equipment unit economics triangulated against top-down end-use industry capex patterns.
Bottom-up volume modeling by product type, technology tier, installation architecture, and end-use intensity converged with top-down industrial automation spending trajectories across the analysis window. Segmentation dimensions spanned belt versus roller versus bucket elevator architectures, electric versus hydraulic drive systems, fixed versus modular deployment models, and mining-logistics-food production end-use clusters. CAGRs derived from replacement-cycle timing, regulatory compliance deadlines, and automation penetration differentials. Forecast inputs incorporated EU Green Deal subsidy uptake rates and e-commerce fulfillment center buildout pipelines.
Revisions become necessary when rare earth export quotas tighten, structural steel price volatility exceeds historical bands, or rail-truck intermodal investments accelerate in Australian and Brazilian mining corridors. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Industrial Elevator Market
Material Handling Equipment
Global Lifting Columns Market
Material Handling Equipment
Heavy Loader Market
Material Handling Equipment
US and Mexico Metal Stamping Market
Material Handling Equipment
Tipper Pads Market
Material Handling Equipment
Material Handling Automation Market
Material Handling Equipment
Wire Pulling and Tensioning Market
Material Handling Equipment
Hooklifts Market
Material Handling Equipment
Lump Breaker Machines Market
Material Handling Equipment
Global Conveyor System Market
Material Handling Equipment
Cherry Picker Forklift Market
Material Handling Equipment
Loading Platform Canopies Market
Material Handling Equipment
Global Screw Conveyors Market
Material Handling Equipment
Global Bucket Loader Market
Material Handling Equipment
Global Conveyors Market
Material Handling Equipment
Port Material Handling Equipment Vehicle Market