
 Heavy Hex Nuts Market | 2026-2036
Heavy Hex Nuts Market Size, Share, and Industry Trends Forecast 2026-2036
Heavy Hex Nuts Market Foresight
Stainless steel is restructuring product economics in heavy hex nuts as coastal infrastructure and renewable energy projects specify higher corrosion resistance. Nucor Fastener leverages its domestic melt-to-finish verticality to control alloy input costs. Infasco anchors its position through deep inventory of ASTM-certified grades for structural bolting. MW Industries differentiates via custom forging capabilities for non-standard dimensions.
Heavy hex nuts are oversized six-sided fasteners with thicker walls and larger bearing surfaces than standard hex nuts, typically manufactured through hot forging or cold forming to achieve proof load ratings exceeding 150,000 psi for structural steel connections. Their primary purpose is to distribute clamping force across bolted joints in high-load infrastructure. Carbon steel dominates volume shipments for commercial construction, while stainless steel commands premium positioning in marine and chemical processing applications. Hot dip galvanized coating types capture the largest share of outdoor infrastructure spend due to extended service life requirements.
ASTM International governs dimensional and mechanical standards for heavy hex nuts in the United States, while ISO 4033 and DIN 934 define metric equivalents for cross-border projects. OSHA fall-protection regulations and AISC structural steel specifications collectively shape demand for certified, traceable fastener lots in commercial building. Buyers must monitor alloy surcharge volatility and evolving Buy America domestic content thresholds for federally funded infrastructure.
Market Dynamics
ASTM A194 and A563 specification tightening is forcing mills to retool heat-treatment lines and invest in spectrometry equipment for lot traceability, compressing margins for non-certified suppliers while rewarding domestic melt-to-finish producers with federal infrastructure eligibility.
Growth Catalysts
- Offshore Wind Buildout:Turbine foundation bolting specifications now require Grade 2H and 2HM heavy hex nuts with Charpy impact certification at sub-zero temperatures. Installation contractors in the US Gulf Coast and North Sea corridors are pre-positioning corrosion-resistant inventory.
- Buy America Threshold Elevation:The Infrastructure Investment and Jobs Act mandates 100 percent domestic iron and steel content for federally funded bridges and transit systems. Fastener distributors are qualifying new domestic forging sources to maintain project eligibility.
- Hot Dip Galvanizing Capacity Expansion:Batch galvanizers in Texas and Louisiana are adding kettle capacity specifically for structural bolting components. This process extension allows nut-forging operations to offer single-source certified assemblies.
Market Restraints
- Alloy Surcharge Volatility:Nickel and molybdenum price swings in stainless steel 316 and 316L grades compress quoting windows to under 48 hours. Distributors carry hedge exposure or pass through spot pricing, destabilizing project budgeting.
- Scrap-Dependent Supply Concentration:US electric arc furnace operators control over 70 percent of domestic carbon steel fastener rod supply. Any curtailment at Nucor, Steel Dynamics, or CMC facilities ripples through forging lead times within weeks.
- Mechanical Galvanizing Substitution:Zinc flake coating systems achieve equivalent salt-spray performance for indoor structural applications at lower applied cost. This process is capturing specification share in commercial building where outdoor exposure is limited.
Strategic Opportunities
- India Infrastructure Acceleration:The National Infrastructure Pipeline and PLI scheme for specialty steel are creating import-substitution demand for ASTM-equivalent heavy hex nuts in power transmission and metro rail projects. Early entrants can establish specification influence with EPC contractors.
- Digital Twin Integration:RFID-embedded fasteners with torque-history logging enable predictive maintenance in wind turbine and bridge applications. This data layer transforms commodity hardware into recurring-revenue monitoring subscriptions.
- Green Hydrogen Electrolyzer Fabrication:Pressurized alkaline and PEM electrolyzer skid manufacturers require super-duplex stainless bolting for high-purity hydrogen service. This application is expanding the addressable market beyond traditional structural grades.
Industry Challenges
- NDT Technician Scarcity:Magnetic particle and ultrasonic inspection certification for ASTM A194 Grade 7 and Grade 7L nuts requires ASNT Level II-qualified personnel. Forging shops compete with oilfield services and aerospace for this limited talent pool.
- Heat-Treatment Bottleneck:Achieving specified hardness ranges across 1-inch to 4-inch nut sizes requires furnace campaigns with precise atmosphere control. Capital equipment for continuous mesh-belt hardening runs $3-5 million per line with 18-month lead times.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heavy Hex Nuts Market |
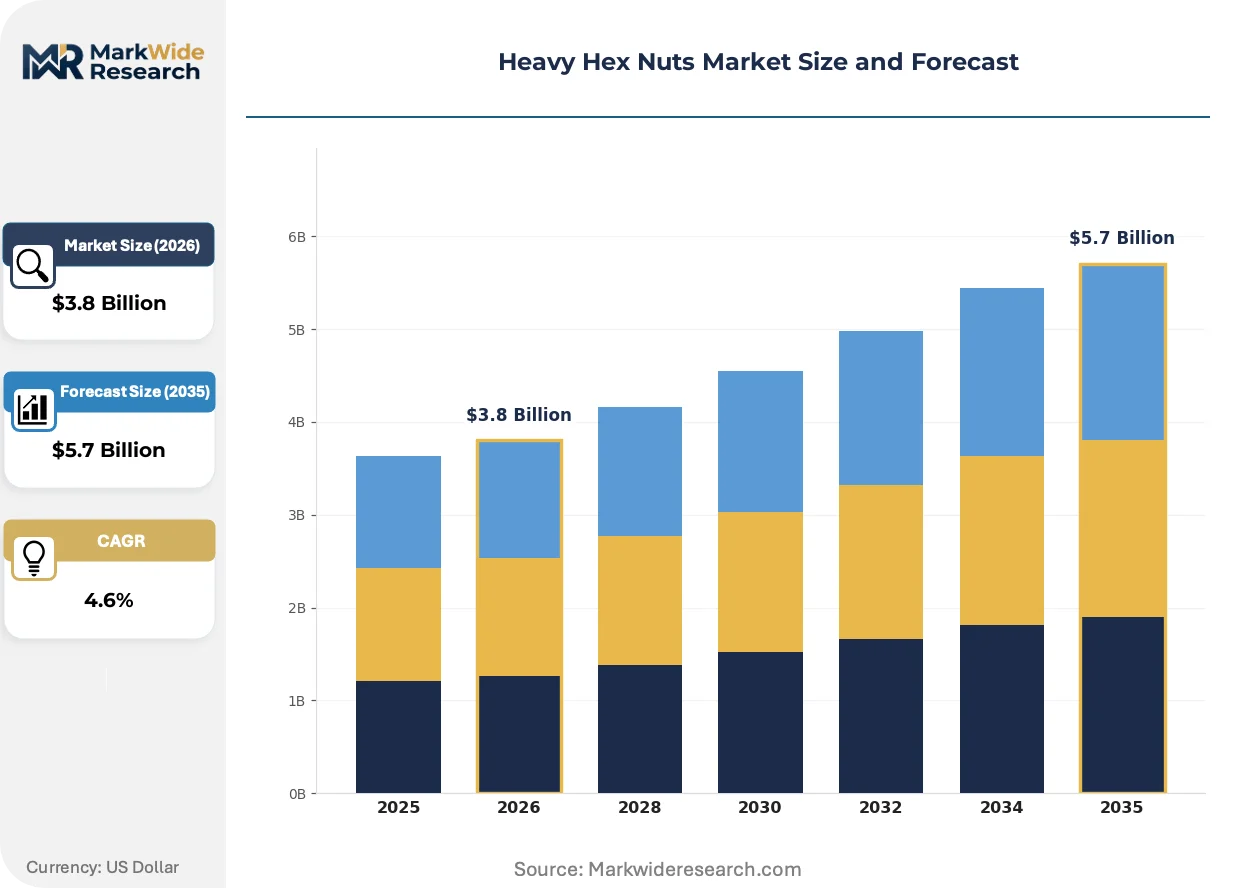
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Heavy Hex, ASTM Heavy Hex, Metric Heavy Hex, Custom Heavy Hex Material: Carbon Steel, Stainless Steel, Alloy Steel, Brass Coating Type: Zinc Plated, Hot Dip Galvanized, Phosphate Coated, Plain Application: Construction, Automotive, Marine, Machinery |
| Companies Covered | Nucor Fastener, Infasco, Vikrant Fasteners, MW Industries, Canco Fastener, Stanley Black & Decker, Fastenal Company, Hilti Group, Würth Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heavy Hex Nuts Market Shifts & Advancements
Material science advances and digital traceability requirements are converging to redefine how heavy hex nuts are specified, manufactured, and monitored through their service life. These developments favor suppliers with metallurgical depth and data infrastructure.
Super-duplex stainless steel grades 2507 and Zeron 100 are integrating into offshore platform and desalination plant specifications where pitting resistance equivalent numbers above 40 are mandatory. Engineering-procurement-construction firms in the UAE and Saudi Arabia are now requiring these alloys for subsea bolting packages. This metallurgical upgrade is compressing the viable supplier base to mills with vacuum arc remelt capability.
OSHA's updated fall-protection standards for steel erection are mandating documented torque verification on all structural connections above six feet. Contractors must now maintain calibration records for hydraulic tensioning equipment and submit nut lot certificates with each inspection phase. Commercial building projects in Texas and California are responding by pre-qualifying fastener distributors with integrated testing laboratories.
Consolidated procurement through integrated supply agreements is displacing spot purchasing for multi-site infrastructure programs. State departments of transportation in Florida, New York, and Illinois are bundling bridge and highway fastener requirements into single-source contracts with penalty clauses for non-conformance. This behavioral shift concentrates volume with distributors capable of holding 90-day certified inventory positions.
Heavy Hex Nuts Market Segmentation
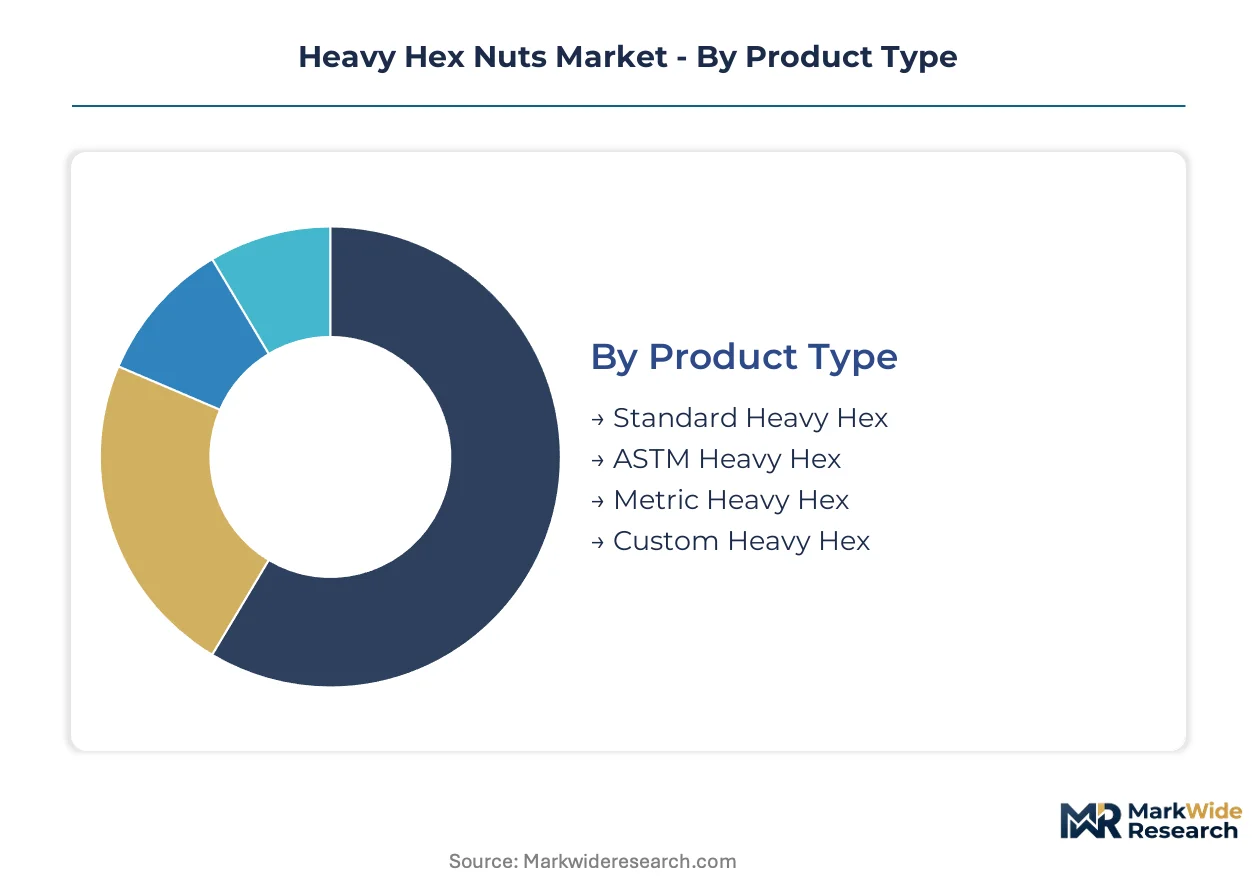
Heavy hex nut procurement splits sharply between specification-driven bulk orders and engineered custom lots. Buyers select across material, coating, and dimensional standards based on load requirements, environmental exposure, and regulatory jurisdiction.
Product Type:
Standardization dominates high-volume infrastructure contracts, while custom forging commands premium positioning in non-standard bolting applications.
- Standard Heavy Hex:Manufactured to unified inch dimensions with proof load ratings matching SAE J995. Bridge contractors in Texas and Louisiana specify these for routine structural connections where interchangeability reduces field inventory complexity.
- ASTM Heavy Hex:Governed by ASTM A194 and A563 with mandatory lot traceability and hardness certification. Federal infrastructure mandates in the United States restrict eligibility to domestically melted and finished lots, compressing the qualified supplier base.
- Metric Heavy Hex:Conforming to ISO 4033 and DIN 934 for cross-border equipment fabrication. European wind turbine OEMs specify these for nacelle assembly lines serving North Sea installation fleets.
- Custom Heavy Hex:Non-standard dimensions produced through open-die forging for specialized machinery and retrofit applications. Lead times extend to 8-12 weeks versus 2-3 weeks for catalog sizes.
Most installed capacity flows through Standard Heavy Hex. Expansion is steepest in ASTM Heavy Hex.
Material:
Cost tiers separate commodity carbon grades from corrosion-resistant alloys, with specification grade determining federal project eligibility.
- Carbon Steel:AISI 1018 and 1045 grades dominate commercial construction volume. Electric arc furnace producers in the United States control rod supply, transmitting scrap price volatility directly to forging margins.
- Stainless Steel:Grades 316 and 316L with molybdenum addition deliver pitting resistance for coastal infrastructure. Offshore wind foundation contractors in the Gulf Coast corridor pre-position inventory ahead of installation windows.
- Alloy Steel:ASTM A194 Grade 2H and 7 specifications achieve high strength-to-weight ratios through quench-and-temper processing. Heat-treatment capacity constraints limit qualified domestic suppliers.
- Brass:C36000 free-machining alloy serves electrical grounding and decorative architectural applications where magnetic interference or aesthetic finish matters.
Carbon Steel absorbs the majority of tonnage. Stainless Steel is climbing the fastest.
Coating Type:
Service life requirements and environmental exposure dictate coating selection, with batch processing economics favoring high-volume galvanizing operations.
- Hot Dip Galvanized:Immersion in molten zinc delivers 50-75 year corrosion protection for outdoor infrastructure. Kettle capacity expansion in Texas and Louisiana allows integrated nut-and-bolt assembly certification.
- Zinc Plated:Electrodeposited coatings for indoor structural applications where salt-spray exposure is limited. Commercial building contractors in California specify these for cost-sensitive steel erection.
- Phosphate Coated:Manganese and zinc phosphate conversion layers improve paint adhesion and corrosion resistance under topcoats. Machinery OEMs specify these for painted frame assemblies.
- Plain:Uncoated finish for immediate welding or applications where surface chemistry must remain unaltered. Oil and gas fabricators prefer these for subsequent overlay welding procedures.
Hot Dip Galvanized commands the largest share of outdoor infrastructure spend. Mechanical galvanizing substitution is gaining share fastest in indoor commercial building.
Application:
End-use concentration varies by project cycle timing, with renewable energy and transportation infrastructure driving specification upgrades.
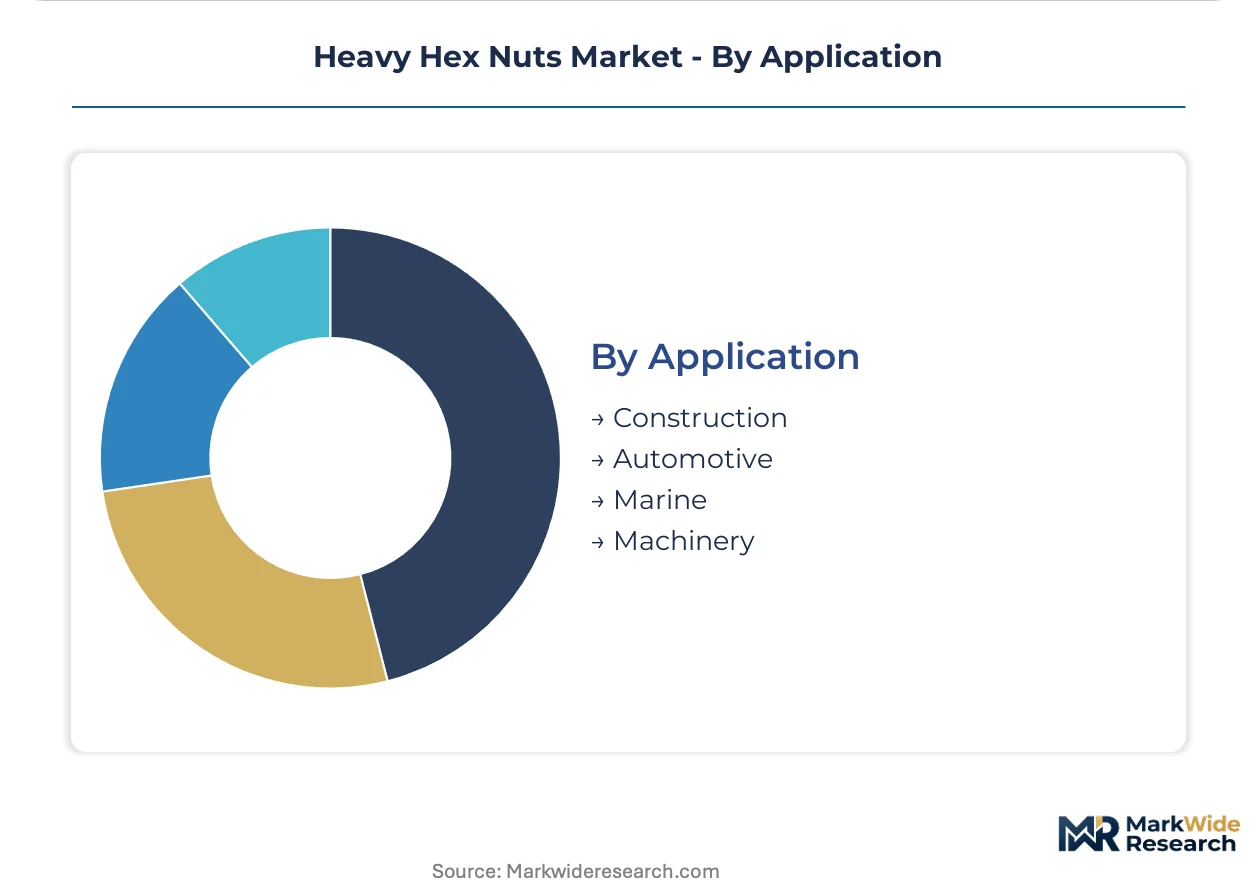
- Construction:Structural steel connections in bridges, buildings, and transmission towers. State departments of transportation in Florida, New York, and Illinois bundle fastener requirements into multi-year supply agreements.
- Marine:Shipbuilding, offshore platforms, and port infrastructure demand super-duplex and 316L grades. EPC contractors in the UAE and Saudi Arabia now require vacuum arc remelt certification for subsea packages.
- Automotive:Heavy truck chassis and equipment mounting brackets. Fleet operators specify Grade 8 equivalents for durability under vibration loading.
- Machinery:Mining equipment, agricultural implements, and industrial presses require non-standard dimensions and high-wear resistance. Custom forging capabilities differentiate suppliers in this segment.
Construction absorbs the majority of volume. Marine applications are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Gulf Coast energy corridor concentrates heavy hex nut demand through offshore wind foundation projects and petrochemical construction. Texas and Louisiana anchor North American procurement volumes. Specification-grade inventory pre-positioning accelerates ahead of federal infrastructure award cycles.
United States
Bridge and transit contractors in Texas, Florida, and New York bundle fastener requirements into multi-year supply agreements with penalty clauses. OSHA fall-protection regulations and AISC structural steel specifications mandate documented torque verification and lot traceability. Domestic melt-to-finish producers in the Southeast and Midwest control federal project eligibility through Buy America compliance.
Germany
North Sea wind turbine OEMs specify metric heavy hex nuts for nacelle assembly lines serving installation fleets across the Baltic and North Sea corridors. REACH and CE marking requirements govern coating chemistry and mechanical certification for cross-border projects. Industrial clusters in North Rhine-Westphalia and Lower Saxony concentrate forging and galvanizing capacity for offshore foundation packages.
India
The National Infrastructure Pipeline and PLI scheme for specialty steel generate import-substitution demand for ASTM-equivalent heavy hex nuts in power transmission and metro rail projects. BIS certification requirements tighten dimensional and mechanical standards for domestic suppliers. Manufacturing clusters in Maharashtra and Gujarat attract forging investments targeting EPC contractor pre-qualification.
UAE
Desalination plant and offshore platform EPC contractors now require super-duplex stainless grades with vacuum arc remelt certification for subsea bolting packages. MOHAP and the country's national construction regulator enforce material traceability for critical infrastructure. Dubai and Abu Dhabi anchor procurement concentration for Gulf petrochemical and renewable energy projects.
China
Dual carbon goals and GB standards alignment drive specification upgrades for wind turbine and high-speed rail bolting. MIIT oversees mechanical certification requirements for structural fasteners in federally prioritized infrastructure. Yangtze River Delta forging operations expand heat-treatment capacity to capture export demand for ASTM-equivalent grades.
Heavy Hex Nuts Market Competitive Landscape
Capacity expansion dominates the current landscape as batch galvanizers in Texas and Louisiana add kettle capacity specifically for structural bolting components. The supplier base stratifies between integrated melt-to-finish producers, specialized forging operations, and distribution-heavy intermediaries. Three archetypes define competitive positioning: domestic vertical integrators controlling alloy input costs, ASTM-certified specialists holding deep inventory positions, and custom forging shops serving non-standard dimensions. M&A activity and heat-treatment line investments represent the dominant competitive moves as specification tightening compresses margins for non-certified suppliers.
Among North American fabricators, Nucor Fastener exemplifies the domestic vertical integrator archetype through captive steel supply. Infasco anchors the ASTM-certified specialist tier with deep inventory positions for structural bolting. MW Industries occupies the custom forging vector for non-standard dimensions. These three companies represent distinct strategic postures rather than direct segment competition, with each archetype capturing value through different certification and capability thresholds.
| Leading Market Players |
|---|
| Nucor Fastener |
| Infasco |
| Vikrant Fasteners |
| MW Industries |
| Canco Fastener |
| Stanley Black & Decker |
| Fastenal Company |
| Hilti Group |
| Würth Group |
| Others |
Supply & Pricing Matrix
Captive melt-to-finish verticality among domestic electric arc furnace operators anchors both supply security and pricing power in the heavy hex nuts market. Nucor Fastener and Steel Dynamics control alloy input costs through in-house steel production, insulating their forging operations from scrap price volatility that compresses margins for rod-dependent competitors.
Pricing Analysis
Alloy surcharge volatility in stainless steel 316 and 316L grades passes directly through to end-user quotations, compressing quoting windows to under 48 hours. Three-tier pricing structure across ASTM-certified premium, standard commercial, and spot-market economy levels separates federal project-eligible lots from non-certified imports. Pricing pressure stems from mechanical galvanizing substitution achieving equivalent salt-spray performance at lower applied cost for indoor structural applications. Commercial building contractors in California exhibit highest price sensitivity, while offshore wind EPC contractors in the Gulf Coast corridor prioritize Charpy-certified inventory over unit cost.
Supply Chain Analysis
Regional distribution centers in Texas and Louisiana function as hub-and-spoke nodes for pre-positioned ASTM-certified inventory ahead of federal infrastructure award cycles. Manufacturing concentrates in the United States, Germany, and China, with domestic electric arc furnace operators controlling over 70 percent of carbon steel fastener rod supply. Raw material dependencies rest on scrap steel, nickel, and molybdenum inputs, with nickel price swings transmitting directly to stainless steel forging margins. Single-source vulnerability at Nucor, Steel Dynamics, or CMC facilities ripples through forging lead times within weeks. Distribution runs through integrated fastener distributors holding 90-day certified inventory positions for state transportation department bundles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The heavy hex nuts market functions as a regulatory compounder where Buy America threshold elevation and OSHA fall-protection mandates continuously tighten specification requirements. The Infrastructure Investment and Jobs Act's 100 percent domestic content mandate for federally funded bridges and transit systems creates structural demand for certified, traceable fastener lots.
For Market Incumbents: Lock in federal project eligibility through spectrometry equipment investments for lot traceability and heat-treatment line certification for ASTM A194 Grade 2H and 7 specifications. Defend against mechanical galvanizing substitution by integrating batch galvanizing capacity for single-source certified nut-and-bolt assemblies. Prioritize captive melt-to-finish verticality to control alloy surcharge exposure in stainless steel grades. For New Entrants and Emerging Players: The price-point gap between vacuum arc remelt-certified super-duplex premium tiers and commodity carbon steel economy lots creates entry space for mid-tier ASTM-equivalent specialists. Target India's National Infrastructure Pipeline and PLI scheme for specialty steel, where BIS certification requirements are tightening but qualified domestic forging capacity remains underdeveloped. Pursue EPC contractor pre-qualification in Maharashtra and Gujarat manufacturing clusters as the primary go-to-market angle. For Investors and Strategic Acquirers: Roll-up economics work for ASTM-certified regional distributors with deep inventory positions because specification tightening compresses margins for non-certified suppliers and concentrates volume with holders of 90-day certified stock. Five-to-ten year viability favors targets with integrated testing laboratories and established state transportation department contracts. Watch heat-treatment line investment announcements as the inflection indicator for supply-side capacity constraints easing or tightening.| Strategic Initiative | Industry Significance |
|---|---|
| Heat-Treatment Line Investment | ASTM A194 certification capacity expands as furnace campaigns achieve precise hardness ranges across nut sizes. |
| Batch Galvanizing Capacity Expansion | Texas and Louisiana kettle additions enable single-source certified nut-and-bolt assemblies for bridge contractors. |
| Digital Twin Integration | RFID-embedded fasteners with torque-history logging transform commodity hardware into recurring-revenue monitoring subscriptions. |
| Super-Duplex Alloy Qualification | Vacuum arc remelt capability opens UAE and Saudi Arabian subsea bolting packages with PREN above 40 requirements. |
| Domestic Forging Source Qualification | Buy America compliance maintains eligibility for Infrastructure Investment and Jobs Act-funded transit and bridge projects. |
Research Methodology
Multiple input streams — primary interviews with fastener procurement managers at EPC contractors and state transportation departments, technical discussions with forging operations managers, and secondary validation through customs data and ASTM certification records — were reconciled through bottom-up and top-down triangulation. Primary fieldwork captured perspectives from bridge contractors in Texas and Florida, offshore wind installation contractors in the Gulf Coast corridor, and galvanizing operations managers in Louisiana. Secondary sources included SEC filings from integrated steel producers, OSHA enforcement data on fall-protection compliance, and state department of transportation procurement databases.
Data-stream reconciliation across the projection horizon applied a segmented analytical framework modeling material grade, coating type, application end-use, and regional regulatory cluster. CAGRs were derived through regression analysis of historical shipment volumes against infrastructure award cycles and renewable energy installation timelines. Forecast inputs incorporated electric arc furnace operating rates, nickel price volatility indices, and federal infrastructure appropriation trajectories without specifying annual allocations.
Caveats apply where alloy surcharge volatility, scrap supply disruptions at major electric arc furnace operators, or mechanical galvanizing specification capture could materially shift the outlook. Forecasts reflect documented assumptions regarding Buy America threshold enforcement consistency and OSHA inspection intensity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Dewatering Screen Market
Material Handling Equipment
Cut-To-Length Line Systems Market
Material Handling Equipment
Silo Bin Activators Market
Material Handling Equipment
Pipe Wipers Market
Material Handling Equipment
Push-Back Racking System Market
Material Handling Equipment
Ship Loader and Unloader Market
Material Handling Equipment
Industrial Piggable Wye Fitting Market
Material Handling Equipment
Material Handling Equipment Market
Material Handling Equipment
Lever Hoist Market
Material Handling Equipment
Explosion Proof Crane Market
Material Handling Equipment
Japan Conveyor Belt Market
Material Handling Equipment
Die Casting Market
Material Handling Equipment
Slag Handling Machine Market
Material Handling Equipment
Trommel Screen Market
Material Handling Equipment
Global Linear Guide Market
Material Handling Equipment
Selective Pallet Racking System Market