
 Modular Conveyor System Market | 2026-2036
Modular Conveyor System Market Size, Share, and Industry Trends Forecast 2026-2036
Modular Conveyor System Market Foresight
German conveyor manufacturers is recalibrating output schedules to match surging automotive and logistics demand across Central Europe. SSI SCHÄFER leverages its intralogistics integration expertise to anchor large-scale distribution center rollouts. Daifuku Co., Ltd. competes through deep specialization in clean-room and high-throughput material handling architectures. Interroll Holding AG dominates the drum motor segment that powers modular roller conveyors for parcel and package flows.
A modular conveyor system comprises standardized, interchangeable sections—belt, roller, chain, or overhead configurations—that engineers assemble, extend, or reconfigure without custom fabrication, typically operating at speeds from 0.5 to 2.5 meters per second with load capacities spanning 5 to 1,500 kilograms per linear meter. These systems transport unit loads through manufacturing, warehousing, and distribution environments where production layouts change frequently. Belt conveyor technology leads in food processing and parcel sortation due to smooth surface continuity and sanitary compliance, while smart technology integrations—sensor-enabled tracking, predictive maintenance algorithms, and IoT-connected drive units—are capturing the fastest expansion as operators prioritize uptime visibility over basic mechanization. Roller conveyor systems retain margin strength in heavy-goods manufacturing where steel construction and bearing longevity justify premium positioning.
The EU Machinery Directive and CE marking framework mandate documented risk assessments and safeguard integration for all powered conveyor installations sold in Europe, compelling vendors to embed interlock switches and emergency-stop redundancy as standard rather than optional features. OSHA lockout/tagout standards in the United States require energy-isolation protocols during maintenance, driving demand for quick-release modular sections that minimize downtime during safety procedures. Stakeholders must weigh upfront platform standardization against the operational flexibility that hybrid manual-automated configurations provide when order profiles shift unpredictably.
Market Dynamics
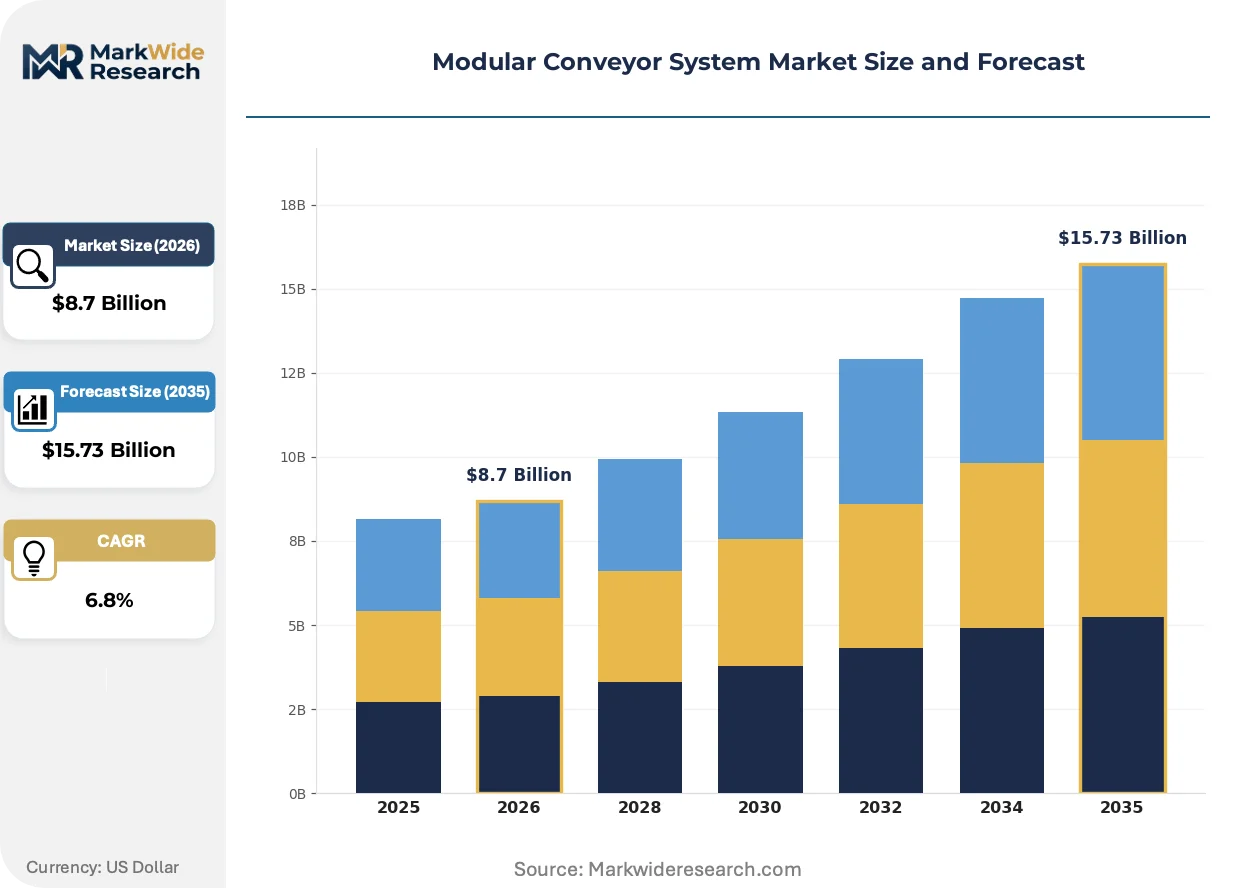
Reconfigurable belt and roller platforms are displacing fixed-line installations as automotive OEMs and third-party logistics providers retrofit assembly and distribution lines across Central Europe, compressing deployment cycles from months to weeks.
Growth Catalysts
- EU Machinery Directive compliance mandates:Documented risk assessments and safeguard integration requirements compel facility operators to replace aging fixed conveyors with modular systems that embed interlock switches and emergency-stop redundancy as standard features.
- E-commerce fulfillment center automation:Automated sortation modules are capturing expanded floor space as parcel volumes strain manual handling capacity in regional distribution hubs.
- Steel bearing longevity in heavy-goods manufacturing:Roller conveyor construction with hardened bearing assemblies justifies premium positioning in automotive stamping and appliance assembly where load cycles exceed one million operations.
Market Restraints
- Stainless steel and aluminum input volatility:Raw material price swings compress margin predictability for conveyor frame and roller drum manufacturers who cannot pass through index-linked adjustments within fixed project contracts.
- German supplier concentration:Drum motor and drive unit production clusters in Baden-Württemberg and Bavaria, creating single-source vulnerability for Central European integrators during capacity constraints.
- Speed-load trade-off limitations:Belt conveyors operating above two meters per second experience accelerated wear on splice joints, restricting high-velocity applications in express parcel sortation.
Strategic Opportunities
- Polish and Czech manufacturing corridors:Greenfield automotive battery plants and appliance assembly facilities in Lower Silesia and Moravia lack installed conveyor base, creating first-mover positioning for modular platform vendors.
- IoT-enabled predictive maintenance convergence:Sensor-embedded drive units combined with cloud-based algorithmic monitoring are opening annuity revenue streams through uptime-guarantee service contracts.
- CE marking acceleration under EU harmonized standards:Streamified conformity assessment procedures reduce time-to-market for reconfigurable platforms versus custom-engineered alternatives.
Industry Challenges
- Mechatronics technician scarcity:Integration of servo-driven modular sections with legacy PLC architectures demands cross-trained personnel scarce in Central European industrial regions.
- OSHA lockout-tagout protocol complexity:Energy-isolation requirements during maintenance drive demand for quick-release modular sections, yet retrofitting existing lines with compliant disconnects extends project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Modular Conveyor System Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Roller Conveyor, Belt Conveyor, Chain Conveyor, Overhead Conveyor Technology: Automated, Manual, Hybrid, Smart End User: Manufacturing, Warehousing, Food Processing, Pharmaceuticals Installation: Fixed, Portable, Modular, Customizable |
| Companies Covered | Honeywell Intelligrated, SSI SCHÄFER, Daifuku Co., Ltd., Siemens Logistics, Hytrol Conveyor Company, Inc., Interroll Holding AG, Fives Group, Intralox, L.L.C., FlexLink AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Modular Conveyor System Market Shifts & Advancements
Smart technology integrations are capturing the fastest expansion as operators prioritize uptime visibility over basic mechanization, compressing the competitive window for sensor-naive equipment suppliers.
Sensor-enabled tracking systems with embedded RFID and optical recognition are expanding into pharmaceutical distribution and high-value electronics fulfillment where lot traceability mandates require item-level accountability. German automotive suppliers are adopting these configurations at pace to satisfy OEM inbound logistics requirements. This visibility layer is expanding into predictive maintenance service models that displace break-fix contracts.
REACH substance restrictions and RoHS hazardous material limits are tightening specifications for polymer belt compounds and electronic drive components sold into European installations. Manufacturers must reformulate PVC and polyurethane formulations or source alternative elastomers to maintain market access. Food processing and pharmaceutical handling segments are most affected, with vendors accelerating halogen-free and plasticizer-reduced material certifications.
Facility operators are consolidating vendor relationships around full-lifecycle service agreements that bundle equipment, installation, and predictive maintenance under single-source accountability. Traditional equipment-only suppliers face displacement by intralogistics integrators offering outcome-based uptime guarantees. This consolidation is most visible in German automotive and third-party logistics verticals where total cost of ownership modeling dominates capital allocation decisions.
Modular Conveyor System Market Segmentation
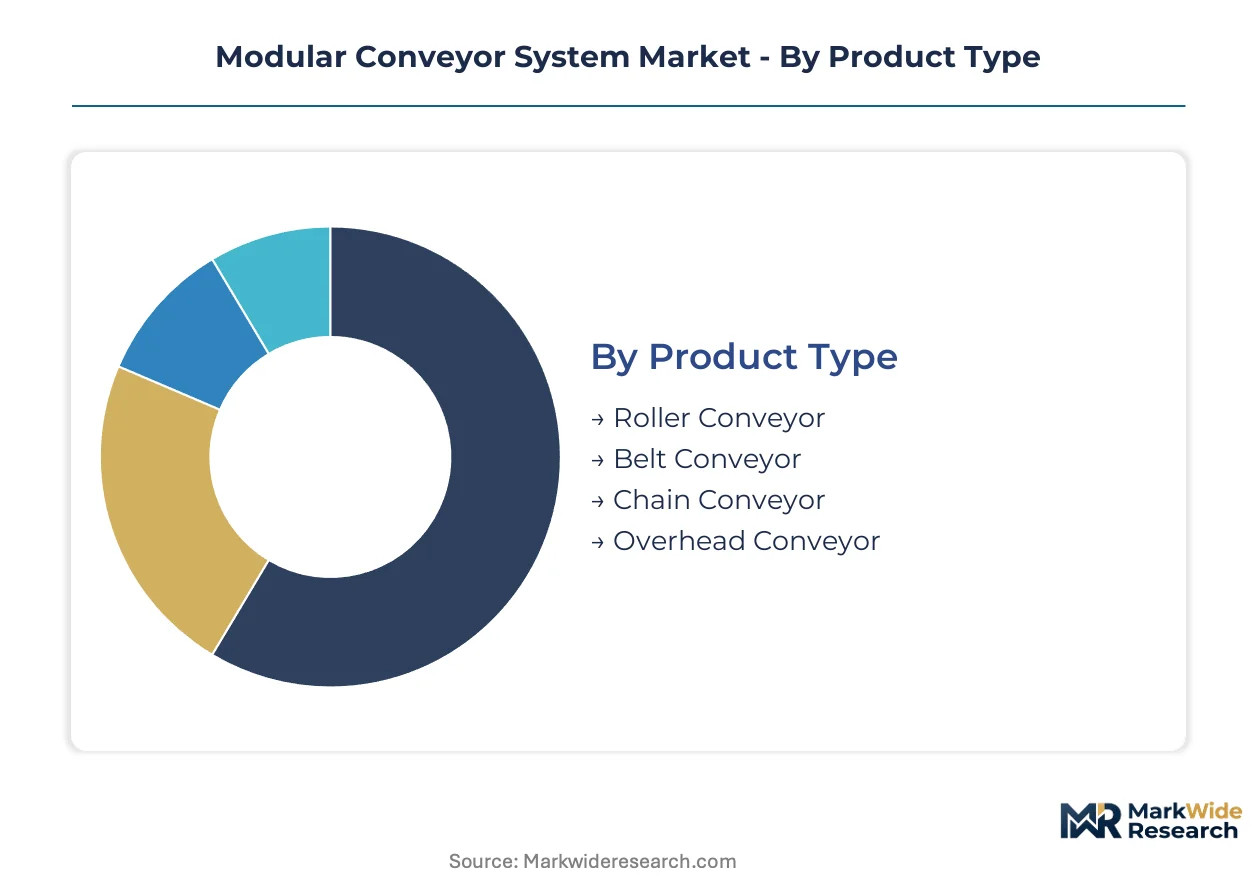
Modular conveyor system buyers prioritize different performance attributes based on their operational environment. Product type selection hinges on load characteristics and surface requirements. Technology tier reflects capital intensity and labor cost trade-offs. End user verticals impose distinct regulatory and throughput demands. Installation mode determines reconfiguration flexibility and compliance overhead.
Product Type:
Buyers in this category differentiate by load weight, surface continuity needs, and bearing durability requirements.
- Roller Conveyor:Steel-framed platforms with hardened bearing assemblies handle unit loads from 50 to 1,500 kilograms per linear meter. Automotive stamping plants in Germany specify these configurations where load cycles exceed one million operations annually.
- Belt Conveyor:Continuous polymer or fabric surfaces enable smooth transport at 0.5 to 2.5 meters per second with sanitary compliance for food-grade applications. Parcel sortation hubs specify belt modules where splice joint wear limits velocity above two meters per second.
- Chain Conveyor:Engineered link systems manage palletized loads and heavy assemblies through manufacturing cells. Metal-forming operations specify hardened chain pitches for abrasive environments.
- Overhead Conveyor:Trolley-mounted carriers free floor space in paint finishing and assembly operations. Automotive OEMs deploy these configurations for body-in-white transport through coating tunnels.
Volume sits with roller configurations; growth tilts toward belt systems in e-commerce fulfillment expansion.
Technology:
Capital deployment patterns separate buyers pursuing full automation from those balancing labor integration with mechanization.
- Automated:Servo-driven sections with programmable logic controllers enable unattended operation at sustained throughput rates. Distribution centers specify automated sortation modules where parcel volumes strain manual capacity.
- Manual:Gravity or minimal-motor configurations rely on operator push or decline momentum. Low-volume assembly operations specify these platforms where product mix changes preclude automation ROI.
- Hybrid:Interchangeable powered and non-powered sections allow workforce scaling against demand fluctuation. Third-party logistics providers specify hybrid architectures where order profiles shift unpredictably.
- Smart:Sensor-embedded drive units with cloud-connected monitoring deliver predictive maintenance visibility. Pharmaceutical distributors specify RFID-tracking configurations where lot traceability mandates require item-level accountability.
Deployment concentrates in automated tiers; expansion accelerates fastest in smart technology integration.
End User:
Regulatory burden and throughput velocity distinguish buyers across vertical applications.
- Manufacturing:Heavy-goods production lines specify steel-construction roller platforms with hardened bearing longevity. Automotive OEMs and appliance assemblers retrofit assembly lines with reconfigurable configurations.
- Warehousing:Distribution operations prioritize modular extension capability and quick-release sections for OSHA lockout-tagout compliance. Regional hubs specify belt and roller hybrids for parcel flow diversity.
- Food Processing:Sanitary-grade polymer belts with halogen-free compounds satisfy REACH substance restrictions and RoHS hazardous material limits. Reformulated PVC and polyurethane formulations maintain European market access.
- Pharmaceuticals:Sensor-enabled tracking with optical recognition ensures lot traceability through distribution networks. German automotive suppliers adopt these configurations to satisfy OEM inbound logistics requirements.
Revenue concentrates in manufacturing verticals; pharmaceutical applications gain share fastest on compliance-driven visibility investment.
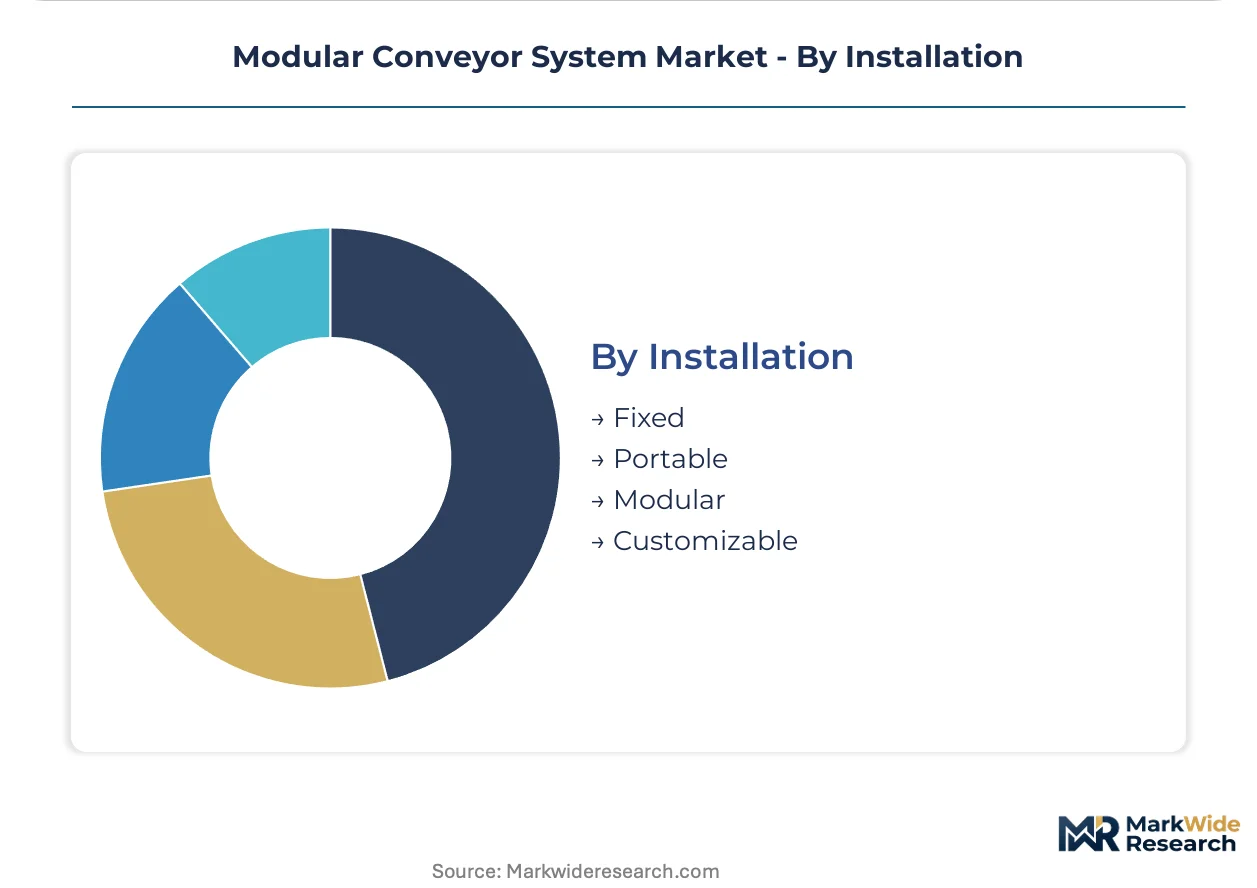
Installation:
Reconfiguration frequency and project timeline compression separate buyers in this category.
- Fixed:Permanent anchoring maximizes stability for high-volume, unchanging production flows. Legacy automotive lines retain these configurations where layout stability outweighs flexibility value.
- Portable:Castor-mounted or skid-based sections relocate without facility modification. Temporary fulfillment operations specify these platforms for seasonal capacity surges.
- Modular:Standardized interchangeability enables extension or reconfiguration without custom fabrication. Central European automotive OEMs and logistics providers compress deployment cycles from months to weeks.
- Customizable:Engineered-to-order sections address non-standard dimensions or environmental constraints. Clean-room and high-throughput material handling architectures specify these configurations.
Installed base remains fixed; new deployment tilts toward modular platforms on EU Machinery Directive compliance and reconfiguration velocity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Steel and aluminum feedstock clusters in Germany's Ruhr Valley and Baden-Württemberg anchor European conveyor manufacturing capacity. Component fabrication concentrates near automotive assembly corridors where just-in-time delivery requirements compress supplier lead times. Regional demand patterns diverge between mature retrofit markets and greenfield expansion zones.
Germany
Automotive OEMs and third-party logistics providers drive retrofit demand across assembly and distribution lines. The EU Machinery Directive and CE marking requirements mandate interlock switches and emergency-stop redundancy as standard features. Drum motor production clusters in Baden-Württemberg and Bavaria supply Central European integrators with drive units.
Poland
Greenfield automotive battery plants and appliance assembly facilities in Lower Silesia lack installed conveyor base, creating first-mover opportunities. REACH substance restrictions tighten specifications for polymer belt compounds entering European distribution networks. Manufacturing corridors near Wrocław attract modular platform vendors seeking unpenetrated production infrastructure.
Czech Republic
Moravian automotive suppliers expand inbound logistics capabilities to satisfy German OEM tier-one requirements. RoHS hazardous material limits accelerate reformulation of electronic drive components for European market access. Brno-Ostrava industrial zones witness distribution center automation investments as e-commerce fulfillment regionalizes.
United States
OSHA lockout-tagout standards require energy-isolation protocols during maintenance, favoring quick-release modular sections. Regional distribution hubs specify belt and roller hybrids for parcel flow diversity under strained manual handling capacity. Southeast manufacturing corridors attract appliance assembly investments with reconfigurable line requirements.
China
Dual carbon goals and GB standards push manufacturing facilities toward energy-efficient drive architectures. Yangtze River Delta electronics fulfillment centers adopt sensor-enabled tracking for lot traceability compliance. Shenzhen-Guangzhou logistics clusters compress deployment cycles through standardized platform procurement.
Modular Conveyor System Market Competitive Landscape
Global majors compete with regional champions across integration depth and specialization breadth. The vendor base stratifies between full-lifecycle intralogistics integrators and component-focused equipment fabricators. Three archetypes dominate: scale-driven distribution center specialists, clean-room and high-throughput material handling architects, and drum motor segment dominators. Competitive moves center on geographic expansion into underpenetrated manufacturing corridors and technology licensing for smart conveyor architectures.
Among Germany-based fabricators, SSI SCHÄFER GmbH and Interroll Holding AG exemplify divergent strategic positions. SSI SCHÄFER occupies the full-lifecycle integrator tier, bundling equipment, installation, and service accountability. Interroll anchors the component-specialist vector with drum motor production that powers modular roller conveyors. Daifuku Co., Ltd. represents the clean-room and high-throughput architecture archetype, competing through deep specialization in material handling environments requiring contamination control.
| Leading Market Players |
|---|
| Honeywell Intelligrated |
| SSI SCHÄFER |
| Daifuku Co., Ltd. |
| Siemens Logistics |
| Hytrol Conveyor Company, Inc. |
| Interroll Holding AG |
| Fives Group |
| Intralox, L.L.C. |
| FlexLink AB |
| Others |
Supply & Pricing Matrix
Certification-grade bifurcation between CE-marked premium platforms and unmarked economy configurations shapes both procurement economics and supplier sourcing patterns. German automotive OEMs pay substantial premiums for documented risk assessments and safeguard integration, while Polish greenfield facilities source basic roller assemblies from regional fabricators operating outside harmonized standards.
Pricing Analysis
Warranty and service-bundling arrangements separate full-lifecycle integrators from component-only suppliers. Three-tier pricing structure across premium, standard, and economy levels reflects CE marking status, bearing longevity ratings, and predictive maintenance inclusion. Cost compression in economy belt modules is intensifying because raw material index volatility cannot pass through fixed project contracts. Third-party logistics providers exhibit highest price sensitivity due to volume procurement leverage, while pharmaceutical distributors prioritize uptime guarantees over unit cost.
Supply Chain Analysis
Drum motor supply rests on Baden-Württemberg and Bavaria production clusters, with steel roller fabrication drawing from Ruhr Valley feedstock mills. Stainless steel and aluminum frame materials hinge on European smelter capacity, while polymer belt compounds source from specialized German and Italian compounders. Single-source vulnerability in servo drive units creates procurement risk during automotive capacity expansions. Distribution runs through OEM-direct channels for large installations and regional integrators for mid-scale retrofits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Drum motor and drive unit production bottlenecks in southern Germany prop pricing power for integrated platform vendors. Capacity constraints at bearing manufacturers limit expansion velocity for roller conveyor specialists.
For Market Incumbents: Deepen captive supply of hardened bearing assemblies through backward integration into Czech and Slovak component fabricators. Lock in multi-year polymer compound offtake agreements before REACH reformulation deadlines tighten. Sensor-naive equipment suppliers from Asia threaten premium positioning in smart conveyor segments. For New Entrants and Emerging Players: Polish automotive battery plant operators represent the most penetrable buyer archetype, lacking installed conveyor base and seeking rapid deployment without legacy system compatibility burdens. Target Moravian appliance assemblers through modular platform leasing models that convert capital expenditure to operational spending. Partner with regional system integrators for CE marking compliance rather than building certification capabilities in-house. For Investors and Strategic Acquirers: Re-rating potential sits with IoT-enabled predictive maintenance specialists given the shift from break-fix contracts to uptime-guarantee service models. Long-term viability favors vendors bundling equipment, installation, and lifecycle accountability under single-source arrangements. Watch for consolidation signals when intralogistics integrators acquire component specialists to close technology gaps.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bearing Manufacturing | Captive supply of hardened assemblies insulates margin from steel price volatility. |
| Predictive Maintenance Platform Launch | Cloud-connected sensor networks convert equipment sales to recurring service revenue. |
| CE Marking Acceleration Program | Streamlined conformity assessment compresses time-to-market versus custom-engineered alternatives. |
| Polish Manufacturing Corridor Expansion | Greenfield battery plants in Lower Silesia lack installed base and seek rapid deployment. |
| Halogen-Free Material Certification | REACH-compliant polymer formulations maintain European market access for food processing segments. |
Research Methodology
Multi-period observation of OEM procurement patterns, integrator backlog data, and CE marking certification timelines anchored the trend analysis, supplemented by interviews with plant engineers at automotive stamping facilities, aftermarket service heads at third-party logistics providers, procurement teams at appliance manufacturers, and technical R&D directors at polymer compounders. Secondary validation drew from EU Machinery Directive implementation reports, OSHA lockout-tagout enforcement data, customs records for steel and aluminum conveyor components, and SEC filings from listed material handling equipment vendors. Bottom-up demand modeling triangulated against top-down industrial capital expenditure surveys.
Segment-weighting across product type, technology tier, end-use vertical, and installation mode informed volume distribution assumptions throughout the forecast period. Roller, belt, chain, and overhead configurations each carried distinct growth trajectories based on load characteristics and surface requirements. CAGRs were derived from installed base replacement cycles, greenfield expansion pipelines, and technology upgrade adoption curves. Steel input price indices and REACH regulatory compliance costs fed directly into margin compression scenarios.
Revisions become necessary when raw material price volatility exceeds contract pass-through thresholds, when EU harmonized standards introduce new safeguard requirements, or when mechatronics technician scarcity constrains deployment velocity. Forecasts reflect documented assumptions about automotive production schedules, e-commerce fulfillment center buildouts, and regulatory enforcement intensity. A small set of triggers—battery plant investment announcements, CE marking directive amendments, and bearing manufacturer capacity expansions—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Apron Feeder Market
Material Handling Equipment
Outdoor Power Equipment (OPE) Market
Material Handling Equipment
Hydraulic Hose and Fittings Market
Material Handling Equipment
Industrial Hoists Market
Material Handling Equipment
Global Submersible Slurry Pumps Market
Material Handling Equipment
Slitting Machines Market
Material Handling Equipment
Elevator Component Market
Material Handling Equipment
Middle East and Africa Conveyors Market
Material Handling Equipment
Mining Hoses Market
Material Handling Equipment
Vibrating Conveyor Market
Material Handling Equipment
Global Cargo Handling Equipment Market
Material Handling Equipment
Dynamic Compactor Market
Material Handling Equipment
Pick and Carry (PNC) Crane Market
Material Handling Equipment
Copper and Aluminum Welding Bar Market
Material Handling Equipment
United States Hand Holes Market
Material Handling Equipment
Pipelayer Market