
 Silo Bin Activators Market | 2026-2036
Silo Bin Activators Market Size, Share, and Industry Trends Forecast 2026-2036
Silo Bin Activators Market Insights
Modular retrofit kits is expanding as the dominant configuration pattern across silo bin activator procurement, letting processors upgrade legacy vessels without full replacement. WAMGROUP leverages its European manufacturing footprint to anchor premium vibratory lines across cement and chemical accounts. General Kinematics competes through heavy-duty mechanical designs purpose-built for mining duty cycles. Schenck Process specializes in integrated weighing-activation systems that extend its control over continuous process lines.
A silo bin activator is a discharge aid device mounted to the bottom or sidewall of bulk storage silos, typically employing vibratory motors generating centrifugal forces between 500 and 3,000 rpm to break arching and ratholing in cohesive powders. Its primary industrial purpose is to ensure controlled, continuous mass flow of bulk solids into downstream conveying, dosing, or processing equipment. Vibratory configurations dominate installed base owing to simpler maintenance and lower energy draw, while electromechanical variants capture the fastest growth in pharmaceutical manufacturing where precise discharge control aligns with batch integrity requirements. Bottom-mounted designs concentrate margin pools in cement production, where high-capacity continuous discharge commands premium positioning over external retrofit mounts.
The US OSHA combustible dust standards and EU ATEX directives shape product design, forcing ignition-proof motor enclosures and static-dissipating elastomer seals in chemical and food applications. India's BIS bulk handling equipment codes and China's GB mechanical vibration standards further segment market access, with compliance costs filtering smaller fabricators from pharmaceutical and mining contracts. Stakeholders must weigh regional certification breadth against platform standardization when configuring regional assembly footprints.
Market Dynamics
Modular retrofit architectures are compressing replacement cycles across silo infrastructure, forcing incumbent suppliers to reconfigure service revenue models around upgrade kits rather than full-vessel sales.
Growth Catalysts
- BIS bulk handling codes:India's tightening material flow standards compel cement producers to retrofit existing silos with compliant discharge aids, creating replacement demand across thousands of installed vessels.
- Pharmaceutical batch integrity requirements:Precise discharge control mandates in sterile powder processing pull electromechanical activator configurations into high-value manufacturing lines.
- Germany's industrial corridor concentration:Dense chemical and mineral processing clusters generate sustained procurement volume for heavy-duty vibratory units with integrated weighing systems.
Market Restraints
- Stainless steel price volatility:Food-grade and pharmaceutical activator fabrication depends on 304/316L sheet metal, exposing margins to commodity swings.
- EU ATEX compliance costs:Ignition-proof motor enclosures and static-dissipating seals add 15-25% to base unit economics, filtering smaller fabricators from chemical contracts.
- Air cannon substitution in mining:High-pressure pneumatic discharge aids compete on capital cost for coarse, non-cohesive bulk solids in Australian and South African extraction operations.
Strategic Opportunities
- China's dual carbon goals:Energy efficiency mandates in building materials processing favor low-draw vibratory designs over pneumatic alternatives in new cement plant construction.
- Integrated weighing-activation convergence:Combined discharge and gravimetric measurement systems capture premium positioning in continuous process lines where batch accuracy determines product quality.
- Aftermarket digital retrofit channels:IoT-enabled condition monitoring kits open recurring revenue streams among installed base owners seeking predictive maintenance capabilities without full replacement.
Industry Challenges
- Vibration analysis technician scarcity:Proper commissioning and troubleshooting of variable-frequency drives requires specialized skills concentrated among aging workforce cohorts in mature industrial economies.
- Legacy silo structural assessment complexity:Retrofit mounting feasibility depends on vessel wall thickness and weld integrity evaluation, extending sales cycles and requiring third-party engineering validation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Silo Bin Activators Market |
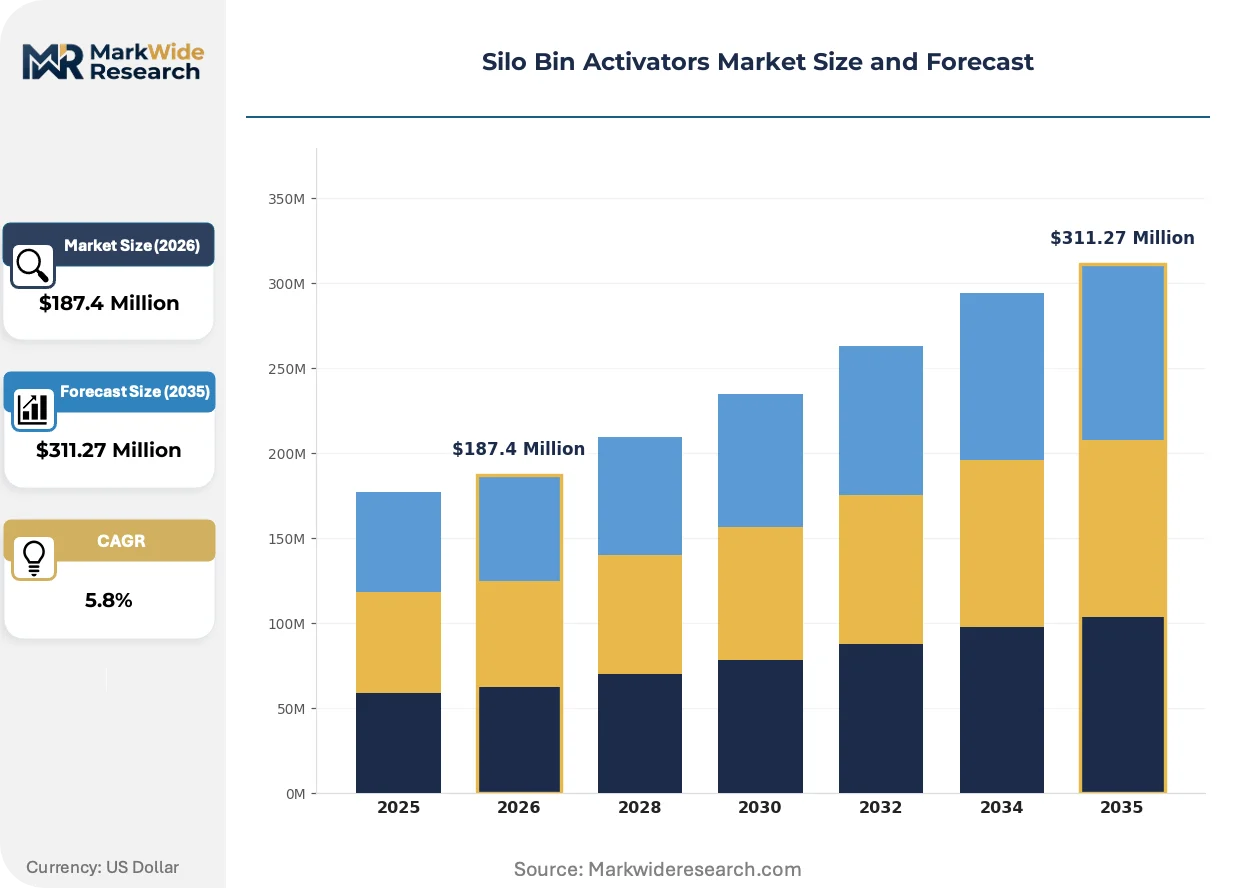
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vibratory, Pneumatic, Mechanical, Hydraulic, Electromechanical Application: Bulk Material Handling, Pharmaceutical Manufacturing, Food Processing, Cement Production, Chemical Processing Mounting Type: External, Internal, Sidewall, Bottom Mounted End User Industry: Mining Operations, Food & Beverage Plants, Construction Firms, Chemical Plants |
| Companies Covered | Vibra Screw, General Kinematics, Carmeuse Systems, Indpro, WAMGROUP, Schenck Process, Carrier Vibrating Equipment, Spiroflow, Vibra Dynamics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Silo Bin Activators Market Trends and Innovations
Intelligent actuation and predictive diagnostics are redefining equipment lifecycle economics, compressing the traditional divide between mechanical hardware and process control systems.
Variable-frequency drive technology is expanding into silo bin activator motor control, enabling real-time adjustment of centrifugal force output to match changing material properties. Cement producers in India and Germany are adopting these systems to handle seasonal moisture variations in raw meal without manual intervention. The technology is expanding into premium positioning across continuous-process installations where unplanned discharge interruption carries six-figure hourly costs.
REACH chemical safety regulations and EU ATEX directives are mandating expanded material disclosure and ignition-risk documentation for elastomer seals and motor housings. Chemical processors must now trace polymer compound compositions through supply chains to demonstrate compliance with restricted substance lists. Food and pharmaceutical activator lines face the steepest compliance burden, driving specification consolidation toward pre-certified component platforms from established European suppliers.
Buyers are unbundling after-sales service from initial equipment procurement, contracting vibration analysis and spare parts logistics to third-party specialists rather than OEM service networks. Mining operators in Australia and cement groups in India lead this disintermediation, using independent maintenance firms to reduce total cost of ownership across multi-site fleets. The shift pressures traditional suppliers to compete on component availability and technical documentation transparency rather than captive service lock-in.
Silo Bin Activators Market Segmentation
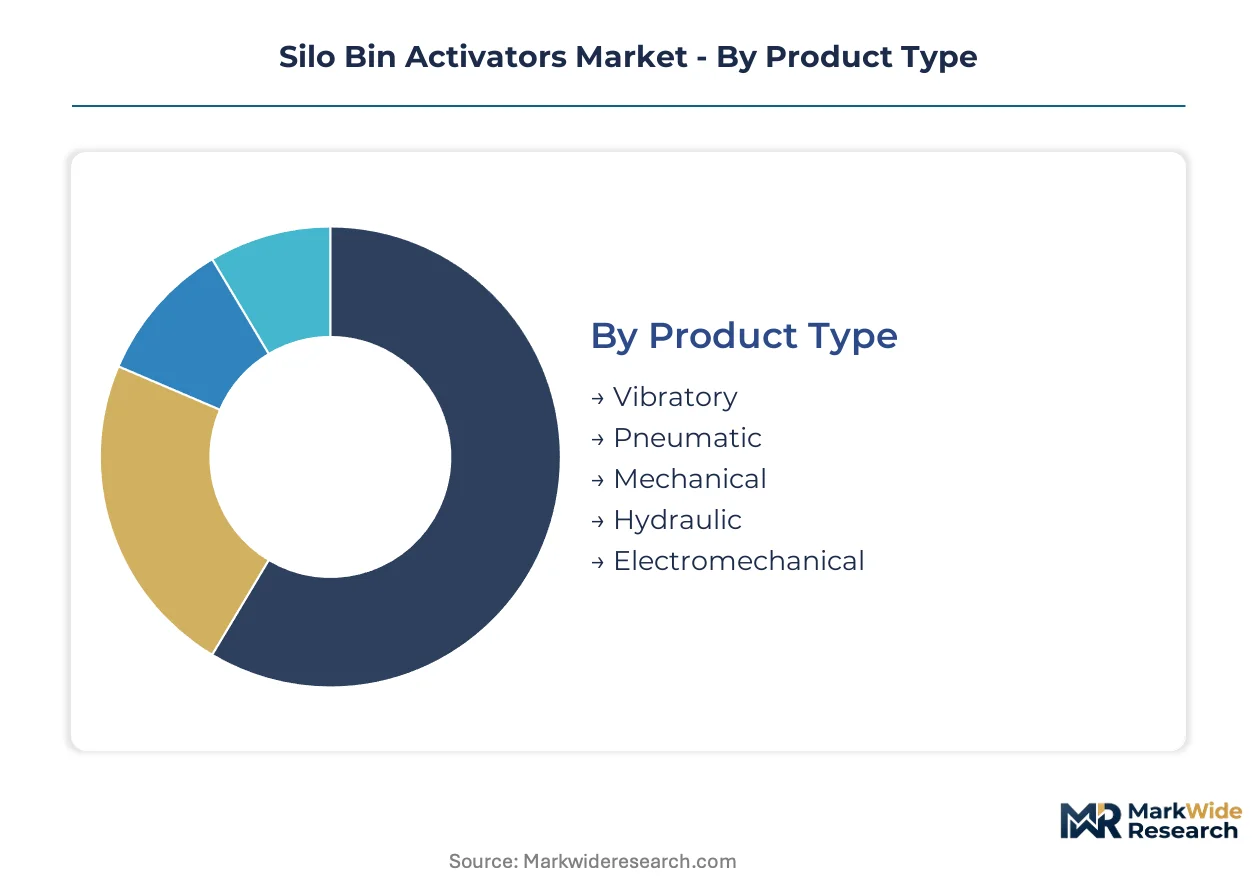
Silo bin activator procurement patterns diverge sharply across operational contexts, with material cohesiveness dictating drive technology selection and vessel geometry constraining mounting configurations. Buyers prioritize retrofit compatibility or integrated weighing precision depending on whether they operate legacy infrastructure or greenfield continuous process lines.
Product Type:
Cost tier separates commodity procurement from premium specification, with energy draw and maintenance intervals driving total ownership calculations across industrial buyer segments.
- Vibratory:Centrifugal force generation between 500 and 3,000 rpm breaks arching in cohesive powders through oscillating motion transmitted via elastomer isolators. Cement producers in India favor these units for seasonal raw meal handling where moisture fluctuations demand adjustable output without compressed air infrastructure. Volume sits with this configuration across installed base.
- Electromechanical:Servo-controlled discharge mechanisms deliver precise batch integrity for sterile powder processing through programmable stroke and speed parameters. Pharmaceutical manufacturers in Germany's industrial corridor specify these systems where gravimetric accuracy determines regulatory compliance and product quality. Growth tilts toward this segment as batch processing expands.
- Pneumatic:Compressed air pulses discharge coarse non-cohesive solids in mining extraction environments where capital cost sensitivity outweighs energy efficiency priorities.
- Mechanical:Heavy-duty rotating agitators handle abrasive mineral concentrates in Australian and South African operations with extended duty cycles.
- Hydraulic:High-torque drive systems manage extremely cohesive materials in specialty chemical applications requiring force levels beyond electromechanical limits.
Procurement volume clusters around vibratory platforms; specification premiums concentrate with electromechanical and hydraulic alternatives.
Application:
Customer type shapes performance requirements, with continuous-process operators demanding uninterrupted mass flow while batch manufacturers prioritize discharge precision over throughput volume.
- Cement Production:High-capacity bottom-mounted configurations handle raw meal, clinker, and finished cement through 24/7 continuous discharge into pneumatic conveying or bulk loading systems. India's BIS certification tightening drives replacement demand across thousands of installed silos as material flow standards elevate compliance burdens. Volume concentrates here.
- Pharmaceutical Manufacturing:Electromechanical activators with integrated weighing systems ensure batch integrity in sterile powder processing where FDA and EMA validation protocols govern equipment qualification. Precise discharge control prevents cross-contamination and dosage variation in high-value active pharmaceutical ingredient handling. Premium positioning dominates.
- Bulk Material Handling:General-purpose vibratory units serve grain, feed, and aggregate storage across distributed agricultural and construction supply chains.
- Food Processing:Stainless steel 304/316L construction with FDA-compliant elastomer seals handles flour, sugar, and dairy powders subject to USDA and FSSAI sanitation mandates.
- Chemical Processing:ATEX-rated ignition-proof enclosures and static-dissipating components manage combustible dust hazards in EU and US regulatory jurisdictions.
Replacement cycles compress in cement; specification complexity escalates in pharmaceutical and chemical segments.
Mounting Type:
Margin structure reflects installation labor intensity and structural engineering requirements, with external retrofits minimizing vessel modification against bottom-mounted premium positioning.
- Bottom Mounted:Direct integration with silo cone section maximizes discharge efficiency and flow pattern control in new construction and major vessel rebuilds. Cement producers specify these configurations for high-capacity continuous operations where unplanned interruption carries substantial hourly costs. Premium economics apply.
- External:Retrofit mounting avoids internal vessel entry, reducing installation downtime and structural assessment complexity for legacy silo upgrades. Modular kit architectures enable phased procurement across multi-site cement and mining fleets. Volume expansion accelerates here.
- Internal:Space-constrained installations in existing chemical and food plants where external clearance is unavailable.
- Sidewall:Specialized applications addressing localized bridging in non-conical vessel geometries or supplemental activation for sluggish zones.
External mounts capture retrofit momentum; bottom-mounted systems defend margin in greenfield specifications.
End User Industry:
Supply concentration aligns with regional industrial clustering, with Germany's chemical corridor and India's cement belt generating differentiated procurement patterns.
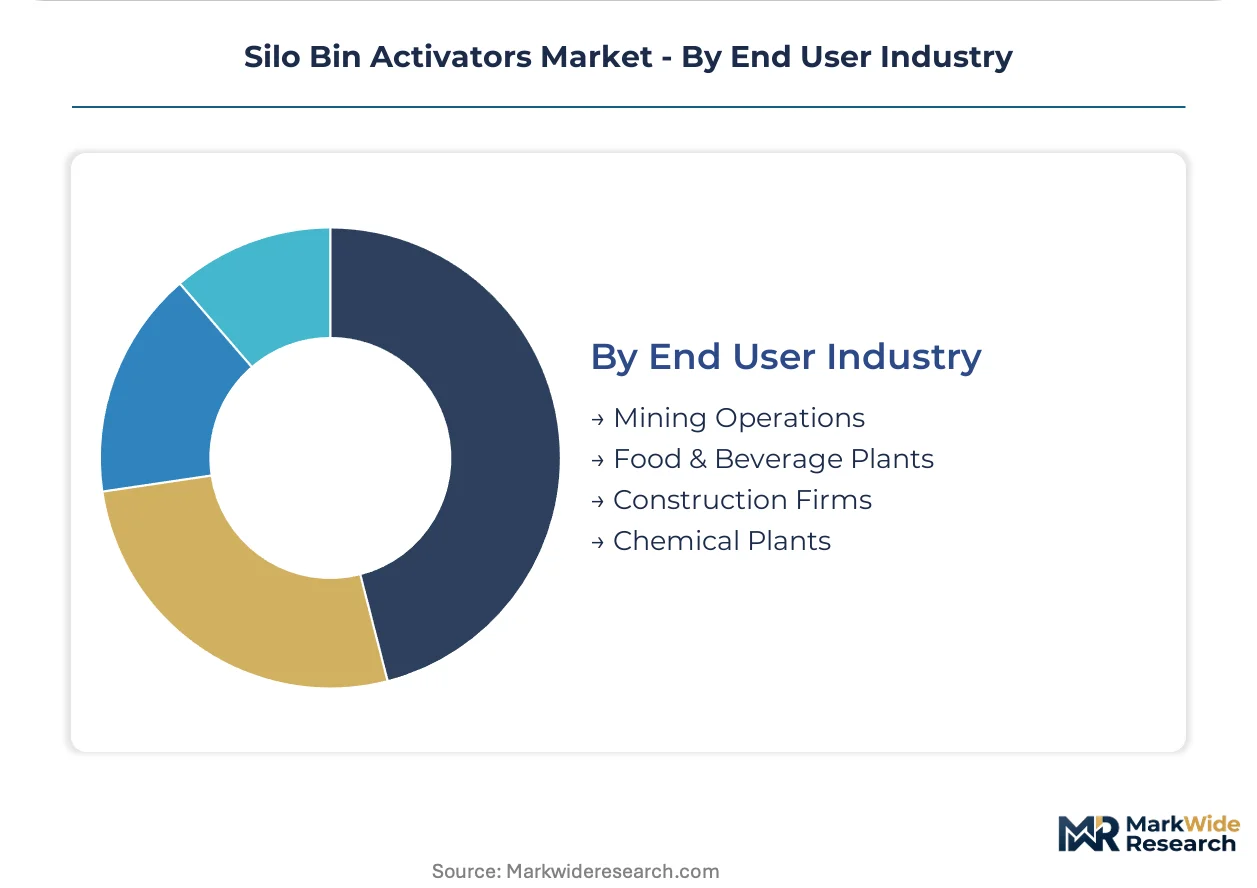
- Mining Operations:Heavy-duty mechanical and pneumatic configurations handle coarse, abrasive concentrates in Australian iron ore and South African platinum extraction. Air cannon substitution pressure limits vibratory penetration in coarse non-cohesive applications. Volume anchors here.
- Chemical Plants:ATEX-compliant electromechanical and hydraulic systems serve EU REACH-regulated operations where ignition risk documentation and polymer traceability dominate specification requirements. Schenck Process and WAMGROUP compete through pre-certified component platforms. Value concentration intensifies.
- Construction Firms:Mobile and semi-permanent silo installations for ready-mix concrete and mortar production favor standardized vibratory units with rapid deployment capability.
- Food & Beverage Plants:Sanitary design requirements and stainless steel fabrication expose margins to commodity price volatility while FDA and FSSAI compliance drives specification consolidation toward established European suppliers.
Mining commands unit volume; chemical and food segments extract specification premiums through compliance complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentration tilts toward Germany and India's industrial corridors, while consumption demand clusters around cement belts in South Asia and mining extraction zones in Australia. Production capabilities align with regional regulatory stringency, creating compliance-driven supply segmentation.
Germany
Electromechanical activator demand concentrates in the North Rhine-Westphalia chemical corridor, where continuous-process manufacturers require integrated weighing systems. REACH chemical safety regulations and EU ATEX directives mandate ignition-proof motor enclosures and polymer traceability documentation. The Ruhr industrial cluster generates sustained procurement volume for heavy-duty units serving pharmaceutical and specialty chemical operations.
India
Cement producers across Rajasthan and Gujarat drive vibratory unit adoption as BIS bulk handling equipment codes tighten material flow compliance standards. The Bureau of Indian Standards certification requirements compel retrofitting of thousands of installed silos with compliant discharge aids. The Mumbai-Pune industrial belt anchors demand for modular external-mount configurations that minimize vessel downtime during upgrades.
United States
OSHA combustible dust standards shape product design for chemical and food processing applications, requiring static-dissipating elastomer seals and explosion-proof enclosures. The Gulf Coast petrochemical corridor generates demand for ATEX-rated systems in export-oriented operations. Texas and Louisiana processing clusters favor variable-frequency drive technology to handle seasonal feedstock variations.
China
Dual carbon goals and GB mechanical vibration standards favor low-energy vibratory designs over pneumatic alternatives in new cement plant construction. The Yangtze River Delta manufacturing base supplies standardized units for domestic construction material processing. Shandong Province's building materials belt concentrates procurement for high-capacity bottom-mounted configurations.
Australia
Mining extraction operations in Western Australia's Pilbara region deploy heavy-duty mechanical activators for coarse iron ore concentrates. Air cannon substitution pressure limits vibratory penetration in non-cohesive bulk solids handling. The Queensland coal belt maintains demand for pneumatic discharge aids where capital cost sensitivity outweighs energy efficiency priorities.
Silo Bin Activators Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base organizes around three strategic archetypes: European engineering houses with pre-certified component platforms, North American heavy-duty specialists serving mining duty cycles, and Asian fabricators competing on modular retrofit economics. Competitive moves concentrate on geographic expansion through distribution partnerships and portfolio diversification into integrated weighing-activation systems.
Among European engineering houses, WAMGROUP and Schenck Process occupy positions anchored by regulatory pre-certification and control system integration. General Kinematics represents the North American heavy-duty archetype with mechanical designs purpose-built for abrasive mineral processing. These three exemplify how competitive positioning splits between compliance-driven specification premiums and durability-focused total cost of ownership.
| Leading Market Players |
|---|
| Vibra Screw |
| General Kinematics |
| Carmeuse Systems |
| Indpro |
| WAMGROUP |
| Schenck Process |
| Carrier Vibrating Equipment |
| Spiroflow |
| Vibra Dynamics |
| Others |
Pricing and Supply Chain Analysis
Variable-frequency drive adoption in vibratory motor control is compressing cost economics while concentrating procurement leverage among German and Italian component suppliers. Cement producers in India and chemical processors in Germany now demand real-time force adjustability, forcing fabricators to standardize on pre-certified VFD platforms or exit premium tiers.
Pricing Analysis
Margin tightening in food-grade and pharmaceutical tiers reflects 304/316L stainless steel commodity exposure and EU ATEX certification overhead. Pricing stratifies across ATEX-certified electromechanical, standard vibratory, and non-certified economy tiers. Cost-down pressure on economy vibratory units accelerates because Indian and Chinese fabricators compete on modular retrofit kit economics. Mining operators in Australia exhibit highest price sensitivity; pharmaceutical manufacturers in Germany show least.
Supply Chain Analysis
Single-source vulnerability sits with Italian vibratory motor specialists and German precision servo manufacturers. Component fabrication concentrates in Germany, Italy, and China. Raw material inputs draw from Swedish specialty steel mills, Malaysian natural rubber plantations, and Chinese rare-earth magnet processors. Supply chain risk centers on EU REACH documentation delays for polymer compound traceability. Distribution runs through regional industrial equipment distributors with captive service networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race. Players are pursuing backward integration into vibration motor manufacturing to escape component margin capture by Italian and German specialists.
For Market Incumbents: To counter air cannon substitution in Australian and South African mining, WAMGROUP and Schenck Process should deepen captive supply of heavy-duty mechanical agitators and expand ATEX-certified component platforms. Certification investment in India's BIS codes defends replacement cycle capture as cement retrofit demand surges. For New Entrants and Emerging Players: Capture modular external-mount retrofit demand across India's Rajasthan-Gujarat cement belt and Australia's Queensland coal operations. The most penetrable segment is aftermarket IoT-enabled condition monitoring kits for legacy vibratory installations. A go-to-market angle through independent maintenance firms bypasses OEM service lock-in. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified industrial conglomerates seeking bulk handling portfolio expansion. Long-term viability favors targets with pre-certified European component platforms and installed base service contracts. Watch BIS enforcement intensity in India as inflection indicator for replacement cycle velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Vibration Motor Manufacturing | Reduces dependency on Italian and German component suppliers while capturing margin pools in electromechanical configurations. |
| ATEX Certification Investment | Opens EU chemical and pharmaceutical procurement channels where REACH documentation mandates filter uncertified competitors. |
| IoT-Enabled Condition Monitoring Launch | Creates recurring revenue streams among cement and mining fleet operators seeking predictive maintenance without full replacement. |
| Modular External-Mount Kit Expansion | Aligns with India's BIS-driven retrofit surge by minimizing vessel downtime and structural assessment complexity. |
| Joint Venture with Regional Distributors | Secures channel control in Germany's North Rhine-Westphalia chemical corridor and India's Mumbai-Pune industrial belt. |
Research Methodology
Independent corroboration across maintenance directors at cement plants, procurement leads at pharmaceutical manufacturers, and aftermarket service heads at mining operations underwrites the qualitative findings. Primary interviews with plant engineers and OEM procurement teams combined with secondary validation from customs trade data, BIS certification registries, and SEC filings of diversified industrial conglomerates. Bottom-up unit economics triangulated against top-down sector expenditure patterns.
Rate-of-change decomposition across the projection horizon separates volume growth from mix-shift toward premium electromechanical configurations. The analytical framework models product type, mounting configuration, end-user industry, and regional regulatory cluster. CAGRs derive from installed base replacement cycles, greenfield cement capacity additions, and pharmaceutical batch processing expansion. Forecast inputs include BIS enforcement timelines and EU ATEX compliance cost trajectories.
The model holds under steady regulatory enforcement and stable stainless steel pricing; deviation in India's BIS certification pace or commodity volatility would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Global Warehouse Racking Market
Material Handling Equipment
Ball Screw Support Unit Market
Material Handling Equipment
Log Loaders Market
Material Handling Equipment
Sifter Fitment Market
Material Handling Equipment
Air Hose Market
Material Handling Equipment
Global Air Cannon System Market
Material Handling Equipment
Electric Single Beam Crane Market
Material Handling Equipment
Weighbridge Market
Material Handling Equipment
Modular Conveyor System Market
Material Handling Equipment
Can Racks Market
Material Handling Equipment
Spring Shackles Market
Material Handling Equipment
Global Conveyors Market
Material Handling Equipment
Australia Forklift Rental Market
Material Handling Equipment
Elevator Component Market
Material Handling Equipment
Rotary Breaker Market
Material Handling Equipment
Drag Chain for Machine Market