
 Slag Handling Equipment Market | 2026-2036
Slag Handling Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Slag Handling Equipment Market Intelligence
The gap between premium and commodity slag handling equipment is restructuring around metallurgical durability standards and automation depth. Harsco Corporation leverages its vertical integration into slag processing services to sustain pricing power in high-temperature applications. Konecranes anchors its position through electromechanical crane systems for steel plants, while CHAENG (Great Wall Machinery) competes on captive foundry-to-equipment manufacturing scale in China.
Slag handling equipment encompasses specialized machinery for transporting, cooling, and processing molten slag generated during iron and steel production, typically operating at temperatures exceeding 1,200 degrees Celsius and requiring refractory-lined vessels and heat-resistant structural components. Slag pots and grab buckets dominate capital expenditure due to their irreplaceable role in blast furnace tapping cycles, while hydraulic technology leads operational deployments for precise load control under thermal stress. Conveyors represent the fastest-growing product category as continuous slag cooling lines displace batch handling in new steel plant builds.
EPA regulations under the Clean Air Act and MEE emissions standards in China compel steel producers to upgrade slag handling systems for reduced particulate release and improved energy recovery. OSHA workplace safety rules and ISO 45001 frameworks further shape equipment design for operator protection in extreme thermal environments. Stakeholders must monitor how carbon border adjustment mechanisms and green steel certification programs redirect procurement criteria toward slag valorization-compatible handling systems.
Market Dynamics
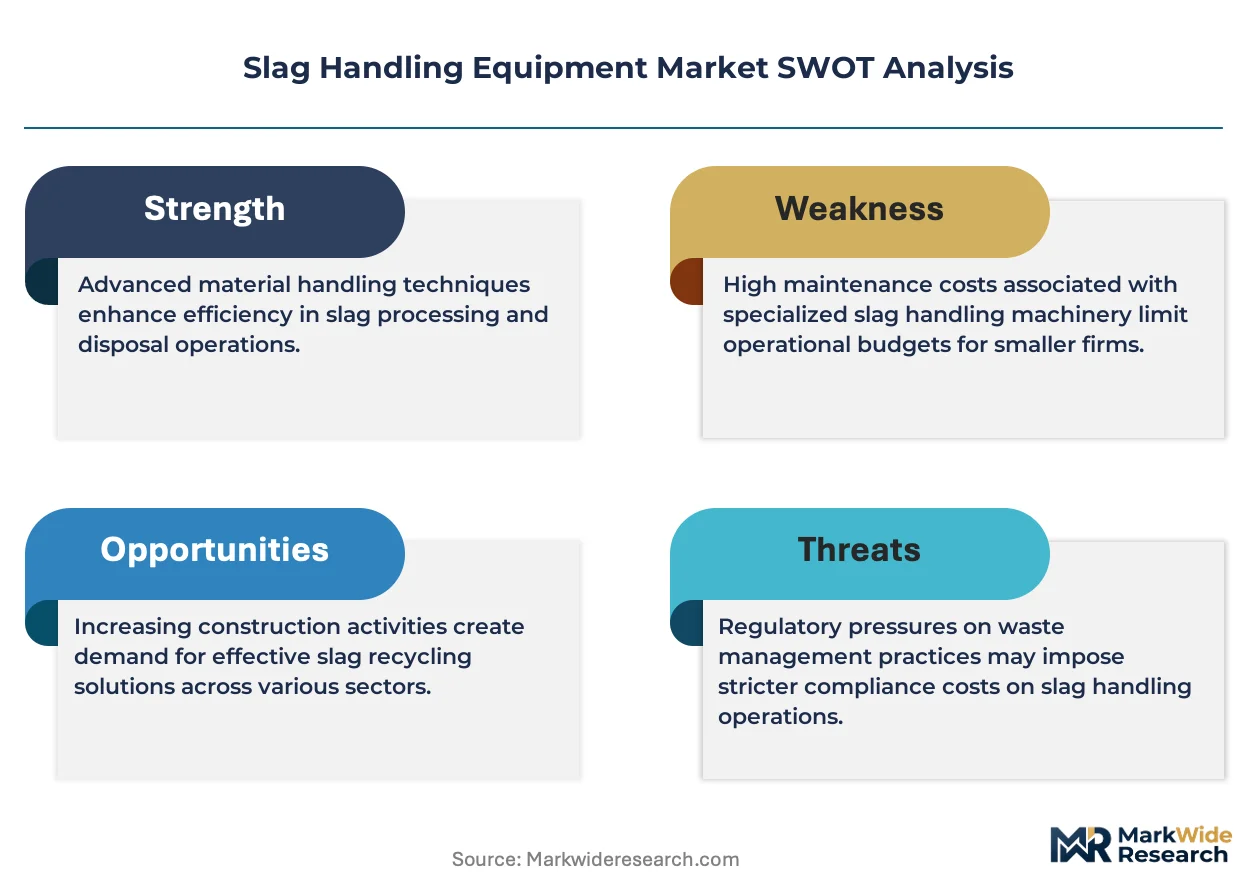
Blast furnace operators are consolidating procurement around slag handling systems that integrate heat recovery and particulate capture, compressing vendor margins while elevating technical certification requirements for equipment longevity above 1,200°C operational thresholds.
Growth Catalysts
- EPA Clean Air Act enforcement:Steel producers in the US face escalating penalties for fugitive emissions during slag tapping, accelerating replacement of open-pit cooling with enclosed conveyor systems.
- Hydraulic precision controls:Integrated steel mills deploy sensor-equipped slag pot carriers to reduce thermal shock damage and extend refractory lining life cycles.
- China's MEE dual carbon mandates:Provincial environmental bureaus tie production permits to slag energy recovery rates, forcing upgrades at Baosteel and Shagang facilities.
Market Restraints
- Nickel alloy cost volatility:Heat-resistant structural components depend on nickel-chromium alloys subject to London Metal Exchange price swings, destabilizing equipment manufacturer margins.
- Refractory supply concentration:Magnesia-carbon brick production clusters in Liaoning province, creating single-source vulnerability for slag pot lining replacement cycles.
- Blast furnace capacity retirement:Electric arc furnace expansion in North America and Europe reduces addressable demand for traditional slag handling infrastructure.
Strategic Opportunities
- India's secondary steel expansion:Induction furnace operators in Gujarat and Tamil Nadu lack standardized slag cooling infrastructure, creating first-mover equipment installation potential.
- Slag valorization integration:Cement producers seeking granulated blast furnace slag as clinker substitute require handling systems compatible with rapid quenching for glassy phase retention.
- EU Carbon Border Adjustment Mechanism:Imported steel faces embedded emissions tariffs, incentivizing European mills to document slag processing efficiency for green certification.
Industry Challenges
- Refractory installation specialist shortage:Qualified crews for ceramic welding and gunning application at extreme temperatures command premium wages, extending equipment commissioning timelines.
- ISO 45001 audit complexity:Thermal stress monitoring and confined space protocols for slag pit maintenance require documentation systems many mid-size fabricators lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Slag Handling Equipment Market |
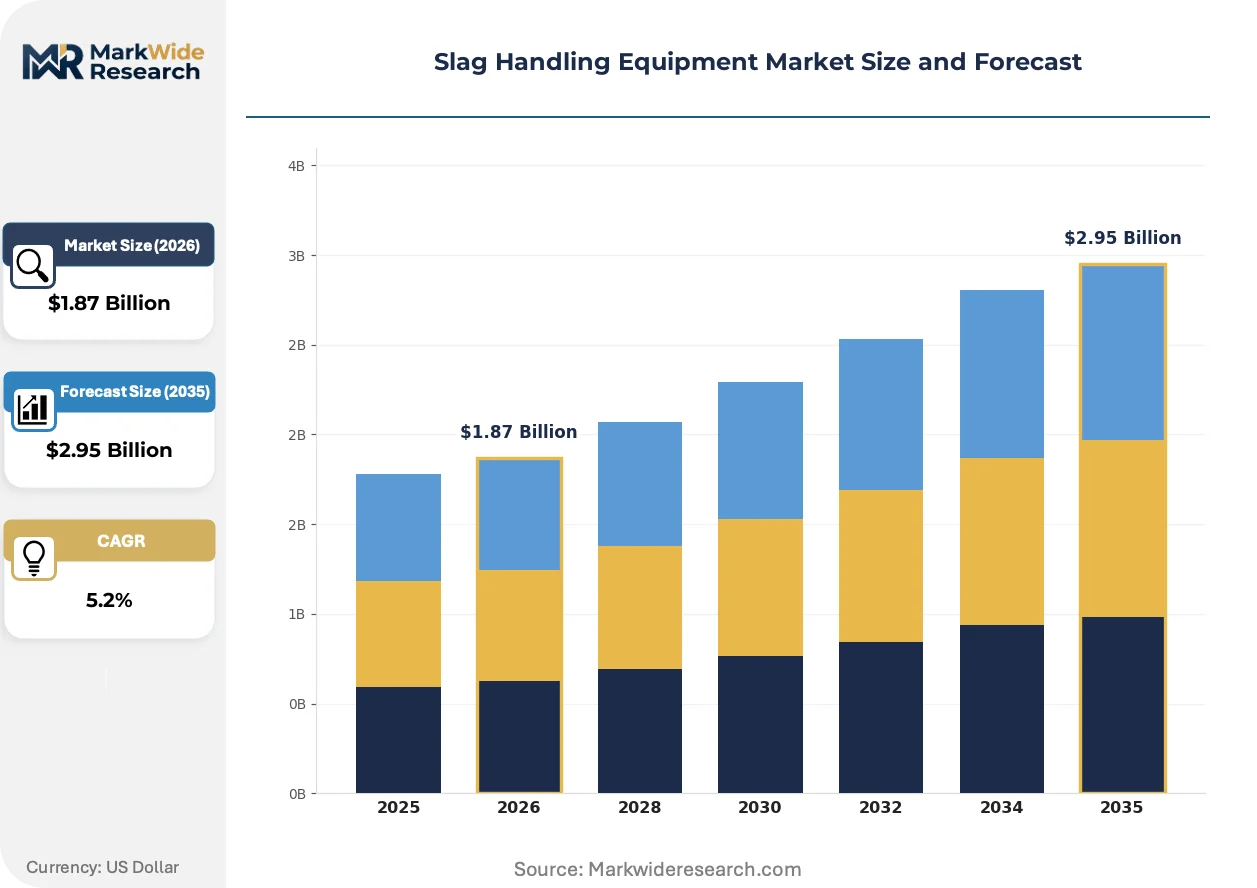
| Market Size in 2026 | $1.87 Billion |
| Market Size in 2035 | $2.95 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Scrapers, Grab Buckets, Slag Pot, Conveyors Technology: Hydraulic, Pneumatic, Electromechanical, Manual Installation: Permanent, Mobile, Semi-permanent, Fixed End User: Steel Plants, Foundries, Metal Processing, Recyclers |
| Companies Covered | AFEX Fire Suppression Systems, ALTA, American Crane and Equipment Corp, BHS-Sonthofen, Dongqi Group, Harsco Corporation, Konecranes, CHAENG (Great Wall Machinery), CITIC Heavy Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Slag Handling Equipment Market Strategic Shifts & Innovations
Equipment architecture is pivoting from standalone mechanical systems toward integrated thermal management platforms that capture waste heat and automate particulate containment, reshaping vendor R&D priorities and buyer total-cost-of-ownership calculations.
Continuous slag cooling conveyors with integrated heat exchangers are overtaking batch pot-handling cycles in new greenfield steel plant construction. Posco and JFE Steel have specified closed-loop conveyor systems for recent furnace expansions in Pohang and Fukuyama. This shift is compressing demand for traditional slag pot carriers while expanding the addressable market for refractory-lined conveyor components and auxiliary cooling infrastructure.
China's MEE has tightened particulate emission limits for ferrous metallurgy operations, compelling steel mills to enclose slag transport corridors and install baghouse filtration. The regulation forces capital allocation toward containment infrastructure rather than production capacity. Hydraulic slag pot carriers with sealed transfer mechanisms now dominate procurement specifications at Hebei and Jiangsu province mills.
Steel producers are unbundling after-sales service contracts from original equipment purchases, creating standalone revenue streams for refractory maintenance and thermal monitoring. Equipment vendors face pressure to certify local service networks or lose multi-year maintenance agreements to third-party specialists. This pattern is most pronounced in Germany and Japan, where integrated mills outsource non-core maintenance functions to reduce fixed labor costs.
Slag Handling Equipment Market Segmentation
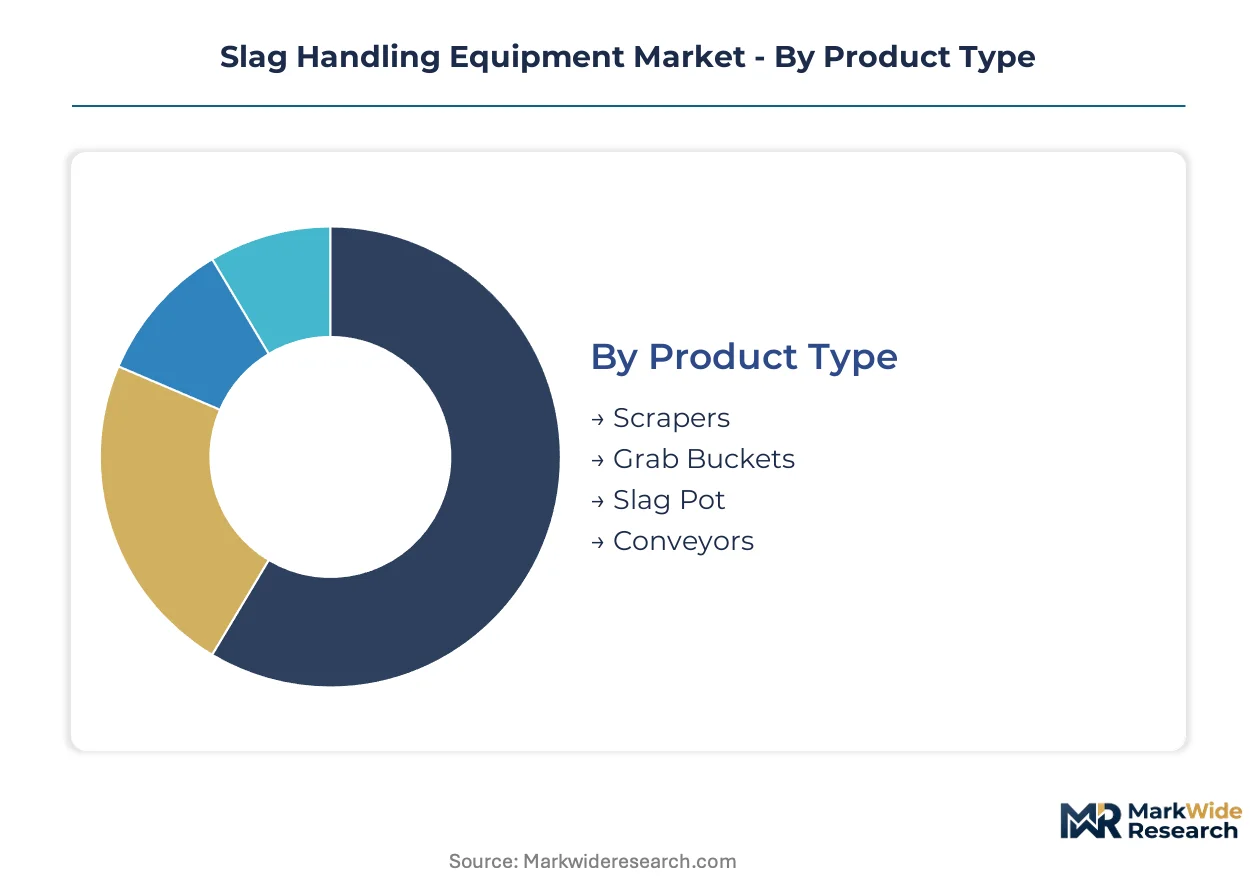
Slag handling equipment procurement decisions hinge on thermal load requirements, operational flexibility needs, and integration complexity with existing furnace infrastructure. Capital allocation patterns across segments reveal where steel producers prioritize durability over adaptability.
Product Type:
Capital intensity peaks with refractory-lined vessels requiring metallurgical-grade steel castings and ceramic welding expertise.
- Scrapers:Mechanized raking systems remove cooled slag crust from pit floors using hardened alloy teeth. Demand clusters at ThyssenKrupp's Duisburg complex and Nippon Steel's Nagoya works where high-volume tapping cycles exceed 12 heats daily.
- Grab Buckets:Clamshell excavators with heat-resistant cable systems extract semi-molten slag from quenching pits. ArcelorMittal's Ghent facility and Tata Steel's Jamshedpur operations specify oversized 25-cubic-meter variants for integrated blast furnace slag recovery.
- Slag Pot:Cast steel vessels with magnesia-carbon linings transport 60-150 metric tons of liquid slag at temperatures exceeding 1,500°C.
- Conveyors:Continuous belt systems with integrated heat exchangers displace batch handling in greenfield installations.
Most installed capacity flows through slag pots and grab buckets. Expansion is steepest in conveyors as closed-loop cooling lines gain specification at Posco and JFE greenfield builds.
Technology:
Control precision requirements separate premium-tier deployments from standard mechanical offerings.
- Hydraulic:Sensor-integrated fluid power systems deliver millimeter-accurate positioning under thermal load stress. Baosteel's Zhanjiang complex and Shagang's Zhangjiagang mills specify proportional valve controls to minimize refractory shock damage during pot placement.
- Pneumatic:Compressed-air actuators power lighter-duty grab mechanisms in secondary steel operations. Gujarat induction furnace clusters deploy these for cost-sensitive slag removal where cycle frequency remains below six heats per day.
- Electromechanical:Motor-driven crane systems dominate slag yard operations at Konecranes installations across Nordic steel plants.
- Manual:Operator-controlled equipment persists in small-scale foundries with annual output below 50,000 tons.
Hydraulic systems command the dominant share of new capital expenditure. Pneumatic alternatives are climbing fastest where induction furnace capacity expands in India's western states.
Installation:
Mobility requirements reflect furnace layout constraints and slag yard configuration flexibility.
- Permanent:Fixed conveyor foundations and dedicated crane rails serve high-throughput blast furnace complexes. Voestalpine's Linz facility and Severstal's Cherepovets works anchor slag handling architecture to concrete substructures supporting 30-year operational horizons.
- Mobile:Rubber-tired carriers and crawler-mounted grab units relocate between tapping stations. Mini-mill operators in Turkey's Iskenderun cluster favor these for electric arc furnace slag management where production schedules shift weekly.
- Semi-permanent:Modular rail systems allow seasonal repositioning without full foundation reconstruction.
- Fixed:Stationary pot car tracks dominate legacy integrated mill configurations.
Permanent infrastructure absorbs the majority of maintenance capital. Mobile configurations are gaining specification fastest at mini-mill greenfields in Southeast Asia.
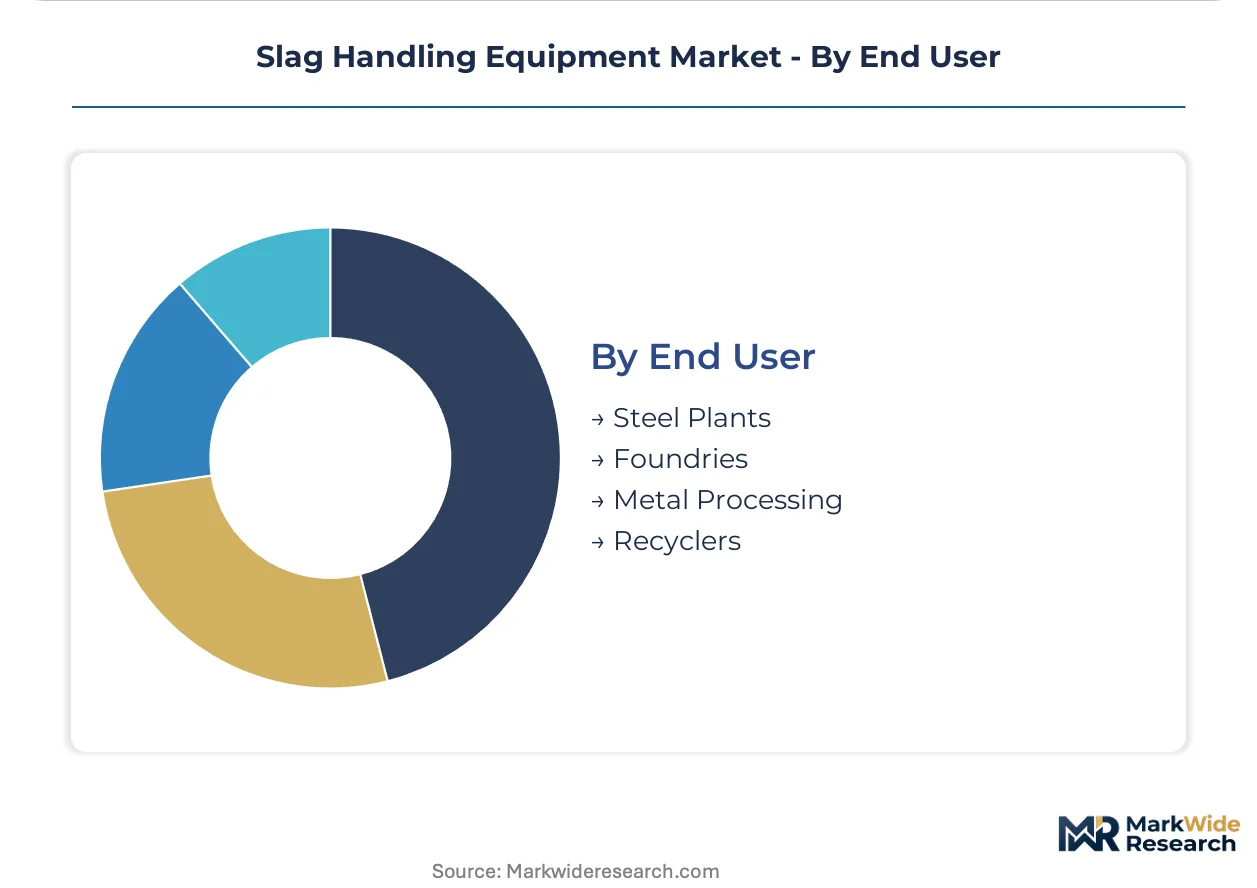
End User:
Volume scale and thermal regime severity create distinct equipment durability requirements across user categories.
- Steel Plants:Integrated blast furnace and basic oxygen furnace operations generate 250-400 kilograms of slag per ton of crude steel. China Baowu, JFE Steel, and Salzgitter AG specify equipment rated for continuous exposure above 1,200°C with 15-year refractory replacement cycles.
- Foundries:Cupola and induction melting operations produce ferrous slag at smaller scale with intermittent thermal loading. Tamil Nadu automotive casting clusters deploy standardized pot carriers without integrated heat recovery.
- Metal Processing:Stainless steel and specialty alloy producers require handling systems resistant to corrosive slag chemistries.
- Recyclers:Post-consumer metal recovery operators process heterogeneous slag streams with unpredictable composition.
Steel plants account for the preponderance of installed equipment value. Recyclers represent the steepest expansion trajectory as circular economy mandates intensify across EU member states.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized refractory installation crews concentrate in Germany's Ruhr Valley, Japan's Chubu industrial corridor, and China's Liaoning province, anchoring equipment commissioning capacity where blast furnace density remains highest.
China
Baosteel and Shagang Group drive procurement of hydraulic slag pot carriers rated for 1,500°C continuous operation. The MEE enforces dual carbon mandates tying production permits to slag energy recovery rates. Hebei and Jiangsu province mills now specify sealed transfer mechanisms to meet tightened particulate emission limits.
Germany
ThyssenKrupp's Duisburg complex and Salzgitter AG anchor demand for 30-year lifecycle equipment with integrated heat recovery. The EU Green Deal and national carbon pricing compel mills to document slag processing efficiency for green steel certification. Voestalpine's Linz facility anchors fixed conveyor foundations serving high-throughput blast furnace operations.
United States
Integrated mills in Indiana and Ohio face escalating EPA Clean Air Act penalties for fugitive emissions during slag tapping. ArcelorMittal's Burns Harbor and Cleveland-Cliffs' Burns Harbor operations accelerate replacement of open-pit cooling with enclosed conveyor systems. OSHA workplace safety rules shape equipment design for operator protection in extreme thermal environments.
Japan
JFE Steel and Nippon Steel specify closed-loop conveyor systems for recent furnace expansions in Fukuyama and Nagoya. METI industrial decarbonization roadmaps push mills toward slag valorization-compatible handling infrastructure. The Chubu region's Nagoya works deploy mechanized raking systems for high-volume tapping cycles exceeding 12 heats daily.
India
Induction furnace operators in Gujarat and Tamil Nadu lack standardized slag cooling infrastructure, creating first-mover equipment installation potential. The Bureau of Indian Standards develops metallurgical equipment safety codes for emerging secondary steel capacity. Tamil Nadu automotive casting clusters deploy standardized pot carriers without integrated heat recovery for smaller-scale cupola operations.
Slag Handling Equipment Market Key Industry Players
Capital-heavy producers compete with asset-light designers across a tiered vendor base where integrated service providers command premium positioning against standalone equipment fabricators. The market structure concentrates around three strategic archetypes: vertically integrated slag processors bundling equipment with long-term service contracts; crane and heavy-lift specialists leveraging electromechanical expertise for steel yard automation; and captive Chinese foundry-equipment manufacturers competing on casting-to-assembly scale. Dominant competitive moves include geographic expansion through local service network certification and portfolio diversification into thermal monitoring and refractory maintenance subscriptions.
Within the integrated processor tier, Harsco Corporation exemplifies the service-bundle archetype through backward integration into slag processing operations. Among crane-system specialists, Konecranes occupies a position defined by electromechanical heavy-lift expertise for steel plant automation. At the captive manufacturing end, CHAENG (Great Wall Machinery) represents the foundry-to-equipment scale model concentrated in China's northern industrial belt. These three anchors illustrate how competitive positioning separates around heat-recovery integration depth, automation control precision, and refractory lifecycle management capabilities.
| Leading Market Players |
|---|
| AFEX Fire Suppression Systems |
| ALTA |
| American Crane and Equipment Corp |
| BHS-Sonthofen |
| Dongqi Group |
| Harsco Corporation |
| Konecranes |
| CHAENG (Great Wall Machinery) |
| CITIC Heavy Industries |
| Others |
Cost & Logistics Intelligence
Certified refractory installation crews concentrated in Germany's Ruhr Valley and Japan's Chubu corridor command wage premiums that widen spreads between premium-tier and standard-tier slag handling equipment. Labor-cost differentials between these specialist clusters and emerging fabrication centers in India and Turkey separate pricing tiers more sharply than raw material inputs alone.
Pricing Analysis
The bundled-vs-unbundled service split now dominates procurement negotiations, with Harsco Corporation and Konecranes anchoring premium positioning through multi-year maintenance subscriptions while standalone fabricators compete on equipment-only transactions. Price differentiation hinges on ISO 45001 certification depth and refractory lifecycle guarantees, with certified vendors capturing margins three times standard mechanical suppliers. Pricing pressure stems from nickel-chromium alloy cost volatility transmitted through London Metal Exchange fluctuations. Induction furnace operators in India's western states exhibit highest price sensitivity, while integrated blast furnace complexes in China and Germany prioritize thermal durability over unit cost.
Supply Chain Analysis
ISO 45001 and MEE emissions certification gating restricts qualified supplier pools to fabricators with documented thermal stress monitoring capabilities. Geographic supply concentrates in China, Germany, and Japan, with magnesia-carbon brick production clustering in Liaoning province creating single-source vulnerability for slag pot lining replacement. Raw material dependencies rest on nickel-chromium alloys, metallurgical-grade steel castings, and ceramic welding consumables. Supply chain risk centers on refractory supply concentration exposing buyers to logistics chokepoints during provincial environmental inspections. Distribution runs through OEM-direct contracts for integrated mills and regional distributor networks for secondary steel operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Slag handling equipment functions as a stable compounder anchored by regulatory mandates that force continuous capital refresh regardless of steel demand cycles. EPA and MEE enforcement creates non-discretionary replacement demand that insulates the sector from commodity volatility.
For Market Incumbents: Deploy local service network certification to defend maintenance contract renewals against third-party specialists. Steel producers in Germany and Japan increasingly unbundle after-sales agreements, threatening OEM recurring revenue streams. Incumbents should anchor refractory lifecycle management capabilities and thermal monitoring subscriptions to retain multi-year agreements.
For New Entrants and Emerging Players: Begin with India's induction furnace clusters in Gujarat and Tamil Nadu, where standardized slag cooling infrastructure remains underdeveloped and procurement specifications favor cost-sensitive pneumatic systems over hydraulic precision. A go-to-market angle targeting Bureau of Indian Standards certification alignment positions entrants for secondary steel expansion.
For Investors and Strategic Acquirers: Vertically integrated slag processors are the most active acquirer in this space, seeking equipment fabrication capabilities to bundle with long-term service contracts. The sector offers viable long-term compounding through regulatory-driven replacement cycles. Acquisition targets should demonstrate ISO 45001 certification depth and established refractory installation partnerships. The signal to watch is carbon border adjustment mechanism implementation pace, which accelerates green steel certification requirements and equipment upgrade timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Refractory Manufacturing | Captive supply of magnesia-carbon linings insulates margins from Liaoning province supply disruptions. |
| Hydraulic Precision Control Certification | Sensor-integrated fluid power systems meet Baosteel and Shagang specifications for 1,500°C operation. |
| Local Service Network Accreditation | Certified maintenance crews in Hebei and Jiangsu secure multi-year agreements at China Baowu facilities. |
| Slag Valorization System Integration | Rapid quenching compatibility positions equipment for cement producer granulated blast furnace slag demand. |
| Continuous Cooling Conveyor Expansion | Closed-loop systems specified at Posco and JFE greenfield builds displace traditional slag pot carriers. |
Research Approach
Direct dialogue with plant engineers at integrated steel mills, aftermarket service directors, refractory installation specialists, and procurement leads at Baosteel and ThyssenKrupp anchored qualitative findings. Secondary validation drew from EPA enforcement databases, MEE emissions filings, SEC 10-K equipment disclosures, and blast furnace capacity registries. Bottom-up equipment shipment tracking and top-down steel production correlation established market sizing boundaries.
Segment-level outputs across product type, technology, installation mobility, and end-user category were modeled over the projection horizon. CAGRs were derived from correlating blast furnace retirement schedules with electric arc furnace expansion trajectories and regulatory compliance deadlines. Forecast inputs incorporated nickel alloy price volatility indices and refractory replacement cycle documentation from ISO 45001 audit records.
Caveats apply where MEE enforcement intensity or EPA penalty escalation could materially shift the outlook beyond modeled replacement rates. Forecasts reflect assumptions regarding blast furnace longevity and slag valorization adoption pace in European cement markets. A model refresh is warranted upon material change in carbon border adjustment mechanism implementation scope or nickel-chromium alloy supply disruptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Rubber Tired Gantry (RTG) Crane Market
Material Handling Equipment
Sifter Fitment Market
Material Handling Equipment
Roller Crusher Market
Material Handling Equipment
Air Hoist Market
Material Handling Equipment
Hooklifts Market
Material Handling Equipment
Conveyor Scales Market
Material Handling Equipment
Electric Stacker Market
Material Handling Equipment
Crushing Screening Equipment Market
Material Handling Equipment
Forklift Tire Market
Material Handling Equipment
Level Loader Market
Material Handling Equipment
Hot-Rolling Mill and Cold-Rolling Mill Market
Material Handling Equipment
Mill Liner Market
Material Handling Equipment
Vibrating Conveyor Market
Material Handling Equipment
Precision Gearbox Machinery Market
Material Handling Equipment
Industrial Wood Chipper Market
Material Handling Equipment
Sorting Equipment Market