
 Forklift Rental Market | 2026-2036
Forklift Rental Market Size, Share, and Industry Trends Forecast 2026-2036
Forklift Rental Market Analysis
ISO 3691 safety certification is reorganizing competitive access in forklift rental, filtering out operators lacking documented maintenance protocols and trained technician pools. United Rentals Incorporated leverages its North American branch density to sustain same-day availability guarantees. Loxam Group S.A. anchors its European position through national coverage in France and cross-border fleet mobility. Sunbelt Rentals Incorporated differentiates via vertical integration into parts distribution and field service capacity.
Forklift rental denotes the temporary provision of powered industrial trucks designed to lift, move, and stack materials, with load capacities typically spanning 1,500 to 36,000 pounds and mast heights reaching 276 inches for high-bay warehousing applications. Electric forklifts now lead product type demand as lithium-ion battery chemistry eliminates acid spills and reduces charging cycles to under two hours. Short-term rental services capture peak-season volume from retail distribution networks, while long-term rental and lease-to-own structures dominate manufacturing accounts seeking balance-sheet flexibility. Warehousing end users represent the deepest margin pool due to predictable utilization schedules and recurring maintenance attachments.
OSHA workplace safety mandates and EPA emissions thresholds govern fleet eligibility in the United States, while the EU Machinery Directive and F-Gas Regulation shape equipment specifications across Europe. These frameworks elevate total cost of ownership calculations and tilt procurement toward certified electric units with documented service histories. Stakeholders must monitor battery technology substitution curves and regional carbon pricing mechanisms to align fleet composition with evolving compliance thresholds.
Market Dynamics
Battery chemistry substitution is compressing rental fleet turnover cycles as lithium-ion systems eliminate acid maintenance and cut charging windows below two hours. This shift is restructuring operator economics and maintenance attachment rates across warehousing contracts.
Growth Catalysts
- EPA Tier 4 Final:The United States emissions mandate is forcing diesel fleet retirement toward electric models, accelerating replacement demand from logistics operators seeking compliance-ready equipment.
- E-commerce fulfillment density:Peak-season volume volatility from Amazon, Shopify, and regional distribution networks is expanding short-term rental commitments as fixed ownership becomes uneconomical.
- Lithium-ion battery chemistry:Faster charging and zero spill risk is displacing lead-acid systems in high-bay warehousing, reducing downtime penalties and enabling multi-shift deployment.
Market Restraints
- Technician scarcity:Certified electric forklift mechanics concentrate in Germany and the Netherlands, creating service bottlenecks for peripheral European markets.
- Battery supply concentration:Lithium cell production clusters in China expose rental fleets to raw material price volatility and export control risks.
- EU F-Gas Regulation:Hydrofluorocarbon phase-down timelines are complicating cold-chain forklift specifications, narrowing model availability for refrigerated warehousing.
Strategic Opportunities
- India warehousing expansion:PLI scheme incentives for manufacturing are creating greenfield logistics parks in Gujarat and Maharashtra with unmet rental equipment demand.
- Telematics convergence:IoT-enabled fleet management systems combined with predictive maintenance algorithms are unlocking outcome-based pricing models for multi-site operators.
- Brazil automotive supplier networks:ANVISA certification alignment with ISO 3691 standards is opening rental access to multinational assembly plant contracts.
Industry Challenges
- ISO 3691 compliance timelines:Documentation gaps in maintenance protocols are disqualifying smaller rental operators from automotive and pharmaceutical contracts.
- Legacy fleet integration:Mixed-material handling environments struggle to synchronize lithium-ion charging infrastructure with existing lead-acic electrical systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Forklift Rental Market |
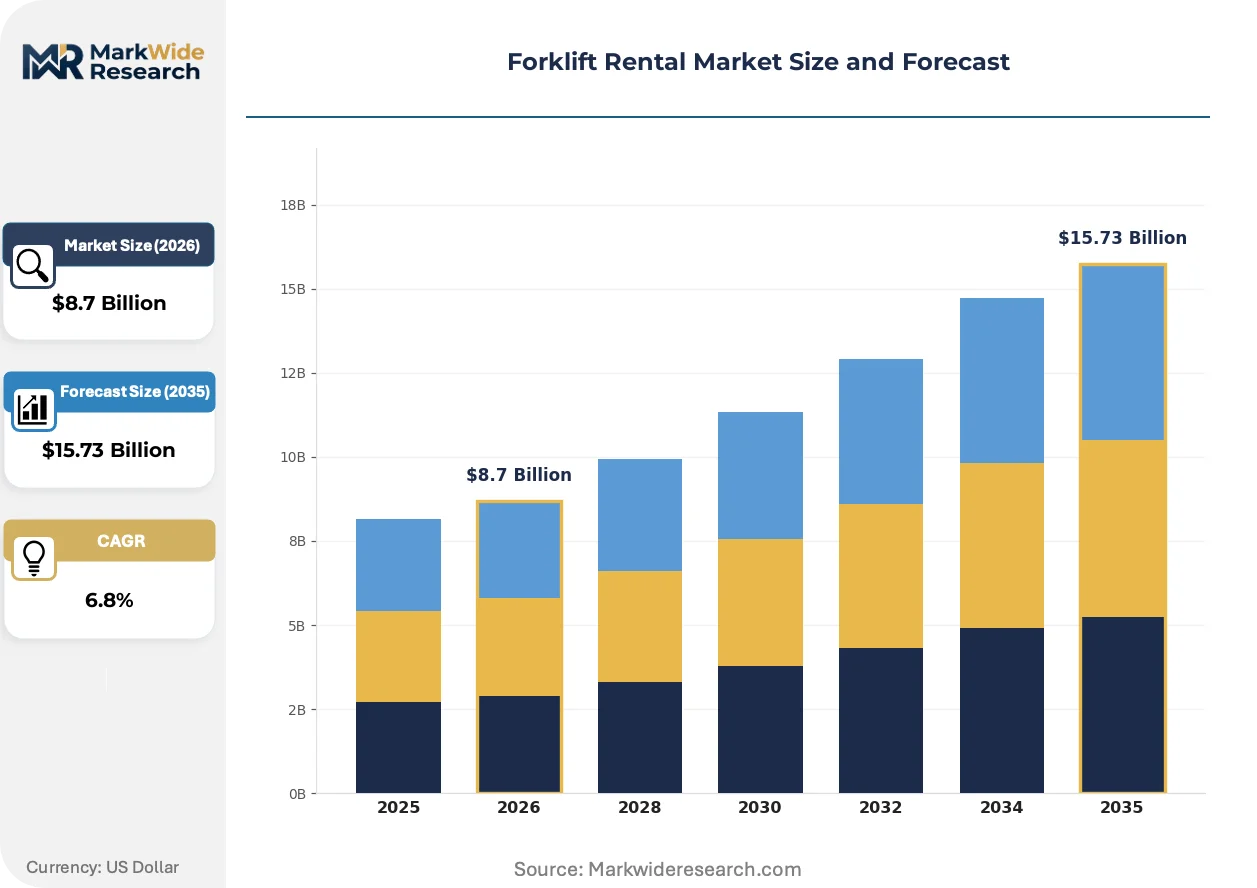
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Forklifts, Diesel Forklifts, LPG Forklifts, Rough Terrain Forklifts End User: Construction, Warehousing, Retail, Manufacturing Operation Type: Indoor, Outdoor, Heavy Duty, Light Duty Service Type: Short-term Rental, Long-term Rental, Lease-to-own, Maintenance Services |
| Companies Covered | H and E Equipment Services Incorporated, Ahern Rentals Incorporated, United Rentals Incorporated, Boels Rental N.V., Loxam Group S.A., Herc Rentals Incorporated, Alta Equipment Group Incorporated, KION Group, Sunbelt Rentals Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Forklift Rental Market Emerging Trajectories
Fleet telemetry and predictive analytics are rewiring how rental contracts are priced and fulfilled. Operators now compete on uptime guarantees rather than day-rate arbitrage.
Lithium-ion battery systems with opportunity-charging capability are displacing conventional lead-acid infrastructure in multi-shift warehousing operations. Food distribution centers and pharmaceutical cold-storage facilities are adopting these systems fastest due to zero-emission indoor requirements. The technology is displacing overnight charging protocols and enabling 24-hour equipment utilization without battery swap labor.
EU F-Gas Regulation phase-down schedules are compressing availability of refrigerant-dependent forklift models for temperature-controlled logistics. Cold-chain operators in Germany and France are accelerating electric fleet conversion ahead of 2030 bans. High-reach units for frozen warehousing now face procurement lead times stretching eighteen months as manufacturers retool production lines.
Outcome-based maintenance contracts are replacing traditional time-and-materials service agreements for enterprise accounts. Automotive suppliers in Stuttgart and Munich are bundling uptime guarantees with rental rates, transferring operational risk to equipment providers. This model is most advanced in German industrial corridors where production downtime costs exceed hourly rental multiples by orders of magnitude.
Forklift Rental Market Segmentation
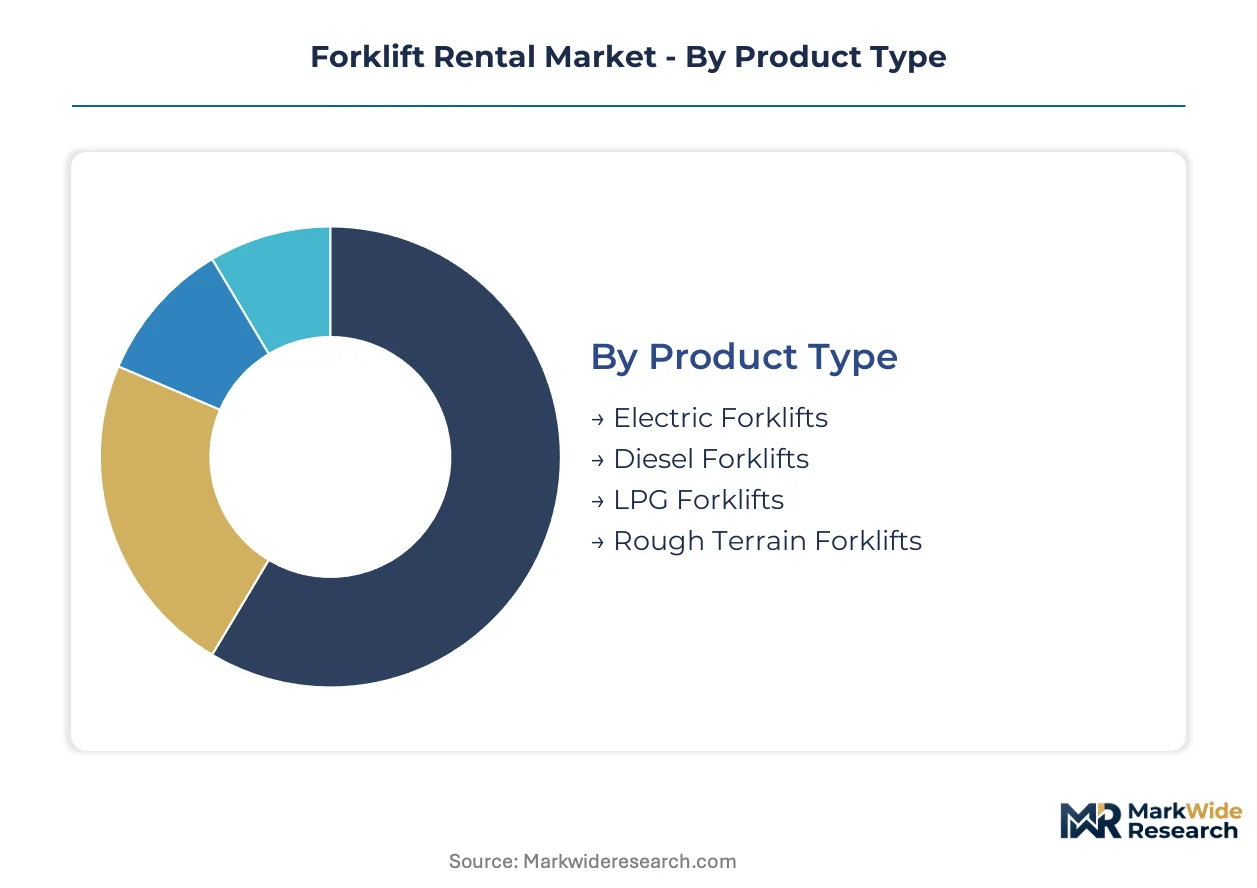
Forklift rental segmentation reveals divergent margin structures across equipment types and service durations. Rental operators calibrate fleet composition and pricing models against utilization patterns that vary sharply between peak-driven retail networks and steady-state manufacturing contracts.
Product Type:
Electric models dominate warehousing channel flows while diesel and LPG units concentrate in outdoor construction yards. Fleet procurement decisions track emissions compliance timelines and charging infrastructure availability across end-use facilities.
- Electric Forklifts:Lithium-ion battery systems deliver sub-two-hour charging cycles and eliminate acid maintenance. Demand concentrates in Germany's automotive supplier corridors and e-commerce fulfillment centers where multi-shift deployment justifies premium rental rates.
- Diesel Forklifts:Internal combustion engines with EPA Tier 4 Final after-treatment systems retain relevance for outdoor construction and heavy manufacturing. Fleet turnover accelerates in the United States as logistics operators retire non-compliant units ahead of enforcement deadlines.
- LPG Forklifts:Propane-powered units bridge indoor-outdoor flexibility for mixed-use facilities lacking electrical infrastructure.
- Rough Terrain Forklifts:Pneumatic-tire designs with elevated ground clearance serve unpaved construction sites and agricultural logistics.
By volume, diesel units retain installed base leadership. By growth pace, electric configurations are climbing the fastest as battery chemistry advances compress total cost of ownership gaps.
End User:
Margin concentration varies by utilization predictability and maintenance attachment rates. Contract structures diverge between spot-market retail demand and enterprise manufacturing accounts seeking balance-sheet flexibility.
- Warehousing:High-bay distribution centers generate recurring revenue through predictable utilization schedules and bundled maintenance agreements. Food and pharmaceutical cold-storage facilities drive electric fleet conversion fastest due to zero-emission indoor mandates.
- Manufacturing:Automotive suppliers in Stuttgart and Munich bundle uptime guarantees with rental rates, transferring operational risk to equipment providers. Just-in-time production schedules demand same-day availability guarantees.
- Construction:Project-based demand fluctuates with building permit cycles and infrastructure spending.
- Retail:Peak-season volatility from e-commerce networks expands short-term rental commitments as fixed ownership becomes uneconomical.
Warehousing commands the deepest margin pool. Retail exhibits the steepest expansion trajectory as fulfillment density intensifies.
Operation Type:
Environmental exposure and load severity determine equipment specification and service interval frequency. Indoor-outdoor classification shapes battery selection and mast height configuration.
- Indoor:Cushion-tire electric forklifts with three-stage masts navigate narrow aisle widths in high-density storage. Lithium-ion systems with opportunity charging enable continuous operation without battery swap labor.
- Outdoor:Pneumatic-tire diesel and LPG units withstand weather exposure and uneven surfaces. Yard logistics at port terminals and lumber yards sustain high-hour utilization.
- Heavy Duty:Load capacities exceeding 15,000 pounds serve steel distribution and container handling.
- Light Duty:Compact electric units with sub-3,000-pound ratings operate in retail backrooms and small-footprint workshops.
Indoor applications dominate fleet deployment by unit count. Heavy duty configurations gain share fastest as port automation and intermodal logistics expand.
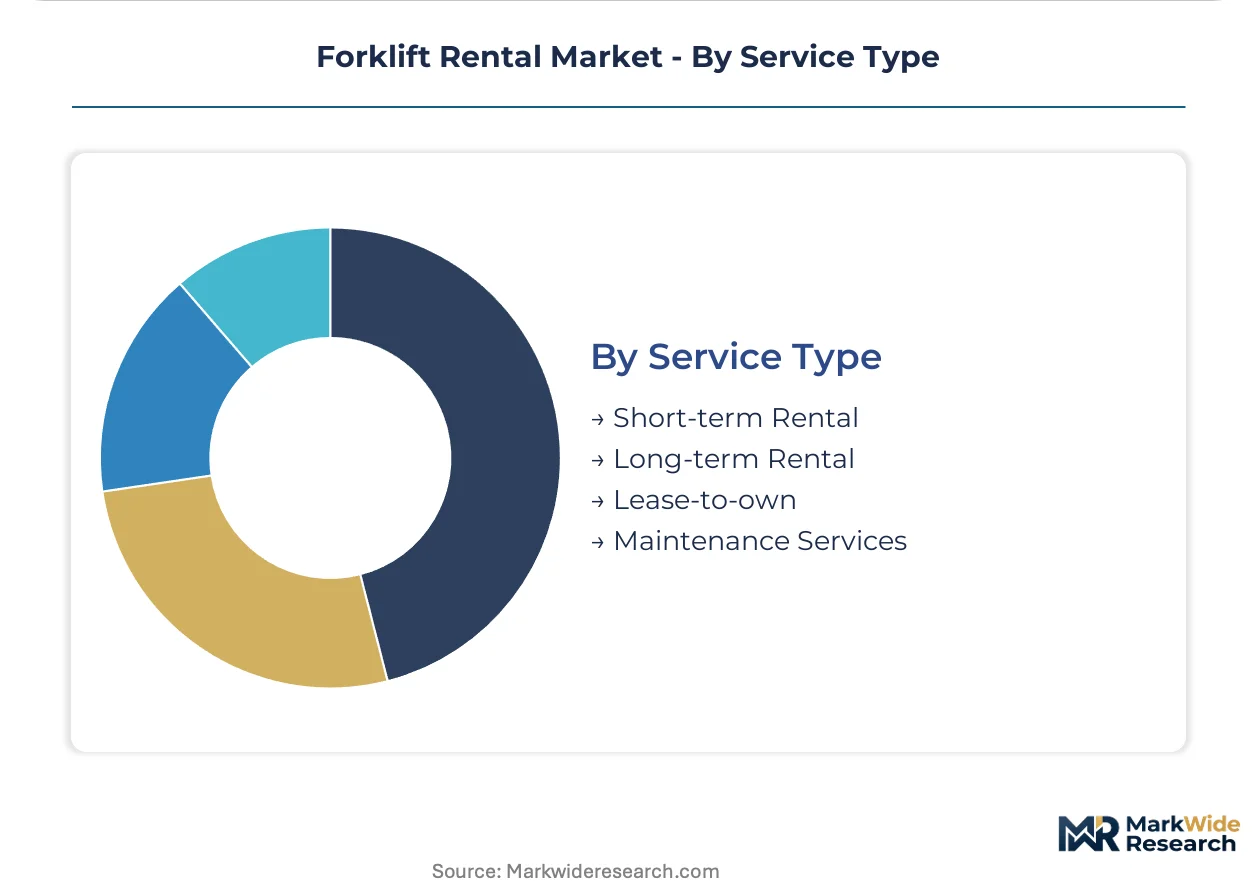
Service Type:
Contract duration and ownership transfer terms segment pricing structures and customer retention economics. Short-term spot markets compete on availability guarantees while long-term arrangements emphasize total cost predictability.
- Short-term Rental:Daily and weekly rates capture peak-season volume from retail distribution networks. United Rentals leverages North American branch density to sustain same-day availability commitments.
- Long-term Rental:Multi-year agreements dominate manufacturing accounts seeking off-balance-sheet equipment access. Automotive suppliers in Germany transfer operational risk through bundled uptime guarantees.
- Lease-to-own:Terminal purchase options appeal to capital-constrained operators building permanent fleet capacity.
- Maintenance Services:Predictive maintenance algorithms and IoT-enabled fleet management unlock outcome-based pricing for multi-site operators.
Long-term rental leads by contract value concentration. Short-term services expand most quickly as e-commerce fulfillment volatility intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA Tier 4 Final and Euro Stage V emissions mandates are restructuring fleet procurement across industrial corridors. National regulations accelerate electric conversion timelines while warehouse automation concentrates demand in specific logistics clusters.
United States
E-commerce fulfillment networks in the Inland Empire and Dallas-Fort Worth drive short-term rental volume spikes. OSHA workplace safety mandates govern fleet eligibility and elevate documentation requirements for maintenance protocols. United Rentals leverages North American branch density to sustain same-day availability guarantees across these distribution corridors.
Germany
Automotive supplier networks in Stuttgart and Munich sustain the highest equipment utilization rates in Europe. EU Machinery Directive and F-Gas Regulation specifications shape cold-chain forklift procurement for pharmaceutical logistics. Industrial logistics density in Baden-Württemberg and Bavaria creates concentrated demand for uptime-guaranteed rental contracts.
China
Dual carbon goals from MEE accelerate electric forklift deployment in Yangtze River Delta warehousing clusters. GB standards and MIIT industrial policy guide fleet composition toward lithium-ion systems. Shenzhen and Shanghai logistics parks exhibit unmet rental equipment demand as greenfield fulfillment centers proliferate.
India
PLI scheme incentives for manufacturing create greenfield logistics parks in Gujarat and Maharashtra with equipment shortages. BIS certification requirements and CDSCO pharmaceutical regulations elevate compliance thresholds for rental operators. Mumbai-Pune and Delhi-Mumbai Industrial Corridor warehouse developments concentrate demand for certified electric units.
Brazil
ANVISA certification alignment with ISO 3691 standards opens rental access to multinational automotive assembly contracts. São Paulo state industrial corridors exhibit rising demand for flexible fleet solutions as supplier networks expand. Cold-chain logistics for food distribution accelerates electric forklift conversion ahead of regulatory phase-ins.
Forklift Rental Market Vendor Landscape
Listed leaders compete with private specialists across fleet scale and service coverage dimensions. The market structures around three tiers: national-scale rental networks with branch density advantages, regional specialists with vertical integration into maintenance, and equipment manufacturers with captive rental divisions. Consolidation pressures favor operators with documented ISO 3691 maintenance protocols and trained technician pools. Strategic moves concentrate on telematics-enabled fleet management and cross-border fleet mobility agreements.
Within the North American scale tier, United Rentals Incorporated and Sunbelt Rentals Incorporated exemplify branch-density competitive positioning. Loxam Group S.A. occupies a position representing European cross-border fleet mobility specialization. These three anchors illustrate how geographic coverage depth and service integration separate market positions.
| Leading Market Players |
|---|
| H and E Equipment Services Incorporated |
| Ahern Rentals Incorporated |
| United Rentals Incorporated |
| Boels Rental N.V. |
| Loxam Group S.A. |
| Herc Rentals Incorporated |
| Alta Equipment Group Incorporated |
| KION Group |
| Sunbelt Rentals Incorporated |
| Others |
Supply Flow & Price Mechanics
Lithium-ion battery chemistry substitution simultaneously redraws supply geography toward East Asian cell manufacturers and compresses rental pricing economics through reduced maintenance attachments. This dual restructuring rewards operators with captive technician pools and penalizes those dependent on third-party service networks.
Pricing Analysis
Certification level under ISO 3691 creates the primary spread between premium and standard rental tiers. Three-tier pricing structure across certified-premium, documented-standard, and basic-economy levels dominates contract structures. Price differentiation stems from maintenance bundling and documented service histories versus spot-market availability. Cost compression in the economy tier is intensifying because uncertified operators face exclusion from automotive and pharmaceutical contracts. Retail distribution networks exhibit highest price sensitivity due to peak-season volatility, while German automotive suppliers accept premium rates for uptime-guaranteed arrangements.
Supply Chain Analysis
Just-in-time fleet positioning dominates rental operator inventory strategy, with lithium-ion battery availability dictating equipment deployment timing. Cell production clusters in China, South Korea, and Japan anchor global forklift powertrain supply. Raw material dependencies span lithium carbonate, cobalt sulfate, and copper busbar assemblies. Single-source vulnerability concentrates in Chinese cathode active material processing. Distribution runs through regional hub-and-spoke networks with cross-border fleet mobility agreements enabling European operators to balance utilization across Germany, France, and the Netherlands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Forklift rental represents a high-growth disruption as EPA Tier 4 Final and Euro Stage V mandates force diesel fleet retirement toward electric models. This regulatory inflection compresses replacement cycles and elevates certified operator premiums.
For Market Incumbents: Compound branch density advantages through telematics-enabled fleet management integration and predictive maintenance algorithm deployment. Threat from battery supply concentration in China demands backward integration into regional battery service partnerships. Priority lever rests on technician certification investments in Germany and the Netherlands where qualified electric forklift mechanics concentrate.
For New Entrants and Emerging Players: Differentiate on cold-chain specialization as EU F-Gas Regulation phase-down narrows model availability for refrigerated warehousing. White-space targets include India greenfield logistics parks in Gujarat and Maharashtra and Brazil automotive supplier corridors seeking ANVISA-aligned certification. Go-to-market angle emphasizes outcome-based uptime guarantees rather than day-rate competition.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale operators with documented ISO 3691 maintenance protocols and trained technician pools in undersupplied peripheral European markets. Long-term viability favors assets positioned for lithium-ion fleet conversion with established automotive and pharmaceutical customer relationships. Signal to watch is battery chemistry substitution curves crossing total cost of ownership parity thresholds against legacy lead-acid systems.
| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | IoT-enabled fleet management unlocks outcome-based pricing for multi-site warehousing operators. |
| Technician Certification Investment | ISO 3691-compliant maintenance protocols secure access to automotive and pharmaceutical contracts. |
| Battery Service Partnership | Regional lithium-ion service capacity reduces downtime penalties and enables multi-shift deployment. |
| Cold-Chain Specialization | F-Gas Regulation alignment captures narrowing model availability for refrigerated logistics. |
| Cross-Border Fleet Mobility | European hub-and-spoke networks balance utilization across Germany, France, and Netherlands corridors. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with warehouse operations directors, fleet maintenance managers, OEM procurement teams, and aftermarket service heads. Secondary validation drew from customs and trade data, equipment registration databases, SEC filings of listed rental operators, and regulatory filings with EPA and EU Machinery Directive authorities. Bottom-up equipment deployment estimates and top-down market sizing triangulated across the analysis window.
Across the projection horizon, volume and value outputs reflect segmentation by product type, end user industry, operation environment, and service contract duration. CAGRs were derived from equipment replacement cycle analysis and fleet composition shift modeling. Industry-specific forecast inputs include battery chemistry substitution curves and regional emissions compliance timelines.
Material uncertainties — raw material price volatility, export control actions, and regulatory enforcement intensity — sit outside the modeled envelope. Forecasts reflect assumptions about technician availability and charging infrastructure deployment pace. Revision becomes warranted when lithium cell supply disruption or carbon pricing mechanism expansion crosses thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Australia Forklift Market
Material Handling Equipment
Automated Material Handling Systems Market
Material Handling Equipment
High Pressure Grease Hose Market
Material Handling Equipment
Bulk Material Handling Products and Technologies Market
Material Handling Equipment
Hydraulic Hoist Market
Material Handling Equipment
Heavy Duty Ramp Market
Material Handling Equipment
Trash Chute Market
Material Handling Equipment
Pneumatic Caster Market
Material Handling Equipment
North America Industrial Duct for Dust Collection Market
Material Handling Equipment
Air Hose Market
Material Handling Equipment
Forklift Work Platforms Market
Material Handling Equipment
United States Automated Material Handling Market
Material Handling Equipment
Europe Conveyors Market
Material Handling Equipment
High-Performance Seals Market
Material Handling Equipment
Middle East and Africa Automated Material Handling Market
Material Handling Equipment
Material Handling Monorails Market