
 Trencher Attachments Market | 2026-2036
Trencher Attachments Market Size, Share, and Industry Trends Forecast 2026-2036
Trencher Attachments Market Analytics
Hydraulic quick-coupler standardization is reconfiguring how trencher attachments integrate with host machines across rental and contractor fleets. Vermeer Corporation leverages its captive distribution network to sustain aftermarket attachment turnover. Caterpillar Inc. anchors its position through backward integration into cutting tool metallurgy. Bobcat Company differentiates via compact-platform trencher attachments purpose-built for tight-access job sites.
Trencher attachments are modular earth-cutting implements mounted to skid steers, compact track loaders, or dedicated trenching units, typically employing hardened steel chains, carbide-tipped teeth, or toothed wheel assemblies to excavate narrow trenches at controlled depths and widths for pipe, cable, or drainage placement. Chain trencher attachments command the largest installed base due to versatility across soil conditions, while rock trencher variants capture premium margin pools in geologically challenging terrain. Wheel trencher attachments lead in agricultural drainage applications where speed and shallow cut profiles matter, and utility contractors represent the fastest-growing end-user channel as fiber and electrification backbones expand.
EPA Tier 4 Final emissions rules shape engine-attachment compatibility requirements, while OSHA excavation safety standards dictate guarding and operator protection specifications that manufacturers must satisfy for US market access. ISO 10261 testing protocols for earth-moving machinery attachments further condition product validation cycles and international export eligibility. Stakeholders must weigh hydraulic flow rate standardization against proprietary coupler investments as fleet interoperability becomes the decisive procurement criterion.
Market Dynamics
Hydraulic quick-coupler standardization is compressing equipment replacement cycles as utility contractors demand plug-and-play compatibility across mixed fleets, forcing attachment manufacturers to abandon proprietary interfaces.
Growth Catalysts
- Fiber-optic backbone deployment:Telecommunications infrastructure mandates in the United States are accelerating trencher attachment procurement for last-mile connectivity projects.
- EPA Tier 4 Final compliance:Emissions rules for off-road diesel equipment are stimulating fleet turnover and attachment upgrades to match new engine specifications.
- Carbide-tipped tooth metallurgy:Advances in cutting tool durability are extending operational uptime in abrasive soil conditions across renewable energy grid installations.
Market Restraints
- Steel alloy price volatility:Input cost swings for hardened chain materials are compressing gross margins for attachment fabricators without long-term supply contracts.
- Proprietary coupler lock-in:Major OEM captive distribution networks in North America limit third-party attachment interoperability and aftermarket access.
- Rock trencher technical ceiling:Extreme geological conditions in granite and basalt formations exceed current wheel-and-chain mechanical limits, restricting addressable terrain.
Strategic Opportunities
- India rural electrification:The country's central electricity authority mandates are creating demand for compact trencher attachments suited to narrow agricultural rights-of-way.
- OSHA excavation safety unbundling:Operator protection specification compliance is opening aftermarket retrofit markets for guarding and shielding systems.
- Telematics-hydraulics convergence:Real-time flow monitoring combined with predictive maintenance algorithms is enabling attachment-as-a-service revenue models.
Industry Challenges
- ISO 10261 validation timelines:Extended earth-moving machinery attachment testing protocols are delaying product launches and export certifications.
- Hydraulic technician scarcity:Specialized skills for high-pressure system integration are constraining dealer service capacity and field support.
- Legacy fleet incompatibility:Older skid steer hydraulic architectures require mechanical adaptation kits that complicate installation and warranty coverage.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Trencher Attachments Market |
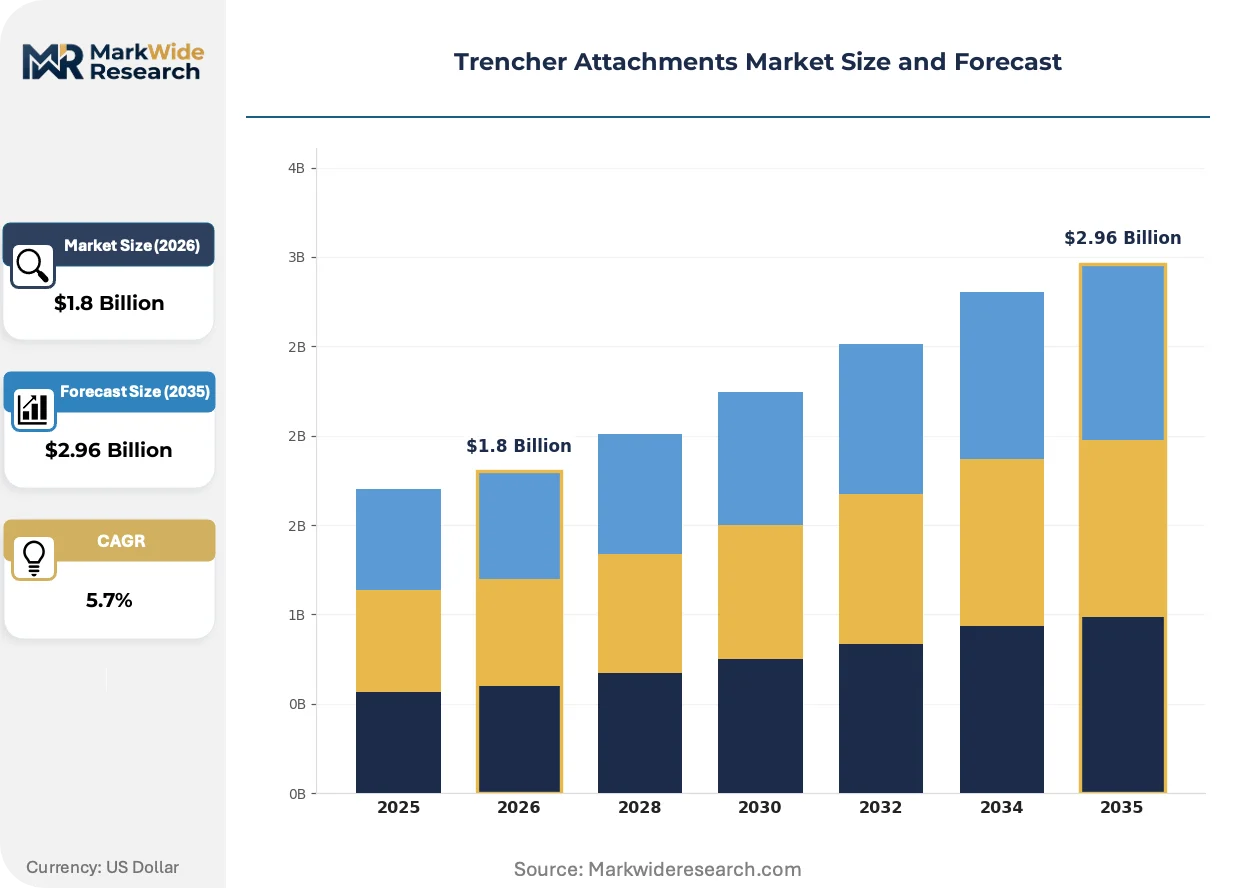
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Standard Trencher, Chain Trencher, Wheel Trencher, Rock Trencher Application: Construction, Agriculture, Utility, Landscaping End User: Contractors, Municipalities, Farmers, Utilities Distribution Channel: Direct Sales, Wholesalers, Online Retail, Dealers |
| Companies Covered | Bobcat Company, Vermeer Corporation, Caterpillar Inc., Case Construction Equipment, Ditch Witch, Toro Company, AFT Trenchers Ltd., Erskine Attachments LLC, Kubota Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Trencher Attachments Market Evolving Landscape
Attachment intelligence and materials science are converging to redefine performance benchmarks, with digital integration and regulatory compliance emerging as the primary axes of product differentiation.
Carbide-composite cutting tooth formulations are extending wear life in high-abrasion conditions. Utility contractors operating in desert Southwest geologies are specifying these upgrades to reduce field replacement frequency. Conventional hardened steel tooth arrays are rendering obsolete for continuous-rock applications where downtime costs dominate project economics.
EPA off-road diesel emissions enforcement is tightening engine-attachment pairing documentation requirements. Manufacturers must now certify hydraulic system compatibility across Tier 4 Final power units to maintain market access. The United States utility contractor segment is responding by consolidating procurement around OEM-verified attachment bundles rather than third-party alternatives.
Rental fleet managers are unbundling attachment maintenance from equipment leases to capture service revenue. Independent rental yards are displacing traditional dealer networks for short-cycle trencher attachment deployment. This pattern concentrates in Texas and Florida municipal infrastructure markets where project volatility favors flexible equipment access over ownership.
Trencher Attachments Market Segmentation
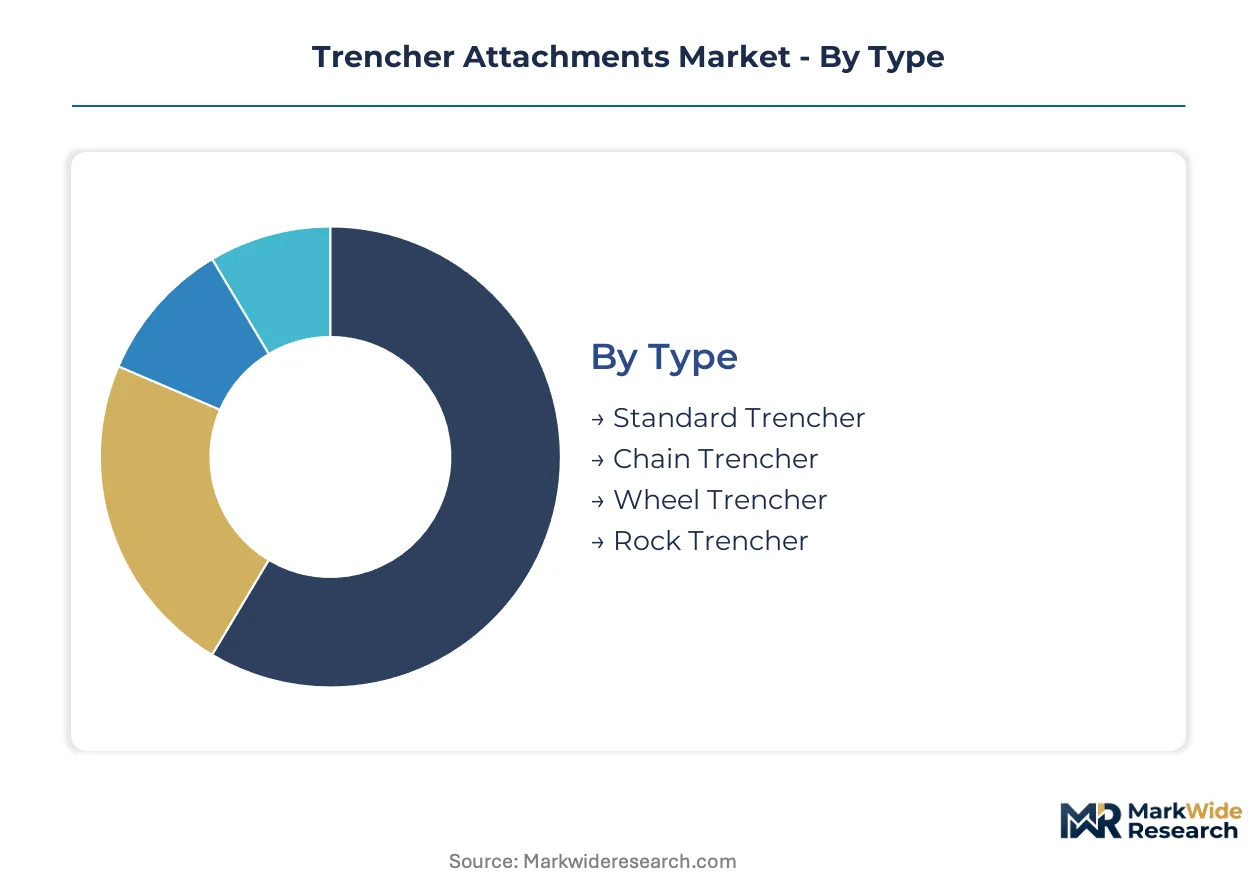
Segmentation in trencher attachments separates volume-driven commodity purchases from precision-engineered premium configurations. Procurement patterns diverge sharply across application environments, with utility contractors prioritizing hydraulic interoperability while agricultural buyers optimize for cut speed per hour.
Type:
Equipment architecture dictates soil penetration mechanics, wear part economics, and host machine compatibility requirements.
- Standard Trencher:General-purpose chain or wheel configurations handle mixed soil conditions with moderate abrasion. Municipal trenching crews in the United States specify these for residential utility corridors where geological predictability reduces premium tooling requirements.
- Chain Trencher:Continuous loop cutting chains with hardened steel links and replaceable teeth achieve precise depth control across variable terrain. Fiber-optic contractors operating in the United States deploy these for last-mile burial where substrate consistency fluctuates block by block.
- Wheel Trencher:Rotating toothed discs excavate shallow trenches at high linear speeds. Agricultural drainage contractors in the United States Midwest favor these for field tile installation where cut depth stays below 36 inches.
- Rock Trencher:Reinforced frame structures and carbide-embedded cutting tools attack consolidated formations. Quarry and mining extension projects in granite belts generate concentrated demand despite mechanical complexity premiums.
Chain Trencher commands the established base. The steepest expansion runs through Rock Trencher.
Application:
End-use environment shapes attachment specification priorities from soil abrasiveness to regulatory exposure.
- Construction:Site preparation and foundation drainage trenches demand rapid deployment across shifting contract portfolios. Commercial builders in the United States Sun Belt specify quick-coupler configurations to minimize equipment repositioning downtime.
- Agriculture:Subsurface drainage and irrigation line burial prioritize cut speed over precision depth. Corn Belt farm cooperatives schedule trencher attachment deployment around planting windows, compressing seasonal demand spikes.
- Utility:Buried electrical, gas, and telecommunications infrastructure requires exacting depth compliance and minimal surface disruption. Electric cooperative electrification mandates in the United States rural zones are accelerating procurement for underground cable burial.
- Landscaping:Aesthetic contouring and irrigation system installation favor compact skid-steer mounts. Golf course maintenance divisions specify low-ground-pressure configurations to protect turf integrity.
Utility captures the dominant revenue share. Landscaping climbs the fastest as residential outdoor renovation spending persists.
End User:
Customer organizational structure determines procurement sophistication, from centralized fleet management to seasonal spot purchasing.
- Contractors:Independent construction and excavation firms balance equipment utilization rates across project pipelines. Utility contractors in the United States are consolidating attachment procurement around OEM-verified bundles to satisfy EPA Tier 4 Final documentation requirements.
- Municipalities:City and county public works departments operate under fixed capital budgets with extended replacement cycles. Street and sewer departments in Texas and Florida municipalities favor rental arrangements to match equipment access to grant-funded project timing.
- Farmers:Owner-operators and agricultural cooperatives purchase attachments for seasonal drainage maintenance. The United States Farm Service Agency cost-share programs influence timing but not specification selection.
- Utilities:Electric, gas, and telecommunications infrastructure owners maintain captive fleets with standardized hydraulic architectures. Rural electric cooperatives are expanding trencher attachment inventories to meet federal electrification connectivity targets.
Contractors anchor volume throughput. Utilities expand most quickly on electrification and fiber backbone mandates.
Distribution Channel:
Channel structure reflects customer proximity requirements, technical support intensity, and transaction scale economics.
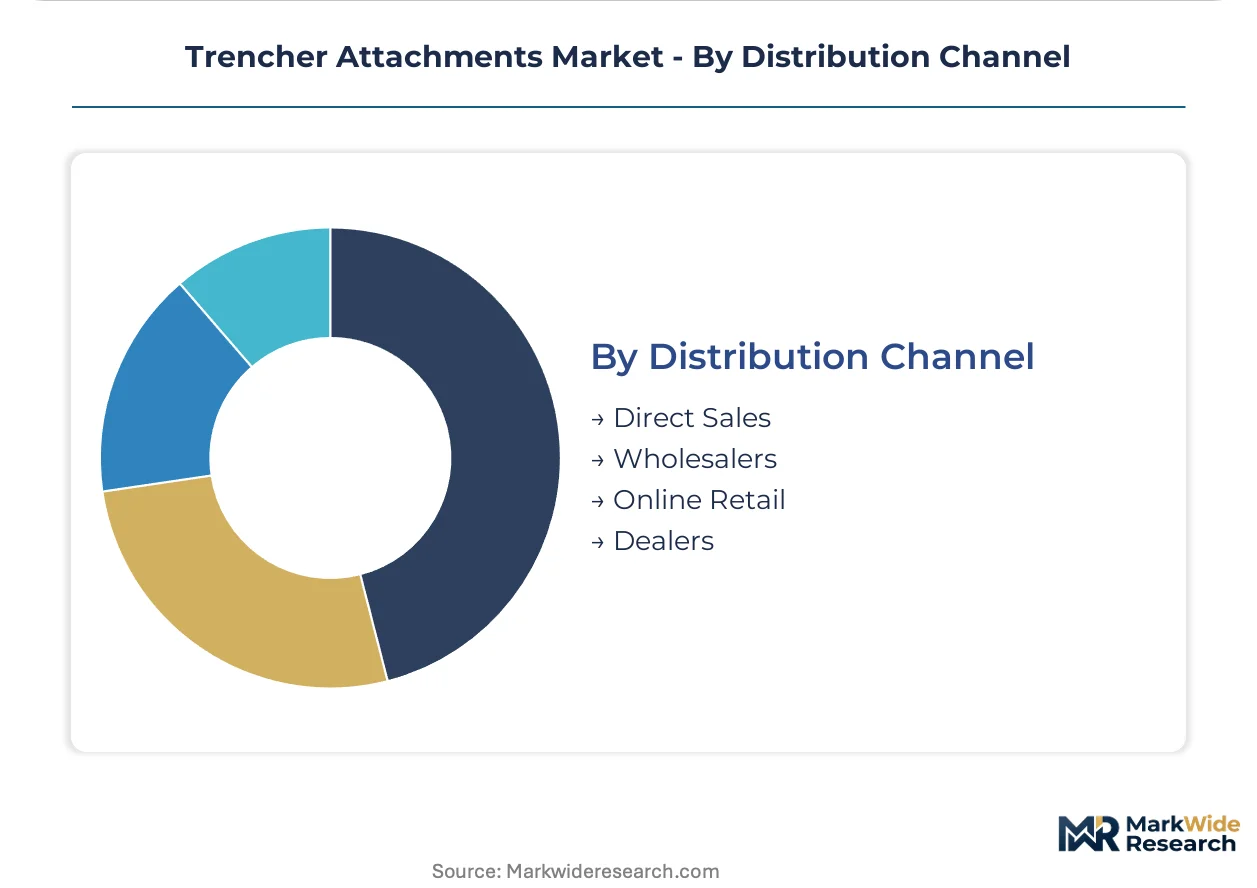
- Direct Sales:Manufacturer-to-fleet transactions serve national accounts and OEM captive distribution. Vermeer Corporation leverages this channel to sustain aftermarket attachment turnover through its dealer network.
- Wholesalers:Regional inventory aggregators supply independent rental yards and smaller contractors. Texas and Florida equipment wholesalers are capturing share as rental fleet managers unbundle attachment maintenance from equipment leases.
- Online Retail:E-commerce platforms facilitate specification comparison and price transparency for standardized attachments. Compact-platform trencher attachments for tight-access job sites generate disproportionate digital inquiry volume.
- Dealers:Authorized distribution provides installation support, warranty administration, and hydraulic system integration. Caterpillar Inc. anchors its dealer network through backward integration into cutting tool metallurgy.
Dealers retain the core transaction flow. Online Retail gains share fastest as specification standardization reduces pre-purchase consultation needs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German trencher attachment manufacturers export precision-engineered cutting systems to utility contractors across the United States, establishing a transatlantic trade corridor that channels European fabrication expertise into North American fiber-optic infrastructure deployment.
United States
Utility contractors in Texas and Florida municipalities drive procurement for quick-coupler trencher attachments as fiber-optic mandates accelerate last-mile burial projects. EPA Tier 4 Final emissions enforcement requires hydraulic system compatibility documentation across fleet replacements. The Dallas-Fort Worth metroplex anchors concentrated demand from independent rental yards unbundling attachment maintenance from equipment leases.
Germany
Precision engineering firms supply carbide-tipped cutting tool metallurgy to global OEMs serving abrasive soil conditions. REACH chemical safety standards govern surface treatment processes for hardened steel chain production. The Baden-Württemberg industrial cluster houses specialized fabricators advancing ISO 10261 validation protocols for earth-moving machinery attachments.
India
Rural electrification mandates from the Central Electricity Authority generate demand for compact trencher attachments suited to narrow agricultural rights-of-way. BIS certification requirements condition product validation timelines for domestic market access. Maharashtra-based equipment distributors are capturing share as state power utilities expand underground cable burial programs.
China
Domestic manufacturers scale production of standard chain trencher configurations for export to Southeast Asian construction markets. GB standards for earth-moving machinery attachments shape quality benchmarking for international buyers. The Yangtze River Delta manufacturing belt concentrates fabrication capacity serving Belt and Road infrastructure projects across Central Asia.
Australia
Mining extension projects in Western Australia generate concentrated demand for rock trencher variants attacking granite and basalt formations. State-level occupational safety regulations govern operator protection specifications for excavation equipment deployment. Perth-based equipment rental networks are expanding inventories to service quarry operations in the Pilbara region.
Trencher Attachments Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a market structure that fragments between captive OEM distribution networks and independent attachment fabricators. Tier-one manufacturers anchor positions through backward integration into cutting tool metallurgy and hydraulic system standardization. Three strategic archetypes dominate: full-line construction equipment OEMs with captive attachment portfolios, specialized trencher manufacturers with dedicated distribution, and independent fabricators serving rental fleet aftermarket demand. Competitive moves concentrate on M&A absorption of regional attachment specialists and capacity expansion into carbide-composite cutting tool production.
Among North American equipment manufacturers, Vermeer Corporation and Caterpillar Inc. exemplify channel-controlling archetypes through captive dealer networks, while Bobcat Company occupies a position emphasizing compact-platform specialization for tight-access job sites. AFT Trenchers Ltd. represents the European precision-fabrication tier serving export markets with ISO-certified attachment systems. These three anchors illustrate the geographic and strategic segmentation governing competitive positioning.
| Leading Market Players |
|---|
| Bobcat Company |
| Vermeer Corporation |
| Caterpillar Inc. |
| Case Construction Equipment |
| Ditch Witch |
| Toro Company |
| AFT Trenchers Ltd. |
| Erskine Attachments LLC |
| Kubota Corporation |
| Others |
Value Network & Pricing Analysis
The Yangtze River Delta to Port of Los Angeles container corridor absorbs freight cost volatility that compresses margins for carbide-tipped cutting tool suppliers while amplifying price differentiation between OEM-verified bundles and third-party alternatives in the United States utility contractor segment.
Pricing Analysis
Cost-plus contracts with steel alloy indexation dominate procurement for hardened chain materials, with pricing stratifying across premium carbide-composite configurations, standard hardened steel arrays, and economy-grade wheel trencher variants. Price differentiation hinges on ISO 10261 certification tier and after-sales service bundling. Pricing pressure stems from steel alloy price volatility compressing fabricator margins. Municipalities exhibit highest price sensitivity, while electric utilities demonstrate lowest sensitivity due to federal electrification mandate urgency.
Supply Chain Analysis
Export-control regimes on advanced carbide sintering technology limit flows from Germany to Chinese fabricators, concentrating precision cutting tool supply in Baden-Württemberg and the United States industrial belt. Raw material dependencies center on tungsten carbide powder, high-grade steel alloys, and hydraulic quick-coupler castings. Supply chain risk manifests in single-source vulnerability for carbide-composite formulations. Distribution runs through captive OEM dealer networks and independent rental yard wholesalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized hydraulic technician scarcity constrains dealer service capacity and field support, creating competitive advantage for stakeholders who secure this capability layer through training pipelines or acquisition.
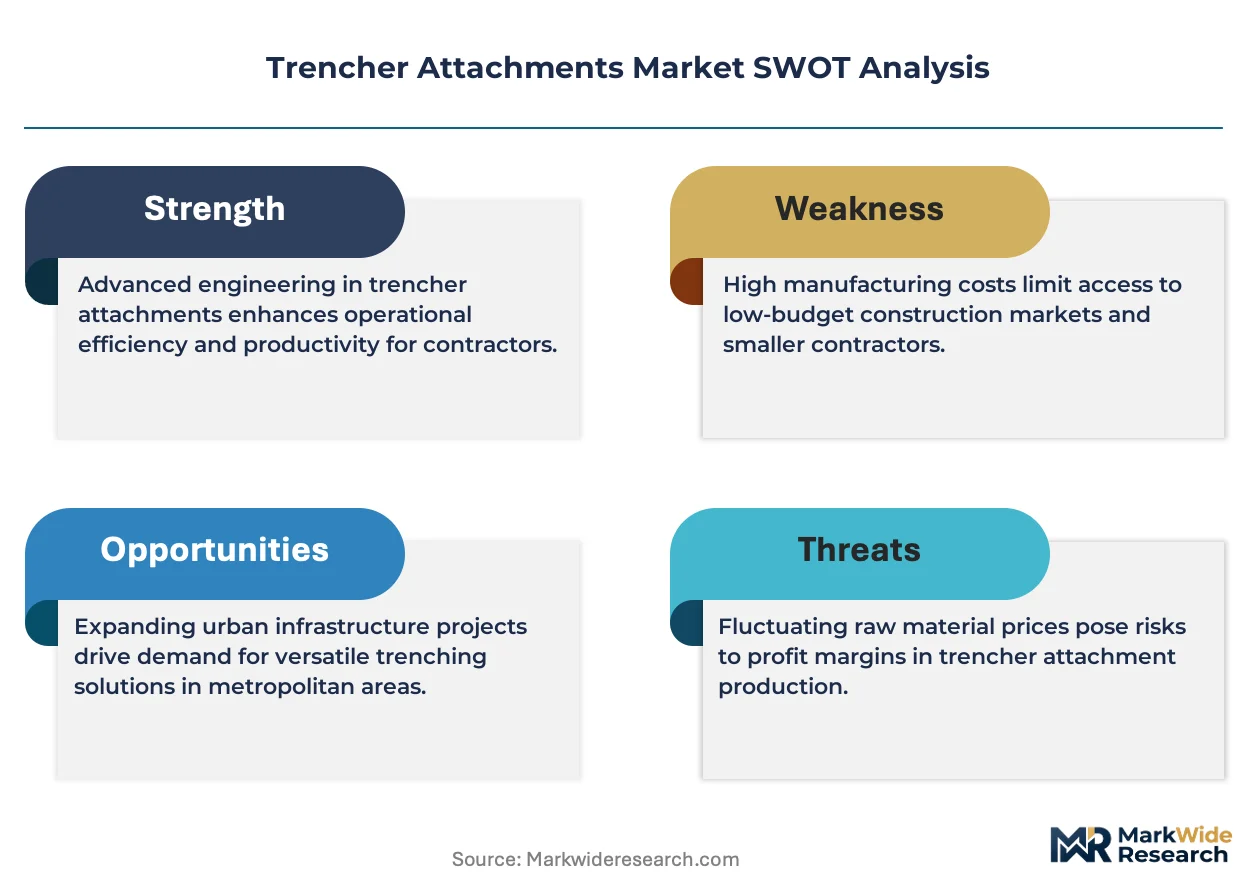
For Market Incumbents: Build captive metallurgy moats through backward integration into carbide-composite cutting tool production and ISO 10261 validation protocol acceleration. Consolidate regional attachment specialists to neutralize independent fabricator threats. Expand capacity in Texas and Florida rental fleet corridors where project volatility favors flexible equipment access. For New Entrants and Emerging Players: India's rural electrification mandates represent underpenetrated white space for compact trencher attachments suited to narrow agricultural rights-of-way. Target Maharashtra-based state power utilities with BIS-certified configurations. Pursue telematics-hydraulics convergence as differentiated go-to-market angle enabling attachment-as-a-service revenue models. For Investors and Strategic Acquirers: Precision-fabrication specialists with ISO-certified attachment systems and established export corridors to United States fiber-optic infrastructure projects offer prime acquisition profiles. Long-term viability rests on EPA Tier 4 Final compliance documentation capabilities and carbide-tipped tooth metallurgy expertise. Monitor OSHA excavation safety standard revisions as inflection indicator for aftermarket guarding and shielding retrofit demand.| Strategic Initiative | Industry Significance |
|---|---|
| Carbide-Composite Production Scale-Up | Backward integration into cutting tool metallurgy secures margin control against steel price volatility. |
| Hydraulic Quick-Coupler Standardization | Interoperability certification unlocks mixed-fleet procurement from United States utility contractors. |
| ISO 10261 Validation Acceleration | Compressed testing timelines enable faster product launches and international export eligibility. |
| Telematics-Hydraulics Platform Integration | Real-time flow monitoring enables predictive maintenance and attachment-as-a-service revenue. |
| India Distribution Channel Expansion | Maharashtra-based partnerships capture Central Electricity Authority rural electrification mandates. |
Research Methodology
A spread of perspectives from attachment product managers, hydraulic system engineers, rental fleet procurement directors, and utility contractor equipment supervisors converged on the working assumptions driving this analysis. Primary fieldwork combined with secondary validation from EPA emissions filings, OSHA safety standard dockets, ISO certification registries, and United States municipal infrastructure budget disclosures. Bottom-up unit economics triangulated against top-down market sizing across equipment type, application environment, and end-user organizational structure.
Demand-supply-balance framing anchored the analytical approach across the projection horizon, with segmentation modeling spanning trencher attachment architecture, soil abrasiveness tier, host machine compatibility class, and regional regulatory cluster. CAGRs derived from historical replacement cycle analysis and forward-looking fleet turnover assumptions. Industry-specific forecast inputs incorporated fiber-optic backbone deployment timelines and rural electrification mandate pacing from federal and state authorities.
Practitioners should monitor EPA Tier 4 Final enforcement intensity, steel alloy commodity price trajectories, and hydraulic technician labor market tightness for early signals of forecast deviation. Forecasts reflect documented assumptions on utility contractor procurement consolidation patterns and rental fleet unbundling velocity. Material shifts in federal infrastructure spending allocation or REACH chemical safety standard revisions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Cherry Picker Crane Market
Material Handling Equipment
Precision Ballscrews Market
Material Handling Equipment
Manual Lifting Light Tower Market
Material Handling Equipment
Cable Conduit Market
Material Handling Equipment
Pipe Jacking Machines Market
Material Handling Equipment
Slow Speed Shredding Machines Market
Material Handling Equipment
Asia-Pacific Forklift Truck Market
Material Handling Equipment
Bale Clamp Intensive Market
Material Handling Equipment
Linear Slides Market
Material Handling Equipment
Global Bucket Loader Market
Material Handling Equipment
Machined Springs Market
Material Handling Equipment
GCC Conveyor Belt Market
Material Handling Equipment
Helical Gear Market
Material Handling Equipment
Water Hose Market
Material Handling Equipment
North America Industrial Duct for Dust Collection Market
Material Handling Equipment
Australia and New Zealand Industrial Fasteners Market