
 Europe Port Equipment Market | 2026-2036
Europe Port Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Port Equipment Market Insights
Polish Baltic port expansion is narrowing the capacity gap with legacy North Sea hubs. Konecranes leverages its automation pedigree to anchor terminal upgrade cycles across Gdansk and Szczecin. Liebherr sustains engineering intensity in heavy-lift crane architectures for wind component handling. Kalmar competes through integrated terminal operating system compatibility.
Europe port equipment encompasses mobile harbor cranes, ship-to-shore gantries, straddle carriers, and automated guided vehicles engineered for lift capacities exceeding fifty tons and twenty-four-hour operational cycles in saline-corrosive environments. Crane Systems dominate capital allocation as mega-vessel calls require outreach specifications above sixty meters, while Electrification segments attract retrofit investment as shore power mandates harden. Automation Solutions represent the fastest-growing technology category as terminal operators prioritize berth productivity over incremental manual labor expansion.
The EU Green Deal's Fit for 55 framework and the F-Gas Regulation constrain diesel-powered equipment procurement while ECHA chemical compliance requirements affect hydraulic fluid formulations and coating systems. Terminal operators must now reconcile CAPEX cycles with CSRD disclosure timelines and emerging EU AI Act risk classifications for autonomous yard equipment. Stakeholders should track how port authority concession renegotiations embed decarbonization clauses as binding performance standards.
Market Dynamics
Terminal operators across Northern Europe face simultaneous pressure from EU Green Deal electrification mandates and mega-vessel capacity requirements, forcing synchronized retrofit cycles that compress traditional equipment replacement timelines.
Growth Catalysts
- EU Green Deal port electrification:Shore power mandates under Fit for 55 are compelling terminal operators to accelerate procurement of electric ship-to-shore gantries and automated guided vehicles with battery architectures.
- Mega-vessel deployment:Ocean carriers operating 24,000+ TEU vessels are demanding outreach specifications above sixty meters, driving replacement of legacy crane systems in Hamburg, Rotterdam, and Antwerp.
- Polish Baltic corridor expansion:Capacity investments at Gdansk and Szczecin are creating synchronized demand for mobile harbor cranes and straddle carriers as hinterland connectivity upgrades proceed.
Market Restraints
- Steel and copper input volatility:Crane superstructure fabrication depends on commodity markets where price swings distort project budgeting cycles for terminal operators.
- Automation component supply concentration:Sensor arrays and drive systems for autonomous yard equipment concentrate among German and Nordic subsystem suppliers, creating delivery bottlenecks.
- ECHA chemical compliance friction:Hydraulic fluid formulations and coating systems face reformulation timelines that extend equipment certification cycles by twelve to eighteen months.
Strategic Opportunities
- Wind component handling specialization:North Sea offshore wind installation ports require heavy-lift crane architectures with lift capacities exceeding eighty tons for nacelle and blade logistics.
- CSRD-aligned equipment financing:Terminal operators can structure concession renegotiations to embed decarbonization clauses as binding performance standards with port authorities.
- Retrofit automation kits:Existing diesel-powered straddle carriers and reach stackers present addressable installed base for electrification and autonomous navigation upgrades.
Industry Challenges
- Electrical systems integration expertise:Terminal engineering teams lack depth in high-voltage shore connection infrastructure and battery thermal management for twenty-four-hour operational cycles.
- EU AI Act risk classification:Autonomous yard equipment faces emerging compliance timelines for safety-critical algorithm documentation that vendors have not yet standardized.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Port Equipment Market |
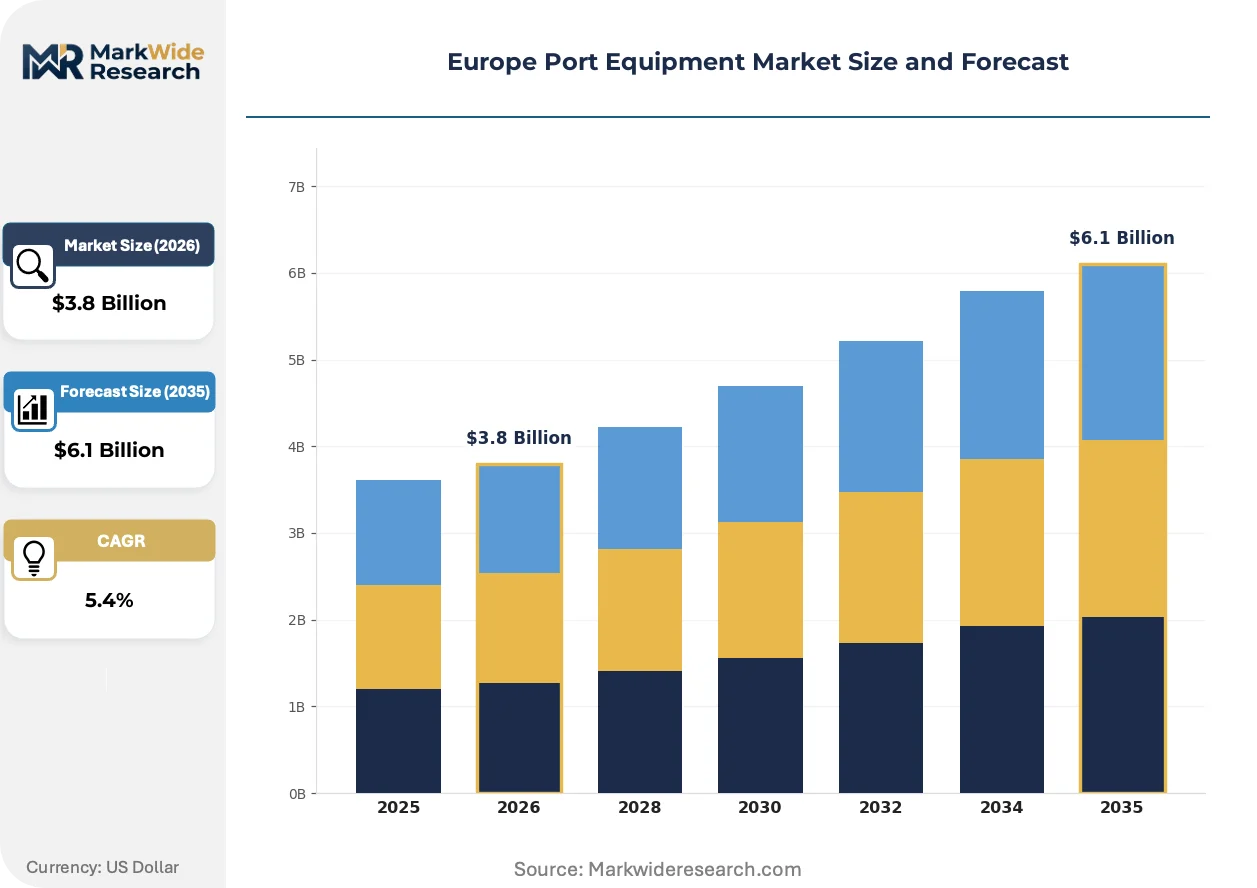
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.1 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crane Systems, Container Handling Equipment, Bulk Handling Equipment, Tugboats Technology: Automation Solutions, Electrification, IoT Integration, Hybrid Technologies End User: Shipping Lines, Port Authorities, Freight Forwarders, Terminal Operators Application: Container Freight, Bulk Cargo, Ro-Ro Services, General Cargo |
| Companies Covered | Konecranes, Kalmar (Cargotec), Liebherr, ZPMC (Shanghai Zhenhua Heavy Industries), SANY, Terex Port Solutions, Hyster-Yale Group, Doosan Infracore, Svetruck, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Port Equipment Market Trends and Innovations
Digital twin architectures and predictive maintenance algorithms are redefining how terminal operators manage asset lifecycle costs across electrified equipment fleets.
Remote crane operation centers using 5G-connected sensor feeds are rendering obsolete traditional cabin-based operator deployment for ship-to-shore gantries. Rotterdam and Hamburg terminal operators are piloting centralized control rooms where single operators manage multiple crane cycles simultaneously. This compression of labor intensity per berth is rendering obsolete the historical correlation between vessel calls and headcount expansion.
The EU AI Act's risk classification framework for autonomous mobile equipment is mandating algorithmic transparency documentation that extends vendor development cycles. Terminal operators must now integrate safety-case submissions into procurement specifications. Heavy-lift crane segments face the steepest compliance burden due to collision-avoidance system criticality.
Leasing structures for electrified handling equipment are displacing traditional ownership models as operators seek to transfer battery degradation risk and technology obsolescence exposure. German and Dutch terminal groups are pioneering power-by-the-hour arrangements with OEMs. This preference shift is most pronounced in automated guided vehicle fleets where software update dependencies complicate asset valuation.
Europe Port Equipment Market Segmentation
Port equipment procurement patterns diverge sharply across operational contexts. Terminal operators prioritize electrification and automation to satisfy EU Green Deal mandates, while bulk cargo handlers emphasize durability metrics over connectivity features.
Product Type:
Cost tier determines capital allocation cycles and concession financing structures across European terminals.
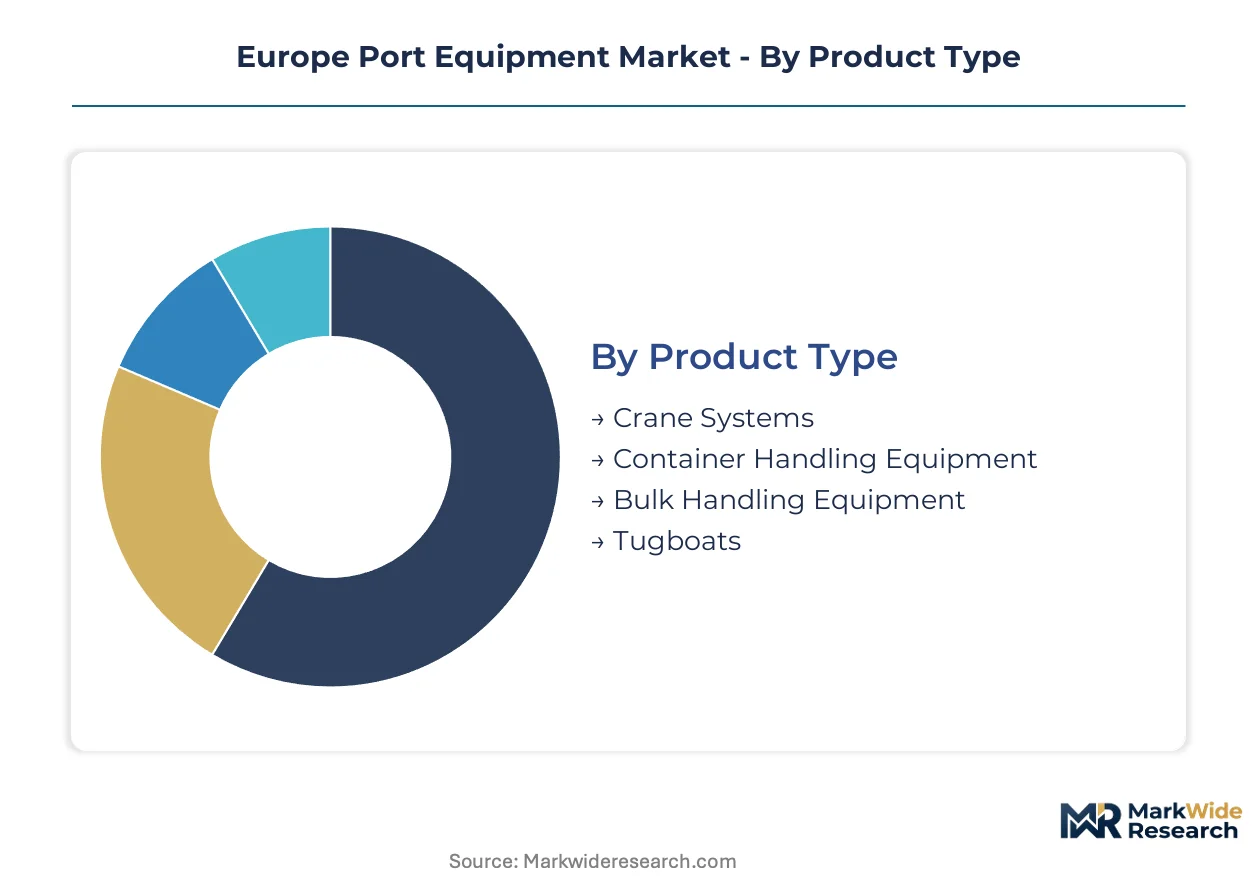
- Crane Systems:Ship-to-shore gantries and mobile harbor cranes engineered for outreach specifications exceeding sixty meters dominate procurement budgets. Hamburg and Rotterdam terminal operators are replacing legacy units to accommodate 24,000+ TEU vessel calls under compressed electrification timelines.
- Container Handling Equipment:Straddle carriers and reach stackers with automated guidance capabilities attract retrofit investment as Polish Baltic ports expand capacity. Gdansk terminal upgrades are synchronizing demand for electric-drive units with hinterland rail connectivity improvements.
- Bulk Handling Equipment:Grab cranes and conveyor systems serve grain and ore terminals at Antwerp and Bremen.
- Tugboats:Harbor assist vessels with hybrid propulsion architectures face extended certification cycles under ECHA chemical compliance for hydraulic fluids.
Crane Systems commands the established base. The steepest expansion runs through Container Handling Equipment.
Technology:
Application context determines which technology layers deliver measurable berth productivity gains versus regulatory compliance alone.
- Automation Solutions:Sensor arrays and autonomous navigation systems for yard equipment are redefining labor deployment models. Remote crane operation centers in Rotterdam are piloting single-operator multi-crane control using 5G-connected sensor feeds, compressing headcount per berth.
- Electrification:Battery architectures and shore power integration dominate procurement specifications under Fit for 55 mandates. German terminal operators are structuring power-by-the-hour leasing arrangements with OEMs to transfer battery degradation risk.
- IoT Integration:Predictive maintenance algorithms and digital twin architectures reduce unplanned downtime for electrified fleets.
- Hybrid Technologies:Dual-fuel systems serve as transitional architectures where full electrification faces infrastructure constraints.
Electrification captures the largest committed capital. Automation Solutions is climbing the fastest as EU AI Act compliance timelines harden.
End User:
Volume concentration and concession tenure length shape procurement authority and technology risk tolerance.
- Terminal Operators:Private concession holders at Rotterdam, Antwerp, and Hamburg control the majority of electrification and automation investment. These entities are embedding decarbonization clauses into port authority renegotiations as binding performance standards.
- Port Authorities:Public entities set shore power infrastructure standards and CSRD disclosure timelines that constrain operator procurement choices.
- Shipping Lines:Ocean carriers exert equipment specification pressure through vessel size deployment and berth priority contracting.
- Freight Forwarders:Logistics intermediaries influence yard equipment utilization patterns through cargo consolidation behavior.
Terminal Operators hold procurement decision authority. Port Authorities are gaining leverage fastest through regulatory infrastructure mandates.
Application:
Customer type and cargo value density determine automation ROI thresholds and electrification payback periods.
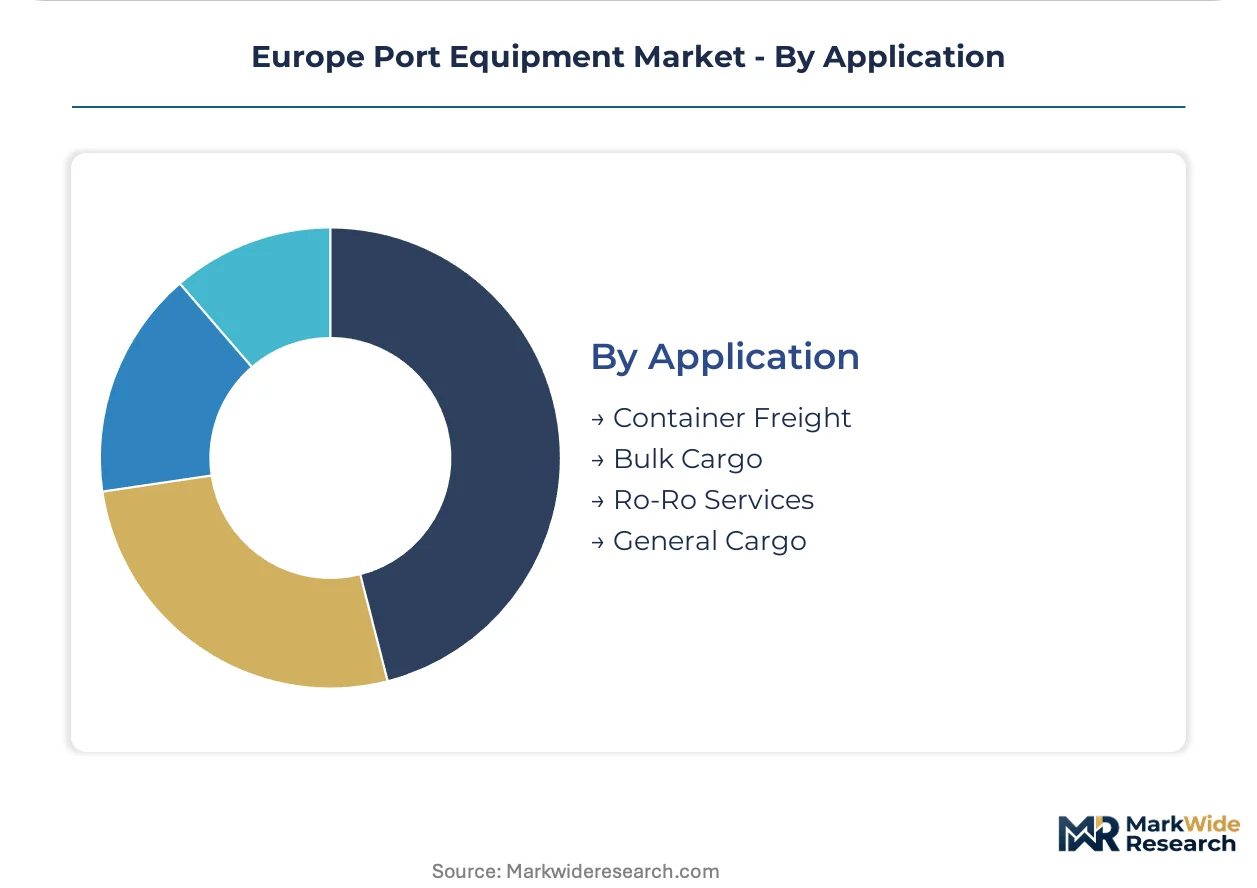
- Container Freight:High-volume, standardized box movements justify automated guided vehicle fleets and remote crane operation investments. The Hamburg-Le Havre corridor concentrates demand for synchronized capacity upgrades across competing terminals.
- Bulk Cargo:Grain, ore, and coal handling requires specialized grab crane architectures with corrosion-resistant coatings meeting ECHA reformulation timelines.
- Ro-Ro Services:Ferry and vehicle carrier terminals at Zeebrugge and Trelleborg prioritize ramp equipment interoperability over full automation.
- General Cargo:Breakbulk and project cargo handling maintains demand for mobile harbor crane flexibility at smaller Baltic and Mediterranean ports.
Container Freight anchors equipment revenue. Bulk Cargo is gaining share fastest as North Sea offshore wind component logistics expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Crane fabrication capacity clusters along the North Sea and Baltic coastlines where terminal electrification mandates are compressing equipment replacement cycles. German and Dutch engineering bases anchor supply-side output for automated gantry systems. Polish port expansion is redrawing procurement geography as Gdansk and Szczecin narrow the capacity gap with legacy Hamburg-Le Havre terminals.
Germany
Automated crane deployments at Hamburg and Bremerhaven terminals are synchronizing with shore power infrastructure upgrades under EU Green Deal timelines. The EU AI Act's risk classification framework is mandating algorithmic documentation for autonomous yard equipment before berth certification. KBA technical standards for high-voltage shore connections are extending vendor qualification periods for electrical system integrators.
Netherlands
Rotterdam terminal operators are piloting remote crane operation centers using 5G-connected sensor feeds to compress labor deployment per berth. CSRD disclosure timelines are embedding decarbonization clauses into port authority concession renegotiations as binding performance standards. The Maasvlakte complex is concentrating demand for electric ship-to-shore gantries with outreach specifications above sixty meters.
Belgium
Antwerp's Deurganck Dock automation upgrades are driving procurement of straddle carriers with battery architectures compliant with F-Gas Regulation constraints. ECHA chemical compliance requirements are extending hydraulic fluid reformulation timelines for heavy-lift crane certification. The port's wind component handling specialization is requiring lift capacities exceeding eighty tons for nacelle logistics.
Poland
Gdansk and Szczecin terminal expansions are creating synchronized demand for mobile harbor cranes as hinterland rail connectivity upgrades proceed. EU Green Deal port electrification mandates are reshaping procurement criteria for handling equipment at Baltic hubs. The Polish Baltic corridor is narrowing the capacity gap with North Sea terminals through coordinated infrastructure investments.
United Kingdom
Felixstowe and London Gateway terminal operators are retrofitting diesel-powered reach stackers with electrification kits to satisfy Fit for 55 shore power mandates. The UK's divergence from EU REACH frameworks is creating parallel chemical compliance pathways for coating systems and hydraulic fluids. North Sea offshore wind installation ports at Hull and Grimsby are specializing in heavy-lift crane architectures for blade and tower component handling.
Europe Port Equipment Market Competitive Landscape
Engineering-intensive specialists and integrated automation providers split the market along technology depth versus system breadth lines. The vendor base concentrates among Nordic and German fabrication clusters where crane superstructure expertise overlaps with autonomous navigation development. Three archetypes dominate: heavy-lift engineering houses with wind component specialization, integrated port technology platforms with terminal operating system compatibility, and scale-driven fabricators with cost-optimized mobile equipment portfolios. Competitive moves center on electrification retrofit partnerships with terminal operators and automation component supply alliances with sensor subsystem vendors.
Among Nordic engineering groups, Konecranes anchors the automation pedigree archetype through its terminal upgrade positioning across Gdansk and Szczecin. Liebherr occupies a position exemplifying heavy-lift crane architecture intensity for wind component handling segments. Kalmar represents the integrated platform approach through terminal operating system compatibility as a competitive anchor. These three companies illustrate how vendor strategy diverges between deep engineering specialization and broad system integration.
| Leading Market Players |
|---|
| Konecranes |
| Kalmar (Cargotec) |
| Liebherr |
| ZPMC (Shanghai Zhenhua Heavy Industries) |
| SANY |
| Terex Port Solutions |
| Hyster-Yale Group |
| Doosan Infracore |
| Svetruck |
| Others |
Pricing and Supply Chain Analysis
Steel and copper commodity volatility compresses pricing tier spreads while forcing terminal operators toward longer-term offtake contracts with Nordic and German fabrication clusters. This input-cost uncertainty simultaneously widens the premium attached to electrified equipment with guaranteed battery performance and reshapes procurement toward leasing structures that transfer degradation risk.
Pricing Analysis
The EU Green Deal's Fit for 55 framework dictates the pricing tier structure across European port equipment procurement. Three-tier pricing stratifies across premium automation-integrated systems, standard electrified units with shore power compatibility, and economy-grade diesel retrofit kits for shorter concession tenures. Price differentiation hinges on CE marking tier for high-voltage electrical systems and volume scale of fleet deployment. Cost compression in the standard tier is intensifying because Polish Baltic terminal expansions are aggregating demand for mid-range mobile harbor cranes. Bulk cargo handlers at Antwerp and Bremen exhibit the highest price sensitivity due to commodity margin constraints, while Rotterdam container terminal operators prioritize automation ROI over unit cost.
Supply Chain Analysis
Crane superstructure feedstock draws from German, Swedish, and Finnish steel fabrication clusters where specialty alloy capacity concentrates. Raw material dependencies center on high-grade structural steel, copper winding for electric drive motors, and lithium-ion cell supply for battery architectures. Single-source vulnerability runs through German and Nordic sensor subsystem suppliers for autonomous navigation arrays. Distribution runs through OEM-direct contracting for large gantry systems and regional equipment distributors for mobile harbor crane portfolios.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue layers are expanding faster than hardware sales as power-by-the-hour leasing and predictive maintenance subscriptions capture terminal operator preference. Software update dependencies and battery lifecycle management are rendering pure equipment margins secondary to recurring revenue streams.
For Market Incumbents: Build switching-cost moats through terminal operating system integration that locks in automation and electrification upgrade cycles. Deepen backward integration into battery thermal management systems to capture margin from high-voltage shore connection infrastructure. Counter ZPMC and SANY cost-optimized entries by embedding CSRD disclosure tooling into equipment telemetry packages.
For New Entrants and Emerging Players: Build out retrofit automation kit offerings targeting Poland's Gdansk and Szczecin terminal expansions where hinterland connectivity upgrades create synchronized demand without incumbent vendor lock-in. Target the heavy-lift crane segment for North Sea offshore wind component handling, where lift capacity requirements exceeding eighty tons favor engineering specialization over scale. Pursue go-to-market partnerships with German electrical systems integrators facing extended KBA qualification periods.
For Investors and Strategic Acquirers: The EU AI Act's risk classification timeline reshapes the acquisition landscape toward vendors with standardized safety-case documentation for autonomous yard equipment. Long-term viability favors integrated port technology platforms over pure fabrication plays as software update dependencies compound. Target mid-cap automation subsystem specialists with sensor array expertise and existing German terminal operator relationships. Monitor ECHA chemical compliance certification progress as an inflection indicator for hydraulic fluid reformulation bottlenecks that could extend equipment delivery timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Electrification Retrofit Partnership | Captures installed base conversion demand at Felixstowe and London Gateway under Fit for 55 mandates. |
| Automation Component Supply Alliance | Secures sensor array availability from German and Nordic subsystem vendors facing delivery bottlenecks. |
| Terminal Operating System Integration | Locks in upgrade cycles through compatibility with Kalmar and Navis platforms at Rotterdam and Hamburg. |
| Wind Component Handling Specialization | Addresses North Sea offshore installation port demand for nacelle logistics at Hull and Grimsby. |
| Power-by-the-Hour Leasing Structure | Transfers battery degradation risk to OEMs while aligning German terminal operator CAPEX with CSRD timelines. |
Research Methodology
Cross-validation between terminal operator procurement directors and OEM aftermarket service heads anchors the qualitative findings in operational reality. Primary interviews encompassed maintenance directors at Rotterdam and Hamburg terminals, Konecranes and Liebherr regional sales engineers, port authority concession managers in Antwerp and Gdansk, and electrical systems integrators navigating KBA technical standards. Secondary validation drew from EU Green Deal regulatory filings, ECHA chemical compliance databases, customs trade data for steel and copper inputs, and SEC 10-K disclosures from listed equipment manufacturers. Bottom-up fleet deployment estimates triangulated against top-down port authority capacity expansion announcements.
Calibration against historical electrification retrofit adoption curves and automation deployment lag times shaped the projection framework across the analysis window. Segmentation dimensions modeled include product type tier, technology layer, end-user procurement authority, and application cargo category. CAGRs derived from equipment replacement cycle compression under EU Green Deal timelines and Polish Baltic corridor capacity additions. Industry-specific inputs encompassed shore power infrastructure buildout schedules and ECHA hydraulic fluid reformulation certification progress.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese scale fabricators or subsidy-backed battery OEMs would shift outcomes. Cross-checking against EU port authority concession renegotiation disclosure timelines is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Reinforced Ultrafine Mill Market
Material Handling Equipment
Middle East Conveyor Belts Market
Material Handling Equipment
Global Air Cannon System Market
Material Handling Equipment
Gas Connectors and Gas Hoses Market
Material Handling Equipment
Hook Lifts and Skip Loaders Market
Material Handling Equipment
East Africa Elevator and Escalator Market
Material Handling Equipment
North America Screw Conveyor Market
Material Handling Equipment
Industrial Piggable Wye Fitting Market
Material Handling Equipment
Motorized Decoiler Machine Market
Material Handling Equipment
Wood Chipper Market
Material Handling Equipment
Pneumatic Conveying Diverters Market
Material Handling Equipment
Carry Deck Crane Market
Material Handling Equipment
Pharmaceutical Material Handling Equipment Market
Material Handling Equipment
Dump Tubs Market
Material Handling Equipment
Hot-Rolling Mill and Cold-Rolling Mill Market
Material Handling Equipment
Trommel Screen Market