
 India Automated Material Handling (AMH) Market | 2026-2036
India Automated Material Handling (AMH) Market Size, Share, and Industry Trends Forecast 2026-2036
India Automated Material Handling (AMH) Market Foresight
Single-source reliance on European AMH imports is decoupling as Indian manufacturers build captive component ecosystems. Godrej Consoveyo Logistics Automation Limited anchors domestic conveyor and crane system production with deep backward integration into steel fabrication and control systems. Addverb Technologies Limited specializes in autonomous mobile robots and AI-driven warehouse orchestration software, competing directly with multinational integrators on deployment speed. Daifuku India Private Limited leverages its parent group's global engineering protocols to sustain premium positioning in automotive assembly line contracts.
Automated material handling encompasses electromechanical systems, sensor networks, and control software that transport, store, and retrieve goods with minimal human intervention, typically operating at throughput rates exceeding manual methods by an order of magnitude. These installations serve to compress order cycle times, reduce inventory damage, and enable real-time traceability across distribution networks. Warehouse Management applications command the largest installed base as third-party logistics operators expand multi-client fulfillment campuses near consumption centers. Robotics technology represents the fastest-expanding segment, with articulated arms and mobile platforms displacing fixed conveyor infrastructure in facilities requiring reconfigurable layouts. Automated Storage Systems and AS/RS product categories concentrate margin pools where vertical space utilization exceeds eighty percent and retrieval precision tolerances tighten.
BIS certification requirements for industrial machinery safety and CEA electrical standards shape equipment design and import compliance timelines for AMH vendors operating in India. The PLI scheme for specialty steel and electronic components indirectly reduces system costs by localizing upstream supply of racks, motors, and drives. Stakeholders must monitor how DGFT's evolving rules of origin for automation hardware affect total landed cost against domestically assembled alternatives, while tracking state-level industrial corridor development that determines site selection for greenfield distribution facilities.
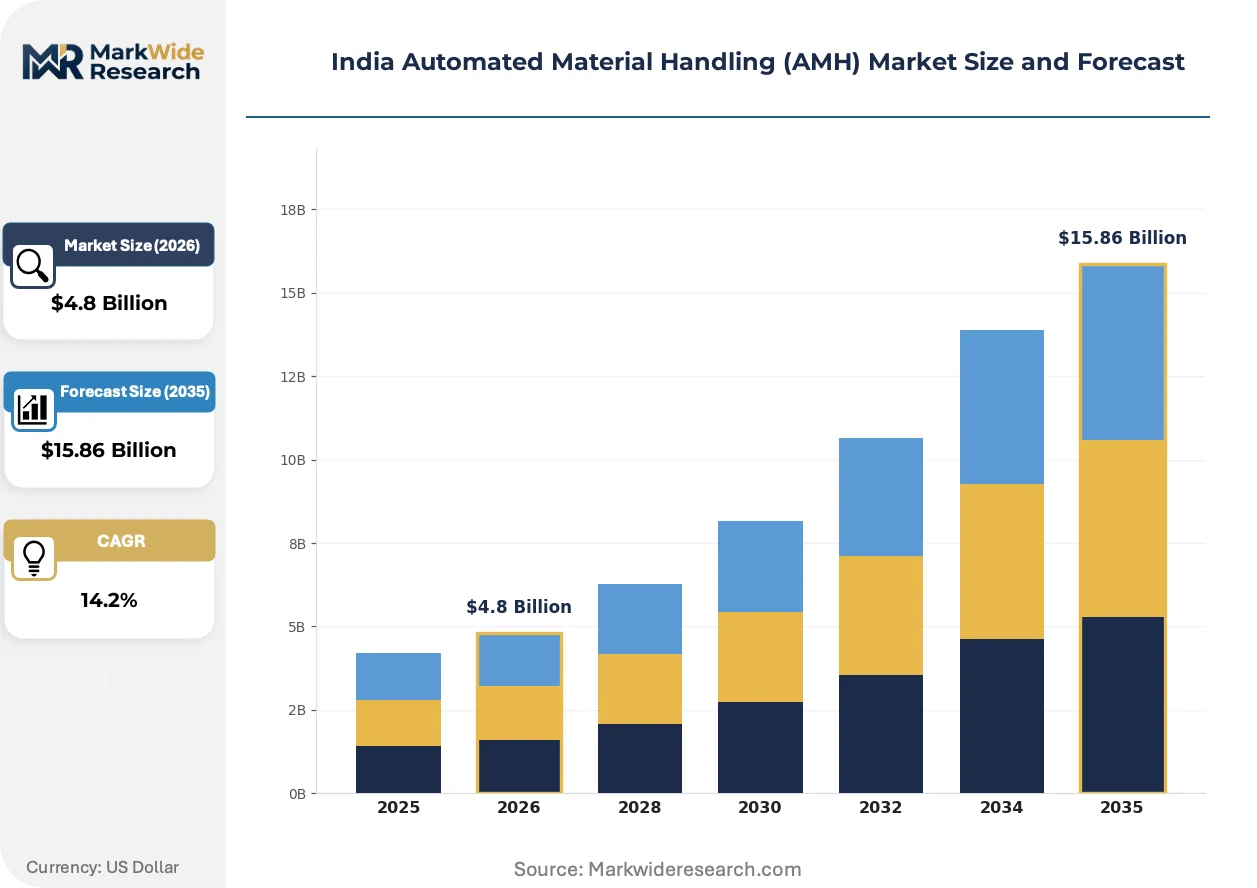
Market Dynamics
E-commerce fulfillment networks are compressing order cycle times to same-day delivery windows, forcing warehouse operators to reconfigure fixed conveyor infrastructure around autonomous mobile robots and AI-driven orchestration layers.
Growth Catalysts
- PLI scheme for manufacturing automation:The government's production-linked incentive framework subsidizes capital equipment purchases, redirecting industrial CAPEX toward automated storage and retrieval systems in automotive and pharmaceutical plants.
- Maharashtra's Pune-Mumbai corridor:Concentrated third-party logistics campuses near consumption centers generate clustered demand for multi-client AMH installations serving FMCG and electronics verticals.
- Articulated robotics:Six-axis arms with machine vision capabilities are penetrating mid-scale warehouses previously priced out of fixed automation, expanding addressable market depth.
Market Restraints
- Specialty steel input volatility:Rack structures and crane components depend on alloy steel grades whose landed costs fluctuate with DGFT duty adjustments and rupee-dollar movements.
- European controller dependency:Programmable logic controllers and servo drives remain concentrated with German and Italian suppliers, exposing integrators to extended lead times and currency risk.
- Power quality limitations:Industrial zones in tier-2 cities suffer voltage instability that degrades precision retrieval tolerances in AS/RS installations below acceptable thresholds.
Strategic Opportunities
- Karnataka's Bengaluru logistics cluster:Underpenetrated cold-chain AMH installations present white space as pharmaceutical exports expand temperature-controlled warehouse requirements.
- BIS-CEA dual certification:Streamlined safety and electrical standards compliance creates first-mover advantage for domestic assemblers against import-dependent competitors.
- 5G private networks:Ultra-low latency connectivity is converging with edge-computing nodes to enable real-time fleet management of autonomous mobile robots in dense warehouse environments.
Industry Challenges
- Mechatronics skill scarcity:Maintenance technicians capable of diagnosing integrated sensor-actuator loops remain concentrated in Pune and Bengaluru, constraining nationwide deployment velocity.
- Legacy WMS integration:Proprietary warehouse management software from the 2010s lacks API architectures compatible with modern orchestration platforms, forcing costly middleware development.
- CEA electrical certification timelines:Bureaucratic approval cycles for high-tension industrial installations extend project commissioning by four to six months beyond mechanical completion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Automated Material Handling (AMH) Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.86 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
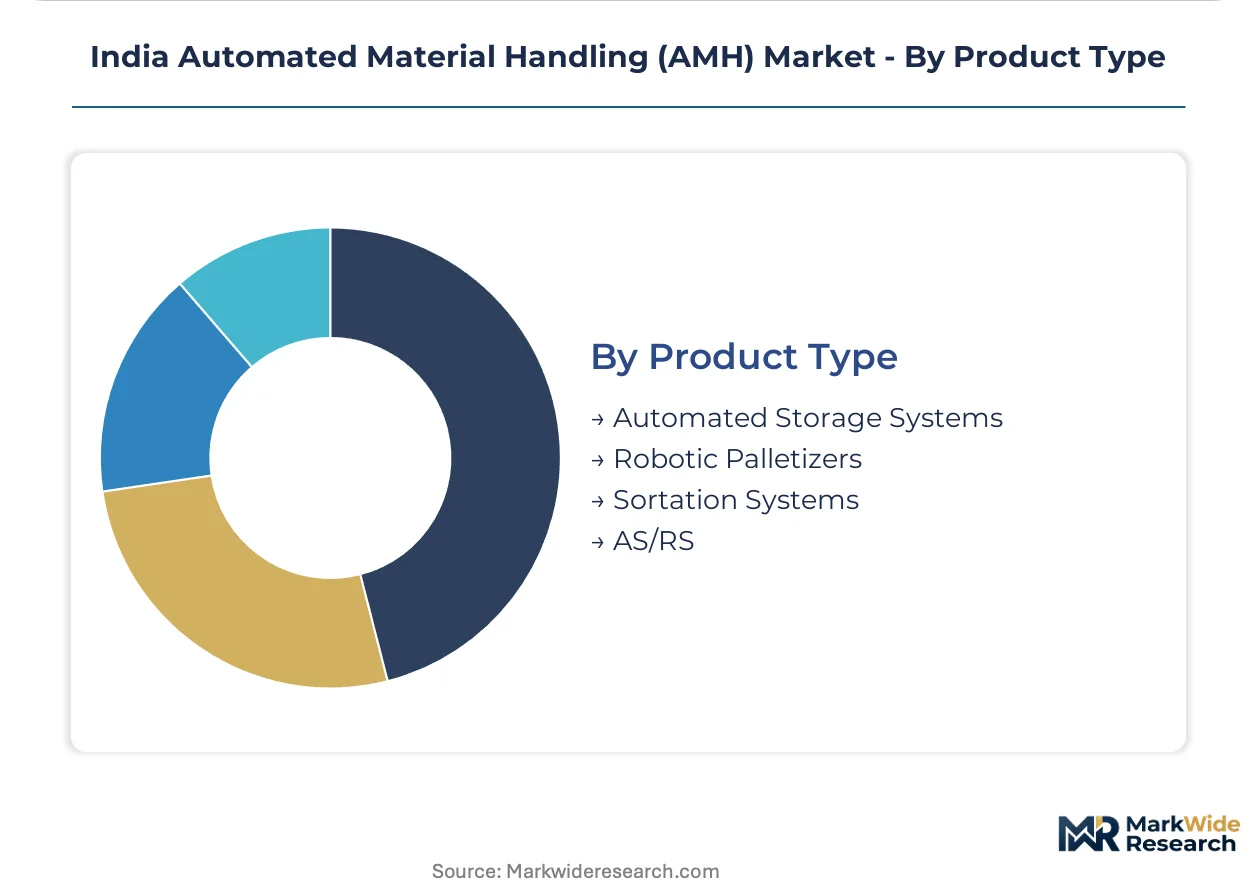
| Segmentation | Application: Warehouse Management, Assembly Line, Packaging, Order Fulfillment Technology: Automated Guided Vehicles, Robotics, Sorting Systems, Conveyor Systems End User: Retail, Automotive, Pharmaceuticals, E-Commerce Product Type: Automated Storage Systems, Robotic Palletizers, Sortation Systems, AS/RS |
| Companies Covered | Daifuku India Private Limited, Godrej Consoveyo Logistics Automation Limited, Kardex India Storage Solutions Private Limited, Honeywell Intelligrated India Private Limited, Schaefer Systems International Private Limited, GreyOrange Pte. Ltd., Addverb Technologies Limited, Murata Machinery India Private Limited, Armstrong Dematic Private Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Automated Material Handling (AMH) Market Shifts & Advancements
Sensor fusion and edge intelligence are redefining throughput benchmarks. Three developments are compressing deployment cycles and reshaping vendor competitive position.
Computer vision systems with depth-sensing arrays are converging with predictive maintenance algorithms to eliminate unplanned downtime in high-velocity sortation environments. Pharmaceutical distributors operating 24-hour fulfillment campuses are adopting these platforms fastest. The technology is converging with digital twin simulations to pre-validate layout configurations before physical installation, cutting commissioning risk.
BIS certification mandates for industrial machinery safety are tightening control system architecture requirements. The regulator's evolving electromagnetic compatibility standards now demand shielded cabling and isolated power supplies that add material cost but reduce field failure rates. Automotive assembly integrators are responding by pre-certifying modular subassemblies rather than validating complete systems post-installation.
Third-party logistics operators are unbundling equipment ownership from operational responsibility. Asset-light contract structures now transfer AMH capital risk to integrators who charge per-pallet-handled fees. This model is penetrating fastest in Maharashtra's multi-client fulfillment campuses where occupancy volatility makes fixed-cost ownership uneconomical for warehouse tenants.
India Automated Material Handling (AMH) Market Segmentation
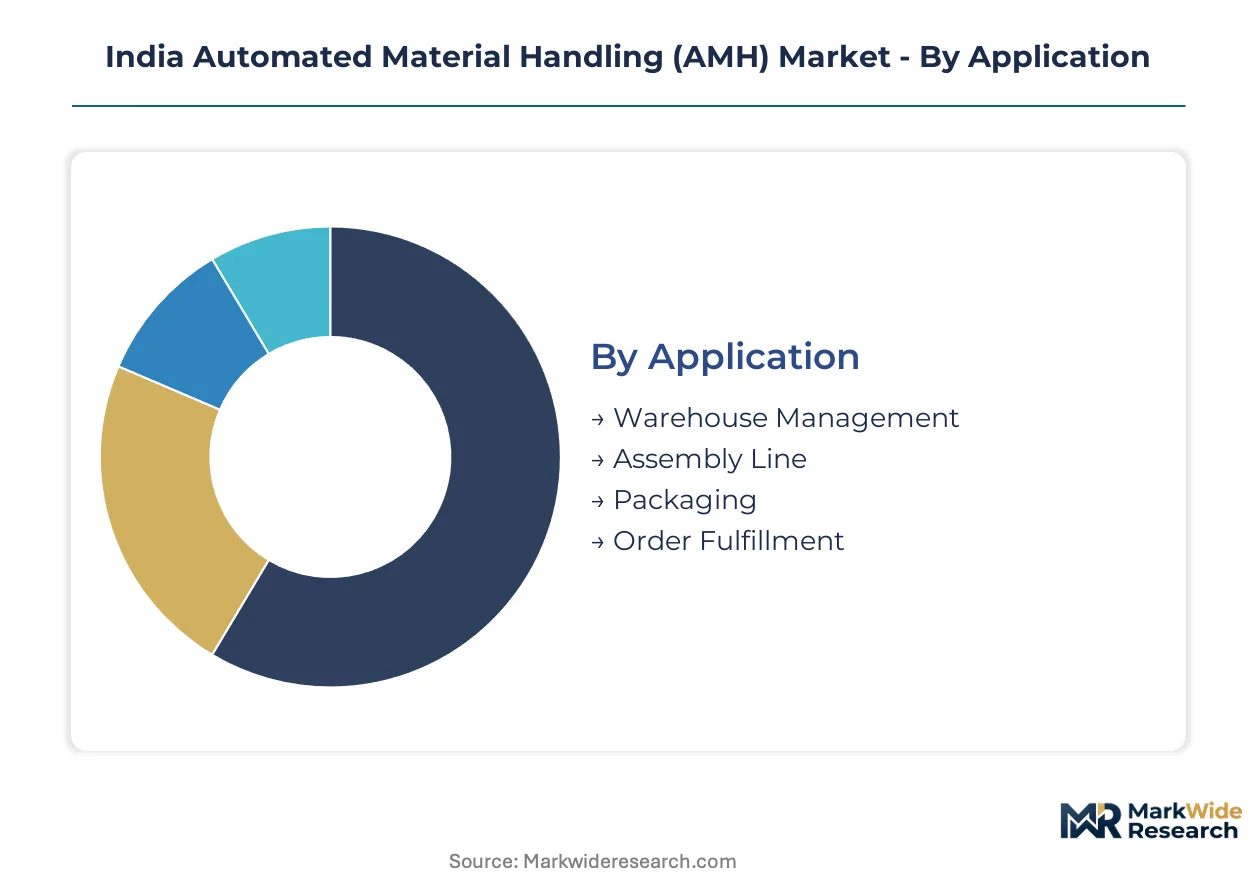
Segmentation reveals how BIS machinery safety and CEA electrical certifications apply differentially across AMH equipment classes. Procurement patterns diverge sharply between automotive assembly integrators seeking pre-certified modular subassemblies and e-commerce operators prioritizing rapid deployment over compliance depth.
Application:
BIS certification timelines stretch longest for segments involving continuous human-robot collaboration, while CEA high-tension approvals concentrate in heavy-load material movement.
- Warehouse Management:Multi-client fulfillment campuses in Maharashtra's Pune-Mumbai corridor drive concentrated demand for AS/RS and conveyor networks. Third-party logistics operators favor pre-certified modular installations to compress commissioning cycles amid occupancy volatility.
- Order Fulfillment:Same-day delivery mandates from e-commerce platforms are accelerating autonomous mobile robot deployments with AI-driven orchestration layers. Karnataka's Bengaluru cluster shows fastest adoption of sensor-fusion sortation for pharmaceutical cold-chain exports.
- Assembly Line:Automotive plants require BIS-compliant safety interlocks and CEA-certified servo drives for synchronized conveyor pacing.
- Packaging:FMCG facilities prioritize compact robotic palletizers with simplified electrical architectures to expedite state-level factory licensing.
Leading the category by volume: Warehouse Management. Growing fastest: Order Fulfillment.
Technology:
Cost tiers separate established electromechanical systems from emerging robotics platforms requiring specialized maintenance capabilities.
- Robotics:Six-axis articulated arms with machine vision penetrate mid-scale warehouses previously priced out of fixed automation. Pune and Bengaluru concentrate the scarce mechatronics technicians capable of diagnosing integrated sensor-actuator loops.
- Automated Guided Vehicles:Magnetic tape and laser-guided platforms dominate automotive assembly for predictable path routing. Tier-2 city power quality limitations constrain deployment in precision retrieval applications.
- Conveyor Systems:Belt and roller configurations from Godrej Consoveyo anchor domestic production with captive steel fabrication.
- Sorting Systems:Cross-belt and tilt-tray sorters integrate computer vision for pharmaceutical distributor 24-hour campuses.
Highest margin pool: Robotics. Steepest volume expansion: Automated Guided Vehicles.
End User:
Application maturity varies by sector regulatory burden and capital intensity.
- E-Commerce:Fulfillment networks compress order cycle times through asset-light contract structures transferring AMH capital risk to integrators. Per-pallet-handled fee models penetrate fastest in Maharashtra's multi-client campuses.
- Automotive:Assembly line contracts demand Daifuku's global engineering protocols for synchronized conveyor pacing and robotic welding integration. PLI scheme subsidies redirect CAPEX toward automated storage in powertrain plants.
- Pharmaceuticals:CDSCO compliance requirements and temperature-controlled exports drive cold-chain AMH investment in Karnataka.
- Retail:Omnichannel distribution centers balance seasonal demand volatility against fixed automation ownership costs.
Deepest installed base: Automotive. Fastest technology refresh: E-Commerce.
Product Type:
Vertical space utilization rates and retrieval precision tolerances determine margin concentration.
- AS/RS:Automated storage and retrieval systems command premium positioning where vertical space utilization exceeds eighty percent. Voltage instability in tier-2 industrial zones degrades retrieval tolerances below acceptable thresholds.
- Automated Storage Systems:Shuttle-based and crane-based configurations localize rack production under PLI scheme specialty steel incentives. DGFT duty adjustments on alloy grades expose integrators to input cost volatility.
- Robotic Palletizers:Articulated arm configurations serve FMCG and pharmaceuticals with compact footprints for brownfield warehouse retrofits.
- Sortation Systems:Cross-belt platforms integrate with 5G private networks for real-time fleet management in dense environments.
Largest revenue concentration: AS/RS. Gaining share fastest: Automated Storage Systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty steel fabrication clusters in Maharashtra and Karnataka anchor India's AMH supply base, with alloy-grade inputs flowing from Jamshedpur and Bhilai to Pune-Mumbai and Bengaluru assembly plants. State-level industrial corridor development determines greenfield distribution facility site selection.
Maharashtra
Third-party logistics operators drive concentrated demand for multi-client AS/RS installations across the Pune-Mumbai corridor. The state's MIDC industrial area approvals prioritize automated warehousing in FMCG and electronics verticals. Chakan and Talegaon industrial zones host captive conveyor fabrication facilities serving automotive assembly integrators.
Karnataka
Pharmaceutical cold-chain exports generate underpenetrated demand for temperature-controlled AMH in the Bengaluru logistics cluster. CDSCO compliance requirements mandate traceability systems that integrate with automated storage infrastructure. The state's Electronics City and Whitefield industrial corridors concentrate robotics deployment for e-commerce fulfillment.
Gujarat
Petrochemical and port logistics operators deploy heavy-load crane systems at Mundra and Hazira industrial hubs. DGFT duty adjustments on European servo drives extend lead times for precision retrieval equipment. Sanand and Halol automotive clusters absorb automated guided vehicles for powertrain component sequencing.
Tamil Nadu
CEA high-tension electrical certification timelines stretch project commissioning in Sriperumbudur and Oragadam industrial belts. Hyundai and Renault-Nissan assembly plants anchor demand for synchronized conveyor pacing systems. The state's electronics manufacturing zones under PLI scheme incentives drive capital equipment purchases for component handling.
Telangana
Hyderabad's pharmaceutical formulation corridors require BIS-compliant safety interlocks for human-robot collaborative packaging lines. The state's life sciences cluster generates demand for clean-room AMH installations with electromagnetic compatibility shielding. Genome Valley biotech parks represent emerging demand for automated cold storage retrieval systems.
India Automated Material Handling (AMH) Market Competitive Landscape
Global majors compete with regional champions across technology licensing and deployment velocity dimensions. The vendor base separates into three tiers: Japanese and European parents with Indian subsidiaries, domestic conglomerates with captive steel fabrication, and venture-backed robotics specialists. Strategic archetypes include premium-positioned system integrators, backward-integrated fabricators, and AI-native orchestration platforms. Competitive moves concentrate on modular subassembly pre-certification and asset-light contract structures transferring capital risk to integrators.
Among Japan-parented integrators, Daifuku India Private Limited exemplifies premium-tier positioning through global engineering protocol access. Domestic conglomerate Godrej Consoveyo Logistics Automation Limited anchors the backward-integrated archetype with captive steel supply chains. Venture-scaled Addverb Technologies Limited occupies the AI-native tier, competing on warehouse orchestration software deployment speed against established hardware vendors.
| Leading Market Players |
|---|
| Daifuku India Private Limited |
| Godrej Consoveyo Logistics Automation Limited |
| Kardex India Storage Solutions Private Limited |
| Honeywell Intelligrated India Private Limited |
| Schaefer Systems International Private Limited |
| GreyOrange Pte. Ltd. |
| Addverb Technologies Limited |
| Murata Machinery India Private Limited |
| Armstrong Dematic Private Limited |
| Others |
Supply & Pricing Matrix
Backward integration into captive steel fabrication and control system production anchors both supply security and margin protection for domestic AMH assemblers. Godrej Consoveyo's in-house production of rack structures and crane components insulates pricing power from DGFT duty volatility on European alloy grades.
Pricing Analysis
Extended warranty and preventive maintenance bundling separates premium-tier integrators from unbundled equipment-only vendors. Three-tier pricing structure across premium, standard, and economy levels tracks certification depth and deployment velocity. Cost compression in the standard tier intensifies as mid-scale warehouses demand six-axis arms with machine vision at fixed-automation price points. E-commerce operators show highest price sensitivity due to asset-light contract structures, while automotive assembly integrators absorb premium positioning for BIS-CEA dual-certified modular subassemblies.
Supply Chain Analysis
Specialty steel inputs rest on Jamshedpur and Bhilai domestic mills, with European and Japanese sources feeding precision servo drives and programmable logic controllers. Rack structures draw from PLI-incentivized local alloy production, while shielded cabling and isolated power supplies for electromagnetic compatibility compliance hinge on German and Italian component imports. Single-source vulnerability concentrates in high-tension electrical controllers, exposing integrators to rupee-dollar movements. Distribution runs through Maharashtra's Pune-Mumbai corridor and Karnataka's Bengaluru cluster, with tier-2 city power quality limitations constraining precision retrieval equipment deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Autonomous mobile robots and AI-driven orchestration layers are displacing fixed conveyor infrastructure, compressing the technology refresh cycle for warehouse operators.
For Market Incumbents: To counter venture-backed robotics specialists competing on deployment speed, Daifuku India and Godrej Consoveyo must pre-certify modular subassemblies under streamlined BIS-CEA protocols. Capacity addition in Karnataka's underpenetrated cold-chain corridor secures first-mover positioning before pharmaceutical export demand hardens. For New Entrants and Emerging Players: Enter via temperature-controlled AMH installations in Bengaluru's pharmaceutical logistics cluster, where CDSCO traceability mandates outpace incumbent response capacity. Karnataka's Genome Valley biotech parks represent the most penetrable white space, with clean-room automated cold storage retrieval systems commanding per-pallet-handled fee structures that transfer capital risk to integrators. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by Japanese and European parents seeking Indian deployment velocity. Long-term viability frames around AI-native orchestration platforms with recurring software revenue streams. The signal to watch is 5G private network rollout pace in dense warehouse environments, which determines real-time fleet management capability gaps.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Subassembly Pre-Certification | BIS-CEA streamlined compliance creates first-mover advantage against import-dependent competitors. |
| Cold-Chain AMH Capacity Expansion | Karnataka's pharmaceutical export corridors generate underpenetrated demand for temperature-controlled retrieval systems. |
| AI-Native Orchestration Platform Development | Addverb Technologies competes with multinational integrators on warehouse management software deployment speed. |
| 5G Private Network Integration | Ultra-low latency connectivity enables real-time autonomous mobile robot fleet management in dense environments. |
| Asset-Light Contract Structure Rollout | Per-pallet-handled fee models transfer AMH capital risk to integrators in Maharashtra's multi-client campuses. |
Research Methodology
Multi-period observation of PLI scheme capital allocation patterns and state-level industrial corridor development anchored the trend analysis, supplemented by interviews with warehouse operations directors, plant engineers at automotive assembly facilities, third-party logistics procurement leads, and aftermarket service heads. Secondary validation drew from BIS machinery safety filings, CEA electrical certification records, DGFT trade data, and state MIDC industrial area approval databases. Bottom-up equipment shipment tracking and top-down industrial CAPEX surveys triangulated market sizing.
Segment-weighting across technology, application, end user, and product type dimensions structured the analytical framework. Robotics and automated guided vehicles received distinct growth trajectories based on mechatronics technician concentration in Pune and Bengaluru. CAGRs derived from equipment replacement cycles, e-commerce fulfillment network expansion, and pharmaceutical cold-chain export growth assumptions. Power quality limitations in tier-2 cities and legacy WMS integration friction informed adoption curve adjustments.
Forecast precision tightens around the base case; tail outcomes carry wider variance under DGFT duty volatility and rupee depreciation scenarios. A small set of triggers warrants ongoing watch: 5G private network spectrum allocation timelines, PLI scheme extension decisions for specialty steel, and CEA high-tension certification backlog clearance rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Vapor Blasting Equipment Market
Material Handling Equipment
Mobile Conveyor Market
Material Handling Equipment
Pipe Wipers Market
Material Handling Equipment
Truck Mounted Cranes Market
Material Handling Equipment
Outdoor Power Equipment (OPE) Market
Material Handling Equipment
Industrial Belt Drives Market
Material Handling Equipment
Cam and Groove Fittings Market
Material Handling Equipment
Heavy Duty Ramp Market
Material Handling Equipment
Wear Plates Market
Material Handling Equipment
Australia Forklift Market
Material Handling Equipment
Robotic Palletizers and De-Palletizers Market
Material Handling Equipment
Drag Chain for Machine Market
Material Handling Equipment
Slag Handling Equipment Market
Material Handling Equipment
Cable Conduit Systems Market
Material Handling Equipment
Material Handling Equipment Tires Market
Material Handling Equipment
Heavy Duty Telehandler Market