
 Tree Milling Machine Market | 2026-2036
Tree Milling Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Tree Milling Machine Market Analytics
A skilled machinist shortage across industrial woodworking is bifurcating the competitive landscape into premium automation suppliers and value-tier manual equipment providers. DMG MORI Co., Ltd. leverages its CNC heritage to capture high-specification lumber processing contracts in Central Europe. Haas Automation, Inc. competes on configurability and aftermarket parts availability for mid-scale furniture manufacturers. Hurco Companies, Inc. specializes in conversational programming interfaces that reduce operator training burdens for smaller milling operations.
A tree milling machine is a stationary or portable powered cutting system that rotates multi-tooth cutters against fixed timber workpieces, typically achieving spindle speeds between 1,000 and 10,000 RPM depending on material density and cutter diameter. Its primary purpose is dimensioning raw logs and lumber stock into precise profiles, joinery components, and finished boards for downstream construction and furniture assembly. CNC product types command the dominant margin pool due to integration complexity and software dependency, while portable units represent the fastest-growing configuration as on-site timber processing gains traction in remote forestry operations. Digital technology adoption concentrates among manufacturer end users seeking batch consistency, whereas artisan and hobbyist segments sustain demand for manual and semi-automatic systems.
OSHA machine guarding standards in the United States mandate interlocked enclosures and emergency stop systems on industrial milling equipment, elevating compliance costs for non-automated suppliers. The EU Machinery Directive and CE marking requirements enforce noise emission limits and vibration exposure thresholds that reshape product design priorities for European market access. Stakeholders must monitor evolving carbon accounting rules for timber processing equipment as sustainability-linked procurement criteria penetrate construction supply chains.
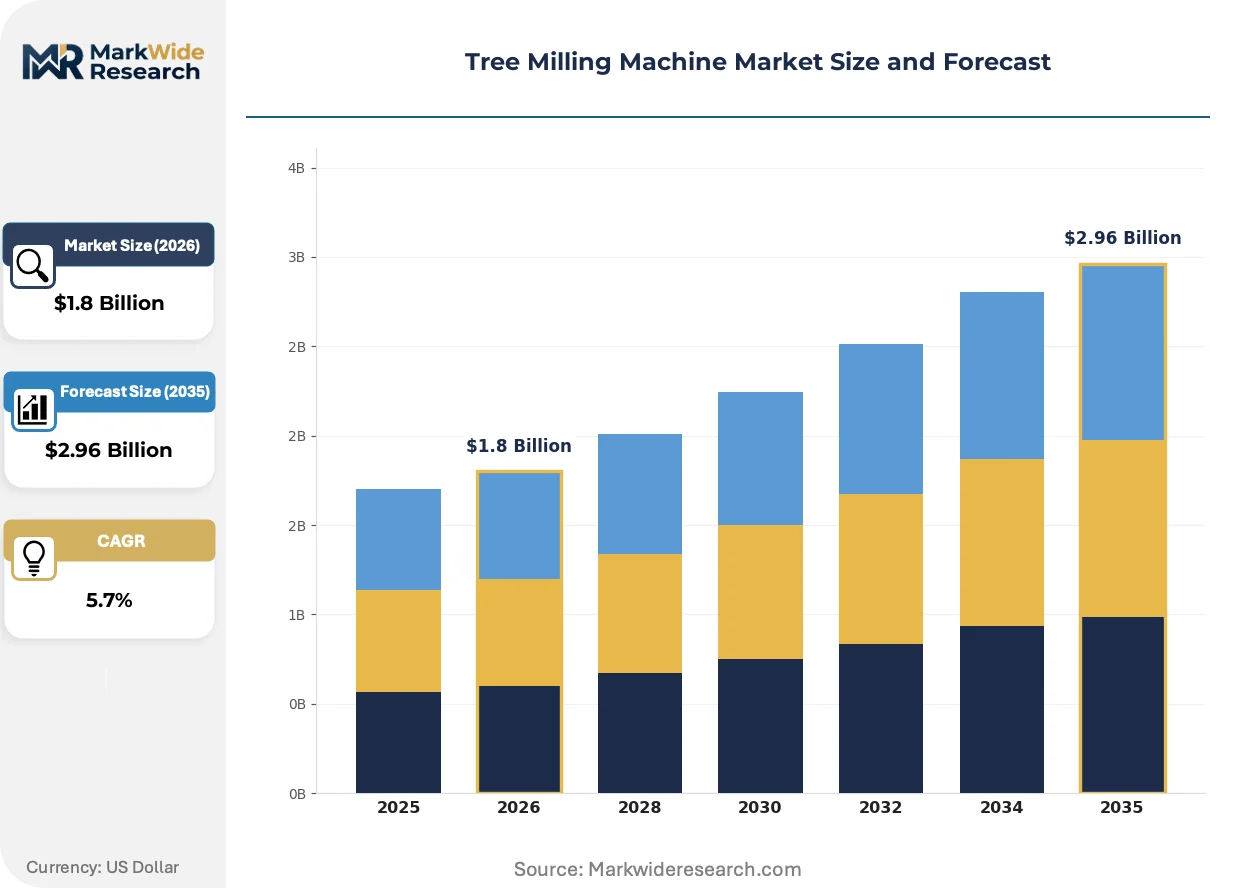
Market Dynamics
Automation pressure from furniture manufacturers seeking batch consistency is compressing margins for manual equipment suppliers while elevating CNC system deployment across Central European precision engineering clusters.
Growth Catalysts
- EU Machinery Directive:CE marking requirements for automated woodworking equipment are accelerating CNC adoption as manufacturers retrofit facilities to meet noise emission and vibration exposure thresholds for European market access.
- Remote forestry operations:Portable tree milling configurations are gaining traction in on-site timber processing where infrastructure limitations prevent centralized milling facility construction.
- Furniture manufacturing:Batch consistency demands from contract furniture producers are pulling advanced spindle control systems into mid-scale production environments previously served by manual equipment.
Market Restraints
- Specialized cutter supply:Carbide insert and high-speed steel tooling production concentrates among German and Japanese suppliers, exposing purchasers to input cost volatility and extended lead times.
- OSHA compliance burden:Interlocked enclosure and emergency stop system mandates elevate capital requirements for non-automated equipment manufacturers serving the US market.
- Manual system substitution:Artisan and hobbyist segments sustain demand for semi-automatic equipment that limits addressable premium for full CNC integration at smaller scale.
Strategic Opportunities
- Conversational programming interfaces:Operator training burden reduction through intuitive control systems opens CNC adoption pathways for smaller milling operations with limited technical staffing.
- Sustainability-linked procurement:Carbon accounting rules penetrating construction supply chains create preference differentiation for timber processing equipment with documented lifecycle emissions profiles.
- Aftermarket parts availability:Configurable platform architectures enabling rapid component replacement are capturing mid-scale furniture manufacturer loyalty in North American markets.
Industry Challenges
- CNC programming proficiency:The skilled machinist shortage across industrial woodworking constrains operational scaling for automated system adopters despite capital availability.
- Legacy equipment integration:Retrofit complexity with existing dust collection and material handling infrastructure extends deployment timelines and elevates total project risk for facility upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tree Milling Machine Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Stationary, CNC, Mini-mill Application: Lumber Production, Furniture Making, Woodworking, Construction End User: Manufacturers, Contractors, Artisans, Hobbyists Technology: Manual, Semi-automatic, Fully Automatic, Digital |
| Companies Covered | DMG MORI Co., Ltd., Yamazaki Mazak Corporation, Haas Automation, Inc., Okuma Corporation, Doosan Machine Tools Co., Ltd., Hurco Companies, Inc., KNUTH Werkzeugmaschinen GmbH, Makino Milling Machine Co Ltd., FANUC Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tree Milling Machine Market Evolving Landscape
Digital control architectures and sustainability compliance frameworks are restructuring competitive advantage in timber processing equipment, separating suppliers capable of software-hardware integration from component assemblers.
Adaptive spindle control systems with real-time density compensation are bifurcating the equipment base. High-volume flooring manufacturers in Germany deploy these systems to optimize cutter life across variable hardwood inputs. The technology is bifurcating margin pools toward integrated platform suppliers while compressing standalone mechanical equipment valuations.
REACH chemical restrictions and evolving F-Gas Regulation thresholds are reshaping coolant and lubricant specifications for high-speed timber cutting. Equipment manufacturers must reformulate bearing seal materials and hydraulic fluid compatibility to maintain European market access. CNC system suppliers with in-house fluid engineering capabilities are capturing specification-setting roles in cross-border procurement.
Service unbundling is fragmenting traditional equipment-plus-maintenance contracts. Large furniture manufacturers in Austria and Switzerland now source predictive monitoring separately from hardware acquisition, pressuring integrated OEM service margins. Independent diagnostic specialists with timber-specific vibration analysis expertise are inserting themselves into multi-year equipment operating agreements.
Tree Milling Machine Market Segmentation
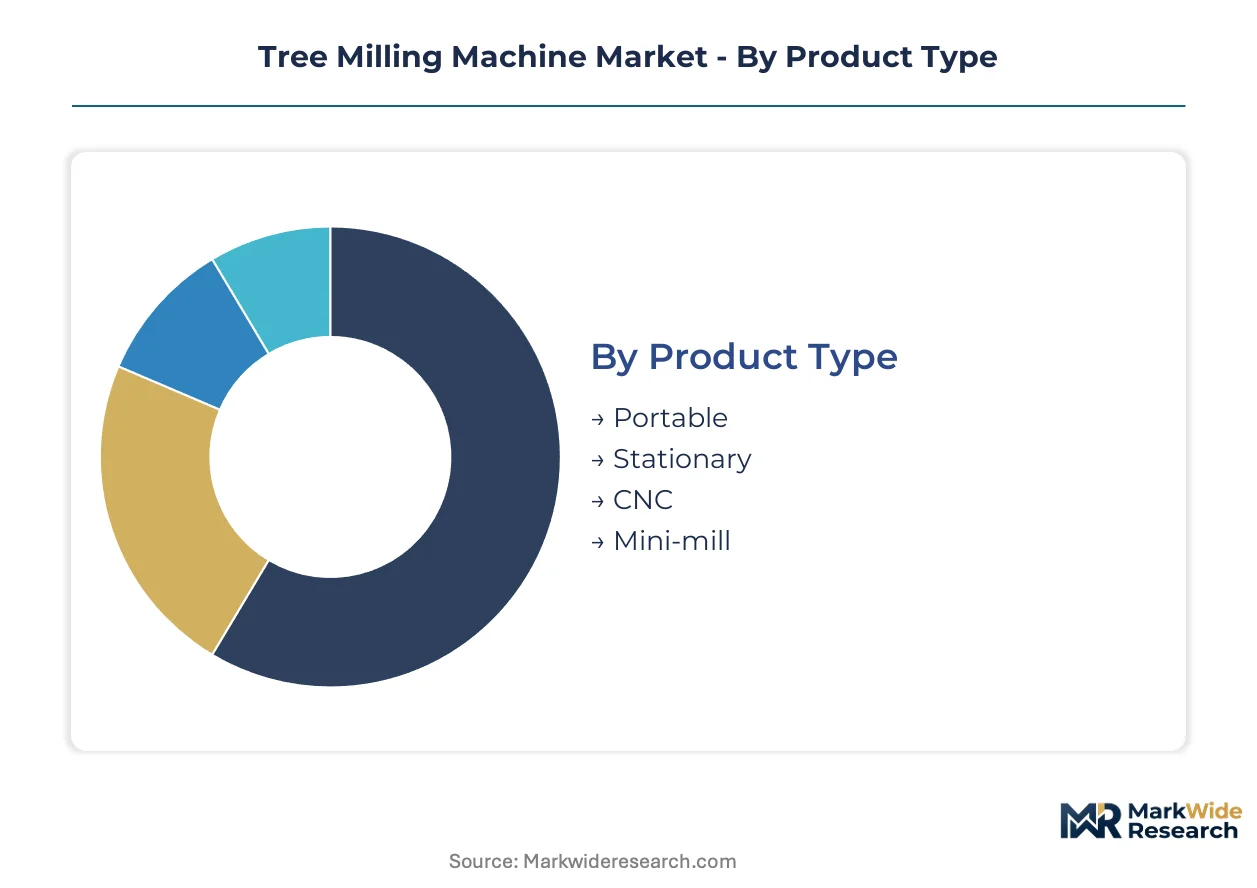
Segmentation in tree milling machines separates export-driven precision equipment from domestically oriented manual systems. Understanding these splits clarifies where compliance investments concentrate and where margin pools shift across automation tiers.
Product Type:
German and Japanese suppliers dominate CNC and stationary system exports, while portable configurations serve fragmented domestic forestry operations across multiple continents.
- CNC:Computer-numerical control systems integrate multi-axis spindle positioning with real-time density compensation algorithms. Demand concentrates among German flooring manufacturers seeking batch consistency across variable hardwood inputs, driven by EU Machinery Directive CE marking requirements for automated woodworking equipment.
- Portable:Compact, transportable units with 1,000-4,000 RPM spindle ranges operate on generator power for remote timber processing. Remote forestry operations in infrastructure-limited regions pull these configurations, with on-site milling gaining traction where centralized facility construction proves uneconomical.
- Stationary:Fixed-base industrial systems with 5,000-10,000 RPM capabilities serve high-volume lumber production facilities.
- Mini-mill:Benchtop units with reduced work envelopes target hobbyist workshops and small-scale artisan operations.
CNC commands the established base. The steepest expansion runs through portable configurations.
Application:
Cost tier stratification separates premium contract furniture specifications from economy-grade construction material processing.
- Furniture Making:Precision joinery and profile cutting for assembled wood products demands tight dimensional tolerances. European contract furniture producers in Austria and Switzerland pull advanced spindle control systems, with batch consistency requirements compressing margins for manual equipment suppliers.
- Construction:Dimensioning structural lumber and engineered wood products for building assemblies. North American housing starts and commercial building activity drive replacement cycles, with sustainability-linked procurement criteria penetrating supply chains.
- Lumber Production:Primary breakdown of raw logs into dimensional stock for downstream processing.
- Woodworking:General-purpose material preparation spanning multiple downstream uses.
Furniture making anchors premium pricing tiers. Construction shows the most rapid volume scaling.
End User:
Customer type determines automation depth, with manufacturers absorbing full CNC integration costs that contractors and artisans resist.
- Manufacturers:Industrial-scale production facilities with dedicated maintenance staff and capital budgets for integrated systems. German precision engineering clusters support deployment, though CNC programming proficiency constraints limit operational scaling despite capital availability.
- Contractors:Project-based operators serving construction and forestry sectors with mobile equipment needs. Aftermarket parts availability and configurable platform architectures capture loyalty in North American markets.
- Artisans:Small-scale producers emphasizing craft differentiation over throughput.
- Hobbyists:Non-commercial users sustaining demand for manual and semi-automatic systems.
Manufacturers absorb the highest equipment specification levels. Contractors represent the most dynamic demand segment.
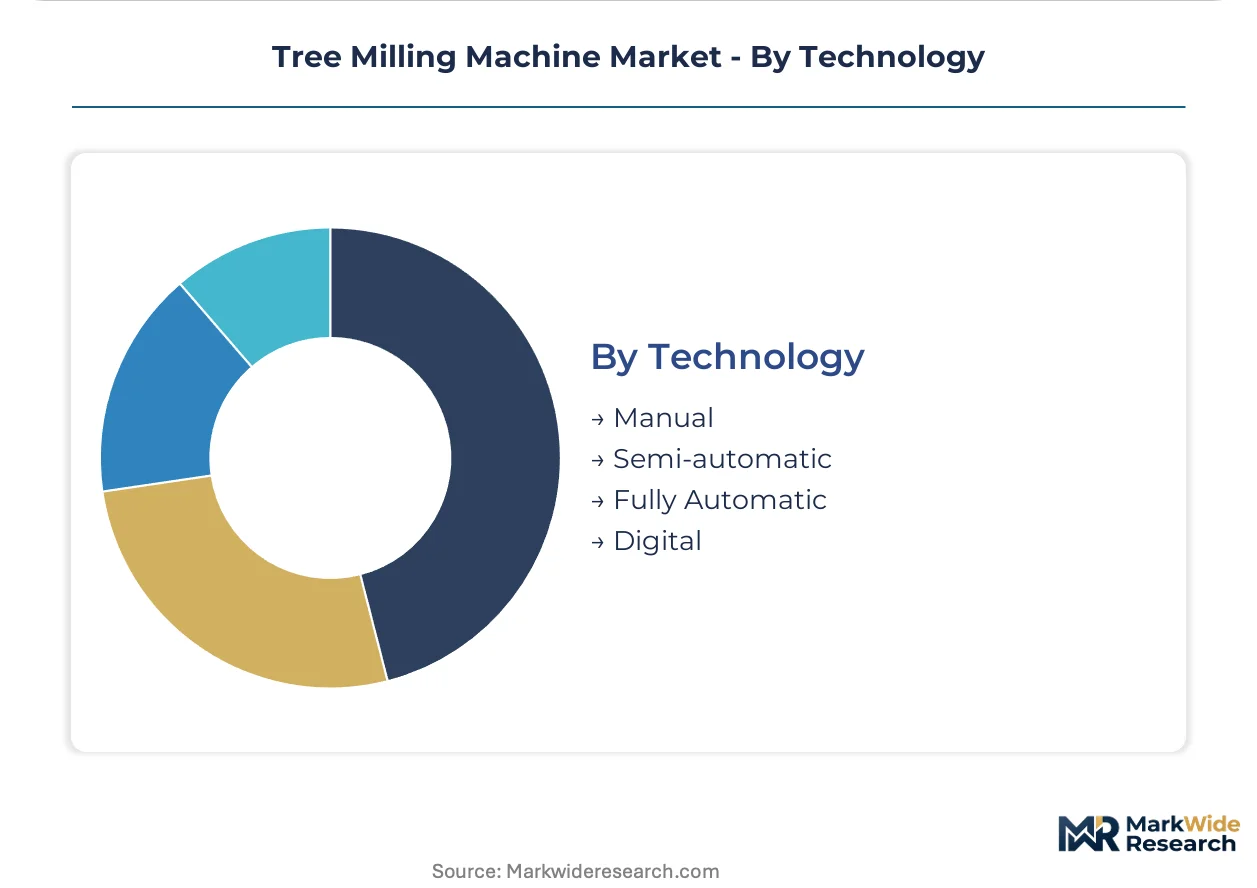
Technology:
Maturity gradients separate legacy mechanical systems from digitally integrated platforms requiring software-hardware coordination.
- Fully Automatic:Closed-loop control systems with minimal operator intervention beyond loading and monitoring. High-volume flooring manufacturers deploy adaptive spindle control with real-time density compensation, with REACH chemical restrictions and F-Gas Regulation thresholds reshaping coolant specifications.
- Digital:Network-connected architectures enabling predictive monitoring and remote diagnostics. Large furniture manufacturers in Austria and Switzerland now source monitoring separately from hardware acquisition, pressuring integrated OEM service margins.
- Semi-automatic:Operator-assisted cycles with automated feed and manual positioning.
- Manual:Hand-controlled operation with mechanical power assistance only.
Fully automatic systems hold the installed base concentration. Digital platforms are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German flooring manufacturers deploy adaptive spindle control systems for batch consistency, while remote forestry operations in infrastructure-limited regions pull portable configurations. This consumption-mix differential separates precision-engineered stationary systems from mobile on-site processing equipment.
United States
North American housing starts and commercial building activity drive replacement cycles for construction-grade milling equipment. OSHA machine guarding standards mandate interlocked enclosures and emergency stop systems, elevating compliance costs for equipment suppliers. The Pacific Northwest timber belt sustains demand for high-volume lumber production systems with integrated dust collection infrastructure.
Germany
Precision engineering clusters in Bavaria and Baden-Württemberg support advanced CNC system deployment for contract furniture production. EU Machinery Directive CE marking requirements enforce noise emission limits and vibration exposure thresholds that reshape product design priorities. Stuttgart-area flooring manufacturers deploy adaptive spindle control with real-time density compensation across variable hardwood inputs.
Japan
Carbide insert and high-speed steel tooling production concentrates among specialized suppliers, exposing purchasers to input cost volatility. METI industrial standards govern machinery safety and performance certification for domestic and export markets. Nagoya-area machine tool builders coordinate with timber processing equipment assemblers on spindle system integration.
China
Domestic furniture manufacturing scale creates volume demand for mid-specification milling systems with conversational programming interfaces. GB standards and MIIT machinery regulations establish baseline safety and electromagnetic compatibility requirements. Yangtze River Delta woodworking equipment clusters supply both domestic mills and Southeast Asian export markets.
Canada
Remote forestry operations in British Columbia and Quebec drive portable unit adoption where centralized facility construction proves uneconomical. Health Canada and provincial occupational safety regulators enforce machinery guarding standards aligned with North American best practices. Ontario-based equipment distributors maintain configurable platform architectures for rapid component replacement across mid-scale operations.
Tree Milling Machine Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the upper layer controlling CNC platform architectures and the lower layer competing on aftermarket parts availability. The market structure separates suppliers capable of software-hardware integration from component assemblers. Three archetypes dominate: heritage CNC system builders with multi-axis heritage, portable equipment specialists serving remote forestry, and conversational programming interface developers reducing operator training burdens. Competitive moves concentrate on geographic expansion through distributor networks and portfolio diversification into predictive monitoring services.
Within the heritage CNC tier, DMG MORI Co., Ltd. and Yamazaki Mazak Corporation exemplify integrated platform suppliers with established European precision engineering relationships. Haas Automation, Inc. occupies a position among North American fabricators emphasizing configurability and aftermarket parts availability for mid-scale furniture manufacturers. Hurco Companies, Inc. represents the conversational programming specialist archetype, with Hurco Companies, Inc. anchoring the operator-training-reduction vector for smaller milling operations with limited technical staffing.
| Leading Market Players |
|---|
| DMG MORI Co., Ltd. |
| Yamazaki Mazak Corporation |
| Haas Automation, Inc. |
| Okuma Corporation |
| Doosan Machine Tools Co., Ltd. |
| Hurco Companies, Inc. |
| KNUTH Werkzeugmaschinen GmbH |
| Makino Milling Machine Co Ltd. |
| FANUC Corporation |
| Others |
Value Network & Pricing Analysis
EU Machinery Directive CE marking requirements gate both supplier qualification and price differentiation simultaneously, as automated woodworking equipment manufacturers must absorb compliance costs to access European contract furniture producers while manual equipment providers face margin compression from certification-driven specification escalation.
Pricing Analysis
Long-term equipment procurement contracts dominate among German flooring manufacturers seeking adaptive spindle control systems with predictive maintenance bundling, while spot-market transactions persist for portable configurations serving remote forestry contractors. Three-tier pricing structure across premium CNC platforms, standard stationary systems, and economy manual units separates buyers by automation depth and after-sales service inclusion. Cost compression in mid-specification segments is intensifying because conversational programming interfaces are democratizing CNC access previously reserved for premium tiers. Artisan and hobbyist segments exhibit highest price sensitivity, whereas industrial manufacturers prioritize lifecycle cost over acquisition price.
Supply Chain Analysis
Carbide insert tooling production concentrates in Germany and Japan, exposing tree milling machine assemblers to input cost volatility when sourcing precision cutters for high-speed timber applications. Spindle system manufacturing draws from Nagoya-area machine tool builders, while control electronics feed from Yangtze River Delta industrial clusters. Single-source vulnerability in specialized bearing seal materials creates procurement risk as REACH chemical restrictions and F-Gas Regulation thresholds reshape coolant compatibility specifications. Distribution runs through Ontario-based equipment distributors maintaining configurable platform architectures for rapid component replacement across North American mid-scale operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is entering a cyclical recovery phase as North American housing starts and commercial building activity drive replacement cycles for construction-grade milling equipment.
For Market Incumbents: Compound service revenue through predictive monitoring unbundling, capturing specification-setting roles in multi-year operating agreements with Austrian and Swiss furniture manufacturers. Deepen backward integration into fluid engineering capabilities to maintain European market access as REACH and F-Gas Regulation thresholds evolve. Defend against independent diagnostic specialists inserting themselves into equipment operating agreements by embedding proprietary vibration analysis algorithms into CNC platform architectures.
For New Entrants and Emerging Players: Differentiate on conversational programming interfaces that reduce operator training burdens for smaller milling operations with limited technical staffing, targeting the gap between Hurco Companies' established position and underserved mid-scale furniture manufacturers. White-space exists in portable configurations for remote British Columbia and Quebec forestry operations where centralized facility construction proves uneconomical. Pursue distributor partnerships with Ontario-based equipment networks rather than direct sales to overcome incumbent channel control.
For Investors and Strategic Acquirers: EU Machinery Directive CE marking requirements reshape the acquisition landscape toward CNC platform suppliers with in-house software-hardware integration capabilities rather than component assemblers. Long-term viability over the coming decade favors integrated platform suppliers capable of sustainability-linked procurement compliance as carbon accounting rules penetrate construction supply chains. Target acquisition candidates with documented lifecycle emissions profiles and established relationships with German precision engineering clusters. Monitor OSHA machine guarding standard enforcement intensity as signal for US market compliance cost trajectory and manual equipment supplier distress.
| Strategic Initiative | Industry Significance |
|---|---|
| Conversational Programming Interface Development | Reduces operator training burdens for smaller milling operations with limited technical staffing. |
| Predictive Monitoring Service Unbundling | Captures specification-setting roles in multi-year operating agreements with Austrian furniture manufacturers. |
| Backward Integration into Fluid Engineering | Maintains European market access as REACH and F-Gas Regulation thresholds reshape coolant specifications. |
| Portable Configuration Platform Expansion | Addresses remote forestry operations in British Columbia where centralized facility construction proves uneconomical. |
| Sustainability-Linked Procurement Certification | Creates preference differentiation as carbon accounting rules penetrate construction supply chains. |
Research Methodology
Desk research of customs and trade data, SEC 10-K filings, and EU Machinery Directive compliance databases preceded structured interviews with maintenance directors at flooring manufacturers, plant engineers at lumber production facilities, OEM procurement teams at furniture makers, and aftermarket service heads at equipment distributors. Primary fieldwork combined with secondary validation from METI industrial standards documentation and Health Canada machinery safety guidelines. Bottom-up equipment shipment analysis triangulated against top-down construction spending and housing start indicators.
Variance decomposition across product type, application, end user, and technology segments structured the analytical framework over the projection horizon. CNC, portable, stationary, and mini-mill categories were modeled separately with automation depth and control architecture complexity as cross-cutting dimensions. CAGRs derived from equipment replacement cycle analysis, regulatory compliance retrofit timelines, and remote forestry infrastructure investment patterns. Forecast inputs included carbide insert tooling lead times, EU Machinery Directive enforcement intensity, and North American housing start volatility.
The analysis sits within stated boundaries; outcomes outside sustained North American residential construction activity or accelerated EU carbon accounting rulemaking would require recalibration. Forecasts reflect assumptions regarding skilled machinist shortage persistence and REACH chemical restriction evolution. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Linear Slides Market
Material Handling Equipment
Vertical Lift Module (VLM) Market
Material Handling Equipment
Forklift Rental Market
Material Handling Equipment
Resistance Welding Products Market
Material Handling Equipment
Global Warehouse Racking Market
Material Handling Equipment
Europe Port Equipment Market
Material Handling Equipment
Conveying Equipment Market
Material Handling Equipment
Hoist Chains Market
Material Handling Equipment
Chain-Driven Roller Conveyors Market
Material Handling Equipment
Firewood Processors Market
Material Handling Equipment
Roll Slitting Machines Market
Material Handling Equipment
Conveyor Sprocket Market
Material Handling Equipment
Global Industrial Weighing Equipment Market
Material Handling Equipment
GCC Conveyor Belt Market
Material Handling Equipment
Container Handler Market
Material Handling Equipment
Drum Handling Equipment Market