
 Global Smart Mining Solution Market | 2026-2036
Global Smart Mining Solution Market Size, Share, and Industry Trends Forecast 2026-2036
Global Smart Mining Solution Market Outlook
Equipment-as-a-service and operational leasing is narrowing the capital barrier for mid-tier mining operators seeking autonomous fleet technology. Caterpillar Inc. leverages its Cat Command platform to sustain technology leadership in remote-controlled and autonomous haul trucks. Komatsu Ltd. anchors its competitive position through the FrontRunner autonomous haulage system, which dominates deployment scale across Pilbara operations. Sandvik AB differentiates through specialized underground automation, controlling niche segments where tunneling precision commands premium positioning.
Smart mining solutions integrate industrial IoT sensors, edge computing nodes, and machine learning algorithms to enable real-time ore tracking, predictive equipment maintenance, and autonomous vehicle coordination in subterranean and open-pit environments. These systems typically operate on sub-50 millisecond latency thresholds to ensure collision avoidance and payload optimization across distributed pit-to-port workflows. IoT Solutions and Autonomous Vehicles represent the deepest margin pools, as hardware-software bundling creates sticky multi-year contracts with mining operators. Cloud-Based deployment is accelerating fastest among tier-two miners seeking to avoid capital-intensive on-premise infrastructure while accessing AI Analytics for mineral processing optimization.
FERC guidelines on critical mineral supply chain resilience, Australia's Department of Industry tailings safety mandates, and ISO 14001 environmental management standards collectively shape product certification requirements and procurement criteria for smart mining vendors. The EU Green Deal's embedded carbon tracking rules are extending compliance obligations to imported concentrate, forcing exporters to adopt Environmental Monitoring modules within their smart mining stacks. Stakeholders must weigh interoperability standards against vendor lock-in risks as autonomous fleet data becomes a contested asset between operators, equipment suppliers, and regulatory filers.
Market Dynamics
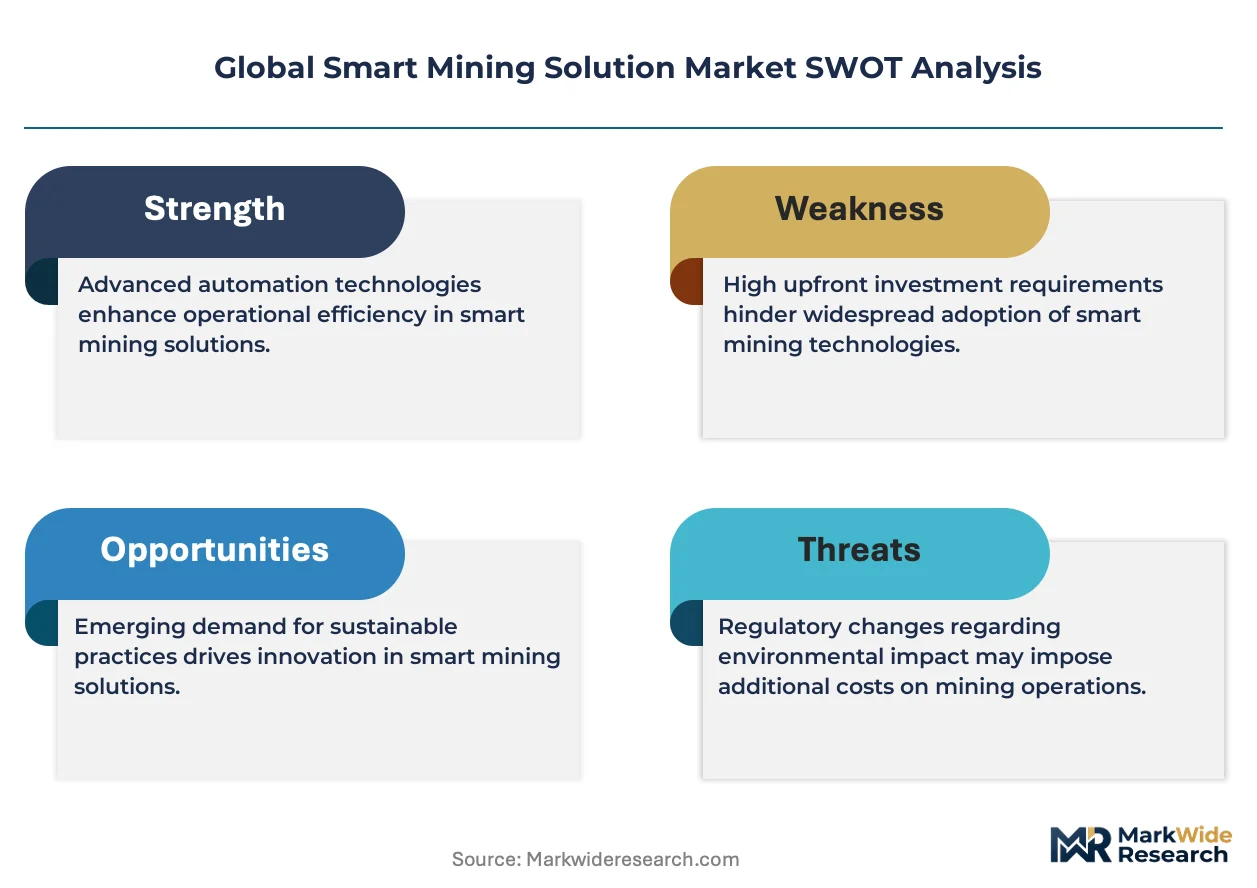
The collision between autonomous fleet deployment and Australia's tailings dam safety mandates is compressing procurement cycles for integrated smart mining stacks. Equipment vendors must now bundle environmental monitoring sensors with haulage automation to satisfy dual compliance and productivity requirements.
Growth Catalysts
- Autonomous Haulage Mandates:Western Australia's Pilbara iron ore operators face competitive pressure to match Rio Tinto's fully autonomous truck fleets, accelerating vendor qualification timelines for automation providers.
- FERC Critical Mineral Guidelines:Supply chain resilience directives from the US regulator are forcing domestic copper and lithium producers to adopt predictive maintenance systems to guarantee output continuity.
- EU Green Deal Carbon Tracking:Embedded emissions rules for imported concentrate are compelling Australian and Chilean exporters to deploy Environmental Monitoring modules within their smart mining stacks.
Market Restraints
- GPU and Edge Computing Shortage:Semiconductor supply constraints from Taiwan and South Korea are extending lead times for machine learning inference hardware required for collision avoidance systems.
- Legacy Fleet Stranding Risk:Mid-tier operators in South Africa and Indonesia face write-down pressures on diesel haul trucks rendered obsolete by battery-electric autonomous alternatives.
- Interoperability Friction:Proprietary data protocols from Caterpillar, Komatsu, and Sandvik create vendor lock-in that prevents mining operators from mixing equipment brands within unified fleet management systems.
Strategic Opportunities
- Underground Coal Automation in Poland:EU Just Transition Fund subsidies are creating first-mover openings for tunneling automation vendors as the country modernizes its Silesian basin operations.
- Equipment-as-a-Service Expansion:Operational leasing models are penetrating mid-tier copper producers in Peru and Chile, lowering capital barriers to autonomous drill and haul technology.
- 5G Private Network Convergence:Telecommunications infrastructure in Canada's Athabasca oil sands and Brazil's Carajás iron ore district is enabling sub-20 millisecond latency for coordinated autonomous fleets.
Industry Challenges
- Autonomous Systems Integration:Mining engineers with combined expertise in geological modeling, machine learning, and heavy equipment maintenance command salary premiums that strain mid-tier operator budgets.
- ISO 14001 Certification Timelines:Environmental management standard compliance for smart mining stacks requires 12-18 month documentation cycles that delay revenue recognition for vendors.
- Interoperability Standards Gap:Absence of unified API frameworks between equipment OEMs forces operators to maintain parallel data lakes, inflating IT infrastructure costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Smart Mining Solution Market |
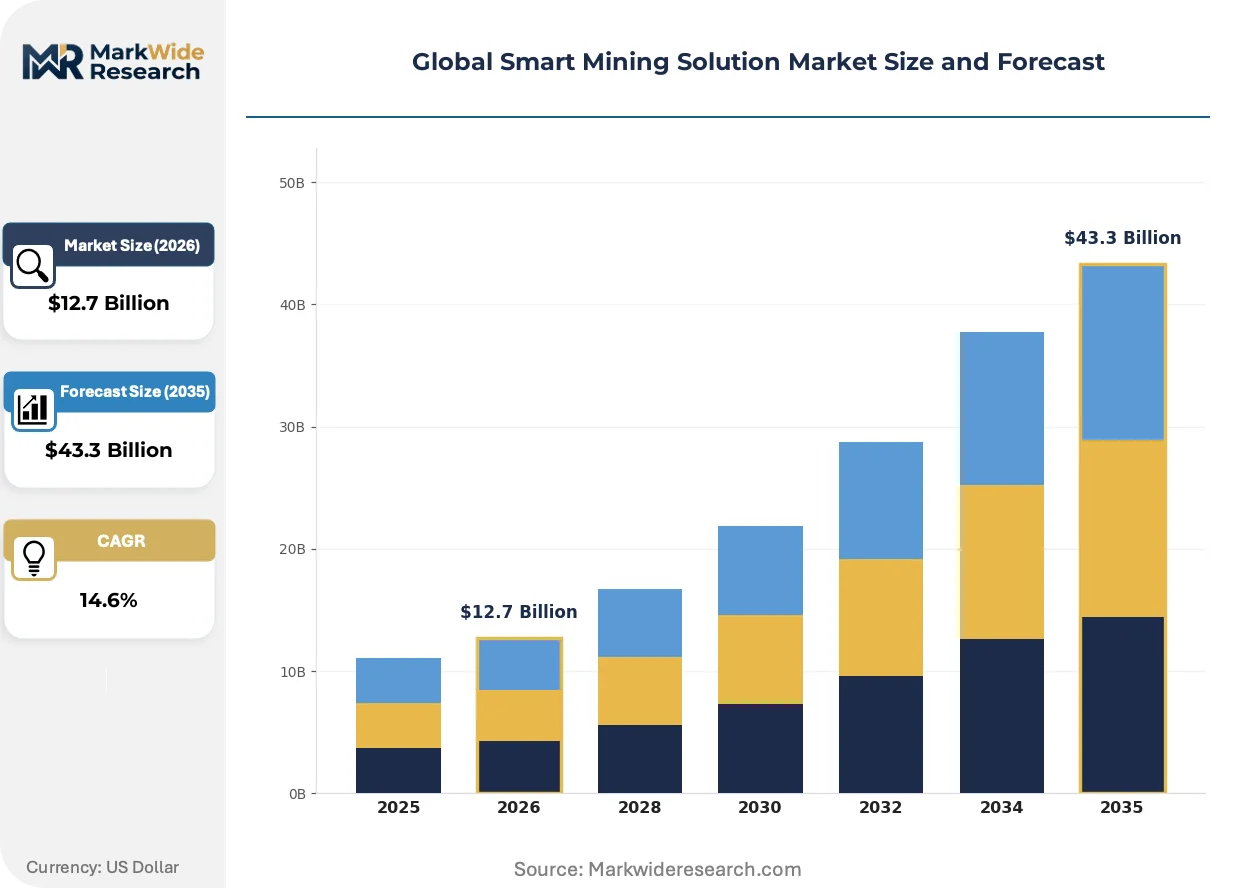
| Market Size in 2026 | $12.7 Billion |
| Market Size in 2035 | $43.3 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: IoT Solutions, AI Analytics, Autonomous Vehicles, Data Management Platforms Application: Resource Management, Supply Chain Optimization, Environmental Monitoring, Safety Management End User: Mining Operators, Equipment Manufacturers, Service Providers, Regulatory Bodies Deployment: On-Premise, Cloud-Based, Hybrid, Edge Computing |
| Companies Covered | ABB Ltd, Caterpillar Inc., Cisco Systems Inc., Rockwell Automation Inc., Komatsu Ltd., SAP SE, Hitachi Construction Machinery Co. Ltd., Siemens, Sandvik AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Smart Mining Solution Market Strategic Shifts
Smart mining technology is converging around three vectors: edge-to-cloud architecture, regulatory-driven environmental sensing, and compressed procurement cycles favoring bundled hardware-software contracts.
Digital twin technology is hybridizing physical asset replication with real-time ore body modeling. Tier-one operators in Western Australia and northern Sweden are deploying these systems to simulate pit geometry changes before committing haul routes. The technology is compressing planning cycles from quarterly to weekly intervals while reducing diesel consumption through optimized grade control.
Australia's Department of Industry, Science and Resources tailings safety mandates are mandating continuous sensor deployment on dam wall integrity. The regulation is forcing copper and gold producers to integrate geotechnical monitoring with existing fleet management platforms. Underground operators in Queensland and New South Wales are responding by specifying vendor contracts that bundle tailings sensing with autonomous drilling systems.
Mid-tier miners are consolidating vendor relationships around full-stack automation providers rather than point solutions. Equipment procurement teams in Chile's Atacama copper belt and Peru's Cerro Verde district now require five-year total cost of ownership guarantees that bundle maintenance, software updates, and spare parts logistics. This behavioral shift is displacing fragmented purchasing across separate drilling, hauling, and processing automation vendors.
Global Smart Mining Solution Market Segmentation
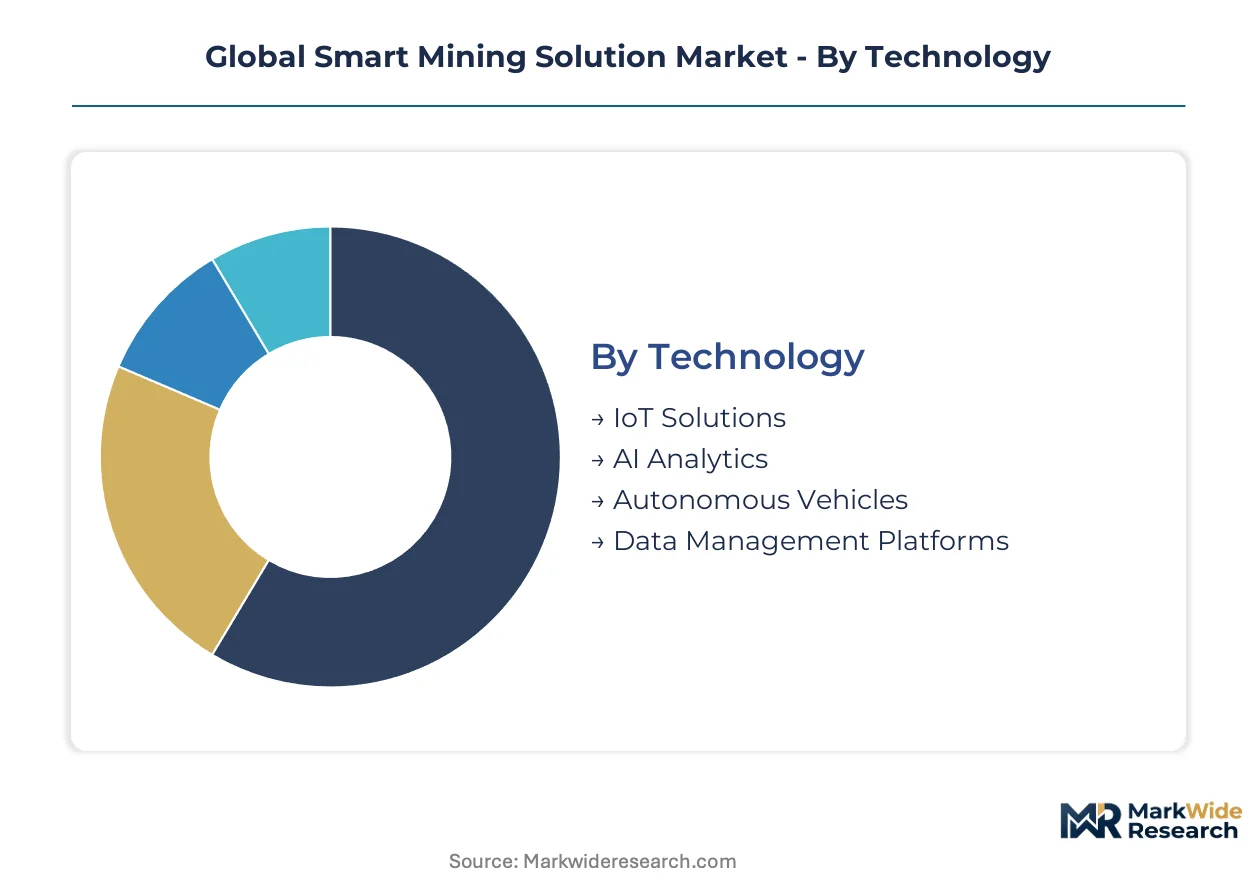
Smart mining solutions fragment across four intersecting dimensions that determine procurement complexity and vendor stickiness. Technology selection dictates integration architecture, while deployment mode shapes capital intensity and data sovereignty constraints. Application focus and end-user type further stratify pricing power and contract duration across the value chain.
Technology:
After-sales-service intensity peaks with Autonomous Vehicles and IoT Solutions, where hardware-software bundling extends contract lifecycles through embedded maintenance protocols and continuous algorithm updates.
- Autonomous Vehicles:Self-driving haul trucks, drill rigs, and underground loaders operate on sub-50 millisecond latency thresholds for collision avoidance. Western Australia's Pilbara iron ore district concentrates demand as Rio Tinto and BHP operationalize fully autonomous fleets, with competitive pressure forcing qualification timelines for automation providers.
- IoT Solutions:Industrial sensor networks for equipment health, ore tracking, and environmental monitoring generate continuous data streams. Australia's Department of Industry tailings dam mandates are accelerating sensor deployment on dam wall integrity, bundling geotechnical monitoring with fleet management platforms.
- AI Analytics:Machine learning algorithms optimize mineral processing and predictive maintenance. Mid-tier copper producers in Chile and Peru access these tools through cloud-based subscriptions to avoid capital-intensive infrastructure.
- Data Management Platforms:Centralized repositories integrate pit-to-port workflows across heterogeneous equipment fleets. Proprietary protocols from major OEMs create interoperability friction that inflates IT infrastructure costs for operators mixing brands.
By volume, IoT Solutions leads through sensor proliferation across tailings, haulage, and processing workflows. By growth pace, Autonomous Vehicles is ahead as competitive pressure in Western Australia and Brazil's Carajás district accelerates fleet conversion.
Application:
Cost tier stratification separates premium bundled stacks from point solutions, with integrated offerings commanding multi-year contracts and higher lifetime value.
- Environmental Monitoring:Continuous emissions tracking, water quality sensing, and rehabilitation compliance modules. The EU Green Deal's embedded carbon rules for imported concentrate are compelling Australian and Chilean exporters to deploy these systems within their smart mining stacks.
- Safety Management:Collision avoidance, personnel tracking, and emergency response coordination in subterranean and open-pit environments. Underground coal operators in Australia's Queensland and New South Wales specify vendor contracts bundling tailings sensing with autonomous drilling systems.
- Resource Management:Real-time ore body modeling and grade control optimization. Tier-one operators in northern Sweden deploy digital twin technology to compress planning cycles from quarterly to weekly intervals.
- Supply Chain Optimization:Pit-to-port logistics coordination and inventory management. FERC critical mineral guidelines are forcing domestic copper and lithium producers to adopt predictive systems guaranteeing output continuity.
Environmental Monitoring captures the steepest expansion trajectory as regulatory compliance obligations extend across exported concentrate value chains.
End User:
Customer type determines procurement authority and technical specification depth, with mining operators driving requirements and equipment manufacturers influencing interoperability standards.
- Mining Operators:Tier-one Pilbara iron ore producers and mid-tier Atacama copper belt miners specify five-year total cost of ownership guarantees bundling maintenance, software updates, and spare parts logistics.
- Equipment Manufacturers:Caterpillar, Komatsu, and Sandvik embed proprietary automation platforms that create vendor lock-in and prevent unified fleet management across mixed-brand operations.
- Service Providers:Equipment-as-a-service and operational leasing specialists narrow capital barriers for mid-tier operators in Peru, Chile, and Indonesia seeking autonomous technology without balance-sheet commitment.
- Regulatory Bodies:Australia's Department of Industry, Science and Resources and the EU Green Deal enforcement mechanisms shape certification requirements and procurement criteria through tailings safety and carbon tracking mandates.
Mining Operators dominate contract value, while Service Providers are gaining share fastest through penetration of operational leasing models.
Deployment:
Supply concentration in semiconductor manufacturing constrains Edge Computing and On-Premise hardware availability, extending lead times for machine learning inference components.
- Cloud-Based:Subscription access to AI Analytics and data storage without capital-intensive infrastructure. Tier-two miners in South Africa and Indonesia favor this mode to bypass on-premise server investments.
- Edge Computing:Localized processing nodes achieving sub-20 millisecond latency for autonomous vehicle coordination. 5G private network convergence in Canada's Athabasca oil sands and Brazil's Carajás district enables this architecture.
- Hybrid:Split workloads between cloud analytics and edge inference, balancing data sovereignty with computational scale. Operators with mixed underground and open-pit operations prefer this flexibility.
- On-Premise:Dedicated server infrastructure for data-sensitive operations or connectivity-constrained sites. GPU and edge computing shortages from Taiwan and South Korea are extending procurement lead times for this mode.
Cloud-Based deployment leads by volume among capital-constrained mid-tier miners, while Edge Computing is climbing the fastest as 5G infrastructure enables coordinated autonomous fleets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Western Australian iron ore operators anchor procurement authority for autonomous haulage systems, while Chilean copper exporters and Canadian oil sands producers concentrate demand for environmental monitoring modules.
Australia
Rio Tinto and BHP have operationalized fully autonomous truck fleets across Western Australia's Pilbara district, compressing vendor qualification timelines for automation providers. The Department of Industry, Science and Resources mandates continuous tailings dam monitoring, accelerating sensor deployment on dam wall integrity. Underground coal operators in Queensland and New South Wales specify bundled contracts combining autonomous drilling with geotechnical sensing systems.
Chile
Copper producers in the Atacama belt deploy Environmental Monitoring modules to satisfy EU Green Deal embedded carbon tracking rules for exported concentrate. The National Mining Society coordinates technology adoption standards across state-owned and private operators. Mid-tier miners in the Cerro Verde district favor Equipment-as-a-Service models to bypass capital-intensive fleet purchases.
Canada
Oil sands operators in Alberta's Athabasca region leverage 5G private networks to achieve sub-20 millisecond latency for coordinated autonomous fleets. Federal critical mineral supply chain directives from Ottawa pressure domestic lithium and copper developers to adopt predictive maintenance systems. Saskatchewan's potash corridor is emerging as a secondary demand center for IoT-enabled resource management platforms.
Brazil
Vale's Carajás iron ore complex drives autonomous haulage adoption through competitive pressure to match Australian productivity benchmarks. ANVISA environmental compliance requirements intersect with ISO 14001 certification timelines, extending procurement cycles for integrated smart mining stacks. The Minas Gerais iron ore triangle concentrates mid-tier operator demand for cloud-based AI Analytics subscriptions.
Poland
EU Just Transition Fund subsidies are modernizing the Silesian coal basin, creating first-mover openings for tunneling automation vendors. The country's national mining regulator mandates personnel tracking and collision avoidance systems for all underground operations. Katowice-based operators are consolidating vendor relationships around full-stack providers offering five-year total cost of ownership guarantees.
Global Smart Mining Solution Market Competitive Environment
Channel-controlling players compete with product-specialist players across a tiered structure where bundled hardware-software offerings command premium positioning. The market consolidates around three strategic archetypes: full-stack automation integrators, component-specialist vendors, and operational leasing intermediaries. Dominant competitive moves include strategic partnerships between equipment OEMs and telecommunications infrastructure providers, plus portfolio diversification into environmental monitoring modules to satisfy regulatory bundling requirements.
Among diversified industrial technology groups, ABB Ltd and Siemens occupy positions exemplifying the full-stack integrator archetype, while Caterpillar Inc. and Komatsu Ltd. anchor the heavy equipment-origin automation tier. Sandvik AB represents the specialized underground automation segment where tunneling precision commands differentiated positioning. These players illustrate how geographic origin and corporate structure shape competitive approach: Swiss and German conglomerates leverage broad industrial portfolios, Japanese and American equipment specialists embed proprietary platforms, and Swedish engineering groups target niche technical requirements.
| Leading Market Players |
|---|
| ABB Ltd |
| Caterpillar Inc. |
| Cisco Systems Inc. |
| Rockwell Automation Inc. |
| Komatsu Ltd. |
| SAP SE |
| Hitachi Construction Machinery Co. Ltd. |
| Siemens |
| Sandvik AB |
| Others |
Value Chain & Pricing Dynamics
Taiwanese semiconductor foundries and South Korean memory fabricators concentrate supply for GPU and edge computing components that smart mining vendors bundle into autonomous haulage and collision avoidance systems, compressing margin capture downstream into software maintenance contracts and sensor-as-a-service subscriptions.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers, with ISO 14001 environmental management and EU Green Deal carbon tracking compliance commanding substantial premiums over baseline offerings. Three-tier pricing structure across premium, standard, and economy levels reflects after-sales service intensity, algorithm update frequency, and spare parts logistics bundling. Pricing pressure stems from mid-tier miners in South Africa and Indonesia demanding operational leasing models that shift capital expenditure to operating expenditure. Tier-one Pilbara operators exhibit lowest price sensitivity due to productivity gains from fully autonomous fleets, while capital-constrained underground coal operators in Queensland negotiate hardest on upfront hardware costs.
Supply Chain Analysis
Electronics manufacturing services in Taiwan, South Korea, and Japan hold dominant capacity for industrial IoT sensors and edge computing nodes deployed across smart mining stacks. Raw material dependencies span high-purity silicon for semiconductors, rare earth elements for magnet assemblies in autonomous vehicle motors, and lithium-ion cells for battery-electric haul truck powertrains. Single-source vulnerability concentrates in Taiwanese foundry capacity for machine learning inference chips, creating procurement risk for collision avoidance systems. Distribution runs through equipment OEM direct sales forces for tier-one operators, with service provider intermediaries penetrating mid-tier miners in Peru and Chile through equipment-as-a-service arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Autonomous haulage deployment intersecting with Australia's tailings dam safety mandates constitutes a structural inflection, compressing procurement cycles and bundling environmental sensing with productivity automation into unified vendor contracts.
For Market Incumbents: Insulate proprietary data protocols by accelerating API standardization efforts that prevent customer defection to competitors offering interoperable fleet management. Defend margin position through backward integration into edge computing hardware production, reducing exposure to Taiwanese semiconductor lead time volatility. Prioritize certification investment in ISO 14001 environmental management to capture regulatory-driven bundling requirements from Australian and EU enforcement mechanisms. For New Entrants and Emerging Players: Build out underground coal automation capabilities in Poland's Silesian basin, where EU Just Transition Fund subsidies create first-mover openings absent entrenched vendor relationships. Target Peru and Chile's mid-tier copper producers through equipment-as-a-service models that bypass capital barriers and displace fragmented point-solution vendors. Establish go-to-market partnerships with telecommunications infrastructure providers enabling 5G private network convergence for sub-20 millisecond latency autonomous coordination. For Investors and Strategic Acquirers: Capital is best deployed toward full-stack automation integrators possessing bundled hardware-software capabilities and five-year total cost of ownership contract structures that generate sticky recurring revenue streams. Long-term viability across the analysis window favors vendors with demonstrated interoperability progress and environmental monitoring module integration. Monitor ANVISA enforcement timelines in Brazil and EU Green Deal carbon tracking implementation as inflection indicators for accelerated procurement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Environmental Monitoring Module Integration | ANVISA and EU Green Deal rules force bundling of geotechnical sensing with autonomous haulage platforms. |
| 5G Private Network Infrastructure Partnership | Telecommunications alliances in Canada's Athabasca and Brazil's Carajás enable coordinated fleet latency thresholds. |
| Equipment-as-a-Service Model Expansion | Operational leasing penetrates mid-tier Chilean and Peruvian copper producers seeking balance-sheet flexibility. |
| Backward Integration into Edge Computing | In-house GPU and inference hardware production reduces Taiwanese foundry dependency for collision avoidance systems. |
| API Standardization Consortium Participation | Interoperability frameworks prevent vendor lock-in defection and enable mixed-brand fleet management contracts. |
Study Parameters
Desk research of SEC filings from Caterpillar and Komatsu, Australian Department of Industry regulatory bulletins, and EU Green Deal implementation guidance preceded structured interviews with mining operations directors, automation procurement leads, and tailings dam safety officers. Primary fieldwork encompassed equipment OEM product managers, telecommunications infrastructure providers, and equipment-as-a-service specialists across Western Australia, Chile, and Canada. Secondary validation drew from FERC critical mineral supply chain directives, ISO 14001 certification databases, and 5G private network deployment records. Bottom-up segment sizing triangulated against top-down market aggregation from disclosed contract values and fleet deployment announcements.
Assumptions held fixed include sustained semiconductor supply constraints from Taiwan and South Korea, continued Australian tailings monitoring mandate enforcement, and EU Green Deal carbon tracking phase-in timelines. Variables stress-tested encompass autonomous vehicle adoption velocity, mid-tier miner capital access conditions, and interoperability standardization progress. Segmentation modeling spanned technology type, deployment architecture, application focus, and end-user procurement authority. CAGRs derived from logistic diffusion curves fitted to historical automation adoption patterns in comparable heavy industries, cross-referenced with disclosed fleet conversion timelines from Rio Tinto and BHP operational data.
Stress conditions across GPU availability, Australian regulatory enforcement intensity, and copper price volatility were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding 5G infrastructure buildout pace and EU carbon border adjustment mechanism implementation scope. Quarterly review of Taiwanese semiconductor foundry utilization rates, Australian Department of Industry inspection citation frequencies, and Chilean National Mining Society technology adoption bulletins is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mining Equipment
Drilling Jumbo Market
Mining Equipment
Asia-Pacific Drill Pipe Market
Mining Equipment
Mining Drill Market
Mining Equipment
Global Underground Mining Vehicles Market
Mining Equipment
Asia Pacific Mining Equipment Market
Mining Equipment
Mining Locomotive Market
Mining Equipment
Commonwealth of Independent States (CIS) Underground Mining Equipment Market
Mining Equipment
DTH Drill Rig Market
Mining Equipment
Surface Mining Equipment Market
Mining Equipment
Digger Machinery Market
Mining Equipment
Surface Mining Market
Mining Equipment
Mine Ventilation System Market
Mining Equipment
Barite Crusher Market
Mining Equipment
Borehole Equipment Market
Mining Equipment
Mining Drilling Services Market
Mining Equipment
Mining Collectors Market