
 Material Handling Monorails Market | 2026-2036
Material Handling Monorails Market Size, Share, and Industry Trends Forecast 2026-2036
Material Handling Monorails Market Foresight
Multi-source procurement of monorail subsystems is broadening as end-users diversify supplier portfolios beyond single-vendor dependencies. Daifuku Co., Ltd. leverages its integrated material handling platform to anchor large-scale automotive plant installations across Asia. Konecranes Inc. sustains competitive positioning through specialized overhead crane-to-monorail interoperability engineering. Schaefer Systems International Inc. differentiates via modular warehouse automation architectures that incorporate electric monorail segments into broader intralogistics ecosystems.
Material handling monorails are overhead track-mounted conveyance systems, typically fabricated from rolled steel I-beams or enclosed profile rails with load capacities ranging from 50 kg to several tonnes, designed to suspend, transport, and position goods along fixed linear paths within industrial facilities. Electric monorails equipped with wireless control technology are capturing accelerated investment as facilities pursue real-time fleet coordination without tethered power rails. Manual and chain monorail variants retain stable demand in cost-sensitive warehousing applications where throughput volumes do not justify full automation capital outlay. Aerospace and pharmaceutical applications command premium positioning due to cleanroom compatibility requirements and precision positioning tolerances.
FDA equipment qualification standards and OSHA overhead crane regulations shape product design criteria for pharmaceutical and general manufacturing deployments in the United States. The EU Machinery Directive and CE marking requirements enforce structural integrity and control-system redundancy benchmarks for European installations. Stakeholders must monitor evolving interoperability standards between automated monorail fleets and warehouse management software platforms to preserve capital deployment flexibility.
Market Dynamics
Wireless control architectures and battery-electric propulsion are rewriting capital deployment patterns as facilities abandon conductor-bar power rails for untethered fleet coordination. OSHA overhead crane regulations and EU Machinery Directive compliance mandates are compressing procurement timelines toward certified automated systems.
Growth Catalysts
- EU Machinery Directive enforcement:CE marking requirements for structural integrity and control-system redundancy are accelerating replacement cycles in German and French automotive plants.
- Just-in-time assembly workflows:Automotive manufacturing lines in Japan and the United States are expanding monorail installations to synchronize component delivery with production cadence.
- Lithium-ion battery density improvements:Extended duty cycles for electric monorails are eliminating downtime for charging in high-throughput warehousing operations.
Market Restraints
- Steel price volatility:Rolled I-beam and enclosed profile rail fabrication costs fluctuate with commodity markets, squeezing margin predictability for system integrators.
- Specialized technician scarcity:Overhead lifting equipment certification requirements under OSHA create bottlenecks in qualified installation and maintenance labor pools.
- Overhead crane substitution:Bridge crane systems retain cost advantages in facilities with irregular load paths or infrequent material movements.
Strategic Opportunities
- Pharmaceutical cleanroom integration:FDA equipment qualification standards create premium positioning for stainless-steel monorail architectures with precision positioning tolerances.
- India warehousing modernization:Logistics verticals in Maharashtra and Gujarat are retrofitting facilities with electric monorail networks under BIS structural standards.
- Warehouse management software interoperability:Real-time fleet coordination APIs are opening channel partnerships between monorail OEMs and enterprise software platforms.
Industry Challenges
- Legacy system integration friction:Automated monorail fleets require middleware development to synchronize with existing programmable logic controller architectures.
- Certification timeline compression:OSHA and EU Notified Body review queues extend project delivery schedules, straining contractor cash conversion cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Material Handling Monorails Market |
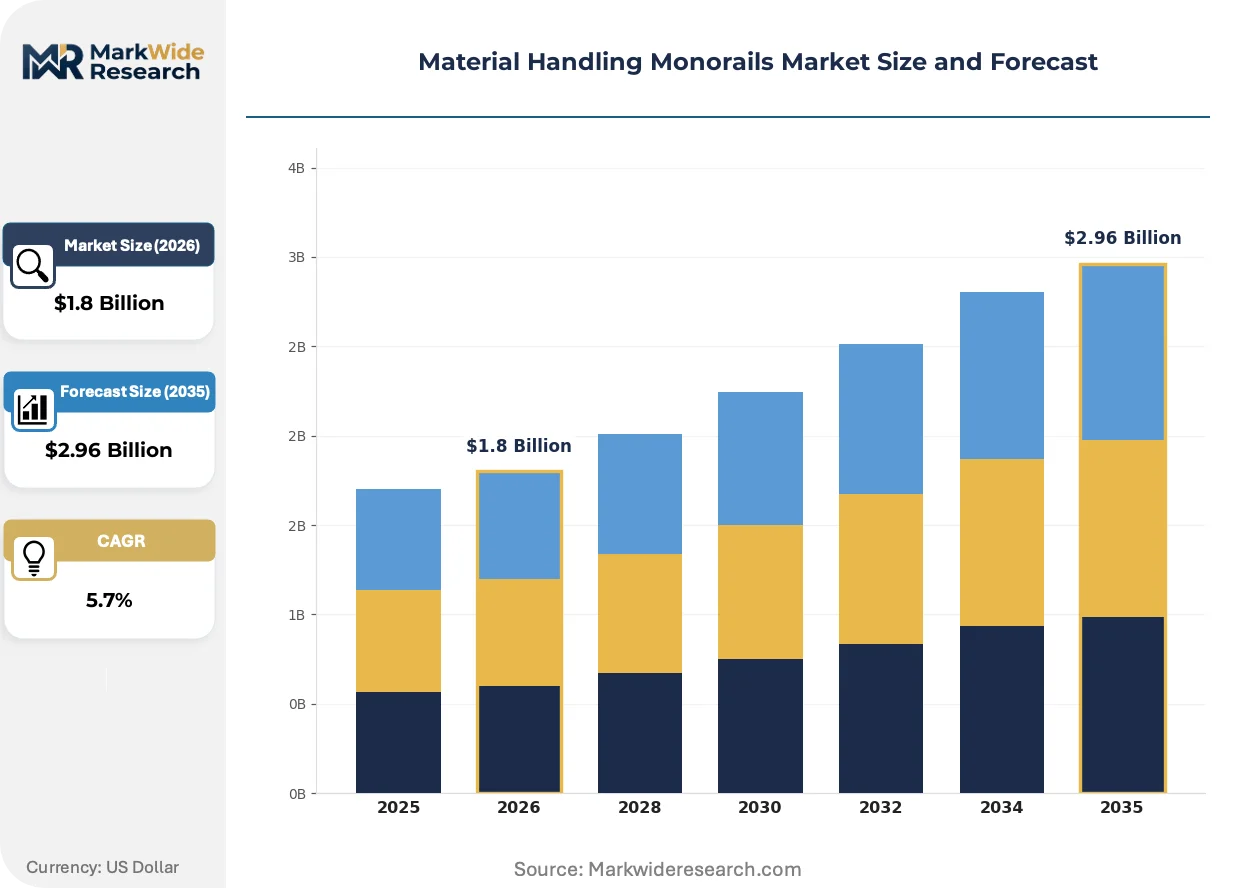
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Overhead Monorails, Chain Monorails, Electric Monorails, Manual Monorails Application: Aerospace, Automotive Manufacturing, Food Processing, Pharmaceutical Industry Vertical: Logistics, Manufacturing, Retail, Warehousing Technology: Automated Systems, Manual Systems, Hybrid Systems, Wireless Control |
| Companies Covered | Daifuku Co., Ltd., Konecranes Inc., Murata Machinery USA, Inc., Schaefer Systems International Inc., EISENMANN Anlagenbau GmbH & Co. KG, ACCO Material Handling Solutions, Acetarc Monorail & Crane Systems, SCAGLIA INDEVA S.p.A., SPANCO Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Material Handling Monorails Market Shifts & Advancements
Electrification and digitalization are converging to untether material flow from fixed infrastructure constraints. Three developments are restructuring competitive advantage and procurement criteria.
Wireless inductive power transfer and onboard battery management systems are rewriting fleet topology economics. Pharmaceutical and aerospace cleanroom operators are adopting these architectures to eliminate conductor-bar contamination risks and enable route reconfiguration without structural modification. The technology is compressing payback periods for facilities with frequent layout changes.
OSHA crane operator certification mandates and EU Machinery Directive control-system redundancy benchmarks are tightening compliance thresholds. Manufacturers must now document fail-safe braking and collision-avoidance logic to secure market access. German automotive plants and US general manufacturing facilities are prioritizing pre-certified subsystem procurement to accelerate commissioning timelines.
Outcome-based maintenance contracts are displacing traditional break-fix service arrangements. Third-party logistics operators in China's eastern manufacturing corridor are unbundling hardware purchase from lifecycle performance guarantees. This restructuring shifts supplier revenue toward uptime commitments and predictive analytics subscriptions.
Material Handling Monorails Market Segmentation
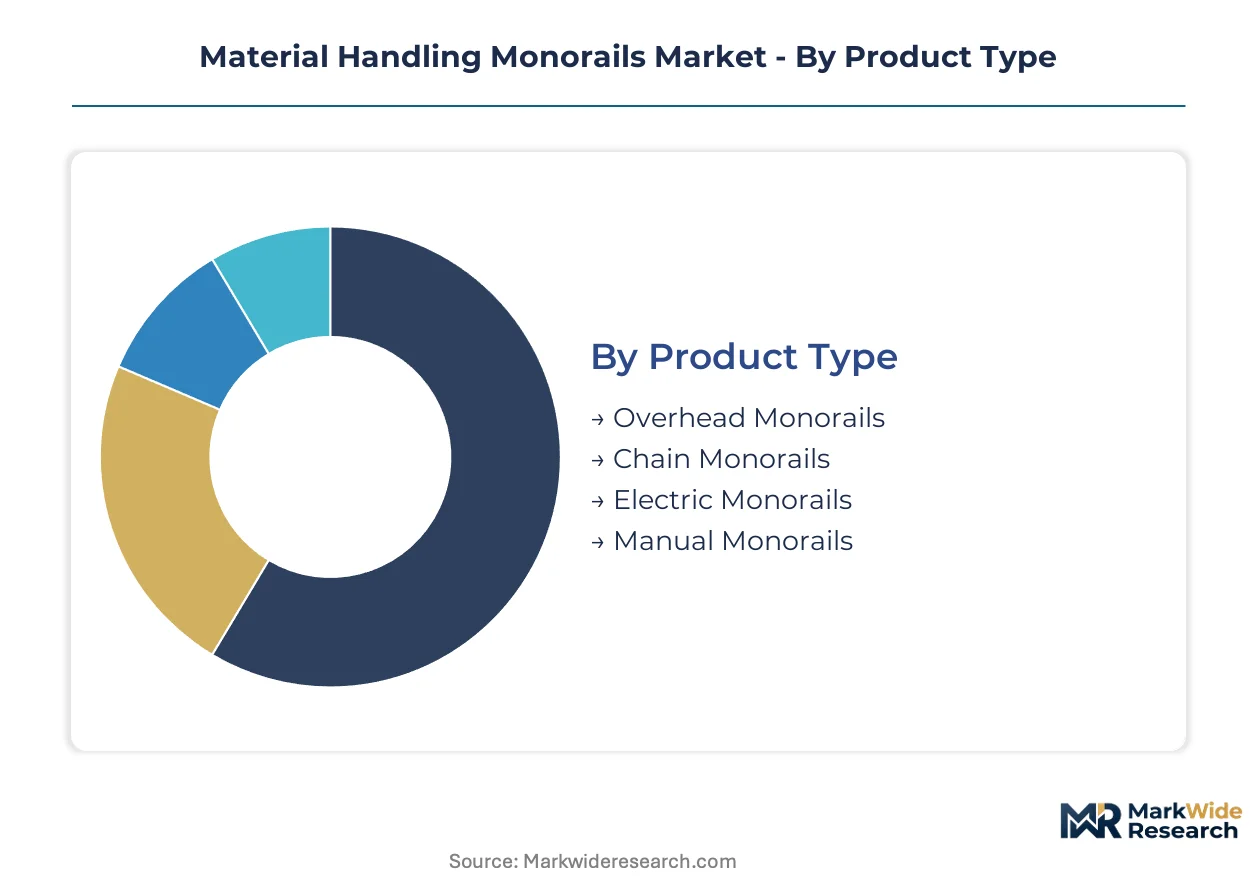
Segmentation in the material handling monorails market exposes divergent engineering requirements across power architectures and end-use environments. Procurement patterns split sharply between facilities pursuing full automation versus those optimizing capital efficiency through manual or hybrid configurations.
Product Type:
Supply concentration in electric and automated variants is tightening as German and Japanese automotive plants consolidate procurement around certified subsystem vendors.
- Electric Monorails:Battery-electric propulsion with onboard lithium-ion packs and wireless control modules eliminates conductor-bar infrastructure. Demand concentrates in China's eastern manufacturing corridor where warehousing operators retrofit facilities for untethered fleet coordination.
- Overhead Monorails:Rolled steel I-beam or enclosed profile rail systems with trolley-mounted hoists handle loads from 50 kg to several tonnes. German automotive lines are expanding installations to synchronize just-in-time component delivery with assembly cadence.
- Chain Monorails:Enclosed track systems with chain-driven trolleys for medium-duty cycles in cost-sensitive operations.
- Manual Monorails:Push-type trolleys on fixed tracks retain stable demand in warehousing applications where throughput volumes do not justify automation capital outlay.
Today's leader: Electric Monorails. Tomorrow's challenger: Overhead Monorails.
Application:
Margin profiles diverge sharply between precision-tolerance cleanroom environments and general manufacturing floors.
- Pharmaceutical:Stainless-steel architectures with FDA equipment qualification compliance and precision positioning tolerances for cleanroom compatibility. Aerospace and pharmaceutical facilities command premium positioning due to contamination control requirements.
- Automotive Manufacturing:Just-in-time assembly workflows in Germany, Japan, and the United States are expanding monorail installations to synchronize component delivery with production cadence.
- Aerospace:Cleanroom-compatible systems with tight positioning tolerances for aircraft component handling.
- Food Processing:Washdown-rated constructions with sanitary finishes for hygiene-critical operations.
Pharmaceutical commands the steepest premium trajectory. Automotive Manufacturing delivers the deepest volume base.
Industry Vertical:
Customer type fragmentation is producing distinct procurement behaviors between asset-heavy manufacturers and third-party logistics operators.
- Warehousing:Electric and wireless-controlled monorail networks are capturing accelerated investment as logistics operators in China's eastern corridor retrofit facilities for real-time fleet coordination.
- Manufacturing:Integrated material handling platforms anchor large-scale automotive plant installations across Asia with overhead crane-to-monorail interoperability requirements.
- Logistics:Outcome-based maintenance contracts are displacing break-fix arrangements as operators unbundle hardware purchase from lifecycle performance guarantees.
- Retail:Distribution center automation with modular warehouse architectures incorporating electric monorail segments into broader intralogistics ecosystems.
Warehousing is gaining share fastest. Manufacturing retains the installed base dominance.
Technology:
Technology maturity curves are compressing procurement timelines toward pre-certified automated systems under OSHA and EU Machinery Directive mandates.
- Wireless Control:Untethered fleet coordination architectures with real-time positioning and route reconfiguration capability. Pharmaceutical cleanroom operators adopt these systems to eliminate conductor-bar contamination risks.
- Automated Systems:Programmable logic controller-synchronized fleets with fail-safe braking and collision-avoidance logic for OSHA compliance.
- Hybrid Systems:Manual override capability on automated tracks for flexibility in variable-throughput environments.
- Manual Systems:Basic push-type or pendant-controlled trolleys for low-complexity material movements.
Wireless Control is expanding most quickly. Automated Systems holds the certification advantage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing monorail procurement across jurisdictions where CE marking and OSHA compliance costs diverge from emerging-market certification pathways. German and Japanese automotive manufacturers maintain premium-tier demand, while Chinese warehousing operators exploit cost-advantaged electric fleet deployment.
China
Lithium-ion battery density improvements and wireless control architectures are accelerating retrofit cycles in warehousing and logistics verticals. GB standards under SAMR jurisdiction enforce structural integrity benchmarks for overhead lifting equipment. Shanghai and Jiangsu province manufacturing clusters are deploying untethered electric monorail networks for real-time fleet coordination.
Germany
Just-in-time assembly workflows in automotive plants are expanding certified subsystem procurement for overhead crane-to-monorail interoperability. EU Machinery Directive enforcement through Notified Body review mandates CE marking for control-system redundancy. Bavaria and Baden-Württemberg automotive corridors are prioritizing pre-certified automated systems to compress commissioning timelines.
United States
OSHA overhead crane regulations are compressing procurement timelines toward compliant automated systems in general manufacturing and pharmaceutical facilities. FDA equipment qualification standards shape stainless-steel architecture requirements for cleanroom compatibility. Michigan and Ohio automotive manufacturing clusters are synchronizing component delivery monorail installations with production cadence.
Japan
Automotive manufacturing lines are expanding monorail installations for just-in-time assembly workflows with precision positioning tolerances. METI industrial standards and JIS certification requirements enforce fail-safe braking documentation for market access. Kanto and Chubu regional production hubs are consolidating procurement around integrated material handling platform vendors.
India
Logistics verticals in warehousing modernization are retrofitting facilities with electric monorail networks under BIS structural standards. Central government infrastructure allocation and state-level industrial corridor programs subsidize automation capital outlay. Maharashtra and Gujarat manufacturing clusters are capturing accelerated investment in battery-electric propulsion systems.
Material Handling Monorails Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue wireless control and battery-electric specialization. The vendor base stratifies across integrated platform providers, modular subsystem specialists, and regional fabrication houses. Three archetypes dominate: automotive-anchored system integrators, warehouse automation architects, and overhead crane interoperability engineers. Consolidation pressure is producing vertical integration moves and geographic licensing arrangements.
Within the integrated platform tier, Daifuku Co., Ltd. and Konecranes Inc. exemplify divergent strategic positioning. Daifuku anchors large-scale automotive plant installations across Asia through its material handling ecosystem. Konecranes occupies a position emphasizing overhead crane-to-monorail interoperability engineering. Schaefer Systems International Inc. represents the modular warehouse automation archetype, incorporating electric monorail segments into broader intralogistics architectures. These three entities collectively illustrate the competitive tension between end-to-end integration and specialized subsystem excellence.
| Leading Market Players |
|---|
| Daifuku Co., Ltd. |
| Konecranes Inc. |
| Murata Machinery USA, Inc. |
| Schaefer Systems International Inc. |
| EISENMANN Anlagenbau GmbH & Co. KG |
| ACCO Material Handling Solutions |
| Acetarc Monorail & Crane Systems |
| SCAGLIA INDEVA S.p.A. |
| SPANCO Inc. |
| Others |
Supply & Pricing Matrix
Certified overhead lifting equipment technicians concentrated in Germany's Bavaria and Baden-Württemberg automotive corridors command wage premiums that compress pricing-tier spreads between premium automated systems and standard manual configurations. Labor-cost differentials between these German engineering clusters and China's Jiangsu province manufacturing bases create arbitrage opportunities for system integrators sourcing installation and commissioning services.
Pricing Analysis
Distributor margins on electric monorail subsystems typically range from 12-18% for standard overhead track configurations to 25-35% for pharmaceutical-grade stainless-steel architectures with FDA qualification documentation. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked automated fleets with fail-safe redundancy from basic chain-driven trolleys. Pricing pressure stems from steel price volatility squeezing margin predictability for rolled I-beam fabrication. Third-party logistics operators in cost-sensitive warehousing applications exhibit highest price sensitivity, while aerospace cleanroom operators prioritize certification grade over unit economics.
Supply Chain Analysis
Lithium-ion battery cell supply rests on South Korean and Japanese specialty producers, with Chinese cathode material processors anchoring midstream consolidation. Rolled steel I-beam and enclosed profile rail fabrication draws from German and Chinese mill capacity, while wireless control module assembly concentrates in Taiwan and South Korea. Single-source vulnerability in semiconductor components for programmable logic controllers creates procurement risk for automated system integrators. Distribution runs through regional system integrators with certified installation capabilities rather than direct OEM-to-end-user channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where OSHA overhead crane certification mandates and EU Machinery Directive enforcement accelerate replacement demand beyond pure capacity expansion cycles.
For Market Incumbents: Anticipate margin compression from battery-electric propulsion commoditization by deepening in-house production of lithium-ion pack assembly and wireless control firmware. Defend positioning through pre-certified subsystem procurement partnerships with German Notified Bodies to compress commissioning timelines for automotive clients facing JIT assembly workflow penalties. For New Entrants and Emerging Players: Launch via outcome-based maintenance contract structures that unbundle hardware purchase from uptime guarantees, targeting India's Maharashtra and Gujarat warehousing modernization programs under subsidized automation capital allocations. White-space concentration sits in pharmaceutical cleanroom integration where FDA equipment qualification barriers deter generalist competitors. For Investors and Strategic Acquirers: Warehouse automation architects with modular intralogistics ecosystems represent the most active acquirer category in this space, seeking electric monorail segment capabilities to complete platform breadth. Long-term viability centers on software interoperability rather than mechanical fabrication scale. Watch wireless fleet coordination API standardization as the inflection signal for platform consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Battery Assembly | Captures lithium-ion pack margin and secures supply continuity for electric fleet deployments. |
| CE Marking Pre-Certification Investment | Accelerates German automotive plant commissioning timelines under EU Machinery Directive enforcement. |
| Warehouse Management Software Partnership | Opens channel access through real-time fleet coordination API integration with enterprise platforms. |
| India Manufacturing Footprint Establishment | Positions for Maharashtra and Gujarat logistics vertical retrofit cycles under BIS structural standards. |
| Outcome-Based Service Contract Launch | Shifts revenue toward predictive analytics subscriptions with uptime performance guarantees. |
Research Methodology
Direct dialogue with plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads combined with secondary validation against customs records, SEC filings, and industrial automation trade association datasets. Bottom-up and top-down triangulation cross-referenced facility-level installation data with macroeconomic industrial production indices across the analysis window.
Segment-level outputs across power architecture, application environment, and technology maturity were derived through regression modeling of replacement cycle timing and regulatory compliance cost absorption rates. CAGRs were computed from installed base turnover projections and greenfield capacity announcements without year-specific anchoring. Steel price volatility and certified technician wage trajectories served as primary sensitivity inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated EU Machinery Directive enforcement or prolonged OSHA certification queue backlogs. Projections reflect assumptions regarding lithium-ion battery density improvement continuity and wireless standard interoperability adoption curves. A small set of regulatory milestone triggers and commodity price inflection points warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Cherry Picker Crane Market
Material Handling Equipment
Cable Conduit Systems Market
Material Handling Equipment
Light Duty Telehandler Market
Material Handling Equipment
Australia Forklift Rental Market
Material Handling Equipment
Drive-In Pallet Racking Market
Material Handling Equipment
Hydraulic Fittings Market
Material Handling Equipment
Spiral Fitting Machines Market
Material Handling Equipment
Machined Springs Market
Material Handling Equipment
Pneumatic Conveying Diverters Market
Material Handling Equipment
Lump Breaker Machines Market
Material Handling Equipment
Hoist Market
Material Handling Equipment
Chain-Driven Roller Conveyors Market
Material Handling Equipment
Container Handler Market
Material Handling Equipment
Industrial Hose Assemblies Market
Material Handling Equipment
Modular Conveyor System Market
Material Handling Equipment
Precision Gearbox Machinery Market