
 ASEAN Conveyor System Market | 2026-2036
ASEAN Conveyor System Market Size, Share, and Industry Trends Forecast 2026-2036
ASEAN Conveyor System Market Outlook
Food and beverage manufacturing is broadening its share of ASEAN conveyor demand as hygiene-grade stainless steel belt systems replace legacy configurations in Thailand and Vietnam. Daifuku Co., Ltd. leverages its regional service network to anchor automated warehousing projects across Southeast Asian logistics hubs. SSI Schaefer AG competes through modular installation architectures that reduce downtime for pharmaceutical clients in Singapore and Malaysia. Murata Machinery, Ltd. specializes in compact roller conveyor cells designed for electronics contract manufacturers with space-constrained floor plans.
A conveyor system comprises motorized or gravity-driven mechanisms using belts, rollers, chains, or screws to transport materials between process stages, with load capacity, speed control, and contamination resistance as critical design parameters. These systems serve as the physical backbone of manufacturing and distribution operations where throughput consistency directly determines operational economics. Belt conveyors dominate food and beverage installations where washdown compliance and gentle product handling create premium margin pools. Automated technology segments are expanding fastest as Thai and Vietnamese factories retrofit for Industry 4.0 compatibility, while manual and hybrid configurations retain cost advantages in smaller warehousing operations across Indonesia and the Philippines.
Thailand's Board of Investment and Vietnam's Ministry of Industry and Trade shape equipment standards through smart factory incentive schemes that mandate programmable logic controller integration and energy efficiency benchmarks. Singapore's Workplace Safety and Health Council enforces conveyor guarding and emergency stop protocols that elevate compliance costs for entry-tier suppliers. Malaysia's Department of Standards Malaysia aligns national specifications with ISO 5040 for continuous handling equipment, creating harmonized procurement criteria across integrated ASEAN supply chains. Stakeholders must monitor how divergent national certification timelines affect cross-border equipment deployment and aftermarket service economics.
Market Dynamics
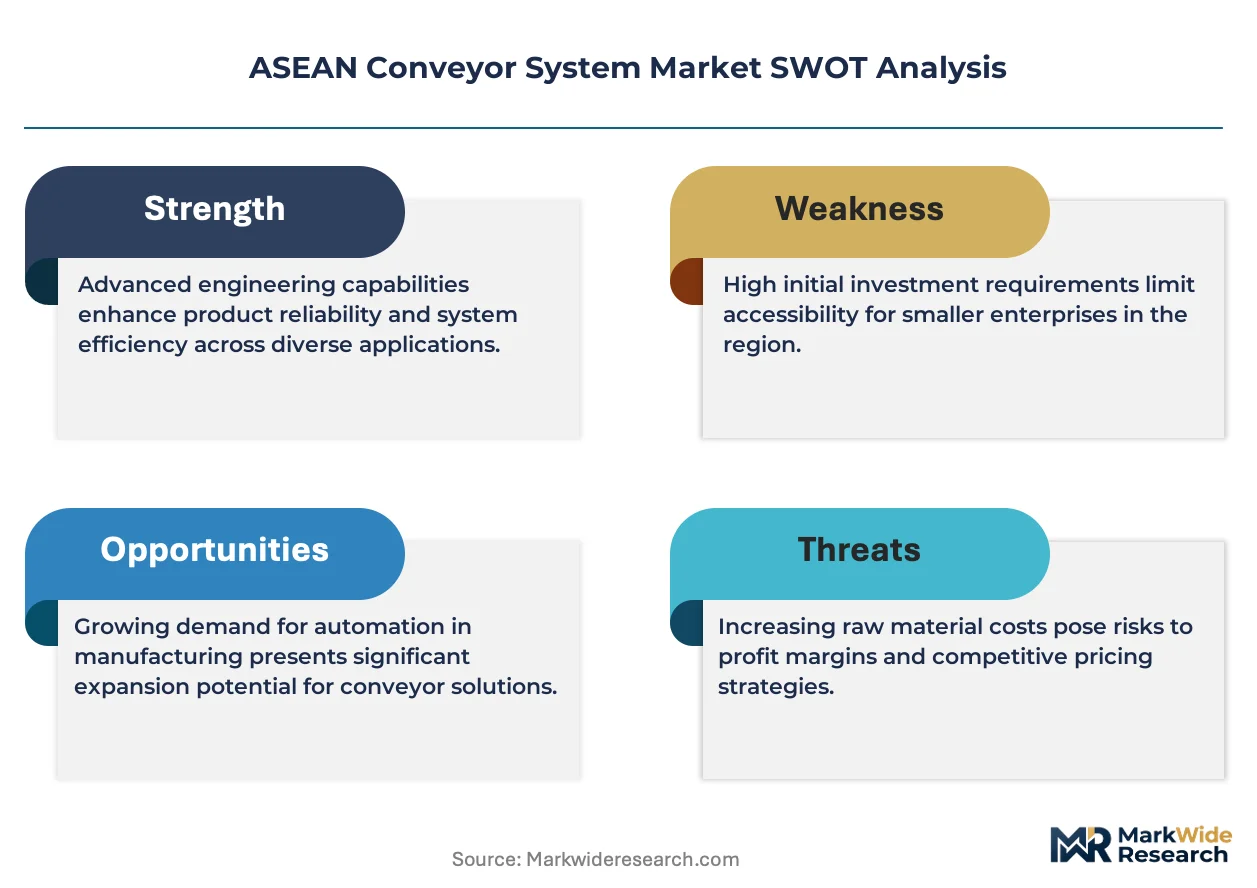
Thailand's Board of Investment smart factory incentives are compressing procurement cycles toward automated programmable conveyors, while Vietnam's northern electronics clusters concentrate precision roller demand in a narrow industrial corridor. This regulatory-demand intersection is restructuring competitive positioning across the six-member economic bloc.
Growth Catalysts
- Thailand BOI Incentive Programs:Tax holidays and import duty exemptions for Industry 4.0 equipment upgrades are accelerating replacement of manual conveyor lines with sensor-integrated belt systems in automotive parts manufacturing.
- Electronics Assembly Concentration:Vietnam's Bac Ninh and Bac Giang provinces host expanding Samsung and Foxconn facilities that specify ISO 5040-compliant precision roller configurations for chip handling operations.
- Food Safety Mandates:Stainless steel hygienic belt systems are displacing legacy PVC configurations as Thailand's FDA-equivalent authority tightens washdown compliance for processed food exports to EU markets.
Market Restraints
- Steel Input Volatility:Hot-rolled coil price fluctuations from Chinese state-owned mills transmit directly to ASEAN conveyor OEM margins, compressing project bidding flexibility for mid-tier Thai fabricators.
- Controller Supply Concentration:Programmable logic controller dependency on German and Japanese suppliers creates 12-16 week lead time risks for Vietnamese system integrators serving just-in-time electronics clients.
- Technical Limitation:Belt conveyor systems face displacement pressure from autonomous mobile robots in Singapore's high-wage warehousing operations where floor space optimization overrides fixed infrastructure economics.
Strategic Opportunities
- Indonesia Underpenetration:Archipelago logistics fragmentation creates white space for modular gravity conveyor installations in third-party distribution centers serving Jakarta-Bandung manufacturing corridors.
- Pharmaceutical Cleanroom Expansion:Malaysia's Penang and Selangor pharma clusters are specifying FDA-validated chain conveyor cells for active ingredient handling, opening premium specification tiers.
- Technology Convergence:Machine vision integration with belt tracking systems is enabling predictive maintenance contracts that shift supplier revenue models from equipment sales to uptime guarantees.
Industry Challenges
- Automation Technician Scarcity:Vietnamese vocational programs produce insufficient PLC programming specialists to service the retrofit wave in Haiphong and Hai Duong industrial zones.
- Legacy Integration Complexity:Thai food processors face 30-40% cost overruns when bridging 1990s-era mechanical lines with new sensor networks for BOI compliance reporting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ASEAN Conveyor System Market |
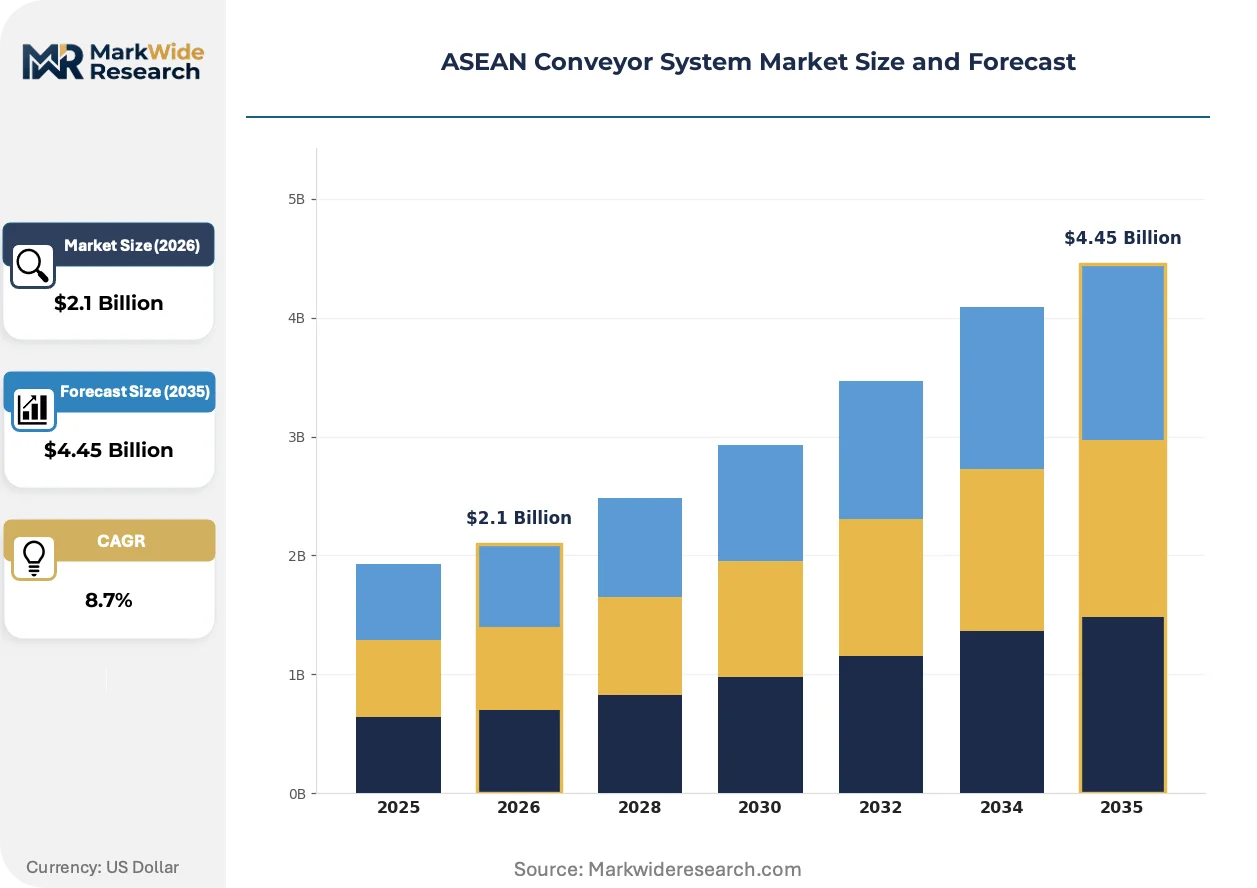
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.45 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Belt Conveyors, Roller Conveyors, Chain Conveyors, Screw Conveyors End User: Manufacturing, Warehousing, Food & Beverage, Pharmaceuticals Technology: Automated, Manual, Hybrid, Programmable Installation: On-site, Modular, Integrated, Portable |
| Companies Covered | Honeywell Intelligrated, Dematic, Daifuku Co., Ltd., Swisslog Holding AG, Vanderlande, SSI Schaefer AG, BEUMER Group, KUKA AG, Murata Machinery, Ltd., Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ASEAN Conveyor System Market Strategic Shifts
Digital thread architectures are threading through ASEAN manufacturing floors, compressing the gap between physical conveyor assets and enterprise planning systems. Three distinct vectors are reshaping equipment specification and supplier economics.
Edge computing modules are integrating directly into motorized roller controllers, enabling real-time vibration analysis and belt tension monitoring without centralized server dependency. Thai automotive tier-one suppliers are piloting these configurations in Rayong province assembly feed lines. This distributed intelligence architecture is compressing maintenance response windows from hours to minutes while reducing cabling infrastructure costs.
Malaysia's Department of Standards Malaysia alignment with ISO 5040 is mandating documented load testing and emergency stop validation for all continuous handling equipment installations. Industrial consequence includes mandatory third-party certification for conveyor systems serving integrated ASEAN supply chains. Pharmaceutical and food processing facilities in Penang and Johor are responding by pre-qualifying suppliers with established ISO 5040 test protocols, filtering out smaller fabricators lacking metrology capabilities.
Buying committees in Vietnam's northern provinces are unbundling after-sales service from initial equipment contracts, creating discrete markets for maintenance, spare parts, and remote monitoring. Electronics contract manufacturers in Bac Ninh are sourcing conveyor hardware from Korean OEMs while contracting maintenance to local Vietnamese service firms. This disintermediation is most visible in the smartphone assembly vertical where annual line reconfiguration cycles favor flexible service relationships over bundled long-term agreements.
ASEAN Conveyor System Market Segmentation
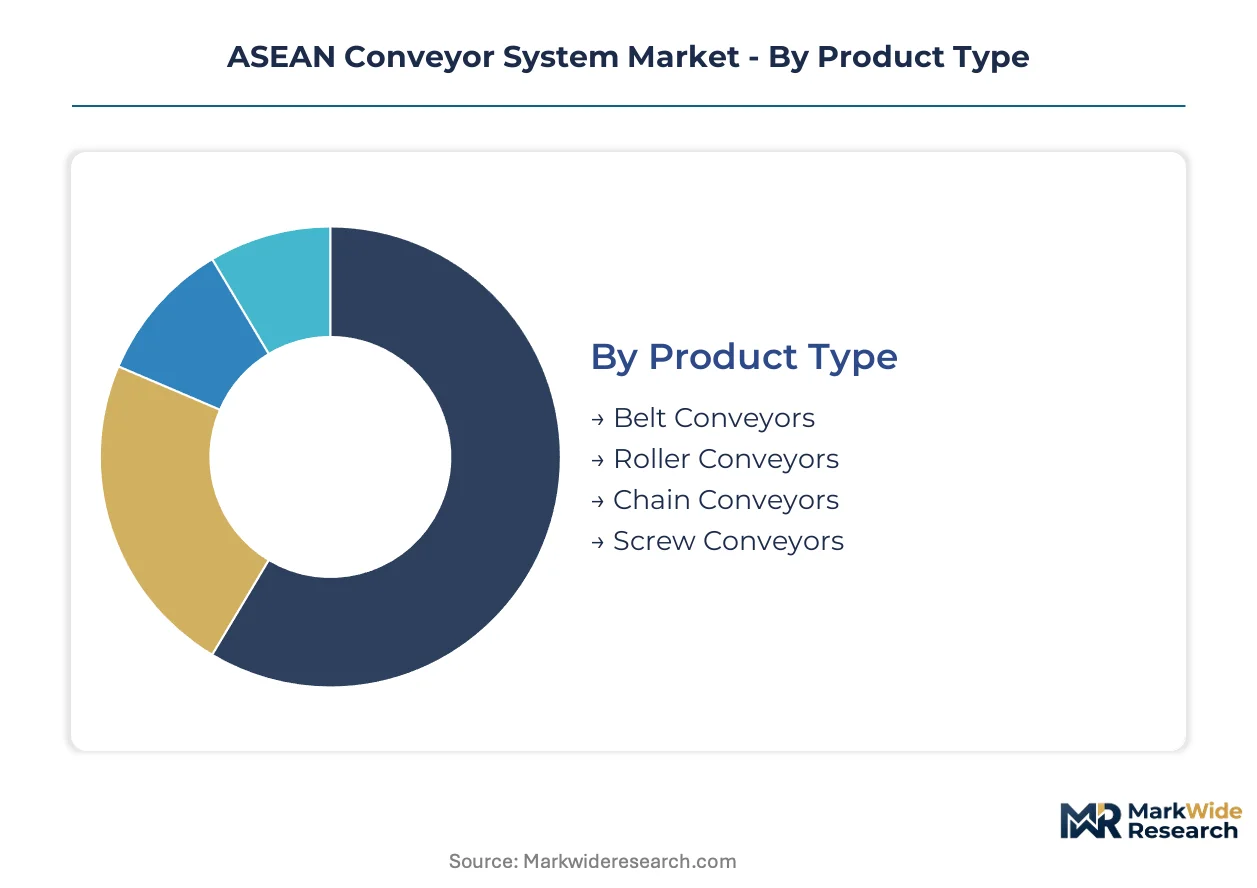
Conveyor system procurement across ASEAN diverges sharply by operational intensity, hygiene mandates, and automation readiness. Equipment specification varies with facility scale, from manual gravity-fed lines in Indonesian warehousing to sensor-integrated programmable systems in Thai automotive plants.
Product Type:
Buyers differentiate primarily by load characteristics and contamination sensitivity rather than initial capital outlay.
- Belt Conveyors:Fabric or modular plastic belts handle bulk solids and packaged goods with continuous surface contact. Thailand's FDA-equivalent washdown mandates for EU-bound food exports are displacing legacy PVC configurations with stainless steel hygienic belt systems in Samut Sakhon processing zones.
- Roller Conveyors:Cylindrical rollers rotate on precision bearings to transport rigid containers and palletized loads with minimal friction. Vietnam's Bac Ninh and Bac Giang electronics clusters specify ISO 5040-compliant precision roller configurations for chip handling operations in Samsung and Foxconn facilities.
- Chain Conveyors:Metal chain links withstand high-temperature and heavy-load environments in automotive assembly. Malaysia's Penang pharma clusters deploy FDA-validated chain cells for active ingredient handling.
- Screw Conveyors:Helical blades rotate within enclosed troughs to move powders and granular materials. Indonesian cement and fertilizer plants favor screw configurations for dust-containment compliance.
Belt conveyors lead volumes today; roller conveyors are gaining share fastest in precision manufacturing corridors.
End User:
Facility automation maturity and regulatory exposure determine equipment complexity and service contract structures.
- Manufacturing:Assembly feed lines and work-in-progress transport dominate capital allocation. Thai automotive tier-one suppliers in Rayong province pilot edge-computing motorized roller controllers for real-time vibration analysis.
- Warehousing:Order fulfillment and cross-docking operations prioritize throughput density. Singapore's high-wage warehousing operations face displacement pressure from autonomous mobile robots where floor space optimization overrides fixed infrastructure economics.
- Food & Beverage:Hygiene-grade stainless steel configurations command premium margins. Thailand and Vietnam broaden installed bases of washdown-compliant belt systems for processed food export growth.
- Pharmaceuticals:Cleanroom-validated chain and belt systems require documented load testing and third-party certification. Malaysia's Department of Standards Malaysia alignment with ISO 5040 filters out smaller fabricators lacking metrology capabilities.
Manufacturing absorbs the largest equipment spend; pharmaceuticals shows the steepest specification escalation trajectory.
Technology:
Control architecture sophistication separates maintenance-intensive mechanical systems from predictive maintenance-enabled digital assets.
- Automated:Sensor networks and programmable logic controllers enable unmanned operation with centralized monitoring. Thai BOI smart factory incentives compress procurement cycles toward automated programmable conveyors with tax holidays and import duty exemptions.
- Manual:Gravity-fed or hand-cranked systems minimize capital expenditure and technical dependency. Smaller warehousing operations across Indonesia and the Philippines retain cost advantages in manual and hybrid configurations.
- Hybrid:Semi-automated zones combine motorized sections with manual sortation stations. Vietnamese electronics contract manufacturers favor hybrid architectures for annual line reconfiguration flexibility.
- Programmable:PLC-integrated systems support Industry 4.0 data exchange protocols and energy efficiency benchmarks. Vietnam's Ministry of Industry and Trade mandates programmable logic controller integration for smart factory incentive eligibility.
Manual systems dominate installed base; programmable configurations climb the fastest as retrofit waves accelerate.
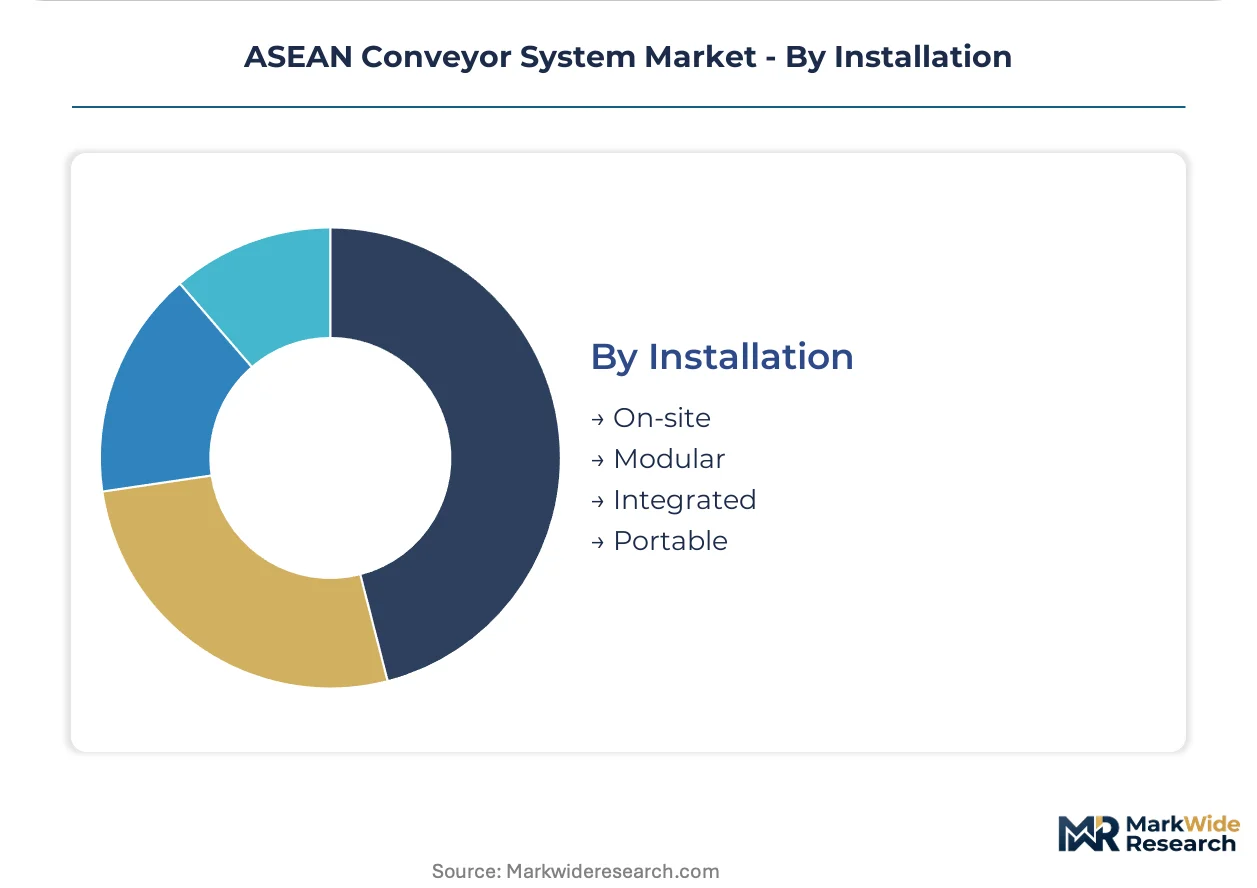
Installation:
Project delivery method shapes downtime risk, supplier qualification requirements, and total cost of ownership calculations.
- On-site:Custom-fabricated and welded structures accommodate irregular facility geometries. Thai food processors face 30-40% cost overruns when bridging 1990s-era mechanical lines with new sensor networks for BOI compliance reporting.
- Modular:Pre-engineered sections reduce installation time and enable future reconfiguration. SSI Schaefer AG competes through modular installation architectures that reduce downtime for pharmaceutical clients in Singapore and Malaysia.
- Integrated:Conveyor systems embed within comprehensive material handling ecosystems including robotics and warehouse management software. Daifuku Co., Ltd. leverages its regional service network to anchor automated warehousing projects across Southeast Asian logistics hubs.
- Portable:Castor-mounted or skid-based units serve temporary operations and seasonal demand spikes. Archipelago logistics fragmentation in Indonesia creates white space for modular gravity conveyor installations in third-party distribution centers.
On-site fabrication retains volume leadership; modular approaches are expanding most quickly for reconfiguration-dependent industries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bac Ninh and Bac Giang provinces anchor ASEAN conveyor demand through expanding electronics assembly corridors. Vietnam's northern industrial belt concentrates precision roller procurement for semiconductor and smartphone manufacturing. Thailand's automotive tier-one suppliers in Rayong province drive automated belt system retrofits.
Thailand
Automotive parts manufacturers in Rayong and Chonburi provinces specify sensor-integrated belt systems for assembly feed lines. Thailand's Board of Investment grants tax holidays and import duty exemptions for Industry 4.0 equipment upgrades. Samut Sakhon processing zones deploy stainless steel hygienic configurations to meet FDA-equivalent washdown mandates for EU-bound food exports.
Vietnam
Samsung and Foxconn facilities in Bac Ninh and Bac Giang drive ISO 5040-compliant precision roller demand for chip handling operations. Vietnam's Ministry of Industry and Trade mandates programmable logic controller integration for smart factory incentive eligibility. Haiphong and Hai Duong industrial zones face automation technician scarcity as vocational programs produce insufficient PLC programming specialists.
Malaysia
Penang and Selangor pharmaceutical clusters specify FDA-validated chain conveyor cells for active ingredient handling. Malaysia's Department of Standards Malaysia aligns national specifications with ISO 5040 for continuous handling equipment. Johor food processing facilities pre-qualify suppliers with established ISO 5040 test protocols, filtering out smaller fabricators lacking metrology capabilities.
Singapore
High-wage warehousing operations face displacement pressure from autonomous mobile robots where floor space optimization overrides fixed infrastructure economics. Singapore's Workplace Safety and Health Council enforces conveyor guarding and emergency stop protocols that elevate compliance costs for entry-tier suppliers. Integrated logistics hubs anchor automated warehousing projects requiring comprehensive material handling ecosystems.
Indonesia
Archipelago logistics fragmentation creates white space for modular gravity conveyor installations in third-party distribution centers. Jakarta-Bandung manufacturing corridors favor manual and hybrid configurations for cost-sensitive warehousing operations. Cement and fertilizer plants in East Java specify screw conveyors for dust-containment compliance in bulk material handling.
ASEAN Conveyor System Market Competitive Environment
Strategic partnerships dominate the current landscape as suppliers anchor regional service networks and anchor automated warehousing projects. The vendor base stratifies across three tiers: multinational integrators with comprehensive material handling ecosystems, regional specialists in modular installation architectures, and local fabricators serving cost-sensitive manual system demand. Two competitive vectors reshape positioning: technology convergence through machine vision integration, and geographic expansion via localized maintenance and spare parts networks.
Among Japanese-headquartered multinationals, Daifuku Co., Ltd. and Murata Machinery, Ltd. occupy positions emphasizing regional service density and compact roller configurations respectively. Daifuku exemplifies the integrated-systems archetype through its automated warehousing footprint across Southeast Asian logistics hubs. Murata Machinery represents the precision-manufacturing specialist tier with roller conveyor cells designed for space-constrained electronics contract manufacturers. SSI Schaefer AG anchors the European-origin modular architecture segment, competing through reduced installation downtime for pharmaceutical and warehousing clients in Singapore and Malaysia.
| Leading Market Players |
|---|
| Honeywell Intelligrated |
| Dematic |
| Daifuku Co., Ltd. |
| Swisslog Holding AG |
| Vanderlande |
| SSI Schaefer AG |
| BEUMER Group |
| KUKA AG |
| Murata Machinery, Ltd. |
| Others |
Value Chain & Pricing Dynamics
Hot-rolled coil price volatility from Chinese state-owned mills cascades through ASEAN conveyor OEM margins, compressing bidding flexibility for mid-tier Thai fabricators while amplifying cost advantages for vertically integrated Japanese and Korean suppliers serving precision roller demand in Vietnam's northern electronics corridor.
Pricing Analysis
Distributor margins of 15-22% separate factory gate pricing from landed equipment costs across Indonesian and Philippine warehousing markets. Three-tier pricing structure across premium ISO 5040-certified systems, standard modular configurations, and economy gravity-fed lines reflects certification investment and after-sales bundling intensity. Price differentiation hinges on PLC integration depth and stainless steel grade specification for Thai food safety compliance. Cost compression in mid-tier belt systems is intensifying because Vietnamese electronics buyers unbundle hardware from service contracts. Manual system buyers in Indonesian third-party logistics show highest price sensitivity; pharmaceutical cleanroom operators in Malaysia Penang show lowest.
Supply Chain Analysis
Refurbishment flows for motorized roller controllers and belt tensioning assemblies remain underdeveloped across ASEAN, creating aftermarket service white space for local Vietnamese and Thai technicians. Manufacturing concentration centers on Japan, Germany, and South Korea for precision roller bearings and programmable logic controllers. Raw material dependencies span hot-rolled steel coil from Chinese mills, specialized polymer compounds for hygienic belts, and precision bearings from Japanese suppliers. Single-source vulnerability in German and Japanese PLC supply creates lead time risk for Vietnamese system integrators serving just-in-time electronics clients. Distribution runs through regional warehousing hubs in Singapore and Bangkok with last-mile installation by certified local service partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ASEAN conveyor demand functions as a stable compounder. Thailand's BOI smart factory incentive schemes and Vietnam's electronics assembly expansion create replacement-cycle visibility that sustains equipment procurement through macroeconomic fluctuations.
For Market Incumbents: Hedge against autonomous mobile robot displacement in Singapore warehousing by deepening predictive maintenance service contracts that shift revenue toward uptime guarantees. Anchor regional service density in Vietnam's Bac Ninh-Bac Giang corridor to capture annual line reconfiguration cycles. Defend margin position through backward integration into precision roller bearing supply rather than exposed steel fabrication.
For New Entrants and Emerging Players: Launch via modular gravity conveyor installations targeting Indonesia's archipelago logistics fragmentation where integrated multinational presence remains thin. Penetrate Jakarta-Bandung third-party distribution centers with portable castor-mounted units for seasonal demand spikes. White space concentrates in aftermarket spare parts and remote monitoring for unbundled Vietnamese electronics contracts.
For Investors and Strategic Acquirers: Roll-up economics work for regional maintenance specialists because Vietnamese buying committees have disintermediated after-sales service from initial equipment contracts, fragmenting vendor relationships. Five-to-ten year viability rests on automation technician scarcity creating captive service revenue streams. Acquisition target archetype: Vietnamese PLC programming specialists with established Foxconn and Samsung facility relationships. Signal to monitor: Thai BOI incentive program expansion or contraction as retrofits accelerate or stall.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Components | Reduces exposure to Chinese steel volatility for Thai automotive belt suppliers. |
| Predictive Maintenance Service Contracts | Captures recurring revenue from Vietnamese electronics line reconfiguration cycles. |
| ISO 5040 Certification Investment | Filters competition in Malaysia pharmaceutical cleanroom specifications. |
| Modular Installation Architecture Expansion | Reduces downtime risk for Singapore pharmaceutical and warehousing clients. |
| Regional Service Network Density Buildout | Anchors automated warehousing projects across Southeast Asian logistics hubs. |
Study Parameters
Multiple input streams — primary interviews with plant engineers and OEM procurement teams, customs and trade flow databases, and ASEAN national standards body filings — were reconciled through bottom-up equipment shipment tallies and top-down manufacturing value-added estimates. Stakeholder consultations spanned maintenance directors at Thai automotive tier-one suppliers, Vietnamese system integrators serving Bac Ninh electronics clusters, and aftermarket service heads at regional distribution partners. Secondary validation drew from Thailand Board of Investment incentive disclosure records, Vietnam Ministry of Industry and Trade smart factory certification registries, and Malaysia Department of Standards Malaysia ISO 5040 alignment documentation.
Historical installation data cross-referenced against panel input from conveyor OEM sales executives and industrial property developers shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type architecture, end-use industry automation maturity, technology control sophistication, and installation delivery method. CAGRs were derived from equipment replacement cycle analysis and incentive-program-driven retrofit acceleration patterns. Industry-specific forecast inputs encompassed Thai BOI tax holiday uptake rates and Vietnamese northern province electronics FDI flow projections.
Forecast precision tightens around the base case; tail outcomes carry wider variance under Chinese steel export restriction scenarios or German-Japanese PLC supply disruption. Practitioners should monitor Thailand BOI incentive renewal schedules and Vietnamese vocational program PLC specialist graduation rates for early signals of retrofit wave sustainability or technician scarcity intensification.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Industrial Racking Systems Market
Material Handling Equipment
Automated Material Handling (AMH) Equipment Market
Material Handling Equipment
Global Bop Handling Systems Market
Material Handling Equipment
Automatic Conveyor Market
Material Handling Equipment
United States Conveyor Belt Market
Material Handling Equipment
Gravity Conveyor Market
Material Handling Equipment
Global Loading Dock Bumpers Market
Material Handling Equipment
Overhead Conveyor Systems Market
Material Handling Equipment
Rubber Tired Gantry (RTG) Crane Market
Material Handling Equipment
India Automated Material Handling (AMH) Market
Material Handling Equipment
Elevator Ropes Market
Material Handling Equipment
Surface Contact Wire Rope Market
Material Handling Equipment
Australia Forklift Market
Material Handling Equipment
Conveyor Belt Market
Material Handling Equipment
Hoist Chains Market
Material Handling Equipment
Slag Handling Equipment Market