
 Electric Single Beam Crane Market | 2026-2036
Electric Single Beam Crane Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Single Beam Crane Market Insights
China's heavy equipment manufacturing corridor is reshaping supply dynamics for electric single beam cranes. Konecranes leverages its European engineering base to compete on high-load precision systems. XCMG anchors its position through domestic scale and cost-optimized fabrication for Asian infrastructure projects. SANY extends its reach into automated crane controls for smart factory deployments.
An electric single beam crane consists of a single horizontal girder mounted atop end trucks, with a hoist trolley traveling along the lower flange to lift loads typically ranging from 0.5 to 20 tons. Wire rope hoists dominate heavy manufacturing applications where lifting height and duty cycles are critical, while chain hoists occupy lighter-load niches in maintenance and assembly workshops. Remote controls and automatic sensors are gaining traction as warehouses and logistic centers prioritize operator safety and throughput optimization.
China's SAMR enforces GB/T crane standards that mandate overload protection and emergency braking systems, while the EU Machinery Directive requires CE marking with documented risk assessments for market access. OSHA in the United States mandates periodic inspection protocols that sustain aftermarket service demand. Stakeholders must monitor evolving interoperability standards between pendant and radio control systems as facilities integrate cranes into broader automation architectures.
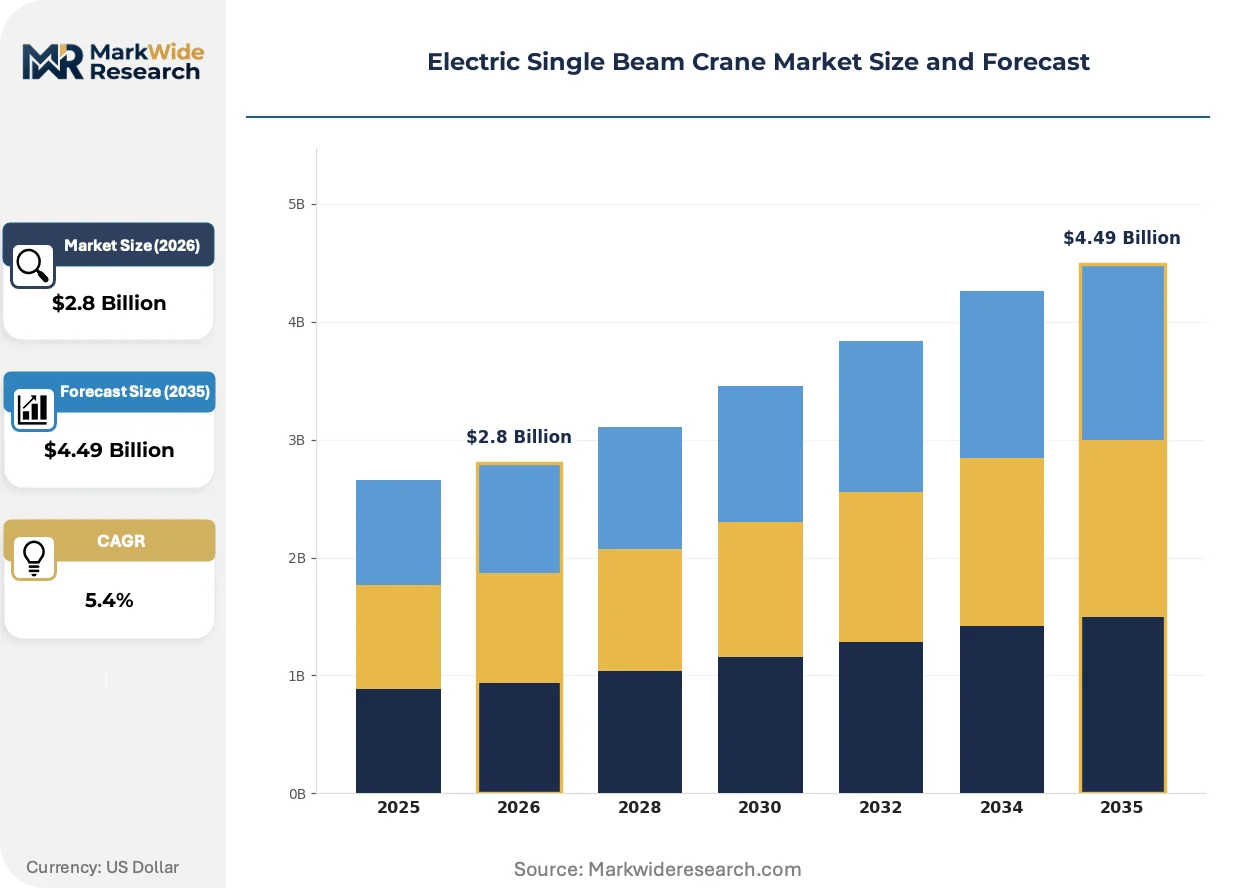
Market Dynamics
Production automation in automotive and heavy machinery manufacturing is pulling crane procurement toward intelligent load-handling systems with integrated safety sensors and remote monitoring capabilities.
Growth Catalysts
- GB/T crane standards:China's SAMR mandates overload protection and emergency braking systems, forcing facility upgrades and replacement cycles across industrial clusters.
- Automotive manufacturing:Assembly line automation requires precision-positioning cranes with synchronized hoist controls for just-in-time component delivery.
- Wire rope hoist technology:Extended lifting heights and continuous duty cycles in heavy fabrication shops favor rope-based systems over chain alternatives.
Market Restraints
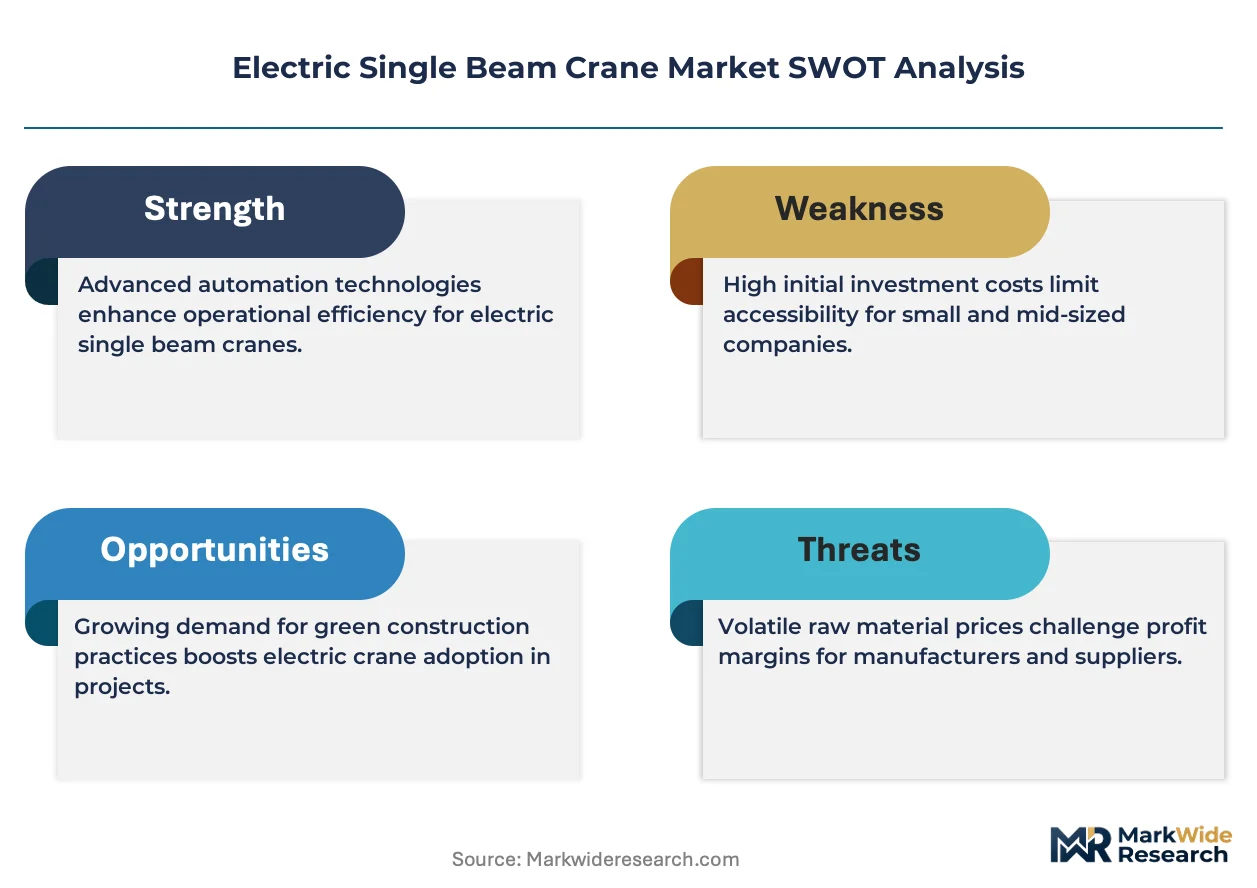
- Steel price volatility:Girder fabrication costs fluctuate with raw material indices, compressing margins for crane builders without long-term supply contracts.
- Supplier concentration:Critical electrical components and variable-frequency drives concentrate among German and Japanese component houses, creating single-source vulnerability.
- Substitution by gantry systems:Outdoor material yards and port-adjacent logistics facilities increasingly specify mobile gantry cranes for span flexibility.
Strategic Opportunities
- Smart factory integration:Automated crane controls converging with warehouse management systems enable unmanned load cycling in distribution centers.
- CE machinery directive compliance:European safety documentation requirements create aftermarket service revenue streams for inspection and recertification.
- Maintenance workshop penetration:Light-capacity chain hoists remain underdeployed in regional repair facilities across India's industrializing states.
Industry Challenges
- Control systems integration:Legacy pendant controls resist interoperability with emerging radio-frequency and automated sensor networks.
- Certification timeline compression:OSHA-mandated inspection protocols strain service technician availability, extending equipment downtime.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Single Beam Crane Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.49 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wire Rope Hoists, Chain Hoists, Winch Hoists, Lever Hoists, Air Hoists Technology: Manual Controls, Remote Controls, Radio Controls, Pendant Controls, Automatic Sensors Application: Manufacturing Units, Construction Sites, Warehouses, Shipyards, Metal Fabrication Plants End User: Manufacturers, Logistic Centers, Maintenance Services, Packaging Facilities, Assembly Workshops |
| Companies Covered | Konecranes, Liebherr, Columbus McKinnon Corporation, ABUS Crane Systems, Terex Corporation, XCMG, SANY, Zoomlion Heavy Industry Science and Technology, Palfinger, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Single Beam Crane Market Trends and Innovations
Intelligent load-handling systems are displacing conventional operator-dependent models as facilities prioritize throughput consistency and incident reduction.
Variable-frequency drive technology is digitizing crane motion control. Automotive assembly plants in Germany and Japan are retrofitting existing installations with VFD-equipped hoists to enable smooth acceleration profiles and precise positioning. The technology is digitizing maintenance scheduling by embedding operational data directly into facility asset management platforms.
REACH substance restrictions are reshaping component material specifications. European crane manufacturers must document hazardous substance compliance in electrical enclosures and cable sheathing, adding documentation burden but creating competitive separation for certified suppliers. Wire rope lubricant formulations face particular scrutiny under extended producer responsibility frameworks.
After-sales service unbundling is fragmenting traditional supply relationships. End-users in China's Yangtze River Delta increasingly contract independent service providers for inspection and repair rather than returning to original equipment sources. This pattern concentrates in high-volume manufacturing corridors where crane populations justify dedicated maintenance staffing.
Electric Single Beam Crane Market Segmentation
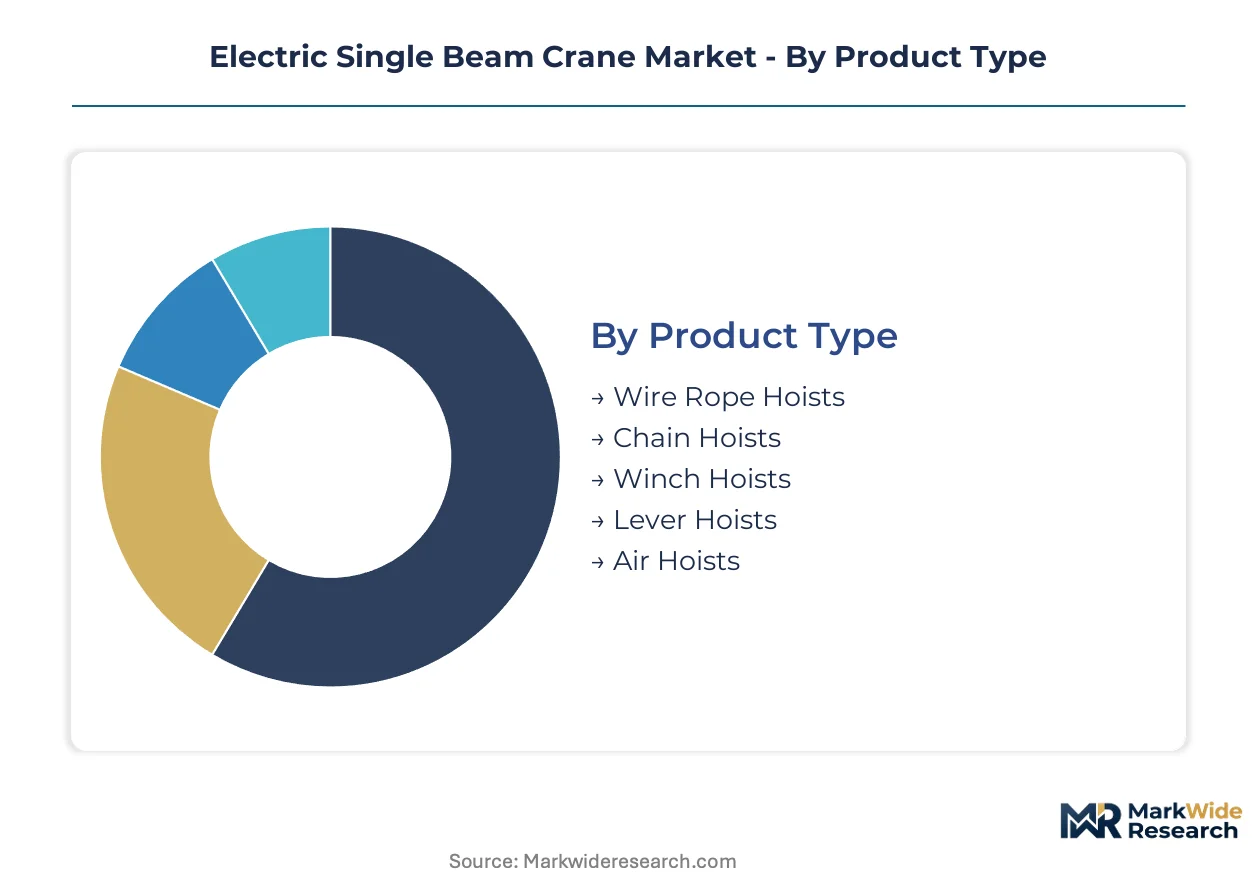
Electric single beam crane procurement patterns diverge sharply across lifting mechanisms, control interfaces, and facility types. Specification decisions cascade from duty cycle intensity, automation maturity, and regulatory exposure in target operating environments.
Product Type:
Cost tier determines hoist selection, with capital outlay and maintenance burden varying across mechanism designs.
- Wire Rope Hoists:Multi-layer drum systems with braided steel cables support continuous-duty cycles above 20 tons. Automotive stamping plants in Germany specify these for die-handling operations where lifting height exceeds 15 meters.
- Chain Hoists:Link-chain mechanisms with compact headroom suit intermittent-duty maintenance bays. India's state-level industrial corridors favor these for cost-constrained assembly workshops with lighter load profiles.
- Winch Hoists:Spooling drum configurations for horizontal pulling applications in shipyard rigging operations.
- Lever Hoists:Ratchet-pawl manual systems for confined-space installation work without electrical supply.
- Air Hoists:Pneumatic motor drives for explosion-risk environments in chemical processing facilities.
Wire rope systems command the established base. The steepest expansion runs through chain hoists in emerging manufacturing economies.
Technology:
Application context shapes control architecture, from human-operated pendant systems to fully automated sensor networks.
- Manual Controls:Direct mechanical linkages via pull chains or levers persist in legacy installations and budget-restricted facilities.
- Remote Controls:Infrared or radio-frequency handheld units enable operator positioning away from suspended loads. Japan's precision electronics manufacturers specify these for cleanroom component handling where personnel proximity risks contamination.
- Radio Controls:Frequency-hopping spread spectrum systems resist interference in steel-intensive environments. South Korea's shipbuilding clusters adopt these for outdoor yard operations with electromagnetic noise from welding equipment.
- Pendant Controls:Pushbutton stations on suspended cables remain dominant in standard-duty warehouse applications across China's Jiangsu province industrial belt.
- Automatic Sensors:Load-weighing, anti-sway, and collision-avoidance modules integrated with facility management systems. Germany's automotive OEMs deploy these for unmanned night-shift material flows.
Pendant controls retain volume leadership. Radio and automatic sensor configurations are climbing the fastest as safety regulations tighten.
Application:
Facility type dictates structural specifications, environmental protection ratings, and duty cycle classifications.
- Manufacturing Units:Heavy fabrication shops with Class A4-A5 duty cycles require reinforced girders and thermal protection. France's aerospace suppliers specify these for titanium machining centers.
- Construction Sites:Temporary installations with modular end trucks and rapid-assembly features. Brazil's infrastructure contractors favor these for precast concrete yard operations.
- Warehouses:High-bay storage retrieval with precision positioning for pallet racking systems. Netherlands distribution hubs integrate these with automated storage and retrieval system orchestration.
- Shipyards:Corrosion-resistant finishes and extended span capabilities for hull assembly bays.
- Metal Fabrication Plants:Spark-resistant components and enhanced duty ratings for plasma cutting environments.
Manufacturing units anchor current procurement volumes. Warehouse automation projects are expanding most quickly.
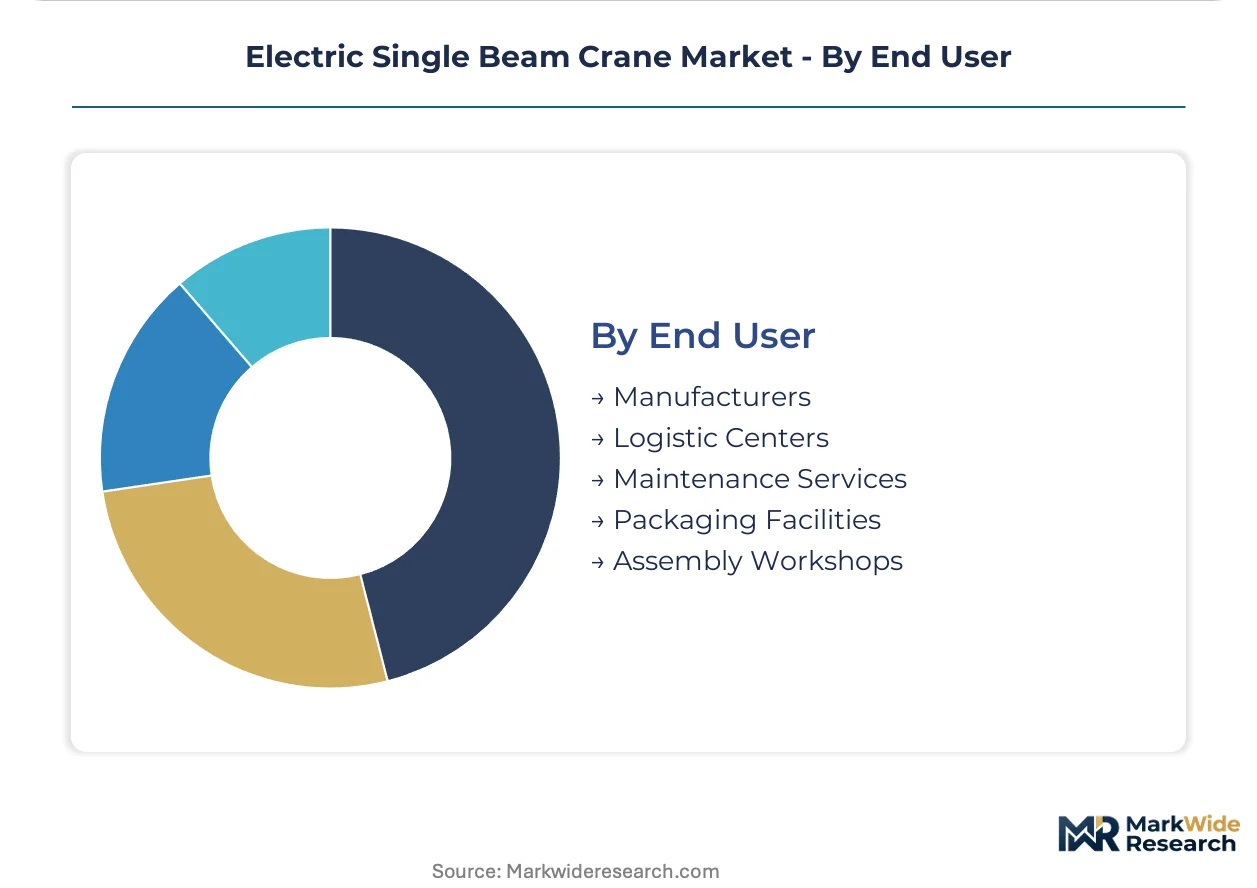
End User:
Customer type segments by operational model, from integrated production to third-party service provision.
- Manufacturers:Captive crane fleets with dedicated maintenance staff and OEM service contracts. Italy's machinery builders maintain these for in-house component movement.
- Logistic Centers:Third-party operators with utilization-maximization requirements and rapid turnaround specifications. Poland's e-commerce fulfillment hubs deploy these for container destuffing operations.
- Maintenance Services:Mobile repair contractors with portable lightweight systems for field equipment servicing.
- Packaging Facilities:Clean-environment specifications with food-grade lubricants and washdown-capable enclosures.
- Assembly Workshops:Low-headroom configurations for component marriage stations in automotive supplier parks.
Manufacturers represent the core installed base. Logistic centers are gaining share fastest as e-commerce infrastructure expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China deploys electric single beam cranes for high-throughput manufacturing automation, while Germany prioritizes precision-positioning systems for automotive die-handling and India favors cost-optimized chain hoists in emerging industrial corridors.
China
Automotive stamping plants and heavy machinery fabrication drive crane procurement in Jiangsu and Shanghai industrial clusters. SAMR's updated GB/T standards mandate overload protection and emergency braking systems, accelerating replacement cycles. Yangtze River Delta manufacturing hubs are retrofitting legacy pendant controls with radio-frequency systems for smart factory integration.
Germany
Automotive OEMs specify precision-positioning cranes for just-in-time component delivery and unmanned night-shift material flows. CE machinery directive compliance requires documented risk assessments, creating aftermarket inspection revenue streams. Stuttgart and Munich industrial zones lead VFD-equipped hoist retrofits for smooth acceleration profiles in die-handling operations.
United States
Warehouse automation and distribution center expansion pull demand toward intelligent load-handling systems with integrated safety sensors. OSHA mandates periodic inspection protocols that sustain aftermarket service demand. Chicago and Detroit manufacturing corridors concentrate procurement for heavy fabrication shops with Class A4-A5 duty cycle requirements.
India
State-level industrial corridors in Maharashtra and Gujarat favor cost-constrained chain hoists for lighter-load assembly workshops. BIS standards govern crane safety certification for domestic market access. Tamil Nadu automotive supplier parks are expanding crane fleets for component marriage stations in low-headroom configurations.
Japan
Precision electronics manufacturers specify remote controls for cleanroom component handling where personnel proximity risks contamination. METI industrial policy promotes factory automation adoption. Nagoya and Osaka industrial zones deploy radio-frequency systems with frequency-hopping spread spectrum to resist electromagnetic interference from welding equipment.
Electric Single Beam Crane Market Competitive Landscape
Capability concentration sits with European engineering specialists; scale advantage sits with Chinese fabrication houses. The market structures around a tiered supplier base where premium-positioning players compete on precision controls and integration services while volume manufacturers optimize for cost and delivery speed. Two strategic archetypes dominate: European-origin precision-systems providers and Asia-Pacific scale fabricators with domestic supply chain control. Competitive moves center on smart factory integration partnerships and geographic expansion through regional distribution networks.
Within the European precision-systems tier, Konecranes and Liebherr represent high-load engineering capability anchored in established industrial automation ecosystems. Among Asia-Pacific scale fabricators, XCMG exemplifies domestic market consolidation through cost-optimized fabrication for infrastructure projects. These three companies occupy distinct competitive positions: Konecranes and Liebherr sit within premium-tier specification markets, while XCMG anchors volume-driven procurement in emerging industrial corridors.
| Leading Market Players |
|---|
| Konecranes |
| Liebherr |
| Columbus McKinnon Corporation |
| ABUS Crane Systems |
| Terex Corporation |
| XCMG |
| SANY |
| Zoomlion Heavy Industry Science and Technology |
| Palfinger |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in China's Jiangsu province fabrication corridors is compressing crane builder margins and accelerating price-based competition among domestic suppliers serving cost-sensitive infrastructure projects.
Pricing Analysis
Long-term offtake contracts dominate procurement for automotive OEMs and heavy machinery builders, insulating tier-one suppliers from spot steel volatility while spot purchasing persists among India's state-level industrial contractors. Three-tier pricing structure across premium, standard, and economy levels separates CE-certified European systems with full automation integration from Chinese standard-duty configurations and unbranded regional fabrications. Price differentiation hinges on certification grade and after-sales service bundling. Pricing pressure stems from steel index volatility and concentrated VFD component sourcing. India's emerging workshop segment exhibits highest price sensitivity; Germany's automotive OEMs show lowest.
Supply Chain Analysis
Upstream structural steel feedstock draws from China, India, and Germany, with high-strength girder alloys concentrated among German and Japanese specialty mills. Critical electrical components—variable-frequency drives, overload protection modules, radio-frequency control systems—rest on single-source vulnerability from German and Japanese component houses. Supply chain risk centers on tariff exposure for European VFD imports into Asian assembly plants. Distribution runs through OEM-direct channels for premium-tier systems and independent equipment dealers for standard-economy configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Factory automation mandates from China's SAMR and Europe's CE machinery directive are compressing replacement cycles and reshaping competitive dynamics across the electric single beam crane market.
For Market Incumbents: Entrench position through backward integration into VFD and sensor module production to escape German-Japanese component house dependency. Lock in long-term steel supply contracts with Jiangsu mills to defend margin posture against spot price volatility. Prioritize smart factory integration partnerships with warehouse management system providers to resist substitution by gantry systems. For New Entrants and Emerging Players: Build out dedicated service capabilities in India's Tamil Nadu and Maharashtra corridors where independent maintenance providers are capturing inspection and repair revenue from legacy OEM relationships. Target chain hoist penetration in regional assembly workshops where cost constraints favor lighter-load mechanisms over wire rope alternatives. Pursue radio-control retrofit packages as the fastest go-to-market angle for smart factory integration demand. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across automated sensor and VFD-equipped crane configurations as software content displaces mechanical differentiation. Long-term viability favors suppliers with captive control system development and regional certification expertise. Acquisition target archetype: mid-tier fabricators with established CE marking documentation and underutilized service networks. Signal to watch: divergence between pendant control retrofit rates and greenfield automatic sensor deployments as automation maturity indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into VFD Production | Reduces dependency on German-Japanese component houses and stabilizes input costs. |
| Smart Factory Integration Partnership | Enables warehouse management system connectivity for unmanned load cycling. |
| CE Marking Documentation Investment | Creates aftermarket inspection revenue streams under Machinery Directive requirements. |
| Regional Service Network Expansion | Captures independent maintenance demand in China's Yangtze River Delta clusters. |
| Radio-Control Retrofit Packaging | Addresses legacy pendant control interoperability gaps in automation architectures. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads; and secondary validation through customs/trade data, SEC filings from listed crane builders, SAMR GB standard documentation, and EU Machinery Directive compliance databases. Bottom-up and top-down triangulation cross-checked segment-level estimates against aggregate market sizing.
Forecast inputs span product type segmentation across wire rope, chain, winch, lever, and air hoist configurations; technology tiers from manual through automatic sensor systems; and application contexts including manufacturing units, warehouses, and shipyards. CAGRs were derived from regression analysis of historical procurement patterns against industrial automation indices and regulatory compliance cycle timing. Industry-specific inputs include steel price indices and VFD component lead time variability.
Stress conditions across steel price volatility, component supply disruption, and regulatory timeline compression were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding automation adoption curves and certification enforcement intensity. Cross-checking against industrial crane import-export statistics and regional manufacturing capacity utilization data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Material Handling Equipment Market
Material Handling Equipment
Hydraulic Seals Market
Material Handling Equipment
Jaw Crushers Market
Material Handling Equipment
Can Racks Market
Material Handling Equipment
Compactor Market
Material Handling Equipment
US Forklift Market
Material Handling Equipment
Loader Crane Market
Material Handling Equipment
Global Loaders Market
Material Handling Equipment
Slag Handling Machine Market
Material Handling Equipment
Freight Elevators Market
Material Handling Equipment
Port Material Handling Equipment Vehicle Market
Material Handling Equipment
Cable Conduit Market
Material Handling Equipment
Dump Tubs Market
Material Handling Equipment
Vertical Platform Lift Market
Material Handling Equipment
Modular Conveyor System Market
Material Handling Equipment
Electric Tugger Market