
 Pipe Wipers Market | 2026-2036
Pipe Wipers Market Size, Share, and Industry Trends Forecast 2026-2036
Pipe Wipers Market Analytics
Buyer concentration among oilfield service companies is shifting toward integrated drilling contractors that bundle pipe wiper procurement with broader rig supply agreements. National Oilwell Varco leverages its rig equipment integration to anchor long-term wiper supply contracts across North American land drilling. Gardner Denver competes through aftermarket parts density and field service proximity to active basins. Baash-Ross specializes in custom elastomer formulations for high-pressure directional drilling applications.
Pipe wipers are annular sealing devices installed on drilling rigs to strip drilling fluid from the exterior of drill pipe during tripping operations, typically constructed from molded polyurethane or reinforced rubber compounds rated for specific pressure differentials and temperature ranges. Their primary purpose is to contain drilling mud within the wellbore, reduce fluid loss, and maintain pressure control integrity during connection and tripping sequences. Single-sided and double-sided product configurations dominate current volume, with polyurethane material grades capturing premium positioning due to superior abrasion resistance and extended cycle life in sour gas environments. Specialty and custom-made segments are gaining traction as extended-reach drilling and managed pressure drilling techniques proliferate in unconventional shale plays.
API Specification 7K governs operational testing and design validation for pipe wipers used in drilling and well servicing equipment, while OSHA 29 CFR 1910.1200 mandates hazard communication for chemical exposure in wiper manufacturing and replacement workflows. EPA regulations on volatile organic compound emissions from polyurethane curing processes are reshaping domestic production footprints and supplier qualification criteria. Stakeholders must monitor evolving API standards for hydrogen sulfide service ratings and assess dual-sourcing strategies as material compliance costs diverge across regional regulatory regimes.
Market Dynamics
Buyer consolidation among integrated drilling contractors is compressing supplier margins while elevating API certification requirements as non-negotiable entry criteria for pipe wiper procurement.
Growth Catalysts
- EPA Emissions Enforcement:Stricter volatile organic compound rules on polyurethane curing processes are accelerating domestic production upgrades and favoring compliant manufacturers in Texas and Louisiana.
- Managed Pressure Drilling Expansion:Extended-reach techniques in Permian Basin unconventional plays are generating demand for specialty elastomer formulations rated for higher pressure differentials.
- Offshore Middle East Development:Saudi Aramco and ADNOC drilling programs are concentrating procurement volumes around API-certified suppliers with regional stocking capabilities.
Market Restraints
- Polyurethane Feedstock Volatility:MDI and polyol price swings tied to petrochemical cycles compress wiper manufacturing margins unpredictably.
- API Certification Concentration:Testing and validation bottlenecks at licensed facilities create multi-month qualification delays for new market entrants.
- Metal Wiper Resurgence:Hardened steel stripping elements are reclaiming share in high-temperature geothermal drilling where elastomer degradation accelerates.
Strategic Opportunities
- Brazil Pre-Salt Expansion:Petrobras drilling campaigns in Santos Basin present untapped demand for sour-gas-rated polyurethane wipers with extended cycle life.
- Digital Inventory Integration:RFID-tagged wiper kits enabling predictive replacement scheduling are penetrating North American land rig fleets.
- EU Green Deal Procurement:REACH-compliant bio-based polyurethane formulations open positioning for suppliers meeting sustainability-linked tender requirements.
Industry Challenges
- Compound Formulation Expertise Gap:Shortage of chemists skilled in hydrogen sulfide service elastomer development extends R&D timelines for next-generation products.
- Legacy Rig Compatibility:Retrofitting modern double-sided wipers onto older BOP stacks requires custom adapter engineering that fragments production runs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pipe Wipers Market |
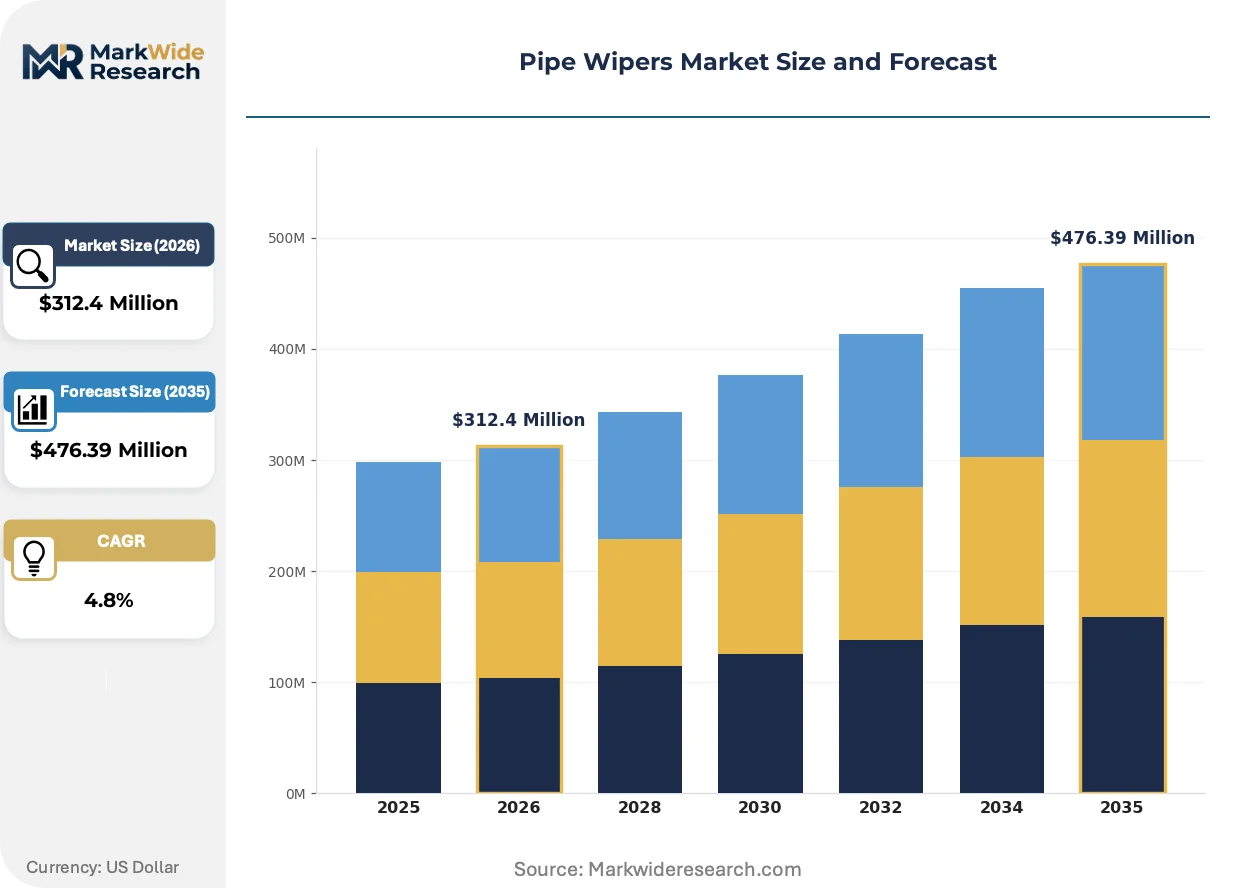
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $476.39 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Sided, Double-Sided, Specialty, Custom-Made Material: Polyurethane, Foam, Fabric, Rubber Application: Oil & Gas, Water Treatment, Construction, Chemical End User: Industrial, Commercial, Residential, Municipal |
| Companies Covered | Gardner Denver, Baash-Ross, National Oilwell Varco, Hole Products, Demco, Oil States Industries, Lewco, Continental, Givens International Drilling Supplies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pipe Wipers Market Evolving Landscape
Material science advances and regulatory compliance automation are restructuring how pipe wipers are specified, manufactured, and replaced across drilling operations.
Advanced polyurethane nanocomposites incorporating ceramic fillers are extending wiper service intervals in abrasive drilling environments. Directional drilling contractors in the Permian Basin are specifying these grades for extended-reach laterals where trip frequency compresses replacement cycles. The technology is decentralizing maintenance scheduling from fixed-interval to condition-based replacement protocols.
EPA enforcement of 40 CFR Part 63 on polyurethane curing emissions is forcing domestic manufacturers toward aqueous-based molding processes or capital-intensive thermal oxidizer installations. Smaller regional suppliers without absorption capacity are exiting the market. Texas and Oklahoma production facilities are most affected, with compliance costs diverging from Mexican and Canadian import alternatives.
Integrated drilling contractors are unbundling wiper procurement from bundled rig supply agreements and establishing direct supplier relationships for aftermarket volumes. Independent rental tool companies and field service networks are capturing replacement demand previously routed through OEM channels. This pattern is most visible in North American land drilling where contractor consolidation has concentrated buyer leverage.
Pipe Wipers Market Segmentation
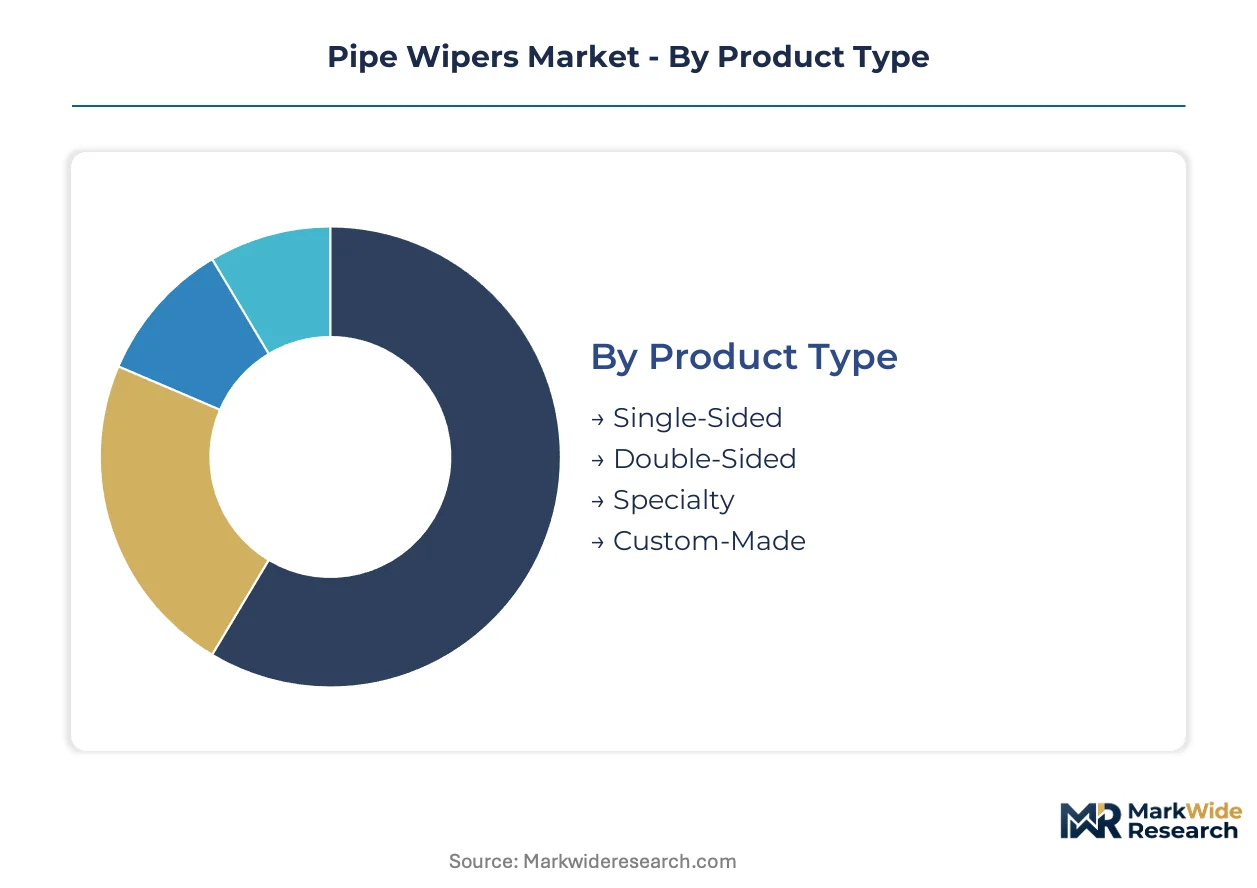
Pipe wiper procurement patterns diverge sharply across product configurations and material grades, with integrated drilling contractors consolidating specifications around API-certified tiers while specialty formulations capture premium positioning in unconventional drilling. Understanding these segment boundaries clarifies where supplier margins concentrate versus where volume commoditization pressures dominate.
Product Type:
Supply concentration clusters around standardized configurations that integrate cleanly with National Oilwell Varco and Gardner Denver rig packages, while custom engineering fragments production runs across smaller elastomer specialists.
- Single-Sided:Molded polyurethane or rubber elements designed for unidirectional stripping action on conventional vertical wells. Demand concentrates in Texas Permian Basin land operations where trip frequency remains moderate and cost-per-unit drives procurement decisions among independent drilling contractors.
- Double-Sided:Symmetrical sealing geometry enabling bidirectional fluid containment during connection sequences in directional drilling. Managed pressure drilling deployments in Middle Eastern offshore developments specify these configurations for pressure integrity assurance in extended-reach laterals.
- Specialty:Engineered profiles for high-temperature geothermal or sour gas service. Saudi Aramco pre-salt programs specify hydrogen sulfide-rated grades.
- Custom-Made:Bespoke elastomer formulations and adapter geometries for legacy BOP stack retrofits. Fragmented demand across aging North American rig fleets.
Single-sided configurations absorb the bulk of installed capacity; specialty grades are expanding most quickly as extended-reach techniques proliferate.
Material:
Cost tier stratification separates premium polyurethane grades from commodity alternatives, with EPA emissions compliance costs widening the gap between domestic and import sourcing.
- Polyurethane:Cast or injection-molded thermoset elastomers with superior abrasion resistance and tear strength. Sour gas ratings and extended cycle life position these grades in Permian Basin unconventional plays where trip costs dominate economics.
- Rubber:Natural or synthetic elastomer compounds offering lower unit cost for standard service conditions. Legacy rig fleets in Oklahoma and Kansas specify these for shallow vertical drilling with predictable replacement intervals.
- Foam:Lightweight cellular polyurethane structures for low-pressure water well applications. Municipal groundwater drilling in Texas Panhandle represents primary demand.
- Fabric:Reinforced textile-polymer laminates for temporary or rental tool applications. Independent rental companies stock these for short-duration workovers.
Polyurethane claims the steepest expansion trajectory on performance differentiation; rubber maintains volume dominance in replacement cycles.
Application:
Customer type segmentation separates capital-intensive exploration programs from maintenance-driven replacement demand, with procurement authority concentrating differently across each.
- Oil & Gas:Downhole drilling and well servicing operations requiring API 7K certification and pressure-rated sealing integrity. ADNOC offshore developments and Permian Basin land drilling anchor procurement volumes.
- Water Treatment:Municipal and industrial water well drilling with lower pressure specifications. Texas groundwater conservation districts specify standard-grade wipers for monitoring well installation.
- Construction:Foundation drilling and geotechnical applications with intermittent duty cycles. Urban infrastructure projects in Houston and Dallas drive replacement demand.
- Chemical:Specialty corrosion-resistant formulations for aggressive fluid environments. Limited niche demand from Texas Gulf Coast petrochemical maintenance.
Oil and gas absorbs the bulk of installed capacity; water treatment is gaining share fastest on municipal infrastructure spending.
End User:
Volume concentration among integrated drilling contractors compresses supplier margins at the industrial tier while fragmenting procurement across smaller commercial and municipal accounts.
- Industrial:Oilfield service companies, drilling contractors, and rental tool fleets with centralized procurement and API certification requirements. National Oilwell Varco supply agreements dominate this tier.
- Commercial:Independent water well contractors and geotechnical drilling operators with dispersed purchasing patterns. Oklahoma and Kansas regional distributors serve this segment.
- Residential:Limited demand from private water well installation in rural Texas and New Mexico. Low volume, high fragmentation.
- Municipal:Government water departments and groundwater conservation districts with formal bidding processes. Texas Commission on Environmental Quality compliance documentation shapes specifications.
Industrial end users command the bulk of supplier attention; municipal procurement is climbing fastest on infrastructure stimulus programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polyurethane feedstock supply from Texas Gulf Coast petrochemical complexes anchors North American pipe wiper manufacturing capacity. Domestic production clusters concentrate near Houston and Lake Charles to minimize MDI and polyol transport costs. Regional demand patterns diverge sharply between Permian Basin land drilling and offshore developments elsewhere.
United States
EPA enforcement of 40 CFR Part 63 emissions rules on polyurethane curing processes is accelerating production facility upgrades in Texas and Louisiana. OSHA 29 CFR 1910.1200 hazard communication mandates reshape workplace safety protocols at wiper manufacturing plants. Midland-Odessa drilling contractors in the Permian Basin specify API 7K-certified double-sided configurations for extended-reach laterals.
Saudi Arabia
Saudi Aramco offshore drilling programs in the Arabian Gulf generate concentrated procurement volumes for sour-gas-rated specialty wipers. The country's national oil company mandates API certification as non-negotiable supplier qualification criteria. Eastern Province industrial zones near Dammam host regional stocking facilities serving Red Sea and Gulf developments.
United Arab Emirates
ADNOC drilling campaigns in offshore Abu Dhabi fields drive demand for high-pressure elastomer formulations rated for managed pressure drilling. MOHAP industrial safety standards govern chemical exposure limits in wiper replacement workflows. Jebel Ali free zone logistics hubs enable rapid distribution to rigs operating across the Arabian Peninsula.
Brazil
Petrobras pre-salt exploration in the Santos Basin creates untapped demand for extended-cycle-life polyurethane grades. ANVISA chemical safety regulations apply to elastomer compound import documentation and handling procedures. Rio de Janeiro supply bases coordinate offshore logistics for deepwater drilling contractors.
Canada
Alberta oil sands thermal drilling operations specify wipers rated for high-temperature steam-assisted gravity drainage applications. Health Canada industrial chemical regulations govern polyurethane component safety data sheet requirements. Edmonton manufacturing facilities serve Western Canadian Sedimentary Basin operators with regionally adapted product lines.
Pipe Wipers Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialty elastomer formulations and digital inventory integration. The vendor base stratifies across three functional layers: integrated rig equipment suppliers with captive wiper production, independent elastomer specialists with formulation expertise, and regional fabricators serving replacement demand. Three archetypes dominate competitive positioning: API-certified volume suppliers anchoring drilling contractor agreements, custom formulation houses capturing premium unconventional applications, and aftermarket distributors exploiting procurement unbundling trends. Competitive moves concentrate on backward integration into polyurethane compounding and geographic expansion through regional stocking partnerships.
Within the integrated equipment tier, National Oilwell Varco anchors long-term supply agreements across North American land drilling. Gardner Denver exemplifies the aftermarket density archetype through field service proximity to active basins. Baash-Ross occupies the specialty formulation position with custom elastomer development for high-pressure directional drilling applications. These three companies represent distinct competitive vectors without implying specific strategic actions or market share claims.
| Leading Market Players |
|---|
| Gardner Denver |
| Baash-Ross |
| National Oilwell Varco |
| Hole Products |
| Demco |
| Oil States Industries |
| Lewco |
| Continental |
| Givens International Drilling Supplies |
| Others |
Value Network & Pricing Analysis
Integrated drilling contractors anchoring procurement in the Permian Basin and Middle Eastern offshore developments command contract-based long-term offtake agreements that compress spot-market pricing power for non-certified suppliers. EPA emissions compliance costs on polyurethane curing processes are widening cost differentials between domestic manufacturers and import alternatives, reshaping how buyers evaluate total landed cost against API certification premiums.
Pricing Analysis
Volume concentrates in standard-grade rubber and polyurethane configurations for land drilling replacement cycles, while margins accrue to specialty elastomer formulations rated for sour gas service and extended-reach applications. Price differentiation rests on API 7K certification tier and after-sales field service proximity, with certified suppliers capturing premium positioning in ADNOC and Saudi Aramco tenders. Cost compression in the standard tier is intensifying as buyer consolidation elevates volume leverage among integrated contractors. Independent water well contractors in Oklahoma and Kansas exhibit highest price sensitivity; offshore drilling contractors in the Arabian Gulf show lowest sensitivity due to pressure-control integrity requirements.
Supply Chain Analysis
Domestic-content preferences in Saudi Aramco and ADNOC procurement programs are reshaping regional stocking requirements and favoring suppliers with Eastern Province and Jebel Ali logistics footprints. Manufacturing concentrates in the United States, China, and Germany, with Texas Gulf Coast petrochemical complexes feeding MDI and polyol inputs to domestic molders. Raw material sourcing draws from Gulf Coast petrochemical infrastructure, German specialty chemical producers, and Chinese polyol manufacturers. Single-source vulnerability concentrates in hydrogen sulfide-rated elastomer formulations where formulation expertise gaps limit qualified suppliers. Distribution runs through rig equipment OEM channels, independent rental tool networks, and regional field service depots.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA emissions enforcement and API certification bottlenecks are accelerating exits among smaller regional manufacturers without compliance absorption capacity, consolidating viable supply around integrated equipment tiers and specialty formulation houses.
For Market Incumbents: Acquire polyurethane compounding capabilities or captive elastomer formulation assets to defend margin structure against feedstock volatility and certification-driven buyer consolidation. National Oilwell Varco and Gardner Denver supply agreements demonstrate how rig equipment integration anchors replacement volume; independents must secure API 7K certification investment and field service density in the Permian Basin to maintain relevance against this threat. Backward integration into MDI and polyol supply relationships offers additional cost control levers. For New Entrants and Emerging Players: Launch via digital inventory integration partnerships with independent rental tool companies capturing unbundled aftermarket demand from drilling contractor procurement shifts. Brazil pre-salt exploration presents the most penetrable geography, with Petrobras drilling campaigns generating untapped demand for extended-cycle-life polyurethane grades without entrenched incumbent relationships. Sour-gas-rated specialty formulations for high-pressure directional drilling offer the clearest white-space positioning, with RFID-tagged predictive replacement kits as the differentiated go-to-market angle. For Investors and Strategic Acquirers: The window for entry favors specialty elastomer formulators with hydrogen sulfide service ratings and regional stocking partnerships in the Middle East. Long-term viability centers on suppliers capable of spanning the certification-cost divergence between EPA-compliant domestic production and import alternatives. The signal to watch is ADNOC and Saudi Aramco procurement unbundling trends, which would accelerate aftermarket channel capture and elevate valuations for independent field service networks.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyurethane Compounding | Captive MDI and polyol supply secures margin protection against petrochemical cycle volatility. |
| API 7K Certification Investment | Non-negotiable entry credential for ADNOC and Saudi Aramco offshore drilling tenders. |
| Regional Stocking Partnership | Jebel Ali and Eastern Province logistics hubs enable rapid response to Arabian Peninsula rig demand. |
| Digital Inventory Integration | RFID-tagged wiper kits penetrate North American land fleets via predictive replacement scheduling. |
| Specialty Elastomer R&D Expansion | Hydrogen sulfide service ratings capture premium positioning in Permian Basin extended-reach drilling. |
Research Methodology
Document review covered SEC filings from oilfield service companies, API certification registries, and EPA enforcement records, complemented by interviews with procurement directors at integrated drilling contractors, plant managers at Texas and Louisiana polyurethane molding facilities, and aftermarket service heads at independent rental tool companies. Secondary validation drew from customs trade data on elastomer compound imports, OSHA workplace safety incident databases, and ADNOC tender documentation. Bottom-up rig count modeling and top-down oilfield equipment spending analysis provided cross-referencing discipline.
Historical rig activity patterns were cross-referenced against panel input from drilling contractor procurement leads to anchor demand assumptions across the projection horizon. Segmentation dimensions modeled include product configuration, material grade tier, application pressure rating, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted rig count forecasts and replacement cycle compression factors specific to extended-reach drilling techniques. Industry-specific inputs incorporated managed pressure drilling adoption curves and EPA compliance cost absorption capacity at domestic manufacturing facilities.
The model assumes a particular technology adoption path for aqueous-based polyurethane molding processes; alternative pathways involving thermal oxidizer installations or import substitution would alter the domestic production outlook and supplier qualification timelines. Forecasts reflect assumptions on API standards evolution for hydrogen sulfide service ratings and buyer consolidation trajectories among integrated contractors. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
East Africa Elevator and Escalator Market
Material Handling Equipment
Heavy Equipment Movers Market
Material Handling Equipment
Truck Loader Crane Market
Material Handling Equipment
Circular Stacker and Reclaimer Market
Material Handling Equipment
Elevator Ropes Market
Material Handling Equipment
Trash Chute Market
Material Handling Equipment
Shaft Shredder Market
Material Handling Equipment
Low Clearance Loaders Market
Material Handling Equipment
Asia-Pacific Forklift Truck Market
Material Handling Equipment
Robotic Palletizers and De-Palletizers Market
Material Handling Equipment
Hoist Controller Market
Material Handling Equipment
Industrial Wood Chipper Market
Material Handling Equipment
Clinching Machines Market
Material Handling Equipment
High-Pressure Die Casting Market
Material Handling Equipment
High Pressure Grinding Rollers Market
Material Handling Equipment
Pipe Clamp Market