
 Global Forklift Market | 2026-2036
Global Forklift Market Size, Share, and Industry Trends Forecast 2026-2036
Global Forklift Market Analysis
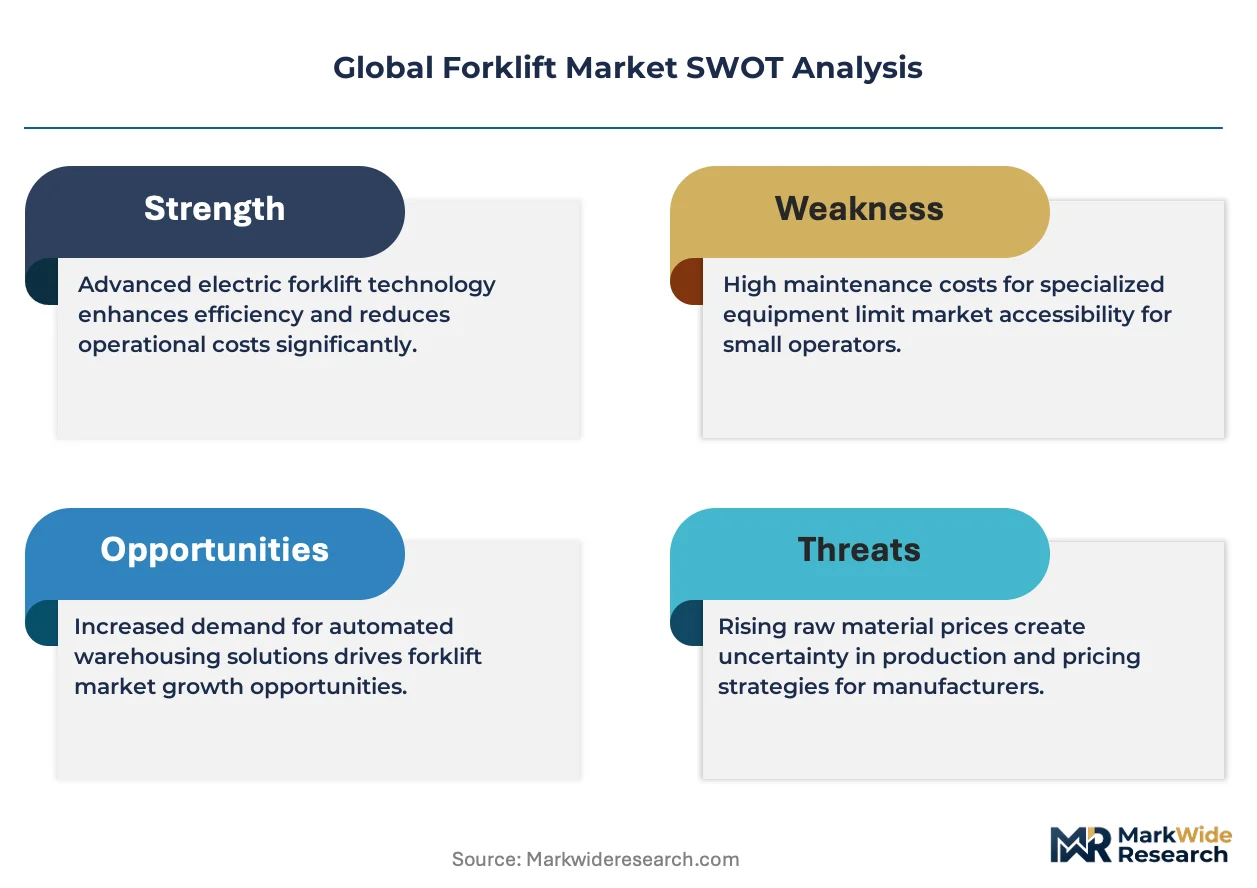
Modular battery-pack configurations is hardening as the dominant procurement architecture, letting buyers swap lithium-ion modules across multiple chassis brands rather than locking into single-vendor ecosystems. Toyota Industries Corporation leverages its captive cell production to control total cost of ownership for fleet operators. KION Group AG anchors its European installed base with integrated energy-service contracts that bundle hardware, charging infrastructure, and predictive maintenance. Hangcha Group Co., Ltd. competes on manufacturing scale from its Zhejiang production complex, shipping standardized electric counterbalance units at price points that pressure incumbents.
A forklift is a powered industrial truck with a mast-mounted lifting mechanism, typically rated by load capacity from under 3 tons to over 10 tons, designed to transport and stack palletized materials across warehouse floors and loading docks. Electric forklifts now dominate new orders in indoor applications where zero-emission operation aligns with indoor air-quality mandates, while internal combustion variants retain structural share in outdoor construction and lumber yards where refueling speed outweighs emission controls. Autonomous navigation technology is displacing conventional operator-driven models in high-throughput distribution centers, though lithium-ion powertrains represent the more immediate margin pool as battery costs fall and cycle life extends. Fuel cell variants occupy a narrow premium tier for multi-shift operations where opportunity charging disrupts workflow continuity.
The EPA enforces Tier 4 Final emission standards on diesel-powered forklifts sold in the United States, compressing the addressable market for internal combustion engines and redirecting R&D budgets toward electric platforms. EMA and national regulators across Germany, France, and Italy enforce CE marking and machinery safety directives that govern load-stability testing and operator protection structures, creating compliance barriers for non-European exporters. OSHA workplace standards in the United States and Japan's METI industrial safety guidelines further shape operator training requirements and fleet insurance costs. Stakeholders must monitor how battery recycling regulations and carbon-border adjustment mechanisms reshape total lifecycle economics across competing powertrain technologies.
Market Dynamics
Lithium-ion battery chemistry is converging with autonomous navigation systems to restructure fleet procurement economics, compressing total cost of ownership calculations and displacing long-established lead-acid maintenance routines across warehouse operations.
Growth Catalysts
- EU F-Gas Regulation phase-down:The mandated reduction in hydrofluorocarbon refrigerants accelerates electric forklift deployment in cold-chain logistics facilities across Germany, France, and Italy.
- E-commerce fulfillment center expansion:Third-party logistics providers in China and the United States are scaling automated storage and retrieval system integration with electric counterbalance fleets.
- Lithium-ion module standardization:Interchangeable battery-pack architectures reduce vendor lock-in and extend equipment lifecycle across multi-brand fleet operations.
Market Restraints
- Cathode material cost volatility:Lithium carbonate and nickel sulfate price swings compress margin predictability for electric forklift assemblers dependent on third-party cell supply.
- Charging infrastructure capex:High-voltage fast-charging station deployment requires electrical grid upgrades that delay fleet electrification timelines for mid-sized warehouse operators.
- Residual value uncertainty:Rapid battery technology iteration creates depreciation risk that tightens equipment financing terms from commercial lenders.
Strategic Opportunities
- India warehouse automation:The country's PLI scheme for manufacturing incentives attracts forklift assembly investment serving domestic e-commerce and automotive sector demand.
- Predictive maintenance bundling:Integrated service contracts combining telematics-enabled uptime guarantees with energy management reshape buyer-supplier relationships.
- Fuel cell niche penetration:Hydrogen-powered variants capture multi-shift operations in Japan and South Korea where continuous runtime requirements block opportunity charging models.
Industry Challenges
- Technician certification gaps:High-voltage battery service training lags fleet electrification pace, extending repair turnaround times and inflating labor costs.
- Legacy fleet integration:Mixed-voltage charging infrastructure and incompatible telematics protocols complicate phased replacement strategies for existing internal combustion units.
- Battery recycling compliance:Emerging extended producer responsibility frameworks in the European Union and California mandate end-of-life collection systems that increase administrative overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Forklift Market |
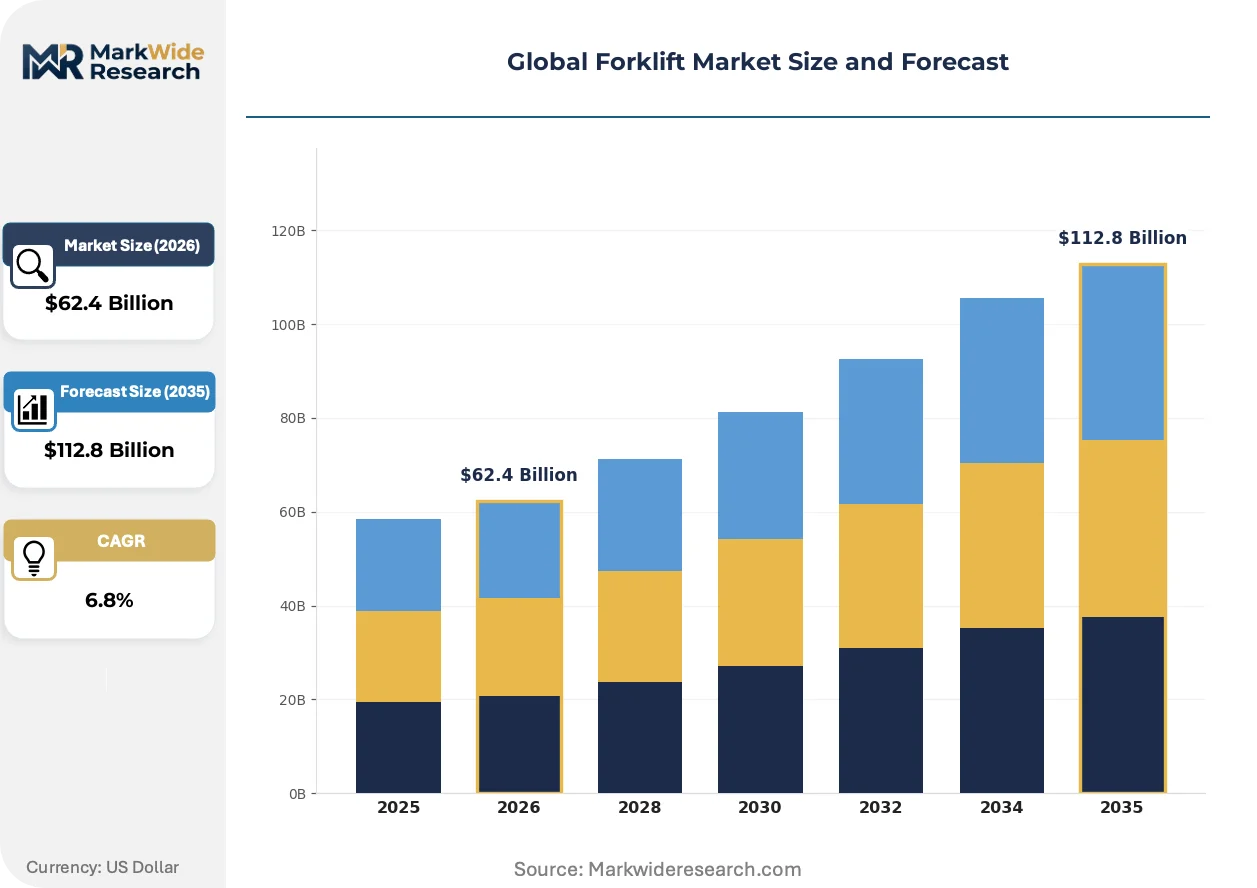
| Market Size in 2026 | $62.4 Billion |
| Market Size in 2035 | $112.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Forklifts, Internal Combustion Forklifts, Reach Trucks, Pallet Jacks End User: Warehousing, Manufacturing, Retail, Construction Technology: Autonomous, Lithium-ion, Fuel Cell, Hydraulic Load Capacity: Under 3 Tons, 3 to 5 Tons, 5 to 10 Tons, Over 10 Tons |
| Companies Covered | Toyota Industries Corporation, KION Group AG, Jungheinrich AG, Mitsubishi Logisnext Co., Ltd., Crown Equipment Corporation, Hyster-Yale Materials Handling, Inc., Hangcha Group Co., Ltd., Clark Material Handling Company, Komatsu Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Forklift Market Emerging Trajectories
Autonomous navigation hardware is penetrating forklift fleets faster than software standardization can consolidate, creating interoperability gaps that buyers must navigate through multi-vendor integration layers.
Computer vision-based obstacle detection is converging with fleet management platforms to enable real-time load-optimization decisions. Amazon and Walmart distribution centers in the United States are deploying these systems at scale. The technology is converging with warehouse execution software to compress labor cost per pallet moved.
The EPA Tier 4 Final emission standards enforce particulate matter and nitrogen oxide limits on diesel-powered forklifts sold in the United States. Equipment financing terms for internal combustion models have tightened as residual value projections deteriorate. Outdoor construction and lumber yard operators are accelerating pilot programs with fast-charge electric variants to retain equipment liquidity.
Fleet procurement through equipment-as-a-service contracts is displacing traditional capital expenditure models among mid-sized third-party logistics providers. Monthly per-truck pricing bundles maintenance, energy, and software subscriptions. This shift is most visible in Germany and the Netherlands where sustainability-linked financing instruments reduce effective borrowing costs for zero-emission fleet commitments.
Global Forklift Market Segmentation
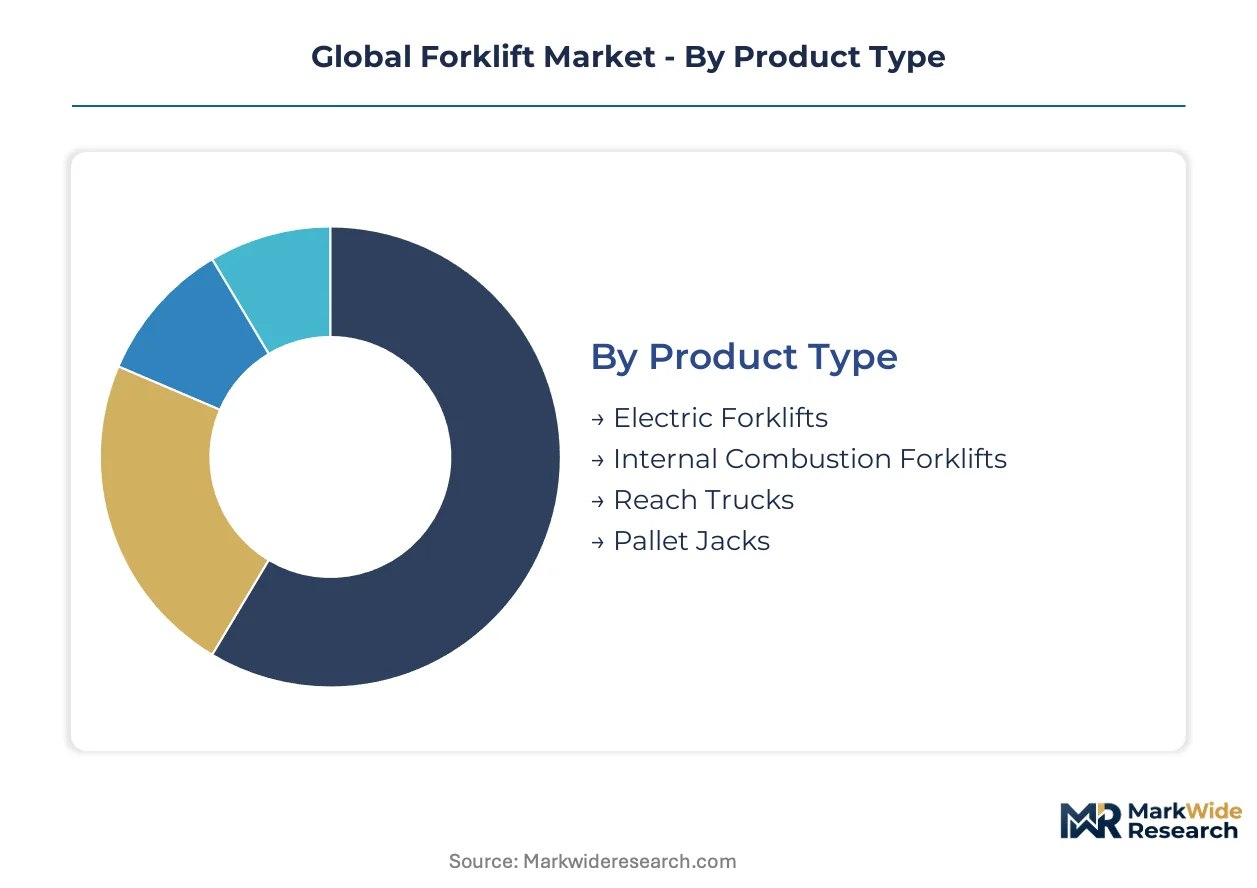
Forklift procurement decisions increasingly pivot on powertrain technology and automation readiness rather than load capacity alone. Buyers evaluate total cost of ownership across charging infrastructure, maintenance protocols, and software integration requirements.
Product Type:
Standardization dominates the low end with interchangeable lithium-ion modules, while premium tiers demand chassis-specific battery architectures and proprietary telematics stacks.
- Electric Forklifts:Battery-powered units with lithium-ion chemistry now deliver 8-10 hour continuous runtime matching lead-acid performance without watering maintenance. Warehouse operators in Germany and the Netherlands favor these for indoor air-quality compliance under EU F-Gas Regulation mandates.
- Internal Combustion Forklifts:Diesel and propane variants retain structural share where refueling speed outweighs emission controls, particularly in outdoor lumber yards and construction sites across the United States facing EPA Tier 4 Final compliance costs.
- Reach Trucks:Narrow-aisle designs with extending masts optimize vertical storage density in automated distribution centers.
- Pallet Jacks:Manual and electric walk-behind units serve last-mile delivery hubs with minimal capital outlay.
Leading the category by volume: Electric Forklifts. Growing fastest: Reach Trucks.
End User:
Margin concentration follows automation intensity, with e-commerce fulfillment centers commanding premium pricing for uptime-guaranteed service contracts.
- Warehousing:Third-party logistics providers operating multi-client facilities drive fleet standardization to reduce training costs and spare parts inventory. Amazon and Walmart distribution centers in the United States deploy autonomous navigation at scale, compressing labor cost per pallet moved.
- Manufacturing:Just-in-time assembly plants require forklifts integrated with warehouse execution software for real-time material flow coordination. Automotive sector demand in China and India concentrates orders for 3-5 ton electric counterbalance units.
- Retail:Big-box stores and grocery chains prioritize compact electric models for back-of-store inventory management.
- Construction:Rough-terrain diesel variants dominate outdoor material handling where electrical grid access remains limited.
Highest automation penetration: Warehousing. Steepest expansion trajectory: Manufacturing.
Technology:
Procurement patterns split between proven lithium-ion deployments and pilot autonomous programs, with fuel cells occupying a narrow premium tier for continuous-shift operations.
- Autonomous:Computer vision and LiDAR-enabled navigation systems eliminate operator labor from repetitive horizontal transport tasks. High-throughput distribution centers in China and the United States justify capital investment through 24-hour runtime without shift changes.
- Lithium-ion:Modular battery-pack configurations reduce vendor lock-in and enable opportunity charging during operator breaks, extending effective daily utilization.
- Fuel Cell:Hydrogen-powered variants capture multi-shift operations in Japan and South Korea where charging downtime disrupts workflow continuity.
- Hydraulic:Conventional lift mechanisms persist in cost-sensitive applications where precision positioning requirements remain modest.
Widest installed base: Lithium-ion. Gaining share fastest: Autonomous.
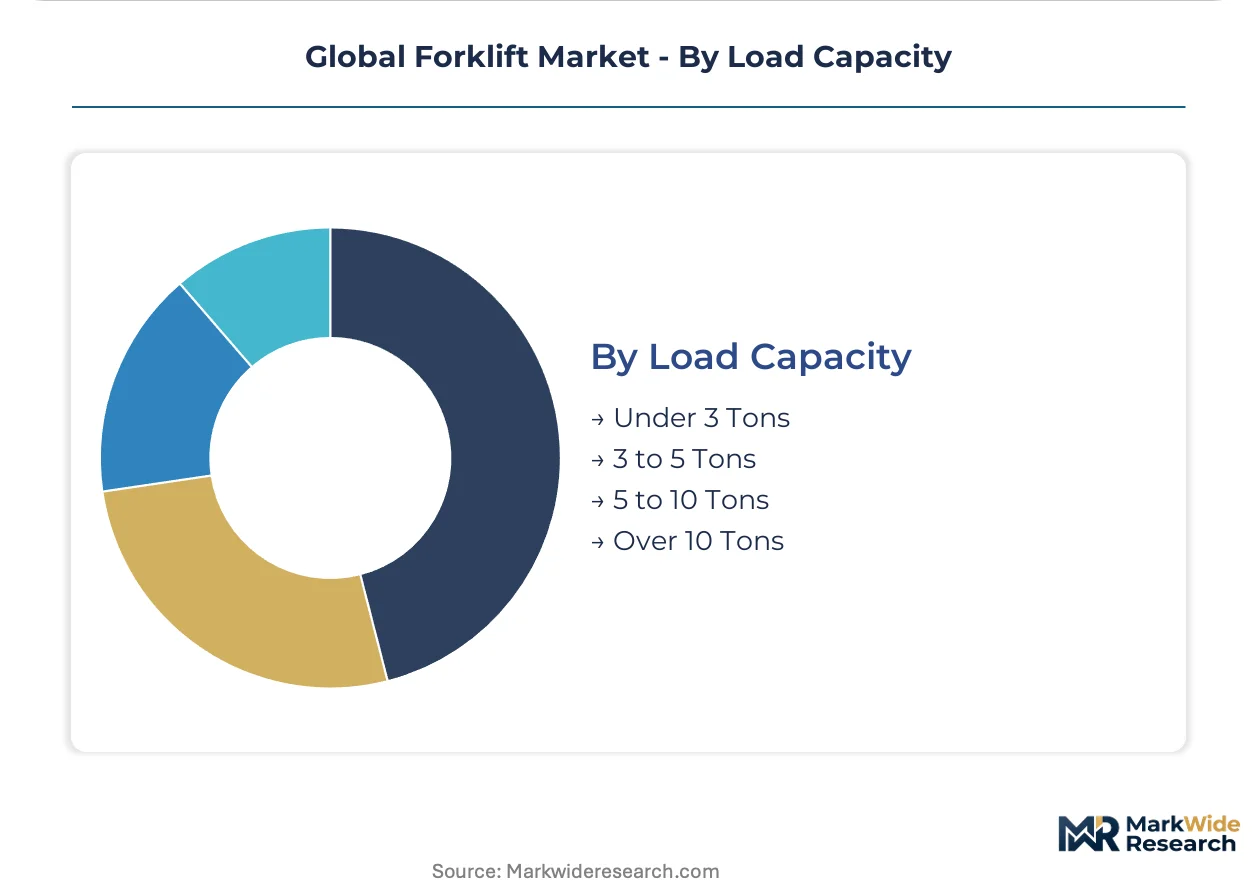
Load Capacity:
Equipment financing terms tighten above 10 tons as residual value uncertainty and specialized maintenance requirements concentrate buyer-seller relationships.
- Under 3 Tons:Compact electric models serve retail backrooms and light manufacturing with three-wheel configurations optimizing maneuverability in tight aisles. Standardized battery formats across multiple chassis brands reduce procurement risk for fleet operators.
- 3 to 5 Tons:Counterbalance designs dominate general warehouse applications with load centers optimized for standard pallet dimensions. Chinese domestic manufacturers compete aggressively on price from Zhejiang production complexes.
- 5 to 10 Tons:Heavy-duty electric and diesel variants serve steel, paper, and automotive component logistics with reinforced masts and stability systems.
- Over 10 Tons:Specialized container handlers and heavy-lift trucks command custom engineering for ports and heavy manufacturing with extended lead times.
Deepest volume concentration: 3 to 5 Tons. Narrowest competitive set: Over 10 Tons.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of global forklift volume while the United States and Germany absorb premium-priced automation-ready fleets. Consumption patterns diverge sharply between cost-driven emerging markets and regulatory-driven replacement cycles in mature economies.
United States
Amazon and Walmart distribution centers in California and Texas deploy autonomous navigation systems at scale, compressing labor cost per pallet moved. OSHA workplace standards and EPA Tier 4 Final emission rules tighten financing terms for internal combustion models. The Chicago-Midwest corridor anchors fleet electrification pilots among third-party logistics providers.
Germany
Automotive just-in-time assembly plants in Bavaria and Baden-Württemberg demand forklifts integrated with warehouse execution software for real-time material flow coordination. EMA machinery safety directives and EU F-Gas Regulation phase-down schedules accelerate lithium-ion replacement of lead-acid fleets. The Ruhr industrial cluster concentrates predictive maintenance service contract innovation.
China
Domestic e-commerce fulfillment centers in the Yangtze River Delta and Pearl River Delta scale automated storage and retrieval system integration with electric counterbalance fleets. MIIT industrial equipment standards and dual carbon goals pressure manufacturers toward zero-emission product lines. Hangcha Group and multinational assemblers compete aggressively from Zhejiang production complexes.
Japan
Multi-shift automotive component logistics in the Chubu/Nagoya region favor hydrogen fuel cell variants where charging downtime disrupts workflow continuity. METI industrial safety guidelines shape operator training requirements and fleet insurance costs. The Kanto/Tokyo corridor pilots telematics-enabled uptime guarantees with integrated energy-service contracts.
India
Automotive sector demand in Maharashtra and Tamil Nadu concentrates orders for 3-5 ton electric counterbalance units serving just-in-time assembly plants. The PLI scheme for manufacturing incentives attracts forklift assembly investment targeting domestic e-commerce growth. The Delhi-NCR logistics corridor expands cold-chain facilities under BIS equipment certification requirements.
Global Forklift Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across a market structure that rewards scale in standardized electric units and customization capability in autonomous systems. The vendor base stratifies into three tiers: captive cell producers controlling total cost of ownership, integrated service providers bundling hardware with energy contracts, and manufacturing-scale competitors shipping standardized units at price points that pressure incumbents. Consolidation pressures intensify as lithium-ion module standardization reduces switching costs and compresses margin pools on hardware sales.
Within the diversified industrial tier, Toyota Industries Corporation and Mitsubishi Logisnext Co., Ltd. represent Japanese conglomerates with captive supply chain advantages. KION Group AG anchors the European integrated-service archetype from its German base. Among manufacturing-scale specialists, Hangcha Group Co., Ltd. exemplifies the Zhejiang-based cost-competitive model. These three patterns—captive vertical control, bundled energy services, and scale-driven standardization—define the competitive vectors reshaping procurement relationships.
| Leading Market Players |
|---|
| Toyota Industries Corporation |
| KION Group AG |
| Jungheinrich AG |
| Mitsubishi Logisnext Co., Ltd. |
| Crown Equipment Corporation |
| Hyster-Yale Materials Handling, Inc. |
| Hangcha Group Co., Ltd. |
| Clark Material Handling Company |
| Komatsu Ltd. |
| Others |
Supply Flow & Price Mechanics
Third-party logistics providers operating multi-client fulfillment centers command pricing leverage through volume commitments that compress per-unit hardware margins while favoring bundled service contracts over transactional equipment sales.
Pricing Analysis
Cost-down pressure on mid-tier electric counterbalance units accelerates because Chinese manufacturers exploit standardized lithium-ion module formats to undercut proprietary battery architectures from European and Japanese incumbents. Three-tier pricing structure across premium automation-ready, standard electric, and economy internal combustion levels separates buyers by certification grade and after-sales bundling intensity. Fleet operators in Germany and the Netherlands exhibit lowest price sensitivity where sustainability-linked financing instruments reduce effective borrowing costs, while mid-sized warehouse operators in India face acute capital constraints that favor equipment-as-a-service subscriptions.
Supply Chain Analysis
Technician certification gaps for high-voltage battery service in Zhejiang and Jiangsu provinces constrain output expansion despite installed assembly capacity, forcing lead times outward for European and North American fleet orders. Manufacturing gravity centers on China, Germany, and Japan, with cell production drawing from lithium carbonate feedstock anchored in Australia and Chile. Single-source vulnerability in refined cathode materials from Chinese processing facilities elevates disruption risk. Distribution runs through OEM-direct channels for large fleet operators and specialized industrial equipment dealers serving fragmented mid-market buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Battery cell supply constraints prop pricing power for captive producers, creating a supply-constrained market structure that favors integrated manufacturers over pure-play assemblers through the projection horizon.
For Market Incumbents: Anchor European market position through predictive maintenance service contracts that bundle charging infrastructure with uptime guarantees, insulating against price erosion from Chinese scale competitors. Deepen backward integration into lithium-ion cell production to control total cost of ownership calculations that fleet operators use in procurement decisions. Prioritize certification investment for autonomous navigation software stacks to defend premium tier positioning.
For New Entrants and Emerging Players: The mid-market price-point gap between Toyota-KION premium service bundles and Hangcha economy hardware creates entry space for standardized electric counterbalance units with interchangeable battery architectures. Target India's PLI-subsidized manufacturing corridor for assembly investment serving domestic e-commerce fulfillment center expansion. Pursue white-label partnerships with established European dealers lacking captive battery supply.
For Investors and Strategic Acquirers: The window for entry favors vertically integrated cell producers with existing automotive battery scale seeking industrial equipment diversification. Acquisition candidates with captive lithium-ion chemistry expertise and established OEM relationships offer superior long-term viability against pure-play hardware assemblers facing margin compression. Monitor EU battery recycling regulation implementation as inflection signal for lifecycle cost advantage shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cell Production | Toyota Industries leverages captive supply to control fleet operator total cost of ownership calculations. |
| Predictive Maintenance Service Bundling | KION Group anchors European installed base with integrated energy contracts combining hardware and uptime guarantees. |
| Autonomous Navigation Software Investment | Computer vision and LiDAR penetration in Amazon and Walmart distribution centers compresses labor cost per pallet moved. |
| India Manufacturing Footprint Expansion | PLI scheme incentives attract assembly investment serving domestic automotive and e-commerce sector demand. |
| Standardized Battery Module Adoption | Interchangeable architectures reduce vendor lock-in and extend equipment lifecycle across multi-brand fleet operations. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs while primary interviews with fleet procurement managers, plant maintenance directors, OEM sales executives, and aftermarket service heads provided operational validation. Secondary sources incorporated MIIT industrial equipment standards, EPA Tier 4 Final enforcement records, EU F-Gas Regulation implementation timelines, and forklift shipment manifests from major Chinese export ports. Bottom-up unit demand modeling across powertrain technologies triangulated against top-down market value estimates from equipment financing disclosures.
Segmentation dimensions modeled at granular level include powertrain technology, automation readiness tier, load capacity band, and end-use vertical across the analysis window. CAGRs derived from regression analysis of historical fleet replacement cycles correlated with regulatory phase-down schedules and e-commerce fulfillment center buildout trajectories. Forecast inputs incorporated lithium carbonate price volatility indices and charging infrastructure deployment rates by national electrical grid capacity.
Inputs from OEM production schedules and third-party logistics fleet expansion plans were available through the study window; gaps in autonomous navigation software standardization timelines introduce uncertainty bands around automation adoption velocity. Forecasts reflect documented assumptions regarding EU battery recycling framework implementation and China dual carbon policy enforcement intensity. Material deviation in cathode material supply chain concentration or F-Gas Regulation phase-down pace warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Scraper Conveyor Market
Material Handling Equipment
Outdoor Power Equipment (OPE) Market
Material Handling Equipment
Global Tension Control Market
Material Handling Equipment
Pedestal Boom System Market
Material Handling Equipment
Industrial Static Equipment Market
Material Handling Equipment
ASEAN Conveyor System Market
Material Handling Equipment
Linear Slides Market
Material Handling Equipment
Compaction Machines Market
Material Handling Equipment
Europe Port Equipment Market
Material Handling Equipment
Conveying Equipment Market
Material Handling Equipment
Global Loaders Market
Material Handling Equipment
Wear Plates Market
Material Handling Equipment
Industrial Hoists Market
Material Handling Equipment
Industrial Counterweights Market
Material Handling Equipment
Hydraulic Hoist Market
Material Handling Equipment
Elevator Ropes Market