
 Cell Therapy Systems Market | 2026-2036
Cell Therapy Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Cell Therapy Systems Market Outlook
GMP-grade automation is rotating from optional to mandatory across commercial cell therapy manufacturing. Thermo Fisher Scientific leverages its end-to-end bioproduction portfolio to anchor large-scale vector and cell line supply. Danaher competes through its Beckman Coulter and Cytiva subsidiaries, dominating analytical and separation workflows for cell isolation and expansion.
Cell therapy systems comprise integrated instrumentation, consumables, and software platforms designed to isolate, expand, genetically modify, and cryopreserve living therapeutic cells under controlled conditions, typically requiring closed-system bioreactors with automated perfusion and real-time metabolite monitoring to maintain cell viability and phenotype consistency. These systems serve the industrial purpose of translating bench-scale protocols into reproducible, regulator-compliant manufacturing processes for patient-specific and off-the-shelf cellular medicines. Autologous cell workflows command premium equipment configurations due to patient-specific lot sizes and contamination sensitivity, while allogeneic platforms benefit from economies of scale that concentrate margin pools in bioreactor and media supply. Gene editing technology integration represents the fastest-growing capability segment as CRISPR-enabled therapies advance through clinical pipelines.
FDA's GMP guidance for cell and gene therapy manufacturing, EMA's ATMP framework, and ISO 14644 cleanroom classification standards collectively determine facility design, process validation requirements, and market access timelines for system vendors. Regulators now mandate process analytical technology and electronic batch records, forcing hardware suppliers to deepen software and data architecture competencies. Stakeholders must monitor how evolving FDA inspection protocols for vector production and EMA traceability requirements for starting materials reshape system specifications and service revenue models.
Market Dynamics
Closed-system automation is displacing open-manufacturing workflows as FDA and EMA mandates for contamination control harden, forcing equipment vendors to embed real-time process analytical technology and electronic batch records into bioreactor platforms.
Growth Catalysts
- FDA GMP guidance for cell and gene therapy:Mandates for process validation and electronic records are accelerating hardware replacement cycles among contract manufacturing organizations.
- CRISPR-enabled allogeneic pipelines:Gene editing integration into cell therapy workflows is expanding demand for automated electroporation and nucleofection systems.
- Academic-commercial research clusters:Concentrated investment in Boston, San Francisco, and Basel is creating localized demand spikes for modular cleanroom infrastructure.
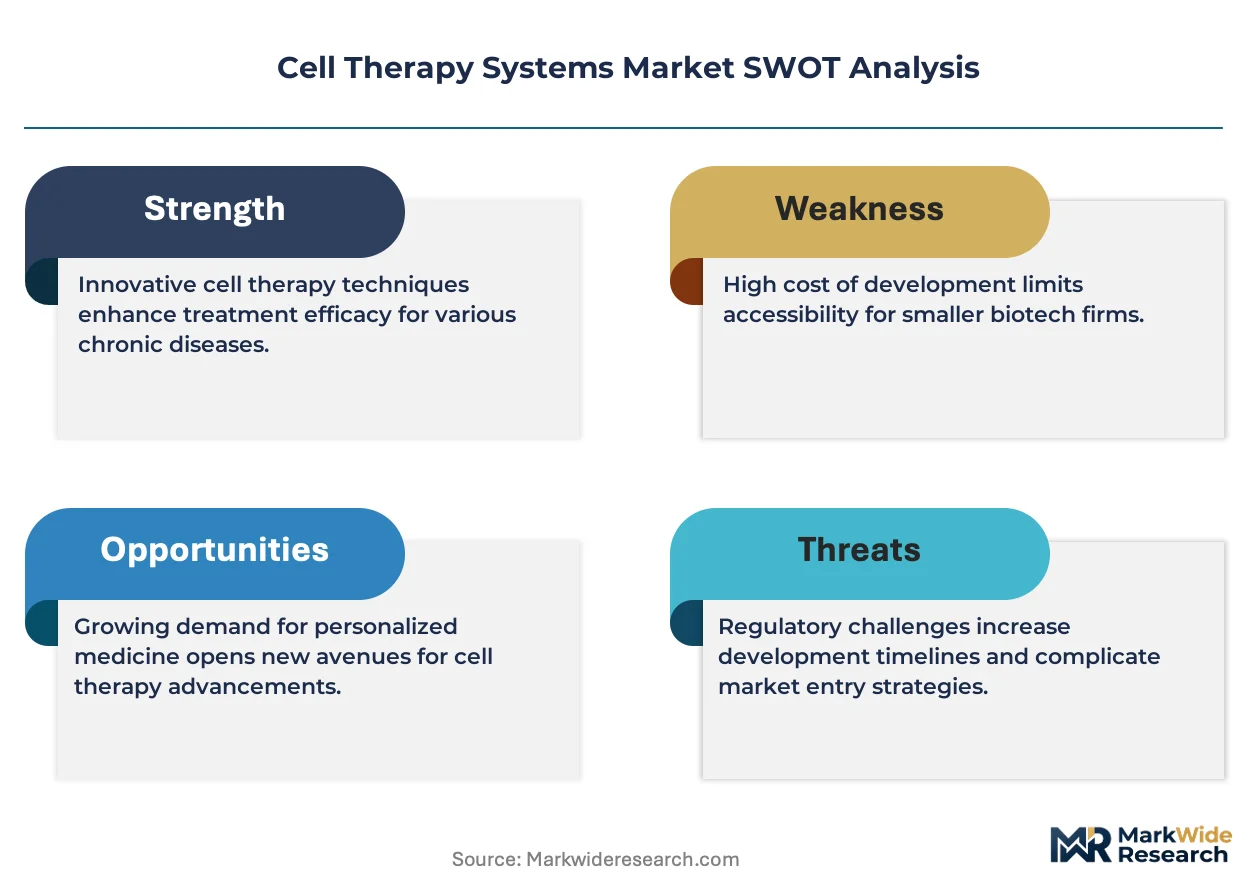
Market Restraints
- Plasmid DNA supply concentration:Limited qualified suppliers for GMP-grade viral vector starting materials creates single-source vulnerability in the United States and Europe.
- ISO 14644 cleanroom certification timelines:Facility qualification periods extending 18-24 months delay commercial manufacturing launches and equipment procurement decisions.
- Specialized talent scarcity:Shortage of cell therapy process engineers with GMP experience inflates labor costs and extends validation timelines.
Strategic Opportunities
- Point-of-care manufacturing:Decentralized production models for autologous therapies could unlock hospital-based cell processing in Germany and Japan.
- EMA ATMP framework incentives:Accelerated assessment pathways for regenerative medicines are attracting platform investments into European manufacturing infrastructure.
- AI-driven media optimization:Machine learning convergence with perfusion bioreactor control is enabling predictive cell expansion protocols.
Industry Challenges
- Legacy MES integration:Connecting new automated cell therapy platforms to existing manufacturing execution systems requires costly custom software bridges.
- Cross-functional skill gaps:Shortage of professionals combining cell biology expertise with automation engineering and regulatory affairs knowledge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cell Therapy Systems Market |
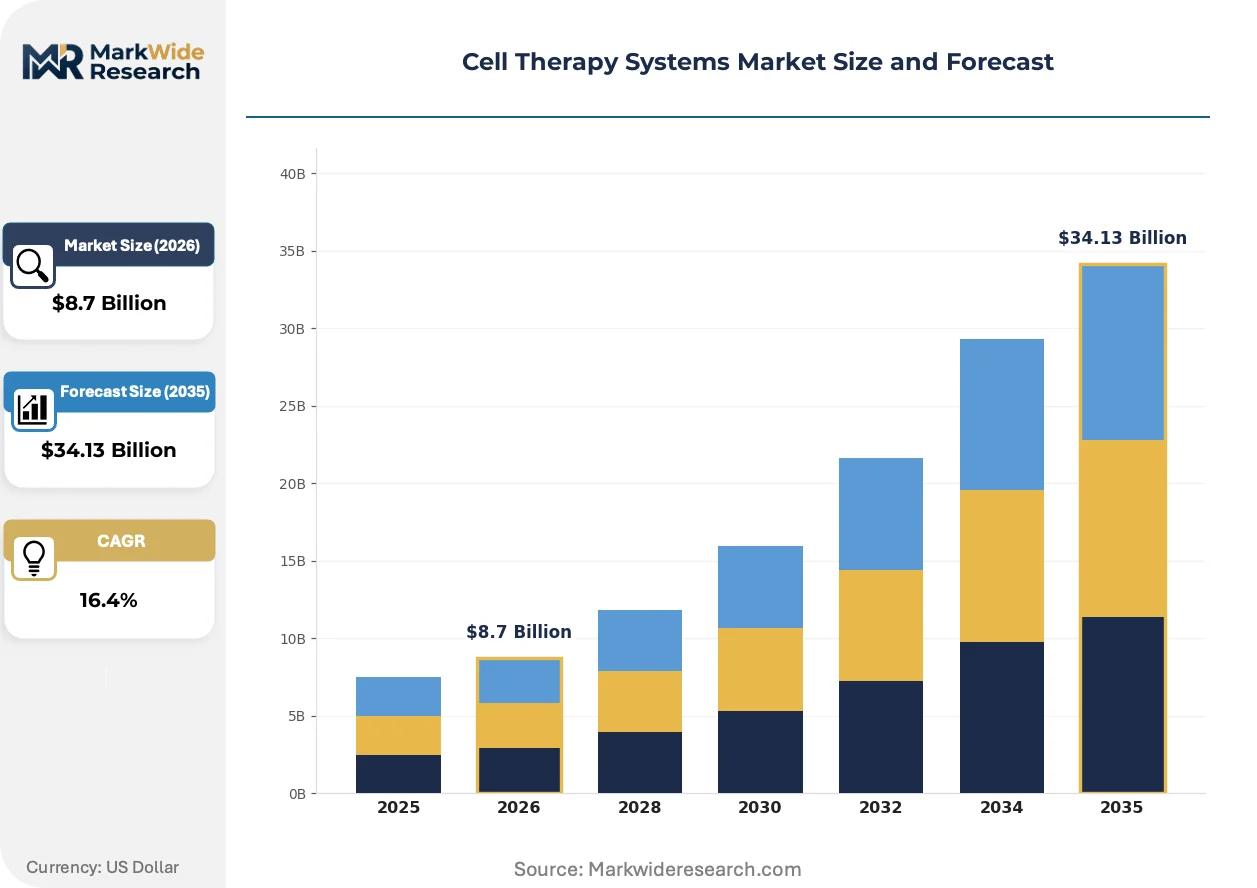
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Autologous Cells, Allogeneic Cells, Stem Cells, T Cells Application: Cancer Treatment, Chronic Diseases, Genetic Disorders, Autoimmune Conditions End User: Hospitals, Research Institutes, Biopharmaceutical Companies, Clinics Technology: Regenerative Medicine, Gene Editing, Cell Isolation, Cell Expansion |
| Companies Covered | Thermo Fisher Scientific, Danaher, Lonza, Sartorius AG, Miltenyi Biotec, Merck KGaA, Terumo Corporation, Fujifilm Cellular Dynamics, Novartis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cell Therapy Systems Market Strategic Shifts
Software-defined manufacturing is overtaking hardware-centric procurement as cell therapy producers prioritize data architecture and regulatory compliance over standalone equipment specifications.
Continuous bioprocessing is displacing fed-batch cell expansion in commercial manufacturing. Large-scale allogeneic producers are adopting perfusion bioreactors with automated cell retention. This shift is compressing facility footprints and reducing media consumption per therapeutic dose.
EMA's revised ATMP GMP Annex guidelines now mandate end-to-end electronic traceability for starting materials. The regulation forces equipment vendors to deepen software competencies and partner with data platform specialists. Contract manufacturers in the Netherlands and Spain are retrofitting legacy installations to meet the new requirements.
Service unbundling is fragmenting traditional equipment procurement. Biopharmaceutical buyers are separating hardware acquisition from validation, training, and maintenance contracts. This pattern is most pronounced among mid-tier cell therapy developers in the United States seeking operational flexibility.
Cell Therapy Systems Market Segmentation
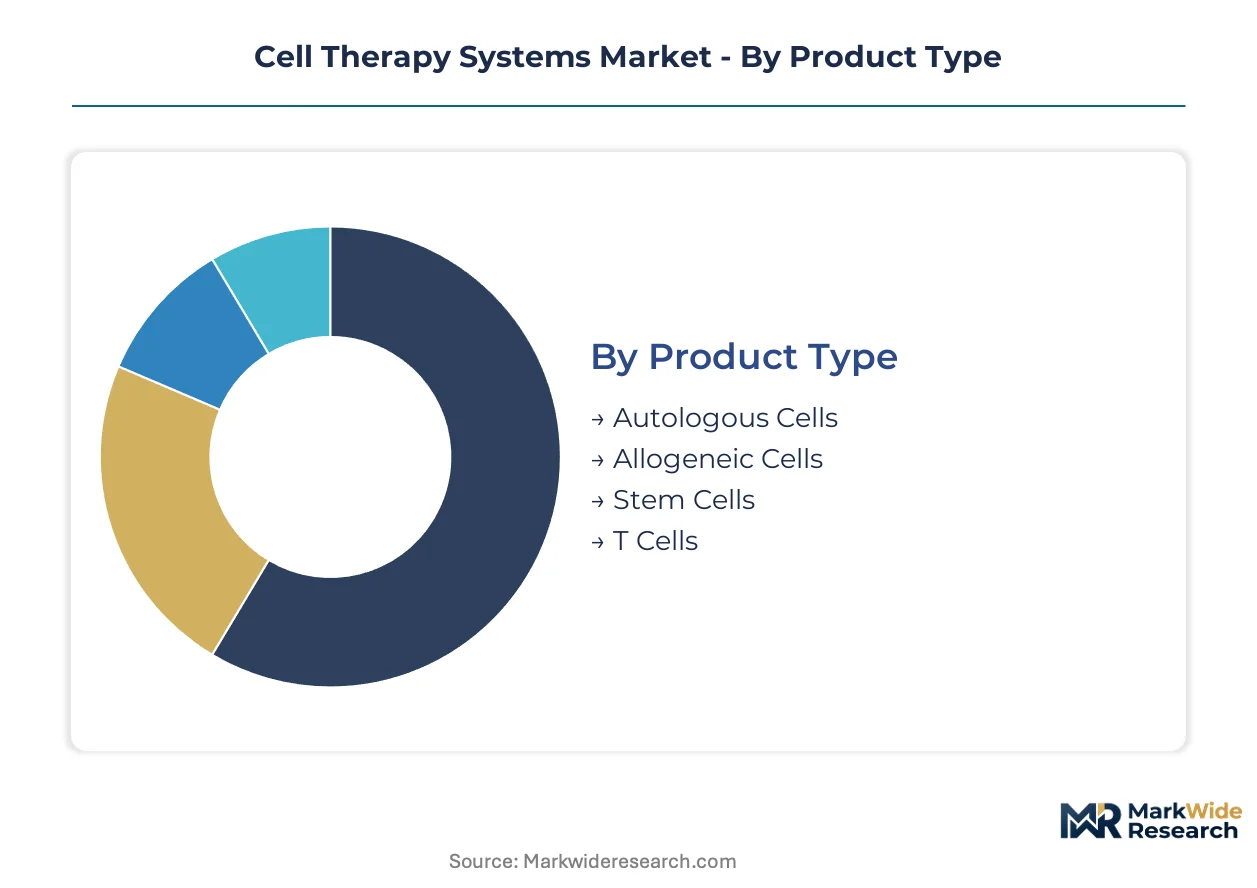
Cell therapy systems demand fragments across therapeutic modalities, each imposing distinct equipment specifications and regulatory pathways. Manufacturers configure platform architectures differently for patient-specific versus donor-derived workflows, while application settings determine automation intensity and cleanroom classification requirements.
Product Type:
Autologous systems dominate domestic manufacturing footprints in the United States and Germany, while allogeneic platforms scale through centralized export-oriented facilities in Switzerland and Singapore.
- Autologous Cells:Closed-system bioreactors with single-use consumables dominate this segment, engineered for lot sizes of one and contamination-sensitive patient-specific processing. Demand concentrates in Boston and San Francisco academic-commercial clusters, driven by FDA-mandated electronic batch records for CAR-T manufacturing.
- Allogeneic Cells:Perfusion bioreactors with automated cell retention enable economies of scale for donor-derived therapies. Manufacturing gravity centers on Basel and Leiden export hubs, constrained by EMA traceability requirements for starting materials.
- Stem Cells:Specialized expansion platforms for pluripotent and adult stem lineages.
- T Cells:Electroporation-integrated systems for genetic modification of lymphocyte populations.
Autologous cells hold the largest share; momentum sits with allogeneic cells as CRISPR-enabled pipelines advance.
Application:
Cancer treatment commands premium equipment configurations, while chronic disease applications prioritize cost-efficient modular platforms.
- Cancer Treatment:CAR-T and TCR-T manufacturing drives demand for cryopreservation-integrated workflows with real-time metabolite monitoring. Leukemia and lymphoma indications anchor procurement in Memorial Sloan Kettering and MD Anderson networks, where FDA inspection protocols for vector production shape validation timelines.
- Chronic Diseases:Diabetes and cardiovascular applications favor scalable allogeneic platforms with reduced per-dose manufacturing costs. European centers in Barcelona and Milan pilot decentralized production models under EMA ATMP accelerated assessment pathways.
- Genetic Disorders:Rare disease indications requiring ultra-low volume precision manufacturing.
- Autoimmune Conditions:Lupus and multiple sclerosis therapies driving novel regulatory submission strategies.
Cancer treatment absorbs the majority of current capacity; autoimmune conditions are climbing the fastest as pipeline diversity expands.
End User:
Biopharmaceutical companies concentrate procurement in high-automation tiers, while research institutes fragment across entry-level and mid-range configurations.
- Biopharmaceutical Companies:Integrated manufacturing suites with MES connectivity and process analytical technology for commercial-scale production. Gilead, Bristol Myers Squibb, and Novartis anchor demand through captive manufacturing and CMO partnerships, with FDA GMP guidance for cell and gene therapy forcing hardware replacement cycles.
- Research Institutes:Modular benchtop systems with flexible protocol adaptation for preclinical development. MIT, Stanford, and ETH Zurich drive localized demand spikes, constrained by ISO 14644 cleanroom certification timelines extending validation periods.
- Hospitals:Point-of-care processing units for autologous therapy preparation.
- Clinics:Compact isolation and expansion systems for specialized treatment centers.
Biopharmaceutical companies dominate revenue; hospitals represent the steepest expansion trajectory as decentralized manufacturing models mature.
Technology:
Gene editing integration commands the highest equipment margins, while cell isolation competes on throughput and reproducibility specifications.
- Gene Editing:Automated electroporation and nucleofection systems for CRISPR-Cas9 and base editing workflows. Intellia, Editas, and CRISPR Therapeutics pipeline progress drives platform investment, with EMA's revised ATMP GMP Annex mandating end-to-end electronic traceability.
- Cell Expansion:Perfusion bioreactors with AI-driven media optimization for predictive growth protocols. Continuous bioprocessing adoption at Lonza and Catalent facilities compresses facility footprints and reduces media consumption per therapeutic dose.
- Regenerative Medicine:Tissue engineering scaffolds and bioreactor systems for organ repair applications.
- Cell Isolation:Magnetic-activated and fluorescence-activated cell sorting platforms for population purification.
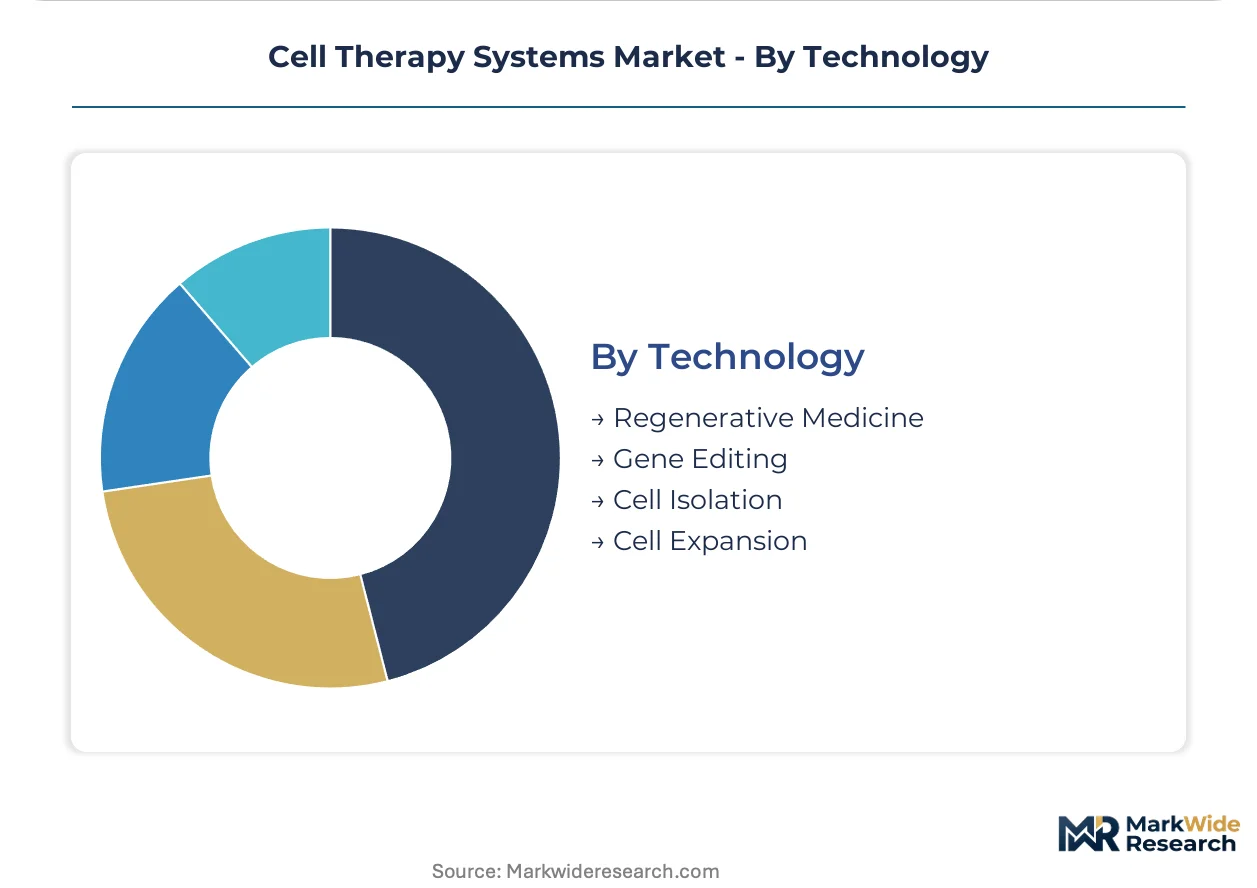
Cell expansion captures the largest installed base; gene editing is gaining share fastest as clinical pipelines mature toward regulatory submission.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cell therapy systems manufacturing clusters in the United States, Germany, Switzerland, and Singapore concentrate capacity for commercial-scale production. FDA and EMA regulatory convergence on closed-system automation is reshaping facility investment patterns across these jurisdictions. Each geography presents distinct infrastructure maturity and compliance pathway characteristics.
United States
FDA-mandated electronic batch records and process analytical technology requirements are accelerating hardware replacement cycles among contract manufacturers. The 21st Century Cures Act framework expedites regenerative medicine advanced therapy designations. Boston and San Francisco academic-commercial clusters anchor demand for modular cleanroom infrastructure serving CAR-T manufacturing.
Germany
Point-of-care manufacturing pilots for autologous therapies are unlocking hospital-based cell processing in Munich and Heidelberg networks. The country's national pharmaceutical regulator enforces ISO 14644 cleanroom certification timelines extending 18-24 months for facility qualification. Baden-Württemberg export hubs concentrate perfusion bioreactor deployment for allogeneic platform scale-up.
Switzerland
Swissmedic oversight of ATMP manufacturing aligns with EMA traceability mandates for starting materials. Basel anchors centralized export-oriented facilities for donor-derived therapy production. The cantonal system supports rapid facility permitting relative to neighboring jurisdictions, attracting platform investments from multinational biopharmaceutical sponsors.
Singapore
Biomedical Sciences Initiative funding is expanding regional manufacturing capacity for Asia-Pacific market access. The Health Sciences Authority harmonizes GMP inspection protocols with FDA and EMA standards. Tuas Biomedical Park clusters vector production and cell line supply capabilities serving export markets.
United Kingdom
Medicines and Healthcare products Regulatory Agency post-Brexit alignment with EMA ATMP frameworks maintains market access continuity. London and Oxford-Cambridge arc research institutes fragment procurement across benchtop and mid-range system configurations. MHRA accelerated access pathways for regenerative medicines are attracting modular cleanroom infrastructure deployment.
Cell Therapy Systems Market Competitive Environment
Concentration sits with diversified life science conglomerates controlling end-to-end bioproduction portfolios. The competitive structure tiers between integrated platform vendors, specialized cell therapy equipment providers, and contract manufacturers backward-integrating into proprietary systems. Two dominant competitive moves are reshaping positioning: strategic partnerships between hardware suppliers and gene editing technology licensors, and capacity expansion into Asian manufacturing hubs to capture regional demand growth.
Among diversified conglomerates, Thermo Fisher Scientific and Danaher occupy positions anchoring large-scale supply chains for vector and analytical workflows. Lonza exemplifies the contract manufacturer archetype that has developed captive platform capabilities through vertical integration into automated cell expansion systems. These three entities represent distinct strategic postures—portfolio breadth, analytical dominance, and manufacturing scale—rather than direct substitution.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Danaher |
| Lonza |
| Sartorius AG |
| Miltenyi Biotec |
| Merck KGaA |
| Terumo Corporation |
| Fujifilm Cellular Dynamics |
| Novartis |
| Others |
Value Chain & Pricing Dynamics
Long-term capacity reservation contracts with GMP-grade plasmid DNA suppliers lock in both supply access and price visibility for cell therapy manufacturers navigating FDA and EMA contamination control mandates. These arrangements concentrate pricing power among qualified viral vector starting material providers in the United States and Europe.
Pricing Analysis
FDA GMP guidance for cell and gene therapy dictates the pricing tier structure across equipment procurement, separating premium closed-system automation platforms from standard benchtop configurations. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 14644 cleanroom certification grade, with FDA-validated systems commanding substantial premiums over research-use equivalents. Cost compression in mid-range bioreactor tiers is intensifying because contract manufacturing organizations consolidate vendor relationships. Academic research institutes exhibit the highest price sensitivity, while commercial-stage biopharmaceutical companies prioritize regulatory compliance over procurement cost.
Supply Chain Analysis
The United States and Germany anchor GMP-grade plasmid DNA and viral vector production, while Switzerland and Singapore concentrate perfusion bioreactor manufacturing for export-oriented allogeneic platforms. Cell therapy systems draw from specialized single-use consumables, automated control modules, and cryopreservation media formulations. Single-source vulnerability in qualified plasmid suppliers creates structural risk for manufacturers dependent on United States-based starting material networks. Distribution runs through direct vendor relationships with biopharmaceutical companies and contract manufacturing organizations, bypassing traditional distribution intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cell therapy systems are approaching a platform-economics inflection where software-defined manufacturing architectures and MES interoperability determine competitive viability. The convergence of electronic batch records with real-time process analytical technology is reshaping vendor consolidation patterns.
For Market Incumbents: Shield installed base relationships through captive supply agreements with GMP-grade plasmid DNA producers, mitigating single-source vulnerability threatening manufacturing continuity. Deepen software competencies in electronic batch records and process analytical technology to defend against specialized automation entrants. Priority investment in MES integration capabilities addresses the legacy system connectivity challenge fragmenting procurement decisions. For New Entrants and Emerging Players: Lead with point-of-care manufacturing platforms for autologous cell processing in German and Japanese hospital networks, where decentralized production models remain underpenetrated. Target chronic disease applications favoring cost-efficient modular configurations over cancer treatment premium equipment. Go-to-market positioning through service unbundling—separating hardware acquisition from validation and training contracts—captures mid-tier developer demand for operational flexibility. For Investors and Strategic Acquirers: Capital is best deployed toward gene editing technology licensors with automated electroporation platform integration, capturing the fastest-growing capability segment as CRISPR pipelines advance. Long-term viability across the analysis window rests on software architecture depth rather than standalone hardware specifications. The signal to watch is EMA ATMP GMP Annex enforcement patterns for electronic traceability mandates, which will accelerate consolidation among vendors lacking data platform competencies.| Strategic Initiative | Industry Significance |
|---|---|
| Closed-System Automation Platform Launch | FDA GMP guidance for cell and gene therapy mandates contamination control compliance across commercial manufacturing. |
| Gene Editing Technology Licensing Agreement | CRISPR Therapeutics and Intellia pipeline progress expands demand for automated electroporation and nucleofection systems. |
| MES Integration Partnership | Electronic batch records requirements force hardware suppliers to deepen software architecture competencies for regulatory compliance. |
| Point-of-Care Manufacturing Pilot | Decentralized autologous production models unlock hospital-based cell processing in Munich and Heidelberg networks. |
| Plasmid DNA Supply Agreement | Limited qualified suppliers for GMP-grade viral vector starting materials creates single-source vulnerability in United States and Europe. |
Study Parameters
A spread of perspectives from cell therapy process engineers, regulatory affairs leads at contract manufacturing organizations, biopharmaceutical manufacturing executives, and hospital procurement managers converged on the working assumptions underpinning demand forecasts. Primary fieldwork combined structured interviews with secondary validation against FDA 483 inspection observations, EMA ATMP assessment reports, ClinicalTrials.gov pipeline tracking, and ISO 14644 facility certification databases. Bottom-up equipment procurement modeling triangulated against top-down biopharmaceutical manufacturing capacity expansion disclosures.
Segmentation dimensions modeled span autologous versus allogeneic cell workflows, cancer treatment versus chronic disease applications, and gene editing versus cell expansion technology platforms across the analysis window. CAGRs derived from installed base growth rates, replacement cycle acceleration from regulatory mandate compliance, and pipeline progression through clinical stages. Forecast inputs incorporated EMA ATMP GMP Annex enforcement timelines and FDA inspection protocol evolution for vector production facilities.
The analysis sits within stated boundaries; outcomes outside sustained FDA and EMA regulatory convergence on closed-system automation would require recalibration of equipment replacement cycle assumptions. Forecasts reflect documented assumptions regarding CRISPR pipeline advancement, plasmid DNA supply expansion, and specialized talent availability. Recalibration cycles align with material shifts in GMP guidance publication, ATMP framework revisions, and gene editing clinical trial readouts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
EMEA Cancer Biological Therapy Market
Cell & Gene Therapy
Rheumatoid Arthritis Stem Cell Therapy Market
Cell & Gene Therapy
Cell Therapy Manufacturing Market
Cell & Gene Therapy
Nucleic Acid and Gene Therapies in Neuromuscular Disorders Market
Cell & Gene Therapy
Global Dendritic Cell Cancer Vaccines Market
Cell & Gene Therapy
Global T-Cell Lymphoma Market
Cell & Gene Therapy
Cancer Stem Cells Market
Cell & Gene Therapy
Middle East and Africa Stem Cell Therapy Market
Cell & Gene Therapy
Leukapheresis Products Market
Cell & Gene Therapy
Asia-Pacific Stem Cell Therapy Market
Cell & Gene Therapy
Leukemia Therapeutics Market
Cell & Gene Therapy
Europe Cell and Gene Therapy Thawing Equipment Market
Cell & Gene Therapy
Cell and Gene Supply Chain Services Market
Cell & Gene Therapy
RNAI Technology Market
Cell & Gene Therapy
Cell and Gene Therapy Contract Development and Manufacturing Organization Market
Cell & Gene Therapy
B Cell Maturation Antigen Targeted Therapy Market