
 Global Viral Vector Vaccines Market | 2026-2036
Global Viral Vector Vaccines Market Size, Share, and Industry Trends Forecast 2026-2036
Global Viral Vector Vaccines Market Foresight
Plasmid DNA is pivoting toward synthetic alternatives as manufacturers seek to reduce batch-to-batch variability and raw material costs. Thermo Fisher Scientific Inc leverages its end-to-end platform to anchor North American supply chains for clinical-grade vectors. Lonza sustains European dominance through specialized fill-finish capabilities at its Visp site. Charles River Laboratories differentiates with integrated testing services that compress release timelines for gene therapy sponsors.
Viral vector vaccines deploy recombinant viruses—typically adenovirus, lentivirus, or poxvirus backbones—as delivery vehicles to introduce pathogen-specific antigens or therapeutic genes into host cells, with titers routinely exceeding 10^10 viral particles per milliliter for clinical batches. Adenovirus platforms occupy the largest share of infectious disease applications due to established COVID-19 manufacturing infrastructure now being repurposed for seasonal influenza and RSV candidates. Oncology applications represent the fastest-expanding segment as lentivirus vectors enable personalized CAR-T manufacturing workflows. Biopharmaceutical companies command the dominant end-user position, though contract research organizations are capturing growing vector production volumes as sponsors outsource capital-intensive manufacturing.
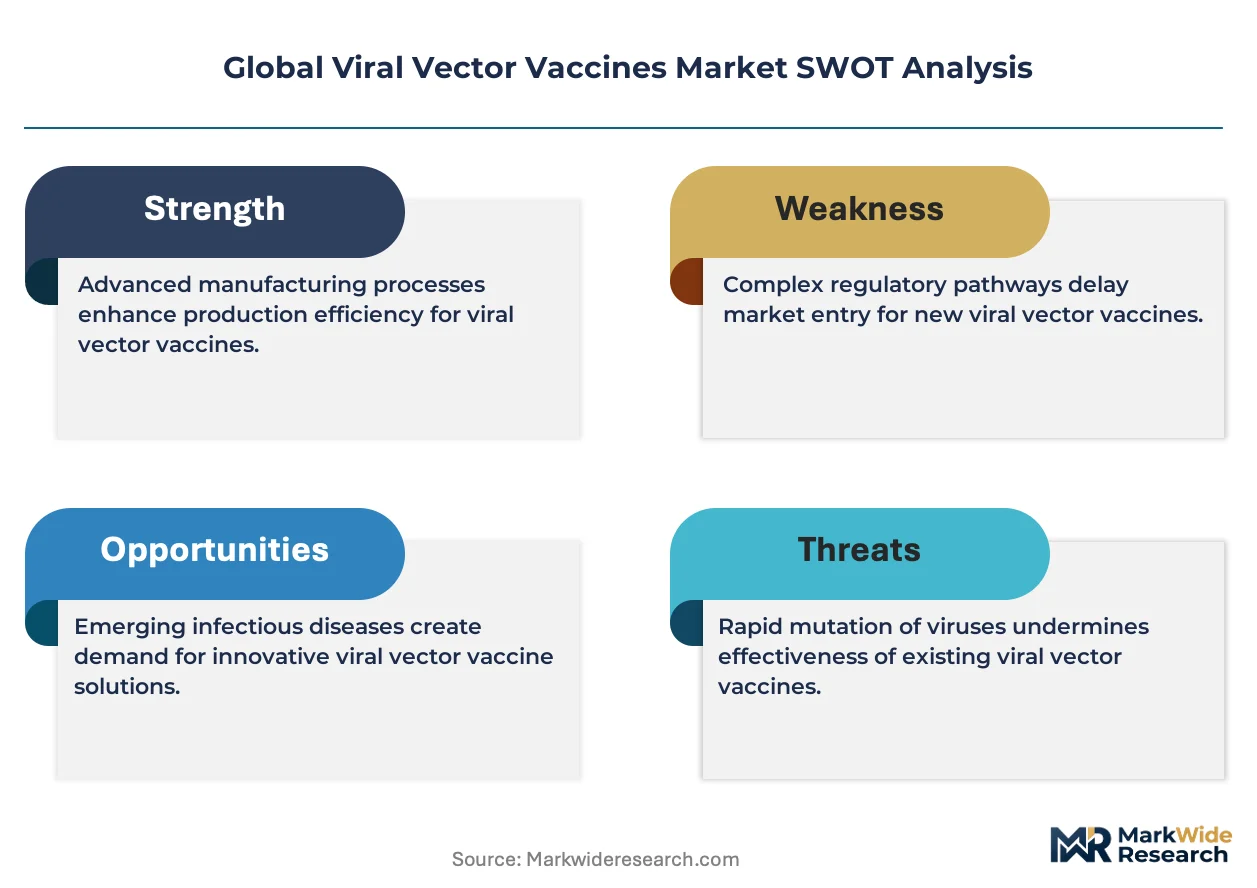
The FDA's Chemistry, Manufacturing, and Controls guidance and EMA's Good Manufacturing Practice Annex 2 revisions are tightening potency assay requirements and facility contamination controls, directly elevating compliance costs for new market entrants. China's NMPA has aligned its gene therapy technical guidelines with ICH standards, accelerating multinational trial submissions but demanding localized stability data. Stakeholders must monitor how evolving biosafety containment classifications from WHO and national regulators reshape facility investment thresholds across manufacturing networks.
Market Dynamics
Manufacturing capacity scarcity for clinical-grade viral vectors is compressing development timelines and elevating contract manufacturing premiums across the value chain. Sponsors now compete for limited GMP suite access at multi-product facilities in the United States, Germany, and Switzerland.
Growth Catalysts
- FDA Accelerated Approval:The pathway compresses Phase II-to-approval timelines for breakthrough gene therapies, pulling forward revenue recognition for vector manufacturers. Oncology sponsors file rolling submissions for CAR-T assets.
- Adenovirus Platform Repurposing:COVID-19 manufacturing infrastructure now supports seasonal influenza and RSV candidates. Biopharmaceutical companies redeploy idle bioreactor capacity without greenfield investment.
- China NMPA Alignment:Technical guidelines harmonized with ICH standards enable multinational sponsors to submit single global dossiers. Localized stability data requirements still apply.
Market Restraints
- Plasmid DNA Supply Concentration:Synthetic DNA alternatives remain limited to pilot-scale batches. Manufacturers depend on a narrow supplier base for GMP-grade starting material.
- EMA Annex 2 Compliance:Revised GMP requirements for potency assays and viral clearance validation extend facility qualification timelines by twelve to eighteen months.
- AAV Manufacturing Yield Ceiling:Transient transfection methods plateau at ten to the fourteenth vector genomes per liter, constraining dose economics for high-dose indications.
Strategic Opportunities
- India CDMO Expansion:Contract development capabilities remain underdeveloped for gene therapy vectors. Domestic biopharmaceutical sponsors seek localized clinical-grade supply.
- Lentivirus Oncology Workflows:Personalized CAR-T manufacturing demands patient-specific vector batches. Automated closed-system bioreactors enable distributed production models.
- Japan PMDA Regenerative Medicine Framework:Conditional approval pathways for gene therapies reduce Phase III requirements. Early commercialization accelerates vector demand from Japanese sponsors.
Industry Challenges
- Vector Analytics Talent Scarcity:Potency assay development requires rare combinations of virology and bioanalytical expertise. CDMOs compete for limited PhD-level scientists.
- Multi-Product Facility Cross-Contamination:Shared GMP suites demand rigorous changeover protocols. Regulatory inspections focus on viral clearance validation between campaigns.
- Release Timeline Compression:Integrated testing services must deliver certificates of analysis within seventy-two hours. QC bottlenecks delay patient dosing schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Viral Vector Vaccines Market |
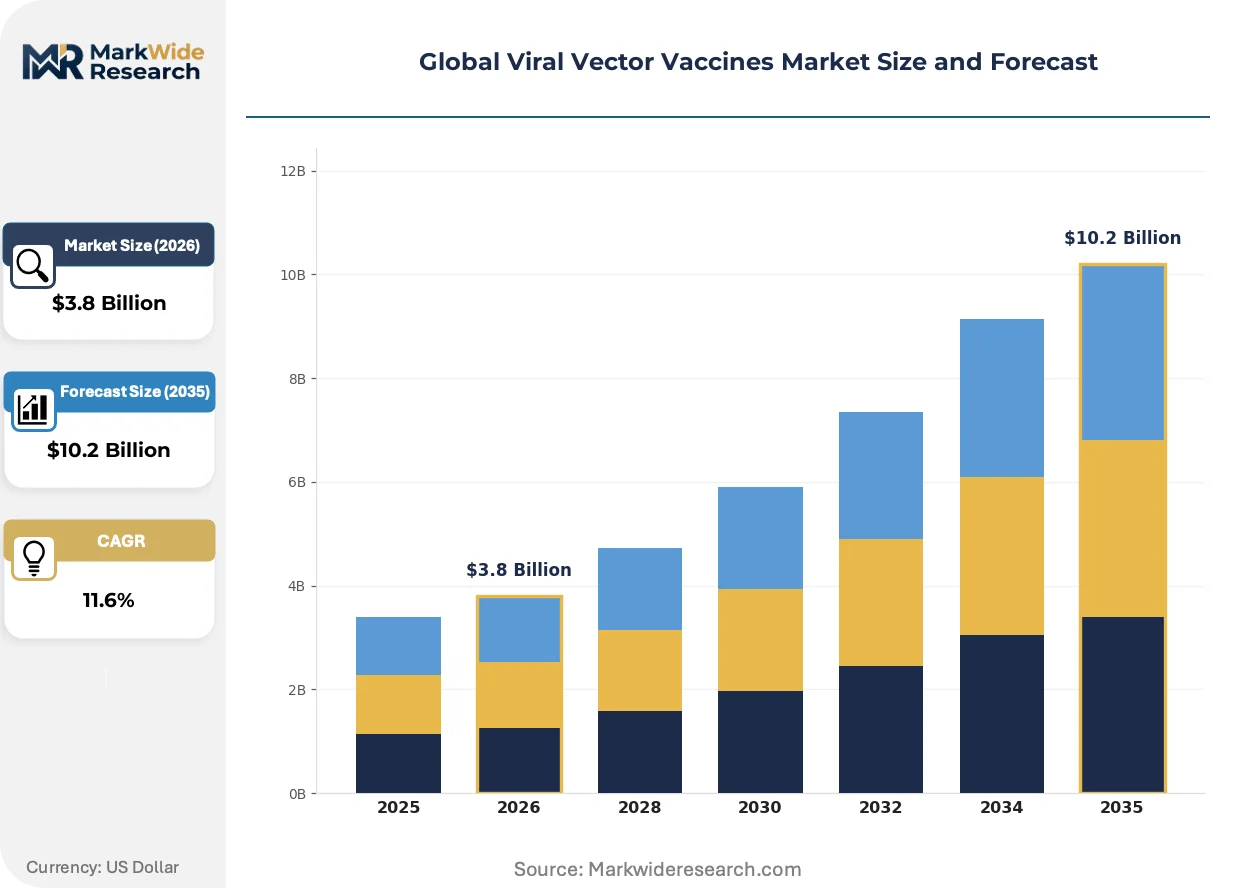
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.2 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vaccine Type: Adenovirus, Lentivirus, Poxvirus, Alphavirus, Herpesvirus Application: Infectious Disease, Oncology, Genetic Disorders, Autoimmune Conditions, Allergy Immunotherapy End User: Research Institutes, Biopharmaceutical Companies, Contract Research Organizations, Public Health Agencies, Academic Laboratories Deployment Model: Inactivated Vaccines, Live Attenuated, Subunit Vaccines, DNA Vaccines, mRNA Vaccines |
| Companies Covered | Merck KGaA, Charles River Laboratories, Thermo Fisher Scientific Inc, Oxford Biomedica, Fujifilm Diosynth Biotechnologies, Lonza, Sanofi, REGENXBIO Inc., Aldevron, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Viral Vector Vaccines Market Shifts & Advancements
Continuous processing architectures and closed-system automation are displacing batch-based manufacturing paradigms in viral vector production. These shifts reduce facility footprint requirements while tightening process control.
Closed-system single-use bioreactors are automating upstream vector production by eliminating open manipulations that risk adventitious agent contamination. Biopharmaceutical sponsors adopt these platforms for Phase III campaigns to secure regulatory favor. The technology is automating facility design decisions, compressing capital deployment timelines from thirty-six to eighteen months for greenfield sites.
EMA's Good Manufacturing Practice Annex 2 revisions mandate enhanced viral clearance validation and environmental monitoring for multi-product vector facilities. The regulation elevates compliance costs for new market entrants while favoring established CDMOs with dedicated suites. Oncology-focused sponsors in Germany and Switzerland accelerate facility segregation investments to preempt inspection findings.
Vector procurement is consolidating toward long-term exclusive supply agreements with tier-one CDMOs. Mid-cap gene therapy sponsors abandon transactional spot purchasing to secure capacity commitments. This behavioral shift concentrates most visible in the United States, where sponsor pipelines for rare disease indications outstrip available GMP manufacturing slots by three-to-one ratios.
Global Viral Vector Vaccines Market Segmentation
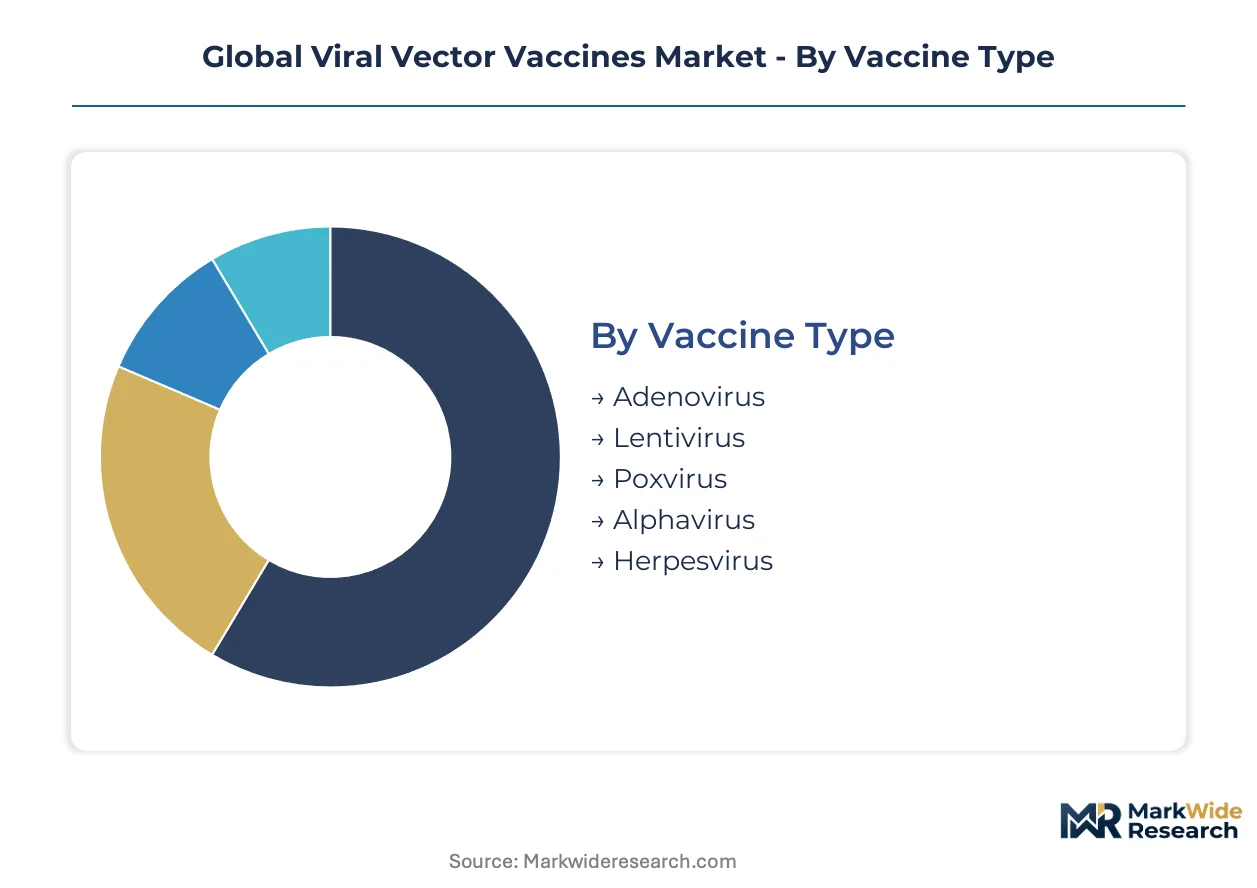
Viral vector vaccines segment across multiple technical and commercial dimensions that determine manufacturing scale, regulatory pathway, and pricing power. Platform selection and end-user procurement patterns create distinct competitive arenas with divergent margin profiles.
Vaccine Type:
Platform upgrade cycles favor adenovirus infrastructure repurposing, while emerging modalities force greenfield investment decisions.
- Adenovirus:Recombinant adenoviral vectors deliver transgenes with high transduction efficiency across dividing and non-dividing cells. Demand concentrates in the United States and China where COVID-19 manufacturing networks now pivot to seasonal influenza and RSV candidates. Established GMP suites at multi-product facilities command premium contract manufacturing rates.
- Lentivirus:Integrating RNA genomes enable stable transgene expression in hematopoietic cells, forming the backbone of CAR-T manufacturing workflows. Germany and Switzerland host the dominant lentivirus CDMO capacity as oncology sponsors seek dedicated suite access for patient-specific vector batches. Automated closed-system bioreactors are displacing legacy open-platform production.
- Poxvirus:Large DNA cargo capacity accommodates multi-antigen vaccines with established safety profiles in human populations.
- Alphavirus:Self-amplifying RNA platforms reduce required dose volumes through intracellular replication machinery.
- Herpesvirus:Neuronal tropism enables gene delivery to central nervous system targets with persistent episomal maintenance.
Adenovirus sits at the top of the volume ranking, with lentivirus climbing the fastest.
Application:
Clinical development costs and reimbursement pathways segment applications by risk tolerance and capital intensity.
- Infectious Disease:Prophylactic vaccines against respiratory pathogens leverage scalable manufacturing with established immunological endpoints. The United States and China concentrate Phase III trial infrastructure for pandemic preparedness candidates. FDA emergency use authorization pathways compress development timelines for outbreak-responsive programs.
- Oncology:Therapeutic cancer vaccines and oncolytic vectors command premium pricing through orphan drug designations and breakthrough therapy status. Germany and Switzerland lead European manufacturing investment as EMA adaptive licensing frameworks enable conditional approvals. Patient-specific manufacturing demands flexible batch sizes.
- Genetic Disorders:Single-dose curative potential justifies high per-patient costs with long-term follow-up requirements.
- Autoimmune Conditions:Tolerance-inducing vectors target specific immune cell populations with complex mechanistic validation.
- Allergy Immunotherapy:Desensitization protocols require repeated dosing with standardized allergen-encoding constructs.
Infectious disease commands the largest absolute revenue pool, though oncology applications gain share fastest through personalized medicine expansion.
End User:
Procurement sophistication and technical capabilities determine service bundling requirements and contract structures.
- Biopharmaceutical Companies:Integrated vector development teams demand end-to-end platforms spanning plasmid supply through fill-finish. The United States concentrates sponsor headquarters with pipelines exceeding available GMP capacity by substantial margins. Long-term exclusive supply agreements now displace transactional spot purchasing.
- Contract Research Organizations:Outsourced manufacturing volumes expand as mid-cap gene therapy sponsors avoid capital-intensive facility investment. China and India attract facility investment to serve domestic biopharmaceutical growth. CDMOs compete for PhD-level vector analytics talent across virology and bioanalytical disciplines.
- Research Institutes:Preclinical-grade vector requirements prioritize scientific collaboration over regulatory documentation.
- Public Health Agencies:Pandemic stockpiling programs demand surge capacity agreements with defined activation triggers.
- Academic Laboratories:Small-batch production for investigator-initiated trials operates under institutional biosafety oversight.
Biopharmaceutical companies anchor procurement volume, with contract research organizations expanding most quickly through sponsor outsourcing.
Deployment Model:
Regulatory classification and manufacturing architecture segment deployment approaches by technical maturity and supply chain configuration.
- Live Attenuated:Replication-competent vectors induce robust cellular and humoral immunity with single-dose efficacy potential. EMA Annex 2 revisions mandate enhanced environmental monitoring for multi-product facilities handling replication-competent agents. Facility segregation investments dominate qualification timelines in Germany and Switzerland.
- Inactivated Vaccines:Chemical or physical inactivation enables broader handling protocols with established distribution infrastructure. The United States and China maintain strategic stockpiles with defined cold chain requirements. Manufacturing yield optimization focuses on antigen preservation through inactivation chemistry.
- Subunit Vaccines:Purified protein components reduce safety concerns while requiring adjuvant formulation expertise.
- DNA Vaccines:Plasmid-based platforms enable rapid design iteration with synthetic manufacturing alternatives reducing batch variability.
- mRNA Vaccines:Lipid nanoparticle encapsulation operates on distinct manufacturing infrastructure from viral vector platforms.
Live attenuated vectors retain the largest installed manufacturing base, though inactivated platforms gain regulatory preference in multi-product facility configurations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Contract manufacturing clusters in the United States, Germany, and China concentrate GMP-grade viral vector capacity for infectious disease and oncology applications. FDA accelerated approval pathways and EMA adaptive licensing frameworks compress development timelines across these jurisdictions. Localized regulatory requirements and facility investment patterns segment regional competitive positioning.
United States
Biopharmaceutical sponsors anchor procurement volume through long-term exclusive supply agreements with tier-one CDMOs. FDA Chemistry, Manufacturing, and Controls guidance tightens potency assay requirements for gene therapy vectors. The Greater Boston and San Francisco Bay Area clusters host the dominant multi-product GMP facilities serving rare disease pipelines.
Germany
Oncology-focused sponsors drive demand for lentivirus vectors in personalized CAR-T manufacturing workflows. EMA Good Manufacturing Practice Annex 2 revisions mandate enhanced viral clearance validation for multi-product facilities. The Visp site in Switzerland and specialized suites near Frankfurt concentrate European fill-finish capabilities.
China
Domestic biopharmaceutical growth attracts facility investment for clinical-grade vector supply. NMPA alignment with ICH standards enables multinational sponsors to submit single global dossiers. Shanghai and Suzhou industrial parks host expanding CDMO capacity for regional gene therapy sponsors.
Switzerland
Specialized lentivirus manufacturing demands dedicated suite access for patient-specific vector batches. Swissmedic oversight of regenerative medicine products elevates facility qualification standards. Basel and Zurich clusters anchor European oncology vector production with automated closed-system bioreactor deployment.
Japan
Conditional approval pathways for gene therapies reduce Phase III requirements and accelerate vector demand. PMDA Regenerative Medicine Framework enables early commercialization for breakthrough therapies. The Kanto region around Tokyo concentrates sponsor headquarters and clinical trial infrastructure.
Global Viral Vector Vaccines Market Competitive Landscape
Global majors compete with regional champions across manufacturing scale and regulatory sophistication. The vendor base stratifies into tier-one CDMOs with dedicated GMP suites, mid-cap specialists with platform-specific expertise, and emerging entrants targeting geographic white spaces. Three archetypes dominate: integrated end-to-end platforms, specialized fill-finish operators, and analytics-focused testing services. Capacity expansion and long-term exclusive supply agreements constitute the dominant competitive moves as sponsors secure manufacturing slots.
Within the integrated platform tier, Thermo Fisher Scientific Inc and Lonza exemplify archetypes spanning plasmid supply through fill-finish. Charles River Laboratories occupies a position emphasizing integrated testing services that compress release timelines. These three anchors represent distinct strategic postures: Thermo Fisher Scientific Inc leverages end-to-end capabilities, Lonza sustains European dominance through specialized infrastructure, and Charles River Laboratories differentiates via analytics integration.
| Leading Market Players |
|---|
| Merck KGaA |
| Charles River Laboratories |
| Thermo Fisher Scientific Inc |
| Oxford Biomedica |
| Fujifilm Diosynth Biotechnologies |
| Lonza |
| Sanofi |
| REGENXBIO Inc. |
| Aldevron |
| Others |
Supply & Pricing Matrix
Biopharmaceutical sponsors with rare disease pipelines dominate procurement volume and enforce contract-based long-term offtake agreements that lock in capacity commitments. Their concentration in the United States and Germany compresses pricing power toward tier-one CDMOs with dedicated GMP suites while squeezing mid-cap sponsors into premium spot rates.
Pricing Analysis
Plasmid DNA cost pass-through from a concentrated supplier base elevates manufacturing service quotes by fifteen to twenty-five percent for clinical-grade batches. Three-tier pricing structure across premium, standard, and economy levels segments by facility segregation grade and release timeline compression. Cost compression in standard-tier lentivirus production is intensifying because automated closed-system bioreactors reduce labor intensity. Mid-cap gene therapy sponsors exhibit highest price sensitivity as they compete for limited GMP slots against well-capitalized oncology programs.
Supply Chain Analysis
PhD-level vector analytics talent scarcity in the United States, Germany, and Switzerland extends facility qualification timelines and elevates labor costs for multi-product GMP sites. Manufacturing draws from GMP-grade plasmid DNA, specialized cell culture media, and single-use bioreactor consumables as critical inputs. Single-source vulnerability for synthetic DNA alternatives constrains batch scaling flexibility. Distribution runs through controlled cold chain networks anchored at regional fill-finish hubs near Frankfurt and Basel.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as oncology sponsors shift demand toward patient-specific lentivirus batches requiring dedicated suite access and seventy-two-hour release timelines.
For Market Incumbents: Cement exclusive supply agreements with tier-one CDMOs before facility segregation investments peak under EMA Annex 2 revisions. Threat from emerging Indian CDMOs with cost-advantaged labor pools demands preemptive capacity reservation in Switzerland and Germany. Backward integration into plasmid DNA supply secures margin control against raw material concentration. For New Entrants and Emerging Players: Continuous processing architectures offer a technology-first wedge into standard-tier adenovirus manufacturing where legacy batch methods dominate. India's underdeveloped gene therapy CDMO infrastructure presents the most penetrable geography. Target domestic biopharmaceutical sponsors seeking localized clinical-grade supply with automated platform partnerships. For Investors and Strategic Acquirers: Large-cap biopharmaceutical companies with rare disease pipelines are the most active acquirer in this space, seeking captive vector capacity. Long-term viability hinges on CAR-T manufacturing workflow expansion across the projection horizon. Acquisition target archetype: mid-cap CDMOs with closed-system bioreactor deployments and Swissmedic or FDA inspection history. Signal to watch: rolling submission filings for breakthrough gene therapies that pull forward capacity commitments.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Automated closed-system bioreactor deployment at Basel facilities compresses capital timelines from thirty-six to eighteen months. |
| Regulatory Approval Pathway | FDA accelerated approval for CAR-T assets pulls forward revenue recognition for vector manufacturers with integrated testing. |
| Long-term Supply Agreement | Exclusive capacity commitments with Lonza and Thermo Fisher Scientific Inc lock out competitors from multi-product GMP suites. |
| Backward Integration | In-house plasmid DNA production at Aldevron reduces batch-to-batch variability and raw material cost pass-through exposure. |
| Geographic Expansion | Shanghai and Suzhou industrial park investments serve NMPA-aligned sponsors with localized stability data capabilities. |
Research Methodology
Multiple input streams — primary interviews with vector manufacturing executives, regulatory affairs leads at CDMOs, and hospital procurement managers for CAR-T programs — were reconciled against FDA Chemistry Manufacturing and Controls guidance documents, EMA GMP Annex 2 revision drafts, and ClinicalTrials.gov gene therapy trial registries. Bottom-up capacity modeling at facility level triangulated against top-down sponsor pipeline analysis across the analysis window.
Data-stream reconciliation anchored volume projections on platform-specific yield ceilings, facility segregation requirements under evolving biosafety classifications, and patient-specific batch economics for personalized oncology workflows. Segmentation dimensions spanned vector type, application area, end-user procurement sophistication, and regional regulatory cluster. CAGRs were derived from capacity expansion announcements cross-referenced with sponsor filing timelines and CDMO booking visibility.
The model holds under stable FDA and EMA regulatory frameworks; deviation in WHO biosafety containment reclassifications or NMPA technical guideline revisions would shift facility investment thresholds and capacity availability assumptions. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
Adipose Derived Stem Cell Therapy Market
Cell & Gene Therapy
Gene Therapy Products Market
Cell & Gene Therapy
Hemophilia Treatment Market
Cell & Gene Therapy
Europe Gene Therapy Market
Cell & Gene Therapy
Cellular Immunotherapy Market
Cell & Gene Therapy
Global T-Cell Acute Lymphoblastic Leukemia Treatment Market
Cell & Gene Therapy
Asia-Pacific Stem Cell Therapy Market
Cell & Gene Therapy
Sandhoff Disease Therapeutics Market
Cell & Gene Therapy
Cell Therapy Cryopreservation and Thaw Performance Test Platforms Market
Cell & Gene Therapy
Lentiviral Vector Contract Development and Manufacturing Organizations Market
Cell & Gene Therapy
Global Neoantigen Cancer Vaccine Market
Cell & Gene Therapy
Cell and Gene Therapy Clinical Trials Market
Cell & Gene Therapy
Cell and Gene Supply Chain Services Market
Cell & Gene Therapy
Global Lentiviral Vectors Market
Cell & Gene Therapy
Niemann-Pick Disease Type C (NPC) Market
Cell & Gene Therapy
Nucleic Acid Therapeutics CDMO Market