
 Cell Therapy Manufacturing Market | 2026-2036
Cell Therapy Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
Cell Therapy Manufacturing Market Analysis
Contract manufacturing channel control is tilting toward integrated platform providers capable of spanning vector production through final fill-finish. Thermo Fisher Scientific leverages its Gibco media franchise and acquisition-built bioproduction network to anchor North American autologous manufacturing capacity. Lonza Group sustains its position through the Cocoon platform and dedicated cell therapy facilities in Singapore and Texas. Samsung Biologics competes on Korean peninsula-based scale, extending into plasmid and viral vector supply for CAR-T programs.
Cell therapy manufacturing encompasses the aseptic production, expansion, genetic modification, and cryopreservation of living therapeutic cells under current Good Manufacturing Practice conditions, typically requiring closed-system bioreactors, serum-free media formulations, and lot release timelines of 14–21 days for patient-specific products. Its primary commercial purpose is converting research-stage cellular interventions into reproducible, scalable treatments for hematologic malignancies and solid tumors. Autologous cell manufacturing occupies the dominant revenue position due to approved CAR-T therapies requiring patient-matched production workflows, while allogeneic cell platforms represent the fastest-expanding segment as off-the-shelf approaches promise reduced cost of goods and shortened vein-to-vein times. Gene editing technology leads R&D investment intensity, with CRISPR-based allogeneic programs attracting manufacturing partnerships that concentrate margin pools in viral vector and electroporation supply.
FDA's regenerative medicine advanced therapy designation and current Good Tissue Practice requirements shape facility design standards, while EMA's ATMP classification system governs European market access pathways for commercial cell therapy sites. Japan's PMDA operates accelerated conditional approval frameworks that demand post-market manufacturing consistency commitments for regenerative products. Stakeholders must monitor regulatory divergence in comparability protocols and real-time release testing standards as jurisdictions refine living-product quality expectations.
Market Dynamics
The FDA's regenerative medicine advanced therapy designation is compressing approval timelines while simultaneously tightening facility qualification standards, forcing manufacturers to revalidate cleanroom infrastructure mid-cycle.
Growth Catalysts
- ATMP Classification:EMA's centralized marketing authorization pathway accelerates European site qualification for commercial cell therapy production.
- Oncology Demand:Hematologic malignancy treatment centers are expanding dedicated apheresis collection infrastructure to feed autologous manufacturing pipelines.
- Electroporation:Non-viral gene delivery methods reduce vector manufacturing bottlenecks and simplify supply chain qualification.
Market Restraints
- Plasmid Supply:Viral vector production depends on concentrated North American plasmid suppliers, creating single-source vulnerability for GMP-grade starting material.
- Facility Capex:ISO 5 cleanroom suites require $50-150 million per site, with 18-24 month construction timelines that outpace demand forecasting accuracy.
- Current Good Tissue Practice:FDA donor eligibility documentation creates batch record complexity that extends lot release by 5-7 days versus conventional biologics.
Strategic Opportunities
- Germany:The country's ATMP manufacturing hub status attracts contract development organizations seeking EMA-aligned regulatory expertise.
- Allogeneic Platforms:Off-the-shelf cell banks enable centralized manufacturing economics that autologous workflows cannot match.
- Real-Time Release Testing:Process analytical technology adoption allows parametric release, eliminating quarantine inventory holding costs.
Industry Challenges
- Aseptic Processing Skill Gap:Closed-system bioreactor operation requires hybrid cell culture and GMP compliance expertise that traditional biologics training programs do not address.
- Comparability Protocol Delays:Post-approval manufacturing changes for living products lack established analytical frameworks, extending regulatory negotiation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cell Therapy Manufacturing Market |
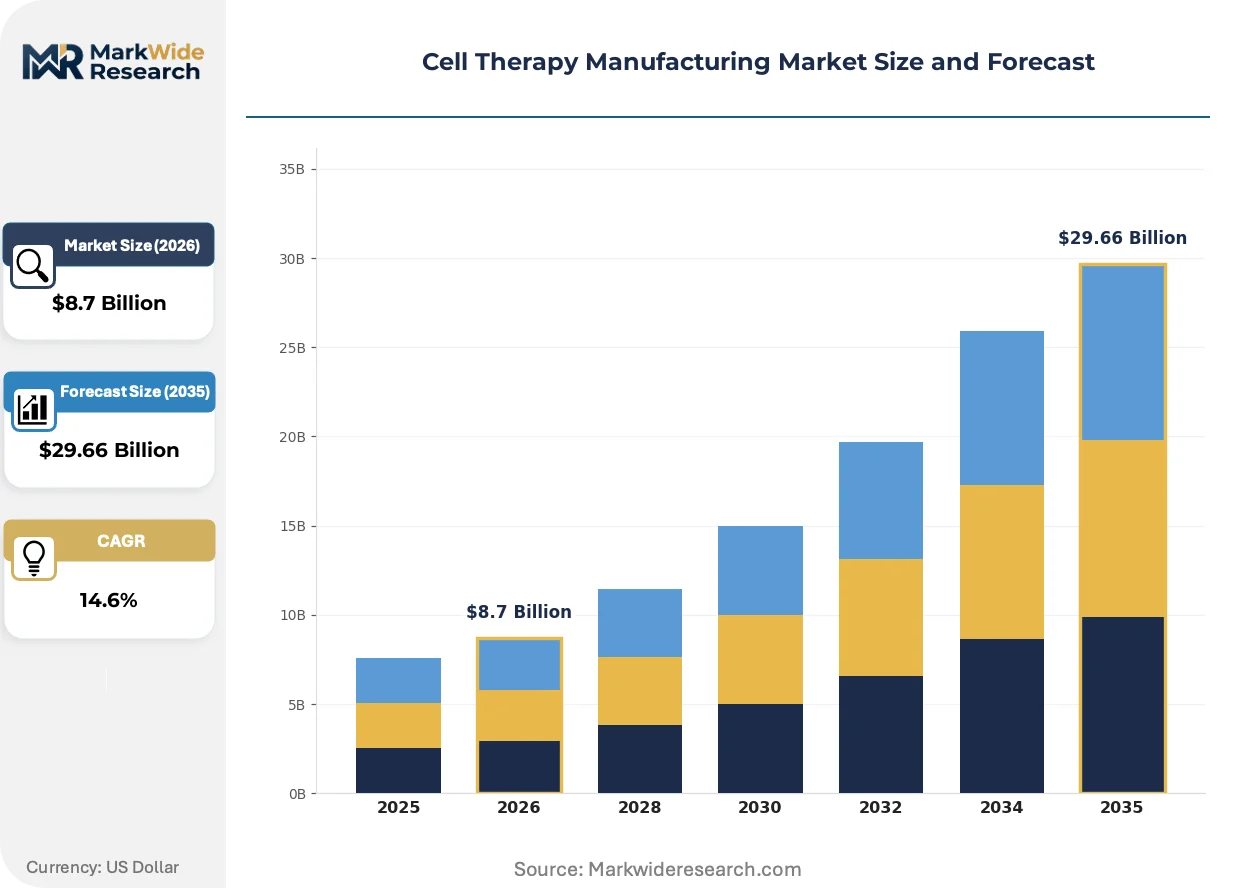
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $29.66 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Autologous Cells, Allogeneic Cells, Stem Cells, CAR-T Cells Technology: Gene Editing, Cell Culture, Microfluidics, Immune Modulation End User: Pharmaceutical Companies, Research Institutions, Contract Manufacturing Organizations, Hospitals Application: Oncology, Autoimmune Diseases, Cardiovascular Diseases, Regenerative Medicine |
| Companies Covered | Thermo Fisher Scientific, Merck KGaA, Catalent, Lonza Group, Cytiva, Charles River Laboratories, Samsung Biologics, Takara Bio, AGC Biologics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cell Therapy Manufacturing Market Emerging Trajectories
Closed-system automation is eliminating open-phase manipulation from cell therapy workflows. Vector manufacturing bottlenecks are driving platform consolidation. Regulatory science investment is outpacing clinical development spending.
Microcarrier-based bioreactor expansion is collapsing the surface-area limitations that flask-based culture imposed on autologous cell yields. Large-scale manufacturers are adopting 50-200 liter single-use vessels for T-cell expansion. This technology compression enables centralized production models that reduce per-patient facility overhead.
EMA's ATMP certification framework is harmonizing quality expectations across member states while adding post-authorization safety study obligations. Manufacturers must maintain pharmacovigilance systems capable of tracking individual patient batches for 15 years. German and Dutch sites are investing in blockchain-based chain-of-custody systems to meet traceability mandates.
Academic medical centers are ceding manufacturing control to specialized CDMOs as vein-to-vein timelines compress below 21 days. Hospital-based cell processing labs cannot match the equipment redundancy and regulatory staffing of dedicated facilities. This channel consolidation concentrates procurement decisions among pharmaceutical sponsors rather than treating physicians.
Cell Therapy Manufacturing Market Segmentation
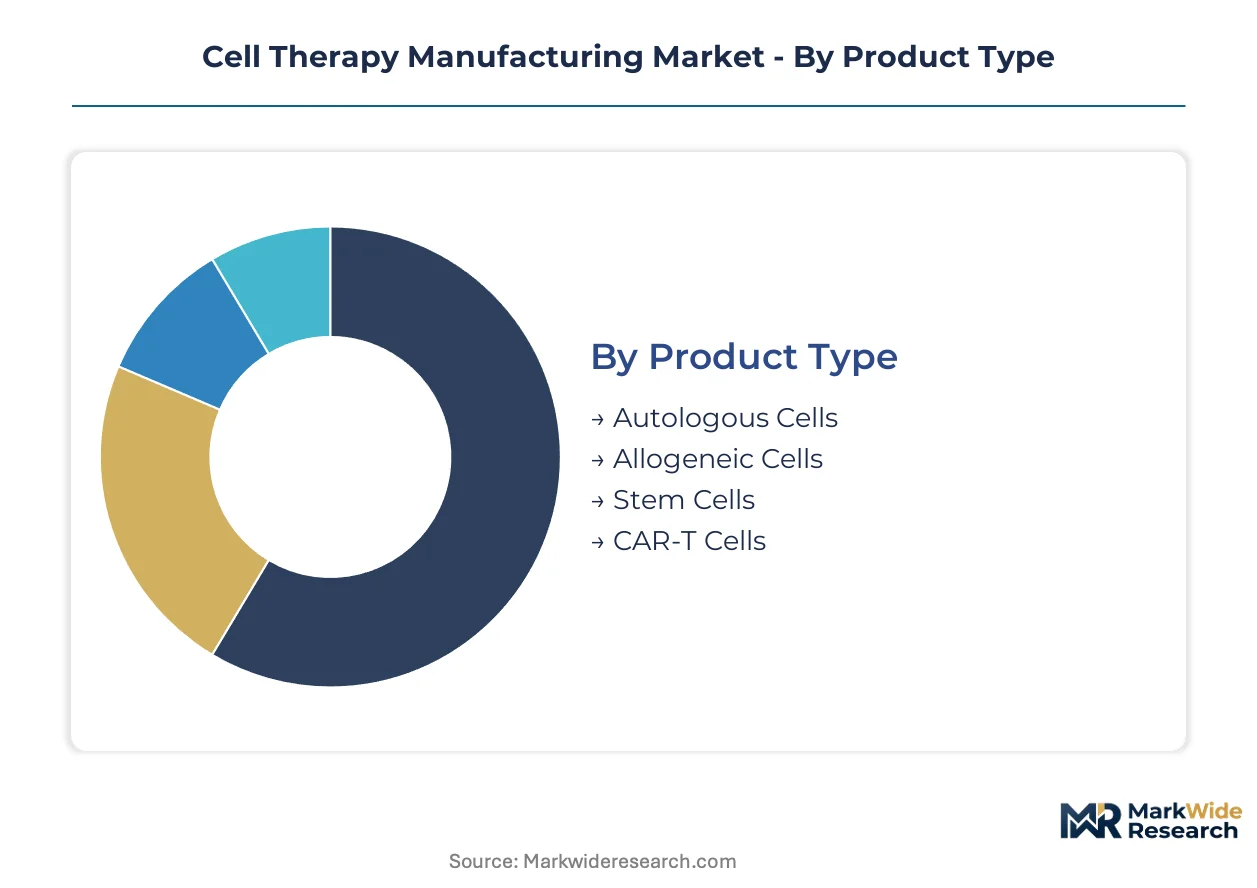
Cell therapy manufacturing segments reflect divergent production economics, regulatory pathways, and technical barriers that reshape competitive positioning across the value chain. Understanding these divisions illuminates where capital deployment concentrates and which technology platforms command premium positioning.
Product Type:
Patient-matched versus universal supply models create fundamentally different facility footprints and margin structures across therapeutic cell categories.
- Autologous Cells:Patient-derived starting material requires dedicated manufacturing suites per batch, with vein-to-vein logistics spanning apheresis collection through cryopreserved infusion. Pharmaceutical sponsors in the United States and Germany dominate demand as CAR-T commercialization scales.
- Allogeneic Cells:Off-the-shelf cell banks enable batch sizes serving hundreds of patients, collapsing per-dose facility overhead and shortening treatment access timelines. Singapore and Texas manufacturing clusters attract investment as centralized production economics displace distributed models.
- Stem Cells:Pluripotent and multipotent lineages require specialized expansion media and karyotype monitoring throughout culture duration.
- CAR-T Cells:Chimeric antigen receptor engineering demands viral vector transduction or electroporation capabilities integrated with T-cell selection workflows.
Established volume favors autologous platforms; emerging adoption favors allogeneic approaches.
Technology:
Process modality determines capital intensity, supply chain qualification burden, and regulatory comparability pathway complexity.
- Gene Editing:CRISPR-Cas9 and base editing systems enable precise genetic modifications without viral vector dependency. Electroporation delivery methods reduce GMP plasmid supply vulnerability that constrains lentiviral manufacturing.
- Cell Culture:Bioreactor expansion systems—stirred-tank, rocking-motion, and fixed-bed configurations—govern achievable cell densities and lot-to-lot consistency. Closed-system adoption accelerates as FDA emphasizes contamination control in pre-approval inspections.
- Microfluidics:Precision fluid handling enables single-cell encapsulation and high-throughput screening applications.
- Immune Modulation:Cytokine engineering and checkpoint modulation protocols require specialized analytical release testing.
Process analytical technology investment concentrates in cell culture platforms; gene editing commands the steepest R&D expansion trajectory.
End User:
Customer type dictates procurement scale, technical specification rigor, and service bundling requirements.
- Pharmaceutical Companies:Integrated sponsors internalize late-stage manufacturing while outsourcing early-phase production to preserve capital flexibility. FDA regenerative medicine advanced therapy designations compress timelines, forcing rapid facility qualification decisions.
- Contract Manufacturing Organizations:Platform providers spanning vector production through fill-finish capture procurement decisions as pharmaceutical sponsors consolidate supplier bases. Lonza's Singapore and Texas facilities exemplify geographic diversification strategies.
- Research Institutions:Academic medical centers maintain process development capabilities but cede commercial-scale production to specialized partners.
- Hospitals:Point-of-care manufacturing models persist in Japan's conditional approval framework despite regulatory staffing limitations.
Procurement consolidation favors contract manufacturing organizations; research institutions retain early-phase process development influence.
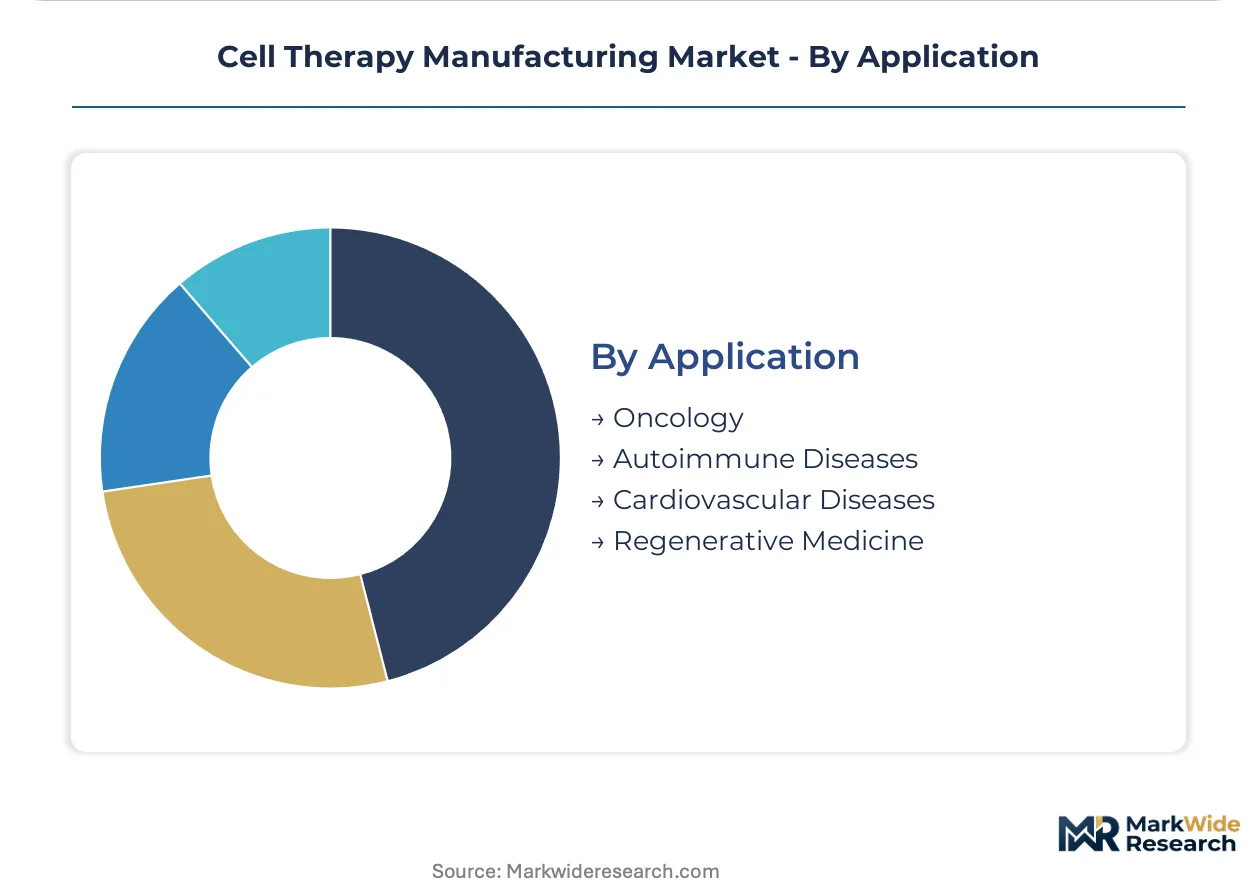
Application:
Therapeutic indication shapes manufacturing throughput requirements, release testing protocols, and reimbursement pathway maturity.
- Oncology:Hematologic malignancy applications dominate commercial volume, with approved CAR-T therapies requiring dedicated apheresis-to-infusion logistics chains. United States treatment centers drive demand concentration.
- Regenerative Medicine:Tissue repair applications span orthopedic, ophthalmic, and cardiac indications with divergent cell type requirements. Japan's PMDA conditional approval framework accelerates market access while demanding post-market manufacturing consistency commitments.
- Autoimmune Diseases:Tolerance induction and regulatory T-cell approaches require distinct potency assays versus cytotoxic cell products.
- Cardiovascular Diseases:Ischemic repair applications face delivery challenges that complicate manufacturing-release-to-administration timelines.
Clinical validation depth favors oncology applications; pipeline expansion favors regenerative medicine indications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized biologics manufacturing corridors in the United States, Germany, and Japan anchor the cell therapy production network, with vector manufacturing capabilities and cleanroom infrastructure clustering near major academic medical centers and regulatory agencies.
United States
FDA's regenerative medicine advanced therapy designation compresses approval timelines while demanding facility requalification mid-cycle. The agency's current Good Tissue Practice requirements extend lot release documentation by 5-7 days versus conventional biologics. Boston and San Francisco Bay Area clusters concentrate autologous manufacturing capacity near hematologic malignancy treatment centers.
Germany
EMA's ATMP classification system governs centralized marketing authorization pathways that accelerate European site qualification. The country's national pharmaceutical regulator mandates pharmacovigilance systems capable of tracking individual patient batches for 15 years post-authorization. Heidelberg and Cologne manufacturing hubs attract contract development organizations seeking EMA-aligned regulatory expertise.
Japan
PMDA's accelerated conditional approval frameworks compress market access timelines while demanding post-market manufacturing consistency commitments. The regulator's regenerative product safety requirements shape facility design standards for domestic production. Osaka and Kobe bioclusters maintain point-of-care manufacturing models alongside centralized commercial facilities.
Singapore
Strategic biologics manufacturing investments position the city-state as a vector production and allogeneic cell banking hub for Asia-Pacific distribution. The national pharmaceutical regulator harmonizes quality expectations with FDA and EMA standards to enable multi-jurisdictional supply. Tuas Biomedical Park hosts dedicated cell therapy facilities serving regional pharmaceutical sponsors.
South Korea
MFDS operates accelerated approval pathways for advanced therapy medicinal products that align with international regulatory science developments. Korean peninsula-based manufacturing scale extends into plasmid and viral vector supply chains for CAR-T programs. Songdo and Incheon bioclusters concentrate electroporation and gene editing technology partnerships.
Cell Therapy Manufacturing Market Vendor Landscape
On the supply side, the industry is consolidating around integrated platform providers capable of spanning vector production through final fill-finish operations. Contract manufacturing channel control tilts toward entities with captive media franchises, dedicated cell therapy facilities, and geographic diversification across regulatory jurisdictions. Three strategic archetypes dominate: diversified life science conglomerates with acquisition-built bioproduction networks, specialized CDMOs with purpose-built cleanroom infrastructure, and Asian-scale manufacturers extending into plasmid and viral vector supply. Competitive moves concentrate on strategic partnerships for gene editing technology access and capacity expansion in Singapore-Texas corridor positioning.
Among diversified conglomerates, Thermo Fisher Scientific anchors North American autologous manufacturing capacity through its Gibco media franchise and acquisition-built network. Lonza Group exemplifies the specialized CDMO archetype through dedicated facilities in Singapore and Texas. Samsung Biologics occupies the Asian-scale manufacturer position, extending Korean peninsula-based production into vector supply chains. These three entities represent distinct strategic postures without implying specific market share or revenue claims.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Merck KGaA |
| Catalent |
| Lonza Group |
| Cytiva |
| Charles River Laboratories |
| Samsung Biologics |
| Takara Bio |
| AGC Biologics |
| Others |
Supply Flow & Price Mechanics
Cryogenic freight corridors connecting Singapore to Texas and Boston to Frankfurt impose per-shipment premiums that compound with batch-size economics, concentrating pricing power among integrated platform providers while forcing smaller autologous manufacturers toward standard-tier service bundles.
Pricing Analysis
Volume-discount tiering separates dedicated-suite autologous contracts from multi-batch allogeneic commitments, with premium tiers capturing GMP-grade viral vector integration and economy tiers limited to open-phase processing. Price differentiation hinges on ISO 5 cleanroom certification level and captive media formulation capabilities. Cost compression in standard-tier autologous manufacturing is intensifying as pharmaceutical sponsors consolidate supplier bases. Academic medical centers exhibit highest price sensitivity; integrated biopharma sponsors prioritize timeline certainty over per-dose cost.
Supply Chain Analysis
Contract-manufacturing concentration rests with Thermo Fisher Scientific, Lonza Group, and Samsung Biologics, which anchor capacity across North America, Singapore, and the Korean peninsula. Plasmid supply draws from concentrated North American sources, while serum-free media formulations source from European chemical suppliers. Single-source vulnerability in GMP-grade starting material creates structural exposure. Distribution runs through pharmaceutical sponsor procurement committees rather than hospital-based channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cell therapy manufacturing functions as a service-attach opportunity where process development partnerships and post-approval regulatory consulting expand faster than standalone facility rental revenue.
For Market Incumbents: Pre-empt electroporation-based gene editing disruption by securing exclusive access to non-viral delivery platform providers. Consolidate position through backward integration into plasmid manufacturing, neutralizing the single-source vulnerability that constrains lentiviral vector supply. Lock in pharmaceutical sponsor relationships with dedicated-suite capacity commitments that emerging CDMOs cannot match.
For New Entrants and Emerging Players: Build out allogeneic cell banking capabilities in the Singapore-Texas corridor, where centralized production economics displace distributed autologous models. Target regenerative medicine applications in Japan's conditional approval framework, where post-market manufacturing commitments create ongoing service revenue. Lead with real-time release testing expertise as the go-to-market wedge against incumbent quarantine-holding cost structures.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified life science conglomerates with underutilized cell therapy assets lacking pharmaceutical sponsor relationships. Long-term viability favors platforms spanning vector production through fill-finish with regulatory alignment across FDA, EMA, and PMDA jurisdictions. Monitor electroporation technology licensing velocity as the inflection signal for viral vector demand displacement.
| Strategic Initiative | Industry Significance |
|---|---|
| Closed-System Automation Deployment | Eliminates open-phase contamination risk that FDA pre-approval inspections increasingly flag. |
| Gene Editing Technology Partnership | Secures CRISPR-based allogeneic program access as electroporation displaces viral vector dependency. |
| Geographic Diversification in Singapore-Texas Corridor | Positions centralized allogeneic manufacturing for Asia-Pacific and North American market access. |
| Real-Time Release Testing Implementation | Enables parametric lot release that eliminates quarantine inventory holding cost disadvantages. |
| Regulatory Science Investment | Accelerates post-approval manufacturing change comparability protocols that lack established frameworks. |
Methodological Framework
Initial hypotheses were tested against primary input from cell therapy manufacturing executives, regulatory affairs leads, pharmaceutical sponsor procurement managers, and CDMO facility directors and refined through secondary validation against FDA regenerative medicine filings, EMA ATMP submission databases, ClinicalTrials.gov intervention records, and national pharmaceutical regulator guidance documents. Bottom-up capacity modeling triangulated against top-down pharmaceutical sponsor pipeline analysis.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning autologous versus allogeneic supply models, gene editing versus viral vector technology platforms, and oncology versus regenerative medicine applications. CAGRs derived from facility capacity expansion announcements, pharmaceutical sponsor manufacturing partnership disclosures, and regulatory approval pathway velocity. Forecast inputs incorporated electroporation technology adoption curves and closed-system bioreactor installation rates.
Stress conditions across plasmid supply disruption, FDA facility inspection backlog, and allogeneic clinical trial failure rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding pharmaceutical sponsor outsourcing propensity and regulatory harmonization progress. Quarterly review of electroporation partnership announcements and CDMO capacity utilization indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
B Cell Maturation Antigen Targeted Therapy Market
Cell & Gene Therapy
Autologous Stem Cell and Non Stem Cell Based Therapies Market
Cell & Gene Therapy
RNA Therapy Clinical Trials Market
Cell & Gene Therapy
Regenerative Medicine Market
Cell & Gene Therapy
Drug Delivery in Cancer Market
Cell & Gene Therapy
Asia Pacific Cancer Biological Therapy Market
Cell & Gene Therapy
Europe Viral Vector Purification Market
Cell & Gene Therapy
Adeno Associated Virus Vector Manufacturing Market
Cell & Gene Therapy
Oncolytic Adenovirus Market
Cell & Gene Therapy
CNS Specific Antisense Oligonucleotide Market
Cell & Gene Therapy
Inherited Orphan Blood Disorders Therapeutics Market
Cell & Gene Therapy
Cell Therapy Technologies Market
Cell & Gene Therapy
North America Gene Therapy Market
Cell & Gene Therapy
Cord Blood Banking Market
Cell & Gene Therapy
MRNA Therapeutics Contract Development and Manufacturing Organization Market
Cell & Gene Therapy
RNAI Technology Market