
 Protein Degeneration Therapy Market | 2026-2036
Protein Degeneration Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
Protein Degeneration Therapy Market Analytics
Specialized medicinal chemists with expertise in E3 ligase biology is collapsing across the contract research sector, constraining the pace of rational drug design for heterobifunctional degraders. Arvinas leverages its first-mover platform to anchor clinical development in oncology and neuroscience indications. Bristol Myers Squibb competes through deep small-molecule libraries and established commercial infrastructure in immunology. Kymera Therapeutics differentiates by occupying the ubiquitin-proteasome system space with a focus on tissue-specific ligase discovery.
Protein degeneration therapy encompasses pharmacological modalities that induce selective intracellular protein degradation, principally through proteolysis-targeting chimeras that recruit E3 ubiquitin ligases to neosubstrates and molecular glues that reshape ligase substrate specificity, with critical functional parameters including ternary complex stability, cooperativity indices, and ligase expression profiles in target tissues. Small molecules currently dominate prescription volumes due to manufacturing scalability and oral bioavailability, while gene therapy vectors represent the fastest-expanding modality as programmable delivery systems improve tissue tropism for central nervous system targets. Biologics concentrate margin pools in rare neuromuscular indications where antibody-based degraders command premium positioning.
The FDA's accelerated approval and breakthrough therapy designations are reshaping trial design and commercial launch timelines for protein degraders, while the EMA's PRIME eligibility criteria are creating parallel access pathways in European markets. China's NMPA has established dedicated review channels for innovative biologics under its drug registration reform, accelerating multinational trial inclusion. Stakeholders must monitor evolving payer evidence requirements for outcomes-based contracts as health technology assessment bodies scrutinize durability data beyond initial response rates.
Market Dynamics
The scarcity of medicinal chemists trained in E3 ligase biology is compressing rational design timelines for heterobifunctional degraders, forcing sponsors to anchor platform investments in fewer, higher-confidence targets.
Growth Catalysts
- FDA Accelerated Approval Pathways:The FDA's breakthrough therapy designation shortens clinical development timelines for first-in-class proteolysis-targeting chimeras by enabling rolling review and priority scheduling.
- Translational Research Expansion:Academic medical centers in the United States are building dedicated protein degradation institutes that funnel discovery-stage assets into sponsored development pipelines.
- Specialized Manufacturing Infrastructure:Contract development organizations in Germany and China have installed purpose-built suites for proteolysis-targeting chimera synthesis, reducing batch-to-batch variability for complex heterobifunctional molecules.
Market Restraints
- Input Cost Volatility:High-purity E3 ligase ligands and linkers face supply constraints from single-source specialty chemical producers in Switzerland and India, inflating cost-of-goods for clinical batches.
- Technical Limitation:Current degraders fail to engage the approximately twenty percent of human proteins lacking surface lysine residues accessible to ubiquitin conjugation, excluding entire target classes.
- Regulatory Friction:The EMA's evolving requirements for ternary complex characterization data are extending chemistry-manufacturing-controls review timelines for novel molecular glue submissions.
Strategic Opportunities
- Central Nervous System Penetration:Blood-brain barrier-permeable degraders targeting tau and alpha-synuclein represent underexploited white space as gene therapy vectors improve neuronal tropism.
- China's NMPA Reform:Dedicated review channels for innovative biologics under China's drug registration reform accelerate multinational trial inclusion and shorten time-to-market for Western sponsors.
- Tissue-Specific Ligase Discovery:Converging advances in single-cell transcriptomics and chemoproteomics enable ligase profiling across immune cell subsets, opening autoimmune and inflammatory indications.
Industry Challenges
- Specialized Talent Scarcity:The contract research sector faces acute shortages of chemists capable of optimizing cooperativity indices in ternary complex formation, constraining iterative design cycles.
- IP Licensing Complexity:Fragmented ownership of E3 ligase patents and linker chemistries forces sponsors into multi-party negotiations, delaying program initiation and diluting exclusivity positions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Protein Degeneration Therapy Market |
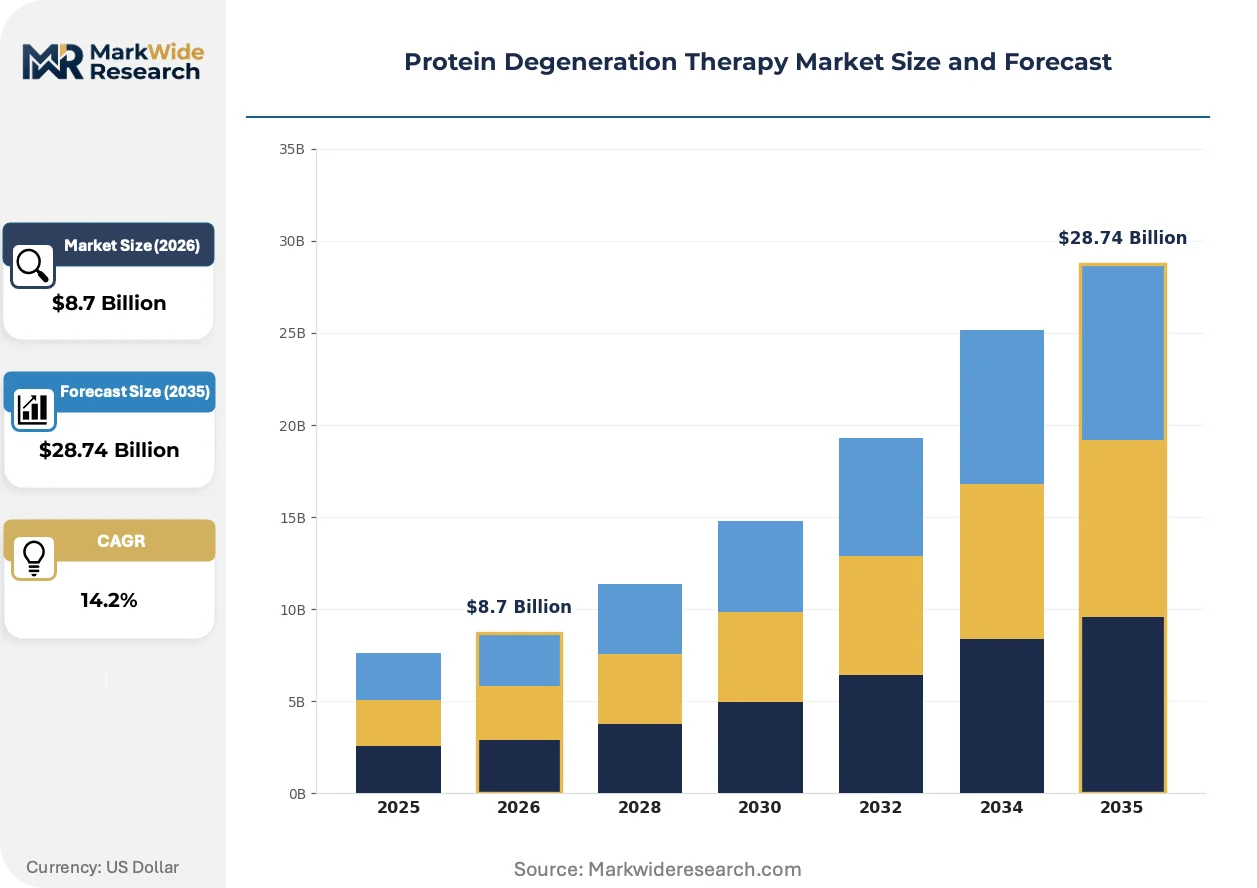
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Small Molecules, Biologics, Gene Therapy, Cell Therapy Application: Neurological Disorders, Muscular Disorders, Cardiovascular Diseases, Autoimmune Conditions Delivery Mode: Intravenous, Subcutaneous, Oral, Topical End User: Hospitals, Clinics, Research Laboratories, Homecare |
| Companies Covered | F. Hoffmann-La Roche AG, Arvinas, Bristol Myers Squibb, Pfizer, Merck & Co., Inc., Amgen Inc., Johnson & Johnson Services, Inc., Novo Nordisk A/S, Kymera Therapeutics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Protein Degeneration Therapy Market Evolving Landscape
Discovery platforms are pivoting from empirical screening toward structure-guided design, compressing hit-to-lead timelines while fragmenting competitive advantage across specialized toolsets rather than scale.
Molecular glue modalities are fragmenting traditional inhibitor markets by enabling degradation of previously undruggable transcription factors. Biopharma discovery groups in oncology and neuroscience are adopting glue-first screening strategies at the expense of conventional occupancy-driven campaigns. The structural consequence is a bifurcation in platform valuation, with ternary complex engineering capabilities commanding premium positioning against standard small-molecule libraries.
REACH registration requirements for novel chemical entities are forcing European sponsors to front-load environmental fate studies for heterobifunctional degraders, adding twelve to eighteen months to preclinical packages. The industrial consequence is a geographic split in program initiation, with some sponsors prioritizing United States filings to defer European regulatory investment. Oncology indications face the steepest compliance burden due to higher dosing regimens and larger patient exposure volumes.
Academic technology transfer offices are consolidating exclusive licensing leverage, displacing non-exclusive research tool agreements that previously enabled broad platform access. Biotech startups in Boston and San Diego now compete for limited slots in top-tier institutional portfolios, driving upfront payment inflation and tighter milestone structures. This concentration is most visible in United States coastal clusters where university endowments prioritize equity participation over royalty streams.
Protein Degeneration Therapy Market Segmentation
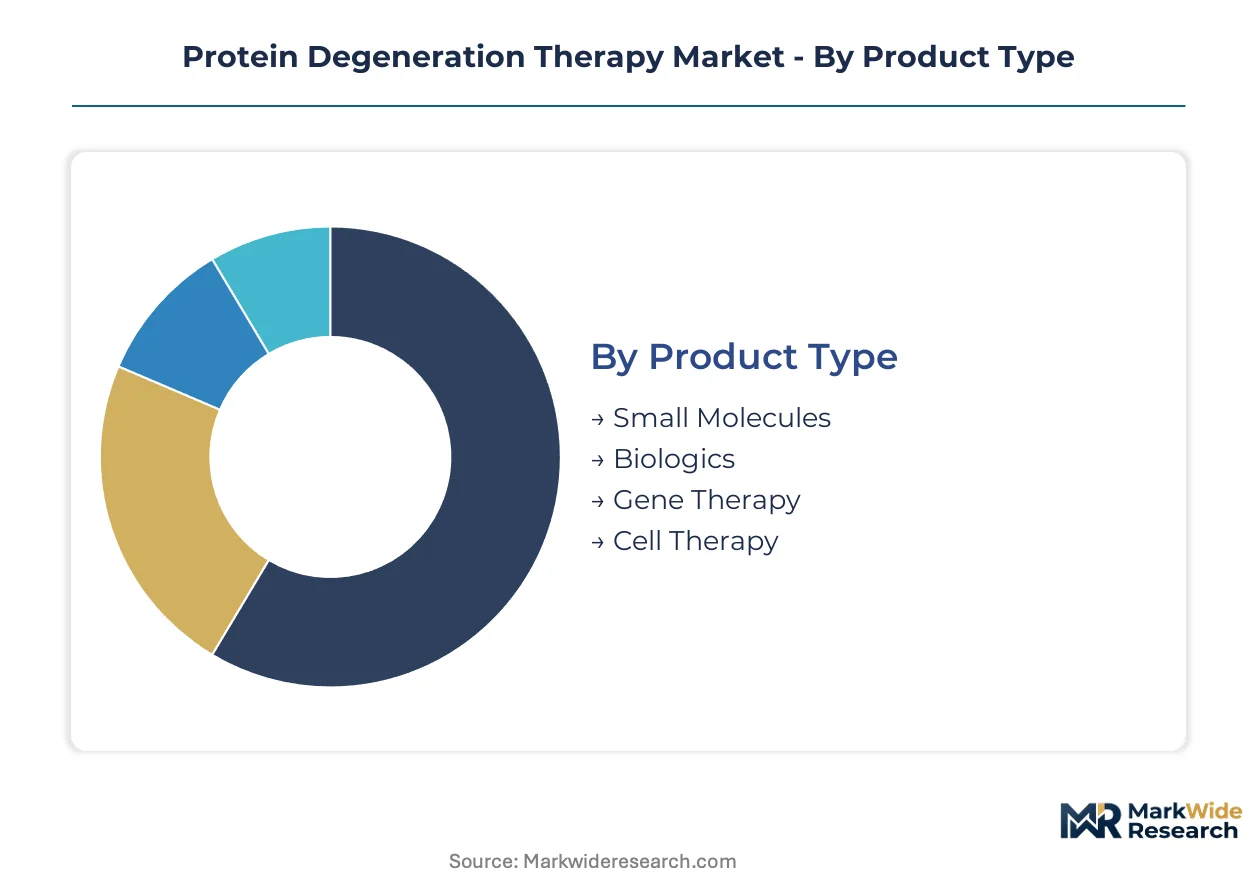
Segmentation in protein degeneration therapy reveals how modality choice, target tissue, and care setting interact to determine development priorities. Product type decisions cascade into manufacturing infrastructure requirements, while application focus shapes regulatory strategy and partnership structures.
Product Type:
Gene therapy vectors face the most acute substitution pressure as molecular glue modalities expand their addressable target space through improved ligase recruitment efficiency.
- Small Molecules:Heterobifunctional degraders and molecular glues dominate current prescription volumes due to established oral bioavailability and scalable synthetic chemistry. Demand concentrates in oncology and autoimmune indications where E3 ligase expression profiles support robust degradation kinetics, though linker stability remains a formulation challenge for central nervous system targets.
- Gene Therapy:Adeno-associated viral vectors and lipid nanoparticles enable programmable delivery of CRISPR-based degradation machinery. Neurological applications in the United States and Germany are driving vector engineering investments as blood-brain barrier penetration improves, yet immunogenicity concerns limit redosing flexibility.
- Biologics:Antibody-based degraders command premium positioning in rare neuromuscular indications requiring high target specificity.
- Cell Therapy:Engineered T-cells expressing targeted degradation constructs remain confined to early-phase academic trials.
Small molecules anchor the volume base while gene therapy gains share at the steepest rate.
Application:
Cost tier differentiation separates mass-market autoimmune opportunities from boutique neuromuscular programs requiring specialized commercial infrastructure.
- Neurological Disorders:Tauopathies and synucleinopathies represent the most technically demanding application due to blood-brain barrier constraints and neuronal ligase expression heterogeneity. Academic medical centers in Boston and San Diego are funneling discovery assets into sponsored development pipelines for Alzheimer's and Parkinson's targets.
- Muscular Disorders:Duchenne muscular dystrophy and spinal muscular atrophy drive biologics demand where antibody-mediated degradation of toxic protein aggregates offers disease-modifying potential. Patient advocacy networks in Germany and the United States are accelerating trial recruitment for pediatric indications.
- Cardiovascular Diseases:Degradation of pro-inflammatory signaling proteins in atherosclerosis remains underexplored relative to oncology precedents.
- Autoimmune Conditions:Tissue-specific ligase profiling across immune cell subsets is opening rheumatoid arthritis and inflammatory bowel disease to molecular glue approaches.
Neurological disorders command the highest development investment while autoimmune conditions expand most quickly into registrational trials.
Delivery Mode:
Volume concentration in hospital-administered routes reflects the current dominance of parenteral biologics and gene therapies in advanced clinical development.
- Intravenous:Infusion centers handle the majority of biologic degrader administrations where dosing precision and adverse event monitoring prove critical. Contract development organizations in Germany have installed purpose-built suites for high-volume parenteral production.
- Oral:Small-molecule degraders achieve patient preference advantages in chronic autoimmune maintenance therapy, though first-pass metabolism constrains bioavailability for certain heterobifunctional scaffolds.
- Subcutaneous:Self-administration potential is driving device co-development for molecular glues in multiple sclerosis.
- Topical:Skin-targeted degraders for psoriasis remain preclinical due to permeation challenges with larger molecular constructs.
Intravenous delivery anchors the volume base while oral formulations gain share at the steepest rate.
End User:
Customer type fragmentation across site-of-care settings determines reimbursement complexity and supply chain configuration for each modality.
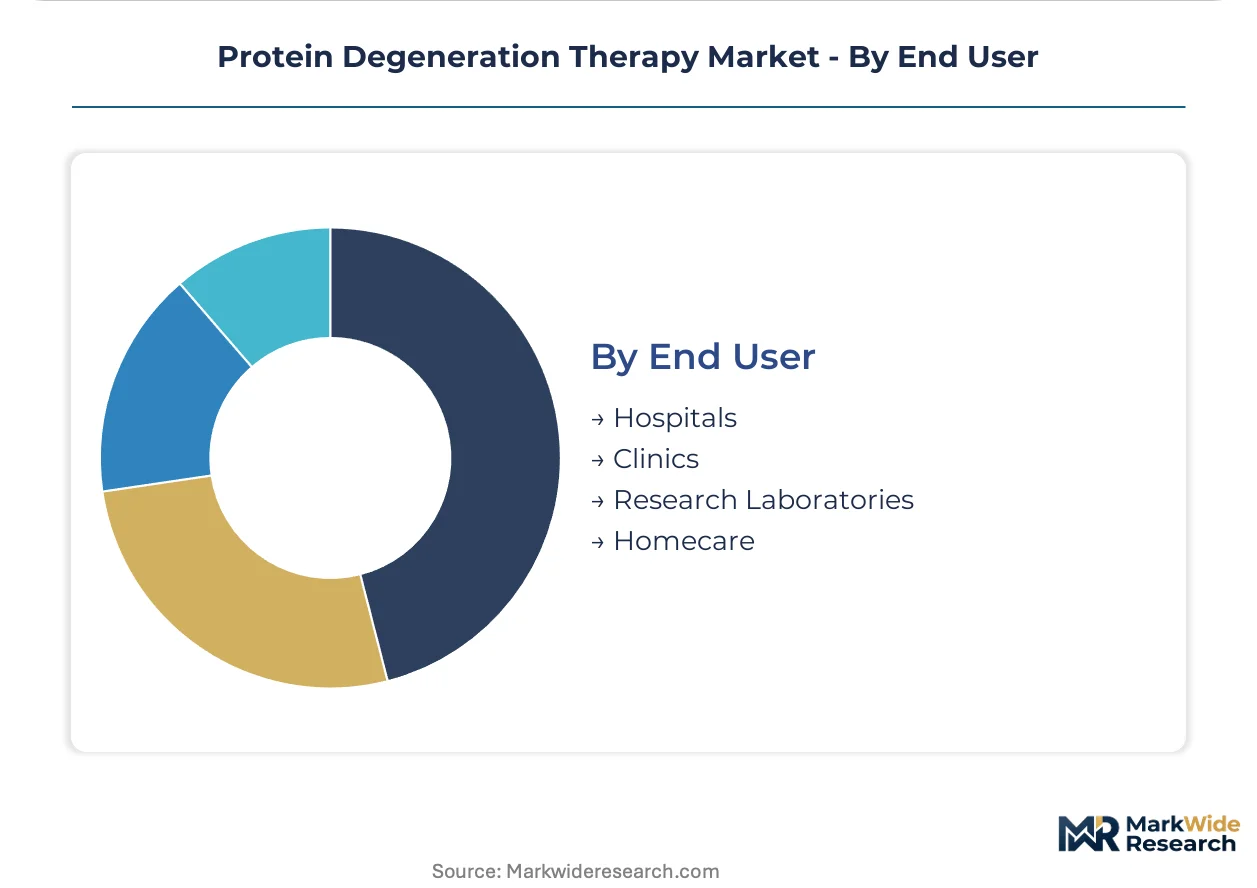
- Hospitals:Academic medical centers in the United States anchor translational research programs and early-phase trial execution for first-in-class degraders. Specialized pharmacy infrastructure supports cold-chain requirements for gene therapy vectors and complex heterobifunctional molecules.
- Research Laboratories:Discovery-stage outsourcing concentrates in Boston, San Diego, and Basel where E3 ligase biology expertise resides in contract research organizations.
- Clinics:Community oncology practices are adopting molecular glues as oral alternatives to infusion-based regimens.
- Homecare:Subcutaneous administration training programs are expanding patient self-management in multiple sclerosis.
Hospitals anchor the volume base while research laboratories gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power for heterobifunctional degraders concentrates in the United States while manufacturing scale advantages cluster in Germany and China, creating a structural asymmetry that shapes regional investment flows.
United States
FDA breakthrough therapy designations and rolling review mechanisms compress development timelines for first-in-class proteolysis-targeting chimeras. The agency's accelerated approval pathways reward sponsors with priority scheduling for novel molecular entities. Boston and San Diego academic medical centers anchor translational research programs that funnel discovery assets into sponsored pipelines.
Germany
Contract development organizations in Bavaria and North Rhine-Westphalia operate purpose-built synthesis suites for complex heterobifunctional molecules, reducing batch-to-batch variability for clinical batches. EMA PRIME eligibility criteria create parallel access pathways that complement FDA timelines for European market entry. Heidelberg and Munich clusters concentrate medicinal chemistry expertise in E3 ligase biology.
China
NMPA dedicated review channels for innovative biologics under drug registration reform accelerate multinational trial inclusion and shorten time-to-market for Western sponsors. Shanghai and Beijing host the majority of active clinical trials for proteolysis-targeting chimera modalities. Domestic contract manufacturers are installing specialized capacity for linker chemistry production.
Switzerland
Single-source specialty chemical producers in Basel supply high-purity E3 ligase ligands, creating supply constraints that inflate cost-of-goods for clinical batches across the industry. Swissmedic maintains alignment with EMA standards while offering streamlined review for orphan indications. The country's precision chemistry heritage supports fragment-based discovery platforms.
United Kingdom
London and Cambridge technology transfer offices consolidate exclusive licensing leverage, displacing non-exclusive research tool agreements that previously enabled broad platform access. The MHRA operates under retained EU alignment for chemistry-manufacturing-controls standards post-Brexit. Oxford and London clusters compete for limited slots in top-tier institutional portfolios.
Protein Degeneration Therapy Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with platform-origin biotechs commanding valuation premiums against scaled pharmaceutical incumbents. The market structure bifurcates between discovery-engine specialists and commercial-infrastructure owners. Three archetypes dominate: platform-anchored biotechs with ternary complex engineering capabilities, diversified pharmaceuticals leveraging small-molecule libraries, and gene therapy vector specialists. Competitive moves concentrate on strategic partnerships for ligase access and geographic expansion into China's NMPA pathway.
Within the platform-specialist tier, Arvinas and Kymera Therapeutics exemplify archetypes that prioritize E3 ligase biology expertise and tissue-specific ligase discovery respectively. Bristol Myers Squibb occupies a position representing scaled pharmaceutical incumbents with established commercial infrastructure. These three entities anchor the competitive landscape through differentiated positioning across the modality spectrum from heterobifunctional degraders to molecular glue approaches.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche AG |
| Arvinas |
| Bristol Myers Squibb |
| Pfizer |
| Merck & Co., Inc. |
| Amgen Inc. |
| Johnson & Johnson Services, Inc. |
| Novo Nordisk A/S |
| Kymera Therapeutics |
| Others |
Value Network & Pricing Analysis
REACH registration requirements for novel chemical entities gate both European supply qualification and price differentiation simultaneously, forcing sponsors to front-load environmental fate studies that add twelve to eighteen months to preclinical packages while creating regulatory-arbitrage opportunities for United States-first filers.
Pricing Analysis
United States pricing for heterobifunctional degraders commands substantial premiums over European and Chinese markets, with three-tier pricing structure across premium, standard, and economy levels separating orphan-designated biologics from chronic autoimmune small molecules and commodity oncology generics. Price differentiation hinges on FDA breakthrough therapy designation and EMA PRIME eligibility tier, with certification level determining reimbursement velocity. Cost compression in standard-tier molecular glues is intensifying because of linker chemistry commoditization. Academic medical centers exhibit lowest price sensitivity due to grant-funded translational programs, while community oncology practices face acute budget constraints.
Supply Chain Analysis
Just-in-time inventory strategies dominate clinical-batch production for heterobifunctional degraders, though strategic stockpiling of high-purity E3 ligase ligands is emerging among sponsors hedging against Swiss and Indian single-source vulnerabilities. Supply concentrates in Switzerland for specialty ligand chemistry, Germany for purpose-built synthesis suites, and China for linker production scale. Raw material dependencies draw from high-purity ubiquitin ligase ligands, polyethylene glycol linkers, and CRISPR guide RNA components. Tariff exposure on Chinese-sourced linkers represents the primary structural risk. Distribution runs through contract development organizations with cold-chain capabilities for gene therapy vectors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment, where FDA accelerated approval pathways and EMA PRIME eligibility create sticky, multi-year exclusivity positions that compound through iterative label expansions.
For Market Incumbents: Compound platform value through exclusive E3 ligase patent licensing and captive linker chemistry production in Germany or China. Arvinas and Bristol Myers Squibb should prioritize backward integration into high-purity ligand supply as single-source Swiss producers inflate cost-of-goods. Capacity addition in Bavaria or Shanghai secures batch consistency for heterobifunctional clinical candidates. Certification investment in FDA breakthrough therapy designation anchors pricing power against emerging molecular glue competitors.
For New Entrants and Emerging Players: Differentiate on blood-brain barrier-permeable degrader engineering for tau and alpha-synuclein targets, where technical barriers have delayed incumbent penetration. Central nervous system applications in Alzheimer's and Parkinson's represent the most penetrable white space. Tissue-specific ligase discovery for autoimmune indications offers secondary entry vectors. Go-to-market execution should prioritize academic medical center partnerships in Boston or San Diego for translational credibility.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with venture-backed platform biotechs in coastal United States clusters that have exhausted Series B runway without achieving IND-enabling milestones. Long-term viability over a five-to-ten year window rests on ternary complex engineering capabilities rather than single-asset pipelines. Acquisition targets should display chemoproteomics infrastructure and exclusive university licensing leverage. The signal to watch is NMPA reform-driven multinational trial inclusion rates for Western sponsors.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | FDA breakthrough therapy designation compresses development timelines for first-in-class degraders. |
| Regulatory Approval Pathway | NMPA dedicated review channels accelerate multinational trial inclusion for Western sponsors. |
| Licensing Agreement | Exclusive E3 ligase patent access from academic technology transfer offices secures platform differentiation. |
| Manufacturing Scale-Up | Purpose-built synthesis suites in Germany reduce batch-to-batch variability for heterobifunctional molecules. |
| Pipeline Diversification | Molecular glue expansion into autoimmune indications fragments traditional inhibitor market share. |
Research Methodology
Operator-level perspectives from drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers anchored the qualitative base, combining structured primary interviews with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up patient-flow modeling and top-down pharmaceutical market sizing were triangulated to constrain estimate variance.
Sensitivity analysis across dosing regimen assumptions, regulatory approval probability weights, and payer access velocity parameters shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include product type, application indication, delivery mode, and end-user setting, with regional regulatory cluster effects incorporated. CAGRs were derived from log-linear trend fitting to historical prescription data and pipeline transition probabilities. Forecast inputs incorporated E3 ligase expression profiling across tissue types and blood-brain barrier permeability coefficients for central nervous system candidates.
The analysis sits within stated boundaries; outcomes outside FDA accelerated approval retention, stable REACH compliance costs, and sustained NMPA reform momentum would require recalibration. Forecasts reflect documented assumptions regarding clinical trial success rates and pricing persistence. Revision becomes warranted when ternary complex characterization data requirements from EMA extend chemistry-manufacturing-controls review timelines beyond threshold tolerances.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
Oncolytic Virus Immunotherapy Market
Cell & Gene Therapy
Global Duchenne Muscular Dystrophy Treatment Market
Cell & Gene Therapy
Retinitis Pigmentosa Treatment Market
Cell & Gene Therapy
Global Gene Therapy Market
Cell & Gene Therapy
Lentiviral Vector Contract Development and Manufacturing Organizations Market
Cell & Gene Therapy
Stem Cell and Gene Therapy Biological Testing Market
Cell & Gene Therapy
Leukapheresis Products Market
Cell & Gene Therapy
T Cell Therapy Market
Cell & Gene Therapy
Cancer Stem Cells Market
Cell & Gene Therapy
Leukemia Therapeutics Market
Cell & Gene Therapy
Europe Cancer Vaccines Market
Cell & Gene Therapy
Europe Cell and Gene Therapy Thawing Equipment Market
Cell & Gene Therapy
Global T-Cell Acute Lymphoblastic Leukemia Treatment Market
Cell & Gene Therapy
Retinal Gene Therapy Market
Cell & Gene Therapy
Stem Cell Reconstructive Market
Cell & Gene Therapy
Global Lentiviral Vectors Market