
 Global Cell Sorting Market | 2026-2036
Global Cell Sorting Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cell Sorting Market Foresight
Biopharmaceutical companies are rotating demand from basic research tools toward GMP-compliant cell sorting platforms for commercial cell therapy production. BD Biosciences leverages its fluorescence-activated portfolio to dominate clinical-grade instrument supply. Thermo Fisher Scientific sustains competitive positioning through integrated workflow solutions spanning reagents, instruments, and analytical software. Beckman Coulter anchors its presence in high-throughput screening applications with centrifugal elutriation systems.
Cell sorting encompasses technologies that isolate and purify cell populations based on physical, optical, or electrical properties at throughputs exceeding 10,000 events per second in commercial flow cytometry platforms. These systems serve critical functions in therapeutic development, diagnostic assay validation, and fundamental biological discovery where population homogeneity determines experimental or clinical outcomes. Fluorescence activated cell sorters command the largest product segment due to decades of protocol standardization and antibody-fluorophore ecosystem maturity. Microfluidic cell sorters represent the fastest-growing product category as manufacturers reduce shear stress on fragile primary cells. Optical sorting technology leads the technology dimension, while acoustic sorting gains traction in gentle handling applications for induced pluripotent stem cell-derived therapies.
FDA 21 CFR Part 11 and EMA GMP Annex 1 requirements shape instrument validation protocols for cell therapy manufacturing environments. ISO 13485 quality management standards govern design controls for in-vitro diagnostic cell sorting devices sold in regulated markets. REACH chemical registration in Europe constrains fluorophore and buffer formulation choices for reagent suppliers. Stakeholders must monitor evolving cell therapy guidance documents across multiple jurisdictions to anticipate compliance-driven instrument upgrade cycles.
Market Dynamics
Cell therapy manufacturers are forcing instrument suppliers to reconfigure validation protocols as FDA 21 CFR Part 11 and EMA GMP Annex 1 tighten audit trails for fluorescence-activated sorting systems used in commercial production workflows.
Growth Catalysts
- Cell therapy manufacturing scale-up:Commercial production of CAR-T and iPSC-derived therapies requires GMP-compliant sorters with closed-system processing capabilities. Clinical trial pipelines in the United States, Germany, and China drive instrument procurement cycles.
- EMA GMP Annex 1 revision:The updated sterile manufacturing guidance mandates contamination control strategies for cell sorting environments. Biopharmaceutical facilities are retrofitting existing instruments or acquiring new platforms to meet these requirements.
- Microfluidic gentle-sorting advances:Reduced shear stress on primary cells and stem cell derivatives enables higher viability in downstream therapeutic applications. Academic and clinical research centers are expanding adoption for fragile cell populations.
Market Restraints
- Fluorophore supply concentration:REACH chemical registration constraints in Europe limit buffer and dye formulation options. Reagent suppliers face extended compliance timelines for novel conjugates.
- Capital intensity of GMP platforms:Clinical-grade fluorescence-activated cell sorters require seven-figure investments plus facility infrastructure modifications. Mid-sized cell therapy developers defer purchases or outsource sorting operations to contract manufacturing organizations.
- Technical throughput ceilings:Current optical detection architectures face physical limits in simultaneous parameter analysis. High-complexity sorting protocols for rare cell populations exceed practical processing rates for commercial manufacturing.
Strategic Opportunities
- Acoustic sorting technology convergence:Integration of acoustic wave manipulation with microfluidic channels enables label-free cell separation. This dual-technology approach reduces reagent costs and simplifies regulatory filings for cell therapy applications.
- ISO 13485 diagnostic device pathway:In-vitro diagnostic instrument certification opens reimbursement channels for clinical flow cytometry. Manufacturers can leverage existing quality management systems to access hospital laboratory budgets.
- India cell therapy manufacturing emergence:CDSCO regulatory frameworks are aligning with ICH guidelines for advanced therapy medicinal products. Domestic biopharmaceutical infrastructure investments create demand for compliant sorting instrumentation.
Industry Challenges
- Cross-functional talent scarcity:Cell therapy manufacturing requires operators fluent in both flow cytometry instrumentation and GMP documentation practices. Training programs at contract manufacturing organizations struggle to produce sufficient qualified personnel.
- Legacy system integration friction:Newer microfluidic and acoustic platforms must interface with established cell culture and cryopreservation workflows. Data format incompatibilities between instrument manufacturers complicate process validation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cell Sorting Market |
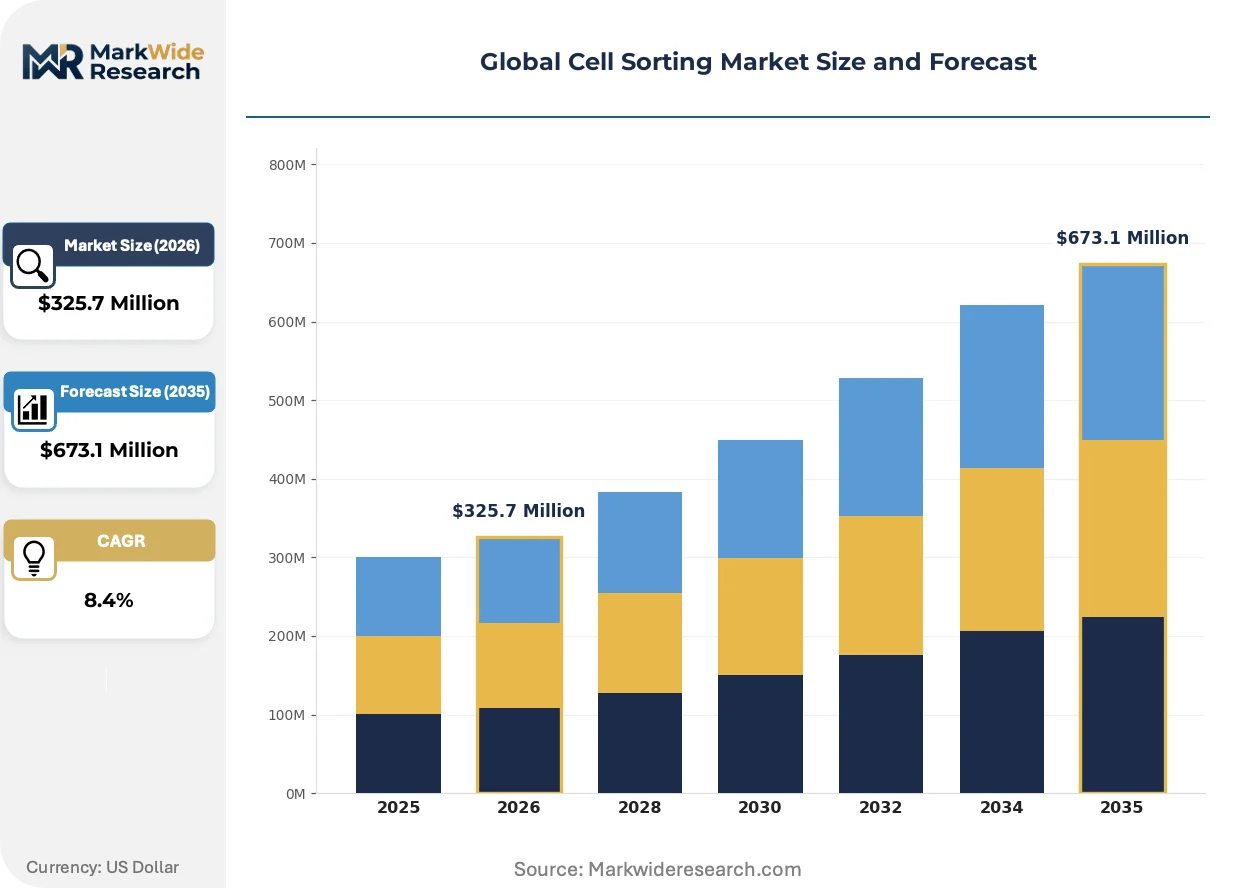
| Market Size in 2026 | $325.7 Million |
| Market Size in 2035 | $673.1 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fluorescence Activated Cell Sorter, Magnetic Activated Cell Sorter, Image Activated Cell Sorter, Microfluidic Cell Sorter Technology: Optical Sorting, Electrical Sorting, Mechanical Sorting, Acoustic Sorting, Dielectrophoretic Sorting Application: Stem Cell Research, Cancer Research, Immunology, Microbiology, Plant Sciences End User: Research Institutions, Biopharmaceutical Companies, Diagnostic Laboratories, Academic Institutes |
| Companies Covered | BD Biosciences, Thermo Fisher Scientific, Beckman Coulter, Bio-Rad Laboratories, Sony Biotechnology, Miltenyi Biotec, Danaher Corporation, Cytek Biosciences, Merck KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cell Sorting Market Shifts & Advancements
Instrument architectures are converging around closed-system processing and artificial intelligence-assisted gating as cell therapy manufacturers demand higher throughput with reduced contamination risk. These shifts are compressing development cycles for next-generation platforms.
Acoustic cell sorting is supplanting traditional droplet-based fluorescence-activated methods in stem cell therapy manufacturing workflows. The technology employs standing acoustic waves to position cells in microfluidic channels without fluorescent labels. Cell therapy developers in Japan and South Korea are adopting these systems at accelerating rates for iPSC-derived product lines. This label-free approach is compressing reagent costs and simplifying regulatory submissions for commercial manufacturing.
EMA GMP Annex 1 revisions are mandating single-use technology adoption for sterile processing environments. The guidance requires demonstrated contamination control across all unit operations including cell isolation and purification. European cell therapy manufacturing facilities are retrofitting sorting suites with disposable fluidics paths and closed sampling ports. This regulatory pressure is accelerating instrument replacement cycles ahead of typical depreciation schedules.
Service unbundling is restructuring how biopharmaceutical buyers contract for cell sorting capabilities. Large manufacturers are separating instrument procurement from application support and validation services, negotiating direct relationships with specialized compliance consultants. This disintermediation of traditional vendor service packages is most pronounced in the United States where cell therapy developers maintain internal regulatory affairs teams. Contract research organizations respond by offering certified sorting services on a per-sample basis without long-term equipment leases.
Global Cell Sorting Market Segmentation
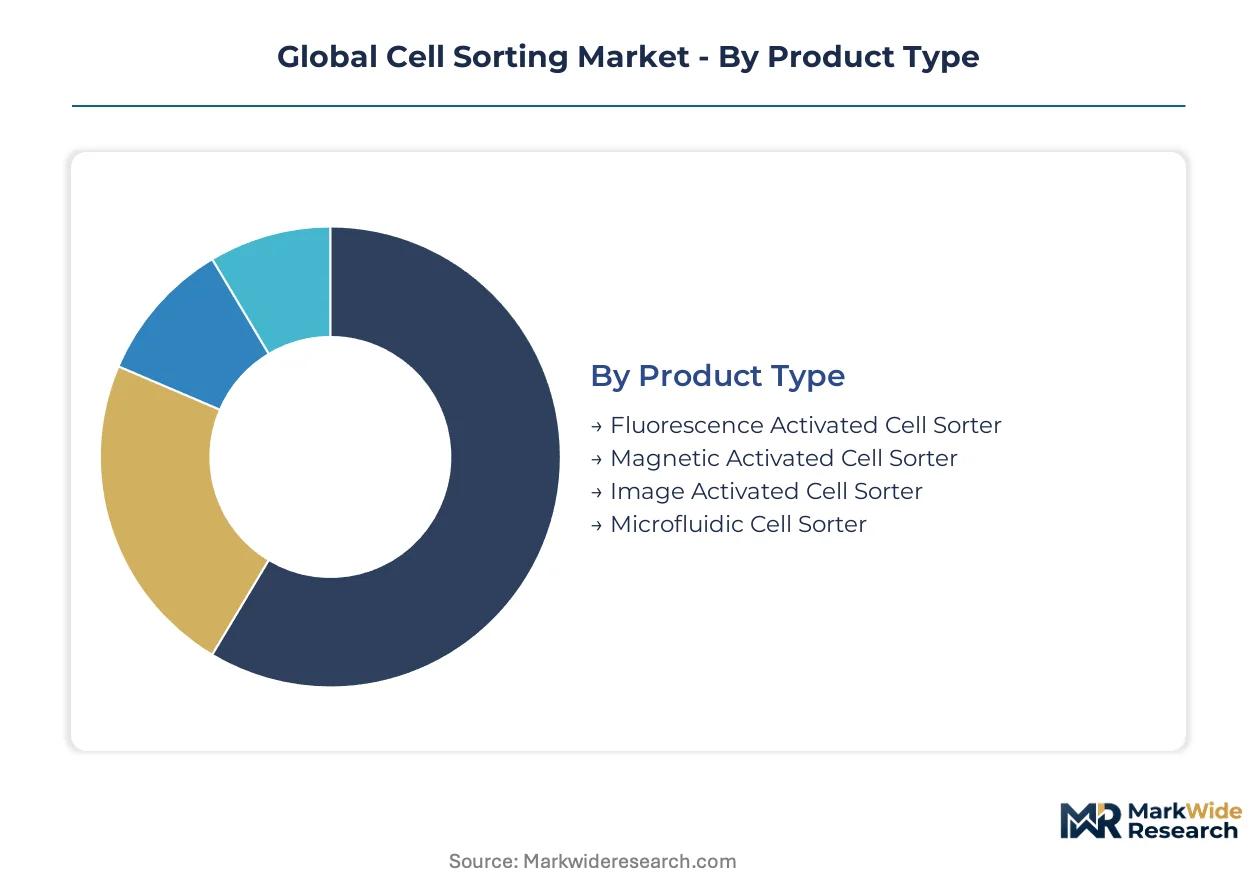
Cell sorting procurement decisions diverge sharply across user archetypes. Research laboratories prioritize parameter flexibility and open reagent compatibility, while commercial cell therapy manufacturers demand validated GMP workflows and closed-system architectures.
Product Type:
Margin pools concentrate in fluorescence-activated platforms due to decades of protocol standardization and consumables lock-in.
- Fluorescence Activated Cell Sorter:These systems detect labeled cells through laser excitation and photomultiplier tube arrays, achieving throughputs exceeding 10,000 events per second. BD Biosciences dominates clinical-grade supply as FDA 21 CFR Part 11 validation requirements tighten for commercial cell therapy production in the United States and Germany.
- Microfluidic Cell Sorter:Reduced shear stress on fragile primary cells and stem cell derivatives enables higher viability in downstream therapeutic applications. Academic centers in Japan and South Korea are expanding adoption for iPSC-derived product lines where gentle handling determines manufacturing yields.
- Magnetic Activated Cell Sorter:Column-based separation using antibody-coated magnetic beads offers simpler workflows without fluidics expertise.
- Image Activated Cell Sorter:Morphometric analysis combined with fluorescence detection enables label-free preliminary gating.
The dominant share belongs to Fluorescence Activated Cell Sorter, while Microfluidic Cell Sorter is closing the gap fastest.
Technology:
Application requirements determine technology selection, with optical architectures commanding the largest installed base.
- Optical Sorting:Laser-based detection systems measure light scatter and fluorescence emission across multiple wavelengths simultaneously. Biopharmaceutical companies in China deploy these platforms for CAR-T manufacturing where multi-parameter analysis ensures population purity for regulatory submissions to the national pharmaceutical regulator.
- Acoustic Sorting:Standing acoustic waves position cells in microfluidic channels without fluorescent labels, eliminating reagent costs and simplifying validation. Cell therapy developers in Japan and South Korea are adopting these systems at accelerating rates for commercial iPSC-derived therapies.
- Electrical Sorting:Impedance-based detection measures cell size and internal conductivity through microelectrode arrays.
- Mechanical Sorting:Physical filtration and centrifugal elutriation separate populations based on density and size differentials.
- Dielectrophoretic Sorting:Non-uniform electric fields exploit frequency-dependent polarizability variations between cell types.
Optical Sorting retains the largest installed base, though Acoustic Sorting is expanding most quickly in stem cell therapy applications.
Application:
Research funding flows and clinical trial pipelines concentrate demand in oncology and immunology workflows.
- Cancer Research:Tumor-infiltrating lymphocyte isolation and circulating tumor cell enrichment demand high-purity sorting for downstream genomic analysis. Research institutions in Germany leverage fluorescence-activated platforms for precision oncology studies aligned with EMA biomarker qualification pathways.
- Stem Cell Research:Pluripotent cell line maintenance and differentiation monitoring require gentle handling to preserve viability. Academic institutes in the United States and Japan are driving microfluidic adoption where shear sensitivity limits conventional droplet sorting.
- Immunology:T-cell subset characterization and rare population isolation support autoimmune and infectious disease research.
- Microbiology:Bacterial and fungal cell separation enables single-cell genomics and antibiotic resistance studies.
- Plant Sciences:Protoplast isolation and chloroplast sorting support agricultural biotechnology applications.
Cancer Research commands the greatest instrument procurement volume, while Stem Cell Research is gaining share fastest through cell therapy manufacturing scale-up.
End User:
Capital availability and regulatory sophistication create distinct purchasing patterns across institutional types.
- Biopharmaceutical Companies:Commercial cell therapy manufacturers require GMP-compliant platforms with closed-system processing and comprehensive audit trails. Facilities in the United States, Germany, and China are retrofitting sorting suites to meet FDA and EMA sterile manufacturing guidance.
- Research Institutions:Academic medical centers and government laboratories prioritize parameter flexibility and multi-user accessibility over validation documentation. Centers in Japan and South Korea are expanding acoustic sorting adoption for stem cell research programs.
- Diagnostic Laboratories:Clinical flow cytometry services demand ISO 13485-certified instruments with standardized assay menus.
- Academic Institutes:Undergraduate and graduate training programs emphasize open-platform systems for educational flexibility.
Biopharmaceutical Companies account for the dominant procurement spend, while Research Institutions are climbing the fastest through expanded government funding for advanced therapy development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German instrument manufacturers export fluorescence-activated systems to biopharmaceutical facilities across the United States and China, establishing the primary trade corridor in clinical-grade cell sorting equipment.
United States
FDA 21 CFR Part 11 validation requirements and CAR-T manufacturing scale-up drive procurement of GMP-compliant sorters. The Inflation Reduction Act supports domestic biopharmaceutical production capacity. Greater Boston hosts the densest concentration of cell therapy developers retrofitting sorting suites for commercial production.
Germany
EMA GMP Annex 1 revisions mandate contamination control strategies for sterile manufacturing environments. REACH chemical registration constrains fluorophore formulation options for reagent suppliers. The Rhine-Main cluster around Frankfurt anchors instrument validation service providers serving European cell therapy manufacturers.
China
NMPA alignment with ICH guidelines for advanced therapy medicinal products accelerates clinical trial pipeline expansion. National pharmaceutical regulator submissions require multi-parameter analysis documentation for CAR-T purity verification. Shanghai and Suzhou biopharmaceutical parks concentrate domestic cell therapy manufacturing investments.
Japan
PMDA guidance on iPSC-derived therapeutic products creates demand for gentle-handling sorting platforms. METI funding programs support microfluidic technology adoption in stem cell manufacturing. The Kansai region around Osaka hosts academic institutes driving acoustic sorting adoption for fragile cell populations.
South Korea
MFDS regulatory frameworks for cell and gene therapies align with international standards for commercial manufacturing. Government biotechnology initiatives fund domestic instrument procurement for contract manufacturing organizations. Seoul Capital Area facilities specialize in iPSC-derived product line development requiring reduced-shear processing.
Global Cell Sorting Market Competitive Landscape
Player mix skews toward diversified life science conglomerates with integrated workflow portfolios. Market structure concentrates around three to four entities controlling clinical-grade instrument supply and validation documentation. Strategic archetypes include fluorescence-activated platform specialists, microfluidic technology innovators, and centrifugal separation equipment providers. Competitive moves center on GMP compliance certification expansion and acoustic sorting technology licensing arrangements.
Within the diversified conglomerate tier, BD Biosciences and Thermo Fisher Scientific exemplify integrated platform strategies spanning instruments, reagents, and analytical software. Beckman Coulter occupies a position in high-throughput screening applications through centrifugal elutriation systems. These three entities anchor the clinical-grade supply base as FDA and EMA validation requirements tighten for commercial cell therapy production workflows.
| Leading Market Players |
|---|
| BD Biosciences |
| Thermo Fisher Scientific |
| Beckman Coulter |
| Bio-Rad Laboratories |
| Sony Biotechnology |
| Miltenyi Biotec |
| Danaher Corporation |
| Cytek Biosciences |
| Merck KGaA |
| Others |
Supply & Pricing Matrix
FDA 21 CFR Part 11 and EMA GMP Annex 1 compliance tiers simultaneously gate supplier qualification and stratify price levels across fluorescence-activated, microfluidic, and acoustic sorting platforms. Buyers face discrete cost jumps when upgrading from research-grade to clinical-grade instrumentation, with validation documentation and closed-system architectures commanding substantial premiums.
Pricing Analysis
Next-generation acoustic and microfluidic platforms command 40-60% premiums over prior-generation fluorescence-activated systems, while current-generation GMP-compliant sorters sit at the apex of the price hierarchy. Three-tier pricing structure across premium clinical-grade, standard research-grade, and economy refurbished levels reflects certification depth and after-sales service bundling. Cost compression in research-grade tiers is intensifying because academic budget constraints and shared facility consolidation reduce per-laboratory procurement volumes. Mid-sized cell therapy developers exhibit highest price sensitivity, deferring capital purchases in favor of contract manufacturing organization outsourcing.
Supply Chain Analysis
Extended lead times for photomultiplier tubes and specialized optical filters now stretch 16-24 weeks, constraining instrument manufacturers' production scheduling flexibility. Component sourcing draws from Germany, Japan, and the United States for precision optical assemblies, while microfluidic chip fabrication concentrates in Taiwan and South Korea. Single-source vulnerability for high-purity fluorophores creates exposure to REACH chemical registration delays in Europe. Distribution runs through direct manufacturer sales teams for clinical-grade platforms, with research-grade instruments flowing through specialized life science distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cell therapy manufacturing demand fragments across GMP compliance tiers, instrument scales, and regional regulatory clusters, creating defendable niches for specialists alongside integrated conglomerates. Service unbundling trends and acoustic technology licensing opportunities open entry points for focused competitors.
For Market Incumbents: Fortify validation documentation superiority and closed-system processing capabilities against microfluidic entrants targeting gentle-handling applications. Invest in ISO 13485 certification expansion for diagnostic laboratory channels. Extend backward integration into fluorophore supply to mitigate REACH-constrained reagent cost volatility. For New Entrants and Emerging Players: GMP compliance consulting and validation service gaps where incumbents bundle rigidly present immediate white-space targets. Target acoustic sorting technology licensing for iPSC-derived therapy developers in Japan and South Korea. Pursue per-sample service contracts with mid-sized cell therapy developers lacking internal regulatory affairs capacity. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across microfluidic platform development as chip manufacturing scales and design tools mature. Five-to-ten-year viability favors acoustic-microfluidic convergence specialists with demonstrated PMDA or MFDS regulatory engagement. Monitor CDSCO framework alignment with ICH guidelines as inflection signal for India manufacturing infrastructure deployment.| Strategic Initiative | Industry Significance |
|---|---|
| Acoustic Technology Licensing | Reduces reagent costs for iPSC-derived therapy developers facing PMDA scrutiny. |
| GMP Validation Service Expansion | Captures procurement budget from biopharmaceutical companies separating instrument and compliance spend. |
| ISO 13485 Certification Pathway | Opens hospital laboratory reimbursement channels for clinical flow cytometry services. |
| Closed-System Architecture Development | Meets EMA GMP Annex 1 sterile manufacturing mandates accelerating European replacement cycles. |
| Regional Manufacturing Footprint | Positions inventory near CDSCO-aligned India cell therapy clusters reducing logistics exposure. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 21 CFR Part 11 guidance documents, EMA GMP Annex 1 revisions, and ISO 13485 quality management standards. Interviews with cell therapy manufacturing directors, regulatory affairs specialists, flow cytometry core facility managers, and GMP compliance consultants informed demand-side dynamics. Secondary validation drew from ClinicalTrials.gov cell therapy pipeline data, NMPA advanced therapy submissions, and PMDA iPSC-derived product guidance. Bottom-up instrument procurement modeling triangulates against top-down market sizing across fluorescence-activated, microfluidic, magnetic, and acoustic platform categories.
Segmentation dimensions modeled include product type, technology architecture, application area, and end-user category across the projection horizon. Cancer research, stem cell research, and immunology workflows anchor demand-side segmentation with cell therapy manufacturing scale-up as the primary growth input. CAGRs derive from instrument replacement cycle analysis, clinical trial pipeline conversion rates, and regulatory-driven upgrade elasticity. Acoustic sorting adoption curves and microfluidic gentle-handling penetration inform technology-transition assumptions.
Underlying assumptions cover FDA and EMA guidance stability, fluorophore supply continuity under REACH, and ICH guideline harmonization progress, with deviation risk concentrated in CDSCO regulatory timeline acceleration and acoustic technology performance validation. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Global Biological Stains Market
Biomedical Technology
Stem Cell Banking Market
Biomedical Technology
Global RNA-Interference (Rnai) Market
Biomedical Technology
Polymerase Chain Reaction Technologies Market
Biomedical Technology
Digital Biology Market
Biomedical Technology
Spine Biologics Market
Biomedical Technology
Strand Displacement Amplicon (SDA) Market
Biomedical Technology
Asia-Pacific Exosome Research Products Market
Biomedical Technology
Exonucleases Market
Biomedical Technology
Global Biocompatibility Testing Services Market
Biomedical Technology
Northern Blotting Market
Biomedical Technology
Global Primary Cell Culture Market
Biomedical Technology
Global Transfection Market
Biomedical Technology
Global Drug Discovery Technologies Market
Biomedical Technology
Strand Displacement Amplification (SDA) Market
Biomedical Technology
Single Cell Multiomics Market