
 Natural Killer (NK) Cell Therapeutics Market | 2026-2036
Natural Killer (NK) Cell Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Natural Killer (NK) Cell Therapeutics Market Foresight
CRISPR-edited iPSC-derived NK cell manufacturing is reshaping therapeutic production by enabling off-the-shelf, scalable allogeneic platforms with standardized quality controls. Fate Therapeutics leverages induced pluripotent stem cell engineering to sustain a pipeline of multiplexed-edited NK product candidates. Bristol-Myers Squibb Company anchors its immuno-oncology franchise through expanded NK cell programs combined with established antibody assets. Nkarta Therapeutics differentiates through cryopreserved, tumor-targeted NK cell designs that occupy a distinct manufacturing niche.
Natural Killer (NK) Cell Therapeutics comprise ex vivo expanded or genetically modified cytotoxic lymphocytes engineered to recognize and eliminate malignant or infected cells without prior antigen sensitization, typically manufactured through feeder cell expansion, cytokine stimulation, or viral vector transduction to achieve therapeutic doses exceeding 10^8 cells per infusion. CAR-NK Cells lead clinical development pipelines due to their built-in tumor-targeting specificity and reduced cytokine release syndrome risk compared with CAR-T alternatives, while Expanded NK Cells represent the most mature manufacturing category with established cytokine-based protocols. Cancer dominates therapy area allocation as hematologic malignancies and solid tumors drive investigator-sponsored and commercial trials, whereas the Autoimmune Disorders segment attracts emerging interest for lupus and multiple sclerosis applications.
The FDA's regenerative medicine advanced therapy designation and EMA's priority medicines scheme shape competitive access by compressing regulatory review timelines for NK cell products demonstrating breakthrough potential. WHO's cell and gene therapy standardization initiatives influence manufacturing benchmarks that determine cross-border clinical trial acceptability and eventual commercial licensing pathways. Stakeholders must monitor evolving allogeneic donor screening requirements and vector supply chain constraints as scaling decisions commit capital toward centralized versus distributed manufacturing architectures.
Market Dynamics
The transition from autologous to allogeneic NK cell manufacturing is compressing production timelines while forcing capital allocation toward centralized GMP facilities capable of supporting multi-product pipelines.
Growth Catalysts
- FDA Regenerative Medicine Advanced Therapy Designation:Accelerated review timelines compress development cycles for breakthrough-designated NK cell products, reducing time-to-market for eligible candidates.
- CAR-NK engineering platforms:Chimeric antigen receptor insertion into NK cells enables tumor-specific targeting without the cytokine release syndrome risks associated with CAR-T alternatives.
- Japan's PMDA Sakigake designation system:Priority review status for innovative cell therapies has attracted trial investment from international sponsors seeking early Asian market entry.
Market Restraints
- Lentiviral vector supply concentration:Manufacturing capacity for GMP-grade viral vectors clusters among a limited pool of CDMOs, creating single-source dependencies for transduction-dependent NK products.
- Cryopreservation formulation costs:Dimethyl sulfoxide and specialized freezing media represent significant per-dose input expenses that scale with manufacturing volume.
- Allogeneic donor screening complexity:Stringent eligibility criteria for iPSC source material limit donor pool availability and extend qualification timelines.
Strategic Opportunities
- Autoimmune disorder applications:Systemic lupus erythematosus and multiple sclerosis represent underexplored therapeutic areas where NK cell immunoregulatory properties may address unmet need.
- Distributed manufacturing networks:Point-of-care production models using closed-system bioreactors could reduce cold-chain logistics burdens for time-sensitive cellular products.
- EMA PRIME eligibility:Priority medicines scheme access provides enhanced regulatory support for NK cell therapies targeting hematologic malignancies with limited treatment options.
Industry Challenges
- Cellular therapy manufacturing workforce scarcity:Qualified GMP operators with aseptic processing and cell culture expertise command premium compensation in competitive biotech labor markets.
- potency assay standardization:Lack of harmonized release criteria across jurisdictions complicates multi-regional trial design and eventual commercial supply.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Natural Killer (NK) Cell Therapeutics Market |
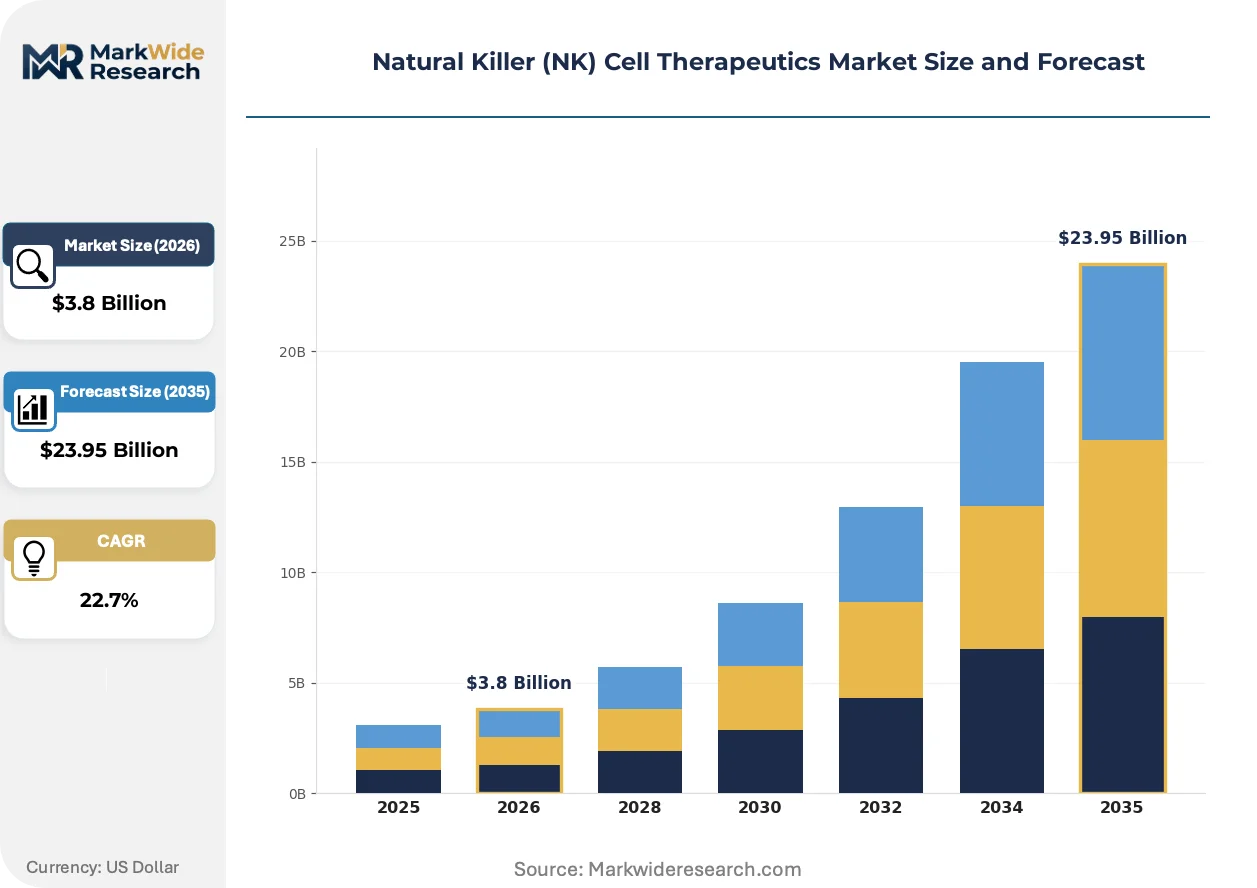
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $23.95 Billion |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CAR-NK Cells, Expanded NK Cells, Innate Lymphoid Cells, Cytokine-Induced Killer Cells Therapy Area: Cancer, Viral Infections, Autoimmune Disorders, Infectious Diseases Administration Route: Intravenous, Intratumoral, Subcutaneous, Intra-Pleural End User: Hospitals, Research Institutes, Specialty Clinics, Pharmaceutical Companies |
| Companies Covered | Bristol-Myers Squibb Company, Fate Therapeutics, Glycostem Therapeutics, Innate Pharma, Nkarta Therapeutics, ImmunityBio, Affimed GmbH, Cytovia Therapeutics, Dragonfly Therapeutics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Natural Killer (NK) Cell Therapeutics Market Shifts & Advancements
Process analytical technology integration is transforming how NK cell manufacturers monitor critical quality attributes in real time, reducing batch failure rates while compressing release timelines.
Closed-system automated bioreactors are digitizing manufacturing execution by replacing open culture vessels with single-use platforms that capture continuous data on pH, dissolved oxygen, and cell density. Academic medical centers in the United States and contract manufacturers in Germany are adopting these systems to reduce operator-dependent variability. This digitization is compressing the gap between clinical-scale and commercial-scale production, enabling faster tech transfer for late-stage candidates.
EMA's revised Good Manufacturing Practice Annex 1 for sterile medicinal products is mandating enhanced contamination control strategies that specifically address cell therapy manufacturing environments. The regulation requires continuous environmental monitoring and rapid microbial detection systems that increase facility capital requirements. European NK cell developers are responding by redesigning cleanroom layouts and investing in isolator-based processing to maintain compliance while protecting pipeline timelines.
Site-of-care manufacturing models are disrupting traditional centralized production by enabling hospital-based cell therapy preparation within dedicated pharmacy suites. Oncology centers in Australia and specialized clinics in South Korea are piloting these distributed approaches to eliminate shipping-related cell viability losses. This shift is most visible in hematologic malignancy treatment networks where same-day infusion protocols are replacing cryopreserved product logistics.
Natural Killer (NK) Cell Therapeutics Market Segmentation
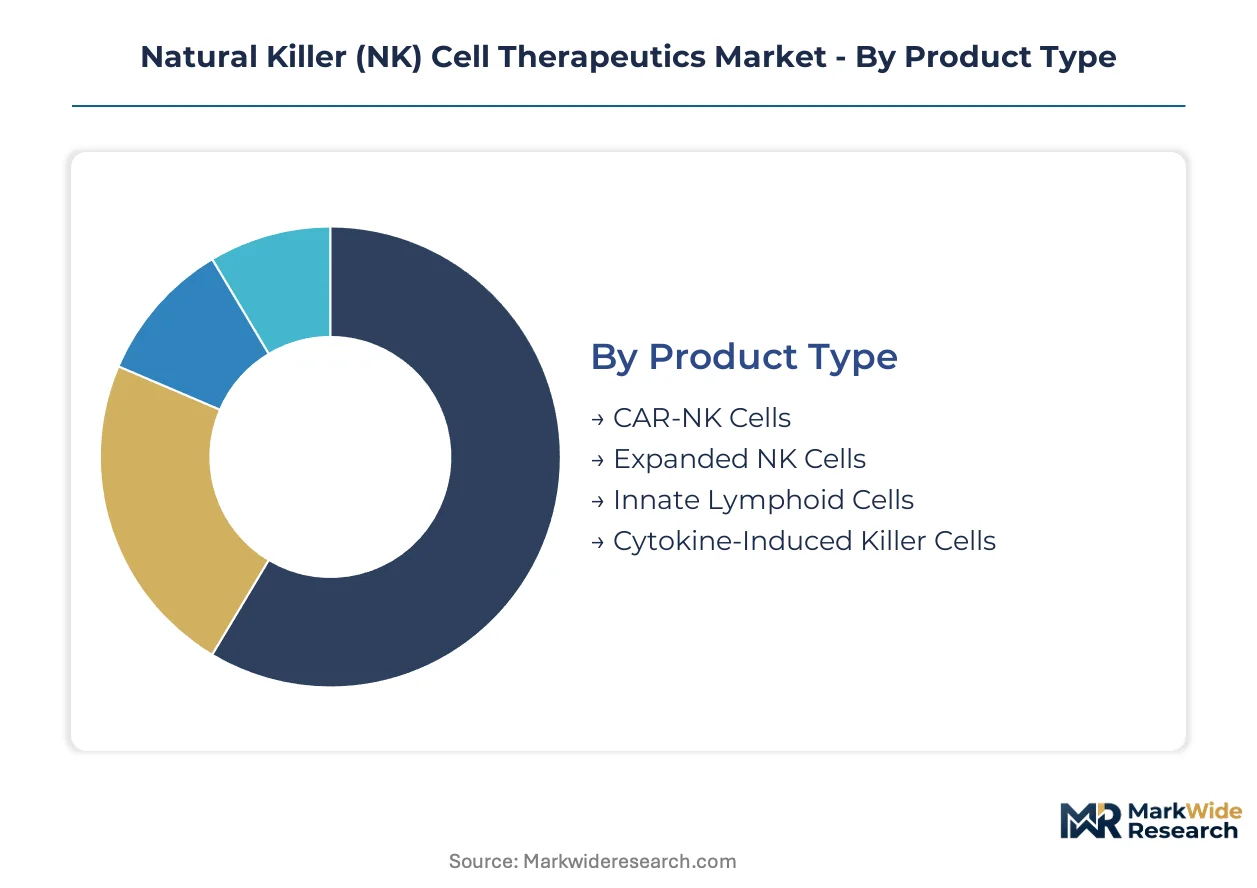
NK cell therapeutic developers segment their pipelines across engineering complexity, disease targeting, delivery mechanisms, and care settings. Each dimension carries distinct manufacturing requirements, regulatory pathways, and reimbursement implications that shape commercial strategy.
Product Type:
Engineering intensity spans from minimally manipulated expanded populations to fully engineered CAR-modified platforms, with each tier demanding different capital commitments and partnership structures.
- CAR-NK Cells:Chimeric antigen receptor insertion transforms NK cells into tumor-targeting therapeutics with built-in specificity against hematologic and solid malignancies. Clinical demand concentrates at academic medical centers in the United States running Phase I/II trials for CD19 and BCMA targets, driven by the reduced cytokine release syndrome risk versus CAR-T alternatives.
- Expanded NK Cells:Cytokine-stimulated ex vivo expansion achieves therapeutic cell doses without genetic modification, representing the most mature manufacturing category with established feeder-cell and feeder-free protocols. Manufacturing investment clusters in Germany and Singapore where contract manufacturers have validated scalable expansion platforms for allogeneic donor-derived products.
- Innate Lymphoid Cells:Broader lymphoid population therapies encompassing NK cell subsets and related innate immune cells are advancing through early discovery pipelines.
- Cytokine-Induced Killer Cells:Heterogeneous cytotoxic populations generated through combined cytokine stimulation occupy a niche in investigator-sponsored trials, particularly in South Korea and China.
The dominant share belongs to Expanded NK Cells, while CAR-NK Cells is closing the gap fastest.
Therapy Area:
Disease application determines cell dose requirements, administration frequency, and competitive positioning against established standards of care.
- Cancer:Hematologic malignancies and solid tumors command the primary therapeutic focus, with acute myeloid leukemia and non-Hodgkin lymphoma representing lead indications where chemotherapy resistance creates addressable need.
- Autoimmune Disorders:Systemic lupus erythematosus and multiple sclerosis applications are expanding most quickly as NK cell immunoregulatory mechanisms attract biotech investment beyond oncology.
- Viral Infections:Cytomegalovirus and other persistent viral targets leverage NK cell innate antiviral recognition, with demand emerging from transplant centers managing reactivation risk.
- Infectious Diseases:Broader infectious applications including resistant bacterial and fungal targets remain preclinical with limited near-term commercial visibility.
Oncology maintains the dominant position, while autoimmune applications are gaining share fastest.
Administration Route:
Delivery modality selection shapes product formulation, cryopreservation requirements, and site-of-care infrastructure needs.
- Intravenous:Systemic infusion remains the standard delivery mechanism for hematologic malignancies, requiring cryopreserved or fresh product logistics and infusion center capacity.
- Intratumoral:Direct tumor injection addresses solid tumor penetration challenges, with demand concentrating at specialized interventional oncology centers in the United States and Japan equipped for image-guided delivery.
- Subcutaneous:Depot-formulation development aims to enable outpatient administration with reduced facility dependency.
- Intra-Pleural:Cavity-directed delivery targets mesothelioma and pleural metastases through specialized thoracic oncology networks.
Intravenous delivery holds the dominant share, while intratumoral administration is climbing the fastest as solid tumor indications advance.
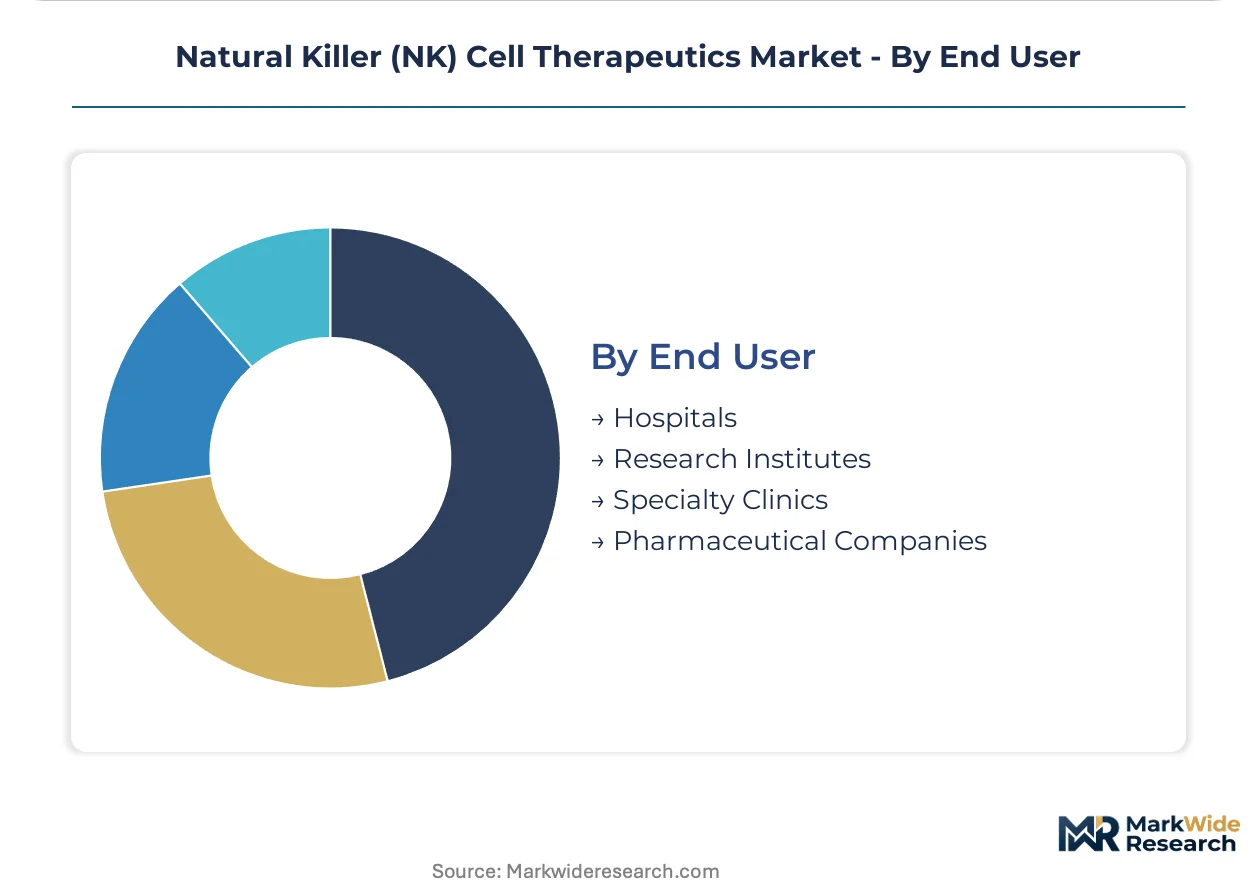
End User:
Customer type determines purchasing authority, reimbursement pathway, and technical support requirements across the value chain.
- Hospitals:Integrated health systems with cellular therapy programs anchor commercial demand, particularly NCI-designated cancer centers with established GMP facilities and apheresis capabilities.
- Pharmaceutical Companies:Large-cap biopharma partners drive pipeline investment through licensing transactions and co-development structures, with Bristol-Myers Squibb and Fate Therapeutics exemplifying platform-focused deal activity.
- Research Institutes:Academic medical centers and national laboratories generate early clinical data through investigator-sponsored trials supported by NIH and foundation funding.
- Specialty Clinics:Focused oncology and immuno-oncology practices represent emerging channels as outpatient administration protocols mature.
Hospitals command the dominant share, while pharmaceutical company partnerships are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Academic medical centers and contract manufacturers concentrate demand across distinct national clusters, with regulatory acceleration programs determining competitive access timelines in each jurisdiction.
United States
NCI-designated cancer centers in Boston and San Francisco drive trial enrollment for CAR-NK and expanded NK platforms. FDA's Regenerative Medicine Advanced Therapy designation compresses review timelines for breakthrough candidates. Manufacturing scale-up concentrates in Massachusetts and California biotech corridors where GMP facility investment exceeds other states.
Germany
Contract manufacturers in Heidelberg and Munich validate scalable expansion platforms for allogeneic donor-derived products. EMA's revised GMP Annex 1 mandates enhanced contamination control strategies that increase facility capital requirements. Cleanroom redesign and isolator-based processing investments cluster in Baden-Württemberg and Bavaria production hubs.
Japan
PMDA's Sakigake designation system attracts international trial investment for innovative cell therapies seeking early Asian market entry. Priority review status compresses regulatory timelines for eligible NK cell candidates. Clinical activity concentrates at Tokyo and Osaka oncology centers equipped for hematologic malignancy protocols.
United Kingdom
London and Cambridge immuno-oncology clusters anchor academic-sponsored trials for innate lymphoid cell applications. MHRA post-Brexit regulatory pathways align with EMA standards while enabling streamlined national approval timelines. Cell therapy manufacturing investment clusters in Stevenage and Oxfordshire biotech parks.
South Korea
Seoul-based oncology centers pilot site-of-care manufacturing models to eliminate shipping-related cell viability losses. MFDS accelerated approval pathways support same-day infusion protocols for hematologic malignancy networks. Specialized clinics in the capital region lead distributed production approaches for time-sensitive cellular products.
Natural Killer (NK) Cell Therapeutics Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a structure defined by platform ownership versus manufacturing scale. Large-cap biopharma anchors immuno-oncology franchises through expanded NK programs combined with antibody assets. Mid-cap cell therapy specialists differentiate through cryopreserved designs and iPSC engineering platforms. Competitive moves concentrate on strategic partnerships for vector supply security and centralized GMP capacity expansion.
Within the iPSC-engineering tier, Fate Therapeutics occupies a position exemplifying multiplexed-edited NK product candidate pipelines. Among tumor-targeted specialists, Nkarta Therapeutics and Bristol-Myers Squibb Company represent distinct manufacturing niches—cryopreserved cell designs versus integrated immuno-oncology franchises. These anchors illustrate how platform complexity and therapeutic area focus determine partnership structures and capital allocation priorities.
| Leading Market Players |
|---|
| Bristol-Myers Squibb Company |
| Fate Therapeutics |
| Glycostem Therapeutics |
| Innate Pharma |
| Nkarta Therapeutics |
| ImmunityBio |
| Affimed GmbH |
| Cytovia Therapeutics |
| Dragonfly Therapeutics |
| Others |
Supply & Pricing Matrix
Cold-chain logistics corridors connecting Massachusetts biotech clusters to European contract manufacturers concentrate cost dynamics that amplify supply concentration effects and downstream price differentiation across CAR-NK and expanded NK cell tiers.
Pricing Analysis
Cost-plus contracts with raw material indexation dominate GMP-grade cytokine and lentiviral vector procurement, anchoring pricing structures to input cost volatility. Three-tier pricing structure across premium CAR-NK, standard expanded NK, and economy cytokine-induced killer cell levels separates engineering complexity tiers. Pricing pressure stems from cryopreservation media cost inflation and vector supply scarcity. Academic medical centers exhibit highest price sensitivity due to grant-funded budgets, while integrated pharmaceutical partnerships absorb premium tiers for pipeline exclusivity.
Supply Chain Analysis
Tariff exposure between United States and China dominates supply chain risk for GMP-grade plasticware and single-use bioreactor components. Manufacturing concentration clusters in United States, Germany, and Singapore where contract manufacturers have validated scalable platforms. Raw material dependencies center on recombinant cytokines, dimethyl sulfoxide cryoprotectant, and clinical-grade viral vectors. Single-source vulnerability persists for lentiviral vector CDMO capacity. Distribution runs through centralized GMP facilities to hospital infusion centers with validated cold-chain protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
CRISPR-edited iPSC platforms are disrupting therapeutic manufacturing economics, with FDA Regenerative Medicine Advanced Therapy designation compressing development timelines and reshaping competitive entry thresholds.
For Market Incumbents: Entrench platform ownership through captive iPSC line development and centralized GMP capacity expansion in Massachusetts and California corridors. Secure vector supply through backward integration into lentiviral manufacturing or exclusive CDMO offtake agreements. Defend against emerging allogeneic competitors by locking academic medical center partnerships through preferred investigator-sponsored trial arrangements.
For New Entrants and Emerging Players: Establish a beachhead in autoimmune disorder applications where NK cell immunoregulatory mechanisms remain underexplored and competitive density is lowest. Target site-of-care manufacturing partnerships with Seoul and Melbourne oncology centers piloting distributed production models. Lead with cryopreserved formulation advantages that eliminate fresh-product logistics burdens.
For Investors and Strategic Acquirers: FDA breakthrough therapy designation reshapes the acquisition landscape by derisking late-stage NK cell assets and compressing due diligence timelines. Long-term viability favors platform-ownership models with multiplexed editing capabilities and validated iPSC master cell banks. Monitor EMA PRIME eligibility decisions as the signal indicating regulatory de-risking and accelerated European market access.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Phase I/II progression at NCI-designated cancer centers validates CAR-NK tumor targeting mechanisms. |
| Regulatory Approval Pathway | FDA Regenerative Medicine Advanced Therapy designation compresses review timelines for breakthrough candidates. |
| Manufacturing Scale-Up | Centralized GMP facility investment in Boston and San Francisco corridors enables multi-product pipeline support. |
| Licensing Agreement | Platform-focused partnerships with large-cap biopharma secure vector supply and antibody combination assets. |
| Pipeline Diversification | Autoimmune disorder expansion into lupus and multiple sclerosis addresses unmet need beyond oncology saturation. |
Research Methodology
Initial hypotheses were tested against primary input from cell therapy manufacturing executives, regulatory affairs leads at FDA and EMA, hospital procurement managers at NCI-designated cancer centers, and payer access specialists, then refined through secondary validation against FDA filings, ClinicalTrials.gov records, EMA submission databases, and GMP inspection reports. Bottom-up demand modeling and top-down market sizing were triangulated to converge on segment-level estimates.
Demand-supply balance framing anchored the forecast framework across the projection horizon, with analytical outputs reflecting modeled segmentation across product type, therapy area, administration route, and regional regulatory cluster. CAGRs were derived from fitted growth curves applied to enrollment trajectories and manufacturing capacity expansion schedules. Industry-specific inputs incorporated vector supply constraints and cryopreservation formulation cost curves.
Sensitivities concentrate around regulatory approval timelines, vector manufacturing capacity bottlenecks, and allogeneic donor screening protocol changes that could compress or extend commercialization pathways. Forecasts reflect documented assumptions regarding clinical success rates and reimbursement pathway clarity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
Gene Therapy Products Market
Cell & Gene Therapy
Europe Viral Vector Purification Market
Cell & Gene Therapy
Cryopreservation Cell Lines Market
Cell & Gene Therapy
Cell Therapy Biomanufacturing Market
Cell & Gene Therapy
Cellular Immunotherapy Market
Cell & Gene Therapy
Cell Regeneration Medicine Market
Cell & Gene Therapy
Europe Cancer Vaccines Market
Cell & Gene Therapy
Cell Therapy Cryopreservation and Thaw Performance Test Platforms Market
Cell & Gene Therapy
Viral Vector Development Market
Cell & Gene Therapy
Adipose Derived Stem Cell Therapy Market
Cell & Gene Therapy
Global T-Cell Acute Lymphoblastic Leukemia Treatment Market
Cell & Gene Therapy
Gene Panel Market
Cell & Gene Therapy
Global Viral Vector Manufacturing Market
Cell & Gene Therapy
Cancer Stem Cells Market
Cell & Gene Therapy
Stem Cell and Gene Therapy Biological Testing Market
Cell & Gene Therapy
Adeno Associated Virus Vector Manufacturing Market